
 Veterinary Radiography Flat Panel Detectors Market | 2026-2036
Veterinary Radiography Flat Panel Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Radiography Flat Panel Detectors Market Analytics
Veterinary radiography technician shortages across major markets is redrawing installation and service timelines for imaging equipment. Varex Imaging Corporation leverages its flat panel foundry scale to sustain cost leadership in detector core production. Canon anchors the premium segment through proprietary CMOS sensor architectures that differentiate image quality for orthopedic diagnostics. IDEXX Laboratories dominates the integrated software-imaging bundle, controlling workflow platforms that lock in recurring service revenue.
Veterinary radiography flat panel detectors are solid-state digital imagers employing amorphous silicon or CMOS photodiode arrays coupled with cesium iodide or gadolinium oxysulfide scintillators, converting X-ray photons into electrical signals for real-time diagnostic display. Their primary commercial purpose is to replace analog film and computed radiography plates in veterinary settings, delivering immediate image availability with reduced radiation exposure for sedated animals. Digital detectors lead product type revenue due to replacement cycles in mature installed bases, while fluoroscopy detectors represent the fastest-expanding category as interventional veterinary procedures grow. Among end users, animal hospitals command the largest volume commitment, though research laboratories yield superior margins from customized high-resolution configurations.
FDA Center for Veterinary Medicine oversees device safety labeling and performance claims, while ISO 13485 quality management standards govern manufacturing consistency for international distribution. The EU Medical Device Regulation through notified bodies extends conformity assessment requirements to veterinary imaging equipment sold in European markets. Stakeholders must monitor evolving AI-enabled diagnostic software regulations that will determine whether algorithm-augmented flat panel systems qualify as standalone regulated devices or accessories.
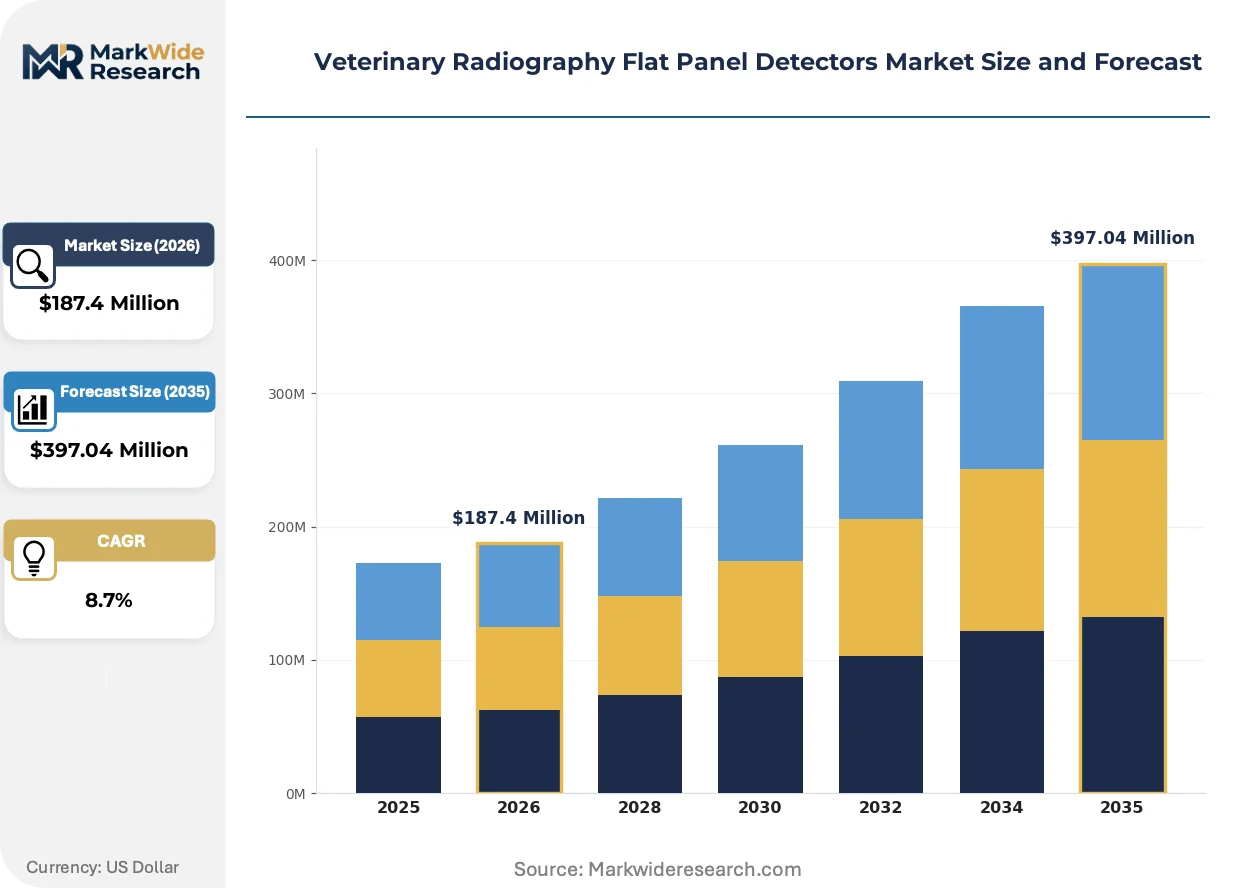
Market Dynamics
The veterinary radiography flat panel detector market is undergoing structural compression as large companion animal hospital chains consolidate purchasing power and demand standardized digital radiography fleets across multi-site networks.
Growth Catalysts
- ISO 13485 Manufacturing Standards:International quality management certification enables cross-border equipment distribution and accelerates vendor qualification for European and Asian markets.
- Interventional Veterinary Procedures:Rising fluoroscopy-guided surgeries in specialty clinics creates demand for real-time imaging detectors with high frame-rate capabilities.
- United States Hospital Consolidation:Corporate veterinary groups like Mars Veterinary Health and National Veterinary Associates standardize equipment procurement across hundreds of locations.
Market Restraints
- Cesium Iodide Scintillator Supply Concentration:Japanese and Korean material suppliers control thin-film deposition capacity, exposing detector manufacturers to input cost volatility and allocation constraints.
- EU Medical Device Regulation Conformity Costs:Extended notified body assessment timelines and clinical documentation requirements delay product launches and inflate regulatory overhead for European market entry.
- Computed Radiography Plate Substitutes:Existing CR systems in cost-sensitive mixed-animal practices delay full digital conversion despite detector performance advantages.
Strategic Opportunities
- Telemedicine-Enabled Teleradiology:Cloud-native detector platforms integrate with remote veterinary radiologist networks, opening subscription revenue models for equipment vendors.
- India Veterinary Infrastructure Expansion:Government livestock health programs and rising pet ownership in metropolitan corridors create first-mover advantages for affordable detector configurations.
- AI-Augmented Diagnostic Software Bundling:Algorithm-embedded flat panel systems that auto-detect fractures or pulmonary patterns command premium positioning and recurring license fees.
Industry Challenges
- Veterinary Radiography Technician Shortages:Limited accredited training programs in the United States and United Kingdom extend installation timelines and strain vendor field service organizations.
- Legacy PACS Integration Complexity:Heterogeneous software environments in acquired hospital chains demand costly middleware development for seamless detector-workflow connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Radiography Flat Panel Detectors Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray Detectors, Digital Detectors, Analog Detectors, Fluoroscopy Detectors End User: Veterinary Clinics, Animal Hospitals, Research Laboratories, Academic Institutions Technology: Flat Panel Technology, Computed Radiography, Direct Radiography, DR Systems Application: Diagnostic Imaging, Treatment Planning, Tissue Analysis, Surgical Assistance |
| Companies Covered | Varex Imaging Corporation, Canon, IDEXX Laboratories, DRGEM, Universal Medical, Trixell, FUJIFILM Holdings America Corporation, Agfa-Gevaert Group, Konica Minolta Business Solutions U.S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Radiography Flat Panel Detectors Market Evolving Landscape
Detector architecture is pivoting toward CMOS-based designs while regulatory frameworks recalibrate around software-enabled devices, reshaping competitive differentiation beyond hardware specifications alone.
Amorphous silicon flat panel technology dominated veterinary radiography for two decades due to manufacturing scale and cost efficiency. Specialty companion animal hospitals and university veterinary teaching hospitals now prioritize CMOS photodiode arrays for superior low-dose performance and faster readout speeds. CMOS-based detector platforms are supplanting legacy amorphous silicon installations in premium-tier replacements, compressing upgrade cycles and fragmenting vendor pricing power across performance tiers.
The FDA Center for Veterinary Medicine is scrutinizing AI-enabled diagnostic claims on imaging equipment with increasing rigor. Algorithm-augmented flat panel systems face reclassification risk as standalone software-as-medical-devices rather than accessories. North American detector manufacturers are responding by segregating hardware and software regulatory submissions, delaying integrated product launches but preserving compliance optionality.
Large veterinary hospital groups now unbundle equipment procurement from service contracts, pitting OEM service networks against independent imaging service organizations. Corporate buyers negotiate detector-only purchases with third-party maintenance agreements, eroding vendor captive service revenue. This disintermediation is most advanced in the United States, where national account purchasing teams extract 15-20% service discounts through competitive tendering.
Veterinary Radiography Flat Panel Detectors Market Segmentation
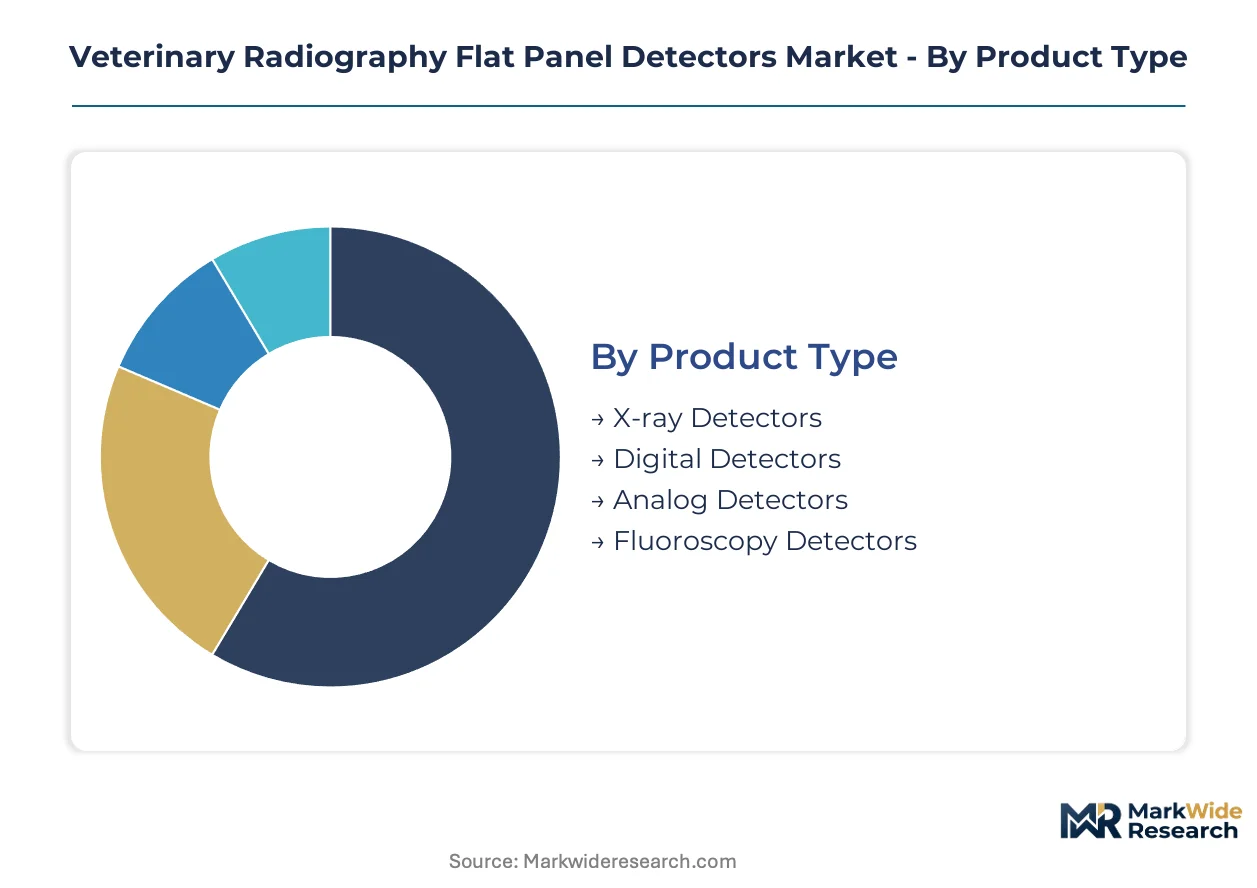
Veterinary radiography flat panel detector procurement channels diverge sharply by segment. Equipment vendors route premium CMOS-based systems through specialty distributors serving academic medical centers, while standard amorphous silicon configurations flow via direct sales teams to consolidated hospital chains.
Product Type:
Distribution channels align detector architecture with buyer sophistication and service intensity requirements.
- X-ray Detectors:Solid-state imagers employing cesium iodide scintillators coupled with thin-film transistor arrays. Demand concentrates in United States specialty veterinary clinics replacing legacy film systems as FDA calibration standards tighten.
- Digital Detectors:Direct-capture flat panel systems eliminating intermediate processing steps. Large companion animal hospital chains in North America standardize procurement across multi-site networks, driving replacement cycles in mature installed bases.
- Analog Detectors:Film-based capture systems with chemical processing requirements. Cost-sensitive mixed-animal practices in rural United States markets delay conversion despite digital performance advantages.
- Fluoroscopy Detectors:High frame-rate real-time imagers for interventional procedures. Specialty clinics performing orthopedic and cardiovascular surgeries generate fastest-expanding demand for motion-capable detector platforms.
Digital detectors dominate installed base. Fluoroscopy detectors are where expansion concentrates.
End User:
Customer type determines pricing tolerance, configuration complexity, and service contract structure.
- Veterinary Clinics:Small-to-midscale independent practices serving companion and mixed animal populations. Price sensitivity delays full digital conversion where computed radiography plates remain functional.
- Animal Hospitals:Large-scale facilities with dedicated imaging suites and anesthesia capabilities. Corporate veterinary groups in the United States extract volume discounts through national account purchasing teams.
- Research Laboratories:Customized high-resolution configurations for preclinical and translational studies. Superior margins reflect low-volume, high-specification procurement with extended validation protocols.
- Academic Institutions:University veterinary teaching hospitals requiring multi-modality integration and trainee accessibility. CMOS photodiode arrays gain preference for superior low-dose performance in educational settings.
Animal hospitals command largest volume commitment. Research laboratories yield superior margin profiles.
Technology:
Technology selection tracks buyer readiness for workflow integration and capital deployment timing.
- Flat Panel Technology:Amorphous silicon and CMOS photodiode array architectures with scintillator conversion layers. Specialty companion animal hospitals prioritize CMOS platforms for faster readout speeds in high-throughput environments.
- Computed Radiography:Photostimulable phosphor plate systems requiring laser scanning digitization. Mixed-animal practices defer replacement where CR infrastructure investment remains partially depreciated.
- Direct Radiography:Immediate digital capture without intermediate processing steps. United States hospital consolidation accelerates DR standardization across acquired network locations.
- DR Systems:Integrated detector-generator-software bundles with workflow automation. IDEXX Laboratories controls recurring revenue through captive software-imaging combinations.
Flat panel technology anchors current procurement. DR systems are climbing the fastest as bundled offerings disassemble component purchasing.
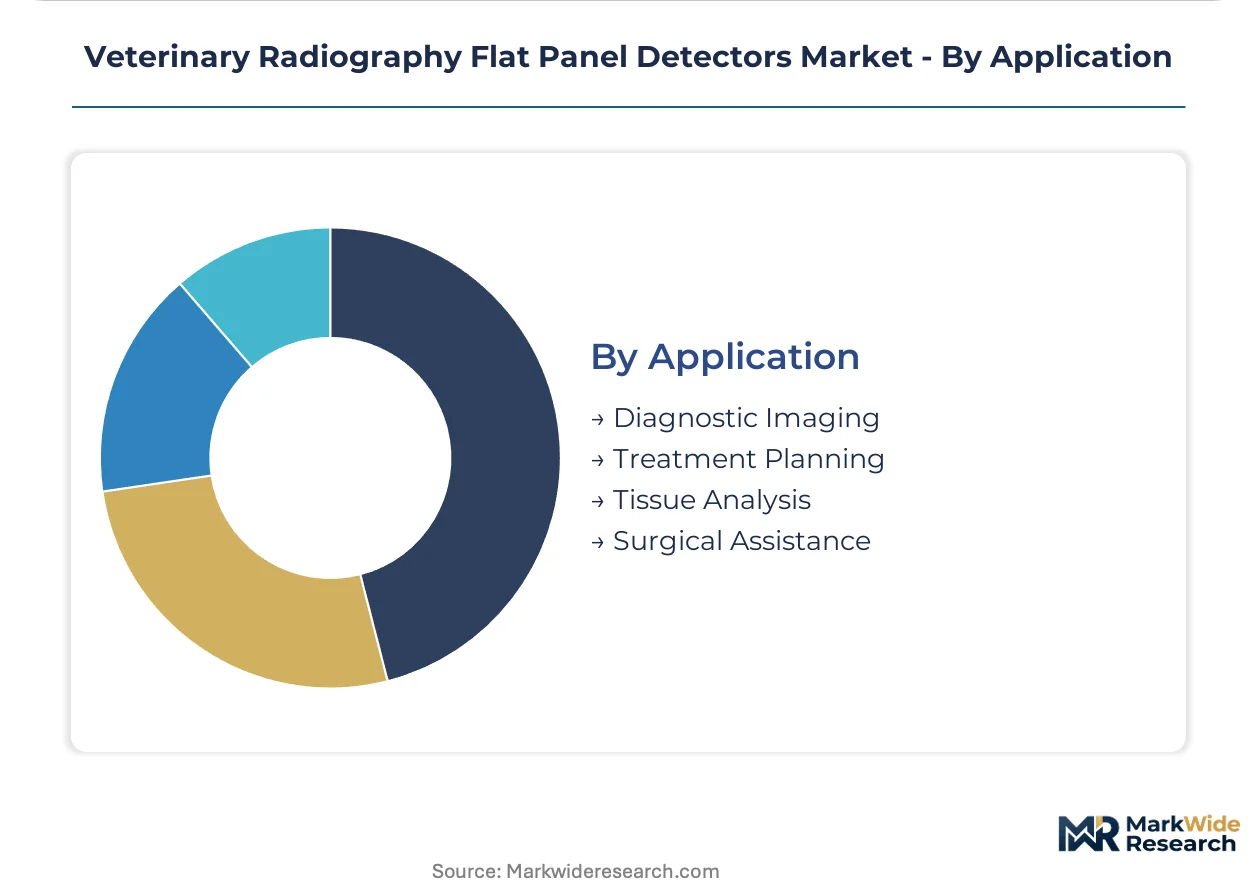
Application:
Application focus shapes detector specification requirements and service intensity.
- Diagnostic Imaging:Routine radiographic examination for trauma, respiratory, and abdominal assessment. Volume concentration in United States emergency and specialty practices drives standard detector configurations.
- Treatment Planning:Pre-procedural imaging for radiation therapy and surgical intervention. Customized high-resolution detectors serve oncology and orthopedic specialists requiring precise anatomical mapping.
- Tissue Analysis:High-magnification imaging for histopathological correlation and research protocols. Research laboratories in academic medical centers specify detectors with extended dynamic range.
- Surgical Assistance:Intraoperative and interventional fluoroscopy for real-time guidance. Rising fluoroscopy-guided procedures in specialty clinics creates demand for high frame-rate detector capabilities.
Diagnostic imaging retains largest procedure volume. Surgical assistance is gaining share fastest as interventional veterinary medicine expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States veterinary hospital chains extract 15-20% service discounts through competitive tendering, while European buyers absorb extended notified body assessment timelines that inflate regulatory overhead. This pricing-power asymmetry concentrates procurement leverage in North American corporate veterinary groups.
United States
Mars Veterinary Health and National Veterinary Associates standardize DR technology across hundreds of locations, consolidating equipment procurement into national account purchasing teams. FDA Center for Veterinary Medicine oversees device safety labeling and calibration standards for veterinary medical devices. Specialty companion animal hospitals in metropolitan corridors accelerate CMOS-based detector replacements.
Germany
University veterinary teaching hospitals prioritize multi-modality integration and trainee accessibility in detector specifications. EU Medical Device Regulation through notified bodies extends conformity assessment requirements, delaying product launches with clinical documentation demands. Industrial clusters in Baden-Württemberg host precision manufacturing suppliers serving detector scintillator deposition equipment.
Japan
Thin-film cesium iodide scintillator deposition capacity concentrates among Japanese material suppliers, exposing detector manufacturers to input cost volatility. METI industrial standards and PMDA quality frameworks govern manufacturing consistency for domestic and export markets. Tokyo-Osaka corridor hosts photodiode array foundries supplying CMOS sensor components.
United Kingdom
Veterinary radiography technician shortages extend installation timelines and strain vendor field service organizations across independent practices. ISO 13485 certification requirements enable cross-border distribution while UK-specific veterinary device regulations align with retained EU MDR provisions. Greater London specialty clinics drive premium-tier CMOS detector demand for orthopedic diagnostics.
India
Government livestock health programs and rising pet ownership in metropolitan corridors create first-mover advantages for affordable detector configurations. BIS standards and CDSCO device registration requirements establish quality benchmarks for imported veterinary imaging equipment. Maharashtra and Karnataka veterinary infrastructure expansion concentrates in Pune and Bangalore metropolitan areas.
Veterinary Radiography Flat Panel Detectors Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the veterinary radiography flat panel detector market. The vendor base stratifies into three tiers: imaging conglomerates with captive software platforms, semiconductor foundries with detector core scale, and regional equipment assemblers serving price-sensitive practices. Two dominant competitive moves are reshaping positioning: large hospital groups unbundle equipment from service contracts to pit OEM networks against independent service organizations, and manufacturers segregate hardware and software regulatory submissions to preserve compliance optionality around AI-enabled diagnostic claims.
Within the imaging technology tier, Varex Imaging Corporation and Canon occupy positions that exemplify divergent strategic archetypes—one leveraging flat panel foundry scale for cost leadership, the other anchoring premium positioning through proprietary sensor architectures. IDEXX Laboratories represents the integrated software-imaging bundle model, controlling workflow platforms that generate recurring service revenue. These three companies illustrate how competitive differentiation now extends beyond hardware specifications into software-enabled service ecosystems and regulatory compliance structures.
| Leading Market Players |
|---|
| Varex Imaging Corporation |
| Canon |
| IDEXX Laboratories |
| DRGEM |
| Universal Medical |
| Trixell |
| FUJIFILM Holdings America Corporation |
| Agfa-Gevaert Group |
| Konica Minolta Business Solutions U.S.A. |
| Others |
Value Network & Pricing Analysis
CMOS photodiode arrays displacing amorphous silicon architectures are redrawing procurement geography toward Japanese and Korean foundry clusters while compressing pricing premiums for legacy detector configurations. This substitution dynamic simultaneously elevates input cost volatility for scintillator materials and fragments vendor pricing power across performance tiers.
Pricing Analysis
The customization-premium spread between configured-to-order high-resolution detectors and standard amorphous silicon configurations spans three distinct pricing tiers based on CMOS sensor grade, ISO 13485 certification level, and after-sales service bundling. Pricing pressure stems from corporate veterinary groups unbundling equipment from service contracts to extract competitive discounts through third-party maintenance agreements. Small independent clinics exhibit highest price sensitivity and delay digital conversion where computed radiography plates remain functional, while research laboratories demonstrate lowest sensitivity due to extended validation protocols and low-volume procurement.
Supply Chain Analysis
Strategic stockpiling of cesium iodide scintillator materials dominates inventory strategy as Japanese and Korean suppliers control thin-film deposition capacity. Manufacturing draws from photodiode array foundries in Japan, scintillator deposition facilities in South Korea, and final assembly operations in the United States and Germany. Single-source vulnerability in specialty chemical inputs exposes detector manufacturers to allocation constraints and commodity price volatility. Distribution runs through specialty distributors serving academic medical centers and direct sales teams penetrating consolidated hospital chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The veterinary radiography flat panel detector market sits in cyclical recovery as replacement cycles accelerate in mature installed bases following pandemic-deferred capital expenditures.
For Market Incumbents: Secure captive scintillator supply through backward integration into thin-film deposition partnerships or long-term offtake agreements with Japanese material suppliers. Lock in software-imaging bundle control by accelerating AI-enabled diagnostic platform development ahead of FDA reclassification risk. Defend against independent service organization encroachment by embedding predictive maintenance telemetry into detector firmware. For New Entrants and Emerging Players: Lead with affordable CMOS-based configurations targeting India's government livestock health programs and metropolitan veterinary infrastructure expansion. Exploit white-space in teleradiology-enabled cloud-native platforms serving technician-shortage markets in the United Kingdom and United States rural corridors. Pursue veterinary radiologist network partnerships as primary go-to-market channel rather than competing head-to-head against established OEM direct sales. For Investors and Strategic Acquirers: FDA algorithm-augmented device reclassification reshapes the acquisition landscape by elevating software regulatory capability as primary diligence criterion. Long-term viability centers on vendors controlling workflow platform ecosystems rather than hardware-only manufacturers. Target acquisition archetypes combine detector core production scale with captive software development capacity. Watch for AI diagnostic software bundling penetration rates crossing threshold inflection in North American specialty clinic procurement as signal for platform consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Scintillator Supply Securement | Long-term offtake agreements with Japanese deposition facilities mitigate single-source raw material risk. |
| AI Software Companion Development | Algorithm-embedded detectors command premium positioning ahead of FDA regulatory reclassification. |
| Cloud-Native Platform Integration | Teleradiology-enabled systems open subscription revenue models through veterinary radiologist network partnerships. |
| CMOS Architecture Transition | Superior low-dose performance accelerates premium-tier replacement cycles in academic medical centers. |
| Third-Party Service Channel Partnership | Independent imaging service organization alliances address corporate buyer unbundling preferences. |
Research Methodology
The analysis maps detector architecture tiers, end-user procurement patterns, and regulatory compliance pathways, each validated through veterinary radiography equipment procurement managers, biomedical engineering directors at academic medical centers, and flat panel detector manufacturing executives. Primary interviews with GPO contracts managers and specialty clinic operations heads combined with secondary validation against FDA Center for Veterinary Medicine device registrations, ISO 13485 certification databases, and hospital capital expenditure records. Bottom-up installed base modeling and top-down market sizing triangulate volume estimates.
Consistency checks against external benchmarks validated projection outputs across the modeling period. Segmentation dimensions include product architecture, end-user facility type, technology generation, and application intensity. CAGRs derive from replacement cycle timing, procurement standardization trends in consolidated hospital networks, and fluoroscopy procedure growth trajectories. Industry-specific inputs incorporate veterinary radiography technician training pipeline constraints and AI diagnostic software regulatory pathway uncertainty.
Forecasts assume regulatory continuity in FDA Center for Veterinary Medicine oversight and EU Medical Device Regulation notified body assessment frameworks; material policy shifts would require re-modeling. Specific risk factors include cesium iodide supply allocation disruptions, AI-enabled device reclassification acceleration, and corporate veterinary group procurement centralization beyond current consolidation trajectories. Revision becomes warranted when fluoroscopy-guided procedure adoption crosses threshold penetration in specialty orthopedic and cardiovascular surgery practices.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intravascular Ultrasound [IVUS] Devices Market
Medical Devices
Contact Lens Lubricant Market
Medical Devices
South Africa Digital X-Ray Devices Market
Medical Devices
Australia Ultrasound Devices Market
Medical Devices
Anterior Cervical Fixation Devices Market
Medical Devices
Global Bioabsorbable Stents Market
Medical Devices
Vascular Guidewires Market
Medical Devices
Focused Ultrasound System Market
Medical Devices
Spinal Trauma Devices Market
Medical Devices
Bilirubin Meters Market
Medical Devices
Global Microdermabrasion Devices Market
Medical Devices
North America Single-Use Medical Device Reprocessing Market
Medical Devices
Transradial Closure Devices Market
Medical Devices
Wearable Bioelectronic Skin Patches Market
Medical Devices
Table-Top Autorefractor Market
Medical Devices
Sinus Implants Market