
 Global Microdermabrasion Devices Market | 2026-2036
Global Microdermabrasion Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microdermabrasion Devices Market Foresight
Equipment leasing and pay-per-use financing models are reshaping competitive access in the microdermabrasion devices sector, lowering capital barriers for mid-tier dermatology clinics and med spas. Koninklijke Philips leverages its hospital-grade manufacturing scale to supply multi-technology platforms that integrate mechanical exfoliation with LED therapy. Lumenis anchors its position through specialization in energy-based aesthetic systems with established service networks across North American and European clinical channels. Trophy Skin competes in the direct-to-consumer segment with compact diamond-tip devices that bypass traditional professional distribution.
Microdermabrasion devices mechanically or chemically abrade the stratum corneum using crystal streams, diamond-tipped wands, vacuum suction, or hydro-infusion systems to stimulate collagen production and enable topical penetration. Diamond microdermabrasion systems dominate professional settings due to precise tip gradation and eliminated crystal disposal requirements, while hydro microdermabrasion represents the fastest-expanding category as combination platforms merge exfoliation with serum infusion. Application demand clusters around skin rejuvenation and acne scar treatment, where repeat sessions generate recurring revenue streams for dermatology clinics and med spas. End-user procurement from plastic surgery centers commands premium pricing for multi-modality platforms that pair microdermabrasion with radiofrequency or oxygen infusion.
The FDA regulates microdermabrasion devices as Class I medical devices with escalating scrutiny on energy-based aesthetic systems that claim collagen remodeling outcomes. The EU Medical Device Regulation requires notified body certification for devices with suction pressures above specified thresholds, tightening market access for non-European manufacturers. ISO 13485 quality management standards shape supplier qualification protocols for institutional buyers across Japan and Australia. Stakeholders must monitor how regulatory divergence between the FDA and EMA on combination-device classifications will reshape product development roadmaps and geographic launch sequencing.
Market Dynamics
Equipment leasing and pay-per-use financing models are compressing capital barriers for mid-tier dermatology clinics and med spas, redistributing competitive access away from large hospital systems toward independent practice networks.
Growth Catalysts
- EU Medical Device Regulation (MDR):Stricter notified body certification requirements for suction-pressure thresholds are accelerating compliance investments among established manufacturers, filtering out marginal competitors and consolidating procurement toward certified suppliers.
- Diamond-tip precision systems:Elimination of crystal disposal liabilities and superior tip gradation control are pulling professional settings away from legacy aluminum oxide platforms.
- South Korean medical tourism infrastructure:K-beauty export channels and concentrated aesthetic clinic density are generating procurement pull that outpaces domestic demand growth in Western markets.
Market Restraints
- FDA Class I escalation risk:Evolving oversight of energy-based aesthetic systems claiming collagen remodeling outcomes is raising pre-market notification burdens and extending launch timelines for combination-device developers.
- Single-source vacuum pump dependency:German and Japanese precision pump manufacturers control critical subcomponent supply, exposing device assemblers to lead time volatility and input cost pressure.
- Intense pulsed light substitution:IPL platforms offering comparable superficial resurfacing with faster session throughput are capturing budget allocations in price-sensitive clinic segments.
Strategic Opportunities
- Brazilian aesthetic clinic expansion:ANVISA regulatory harmonization efforts and rising disposable income in São Paulo and Rio de Janeiro metro corridors are opening underpenetrated demand pockets for mid-range diamond systems.
- Hydro-infusion serum convergence:Combination platforms merging mechanical exfoliation with hyaluronic acid and peptide infusion are commanding premium positioning in med spa channels.
- Direct-to-consumer channel innovation:Compact diamond-tip devices bypassing professional distribution are capturing home-use spend from consumers seeking maintenance between clinical sessions.
Industry Challenges
- Biomedical engineer talent scarcity:Cross-functional expertise spanning vacuum system design, dermatological efficacy validation, and ISO 13485 quality management is concentrating among a narrow supplier base.
- Legacy EMR integration friction:Microdermabrasion session documentation protocols require custom API development to sync with established dermatology practice management platforms.
- Notified body queue congestion:EU MDR certification backlogs are extending time-to-market for suction-enabled devices above pressure thresholds, compressing revenue recognition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microdermabrasion Devices Market |
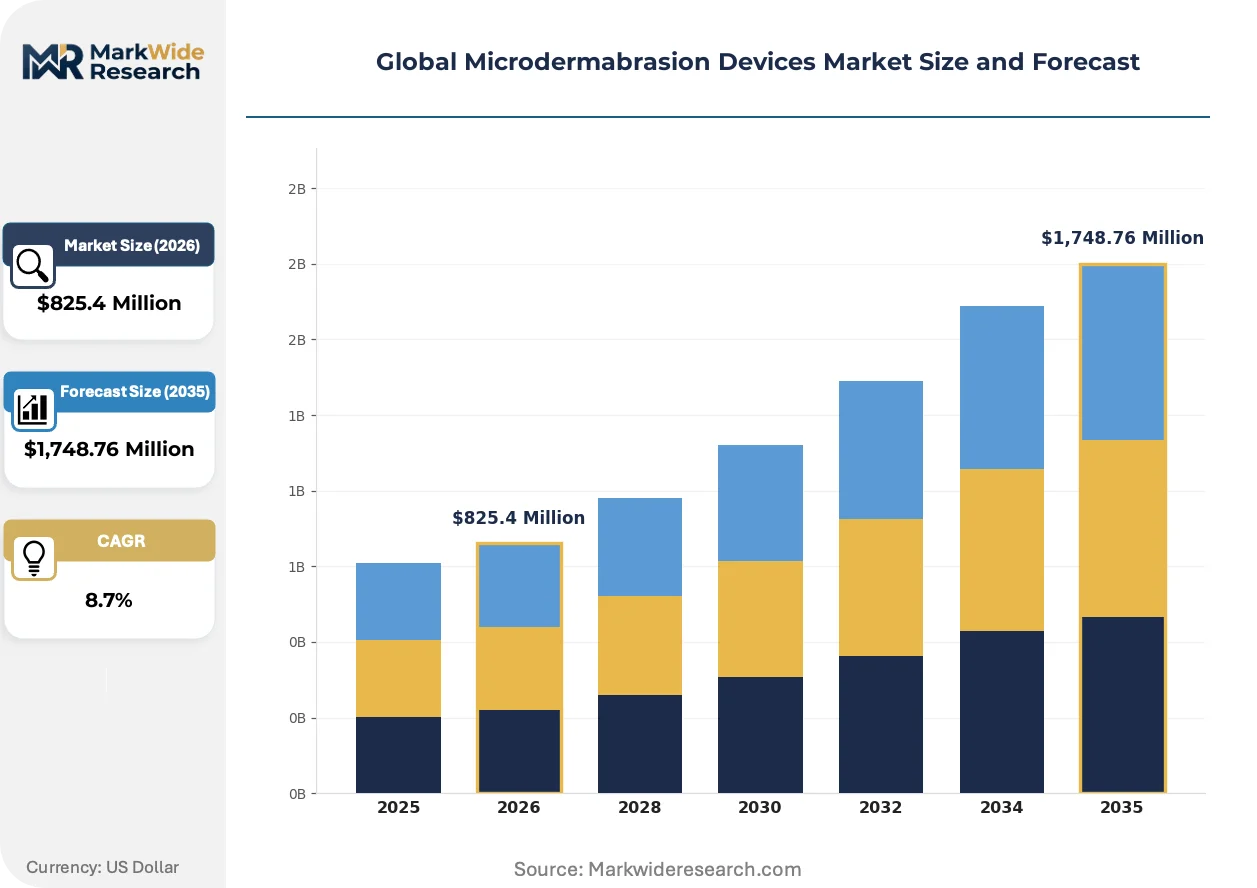
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,748.76 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystal Microdermabrasion, Diamond Microdermabrasion, Hydro Microdermabrasion, Ultrasonic Microdermabrasion, Vacuum Microdermabrasion Technology: Mechanical Exfoliation, Oxygen Infusion, LED Therapy, Sonophoresis, Radiofrequency Application: Acne Scar Treatment, Hyperpigmentation, Skin Rejuvenation, Wrinkle Reduction, Age Spot Removal End User: Dermatology Clinics, Med Spas, Plastic Surgery Centers, Cosmetic Salons, Wellness Centers |
| Companies Covered | Johnson & Johnson, Koninklijke Philips, Lumenis, Trophy Skin, Silhouet-Tone, Skin for Life, Altair Instruments, Dermaglow, PMD Beauty, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microdermabrasion Devices Market Shifts & Advancements
Connected device architectures and algorithmic treatment parameter optimization are redefining how clinical outcomes are standardized, shifting competitive differentiation from hardware specifications to data-driven protocol libraries.
Sensor-embedded diamond-tip handpieces with real-time pressure feedback and session logging are digitizing treatment documentation for malpractice defense and outcome tracking. Dermatology clinics in the United States and Germany are piloting these systems to justify repeat session recommendations with objective stratum corneum depth metrics. This capability is compressing liability insurance premiums for early adopters while creating switching costs tied to historical patient data repositories.
Japan's PMDA and Australia's TGA are tightening adverse event reporting requirements for vacuum-suction aesthetic devices, forcing manufacturers to maintain post-market surveillance infrastructure that smaller competitors cannot sustain. The regulatory burden is concentrating market access among firms with established pharmacovigilance departments. Multi-modality platform developers are responding by segregating microdermabrasion modules into standalone Class I registrations to isolate compliance risk.
Subscription-based consumable replenishment programs are displacing traditional distributor stocking models in North American med spa channels. Device manufacturers are capturing recurring revenue through locked-tip authentication systems that block third-party diamond consumables. California and Texas aesthetic clinic chains are consolidating vendor relationships around suppliers offering integrated financing, training, and consumable logistics, compressing independent distributor margins.
Global Microdermabrasion Devices Market Segmentation
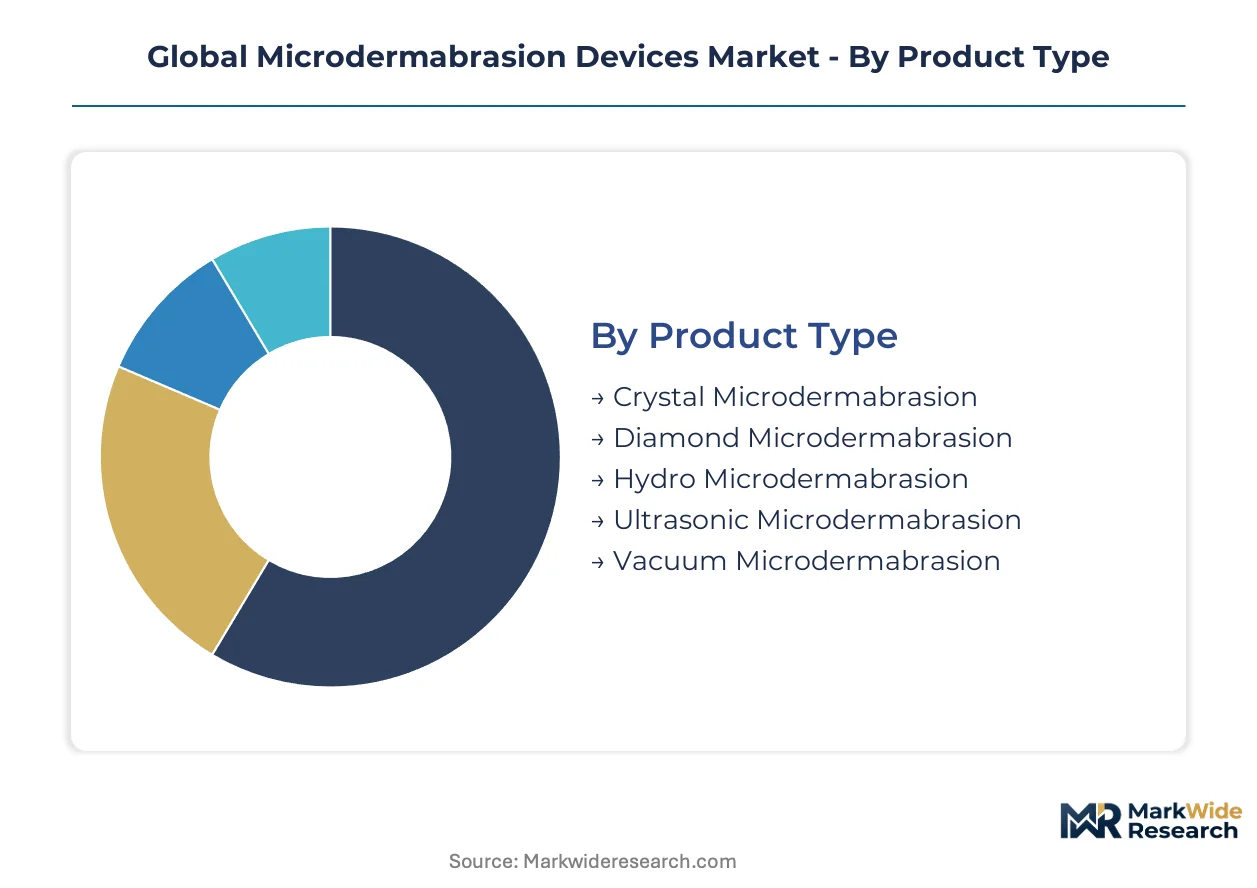
Segmentation in microdermabrasion devices reflects divergent clinical workflows, capital constraints, and outcome expectations across professional settings. Product architecture and technology integration choices determine reimbursement pathways, regulatory classification, and consumable revenue potential.
Product Type:
Mature mechanical systems dominate installed base volumes while emerging fluid-based platforms reshape premium positioning.
- Diamond Microdermabrasion:Precision-graded tip systems eliminate crystal disposal liabilities and enable controlled stratum corneum depth targeting. Dermatology clinics in Germany and the United States prioritize these platforms for malpractice defensibility and standardized outcome documentation.
- Hydro Microdermabrasion:Combination platforms merge vacuum suction with serum infusion capabilities, commanding premium pricing in med spa channels seeking differentiation through simultaneous exfoliation and hydration delivery.
- Crystal Microdermabrasion:Legacy aluminum oxide stream systems retain cost-sensitive salon penetration but face regulatory pressure around inhalation exposure protocols.
- Ultrasonic Microdermabrasion:High-frequency vibration systems target sensitive skin applications with reduced erythema recovery times.
- Vacuum Microdermabrasion:Suction-only modalities serve entry-level clinic segments with minimal consumable requirements.
Diamond systems retain volume leadership; hydro platforms hold the steepest expansion curve.
Technology:
Technology stacking determines device classification thresholds and service revenue attach rates across end-user tiers.
- Mechanical Exfoliation:Core abrasive functionality using diamond tips or crystal streams constitutes the baseline Class I regulatory pathway with minimal pre-market notification burden.
- Radiofrequency:Thermal collagen remodeling modules escalate FDA scrutiny to Class II clearance requirements while enabling premium pricing in plastic surgery centers.
- LED Therapy:Photobiomodulation add-ons extend session value with minimal incremental hardware cost.
- Oxygen Infusion:Post-exfoliation serum delivery systems capture recurring consumable revenue in med spa channels.
- Sonophoresis:Ultrasonic penetration enhancement targets professional settings seeking topical delivery differentiation.
Mechanical exfoliation anchors installed base economics; radiofrequency integration commands the highest per-session pricing premium.
Application:
Clinical indication focus shapes device specification requirements and repeat visit scheduling protocols.
- Skin Rejuvenation:Generalized photodamage and texture improvement applications generate the highest session frequency with predictable 4-6 week recurrence intervals driving recurring revenue.
- Acne Scar Treatment:Boxcar and rolling scar subtypes require aggressive tip gradation and extended treatment courses, concentrating demand in dermatology clinics with physician oversight.
- Wrinkle Reduction:Periorbital and perioral fine line targeting pulls demand toward combination platforms with radiofrequency thermal delivery.
- Hyperpigmentation:Melasma and post-inflammatory pigmentation protocols favor hydro systems with tyrosinase inhibitor infusion capabilities.
- Age Spot Removal:Solar lentigines respond to focused mechanical abrasion with shorter treatment courses than scar revision.
Skin rejuvenation sustains the broadest addressable patient base; acne scar treatment commands the longest revenue capture per patient journey.
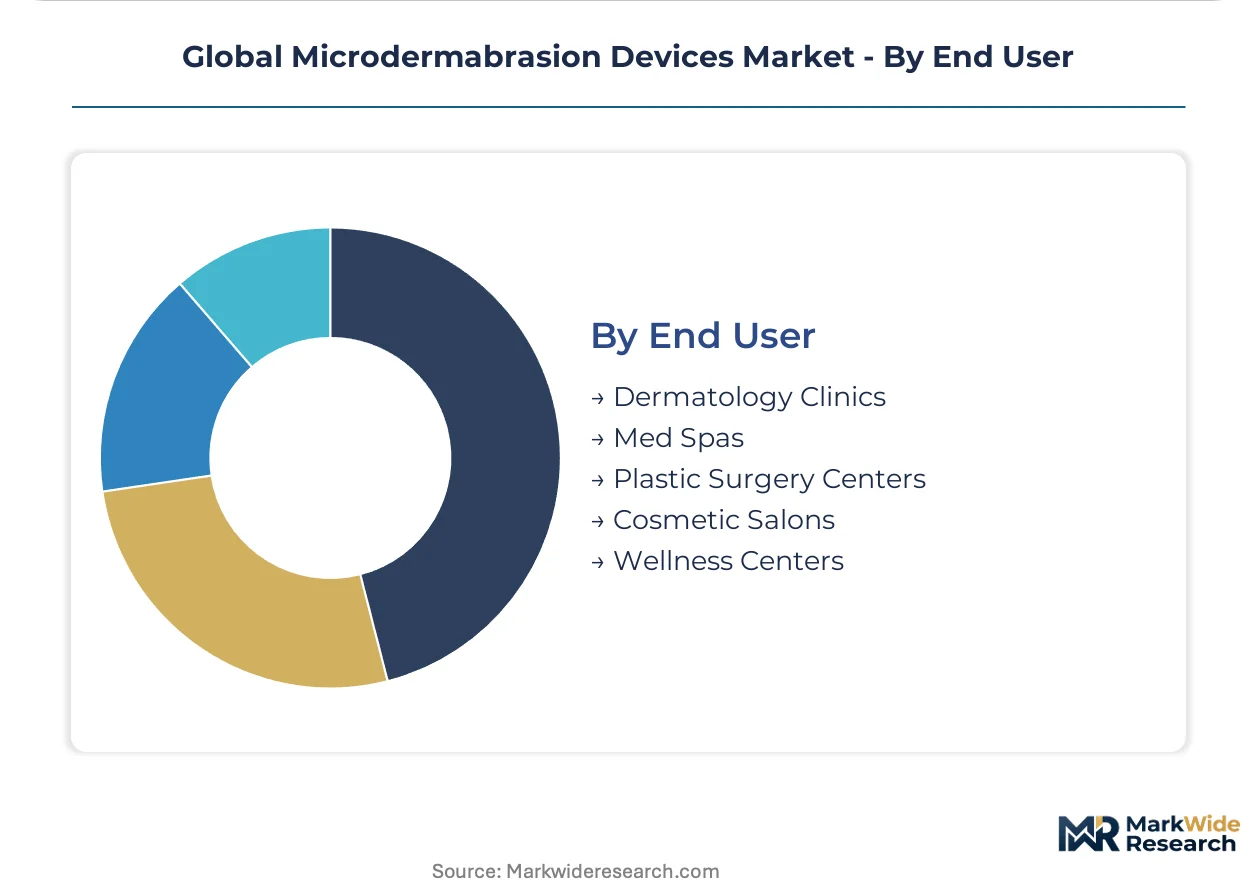
End User:
Capital availability and regulatory tolerance stratify procurement specifications across practice types.
- Dermatology Clinics:Physician-supervised settings demand FDA-cleared platforms with comprehensive liability documentation and EMR integration capabilities for outcome tracking.
- Med Spas:Non-physician operated facilities prioritize combination platforms with intuitive interfaces and manufacturer-provided training certification programs.
- Plastic Surgery Centers:Hospital-affiliated practices specify multi-modality systems integrating microdermabrasion with energy-based tightening for comprehensive pre- and post-operative protocols.
- Cosmetic Salons:Unlicensed aesthetic venues drive demand for compact, lease-friendly diamond systems with minimal maintenance requirements.
- Wellness Centers:Holistic health facilities seek hydro platforms aligned with natural skincare positioning and minimal downtime marketing.
Dermatology clinics concentrate premium procurement volume; med spas are expanding installed base most aggressively through financing-enabled access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes cluster around three poles: hospital-affiliated dermatology networks in the United States, medical tourism aggregators in South Korea, and independent med spa chains in Germany. Each geography imposes distinct regulatory entry costs and procurement financing norms.
United States
Dermatology clinic consolidation in Texas and Florida drives bulk procurement of multi-modality platforms. FDA Class I medical device oversight escalates scrutiny for energy-based systems claiming collagen remodeling. The Dallas-Fort Worth metro corridor hosts dense clusters of physician-owned practices negotiating enterprise pricing.
Germany
Med spa chains in Bavaria and North Rhine-Westphalia prioritize lease-friendly diamond systems with ISO 13485 certification. EU MDR notified body requirements for suction-pressure thresholds filter out non-European suppliers. Munich's aesthetic device distribution hub channels inventory into Central European markets.
South Korea
Medical tourism infrastructure in Seoul and Busan generates concentrated procurement pull for combination hydro-infusion platforms. MFDS device registration aligns with K-beauty export channel requirements. Gangnam's aesthetic clinic density exceeds any comparable global cluster.
Brazil
ANVISA regulatory harmonization efforts unlock mid-range diamond system demand in São Paulo and Rio de Janeiro metro corridors. Rising disposable income expands addressable patient bases beyond legacy salon channels. The Southeast region concentrates installed base growth.
Japan
PMDA adverse event reporting requirements for vacuum-suction devices concentrate market access among established pharmacovigilance-capable suppliers. Tokyo and Osaka dermatology clinics pilot sensor-embedded handpieces for outcome documentation. Post-market surveillance infrastructure creates compliance moats.
Global Microdermabrasion Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. The vendor base stratifies between hospital-grade manufacturers with service networks and compact-device specialists targeting direct-to-consumer bypass. Three archetypes dominate: diversified health technology conglomerates, energy-based aesthetic system specialists, and home-use device innovators. Competitive moves center on locked-tip consumable authentication and subscription-based replenishment programs displacing traditional distributor stocking.
Among diversified health technology conglomerates, Koninklijke Philips occupies a position exemplifying hospital-grade manufacturing scale applied to multi-technology platforms. Lumenis represents the energy-based aesthetic system specialist archetype with established service infrastructure. Trophy Skin anchors the direct-to-consumer compact device tier. Each exemplifies distinct channel control strategies rather than overlapping competitive terrain.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Koninklijke Philips |
| Lumenis |
| Trophy Skin |
| Silhouet-Tone |
| Skin for Life |
| Altair Instruments |
| Dermaglow |
| PMD Beauty |
| Others |
Supply & Pricing Matrix
Munich's precision manufacturing cluster anchors European vacuum pump supply, concentrating input cost leverage among German and Japanese subcomponent suppliers while downstream device assemblers absorb lead time volatility through contract escalation clauses.
Pricing Analysis
Certification level creates the primary spread between premium FDA-cleared multi-modality platforms and economy-tier salon devices. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 quality grade, after-sales service bundling, and geographic delivery cost. Cost compression in the mid-tier segment is intensifying because locked-tip authentication systems block third-party consumables and force recurring revenue capture. Med spa chains exhibit highest price sensitivity due to financing-enabled procurement, while plastic surgery centers show lowest sensitivity given per-session pricing premiums.
Supply Chain Analysis
German and Japanese export-control regimes on precision vacuum technology limit component flows to non-certified device assemblers, concentrating supply access among established manufacturers. Manufacturing draws from Germany, Japan, and South Korea for vacuum pumps, diamond-tip consumables, and sensor-embedded handpieces. Single-source dependency on precision pump manufacturers creates structural vulnerability to lead time volatility. Distribution runs through manufacturer-direct service networks and consolidated med spa chain contracts, compressing independent distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The microdermabrasion devices market sits in early-cycle expansion as hydro-infusion combination platforms penetrate med spa channels and financing models compress capital barriers for independent clinics.
For Market Incumbents: Insulate service revenue through locked-tip authentication systems that block third-party diamond consumables and capture recurring replenishment spend. Deepen backward integration into precision vacuum pump supply to reduce single-source dependency on German and Japanese manufacturers. Accelerate FDA 510(k) clearance timelines for energy-based combination modules before Class II escalation tightens pre-market notification burdens. For New Entrants and Emerging Players: Brazilian aesthetic clinic density in São Paulo and Rio de Janeiro metro corridors offers underpenetrated white-space for mid-range diamond systems ahead of ANVISA regulatory harmonization completion. Direct-to-consumer compact devices bypassing professional distribution capture home-use maintenance spend between clinical sessions. Partner with subscription-based financing platforms to lower capital barriers for independent dermatology practices. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified health technology conglomerates with hospital-grade manufacturing scale and established service networks over pure-play device specialists. Long-term viability hinges on pharmacovigilance infrastructure sustainability under tightening PMDA and TGA adverse event reporting requirements. Watch EU MDR notified body queue congestion as inflection indicator for time-to-market compression among suction-enabled device developers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR notified body certification unlocks Central European med spa procurement channels. |
| Hospital System Partnership | Enterprise pricing agreements with Texas and Florida dermatology networks secure bulk volume commitments. |
| Software Companion Development | Sensor-embedded handpieces with real-time pressure feedback digitize outcome documentation for malpractice defense. |
| Reimbursement Strategy | Protocol libraries demonstrating objective stratum corneum depth metrics justify repeat session recommendations. |
| FDA Submission | Class I medical device registration with isolated microdermabrasion modules reduces compliance risk from energy-based combination claims. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR notified body certifications, and hospital procurement databases. Interviews with biomedical engineers, dermatology clinic purchasing committees, GPO contracts managers, and med spa operations directors informed demand-side validation. Top-down market sizing triangulates against bottom-up installed base estimates across professional and direct-to-consumer channels.
Forecast inputs include technology adoption curves for hydro-infusion platforms, financing penetration rates among independent clinics, and regulatory timeline assumptions across the analysis window. Segmentation models capture product type, technology stack, clinical application, and end-user tier with geographic clustering by country-specific regulatory frameworks. CAGRs derive from procedure volume growth, device replacement cycles, and consumable attach rate projections.
Macroeconomic conditions sit as an overlay; deviation in aesthetic discretionary spending, medical tourism flows, and clinic capital expenditure cycles would shift the trajectory. Forecasts reflect assumptions around EU MDR certification throughput, FDA classification stability, and vacuum pump supply continuity. Material shifts in regulatory divergence between FDA and EMA on combination-device classifications would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Traumatic Brain Injury Assessment and Management Devices Market
Medical Devices
Global Hemorrhoid Treatment Devices Market
Medical Devices
Germany Spinal Surgery Devices Market
Medical Devices
Global Operating Microscopes Market
Medical Devices
Urology Guidewires Market
Medical Devices
Global Pathological Microscopes Market
Medical Devices
Global Casting Devices Market
Medical Devices
Acellular Dermal Matrix Market
Medical Devices
Centrifugation-Free Sperm Separation Systems Market
Medical Devices
Medical Electronics Market
Medical Devices
Arteriosclerosis Detector Market
Medical Devices
Electric Acupuncture Devices Market
Medical Devices
Hearing Aid Dehumidifier Market
Medical Devices
North America Smart Medical Devices Market
Medical Devices
Cystic Fibrosis Devices Market
Medical Devices
Muscle Stimulation Devices Market