
 Australia Veterinary Healthcare Market | 2026-2036
Australia Veterinary Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Veterinary Healthcare Market Outlook
Biologic active ingredients are replacing traditional small-molecule formulations across companion animal therapeutics, which is expanding product economics for manufacturers serving the premium pet segment. Zoetis Inc leverages its biologics manufacturing infrastructure to sustain competitive positioning in vaccine development. Elanco Animal Health anchors its portfolio through parasiticide specialization for livestock and companion species. IDEXX Laboratories dominates diagnostic instrumentation with automated hematology and chemistry platforms deployed across Australian veterinary clinics.
Australia veterinary healthcare encompasses the prevention, diagnosis, and treatment of disease in companion animals, livestock, and wildlife through pharmaceuticals, biological products, medical devices, and clinical services. Veterinary pharmaceuticals require TGA registration under the Australian Pesticides and Veterinary Medicines Authority joint framework, with stability testing mandated at 25°C/60% relative humidity for shelf-life determination. Pharmaceuticals command the largest revenue share among product types due to chronic disease management in aging pet populations. Diagnostic services represent the fastest-expanding application segment as point-of-care testing platforms reduce referral dependency for general practitioners. Online retail channels capture accelerating volume as pet owners replenish parasite preventives through subscription models between clinic visits.
TGA registration requirements and APVMA chemical review processes govern market access timelines for new veterinary actives entering Australia. The Australian Veterinary Association's clinical practice standards influence equipment procurement decisions across independent and corporate clinic networks. Stakeholders must monitor regulatory harmonization discussions between TGA and international reference agencies that could compress registration lag for novel biologics.
Market Dynamics
Pet owner expenditure on preventive diagnostics is compressing treatment timelines and elevating the economic weight of early-stage disease detection across Australian veterinary practices.
Growth Catalysts
- Companion animal aging demographics:Extended pet lifespans are expanding chronic disease management requirements and sustaining pharmaceutical consumption cycles.
- TGA-APVMA harmonization discussions:Regulatory alignment with international reference agencies is accelerating biologic registration pathways for novel vaccines.
- Point-of-care instrumentation:Automated hematology platforms are reducing referral dependency and capturing diagnostic revenue within general practice clinics.
Market Restraints
- Active ingredient supply concentration:Biologic API manufacturing clusters in North American and European contract facilities expose Australian formulators to shipping bottlenecks and cold-chain integrity risks.
- TGA stability testing mandates:The 25°C/60% relative humidity shelf-life determination protocol extends registration timelines for thermally sensitive formulations.
- Specialist veterinary labor scarcity:Credentialing bottlenecks in diagnostic imaging and surgery constrain service capacity expansion in New South Wales and Victoria.
Strategic Opportunities
- Subscription-based parasite prevention:Online retail channels are capturing recurring revenue through automated replenishment models between clinic visits.
- Wildlife disease surveillance integration:Biosecurity mandates are creating procurement pathways for veterinary diagnostic services within government conservation programs.
- Biologic manufacturing infrastructure:Domestic fill-finish capacity investment would compress import dependency for temperature-sensitive vaccine doses.
Industry Challenges
- Veterinary technician training pipeline gaps:TAFE and university program throughput is failing to match clinic network expansion rates in metropolitan corridors.
- Legacy practice management system integration:Independent clinics face data migration friction when adopting cloud-based diagnostic platform connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Veterinary Healthcare Market |
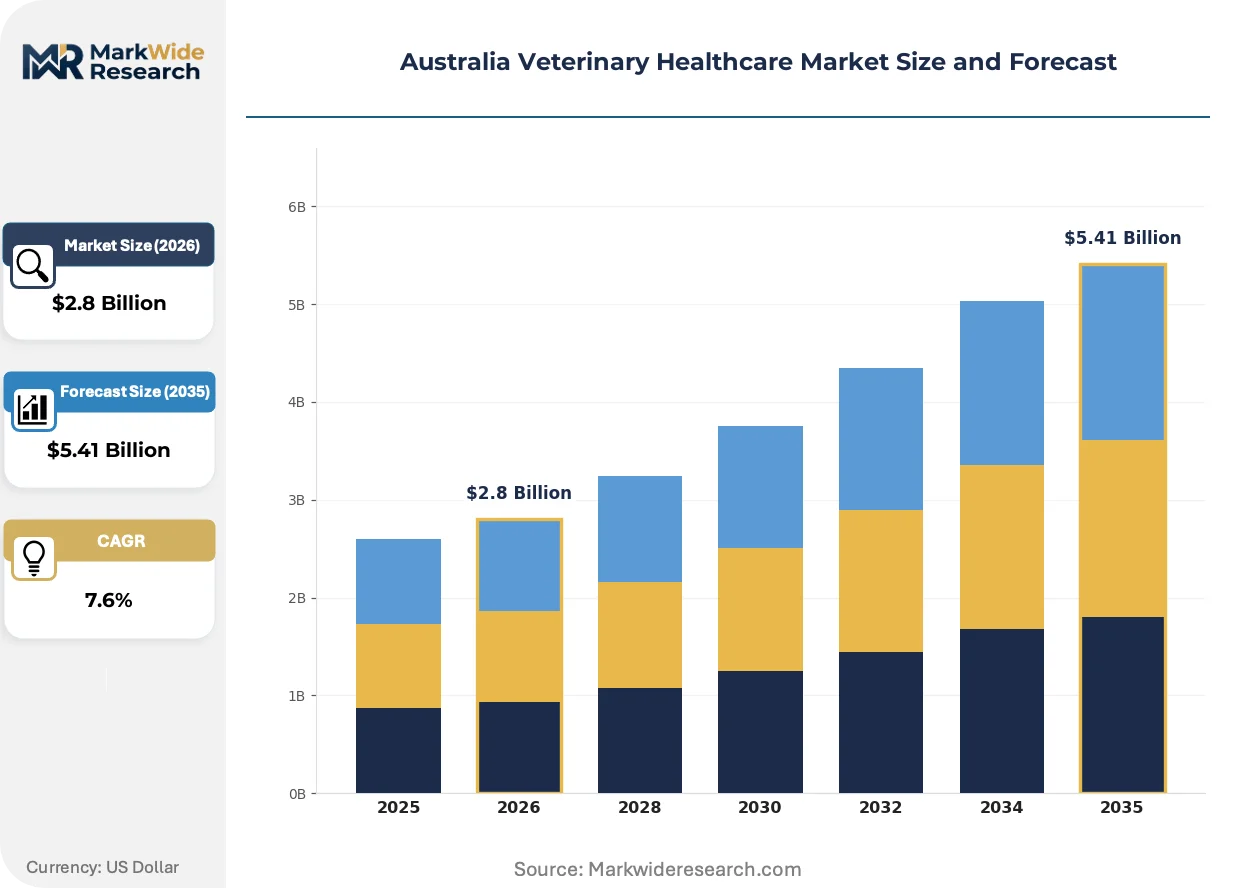
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Vaccines, Nutraceuticals, Medical Devices End User: Pet Owners, Veterinarians, Animal Hospitals, Research Institutions Application: Preventive Care, Surgical Treatment, Diagnostic Services, Emergency Care Distribution Channel: Online Retail, Veterinary Clinics, Pharmacies, Distributors |
| Companies Covered | Elanco Animal Health, IDEXX Laboratories, Zoetis Inc, Covetrus, Dechra Pharmaceuticals, Merck & Co. Inc., Virbac, Greencross Ltd, Boehringer Ingelheim Animal Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Veterinary Healthcare Market Strategic Shifts
Diagnostic workflow automation and biologic formulation advances are restructuring how Australian veterinarians capture value from preventive care relationships.
Point-of-care chemistry analyzers is modularizing laboratory infrastructure by embedding multiplex testing capability directly within general practice settings. Regional clinic networks in Queensland and Western Australia are deploying these units to retain pathology revenue previously lost to centralized reference laboratories. This distributed architecture is compressing diagnostic turnaround from days to minutes.
TGA's veterinary medicine registration framework is tightening evidentiary standards for novel biologic actives entering the Australian market. The APVMA chemical review process now demands expanded environmental fate data for parasiticide formulations used in livestock applications. Companion animal vaccine developers are responding by front-loading stability documentation to preempt regulatory queries.
Pet owner purchasing patterns are fragmenting across physical and digital channels as subscription models displace single-transaction parasite prevention purchases. Veterinary clinics in Victoria are unbundling preventive product sales from consultation services to compete with online retailers. This channel diversification is most pronounced in urban corridors where same-day delivery logistics have matured.
Australia Veterinary Healthcare Market Segmentation
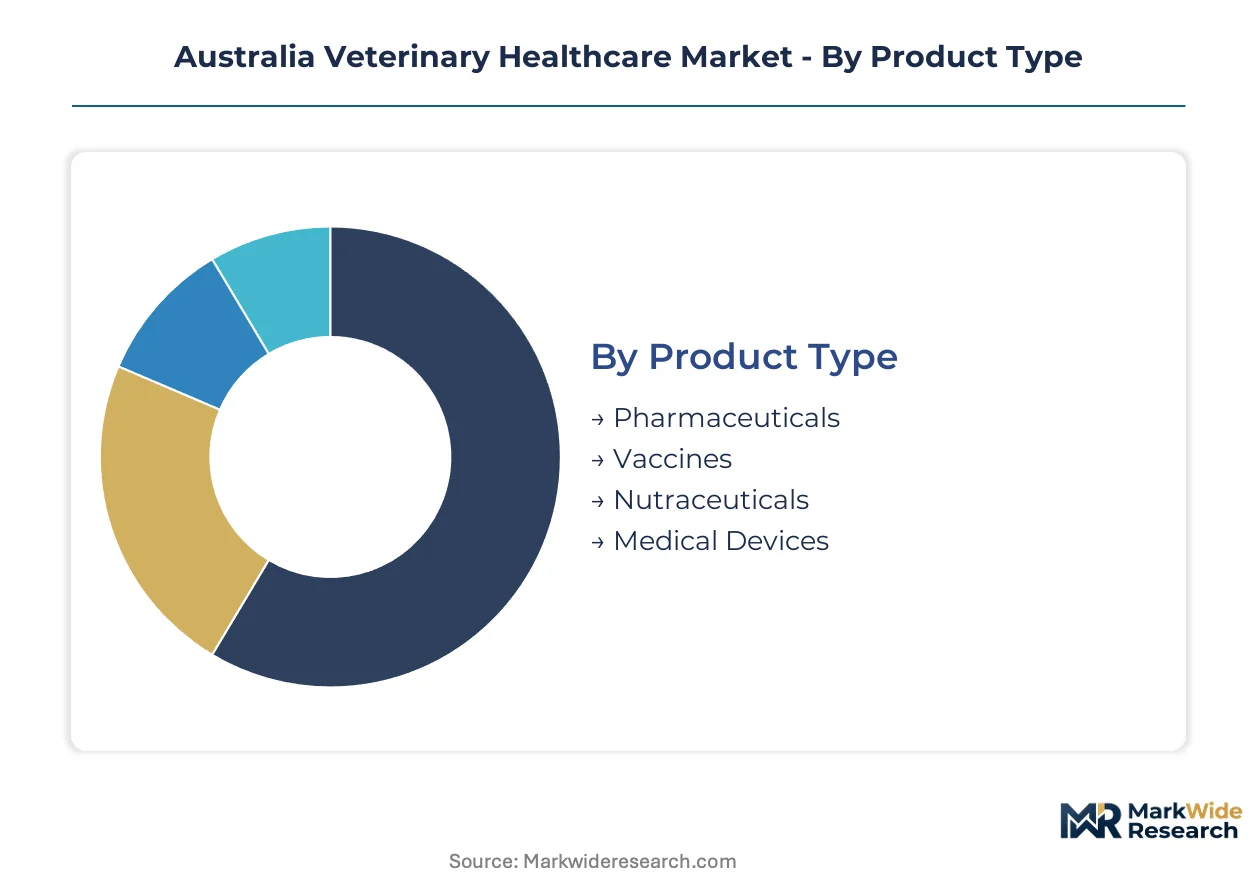
Segmentation in Australian veterinary healthcare reveals how product economics, service delivery models, and channel preferences diverge across companion animal and livestock applications. Understanding these splits enables stakeholders to align manufacturing capacity, clinical training investments, and distribution partnerships with where expenditure is actually concentrating.
Product Type:
Standardization dominates commodity parasiticides while biologics demand bespoke cold-chain infrastructure and stability documentation under TGA guidelines.
- Pharmaceuticals:Small-molecule formulations for chronic disease management in aging companion animals require shelf-life validation at 25°C/60% relative humidity per TGA mandates. Demand concentrates in New South Wales and Victoria where specialist hospital networks sustain prescription volumes for cardiometabolic and renal therapeutics.
- Vaccines:Temperature-sensitive biologic doses for core companion animal immunization and livestock disease prevention depend on imported API fill-finish capacity with domestic distribution networks managing last-mile cold integrity. TGA-APVMA harmonization discussions are compressing registration timelines for novel platform technologies.
- Nutraceuticals:Dietary supplements targeting joint health and dermatological conditions in premium pet segments bypass prescription requirements while competing for shelf space in veterinary clinic retail zones.
- Medical Devices:Surgical instrumentation and patient monitoring equipment procurement cycles track corporate clinic network expansion rates across metropolitan corridors.
Most installed capacity flows through Pharmaceuticals. Expansion is steepest in Vaccines.
End User:
Customer sophistication tiers separate price-sensitive transactional purchasers from relationship-driven preventive care adopters with divergent service expectations.
- Pet Owners:Direct-to-consumer expenditure on diagnostics and therapeutics is fragmenting across physical clinic visits and subscription-based online replenishment models for parasite prevention products.
- Veterinarians:General practitioners in independent and corporate practice settings drive point-of-care instrumentation procurement decisions while specialist credentialing bottlenecks constrain service capacity in diagnostic imaging and surgery.
- Animal Hospitals:Corporate networks in New South Wales and Victoria concentrate capital equipment investment in automated hematology and chemistry platforms to capture diagnostic revenue previously referred to centralized laboratories.
- Research Institutions:Wildlife disease surveillance mandates under biosecurity protocols create procurement pathways for veterinary diagnostic services within government conservation programs.
Revenue concentration sits with Animal Hospitals. Pet Owners are gaining share fastest through channel diversification.
Application:
Service intensity and margin profiles vary sharply between scheduled preventive relationships and acute intervention episodes with unpredictable resource demands.
- Preventive Care:Vaccination schedules and parasite prevention protocols generate recurring consultation revenue while establishing pharmaceutical consumption cycles across pet lifespans.
- Surgical Treatment:Orthopedic and soft-tissue procedures require specialist labor availability that credentialing pipeline gaps restrict in high-demand metropolitan corridors.
- Diagnostic Services:Point-of-care testing platforms are reducing referral dependency for general practitioners and capturing pathology revenue within clinic walls through distributed analyzer deployment.
- Emergency Care:After-hours service provision depends on 24-hour hospital network density concentrated in Sydney and Melbourne metropolitan zones.
Preventive Care anchors installed service capacity. Diagnostic Services are climbing the fastest as instrumentation modularizes laboratory infrastructure.
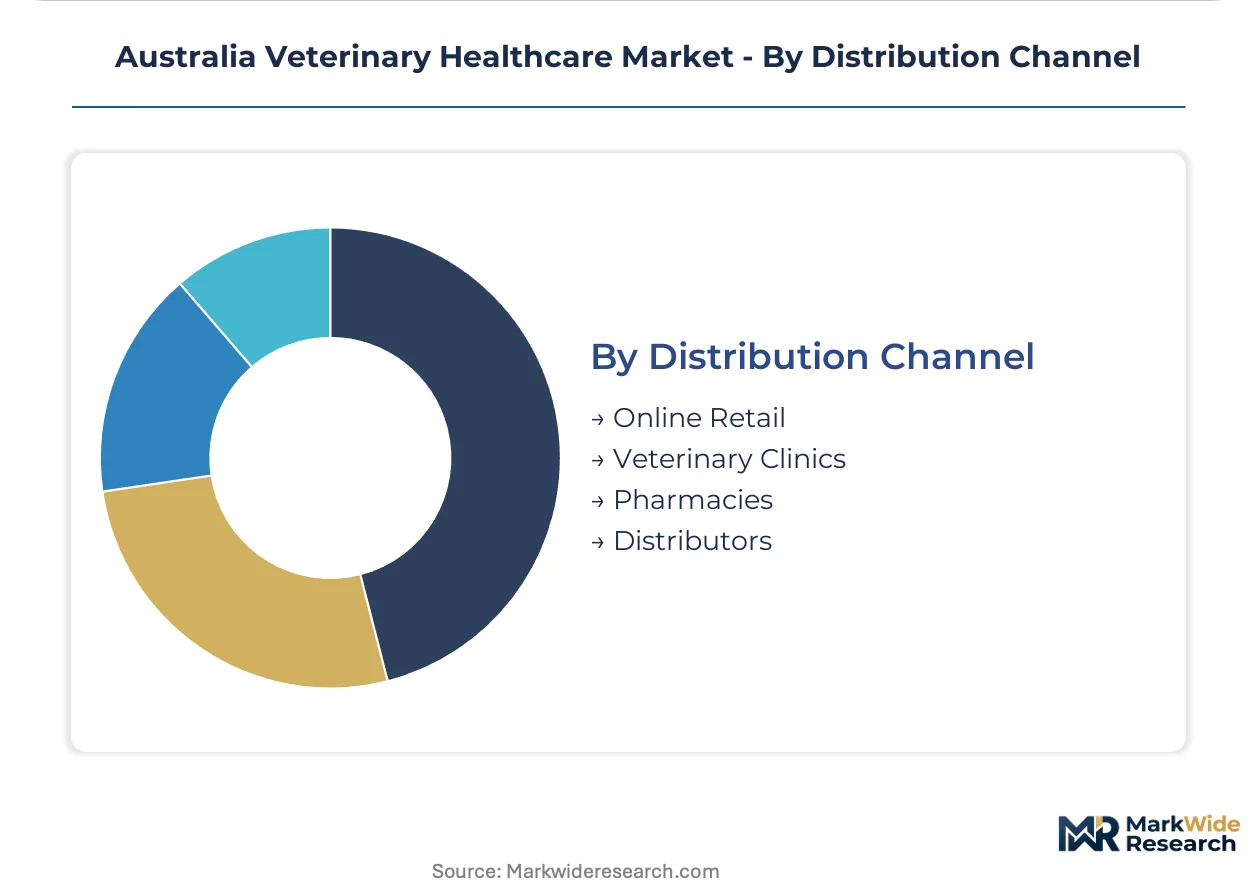
Distribution Channel:
Channel economics diverge between high-touch clinical consultation bundling and low-friction digital replenishment with divergent customer acquisition costs.
- Online Retail:Subscription models for parasite preventives capture recurring revenue between clinic visits, with same-day delivery logistics maturing in urban Victorian corridors enabling competitive positioning against traditional veterinary dispensing.
- Veterinary Clinics:Physical consultation settings retain therapeutic dispensing for prescription-required pharmaceuticals while unbundling preventive product sales to compete with digital channels.
- Pharmacies:Community pharmacy networks participate in limited companion animal product categories with restricted prescription authority under TGA frameworks.
- Distributors:Wholesale intermediaries manage inventory and cold-chain logistics for temperature-sensitive biologics between manufacturers and clinical endpoints.
Veterinary Clinics still channel the majority of product flows. Online Retail shows the steepest expansion trajectory as pet owner purchasing patterns fragment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sydney and Melbourne veterinary hospital networks concentrate specialist diagnostic capacity and pharmaceutical dispensing volume across the Australian market.
New South Wales
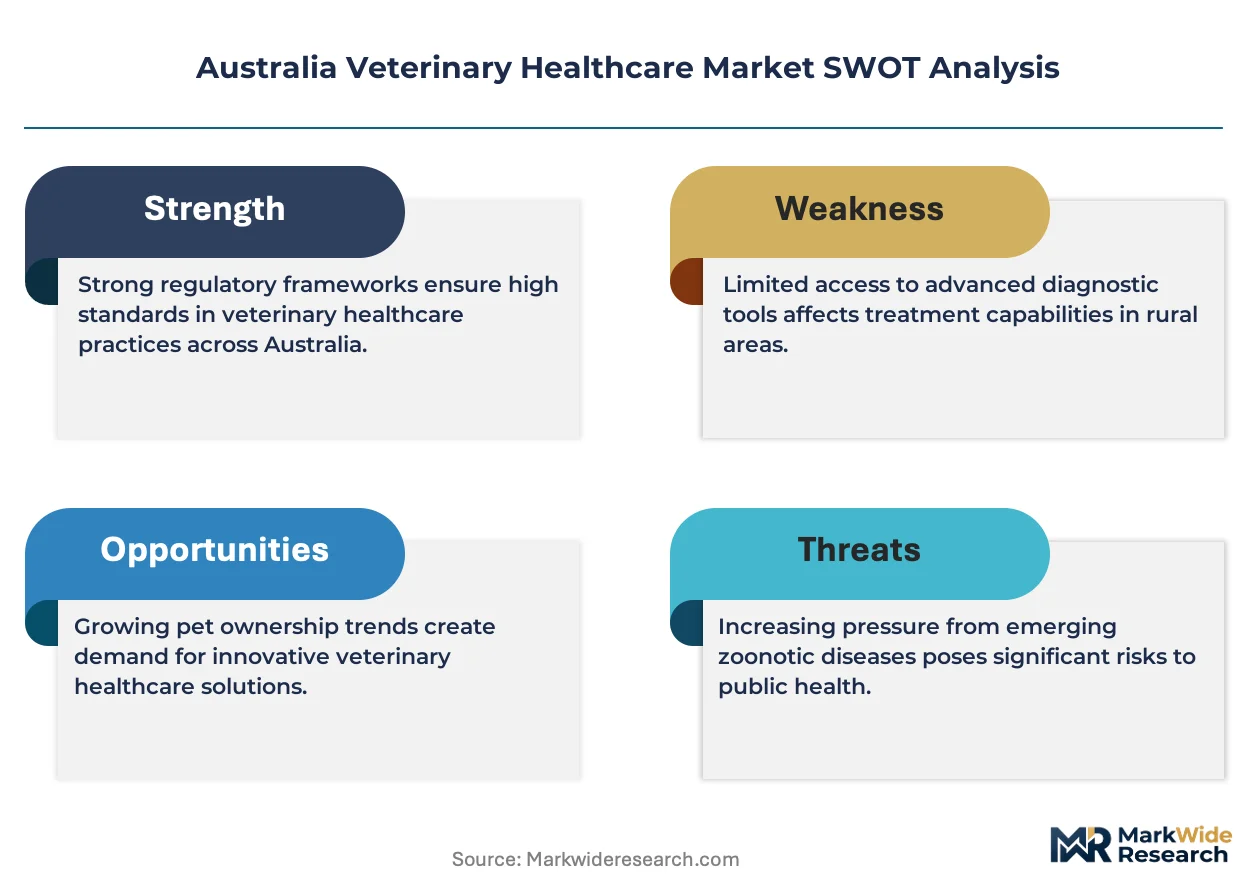
Companion animal aging demographics in Sydney metropolitan corridors sustain chronic disease pharmaceutical consumption. TGA registration requirements govern veterinary medicine distribution timelines across the state. Specialist credentialing bottlenecks in diagnostic imaging constrain service expansion within corporate hospital networks clustering in Greater Sydney.
Victoria
Pet owner expenditure on preventive diagnostics elevates point-of-care instrumentation procurement in Melbourne veterinary clinics. The Australian Veterinary Association's clinical practice standards influence equipment decisions across independent and corporate networks. Same-day delivery logistics maturity in urban corridors accelerates subscription-based parasite prevention channel fragmentation.
Queensland
Regional clinic networks deploy automated hematology platforms to retain pathology revenue previously lost to centralized laboratories. APVMA chemical review processes demand expanded environmental fate data for livestock parasiticide formulations. Distributed diagnostic architecture in Brisbane and Gold Coast metropolitan zones compresses turnaround times from days to minutes.
Western Australia
Wildlife disease surveillance mandates under biosecurity protocols create procurement pathways for veterinary diagnostic services within government conservation programs. TAFE veterinary technician training pipeline gaps fail to match clinic network expansion rates in Perth metropolitan corridors. Remote practice settings drive telemedicine adoption for specialist consultation access.
Australia Veterinary Healthcare Market Competitive Environment
Global majors compete with regional champions across product registration timelines and distribution infrastructure. The Australian veterinary healthcare sector exhibits tiered concentration with multinational pharmaceutical developers anchoring vaccine and therapeutic portfolios alongside domestic clinic networks controlling service delivery endpoints. Three archetypes dominate: biologics specialists leveraging cold-chain infrastructure, diagnostic platform providers embedding instrumentation within practice workflows, and corporate veterinary service aggregators consolidating metropolitan clinic density. Competitive dynamics center on TGA registration acceleration strategies and point-of-care technology deployment partnerships.
Within the biologics and pharmaceutical tier, Zoetis Inc and Elanco Animal Health exemplify multinational developers navigating TGA-APVMA harmonization pathways. IDEXX Laboratories occupies a position representing diagnostic instrumentation specialization. These three entities anchor distinct competitive vectors—vaccine manufacturing infrastructure, parasiticide formulation expertise, and automated hematology platform deployment—across the Australian market landscape.
| Leading Market Players |
|---|
| Elanco Animal Health |
| IDEXX Laboratories |
| Zoetis Inc |
| Covetrus |
| Dechra Pharmaceuticals |
| Merck & Co. Inc. |
| Virbac |
| Greencross Ltd |
| Boehringer Ingelheim Animal Health |
| Others |
Value Chain & Pricing Dynamics
APVMA chemical review environmental fate mandates gate qualified supply for livestock parasiticide formulators and compress premium-tier pricing access to veterinarians demonstrating compliance documentation. TGA stability testing protocols at 25°C/60% relative humidity further segment manufacturers capable of shelf-life validation investment from commodity competitors.
Pricing Analysis
Input-cost pass-through from biologic API cold-chain logistics and TGA registration documentation requirements shapes pricing structures across Australian veterinary healthcare. Subscription-based parasite prevention models stratify across premium, standard, and economy tiers based on brand recognition and veterinary consultation bundling. Cost compression in generic small-molecule pharmaceuticals intensifies as Indian and Chinese API suppliers expand export capacity. Corporate clinic networks exhibit lowest price sensitivity due to consolidated procurement volumes, while independent practitioners in regional Queensland and Western Australia face acute margin pressure from online retail channel fragmentation.
Supply Chain Analysis
Single-source vulnerability sits with North American and European contract manufacturing facilities supplying temperature-sensitive biologic active ingredients to Australian formulators. Domestic fill-finish capacity for companion animal vaccines draws from imported API stocks with last-mile cold integrity managed through specialized distributor networks. Tariff exposure on pharmaceutical intermediates sourced from China and India elevates landed cost volatility for generic manufacturers. Distribution runs through wholesale intermediaries managing inventory and logistics between multinational developers and clinical endpoints across New South Wales and Victoria hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia veterinary healthcare market functions as a regulatory compounder where TGA-APVMA harmonization discussions on biologic registration pathways accelerate demand for compliant manufacturing infrastructure and documentation capabilities.
For Market Incumbents: Acquire domestic fill-finish capacity to compress import dependency for temperature-sensitive vaccine doses. Consolidate point-of-care instrumentation deployment partnerships with corporate clinic networks in Sydney and Melbourne to lock in diagnostic revenue streams. Credentialing pipeline gaps in specialist veterinary labor represent a margin pressure point addressable through in-house training academy development. For New Entrants and Emerging Players: Automated telemedicine platforms for remote specialist consultation access present a technology-first wedge into Western Australia and Queensland regional practice settings. Wildlife disease surveillance procurement pathways under biosecurity mandates offer the most penetrable white-space target for diagnostic service providers. Direct-to-veterinarian SaaS subscription models bypass incumbent distributor relationships. For Investors and Strategic Acquirers: Roll-up economics work for corporate veterinary service aggregators because independent clinic succession planning creates acquisition-ready targets in metropolitan corridors. Five-to-ten-year viability hinges on point-of-care technology integration depth rather than physical asset scale. Monitor TGA registration timeline compression for novel biologics as the inflection indicator signaling manufacturing infrastructure investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Biologic Fill-Finish Capacity Investment | Cold-chain integrity control reduces API import dependency for TGA-registered vaccine doses. |
| Point-of-Care Platform Deployment Partnerships | Automated hematology analyzer embedding captures pathology revenue within general practice clinics. |
| Subscription-Based Parasite Prevention Models | Recurring revenue automation between clinic visits counters online retail channel fragmentation. |
| Veterinary Technician Training Pipeline Expansion | TAFE program throughput increases match clinic network expansion rates in metropolitan corridors. |
| Wildlife Diagnostic Service Procurement Pathways | Biosecurity mandate alignment opens government conservation program revenue streams. |
Study Parameters
Direct dialogue with veterinary practice owners, pharmaceutical regulatory affairs specialists, corporate hospital network procurement directors, and APVMA compliance officers grounded qualitative findings. Secondary validation drew from TGA veterinary medicine registration databases, APVMA chemical review public summaries, Australian Bureau of Statistics trade data, and Australian Veterinary Association clinical standards documentation. Bottom-up segmentation modeling triangulated against top-down market sizing from pharmaceutical import records and clinic network expansion filings.
Bottom-up demand modeling across product type, end user, application, and distribution channel dimensions anchored value projections over the analysis window. Treatment intensity indices by companion animal life stage and livestock production system density informed pharmaceutical consumption forecasts. CAGRs derived from regression analysis of historical import volumes, clinic visit frequency trends, and pet owner expenditure survey data. Regulatory timeline assumptions incorporated TGA-APVMA harmonization discussion progress indicators.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biologic API supply chain disruptions, specialist veterinary labor credentialing bottlenecks, and online retail channel penetration rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Canine Arthritis Market
Veterinary
Veterinary Clostridium Vaccine Market
Veterinary
Veterinary Healthcare Market
Veterinary
Bovine Mastitis Market
Veterinary
Europe Veterinarians Market
Veterinary
Global Veterinary Infusion Pumps Market
Veterinary
Bovine Mastitis Treatment System Market
Veterinary
Veterinary Contract Development and Manufacturing Organizations (CDMO) Market
Veterinary
ASEAN Poultry Vaccines Market
Veterinary
Veterinary Disinfectants Market
Veterinary
Milking Salve Market
Veterinary
Global Veterinary Point of Care Market
Veterinary
Swine Respiratory Diseases Treatment Market
Veterinary
Europe Veterinary Healthcare Market
Veterinary
Veterinary Biologicals Biobank Market
Veterinary
United Kingdom Veterinary Healthcare Market