
 United Kingdom Veterinary Healthcare Market | 2026-2036
United Kingdom Veterinary Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Veterinary Healthcare Market Analytics
The United Kingdom veterinary healthcare sector is decoupling into two distinct operational strata: premium-tier specialist referral networks commanding higher fees for complex procedures, and commodity-level general practice competing on volume and convenience pricing. IVC Evidensia leverages its multi-site platform to sustain economies of scale across diagnostic and surgical services. CVS Group anchors its position through extensive geographic coverage of small animal hospitals. Zoetis differentiates via its pharmaceutical and vaccine portfolio depth tailored to UK livestock and companion animal protocols.
United Kingdom veterinary healthcare encompasses the prevention, diagnosis, and treatment of disease in companion animals, livestock, and exotic species, delivered through clinical services, pharmaceuticals, biologics, and diagnostic modalities including immunoassays, molecular testing, and imaging systems. Its primary purpose is to maintain animal health welfare standards, ensure food safety through herd health management, and support the human-animal bond in pet-keeping households. Pharmaceuticals and diagnostics represent the most concentrated margin pools, with vaccines showing structural resilience due to mandatory and recommended immunization schedules. Companion animals dominate volume, while livestock segments tie directly to agricultural productivity metrics and export compliance requirements.
The Veterinary Medicines Directorate regulates product licensing, residues surveillance, and antimicrobial stewardship under UK national frameworks post-EU transition. DEFRA's animal health and welfare codes, alongside RCVS practice standards, shape clinical governance and market access conditions for service providers. Stakeholders must monitor evolving veterinary prescribing restrictions and the pace of corporate consolidation to calibrate investment and partnership decisions.
Market Dynamics
Corporate consolidation across the United Kingdom veterinary healthcare sector is compressing independent practice margins while concentrating diagnostic purchasing power into fewer procurement networks. This structural force is reshaping supplier relationships and service pricing architecture nationwide.
Growth Catalysts
- RCVS Practice Standards Framework:Mandatory accreditation requirements for specialist referral centers are elevating clinical governance expectations and driving infrastructure investment across tier-one facilities.
- Companion Animal Preventive Care Protocols:Pet insurance penetration above forty percent in Greater London is normalizing wellness screening and early intervention diagnostics among urban households.
- Point-of-Care Testing Platforms:Rapid immunoassay and molecular diagnostic systems are decentralizing laboratory workflows into general practice settings.
Market Restraints
- Veterinary Medicines Directorate Pharmacovigilance Burden:Post-EU transition licensing requirements are extending product registration timelines and elevating compliance costs for novel therapeutics.
- Antimicrobial Stewardship Restrictions:DEFRA prescribing guidelines are constraining revenue from traditional antibiotic formulations and demanding alternative therapeutic development.
- Specialist Workforce Concentration:Diploma-holding surgeons and internal medicine consultants cluster disproportionately in the South East, limiting service availability in Northern England and Wales.
Strategic Opportunities
- Telemedicine Triage Services:Remote consultation platforms are capturing post-pandemic consumer preference for convenience-first veterinary access, particularly among millennial pet owners in metropolitan zones.
- Livestock Export Compliance Testing:Bovine tuberculosis and brucellosis screening mandates tied to EU trade continuity agreements are sustaining demand for accredited diagnostic laboratory capacity.
- One Health Data Integration:Zoonotic disease surveillance networks linking veterinary and human health databases are opening government-funded research and service contracts.
Industry Challenges
- Veterinary Nurse Recruitment Pipeline:Training program capacity constraints and emigration of qualified staff to Australia and North America are elevating wage pressure across practice tiers.
- Diagnostic Equipment Refresh Cycles:MRI and CT capital requirements exceed five hundred thousand pounds per unit, straining independent practice balance sheets against corporate competitors with centralized financing.
- Legacy Practice Management System Migration:Cloud-based platform transitions are disrupting appointment scheduling and clinical record accessibility during implementation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Veterinary Healthcare Market |
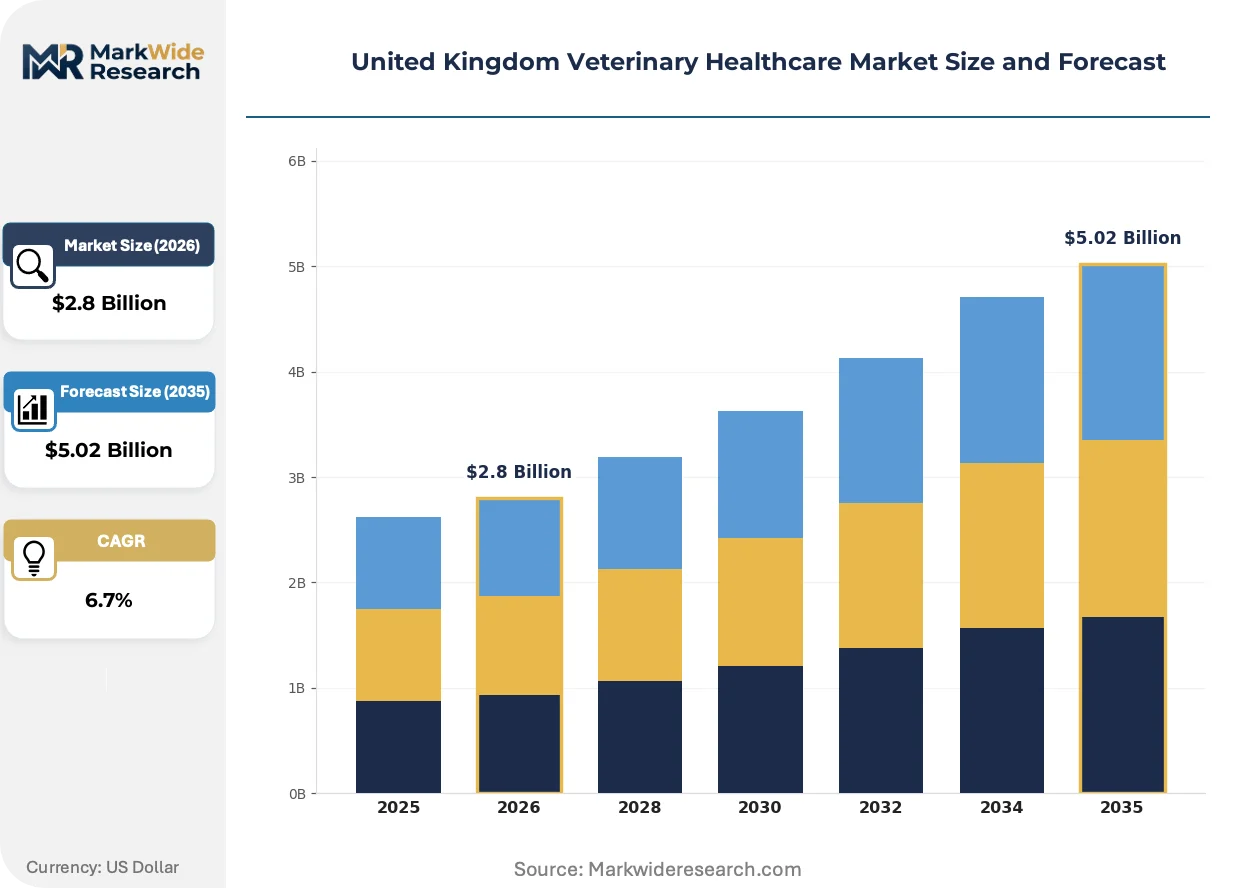
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
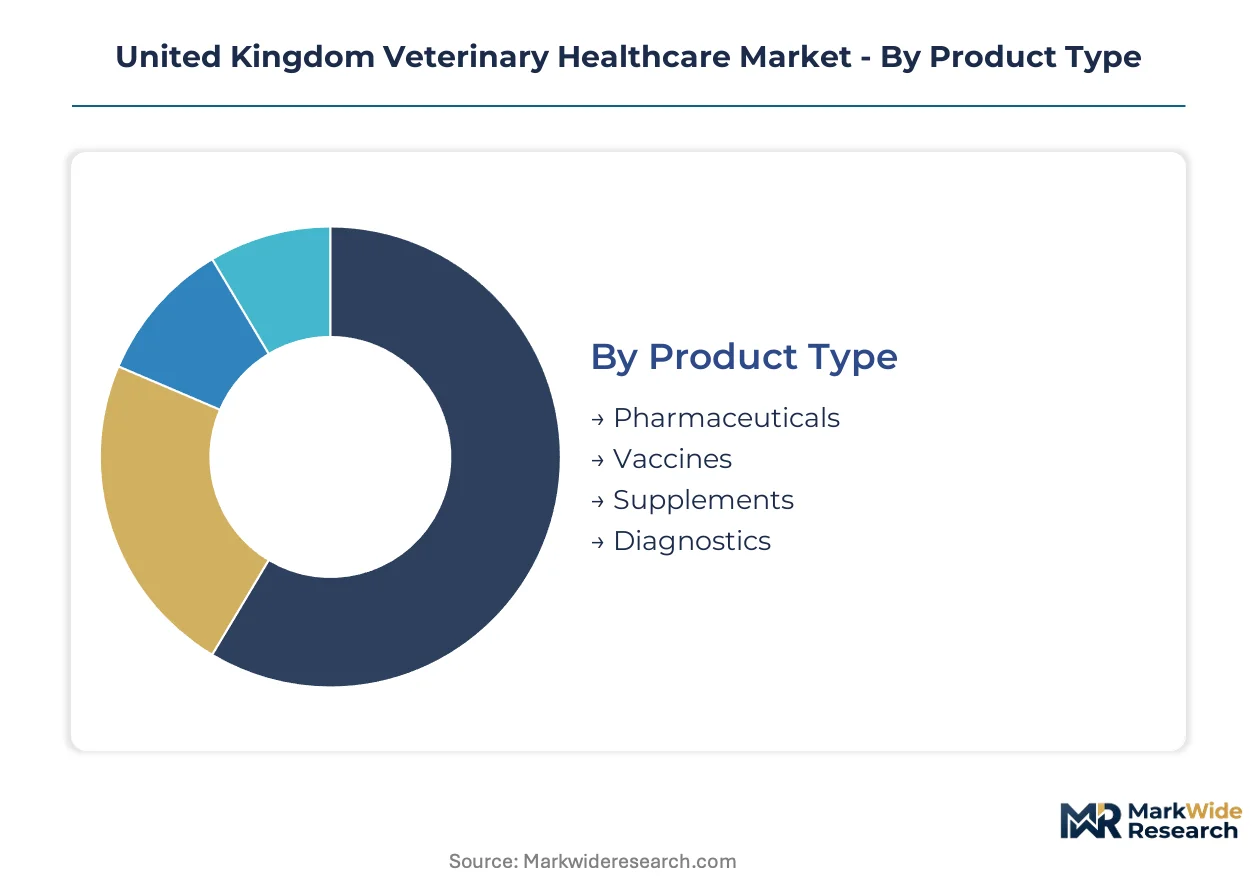
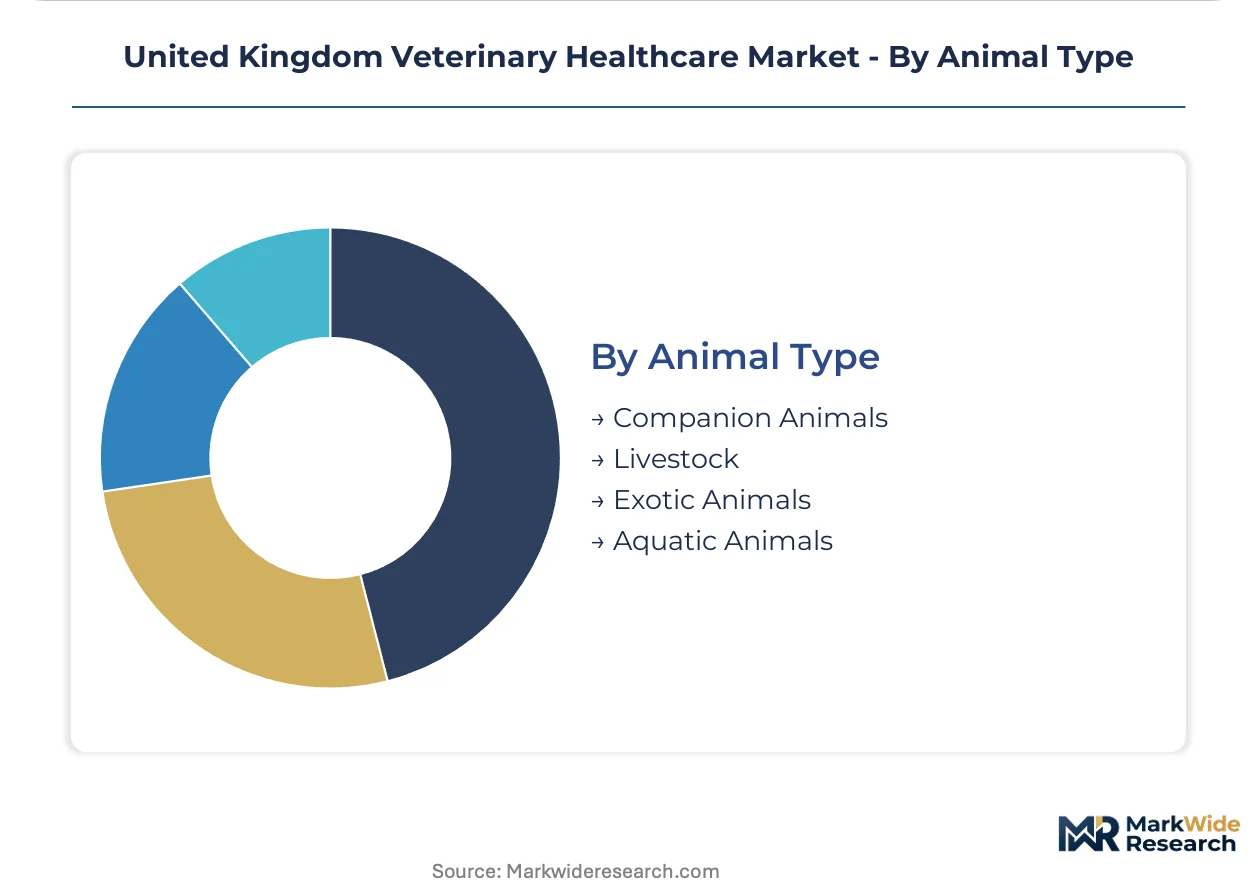
| Segmentation | Product Type: Pharmaceuticals, Vaccines, Supplements, Diagnostics End User: Veterinary Clinics, Animal Hospitals, Research Laboratories, Pet Owners Treatment Type: Preventive Care, Surgical Procedures, Emergency Care, Routine Checkups Animal Type: Companion Animals, Livestock, Exotic Animals, Aquatic Animals |
| Companies Covered | IVC Evidensia, CVS Group, Pets at Home, Linnaeus Group, VetPartners, Medivet Group, Boehringer Ingelheim, Zoetis, MSD Animal Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Veterinary Healthcare Market Evolving Landscape
Digital diagnostic platforms and regulatory data transparency mandates are converging to reshape how United Kingdom veterinary services are delivered, priced, and governed. Three developments are commanding strategic attention from practice owners and pharmaceutical suppliers.
Artificial intelligence-assisted radiographic interpretation is integrating machine learning algorithms into first-line diagnostic workflows at corporate practice chains. These systems flag pulmonary and orthopedic abnormalities for specialist review, compressing time-to-diagnosis intervals for general practitioners managing high caseloads. The technology is integrating clinical decision support into routine workflows without displacing specialist referral demand.
The Veterinary Medicines Directorate's updated antimicrobial resistance monitoring requirements are mandating real-time prescription data submission from all dispensing practices. This regulatory shift is forcing pharmaceutical suppliers to restructure distribution reporting systems and elevating transparency around veterinary antibiotic consumption patterns. Livestock veterinarians in intensive agricultural regions face the steepest compliance adaptation requirements.
Subscription-based preventive care plans are displacing traditional fee-for-service billing across small animal general practice. Pet owners in Greater Manchester and the West Midlands are locking in monthly payments covering vaccinations, parasite control, and routine examinations. This behavioral shift is smoothing practice revenue volatility while compressing per-visit diagnostic upsell opportunities.
United Kingdom Veterinary Healthcare Market Segmentation
Segmentation reveals how capital, regulatory compliance, and clinical capability distribute across the United Kingdom veterinary healthcare sector. Understanding these divisions clarifies where procurement power concentrates and which service tiers face margin compression.
Product Type:
Supply concentration in pharmaceutical manufacturing and diagnostic platform distribution shapes competitive dynamics across product categories.
- Pharmaceuticals:Small-molecule therapeutics and antimicrobial formulations dominate procurement budgets. Demand clusters in livestock-intensive regions of Northern England and Wales where herd health protocols require bulk therapeutic purchasing under Veterinary Medicines Directorate oversight.
- Vaccines:Attenuated and recombinant biologics for companion animal core immunization schedules sustain recurring revenue streams. Greater London practices with high pet insurance penetration drive premium vaccine adoption alongside mandatory livestock export compliance testing in agricultural zones.
- Supplements:Nutraceuticals and dietary additives address joint health, dermatological, and digestive conditions in aging companion animal populations.
- Diagnostics:Immunoassay kits, molecular testing platforms, and imaging consumables decentralize into general practice settings.
Pharmaceuticals absorb the bulk of installed capacity; diagnostics is expanding most quickly.
End User:
Customer type determines pricing leverage, with corporate chains extracting volume discounts unavailable to independent operators.
- Veterinary Clinics:General practice facilities deliver primary care, vaccination, and minor surgical services. South East England concentrates the highest clinic density per capita, intensifying competition for insured client bases in suburban corridors.
- Animal Hospitals:Multi-disciplinary referral centers house specialist surgical, imaging, and internal medicine departments. These facilities command premium fees for complex procedures in Greater London and Manchester, where pet owner willingness to pay for advanced intervention peaks.
- Research Laboratories:Academic and commercial facilities conduct pharmacovigilance, vaccine efficacy, and zoonotic disease surveillance under government contract.
- Pet Owners:Direct-to-consumer channels for parasite control products and nutritional supplements bypass clinical intermediaries.
Animal hospitals capture the highest margin per transaction; pet owner direct purchasing is climbing the fastest.
Treatment Type:
Application focus separates preventive revenue stability from episodic emergency income volatility.
- Preventive Care:Wellness examinations, vaccination protocols, and parasite prevention programs generate predictable recurring revenue. Subscription-based preventive plans in urban markets smooth cash flow while locking in client loyalty against competitor poaching.
- Surgical Procedures:Orthopedic, soft tissue, and dental interventions require specialized equipment and anesthesia monitoring. Tier-one referral hospitals in the South East concentrate complex surgical caseloads, leaving general practices with routine sterilization and dental extractions.
- Emergency Care:After-hours critical services address trauma, toxicities, and acute medical decompensation.
- Routine Checkups:Scheduled health assessments establish baseline diagnostics and detect subclinical disease progression.
Preventive care underwrites practice financial stability; emergency services show the steepest expansion trajectory.
Animal Type:
Volume distribution across species determines regulatory exposure and therapeutic protocol complexity.
- Companion Animals:Canine and feline populations drive the majority of clinical service revenue. Urban households in Greater London, Birmingham, and Manchester sustain demand for advanced oncology, cardiology, and rehabilitation services.
- Livestock:Cattle, sheep, and swine health management ties directly to agricultural productivity and export compliance. DEFRA-mandated disease surveillance programs in dairy-intensive regions of South West England and Cheshire sustain veterinary field service demand.
- Exotic Animals:Avian, reptile, and small mammal species require species-specific diagnostic and therapeutic expertise concentrated in specialist practices.
- Aquatic Animals:Ornamental fish and commercial aquaculture health services remain a niche segment with limited specialist availability.
Companion animals dominate transaction volume; livestock services face regulatory-driven consolidation pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater London concentrates the United Kingdom's highest veterinary service density, with specialist referral hospitals and corporate practice chains clustering across the South East corridor. This metropolitan concentration shapes national pricing benchmarks and clinical capability distribution.
Greater London and South East
Pet insurance penetration exceeds forty percent across Greater London households, normalizing wellness screening and advanced intervention diagnostics. The Royal College of Veterinary Surgeons mandates specialist accreditation for referral centers operating within this zone. Corporate practice chains cluster along the M25 corridor, capturing insured client bases through multi-site diagnostic networks.
Midlands
Urban centers in Birmingham and Manchester sustain demand for cardiology and oncology services among aging companion animal populations. DEFRA regional veterinary laboratories coordinate bovine tuberculosis surveillance across Staffordshire and Cheshire dairy corridors. Independent general practices compete on subscription preventive care plans to retain client loyalty against corporate expansion.
North England
Livestock field services dominate veterinary demand across Yorkshire and Cumbria sheep-cattle farming regions. The Veterinary Medicines Directorate's antimicrobial stewardship guidelines constrain prescribing patterns among agricultural practitioners. Specialist workforce scarcity limits complex surgical availability, driving referrals southward to Manchester or Leeds teaching hospitals.
Scotland
Remote rural practice networks address dispersed Highland livestock populations alongside concentrated urban companion animal demand in Edinburgh and Glasgow. Scottish Government agricultural support programs subsidize large animal veterinary access in island and crofting communities. University veterinary schools anchor research collaboration and specialist training pipelines.
Wales
Bovine tuberculosis eradication programs sustain field veterinary demand across Pembrokeshire and Carmarthenshire beef-dairy regions. Welsh Government rural development schemes fund practice infrastructure in underserved areas. Specialist exotic animal and equine services concentrate around Cardiff and Wrexham corridor cities.
United Kingdom Veterinary Healthcare Market Competitive Landscape
Premium-margin players sit above commodity-margin players across diagnostic capability and specialist accreditation tiers. Corporate consolidators command centralized procurement leverage over pharmaceutical and equipment suppliers. Three archetypes dominate: multi-site corporate platforms, independent specialist referral networks, and pharmaceutical-diagnostics integrated suppliers. M&A activity compresses independent practice numbers while vertical integration into laboratory and cremation services deepens revenue capture.
Among United Kingdom-based corporate platforms, IVC Evidensia and CVS Group exemplify scale-driven consolidation archetypes, each operating extensive geographic networks of small animal hospitals and general practices. Zoetis anchors the pharmaceutical-diagnostics integrated tier, representing suppliers with portfolio breadth across companion animal and livestock therapeutic categories. These three entities occupy distinct competitive positions without direct overlap in core capability emphasis.
| Leading Market Players |
|---|
| IVC Evidensia |
| CVS Group |
| Pets at Home |
| Linnaeus Group |
| VetPartners |
| Medivet Group |
| Boehringer Ingelheim |
| Zoetis |
| MSD Animal Health |
| Others |
Value Network & Pricing Analysis
Corporate procurement consolidation across IVC Evidensia and CVS Group networks is compressing supplier margins while demanding volume-commitment discounts from pharmaceutical distributors. This buyer-side concentration forces manufacturers to restructure rebate tiers and absorb logistics costs, narrowing workable price bands for independent practice suppliers.
Pricing Analysis
Value-based pricing anchored to clinical throughput and diagnostic accuracy separates premium-tier specialist referral centers from commodity general practice. Three-tier pricing structure across premium, standard, and economy levels reflects RCVS accreditation status, equipment sophistication, and geographic density of insured households. Cost compression in general practice is intensifying because subscription preventive care plans cap per-visit revenue while elevating client acquisition spend. Price-sensitive independent operators in Northern England and Wales face the steepest margin erosion, while Greater London referral hospitals retain pricing power through diploma-holder scarcity.
Supply Chain Analysis
Veterinary nurse and specialist surgeon availability constraints in the United Kingdom, Ireland, and Australia are elevating workforce costs across clinical service tiers. Active pharmaceutical ingredient sourcing for companion animal therapeutics draws from India, China, and Switzerland, with cold-chain biologics production concentrated in Belgium and the Netherlands. Single-source vulnerability around recombinant vaccine substrates poses continuity risk during regulatory inspection backlogs. Distribution runs through pharmaceutical wholesalers with direct-to-practice delivery networks, bypassing retail intermediaries for prescription-controlled products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom veterinary healthcare sector functions as a consolidation play where corporate platform scale is displacing independent practice viability. Antimicrobial stewardship compliance costs and diagnostic equipment capital requirements are accelerating exits among undercapitalized operators.
For Market Incumbents: Acquire specialist diploma-holder practices and accredited referral hospital assets to deepen geographic coverage and capture insured client bases. Consolidate procurement leverage across multi-site networks to extract pharmaceutical distributor concessions. Build backward integration into in-house laboratory and cremation services to capture margin pools currently flowing to third-party providers. Defend against telemedicine platform entrants by embedding remote consultation into existing client relationships. For New Entrants and Emerging Players: Enter via telemedicine triage platforms targeting millennial pet owners in Greater Manchester and Birmingham metropolitan zones where corporate penetration remains incomplete. Target livestock export compliance testing services in Welsh and Scottish agricultural corridors where DEFRA-mandated disease surveillance sustains field veterinary demand. Pursue white-label diagnostic platform partnerships with independent practices seeking to avoid corporate affiliation while accessing corporate-grade technology. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale specialist referral networks holding RCVS accreditation and concentrated insured client bases given continued corporate consolidation velocity. Long-term viability favors platforms with embedded pharmaceutical distribution relationships and captive laboratory capacity. The signal to watch is Veterinary Medicines Directorate enforcement intensity around pharmacovigilance compliance, which could accelerate distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Specialist Practice Acquisition | RCVS-accredited referral centers command premium fees and lock in insured client loyalty. |
| In-House Laboratory Buildout | Captive diagnostic capacity captures margin from third-party reference laboratories and accelerates turnaround. |
| Telemedicine Platform Launch | Remote consultation meets post-pandemic convenience preference among urban millennial pet owners. |
| Preventive Care Subscription Rollout | Monthly billing smooths revenue volatility and reduces client churn against competitor poaching. |
| Livestock Compliance Testing Expansion | DEFRA-mandated bovine tuberculosis screening sustains contracted revenue in agricultural regions. |
Research Methodology
Veterinary Medicines Directorate regulatory filings, RCVS practice accreditation databases, and DEFRA animal health surveillance reports formed the secondary backbone of this analysis. Primary interviews with veterinary practice owners, pharmaceutical distribution managers, specialist referral surgeons, and pet insurance underwriting directors validated demand-side assumptions. Bottom-up modeling of clinic-level revenue per veterinarian and top-down triangulation against pharmaceutical sales data refined market sizing across the analysis window.
Historical trendline analysis of practice consolidation velocity, pet insurance penetration curves, and antimicrobial prescription volume shaped the projection framework. Segmentation modeling captured product type dynamics, end-user concentration patterns, treatment type revenue stability, and animal type regulatory exposure. CAGRs were derived from fitted growth curves against documented corporate expansion trajectories and livestock export compliance testing mandates. Forecast inputs incorporated Veterinary Medicines Directorate licensing timeline assumptions and specialist workforce pipeline constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory enforcement shifts or veterinary nurse emigration acceleration. Projections reflect assumptions around corporate acquisition pace and pet owner willingness-to-pay elasticity. A small set of named triggers warrants ongoing watch: RCVS accreditation requirement tightening, DEFRA antimicrobial restriction expansion, and telemedicine regulatory clarification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Pet Light Therapy Devices Market
Veterinary
Rabies Veterinary Vaccines Market
Veterinary
Global Veterinary Artificial Insemination Market
Veterinary
Global Veterinary Holters Market
Veterinary
Veterinary Biologicals Biobank Market
Veterinary
Companion Animal Arthritis Market
Veterinary
Bovine Mastitis Market
Veterinary
Veterinary Progesterone Testing Market
Veterinary
Veterinary Endotracheal Tubes Market
Veterinary
Global Companion Animal Specialty Drugs Market
Veterinary
Veterinary CRO and CDMO Market
Veterinary
Global Dog Vaccines Market
Veterinary
US Surgical Pet Collar Market
Veterinary
Global Veterinary Hematology Analyzers Market
Veterinary
Australia Veterinary Healthcare Market
Veterinary
Europe Veterinarians Market