
 Veterinary Healthcare Market | 2026-2036
Veterinary Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Healthcare Market Intelligence
The FDA's Center for Veterinary Medicine is restructuring the cost-of-entry calculus for novel therapeutics and biologics, forcing developers to absorb lengthier pre-market validation cycles. Zoetis Inc. leverages its vertically integrated manufacturing network to compress regulatory timelines across species-specific product lines. Merck Animal Health anchors its competitive position through deep R&D investment in livestock vaccine platforms. Boehringer Ingelheim dominates the parasiticide segment with sustained channel control through direct-to-clinic distribution infrastructure.
Veterinary healthcare encompasses the prevention, diagnosis, and treatment of disease in companion and production animals, spanning biologic formulations with defined potency specifications, chemically synthesized pharmaceuticals, and in vitro diagnostic assays calibrated to species-specific reference ranges. Its primary commercial purpose is to sustain animal productivity in food systems while extending lifespan and quality of life in companion species. Pharmaceuticals and vaccines together occupy the largest value pools, with diagnostics representing the fastest-expanding segment as point-of-care instrumentation migrates from reference laboratories into clinical settings. Injectable delivery modes sustain premium pricing relative to oral alternatives, particularly in livestock applications where dosing precision affects withdrawal intervals and food safety compliance.
The USDA's Animal and Plant Health Inspection Service governs interstate movement of veterinary biologics, while the EPA regulates ectoparasiticide environmental fate, creating overlapping compliance obligations for manufacturers with multi-species portfolios. ISO 17025 accreditation for diagnostic laboratories is becoming a de facto market access requirement in contracted research and food chain testing. Stakeholders must monitor how FDA guidance on compounded veterinary drugs evolves, as enforcement discretion shifts could redirect demand toward approved pharmaceutical pathways or fragment the market between regulated and unregulated supply channels.
Market Dynamics
Companion animal insurance penetration is restructuring veterinary service economics, converting episodic out-of-pocket spending into predictable reimbursement flows that expand treatment authorization rates and shift clinic revenue mix toward advanced procedures.
Growth Catalysts
- Pet Humanization Trajectory:Owners now allocate discretionary income toward oncology and orthopedic interventions previously reserved for human medicine, expanding the addressable therapeutic market for specialty practices.
- USDA Streamlined Licensing:The Animal and Plant Health Inspection Service has compressed biologics approval timelines for minor species, accelerating product commercialization in aquaculture and exotic companion segments.
- Point-of-Care Migration:In-house diagnostic instrumentation is displacing reference laboratory dependency, capturing margin previously lost to external vendors and compressing diagnostic turnaround from days to minutes.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:China and India supply over seventy percent of veterinary API requirements, exposing formulators to geopolitical friction and supply interruption risk.
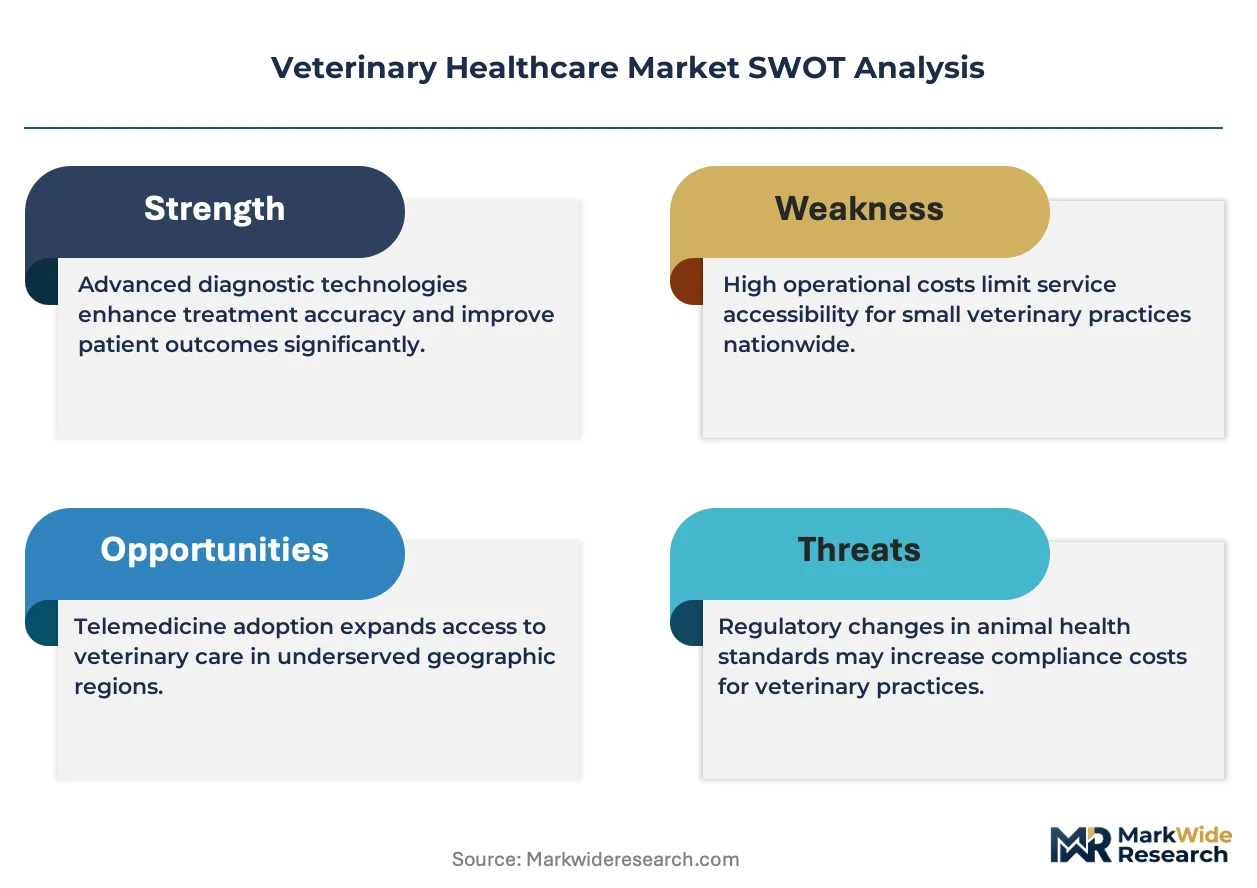
- FDA Pre-Market Burden:Center for Veterinary Medicine efficacy demonstration standards for novel therapeutics extend development timelines and elevate capital requirements beyond mid-tier developer capacity.
- Generic Erosion in Antimicrobials:Patent expiration across legacy antibiotic classes has collapsed pricing power, redirecting R&D investment toward biologics with steeper technical barriers.
Strategic Opportunities
- Telemedicine Regulatory Opening:State veterinary medical boards are revising practice act definitions to permit remote consultation, creating channel expansion for platforms integrating diagnostic data with clinical decision support.
- One Health Surveillance Integration:Zoonotic pathogen monitoring mandates are converging human and veterinary diagnostic infrastructure, opening contracted service opportunities for laboratories with dual-species capability.
- Sustainable Protein Demand:Precision livestock health management systems are capturing investment as integrated poultry and swine operators seek antibiotic reduction pathways compliant with EU Green Deal import standards.
Industry Challenges
- Veterinary Specialist Scarcity:Board-certified practitioners in surgery and internal medicine cluster in metropolitan corridors, leaving exurban and rural clinics dependent on generalist capacity for complex cases.
- Interoperability Fragmentation:Practice management software, diagnostic devices, and insurance platforms operate on non-standard data architectures, forcing manual reconciliation and delaying real-time care coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Healthcare Market |
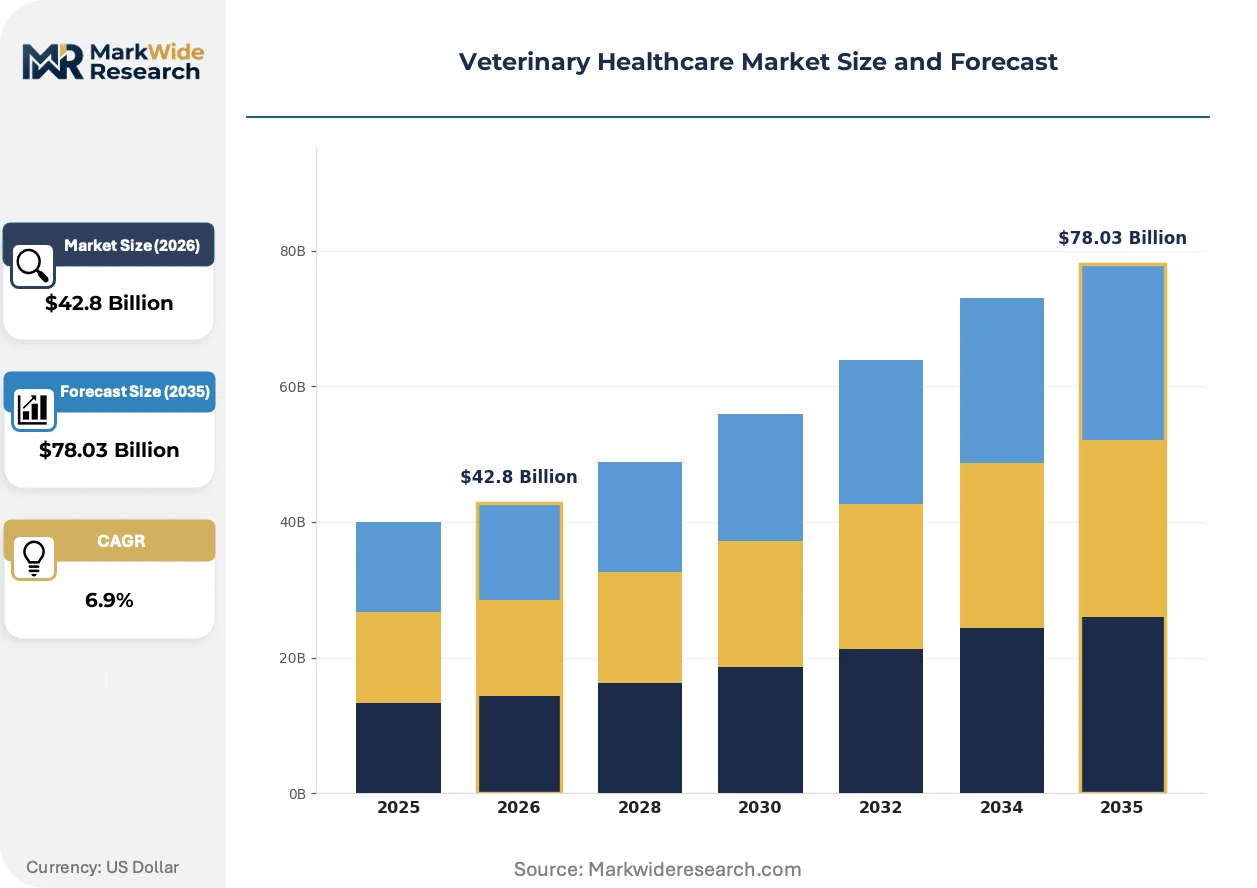
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $78.03 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Pharmaceuticals, Feed Additives, Diagnostics End User: Veterinary Clinics, Animal Hospitals, Pet Owners, Research Institutions Delivery Mode: Injectable, Oral, Topical, Intranasal Animal Type: Pets, Livestock, Poultry, Aquaculture |
| Companies Covered | Zoetis Inc., Merck Animal Health, Elanco Animal Health, Boehringer Ingelheim, IDEXX Laboratories, Ceva Santé Animale, Virbac, Vetoquinol, Dechra Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Healthcare Market Strategic Shifts & Innovations
Digital pathology and artificial intelligence classification are compressing diagnostic interpretation timelines while monoclonal antibody platforms are displacing small-molecule therapeutics in chronic disease management. These shifts are redistributing value capture across the supply chain.
mRNA vaccine platforms are overtaking killed and modified-live formulations in development pipelines. Zoetis and academic consortia have validated thermostable lipid nanoparticle delivery for foot-and-mouth disease and avian influenza candidates. This technology is enabling rapid strain-matched response to emerging pathogens without embryonated egg manufacturing constraints.
The FDA's expanded oversight of compounded veterinary drugs under GFI #256 is restructuring pharmacy practice. Bulk drug substance restrictions are channeling demand toward approved pharmaceutical pathways. Small-animal general practices in the United States are responding by consolidating purchasing through veterinary services organizations to secure manufacturer-direct pricing.
Subscription-based wellness plans are displacing fee-for-service billing in companion animal primary care. Banfield and corporate consolidators bundle preventive diagnostics with unlimited office visits, smoothing revenue cyclicality and locking patient retention. This model concentrates in suburban United States markets where pet owner lifetime value calculations support predictable monthly outlays.
Veterinary Healthcare Market Segmentation
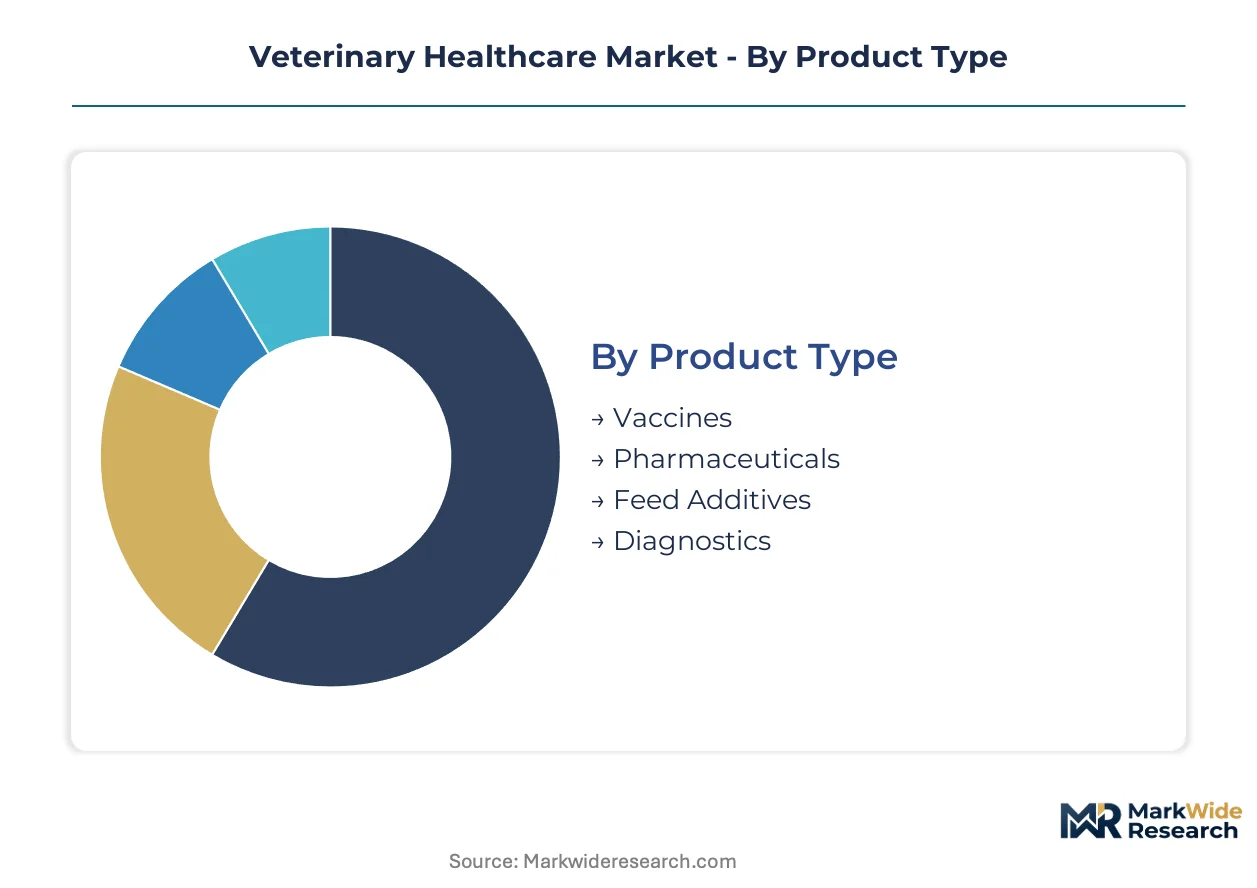
Veterinary healthcare segmentation reveals divergent margin structures across species and delivery technologies. Product mix varies sharply between companion animal practices seeking premium therapeutics and livestock operators optimizing cost-per-dose economics. Understanding these fault lines enables targeted portfolio allocation and channel strategy design.
Product Type:
Vaccines command volume leadership while diagnostics capture the steepest value expansion trajectory.
- Vaccines:Modified-live and killed formulations dominate preventive protocols across species. USDA-licensed products for livestock anchor procurement contracts with integrated protein producers in the United States and Brazil. Companion animal vaccine schedules drive recurring clinic traffic and anchor wellness plan economics.
- Pharmaceuticals:Small-molecule antimicrobials and parasiticides face generic compression while monoclonal antibodies for chronic disease management reset pricing benchmarks. FDA Center for Veterinary Medicine oversight elevates development costs for novel chemical entities.
- Feed Additives:Probiotics, enzymes, and acidifiers support antibiotic-free production commitments. EU Green Deal import standards accelerate adoption in export-oriented poultry and swine operations.
- Diagnostics:In-house analyzers and point-of-care assays displace reference laboratory dependency. PCR and immunoassay platforms capture margin previously lost to external vendors while compressing turnaround times.
Today's leader: Vaccines. Tomorrow's challenger: Diagnostics.
End User:
Channel concentration favors institutional buyers with scale purchasing leverage over fragmented direct-to-consumer pathways.
- Veterinary Clinics:General and specialty practices constitute the primary dispensing channel for companion animal therapeutics. Corporate consolidators and veterinary services organizations reshape procurement through centralized purchasing agreements.
- Animal Hospitals:Emergency and referral centers command premium pricing for complex surgical and medical interventions. Specialty credentialing concentrates in metropolitan United States corridors.
- Pet Owners:Direct purchase of OTC parasiticides and nutritional supplements bypasses professional channels. E-commerce platforms and subscription models capture share from traditional retail.
- Research Institutions:Contract research organizations and academic veterinary medical centers drive demand for research-grade biologics and specialized diagnostic reagents.
Institutional buyers consolidate procurement power while pet owner direct channels fragment.
Delivery Mode:
Route of administration determines manufacturing complexity, cold chain requirements, and dosing compliance economics.
- Injectable:Parenteral formulations sustain premium pricing through precise dosing and assured bioavailability. Withdrawal interval management in livestock applications ties directly to food safety compliance.
- Oral:Tablets, suspensions, and medicated feeds enable mass administration in production animal settings. Palatability engineering and stability under gastric conditions drive formulation differentiation.
- Topical:Transdermal parasiticides and otic preparations offer owner convenience in companion animal applications. EPA environmental fate regulations govern ectoparasiticide registration.
- Intranasal:Mucosal delivery platforms generate local immunity for respiratory pathogens. Thermostable formulations reduce cold chain burden in field vaccination programs.
Injectables defend margin premiums; oral and intranasal formats expand accessible volume.
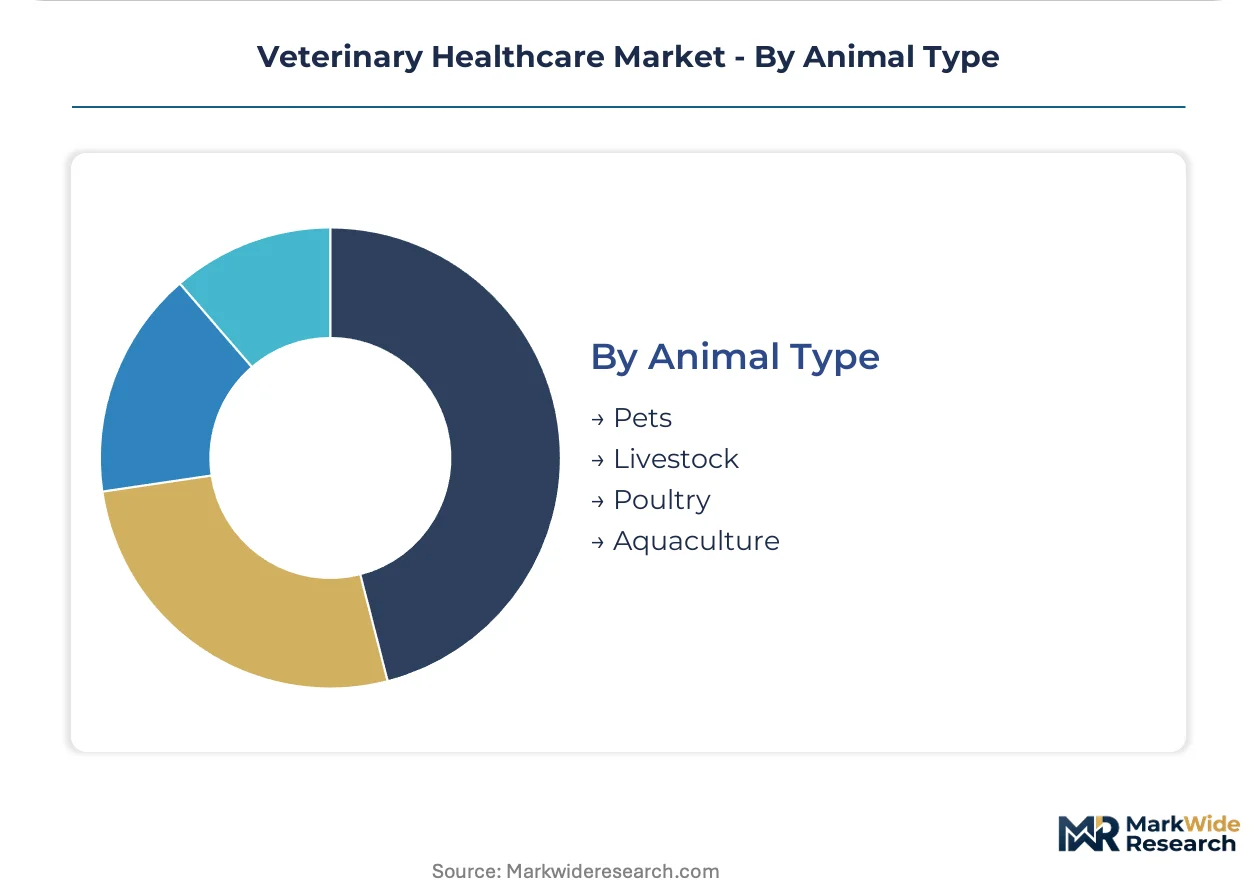
Animal Type:
Species-specific physiology and production economics create distinct therapeutic value pools and regulatory pathways.
- Pets:Dogs and cats drive oncology, orthopedic, and chronic disease management spending. Pet humanization trends in the United States and Western Europe expand addressable therapeutic intensity.
- Livestock:Cattle, swine, and small ruminant health management focuses on reproductive efficiency and growth optimization. Export market access requirements dictate disease control investment levels.
- Poultry:High-density production systems prioritize respiratory and enteric disease prevention. Integrated operators deploy precision health monitoring for antibiotic reduction compliance.
- Aquaculture:Vaccination and health management in salmon, shrimp, and tilapia operations accelerates with USDA streamlined licensing for minor species. Norway, Chile, and Scotland anchor commercial scale.
Companion animals concentrate value per dose; livestock and poultry anchor absolute volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The veterinary healthcare industry traces its modern commercial roots to the post-war expansion of livestock production in the United States and the subsequent professionalization of companion animal medicine across Western Europe. Geographic demand patterns now reflect divergent regulatory environments, species production economics, and pet ownership cultures.
United States
Companion animal specialty hospitals cluster in metropolitan corridors from Boston to Los Angeles, driving oncology and orthopedic procedure volumes. FDA Center for Veterinary Medicine oversight elevates development costs for novel therapeutics, favoring established manufacturers with regulatory infrastructure. Corporate consolidators in Texas, Florida, and the Pacific Northwest are centralizing procurement through veterinary services organizations.
Germany
Precision livestock farming systems in Lower Saxony and Bavaria anchor demand for automated health monitoring and antibiotic reduction compliance. EMA veterinary product guidelines harmonize with EU Green Deal sustainability mandates, shaping feed additive and vaccine registration pathways. The Hanover veterinary medical cluster supports translational research partnerships between university hospitals and animal health manufacturers.
China
Industrialized swine and poultry operations in Sichuan and Shandong provinces are scaling veterinary pharmaceutical consumption as biosecurity standards tighten. NMPA regulatory convergence with international standards is accelerating approval timelines for imported vaccines. Yangtze River Delta veterinary distributors are consolidating cold chain logistics for temperature-sensitive biologics.
Brazil
Beef cattle health management in Mato Grosso and Goiás dominates parasiticide and reproductive vaccine demand for export-oriented herds. ANVISA veterinary product registration aligns with Mercosur trade protocols, influencing formulation standards across South America. São Paulo-based integrated protein operators are deploying precision health systems to meet EU import certification requirements.
United Kingdom
Small animal referral centers in London and the Southeast concentrate specialist veterinary capacity for complex surgical interventions. VMD post-Brexit regulatory autonomy is diverging from EU veterinary product approval pathways, creating parallel registration requirements. Manchester and Liverpool university veterinary schools are expanding research commercialization partnerships with diagnostic platform developers.
Veterinary Healthcare Market Key Industry Players
The competitive structure tilts toward integrated pharmaceutical manufacturers with captive biologics production and direct-to-clinic distribution infrastructure. Market concentration is pronounced in vaccines and parasiticides, where regulatory capital requirements and manufacturing scale economies filter mid-tier entrants. Two strategic archetypes dominate: vertically integrated life science conglomerates with multi-species portfolios, and diagnostics-focused platform specialists with recurring revenue instrumentation models. Competitive moves center on corporate practice group consolidation for channel control and mRNA technology licensing for rapid pathogen response capabilities.
Within the integrated pharmaceutical tier, Zoetis Inc. and Merck Animal Health exemplify scale-driven archetypes with species-spanning manufacturing networks, while IDEXX Laboratories occupies a position representing diagnostics platform specialization. Boehringer Ingelheim anchors the parasiticide segment through distribution infrastructure depth. These entities collectively illustrate how regulatory endurance and channel proximity determine sustainable positioning.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Merck Animal Health |
| Elanco Animal Health |
| Boehringer Ingelheim |
| IDEXX Laboratories |
| Ceva Santé Animale |
| Virbac |
| Vetoquinol |
| Dechra Pharmaceuticals |
| Others |
Cost & Logistics Intelligence
Captive biologics manufacturing networks anchor both supply resilience and pricing power for integrated veterinary pharmaceutical developers. Zoetis and Merck Animal Health compress cost structures through in-house production of modified-live vaccines and monoclonal antibody platforms, insulating margin from API spot market volatility while commanding premium positioning in companion animal therapeutics.
Pricing Analysis
The bundled-vs-unbundled service split separates subscription wellness plans from episodic fee-for-service billing. Three-tier pricing structure across premium, standard, and economy levels stratifies by diagnostic intensity and therapeutic modality, with oncology and orthopedic interventions capturing the highest tier. Cost compression in antimicrobials intensifies because generic erosion has collapsed legacy antibiotic pricing, while pet owners in suburban United States markets show lowest price sensitivity for chronic disease management.
Supply Chain Analysis
Domestic-content mandates in China's NMPA veterinary vaccine procurement are reshaping sourcing patterns for multinational formulators. Active pharmaceutical ingredient production concentrates in China and India, drawing from fermentation-derived bulk chemicals and synthetic organic intermediates. Single-source vulnerability in lipid nanoparticle excipients for mRNA platforms threatens strain-matched vaccine response timelines. Distribution runs through veterinary services organizations and direct-to-clinic channels controlled by Boehringer Ingelheim and Elanco.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The veterinary healthcare market reads as a late-cycle quality story. Pet humanization trajectories in the United States and Western Europe concentrate demand toward premium oncology and orthopedic specifications that sustain therapeutic intensity.
For Market Incumbents: To counter generic erosion in legacy antimicrobials, deepen backward integration into monoclonal antibody manufacturing and secure USDA streamlined licensing for minor species expansion. Channel control through veterinary services organization partnerships defends dispensing volume against direct-to-consumer parasiticide platforms.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in point-of-care diagnostics opens white-space targeting of exurban and rural general practices lacking in-house analyzer capacity. Aquaculture vaccination in Norway and Chile presents the most penetrable geography given USDA compressed timelines for minor species biologics. Telemedicine platform integration with diagnostic data streams offers a defensible go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for diagnostics platform specialists because recurring revenue instrumentation models generate predictable replacement cycles and consumable attachment rates. The five-to-ten year viability window favors laboratories with ISO 17025 accreditation and dual-species human-veterinary capability. Watch FDA enforcement discretion shifts on compounded veterinary drugs under GFI #256 as the signal for demand migration toward approved pharmaceutical pathways.
| Strategic Initiative | Industry Significance |
|---|---|
| mRNA Platform Licensing | Thermostable lipid nanoparticle delivery accelerates foot-and-mouth and avian influenza strain-matched response without egg manufacturing constraints. |
| Veterinary Services Organization Consolidation | Corporate practice group acquisition centralizes procurement power and locks manufacturer-direct pricing for small-animal general practices. |
| Point-of-Care Instrumentation Deployment | In-house PCR and immunoassay platforms capture diagnostic margin previously lost to reference laboratories while compressing turnaround times. |
| One Health Surveillance Integration | Zoonotic pathogen monitoring mandates open contracted service opportunities for laboratories with dual-species diagnostic capability. |
| Precision Livestock Health Systems | Antibiotic reduction compliance with EU Green Deal import standards drives adoption in integrated poultry and swine operations. |
Research Approach
Direct dialogue with veterinary pharmaceutical executives, regulatory affairs specialists at FDA Center for Veterinary Medicine, procurement directors at corporate practice groups, and diagnostic platform engineers grounded the qualitative foundation. Secondary validation drew from USDA APHIS biologics licensing records, FDA GFI #256 guidance documents, EPA ectoparasiticide registration databases, and ISO 17025 accreditation listings. Bottom-up and top-down triangulation cross-checked manufacturer shipment data against clinic-level procedure volume estimates.
Bottom-up modeling aggregated species-specific product demand across companion animal and livestock segments, while top-down approaches validated aggregate market trajectories against protein production economics and pet ownership expenditure surveys. Segmentation dimensions spanned product type, animal species, delivery mode, and end-user channel. CAGRs were derived from regression analysis of historical approval timelines, insurance penetration curves, and specialty hospital procedure growth. Forecast inputs incorporated telemedicine regulatory liberalization pace and mRNA manufacturing scale-up timelines.
Caveats apply where FDA compounded drug enforcement shifts, geopolitical API supply interruptions, or zoonotic pandemic response priorities could materially shift the outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Bovine Mastitis Market
Veterinary
USA Animal Model Market
Veterinary
Pet Hypothyroidism Therapy Market
Veterinary
Mexico Veterinary Healthcare Market
Veterinary
Veterinary Wound Sprays Market
Veterinary
Pet DNA Testing Market
Veterinary
Veterinary Antimicrobial Susceptibility Testing Market
Veterinary
Bovine Collagen Market
Veterinary
North America Veterinary Healthcare Market
Veterinary
Veterinary Disinfectants Market
Veterinary
Global Veterinary Artificial Insemination Market
Veterinary
Global Equine Supplement Products Market
Veterinary
Europe Veterinary Healthcare Market
Veterinary
Otc Pet Medication Market
Veterinary
Global Dog Vaccines Market
Veterinary
Veterinary Immunodiagnostics Market