
 Global Animal Sedative Market | 2026-2036
Global Animal Sedative Market Size, Share, and Industry Trends Forecast 2026-2036
Global Animal Sedative Market Foresight
Subscription-based anesthesia monitoring and perioperative support services is hardening into a recurring revenue layer alongside traditional pharmaceutical sales. Zoetis leverages its integrated diagnostics-to-therapeutics platform to capture follow-on service contracts across North American veterinary chains. Dechra Pharmaceuticals anchors its position through specialist-led equine sedation protocols in Europe and Australasia. Boehringer Ingelheim competes on manufacturing scale, supplying bulk active pharmaceutical ingredients to third-party veterinary formulators.
Animal sedatives comprise pharmacological agents that induce calmness, muscle relaxation, or unconsciousness in non-human species, typically formulated at species-specific dosages measured in milligrams per kilogram of body weight to achieve targeted plasma concentrations without cardiorespiratory compromise. Their primary commercial purpose spans surgical anesthesia, diagnostic immobilization, and transport stress reduction across production and companion animal settings. Injectable alpha-2 agonists such as dexmedetomidine dominate procedural sedation in companion animal clinics due to rapid onset and reversibility with atipamezole. Oral benzodiazepines occupy the home-administered pre-visit calming segment, where pet owner convenience commands margin premiums over clinic-managed alternatives. Transdermal delivery remains nascent, constrained by variable skin permeability across species and coat types.
The FDA Center for Veterinary Medicine governs new animal drug approvals and residue tolerance setting, while the EMA coordinates centralized marketing authorizations across EU member states through its Committee for Medicinal Products for Veterinary Use. Both frameworks mandate species-specific withdrawal periods and Good Manufacturing Practice compliance that shape product development pipelines and geographic launch sequencing. ISO 10993 biocompatibility standards and national pharmacopeial monographs further constrain formulation choices for novel delivery systems. Stakeholders must monitor evolving controlled-substance scheduling for opioid-class sedatives, as regulatory reclassification would force reformulation investments and channel restrictions across multiple jurisdictions.
Market Dynamics
Veterinary practice consolidation is compressing procurement autonomy and forcing pharmaceutical suppliers to negotiate with centralized buying groups rather than individual clinics. This structural concentration is reshaping contract terms, rebate structures, and service bundling across the animal sedative value chain.
Growth Catalysts
- Alpha-2 Agonist Reversibility:The rapid reversibility of dexmedetomidine with atipamezole is expanding procedural sedation in companion animal dentistry and soft-tissue surgery, reducing recovery liability for veterinary operators.
- FDA Residue Monitoring Tightening:Enhanced surveillance protocols for food-producing species are driving adoption of species-specific withdrawal period management systems and validated analytical methods in livestock operations.
- Specialty Emergency Network Expansion:United States-based consolidation of 24-hour referral hospitals is standardizing anesthesia protocols and creating bulk purchasing corridors for sedative formularies.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Bulk manufacturing of alpha-2 agonists and benzodiazepines concentrates in a limited supplier base, exposing formulators to single-source disruption risk and input cost volatility.
- Transdermal Permeability Variability:Inconsistent drug absorption across species coat types and skin thickness is constraining development of owner-administered alternatives to clinic-based injectable protocols.
- Controlled Substance Scheduling Uncertainty:Pending regulatory reclassification of opioid-class sedatives threatens to force channel restrictions and reformulation investments across multiple national jurisdictions.
Strategic Opportunities
- Home-Administered Oral Formulations:Pre-visit calming protocols for anxious companion animals represent an underdeveloped segment where pet owner convenience commands margin premiums over traditional clinic-managed sedation.
- Subscription Anesthesia Monitoring Services:Perioperative support contracts are hardening into recurring revenue layers that complement traditional pharmaceutical sales and deepen veterinary chain relationships.
- EMA Centralized Authorization Pathways:Harmonized marketing authorizations across EU member states enable streamlined geographic expansion for novel species-specific formulations and delivery systems.
Industry Challenges
- Veterinary Anesthesiologist Scarcity:Limited specialist training programs are constraining protocol standardization and quality assurance in expanding specialty hospital networks.
- Withdrawal Period Validation Costs:Species-specific residue depletion studies require substantial capital investment and extended timelines, particularly for minor species and exotic indications.
- ISO 10993 Biocompatibility Compliance:Novel polymeric delivery systems face extended testing protocols that delay product launch sequencing and inflate development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Animal Sedative Market |
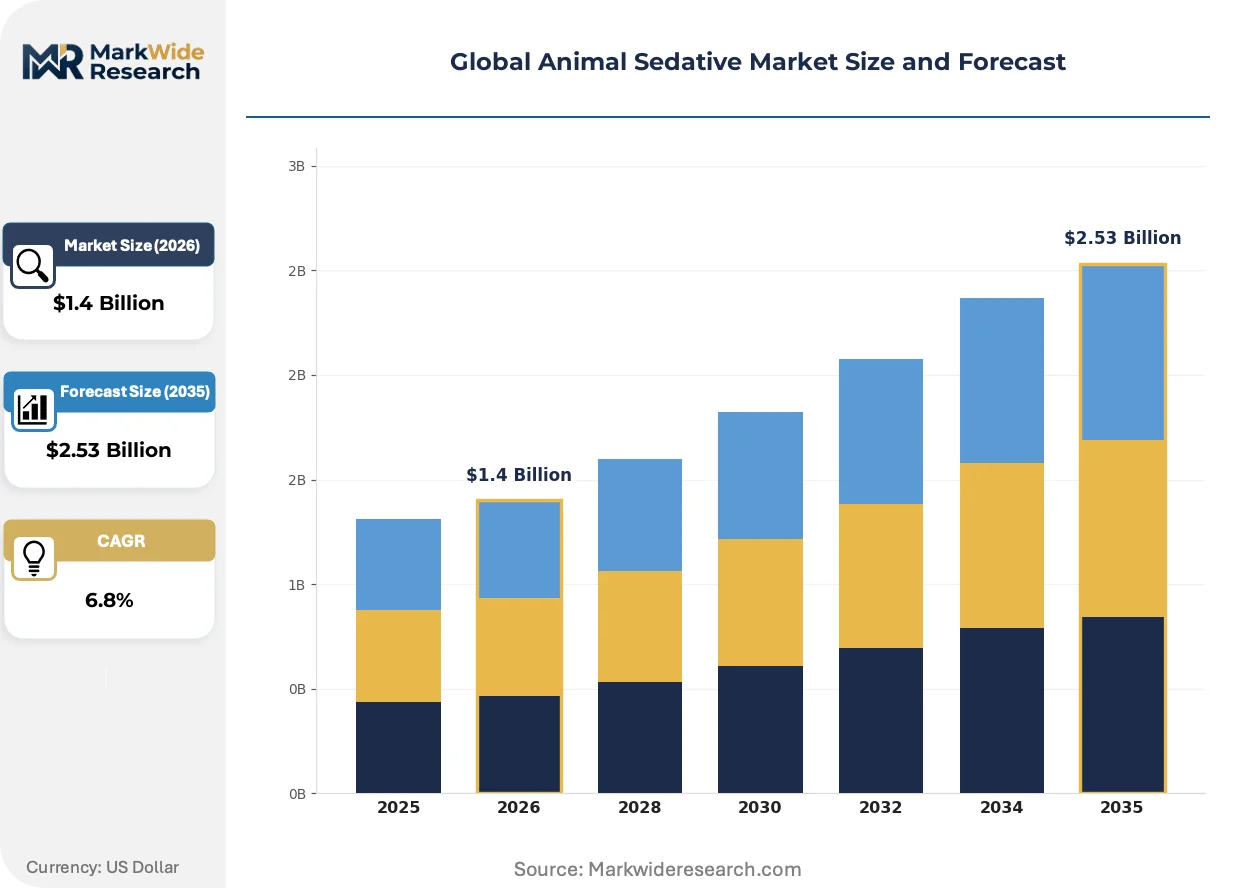
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alpha-2 Agonists, Phenothiazines, Benzodiazepines, Opioids, Barbiturates Animal Type: Companion Animals, Livestock, Equines, Exotic Pets Delivery Mode: Injectable, Oral, Inhalation, Transdermal End User: Veterinary Clinics, Research Institutions, Zoos, Animal Shelters |
| Companies Covered | Zoetis, Elanco, Merck & Co., Dechra Pharmaceuticals, Virbac, Boehringer Ingelheim, Ceva, Ouro Fino Saude Animal Group, Bimeda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Animal Sedative Market Shifts & Advancements
Digital anesthesia monitoring platforms are converging with pharmaceutical supply to create integrated perioperative ecosystems. This fusion is compressing the traditional separation between drug delivery and physiological surveillance.
Target-controlled infusion systems for intravenous sedation are modularizing anesthesia delivery in high-volume companion animal referral hospitals. These platforms enable precise plasma concentration maintenance without continuous manual titration. Large specialty networks in the United States and Western Europe are adopting these systems at accelerating rates, compressing the skill gap between specialist and general practice anesthesia outcomes.
REACH chemical registration requirements are forcing reformulation of excipient portfolios for European market access. The industrial consequence is a phased migration toward bio-based solvents and polymer carriers with established safety dossiers. Injectable sedative manufacturers serving EU veterinary markets are accelerating alternative excipient qualification to avoid supply discontinuities.
Consolidated procurement by corporate veterinary groups is unbundling traditional distributor relationships and establishing direct manufacturer contracts with volume-based pricing tiers. Independent distributors serving smaller practices face margin compression as buying groups capture preferential terms. This pattern is most visible in United States metropolitan corridors where specialty emergency networks have achieved critical mass.
Global Animal Sedative Market Segmentation
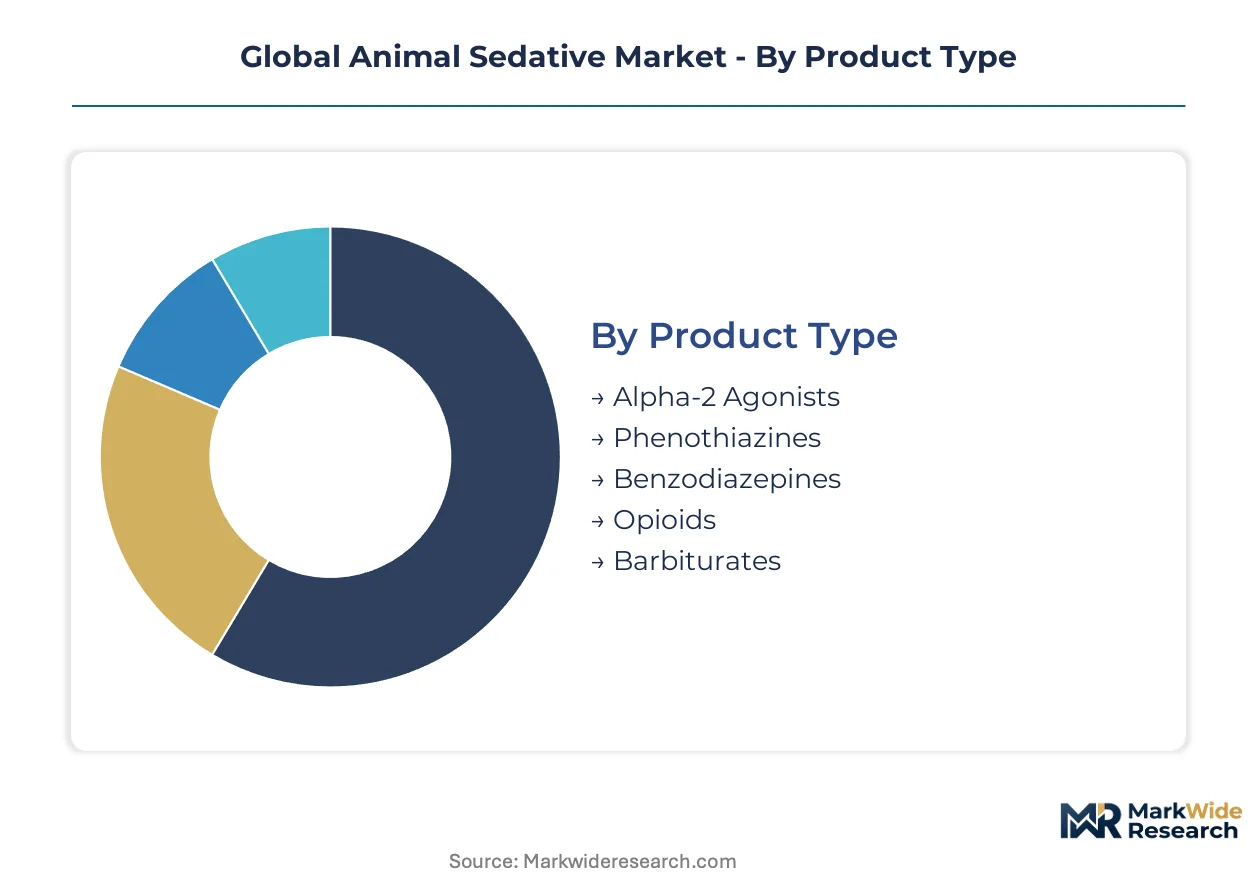
Animal sedatives fragment across pharmacological classes, species physiology, and procedural contexts. Buyers prioritize reversibility profiles for companion animal dentistry, residue compliance for livestock, and handling safety for exotic species. Each dimension carries distinct regulatory pathways and margin structures.
Product Type:
Procurement decisions hinge on reversal capability and species-specific safety margins.
- Alpha-2 Agonists:Dexmedetomidine formulations dominate procedural sedation in companion animal clinics due to rapid onset and clean reversal with atipamezole. United States specialty networks standardize on these agents for soft-tissue surgery, reducing recovery liability and anesthesia staffing intensity.
- Benzodiazepines:Oral midazolam and diazepam serve pre-visit calming protocols where pet owner convenience commands premium pricing over clinic-managed injectables. Home administration growth in North American metropolitan markets drives formulation innovation in palatable tablet and liquid presentations.
- Phenothiazines:Acepromazine remains cost-effective for equine transport and large-animal restraint despite prolonged recovery windows.
- Opioids:Butorphanol and buprenorphine face scheduling uncertainty across multiple jurisdictions, constraining channel access.
- Barbiturates:Pentobarbital concentrates in euthanasia applications with tightly controlled distribution.
Volume sits with Alpha-2 Agonists; growth tilts toward Benzodiazepines.
Animal Type:
Species physiology dictates dosage precision and withdrawal period complexity.
- Companion Animals:Canine and feline sedation commands the largest revenue pool, driven by dental and orthopedic procedure expansion in consolidated United States veterinary chains. FDA residue tolerance frameworks are less constraining than for food-producing species, enabling faster protocol innovation.
- Livestock:Cattle and swine applications require stringent withdrawal period management under FDA Center for Veterinary Medicine surveillance. Enhanced residue monitoring is driving validated analytical method adoption in feedlot and dairy operations.
- Equines:Specialist-led protocols in Europe and Australasia emphasize cardiovascular stability during standing surgical procedures.
- Exotic Pets:Avian and reptile sedation demands species-specific pharmacokinetic data that most manufacturers lack, creating supply gaps.
Revenue concentrates in Companion Animals; steepest expansion trajectory emerges in Livestock compliance systems.
Delivery Mode:
Route selection balances onset speed against handler skill requirements and owner compliance.
- Injectable:Intravenous and intramuscular formulations deliver precise plasma concentrations for surgical anesthesia. Target-controlled infusion systems in high-volume United States referral hospitals are modularizing delivery and compressing outcomes variance between specialist and general practice settings.
- Oral:Home-administered protocols for pre-visit anxiety represent an underdeveloped margin opportunity where convenience premiums exceed clinic-managed alternatives.
- Inhalation:Isoflurane and sevoflurane maintenance dominates prolonged procedures in equipped facilities.
- Transdermal:Variable skin permeability across coat types and species constrains development, with feline applications showing modest progress.
Injectable routes capture procedural volume; Oral formulations gain share fastest in companion animal wellness.
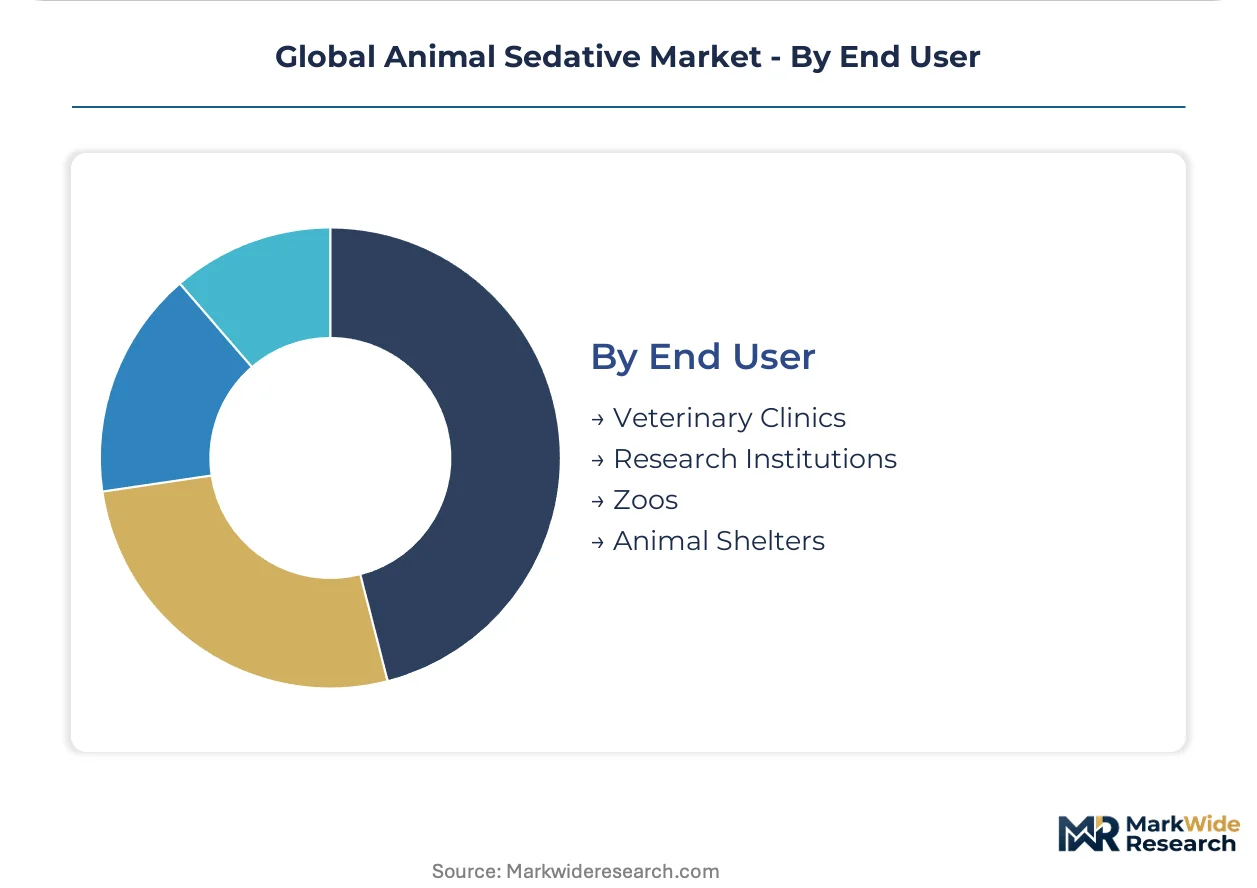
End User:
Facility type determines procurement scale, protocol standardization, and service bundling potential.
- Veterinary Clinics:Consolidated corporate groups in the United States are unbundling distributor relationships for direct manufacturer contracts with volume tiers. Anesthesia monitoring subscriptions are hardening into recurring revenue layers alongside pharmaceutical supply.
- Research Institutions:Protocol-driven demand for species-specific formulations with documented pharmacokinetic profiles supports premium pricing.
- Zoos:Exotic species collections require customized immobilization protocols with limited commercial off-the-shelf availability.
- Animal Shelters:Cost constraints favor generic phenothiazines and barbiturates for population management.
Procurement autonomy concentrates in Veterinary Clinics; Research Institutions offer the most durable margin structure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kansas City anchors North American veterinary pharmaceutical distribution, where specialty emergency networks consolidate procurement corridors for alpha-2 agonist formularies. This metropolitan concentration shapes contract negotiations across the United States, Germany, United Kingdom, Japan, and Australia.
United States
Specialty and emergency veterinary networks in Texas and Florida drive bulk purchasing standardization for dental and orthopedic sedation protocols. FDA Center for Veterinary Medicine residue surveillance tightens compliance requirements for food-producing species. The Research Triangle Park corridor in North Carolina hosts contract research organizations conducting pharmacokinetic studies for novel species-specific formulations.
Germany
Equine sedation specialists in Lower Saxony and Baden-Württemberg emphasize cardiovascular stability protocols for standing surgical procedures. REACH chemical registration mandates accelerate bio-based solvent migration in injectable excipient portfolios. The Munich-Stuttgart industrial corridor concentrates manufacturing scale for active pharmaceutical ingredients serving European veterinary formulators.
United Kingdom
Companion animal dentistry expansion in Greater London and Manchester veterinary chains elevates demand for reversible sedation agents. The Veterinary Medicines Directorate coordinates national withdrawal period enforcement aligned with EMA centralized authorization pathways. Cambridge's life sciences cluster supports pharmacokinetic modeling for minor species and exotic indications.
Japan
Metropolitan Tokyo and Osaka veterinary hospitals adopt target-controlled infusion systems for intravenous sedation maintenance. PMDA marketing authorization requirements shape species-specific formulation development timelines. The Kansai region's pharmaceutical manufacturing base supplies precision dosage forms for companion animal procedural sedation.
Australia
Livestock export operations in Queensland and New South Wales require stringent residue management under TGA veterinary medicine surveillance. Specialist-led equine protocols in Victoria and New South Wales emphasize handling safety during transport immobilization. Sydney's research institutions document pharmacokinetic profiles for exotic species collections.
Global Animal Sedative Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the animal sedative value chain, creating a tiered structure where integrated pharmaceutical platforms coexist with specialist formulation houses. The market concentrates around three strategic archetypes: diagnostics-to-therapeutics integrators, species-specific protocol specialists, and bulk active pharmaceutical ingredient suppliers. Consolidated procurement by corporate veterinary groups accelerates direct manufacturer contracting, displacing traditional distributor relationships. Geographic expansion through EMA centralized pathways and backward integration into active ingredient production represent dominant competitive moves.
Among integrated veterinary health platforms, Zoetis and Elanco occupy positions spanning diagnostics through perioperative service contracts, anchoring recurring revenue layers alongside traditional pharmaceutical supply. Dechra Pharmaceuticals exemplifies the specialist archetype, with European and Australasian equine protocol concentration. Boehringer Ingelheim represents manufacturing-scale supply, furnishing bulk active pharmaceutical ingredients to third-party veterinary formulators. Merck & Co. and Virbac sit within diversified animal health portfolios where sedation agents complement broader therapeutic franchises. Ceva, Ouro Fino Saude Animal Group, and Bimeda occupy regional and species-specific market positions.
| Leading Market Players |
|---|
| Zoetis |
| Elanco |
| Merck & Co. |
| Dechra Pharmaceuticals |
| Virbac |
| Boehringer Ingelheim |
| Ceva |
| Ouro Fino Saude Animal Group |
| Bimeda |
| Others |
Supply & Pricing Matrix
Target-controlled infusion systems for intravenous sedation are compressing cost economics in high-volume United States referral hospitals while simultaneously concentrating procurement power among consolidated veterinary chains. This technology shift forces pharmaceutical suppliers to bundle perioperative service contracts with traditional drug sales, reshaping both margin structures and downstream distribution relationships.
Pricing Analysis
Outcome-based pricing anchors companion animal sedation, where rapid reversibility with atipamezole commands premium positioning over prolonged-recovery alternatives. Three-tier pricing structure across premium, standard, and economy levels separates patented alpha-2 agonist formulations from authorized generics and commodity phenothiazines. Cost compression in the generic tier is intensifying because corporate buying groups extract volume rebates exceeding traditional distributor margins. Research institutions exhibit the lowest price sensitivity due to protocol-driven demand for documented pharmacokinetic profiles.
Supply Chain Analysis
Direct-to-specialty-network channels handle consolidated procurement demand from United States veterinary chains, displacing traditional distributor intermediaries. Active pharmaceutical ingredient production concentrates in Germany, India, and China, with the Munich-Stuttgart corridor supplying European formulators and Indian manufacturers furnishing bulk benzodiazepine intermediates. Supply chain risk centers on single-source vulnerability for alpha-2 agonist precursors, where limited qualified suppliers expose formulators to disruption. Distribution runs through centralized buying groups in metropolitan Texas and Florida corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
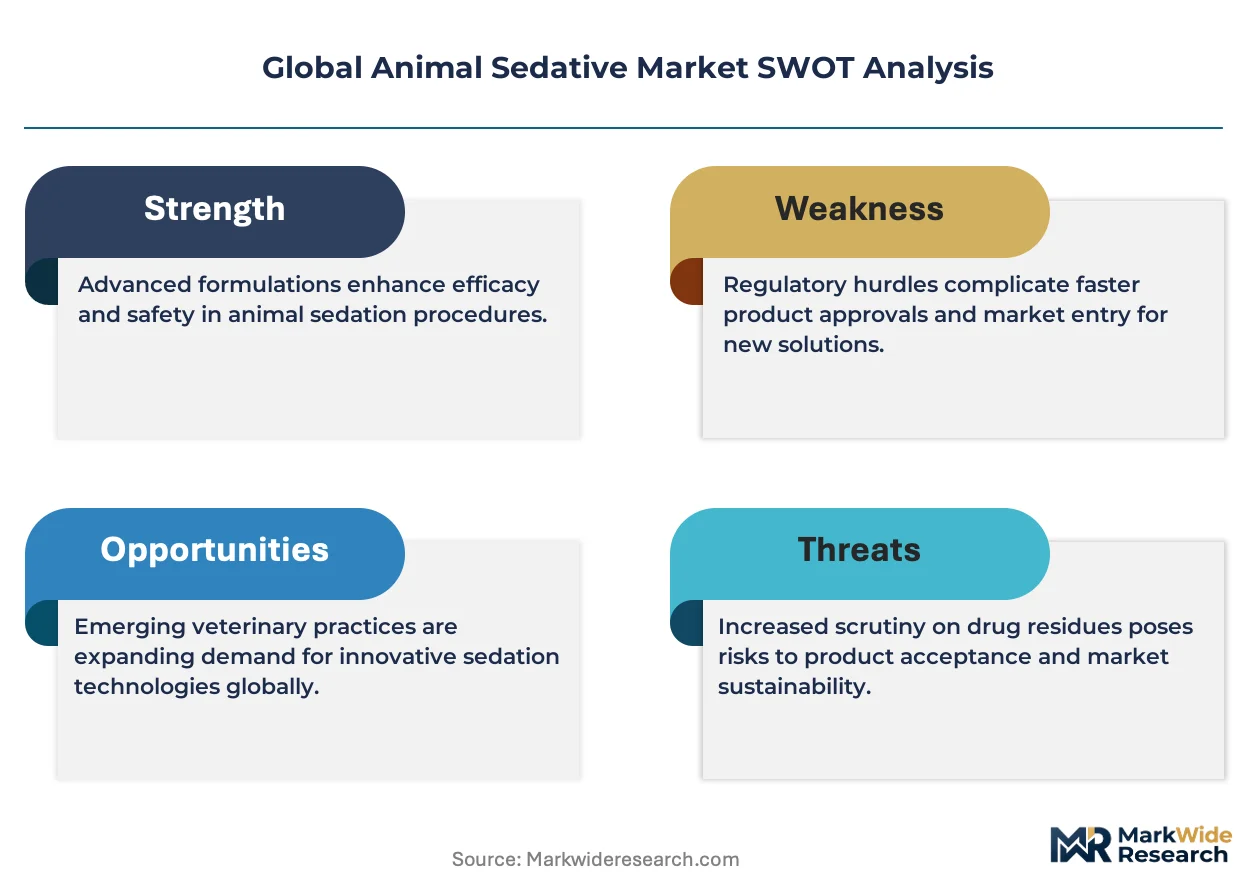
This market reads as a cost-of-compliance story where FDA Center for Veterinary Medicine residue tolerance frameworks and EMA centralized authorization pathways erect barrier-to-entry moats favoring incumbents with validated withdrawal period data and established GMP infrastructure.
For Market Incumbents: Hedge against API supply disruption through backward integration into alpha-2 agonist precursor manufacturing or captive supply agreements with qualified Indian and German suppliers. Consolidated procurement by corporate veterinary chains threatens margin compression; defend through subscription-based anesthesia monitoring services that deepen account stickiness beyond transactional drug sales. For New Entrants and Emerging Players: Enter via home-administered oral benzodiazepine formulations for pre-visit companion animal calming, the most penetrable segment where convenience premiums exceed clinic-managed injectables. White-space targets include exotic species pharmacokinetic data services and transdermal delivery systems for feline applications. Pursue regulatory arbitrage through EMA centralized authorization pathways for streamlined EU market access. For Investors and Strategic Acquirers: Re-rating potential sits with specialist formulation houses possessing species-specific protocol expertise and established relationships with European equine practitioners given accelerating consolidation in Australasian veterinary networks. Long-term viability favors platforms combining pharmaceutical supply with digital anesthesia monitoring capabilities. Monitor FDA scheduling decisions for opioid-class sedatives as an inflection indicator for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Manufacturing | Captive supply of alpha-2 agonist precursors mitigates single-source disruption risk from German and Indian suppliers. |
| Subscription Anesthesia Monitoring Launch | Perioperative service contracts harden recurring revenue layers alongside traditional pharmaceutical sales to veterinary chains. |
| EMA Centralized Authorization Pursuit | Harmonized EU marketing authorizations streamline geographic expansion for novel species-specific formulations. |
| Home-Administered Oral Formulation Development | Pre-visit calming protocols capture convenience premiums from anxious pet owners in North American metropolitan markets. |
| Exotic Species Pharmacokinetic Database Buildout | Documented safety profiles for avian and reptile sedation address supply gaps in zoo and research institutional procurement. |
Research Methodology
Independent corroboration across regulatory filings, procurement contract databases, and pharmacokinetic study registries underwrites the qualitative findings. Primary interviews with veterinary anesthesiologists, pharmaceutical regulatory affairs leads, corporate procurement directors at consolidated veterinary chains, and exotic animal specialists combined with secondary validation from FDA Center for Veterinary Medicine residue surveillance reports, EMA Committee for Medicinal Products for Veterinary Use authorizations, and ISO 10993 biocompatibility standards. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates.
Historical reference periods anchored the forecast window to observed adoption curves for target-controlled infusion systems and subscription service penetration rates. The analytical framework projects across pharmacological class, species type, delivery mode, and end-user facility tier throughout the forecast period. CAGRs derive from segmented growth rate blending weighted by revenue contribution. Modeled inputs include veterinary practice consolidation velocity, regulatory scheduling uncertainty for opioid-class agents, and REACH chemical registration timelines affecting excipient portfolios.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory reclassification of controlled substances or supply disruption in concentrated API manufacturing geographies. Projections reflect assumptions regarding continued specialty network expansion and sustained pet owner willingness to pay for convenience-oriented home administration protocols. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Europe Dog Dewormers Market
Veterinary
Veterinary Healthcare Market
Veterinary
Rabies Veterinary Vaccines Market
Veterinary
Global Pet Obesity Management Market
Veterinary
Canine Parvovirus Market
Veterinary
Veterinary Immunodiagnostics Market
Veterinary
Global Livestock Vaccines Market
Veterinary
Australia Veterinary Healthcare Market
Veterinary
Veterinary Tables Market
Veterinary
Global Veterinary Electrosurgery Market
Veterinary
Global Veterinary Drugs Market
Veterinary
India Veterinary Healthcare Market
Veterinary
Global Veterinary Monitoring Equipment Market
Veterinary
Canine Arthritis Market
Veterinary
Veterinary Vaccines Market
Veterinary
Veterinary Respiratory Disease Treatment Market