
 Global Animal Model Market | 2026-2036
Global Animal Model Market Size, Share, and Industry Trends Forecast 2026-2036
Global Animal Model Market Foresight
The EU Green Deal's chemical sustainability targets is pivoting contract research organizations toward human-relevant alternative methods while maintaining validated animal pathways for regulatory submission. Charles River Laboratories International Inc. anchors North American toxicology capacity through captive breeding networks and GLP-certified study execution. GenOway specializes in CRISPR-edited rodent lines for immuno-oncology targets, differentiating its catalog against standardized off-the-shelf offerings. Eurofins Scientific SE extends its European footprint through distributed vivarium infrastructure that reduces logistics stress on live shipments.
Animal models comprise living organisms—predominantly mice, rats, and non-human primates—engineered or selected to mimic human physiological, genetic, or disease states through spontaneous mutation, chemical induction, or targeted genomic alteration. These systems serve as predictive substrates for pharmacokinetic profiling, efficacy validation, and safety liability detection before human clinical exposure. Rodent models dominate volume throughput in drug discovery applications, while non-human primates command premium positioning in biologic safety assessment where Fc receptor biology or complement activation risk demands phylogenetic proximity. Academic institutions sustain foundational demand in behavioral studies and genetic research, though pharmaceutical companies concentrate value in custom disease modeling programs with exclusive licensing terms.
FDA's Animal Rule governs efficacy testing for medical countermeasures where human challenge studies are unethical, while EPA and OECD Test Guidelines prescribe species-specific protocols for environmental toxicology. EMA's Committee for Medicinal Products for Human Use enforces the 3Rs replacement-reduction-refinement framework through marketing authorization assessments, tightening justification requirements for primate use. Stakeholders must monitor evolving regulatory acceptance of organ-on-chip and computational simulation platforms as these deployment modalities challenge traditional in vivo testing facilities for standard safety endpoints.
Market Dynamics
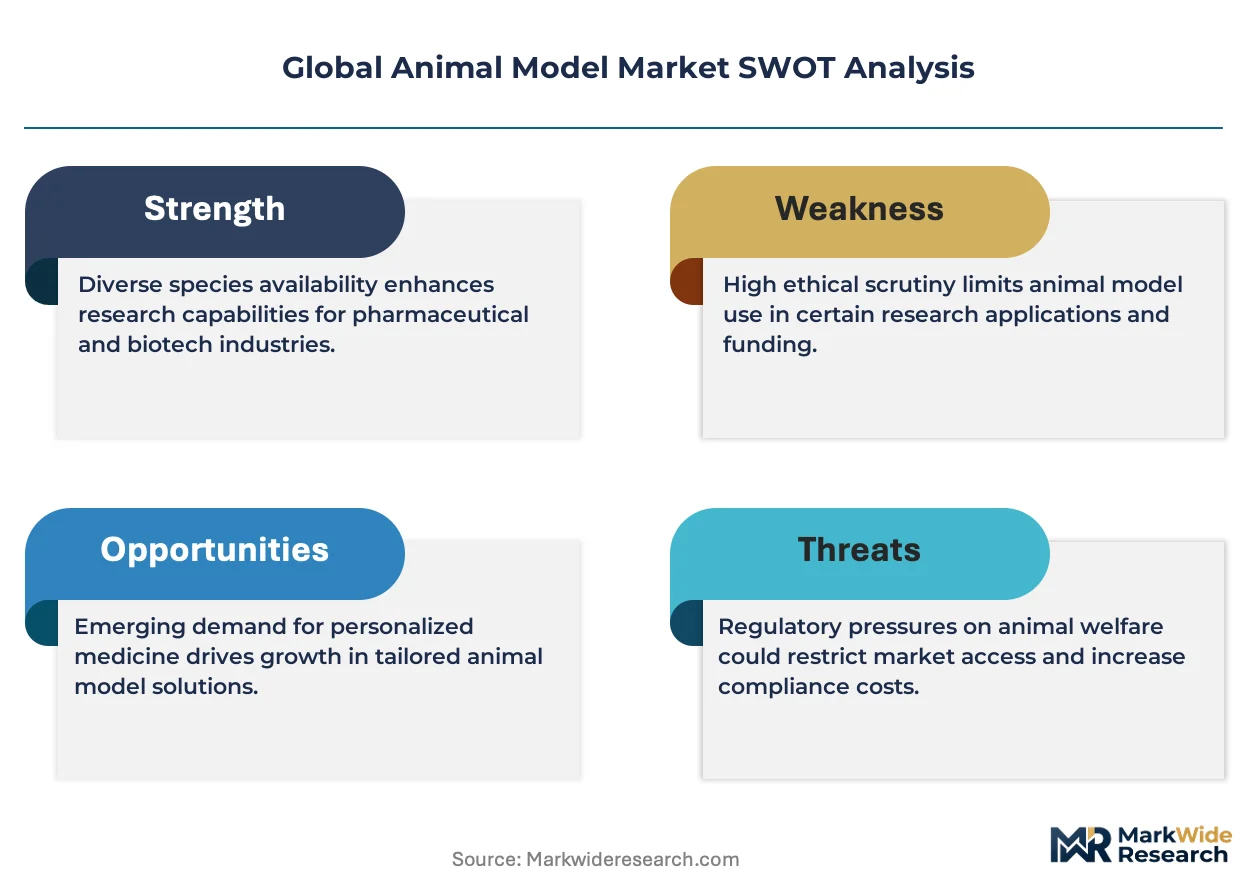
The FDA's Animal Rule pathway for biodefense countermeasures and the EU's Directive 2010/63/EU on animal welfare are compressing study design flexibility while elevating sourcing compliance costs across contract research networks.
Growth Catalysts
- Biodefense Countermeasure Mandates:The FDA's Animal Rule creates a regulatory pathway for efficacy testing where human challenge studies are unethical, sustaining demand for validated non-human primate and rodent models in US government-funded research programs.
- Oncology Pipeline Expansion:Pharmaceutical companies in immuno-oncology are commissioning CRISPR-edited humanized mouse models to profile checkpoint inhibitor combinations, converting standardized catalog purchases into custom development contracts.
- China's NMPA Alignment:China's national pharmaceutical regulator is harmonizing preclinical data requirements with ICH guidelines, compelling domestic biotech firms to source GLP-compliant animal studies from certified international suppliers.
Market Restraints
- Primate Supply Concentration:Cambodia, Vietnam, and Mauritius control over 80% of cynomolgus macaque breeding capacity, exposing buyers to export moratoria and CITES permitting volatility.
- Genetic Drift in Outbred Lines:Standardized rodent colonies accumulate spontaneous mutations across generations, degrading phenotype reproducibility and forcing expensive colony refresh cycles.
- 3Rs Compliance Burden:EMA's Committee for Medicinal Products for Human Use tightens justification requirements for primate use through marketing authorization assessments, extending study design timelines.
Strategic Opportunities
- Human-Relevant Method Convergence:Organ-on-chip platforms paired with computational toxicology models offer hybrid validation pathways that reduce live animal dependency while preserving regulatory acceptability for standard safety endpoints.
- India's Contract Research Expansion:India's CDSCO is expanding GLP certification capacity for domestic vivarium infrastructure, positioning the country as a lower-cost alternative for rodent toxicology studies serving export markets.
- Japan's Regenerative Medicine Demand:Japan's PMDA accelerated approval framework for cell and gene therapies is stimulating demand for immunodeficient mouse models with humanized immune systems for xenograft efficacy studies.
Industry Challenges
- Veterinary Pathology Specialist Scarcity:Board-certified veterinary pathologists capable of interpreting lesion data for regulatory submissions command premium compensation, constraining study throughput at mid-sized contract research organizations.
- Biosecurity Infrastructure Capex:African Swine Fever and SARS-CoV-2 containment requirements are forcing vivarium operators to upgrade HVAC filtration, staff decontamination protocols, and sentinel monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Animal Model Market |
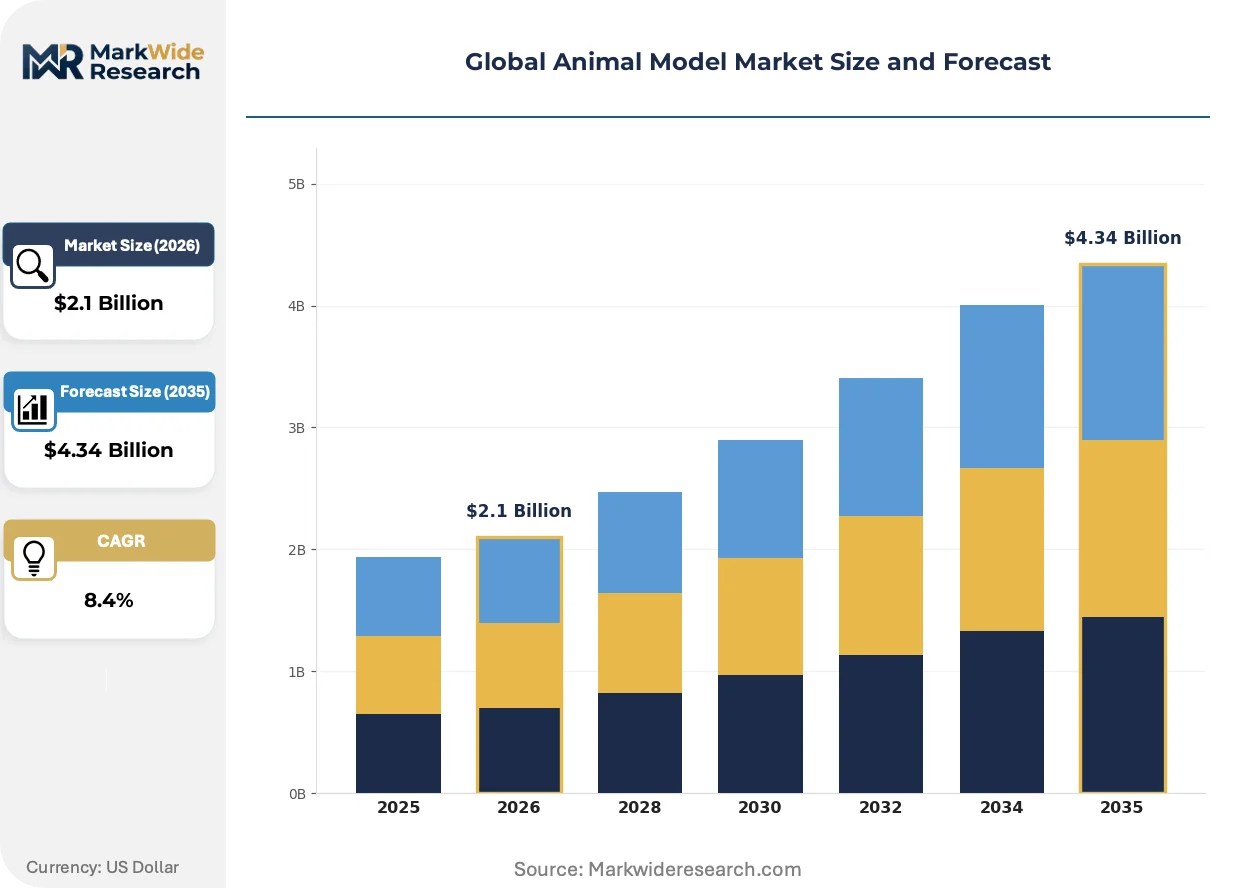
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Model Type: Rodents, Non-Human Primates, Invertebrates, Avian, Amphibians Application: Disease Modeling, Drug Discovery, Toxicology Testing, Behavioral Studies, Genetic Research End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Contract Research Organizations, Government Laboratories Deployment: In Vivo Testing Facilities, Ex Vivo Systems, In Vitro Surrogates, Computational Simulation Platforms |
| Companies Covered | GenOway, Crown Bioscience, Charles River Laboratories International Inc., Inotiv, Janvier Labs, The Jackson Laboratory, Eurofins Scientific SE, BIOCYTOGEN, Taconic Biosciences, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Animal Model Market Shifts & Advancements
CRISPR-editing workflows, regulatory acceptance frameworks for alternative methods, and procurement model consolidation are restructuring how pharmaceutical and biotechnology firms source predictive biology substrates.
CRISPR-Cas9 germline editing is modularizing the production of humanized rodent lines carrying patient-derived oncogenic mutations or immune checkpoint knock-ins. Large pharmaceutical companies are internalizing this capability through captive breeding programs rather than relying on catalog distributors. The technology is compressing model development timelines from 18 months to under 6 months for standard knockouts.
The EU Green Deal's chemical sustainability targets are redirecting contract research organization investment toward validated in vitro and computational methods. REACH registration deadlines are tightening mammalian study waivers for substances with adequate alternative data packages. European toxicology service providers are responding by acquiring organ-on-chip startups and building computational toxicology divisions.
Consolidated procurement through preferred supplier agreements is displacing project-by-project vendor selection at top-20 pharmaceutical companies. Centralized model sourcing teams are negotiating enterprise pricing and dedicated colony capacity with single-source partners. This concentration is most visible in the United States, where National Institutes of Health grant recipients face pressure to demonstrate cost efficiency through volume commitments.
Global Animal Model Market Segmentation
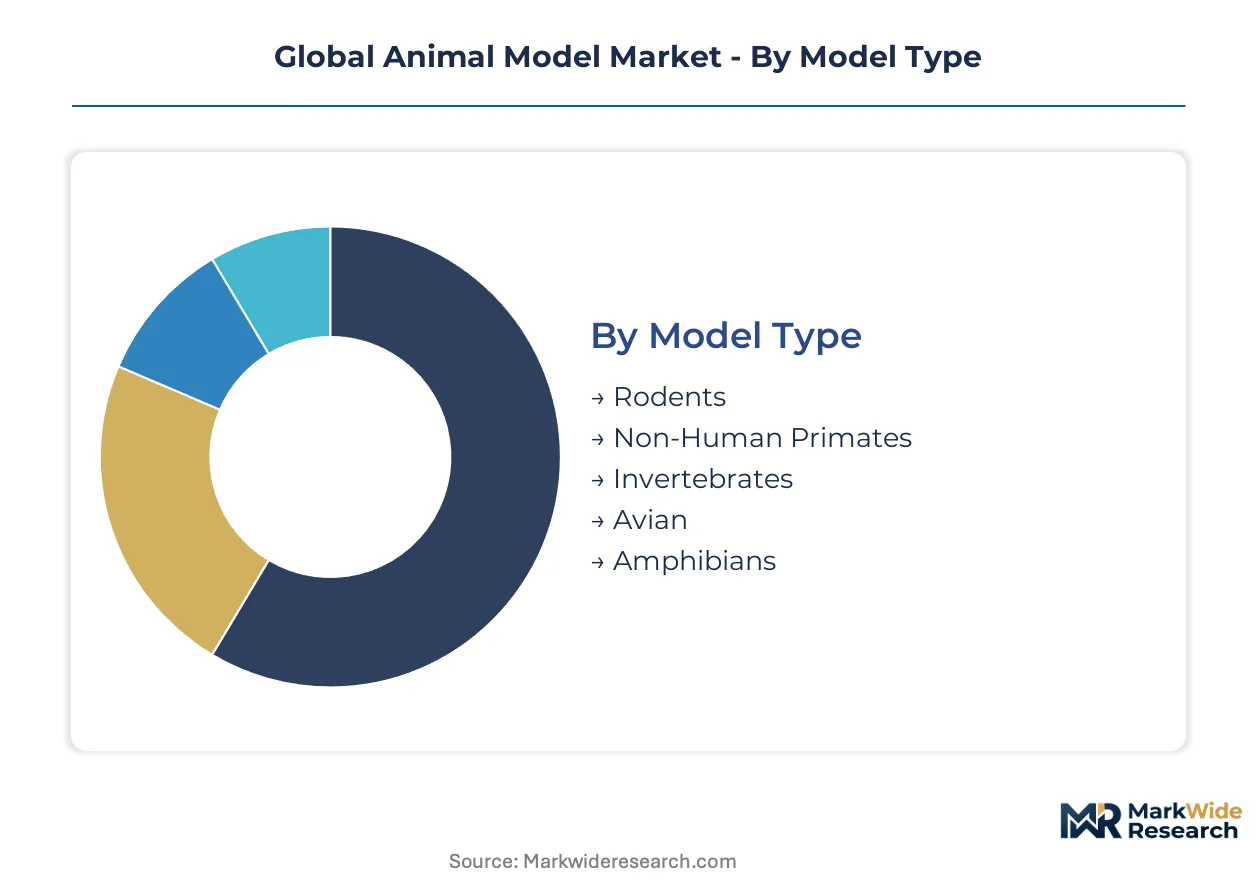
Animal model procurement hinges on regulatory validation tiers that vary sharply across species and study types. Pharmaceutical sponsors map segment selection directly to FDA Animal Rule pathways, EMA 3Rs compliance thresholds, and OECD Test Guideline specifications.
Model Type:
GLP certification requirements escalate from rodent facilities through primate centers, with FDA and EMA audit frequencies determining viable supplier pools for each segment.
- Rodents:Mice and rats engineered through CRISPR-Cas9 germline editing constitute the volume backbone of preclinical pharmacology. Pharmaceutical companies in the United States commission humanized mouse lines for immuno-oncology checkpoint inhibitor profiling, converting standardized catalog purchases into exclusive development contracts.
- Non-Human Primates:Cynomolgus and rhesus macaques provide phylogenetic proximity essential for Fc receptor biology and complement activation risk assessment in biologic safety studies. Cambodia, Vietnam, and Mauritius control breeding capacity, exposing buyers to CITES permitting volatility and export moratoria.
- Invertebrates:Drosophila melanogaster and Caenorhabditis elegans serve high-throughput genetic screening with minimal regulatory burden.
- Avian:Chicken embryos support developmental toxicity and vaccine production applications under streamlined protocols.
- Amphibians:Xenopus laevis and tropicalis models anchor developmental biology and ecotoxicology research.
Leading the category by volume: Rodents. Growing fastest: Non-Human Primates.
Application:
Study design complexity and timeline pressure fragment demand across therapeutic areas, with oncology commanding premium pricing for custom genetically engineered models.
- Disease Modeling:Patient-derived xenografts and CRISPR-edited oncogenic mutations replicate human pathology for mechanism-of-action studies. Japan's PMDA accelerated approval framework for cell and gene therapies stimulates demand for immunodeficient mouse models with humanized immune systems.
- Drug Discovery:Lead optimization programs require pharmacokinetic and efficacy validation in predictive substrates before clinical entry. China's NMPA alignment with ICH guidelines compels domestic biotech firms to source GLP-compliant studies from certified international suppliers.
- Toxicology Testing:REACH registration deadlines and EPA Test Guidelines prescribe species-specific protocols for environmental and pharmaceutical safety assessment.
- Behavioral Studies:Academic institutions sustain foundational demand for neuropharmacology and psychiatric drug development.
- Genetic Research:Spontaneous mutation characterization and gene function elucidation drive basic science procurement.
Disease Modeling captures the steepest expansion trajectory as immuno-oncology pipelines multiply. Toxicology Testing maintains the largest absolute spend.
End User:
Procurement scale and exclusivity requirements divide the customer base, with top-20 pharmaceutical companies consolidating through preferred supplier agreements.
- Pharmaceutical Companies:Internal captive breeding programs and enterprise pricing negotiations with single-source partners characterize large-cap sponsor behavior. Centralized model sourcing teams at US and European headquarters demand dedicated colony capacity.
- Biotechnology Firms:Virtual development models rely on contract research organizations for flexible, milestone-based study execution without fixed infrastructure investment.
- Academic Institutions:NIH grant recipients face cost efficiency pressure through volume commitments to approved vendor networks.
- Contract Research Organizations:Charles River Laboratories and Eurofins Scientific extend distributed vivarium infrastructure to reduce logistics stress on live shipments.
- Government Laboratories:US biodefense countermeasure programs under FDA Animal Rule sustain validated non-human primate and rodent model demand.
Pharmaceutical Companies dominate segment value. Biotechnology Firms are expanding most quickly as venture-funded immuno-oncology startups proliferate.
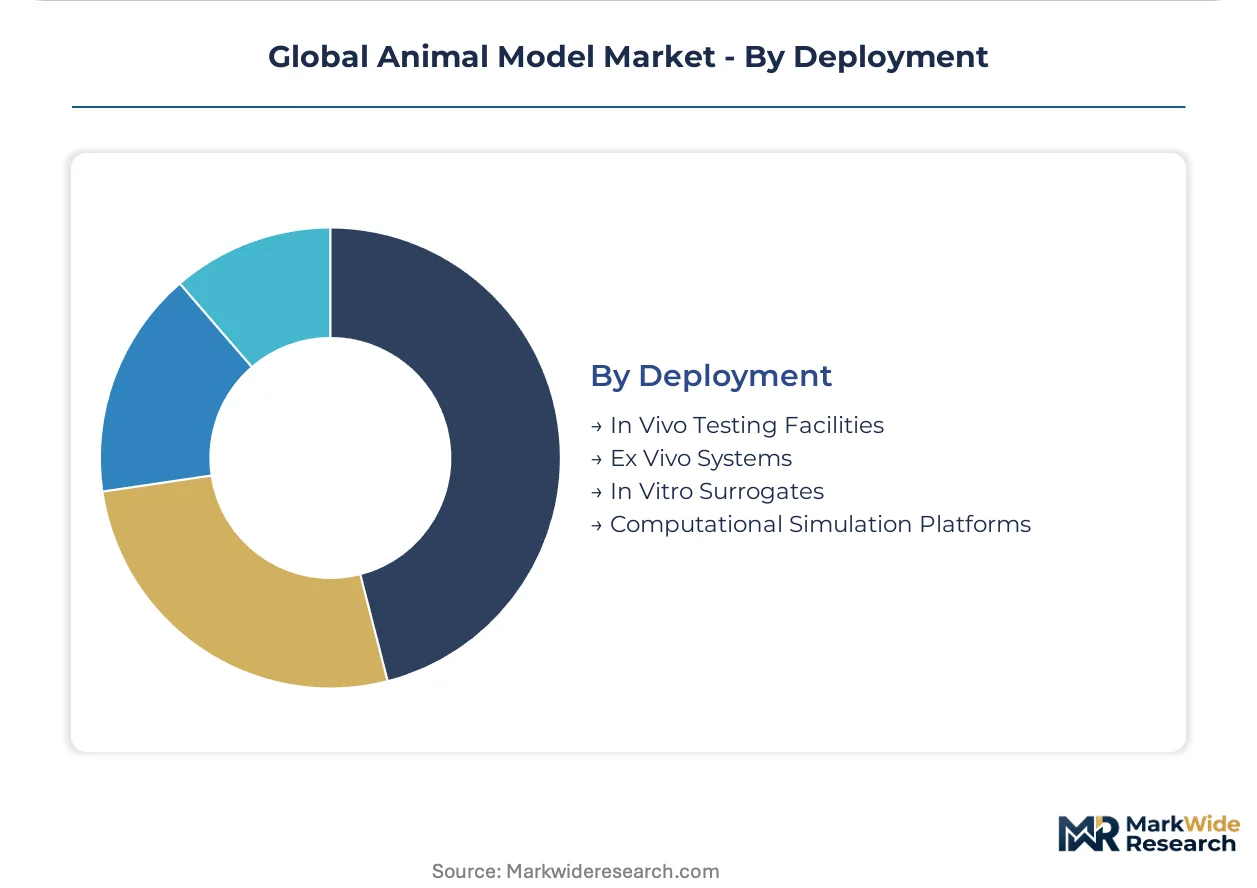
Deployment:
Regulatory acceptance timelines for alternative methods determine hybrid study designs that blend traditional in vivo with emerging platform technologies.
- In Vivo Testing Facilities:GLP-certified vivariums with biosecurity infrastructure for African Swine Fever and SARS-CoV-2 containment anchor regulatory submission packages. HVAC filtration and sentinel monitoring upgrades constrain mid-sized operator capacity.
- Ex Vivo Systems:Precision-cut tissue slices and organ cultures bridge whole-animal and cellular approaches for mechanistic toxicology.
- In Vitro Surrogates:Organ-on-chip platforms paired with computational models offer hybrid validation pathways under EU Green Deal chemical sustainability targets.
- Computational Simulation Platforms:AI-driven toxicology prediction and physiologically-based pharmacokinetic modeling reduce live animal dependency for standard safety endpoints.
In Vivo Testing Facilities retain regulatory submission dominance. Computational Simulation Platforms are gaining share fastest as EMA and FDA pilot qualification pathways for alternative methods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cambridge, Massachusetts anchors the world's densest concentration of genetically engineered rodent production, with MIT and Harvard spin-offs clustering around Kendall Square's biotech corridor.
United States
The National Institutes of Health sustains the largest publicly funded preclinical research ecosystem, with grant recipients directing substantial procurement toward GLP-certified vivarium networks. FDA's Animal Rule pathway for biodefense countermeasures sustains validated non-human primate demand through government-funded research programs. The San Francisco Bay Area and Boston metropolitan region concentrate contract research organization capacity for pharmaceutical sponsor studies.
China
Domestic biotech firms are expanding CRISPR-edited rodent production to serve immuno-oncology pipeline validation. NMPA harmonization with ICH guidelines compels sourcing of GLP-compliant studies from certified international suppliers. Shanghai and Suzhou industrial parks host expanding vivarium infrastructure targeting export market certification.
Germany
EMA's Committee for Medicinal Products for Human Use enforces stringent 3Rs justification requirements through marketing authorization assessments. EU Directive 2010/63/EU elevates sourcing compliance costs across contract research networks. Munich and Heidelberg clusters specialize in behavioral pharmacology studies for central nervous system drug development.
Japan
PMDA's accelerated approval framework for cell and gene therapies stimulates demand for immunodeficient mouse models with humanized immune systems. Domestic pharmaceutical sponsors commission xenograft efficacy studies under compressed timeline pressure. Osaka and Kobe harbor specialized breeding facilities serving regenerative medicine pipelines.
India
CDSCO expansion of GLP certification capacity positions the country as a lower-cost alternative for rodent toxicology studies serving export markets. Contract research organizations in Hyderabad and Bengaluru build distributed vivarium infrastructure to reduce logistics stress on live shipments. Government funding for pharmaceutical research infrastructure accelerates compliance upgrades.
Global Animal Model Market Competitive Landscape
The competitive structure tilts toward integrated service providers with captive breeding networks and GLP-certified study execution capabilities. Consolidation pressures favor organizations combining model production with toxicology service delivery. Three archetypes dominate: genome engineering specialists, full-service contract research organizations, and distributed vivarium operators. Strategic moves center on preferred supplier agreements with top-20 pharmaceutical companies and technology licensing for CRISPR editing workflows.
Within the integrated service tier, Charles River Laboratories International Inc. and Eurofins Scientific SE exemplify the convergence of captive breeding with regulatory-compliant study execution. GenOway occupies a specialist position representing the genome engineering archetype, differentiating through CRISPR-edited rodent lines rather than standardized catalog offerings. These three entities anchor the competitive landscape across North American and European procurement channels.
| Leading Market Players |
|---|
| GenOway |
| Crown Bioscience |
| Charles River Laboratories International Inc. |
| Inotiv |
| Janvier Labs |
| The Jackson Laboratory |
| Eurofins Scientific SE |
| BIOCYTOGEN |
| Taconic Biosciences, Inc. |
| Others |
Supply & Pricing Matrix
GLP certification tiering creates a bifurcated cost structure where FDA-audited vivarium capacity commands substantial premiums over non-certified breeding operations, concentrating pricing power among integrated service providers while compressing margins at mid-sized contract research organizations lacking captive colony networks.
Pricing Analysis
Throughput-linked pricing anchors the rodent segment, with pharmaceutical sponsors paying per-study premiums for humanized CRISPR-edited lines versus standardized catalog strains. Certification grade and customization depth drive differentiation, with exclusive development contracts carrying three-to-five-fold multiples over off-the-shelf purchases. Cost compression in standardized rodent offerings is intensifying as Chinese domestic producers expand GLP-compliant capacity. Biotechnology firms exhibit highest price sensitivity due to milestone-dependent funding, while government biodefense programs demonstrate lowest sensitivity given regulatory mandate requirements.
Supply Chain Analysis
Live animal return flows are structurally absent, creating unidirectional logistics dependencies where temperature-controlled air freight and customs clearance delays directly degrade specimen viability. Cambodia, Vietnam, and Mauritius concentrate cynomolgus macaque breeding, while the United States and China anchor genetically engineered rodent production. Germline-edited founder lines and specific-pathogen-free breeding stock constitute critical input dependencies. Single-source vulnerability pervades primate supply given CITES permitting concentration. Distribution runs through specialized courier networks with dedicated veterinary escort protocols rather than standard freight channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU Directive 2010/63/EU and FDA Animal Rule requirements erect substantial barrier-to-entry moats, advantaging incumbent players with established GLP certification and captive breeding infrastructure against capital-constrained challengers.
For Market Incumbents: Deepen backward integration into CRISPR editing workflows to compress model development timelines below six months, defending against genome engineering specialists capturing custom contract share. Expand dedicated colony capacity in India and China to offset primate supply concentration risk in Southeast Asia. Fortify preferred supplier agreements with top-20 pharmaceutical sponsors through enterprise pricing and exclusive capacity reservations.
For New Entrants and Emerging Players: Launch via organ-on-chip platform partnerships targeting REACH registration waivers under EU Green Deal chemical sustainability mandates, penetrating the fastest-growing alternative method segment. Target India's CDSCO-expanding GLP certification corridor for rodent toxicology outsourcing demand. Position as hybrid validation providers bridging in vivo and computational approaches rather than competing directly on captive breeding infrastructure.
For Investors and Strategic Acquirers: Re-rating potential sits with genome engineering specialists possessing proprietary CRISPR editing platforms given pharmaceutical sponsor demand for humanized immuno-oncology models. Long-term viability favors integrated service providers combining model production with toxicology execution capabilities. Monitor FDA and EMA pilot qualification pathways for organ-on-chip and computational simulation platforms as inflection signals for alternative method substitution rates.
| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Editing Workflow Internalization | Pharmaceutical sponsors compress model development timelines from 18 months to under 6 months for standard knockouts. |
| Preferred Supplier Agreement Consolidation | Top-20 pharmaceutical companies negotiate enterprise pricing and dedicated colony capacity with single-source partners. |
| Organ-on-Chip Platform Acquisition | European contract research organizations acquire startups to build hybrid validation pathways under REACH registration deadlines. |
| India GLP Certification Expansion | CDSCO capacity buildout positions the country as lower-cost alternative for rodent toxicology studies serving export markets. |
| Primate Supply Diversification | Vietnam and Mauritius breeding capacity investments reduce CITES permitting volatility exposure for biologic safety assessment demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across vivarium operators, pharmaceutical development executives, regulatory affairs leads, and contract research organization procurement directors. FDA Animal Rule guidance documents, EMA marketing authorization assessments, and OECD Test Guidelines provided protocol-specific validation. NIH grant expenditure databases and CDSCO certification registries supplied demand-side calibration. Bottom-up model production capacity estimates triangulated against top-down pharmaceutical R&D spending allocations.
Data-stream reconciliation across species-specific supply volumes, study-type demand segmentation, and regional regulatory compliance tiers generated consistent projections. Segmentation dimensions spanned model type, application area, end-user archetype, and deployment modality across the analysis window. CAGRs derived from compound growth trajectory fitting against historical capacity expansion and pipeline announcement patterns. Forecast inputs incorporated CRISPR editing adoption curves and alternative method regulatory acceptance timelines.
Export moratoria, genetic drift in standardized colonies, and accelerated alternative method qualification are the dominant revision risks to supply and demand assumptions. Forecasts reflect documented assumptions regarding regulatory pathway stability and pharmaceutical sponsor outsourcing propensity. Practitioners should monitor CITES permitting volatility, 3Rs compliance threshold tightening, and organ-on-chip validation milestones for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Global Veterinary Infusion Pumps Market
Veterinary
Rabies Veterinary Vaccines Market
Veterinary
Clonorchiasis Market
Veterinary
Pet Hypothyroidism Therapy Market
Veterinary
US Companion Animal Diagnostics Market
Veterinary
Global Veterinary Rapid Test Market
Veterinary
Pet Cancer Therapeutics Market
Veterinary
Veterinary Wound Sprays Market
Veterinary
Australia Veterinary Healthcare Market
Veterinary
Veterinary Vaccines Market
Veterinary
Companion Animal Drugs Market
Veterinary
Global Porcine Vaccine Market
Veterinary
Veterinary Point-Of-Care Diagnostics Market
Veterinary
Orthopedic Dog Bed Market
Veterinary
Bovine Respiratory Disease Treatment Market
Veterinary
Europe Veterinary Vaccine Market