
 Veterinary Clostridium Vaccine Market | 2026-2036
Veterinary Clostridium Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Clostridium Vaccine Market Analysis
India's veterinary manufacturing corridor is tilting toward biological production, with Zoetis Services LLC leveraging its local formulation capabilities to serve South Asian ruminant herds. Boehringer Ingelheim International GmbH anchors European supply through specialized toxoid production platforms. Merck Animal Health competes in the North American cattle segment with integrated diagnostics-to-vaccine service models.
Veterinary Clostridium vaccines are inactivated bacterial preparations containing toxoids or bacterins derived from Clostridium chauvoei, septicum, novyi, perfringens, or haemolyticum strains, formulated with adjuvants to elicit protective immunity against gas gangrene, enterotoxemia, and blackleg in livestock populations. Their primary commercial purpose is to reduce mortality, carcass condemnation, and production losses in intensive grazing and feedlot systems. Multivalent formulations now lead product type revenue pools by addressing multiple clostridial pathogens in single-dose protocols, while subcutaneous administration routes dominate delivery due to handler safety and reduced carcass blemish risk compared to intramuscular alternatives. Cattle represents the most mature animal type segment, though goat-specific demand is accelerating in Mediterranean and Middle Eastern supply chains.
USDA Center for Veterinary Biologics oversees batch release testing and facility licensing, while EMA's Committee for Medicinal Products for Veterinary Use shapes European label claims and withdrawal period standards. India's CDSCO and BIS frameworks are tightening import substitution requirements for veterinary biologicals, redirecting procurement toward domestic manufacturers. Stakeholders must monitor evolving residue-testing protocols at export destination borders and align formulation portfolios with regional strain prevalence databases.
Market Dynamics
Commercial livestock operations are consolidating procurement around multivalent formulations that reduce handling labor and injection-site lesions, compressing demand for single-pathogen products while elevating adjuvant performance standards across North American feedlot systems.
Growth Catalysts
- USDA Guidelines for Clostridial Disease Prevention:Updated federal protocols mandate expanded vaccination coverage in interstate cattle movements, creating compliance-driven procurement cycles for feedlot operators.
- Brazil Pre-Slaughter Certification Programs:Beef export protocols now integrate herd-health documentation, requiring documented toxoid administration for EU and Chinese market access.
- Adjuvant Platform Advances:Oil-in-water emulsion technologies are improving antigen presentation in ruminant species, extending duration of immunity and reducing booster frequency.
Market Restraints
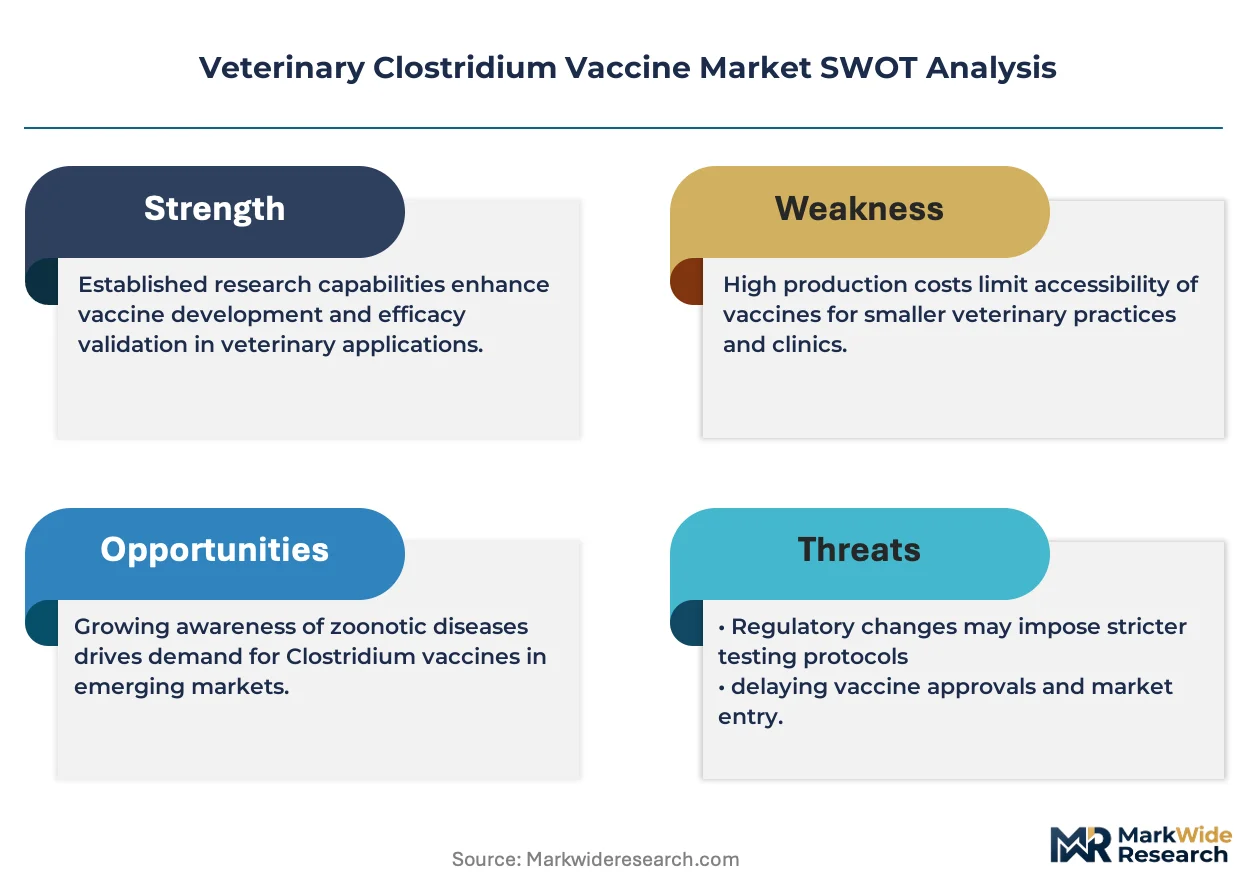
- Thermostability Limitations:Cold-chain requirements for aluminum-hydroxide-adjuvanted products restrict distribution reach in sub-Saharan African pastoral systems lacking reliable refrigeration infrastructure.
- Input Cost Volatility:Bovine serum albumin and specialized fermentation media prices fluctuate with pharmaceutical-grade raw material markets, squeezing margin structures for toxoid manufacturers.
- Regulatory Friction:Divergent EMA and USDA withdrawal period standards complicate label harmonization for multivalent products targeting transatlantic export herds.
Strategic Opportunities
- Indian Domestic Manufacturing Incentives:CDSCO import substitution frameworks and PLI scheme benefits are redirecting public sector procurement toward local biological production facilities.
- Goat-Specific Formulation Gap:Mediterranean and Middle Eastern supply chains lack optimized dosing protocols for small ruminant breeds, creating white space for species-tailored toxoid concentrations.
- Diagnostics-Vaccine Integration:Serological surveillance platforms paired with automated vaccination scheduling are emerging as bundled service offerings in North American integrated cattle operations.
Industry Challenges
- Strain Surveillance Infrastructure:National veterinary laboratories in major producing regions maintain incomplete Clostridium prevalence databases, complicating regional formulation decisions.
- Handler Certification Bottlenecks:Subcutaneous administration training requirements and needlestick safety protocols extend workforce onboarding timelines in expanding commercial operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Clostridium Vaccine Market |
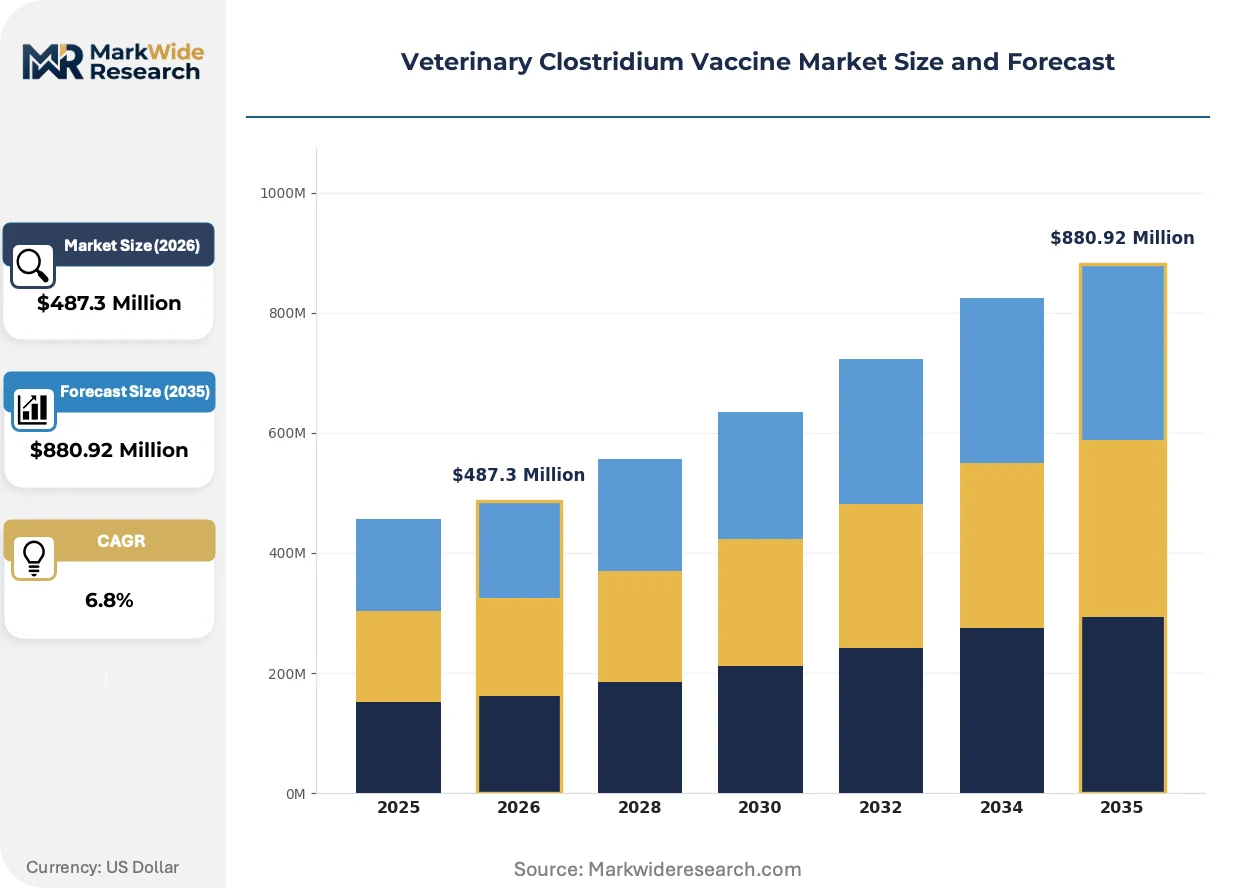
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monovalent, Bivalent, Trivalent, Multivalent Animal Type: Cattle, Swine, Sheep, Goats Administration Route: Intramuscular, Subcutaneous, Oral, Intravenous Distribution Channel: Veterinary Clinics, Online Stores, Pharmacies, Distributors |
| Companies Covered | Zoetis Services LLC, Boehringer Ingelheim International GmbH, Merck Animal Health, Elanco Animal Health, Virbac, Ceva, Bimeda, Inc., Bayer AG, HIPRA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Clostridium Vaccine Market Emerging Trajectories
Recombinant toxoid engineering and precision livestock monitoring are converging to reshape product development priorities, with manufacturers prioritizing duration-of-immunity data over traditional seroconversion metrics in label claims.
Molecular farming platforms using plant-based expression systems for clostridial antigens are hybridizing conventional bacterial fermentation supply chains. Early adopters in European research consortia are piloting Nicotiana benthamiana-derived toxoids for reduced endotoxin burdens. This technology is hybridizing cost structures by eliminating mammalian cell culture infrastructure while introducing novel glycosylation pattern regulatory review cycles.
EMA's revised immunological veterinary medicinal product guidelines now require enhanced pharmacovigilance reporting for multivalent combinations, extending post-authorization study obligations. Manufacturers face expanded field efficacy documentation requirements for novel adjuvant systems. Cattle operations in Germany and France are restructuring procurement contracts to allocate liability for adverse event reporting across distributor-veterinarian relationships.
Integrated health service contracts are displacing standalone vaccine transactions in North American feedlot segments, with buyers purchasing mortality risk reduction rather than unit doses. Major cattle feeding operations in Texas and Kansas now specify outcome-based performance guarantees tied to post-vaccination necropsy rates. This restructuring concentrates purchasing authority within livestock procurement departments rather than decentralized veterinary service providers.
Veterinary Clostridium Vaccine Market Segmentation
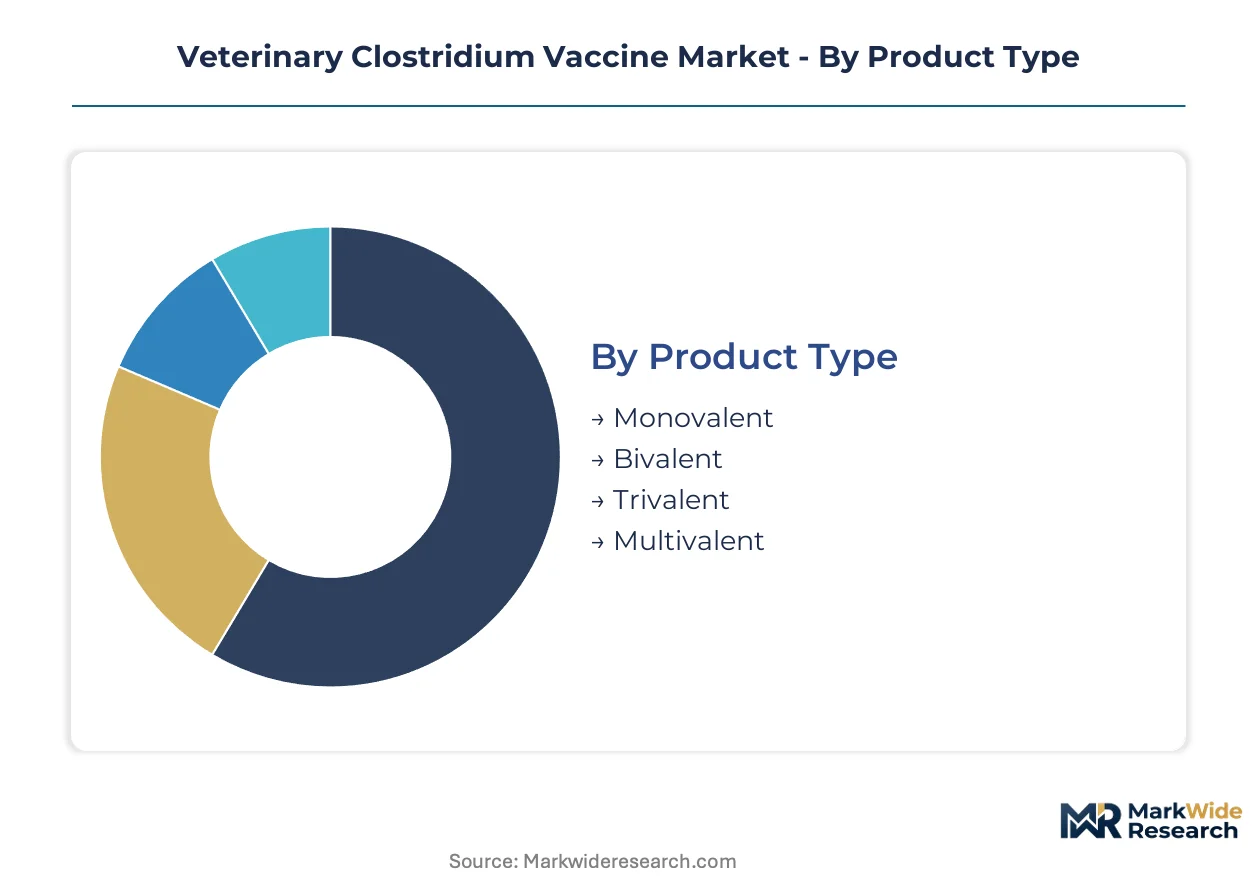
Veterinary Clostridium vaccine purchasing cycles vary sharply across product formulations and animal categories, with multivalent products commanding longer procurement horizons than monovalent alternatives. Understanding these turnover rhythms helps manufacturers align production schedules with seasonal vaccination windows in temperate grazing regions.
Product Type:
Cycle times stretch from annual replacement for basic monovalent stocks to multi-year supply agreements for advanced multivalent formulations, compressing cash conversion for simpler products while locking in extended revenue visibility for complex combinations.
- Monovalent:Single-pathogen formulations targeting Clostridium chauvoei or perfringens alone dominate price-sensitive pastoral operations in sub-Saharan Africa. Herd managers in Kenya and Nigeria rotate these products seasonally due to limited cold-chain endurance and constrained procurement budgets.
- Multivalent:Combined toxoid preparations addressing five to seven clostridial strains simultaneously anchor North American feedlot procurement through integrated health service contracts. Kansas and Texas cattle operations specify these formulations in outcome-based agreements tied to mortality reduction guarantees.
- Bivalent:Dual-strain products concentrate in Southeast Asian smallholder systems where blackleg-enterotoxemia combinations match prevalent disease patterns.
- Trivalent:Three-pathogen formulations serve specialized dairy operations in New Zealand requiring narrower protection profiles than full multivalent coverage.
Multivalent formulations anchor the volume base while goat-specific monovalent adaptations gain share at the steepest rate in Mediterranean supply chains.
Animal Type:
Customer concentration diverges between consolidated cattle feedlots purchasing at scale and fragmented small ruminant holders buying through veterinary intermediaries, reshaping margin structures across species lines.
- Cattle:Intensive beef and dairy operations in the United States, Brazil, and Australia drive bulk procurement of aluminum-adjuvanted toxoids with extended duration-of-immunity claims. Feedlot medicine protocols mandate clostridial coverage as a condition for mortality insurance eligibility.
- Goats:Mediterranean and Middle Eastern supply chains lack optimized dosing protocols for small ruminant breeds, creating formulation gaps that regional manufacturers in Turkey and Iran are addressing through species-specific concentration adjustments.
- Swine:Clostridium perfringens type C protection dominates farrowing house protocols in Denmark and the Netherlands, with sow vaccination schedules timed to colostral antibody transfer.
- Sheep:Pastoral systems in Australia and Uruguay rely on multivalent coverage against pulpy kidney and blackleg, with shearing-season administration windows dictating annual procurement timing.
Cattle operations concentrate the revenue base while goat vaccination protocols expand most quickly through Middle Eastern commercialization programs.
Administration Route:
Handler safety regulations and carcass quality standards are elevating subcutaneous protocols while intramuscular alternatives retreat to legacy herd management systems with less stringent blemish penalties.
- Subcutaneous:Neck or shoulder placement behind the ear dominates North American and European feedlot protocols, minimizing injection-site lesions that trigger carcass condemnation. USDA grading standards penalize intramuscular blemishes, reinforcing subcutaneous preference.
- Intramuscular:Deep muscle delivery persists in developing market pastoral systems where handler training infrastructure remains limited and needlestick safety protocols are less enforced.
- Oral:Drinking water and feed-administered formulations serve extensive grazing operations in Argentina and South Africa where mustering costs exceed vaccine delivery economics.
- Intravenous:Emergency therapeutic applications in acute toxemia cases represent a narrow niche, with products restricted to veterinary prescription channels in regulated markets.
Subcutaneous delivery anchors the volume base while oral administration gains share at the steepest rate in extensive ranching systems with high labor costs.
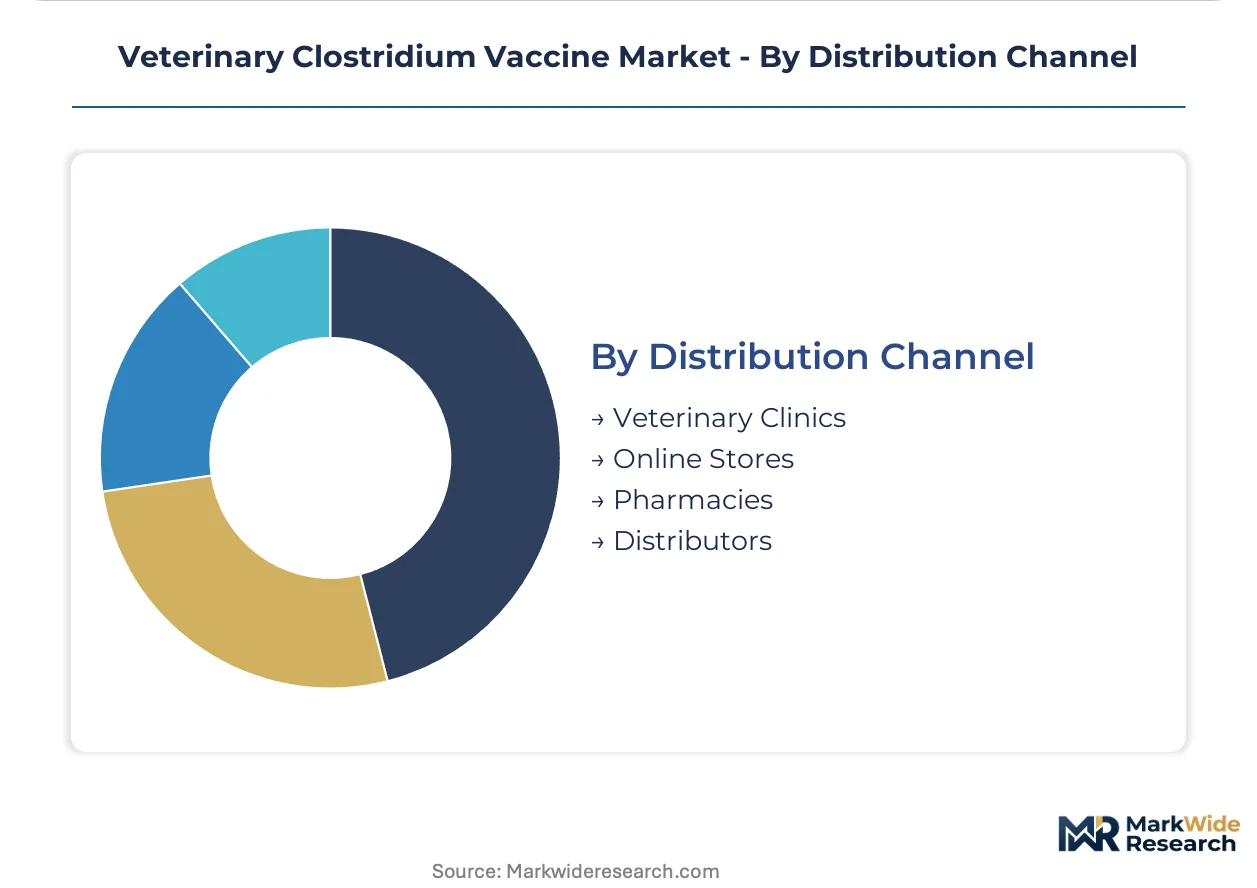
Distribution Channel:
Channel economics fragment between high-touch veterinary service relationships in developed markets and direct procurement efficiency pressures in emerging commercial livestock sectors.
- Veterinary Clinics:Full-service practices in Germany, France, and Japan bundle vaccination with serological surveillance and automated scheduling platforms, capturing premium positioning through outcome-based contracts.
- Distributors:Agricultural supply cooperatives in the United States and Brazil aggregate demand from mid-sized feedlots, negotiating volume discounts and consolidated delivery logistics.
- Online Stores:E-commerce penetration accelerates in Indian and Southeast Asian markets where veterinary pharmaceutical platforms bypass traditional wholesale markups for smallholder producers.
- Pharmacies:Retail pharmaceutical channels serve companion animal crossover demand and emergency livestock procurement in regions with limited veterinary infrastructure.
Veterinary clinics anchor the value base while online platforms gain share at the steepest rate in price-sensitive emerging markets with expanding digital infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biological manufacturing capacity clusters in the United States, Germany, Brazil, India, and Australia, with each jurisdiction shaping local procurement through distinct regulatory frameworks and livestock production economics.
United States
Feedlot operators in Kansas and Texas drive bulk toxoid procurement through integrated health service contracts tied to mortality reduction guarantees. USDA Center for Veterinary Biologics mandates batch release testing for interstate cattle movements, compressing procurement cycles around compliance deadlines. The Texas Panhandle cattle feeding corridor anchors North American demand for aluminum-adjuvanted multivalent formulations.
Germany
Specialized dairy operations in Bavaria and Lower Saxony require narrower protection profiles than full multivalent coverage, sustaining demand for trivalent and bivalent preparations. EMA's Committee for Medicinal Products for Veterinary Use shapes label claims and withdrawal period standards, complicating harmonization for export-oriented producers. The Baden-Württemberg research corridor pilots molecular farming platforms using Nicotiana benthamiana-derived toxoids.
Brazil
Beef export protocols now integrate herd-health documentation requiring documented toxoid administration for EU and Chinese market access. ANVISA oversees veterinary biological licensing while pre-slaughter certification programs concentrate procurement authority within São Paulo and Mato Grosso processing cooperatives. The São Paulo state livestock cluster drives multivalent formulation demand through vertically integrated export supply chains.
India
CDSCO import substitution frameworks and PLI scheme benefits redirect public sector procurement toward domestic biological production facilities in Maharashtra and Gujarat. Zoetis Services LLC leverages local formulation capabilities to serve South Asian ruminant herds. The Hyderabad-Vijayawada veterinary manufacturing corridor expands biological production capacity to capture regional smallholder demand.
Australia
Pastoral systems in New South Wales and Victoria rely on multivalent coverage against pulpy kidney and blackleg, with shearing-season administration windows dictating annual procurement timing. The country's national pharmaceutical regulator maintains stringent cold-chain standards that filter product entry. The Riverina sheep-grazing district sustains concentrated demand for Clostridium perfringens and septicum combinations.
Veterinary Clostridium Vaccine Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in toxoid fermentation and adjuvant supply. The market exhibits moderate consolidation among biological manufacturers with established veterinary distribution networks, while regional formulators compete on price in emerging markets. Three archetypes dominate: integrated animal health conglomerates with diagnostics-to-vaccine service models, specialized toxoid producers leveraging bacterial fermentation expertise, and regional biological manufacturers capturing import substitution opportunities. Competitive dynamics center on capacity expansion in Indian manufacturing corridors and strategic partnerships bundling serological surveillance with automated vaccination scheduling.
Among integrated animal health conglomerates, Zoetis Services LLC and Boehringer Ingelheim International GmbH occupy positions exemplifying the platform-integrator archetype through combined pharmaceutical and biological portfolios. Merck Animal Health represents the North American cattle-segment specialist model. These entities anchor competitive positioning through geographic manufacturing footprints and service bundling rather than standalone product differentiation, with each reflecting distinct strategic origins in human pharmaceutical development, dedicated animal health spinoffs, or regional biological heritage.
| Leading Market Players |
|---|
| Zoetis Services LLC |
| Boehringer Ingelheim International GmbH |
| Merck Animal Health |
| Elanco Animal Health |
| Virbac |
| Ceva |
| Bimeda, Inc. |
| Bayer AG |
| HIPRA |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on bovine serum albumin from pharmaceutical-grade suppliers determines both pricing tier spreads and supply chain shape, compressing margins for toxoid manufacturers while forcing regional formulators toward import substitution strategies. This input concentration cascades through multivalent formulation costs and cold-chain distribution economics.
Pricing Analysis
USDA Center for Veterinary Biologics batch release testing dictates the pricing tier structure, separating premium multivalent formulations with extended duration-of-immunity claims from standard aluminum-adjuvanted products and economy monovalent alternatives. Price differentiation rests on certification grade and volume scale, with integrated health service contracts commanding premium positioning through outcome-based mortality guarantees. Cost compression in the economy tier is intensifying because Kenyan and Nigerian pastoral operations rotate single-pathogen products seasonally due to constrained procurement budgets. Feedlot medicine protocols in Kansas and Texas exhibit the lowest price sensitivity, while sub-Saharan African smallholders demonstrate acute responsiveness to per-dose costs.
Supply Chain Analysis
Tariff exposure between the United States and Brazil dominates supply chain risk calculations for multivalent formulations targeting transatlantic export herds. Manufacturing gravity centers on the United States, Germany, and India, with toxoid fermentation drawing from bovine serum albumin, specialized fermentation media, and oil-in-water adjuvant inputs. Single-source vulnerability in pharmaceutical-grade raw material markets threatens production continuity for aluminum-hydroxide-adjuvanted products. Distribution runs through agricultural supply cooperatives in consolidated North American feedlot segments and veterinary pharmaceutical platforms in Indian and Southeast Asian smallholder systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a livestock cycle recovery phase anchored by expanded USDA clostridial coverage mandates and Brazilian pre-slaughter certification program rollouts, with procurement cyclicality tied to temperate grazing region seasonal vaccination windows.
For Market Incumbents: Insulate formulation portfolios against strain surveillance infrastructure gaps by deepening backward integration into toxoid fermentation capacity in the Hyderabad-Vijayawada corridor. Anchor channel control through diagnostics-vaccine integration bundles that automate vaccination scheduling for North American integrated cattle operations, neutralizing emerging regional formulators capturing CDSCO import substitution incentives. For New Entrants and Emerging Players: Establish a beachhead in goat-specific formulation gaps across Mediterranean and Middle Eastern supply chains where optimized dosing protocols for small ruminant breeds remain undeveloped. Target species-tailored toxoid concentration development as the most penetrable segment, leveraging local manufacturing partnerships in Turkey and Iran to bypass established cold-chain distribution barriers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized toxoid producers with bacterial fermentation expertise over diversified pharmaceutical conglomerates. Long-term viability across the analysis window hinges on molecular farming platform adoption and precision livestock monitoring integration. Watch serological surveillance platform penetration rates as the inflection indicator for outcome-based contract restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Molecular Farming Platform Development | EMA revised immunological veterinary medicinal product guidelines now require enhanced pharmacovigilance reporting for Nicotiana benthamiana-derived toxoid candidates. |
| Diagnostics-Vaccine Integration | Merck Animal Health and Zoetis Services LLC compete through bundled serological surveillance platforms paired with automated vaccination scheduling for Texas Panhandle feedlots. |
| Import Substitution Manufacturing | CDSCO frameworks and PLI scheme benefits redirect Indian public sector procurement toward domestic biological production facilities in Maharashtra and Gujarat. |
| Outcome-Based Contract Restructuring | Kansas and Texas cattle operations now specify mortality reduction guarantees tied to post-vaccination necropsy rates rather than unit dose transactions. |
| Goat-Specific Formulation Development | Turkey and Iran regional manufacturers address Mediterranean and Middle Eastern supply chain gaps through species-tailored toxoid concentration adjustments. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with feedlot medicine directors, veterinary biologics regulatory affairs leads, agricultural supply cooperative procurement managers, and toxoid fermentation plant engineers. Secondary validation drew from USDA Center for Veterinary Biologics batch release databases, EMA Committee for Medicinal Products for Veterinary Use submission records, CDSCO import substitution framework documentation, and ANVISA veterinary biological licensing filings. Bottom-up segmentation modeling triangulated against top-down macroeconomic livestock production forecasts.
Calibration anchored volume and value outputs to historical vaccination protocol adoption curves across temperate grazing regions. Segmentation dimensions spanned product type, animal species, administration route, and distribution channel complexity. CAGRs were derived through regression analysis of procurement cycle timing against seasonal administration windows. Forecast inputs incorporated strain prevalence database completeness scores and cold-chain infrastructure penetration rates by national veterinary laboratory network.
Sensitivities concentrate around thermostability breakthroughs eliminating aluminum-hydroxide-adjuvanted cold-chain requirements, EMA-USDA withdrawal period harmonization progress, and Brazilian pre-slaughter certification program enforcement intensity. Forecasts reflect documented assumptions regarding livestock export protocol evolution and regional manufacturing capacity expansion timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Spay and Neuter Market
Veterinary
Global Porcine Vaccine Market
Veterinary
North America Veterinary Healthcare Market
Veterinary
OTC Cat Medicines Market
Veterinary
Global Canine Influenza Vaccine Market
Veterinary
Mexico Veterinary Healthcare Market
Veterinary
Bovine Mastitis Market
Veterinary
Bovine Collagen Market
Veterinary
Veterinary Anesthesia Drugs Market
Veterinary
CBD Pet Market
Veterinary
North America and Europe Veterinary Telehealth Market
Veterinary
Orthopedic Dog Bed Market
Veterinary
Animal Antibiotics Market
Veterinary
Milking Salve Market
Veterinary
Veterinary Disinfectants Market
Veterinary
Global Dog Vaccines Market