
 Pet Light Therapy Devices Market | 2026-2036
Pet Light Therapy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Light Therapy Devices Market Insights
ISO 13485 certification for veterinary medical devices is reorganizing competitive entry barriers, forcing smaller suppliers to upgrade quality management systems or exit commercial channels. Companion Animal Health leverages its established veterinary distribution network to sustain placement in university teaching hospitals. LiteCure dominates the high-power laser segment through direct sales teams that control training and protocol development for certified veterinary technicians.
Pet light therapy devices emit specific wavelengths—typically 600–1000 nm in the red to near-infrared spectrum—to stimulate cellular metabolism through photobiomodulation, with power densities ranging from 10 mW/cm² for LED arrays to several watts for surgical-class lasers. LED therapy devices occupy the fastest-expanding tier as home-use protocols gain traction among pet owners seeking inflammation reduction without clinic visits. Pain management applications anchor professional segment margins, while wound healing protocols in animal hospitals command premium pricing due to required veterinary supervision and documentation standards.
FDA Center for Veterinary Medicine oversight of therapeutic laser claims, combined with FCC electromagnetic emissions compliance for electronic veterinary equipment, shapes product labeling and interstate commerce requirements for manufacturers. The EU MDR framework, though not yet fully harmonized for veterinary devices, pressures exporters to maintain dual technical files for human-grade and animal-grade certification pathways. Stakeholders must monitor whether emerging state-level veterinary practice acts in California, Texas, and Florida will restrict at-home laser use to prescription-only distribution, fundamentally altering channel economics for LED and infrared device categories.
Market Dynamics
ISO 13485 certification requirements are forcing veterinary device manufacturers to restructure quality management systems, elevating compliance costs while consolidating supplier tiers around audit-ready production facilities.
Growth Catalysts
- Photobiomodulation protocol standardization:Veterinary teaching hospitals in the United States are codifying treatment parameters for post-surgical recovery, creating referenceable clinical frameworks that accelerate equipment placement in specialty practices.
- FDA Class II clearance pathway maturation:The FDA Center for Veterinary Medicine has published clearer 510(k) guidance for therapeutic laser wavelength documentation, reducing submission cycle variability for manufacturers with robust technical files.
- Home-use LED device accessibility:Pet owners seeking inflammation management without clinic scheduling friction are driving direct-to-consumer channel development for lower-power red and near-infrared arrays.
Market Restraints
- Optical component supply concentration:High-precision laser diodes for therapeutic wavelengths depend on a limited supplier base concentrated in East Asian manufacturing clusters, exposing lead time volatility.
- Veterinary supervision mandates:State-level veterinary practice acts in jurisdictions including California and Texas restrict high-power laser deployment to credentialed personnel, constraining at-home market penetration for surgical-class devices.
- LED efficacy perception gaps:Professional segments retain preference for high-power laser platforms despite emerging clinical evidence for LED photobiomodulation, slowing category convergence.
Strategic Opportunities
- Telemedicine-integrated home protocols:Remote veterinary consultation platforms are creating prescription pathways for monitored at-home light therapy, bridging regulatory compliance with consumer convenience.
- Equine and production animal expansion:Large-animal veterinary practices represent underpenetrated demand for musculoskeletal pain management devices outside the concentrated companion animal segment.
- EU MDR harmonization preparation:Exporters investing in dual technical file systems for human-grade and veterinary-grade certification pathways will capture first-mover positioning as European regulatory clarity emerges.
Industry Challenges
- Certified veterinary technician training bottlenecks:Device manufacturers must maintain direct training infrastructure or partner with accredited continuing education providers to ensure protocol compliance and liability risk management.
- Dual-use classification ambiguity:Products spanning professional and consumer power thresholds face inconsistent state-level prescription requirements, complicating inventory and labeling strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Light Therapy Devices Market |
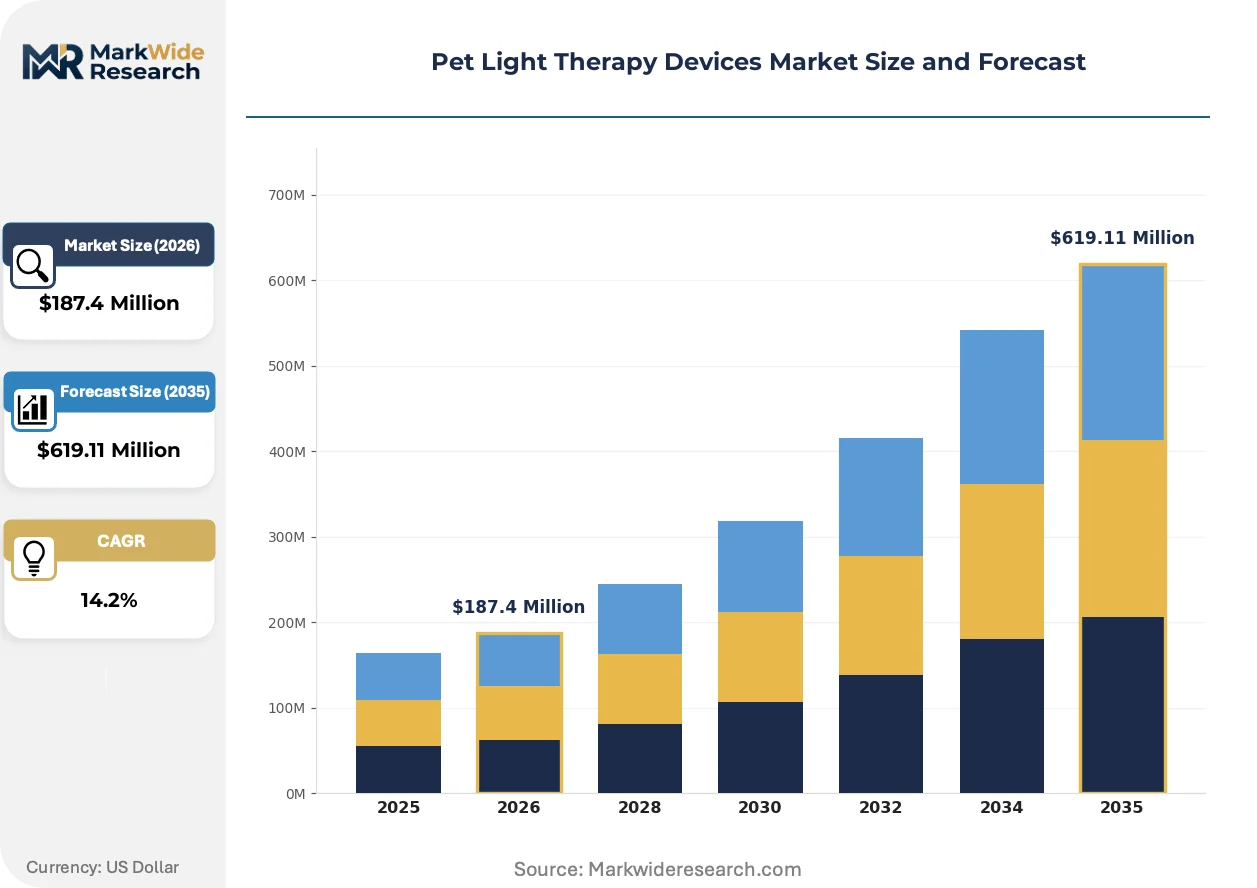
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Therapy Devices, LED Therapy Devices, Infrared Therapy Devices, UV Light Therapy Devices Application: Wound Healing, Pain Management, Inflammation Reduction, Arthritis Treatment, Skin Disorders End User: Veterinary Clinics, Animal Rehabilitation Centers, Pet Owners, Animal Hospitals Distribution Channel: Online Retailers, Specialty Pet Stores, Veterinary Distributors, Direct Sales |
| Companies Covered | Companion Animal Health, LiteCure, K-Laser, Respond Systems, Multi Radiance Medical, THOR Photomedicine, Erchonia, MedcoVet, BioPhotas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Light Therapy Devices Market Trends and Innovations
Device architecture is fragmenting into modular, software-configurable platforms that separate optical delivery from control systems, enabling rapid wavelength and protocol updates without hardware replacement cycles.
Multi-wavelength LED arrays with programmable spectral output are decomposing the historical dominance of fixed-wavelength laser platforms in professional settings. University teaching hospitals are piloting these systems for comparative efficacy studies. The technology is decomposing capital equipment refresh cycles by allowing firmware-based protocol expansion rather than device replacement.
The EU MDR framework is extending documentation requirements to veterinary device exporters even where full harmonization remains incomplete. Manufacturers must maintain technical files that satisfy both animal-grade and human-grade certification pathways. European distributors are demanding pre-submission evidence packages that anticipate eventual MDR veterinary annex coverage.
Subscription-based equipment access models are displacing outright purchase arrangements in multi-location veterinary practice groups. Corporate consolidators prefer per-treatment fee structures that align capital outlay with revenue generation. This shift is most visible in the United States, where specialty veterinary roll-ups are standardizing equipment procurement across acquired practices.
Pet Light Therapy Devices Market Segmentation
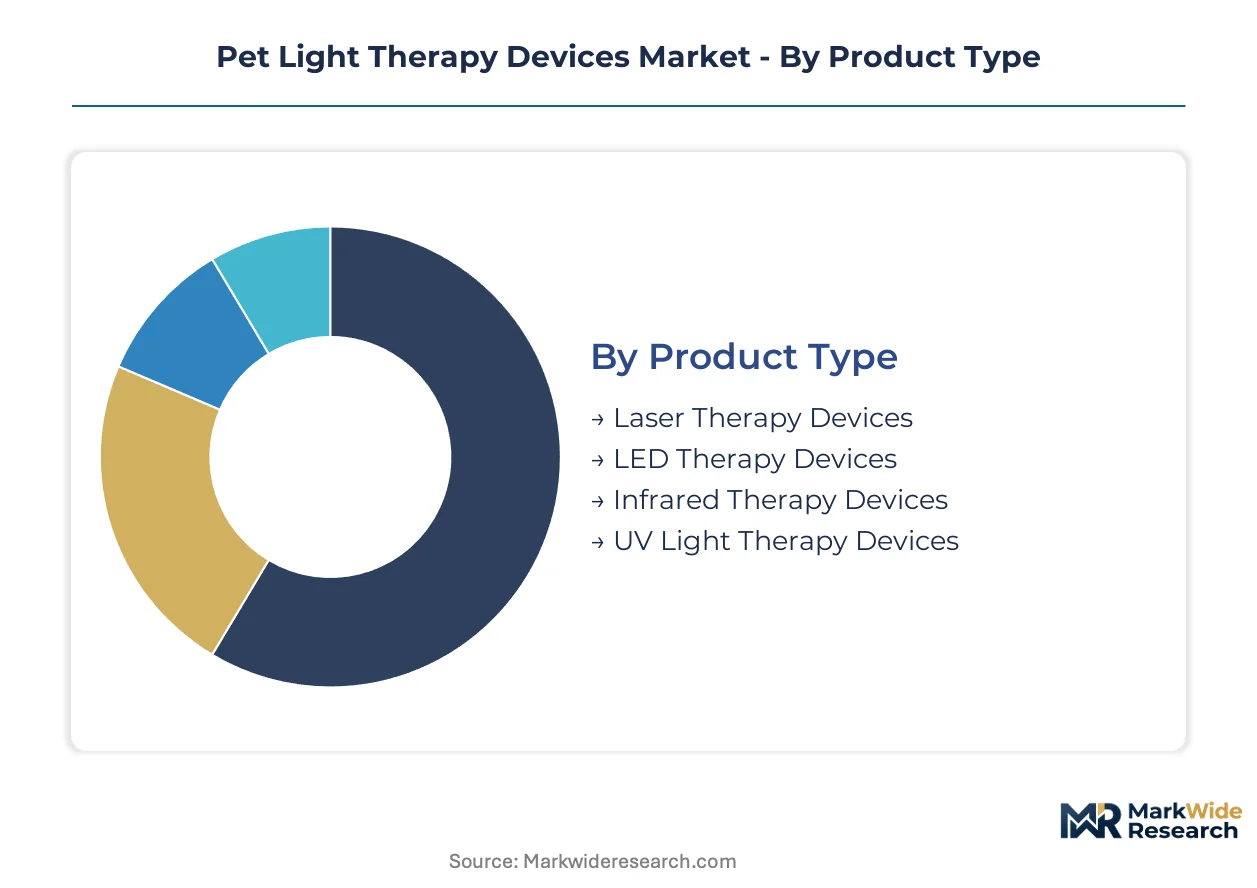
Segmentation in pet light therapy devices reveals how power specifications, supervision requirements, and channel economics partition demand across professional and consumer domains. Understanding these divides exposes where margin pools concentrate and where regulatory friction constrains expansion.
Product Type:
Channel access varies sharply by power output—high-wattage lasers flow through credentialed distribution requiring veterinary certification, while lower-power LED arrays reach consumers through direct-to-consumer platforms.
- Laser Therapy Devices:Surgical-class systems deliver 1-15 watts at precise therapeutic wavelengths (typically 800-980 nm), demanding active cooling and calibrated dosimetry. Demand concentrates in university teaching hospitals and specialty referral practices where certified veterinary technicians administer post-surgical protocols under FDA Center for Veterinary Medicine oversight.
- LED Therapy Devices:Arrays emitting 600-850 nm at 10-100 mW/cm² power densities operate without active cooling, enabling compact form factors. Expansion concentrates in direct-to-consumer channels where pet owners seek inflammation management for osteoarthritis and soft tissue injuries without clinic scheduling friction.
- Infrared Therapy Devices:Penetration depths of 3-5 centimeters suit deep musculoskeletal applications in equine and large-animal rehabilitation settings.
- UV Light Therapy Devices:Narrowband UVB emission targets dermatological conditions including allergic dermatitis and localized infections in controlled clinical environments.
Laser therapy devices dominate installed base in professional settings. LED therapy devices are where expansion concentrates fastest.
Application:
Reimbursement coding and supervision intensity create divergent margin profiles across therapeutic indications, with chronic conditions supporting recurring revenue streams.
- Pain Management:Photobiomodulation for osteoarthritis and post-operative analgesia commands premium pricing in specialty practices, anchored by American Animal Hospital Association protocol standardization and pet insurance reimbursement pathways.
- Wound Healing:Accelerated tissue repair applications require documented treatment parameters and veterinary supervision, concentrating demand in animal hospitals with surgical caseloads and structured follow-up protocols.
- Inflammation Reduction:Soft tissue inflammatory conditions drive home-use LED adoption where convenience outweighs power density advantages of clinical lasers.
- Arthritis Treatment:Chronic degenerative joint disease creates recurring treatment demand in geriatric companion animal populations, supporting subscription-based equipment access models.
- Skin Disorders:Dermatological phototherapy addresses allergic and autoimmune conditions with specialized UV and narrow-spectrum LED configurations.
Pain management anchors professional segment margins. Inflammation reduction is climbing fastest in consumer-accessible channels.
End User:
Capital intensity and regulatory exposure stratify the customer base, with institutional buyers prioritizing training infrastructure and liability frameworks over unit economics.
- Veterinary Clinics:General practice settings deploy mid-power laser and LED systems for routine post-surgical and chronic pain protocols, representing the volume foundation for equipment manufacturers with established distribution relationships.
- Animal Hospitals:Twenty-four-hour emergency and referral centers command the highest-power surgical-class lasers, where overnight staffing and intensive caseloads justify capital investment in multi-wavelength platforms.
- Animal Rehabilitation Centers:Dedicated physical therapy facilities integrate light therapy with hydrotherapy and therapeutic exercise, creating bundled service offerings for orthopedic and neurological recovery.
- Pet Owners:Home-use device purchasers respond to direct-to-consumer marketing emphasizing convenience and cost amortization over clinic visit accumulation, though state-level veterinary practice acts in California and Texas constrain prescription-free laser access.
Veterinary clinics dominate installed base across product tiers. Pet owners represent the steepest expansion trajectory as LED efficacy evidence accumulates.
Distribution Channel:
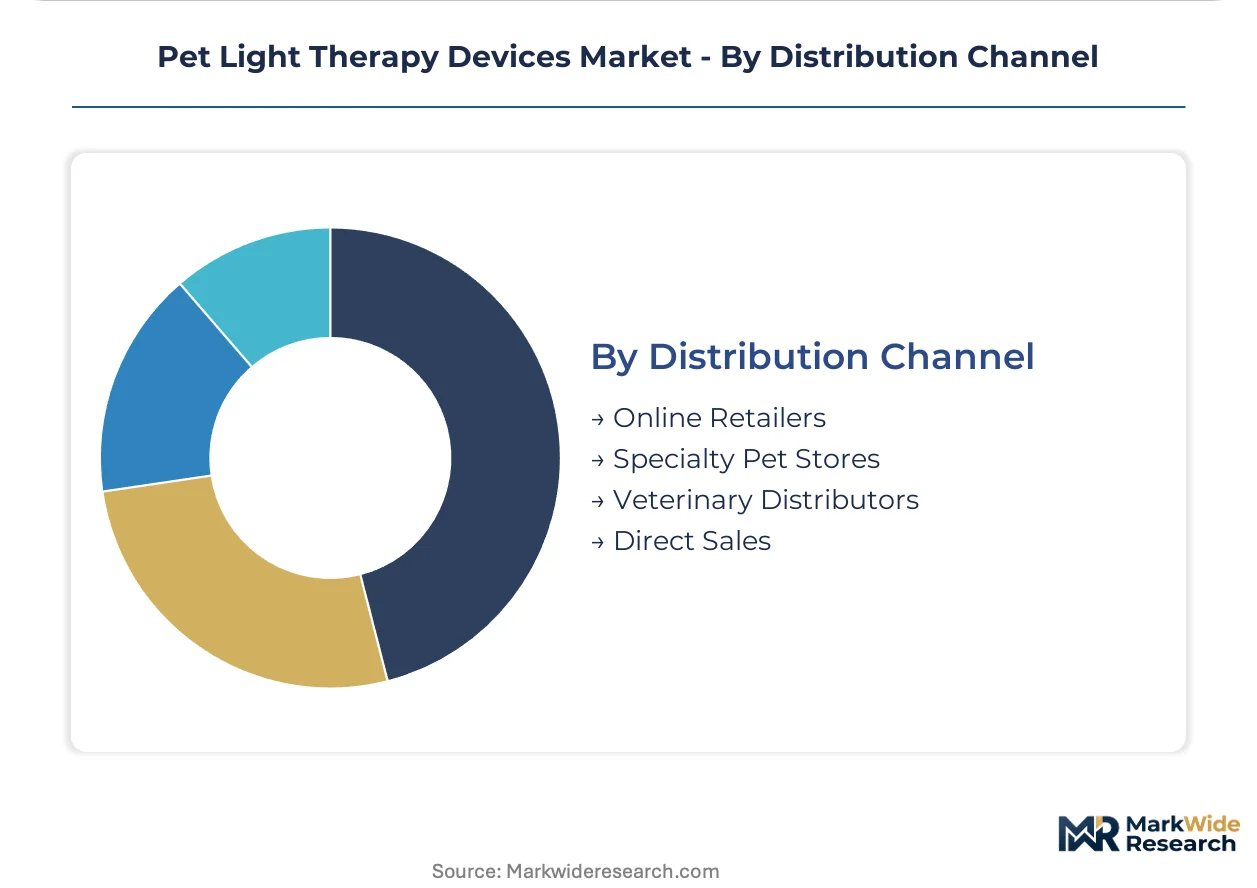
Channel selection locks in margin structure and customer relationship depth, with direct sales capturing training revenue and online platforms sacrificing service attachment for volume velocity.
- Veterinary Distributors:Henry Schein Animal Health and MWI Veterinary Supply control placement in independent practices, bundling equipment with continuing education credits and protocol certification programs.
- Direct Sales:Manufacturers including LiteCure and Companion Animal Health maintain captive sales organizations targeting multi-location specialty groups and university teaching hospitals with customized training infrastructure.
- Online Retailers:Amazon and Chewy facilitate LED device access for pet owners, though wavelength accuracy claims face limited verification compared to professional-grade procurement channels.
- Specialty Pet Stores:Premium brick-and-mortar retailers curate home-use wellness devices, emphasizing visible red-light aesthetics and companion grooming product adjacencies over clinical efficacy documentation.
Veterinary distributors dominate professional equipment flow. Online retailers are gaining share fastest in the home-use tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance pathways for veterinary therapeutic lasers are tightening documentation standards, while state-level veterinary practice acts in California, Texas, and Florida are reshaping distribution economics for home-use devices.
United States
Pet insurance penetration rates exceeding 3% of the dog and cat population are financing specialty veterinary equipment purchases. The FDA Center for Veterinary Medicine's 510(k) guidance for Class II therapeutic lasers demands wavelength-specific technical documentation. University teaching hospitals in California, Texas, and Florida are codifying photobiomodulation protocols for post-surgical recovery.
Germany
Veterinary specialty practice density in Bavaria and North Rhine-Westphalia supports premium equipment investment rates. The EU MDR framework pressures exporters to maintain dual technical files for human-grade and animal-grade certification pathways. Stuttgart-based veterinary distributors are bundling photobiomodulation equipment with continuing education credits.
United Kingdom
Corporate consolidators in the veterinary sector are standardizing equipment procurement across multi-location practice groups. The Veterinary Medicines Directorate maintains oversight of therapeutic device claims while the Medicines and Healthcare products Regulatory Agency evaluates cross-border import pathways. London-area specialty referral centers command the highest-power surgical-class laser installations.
Japan
Geriatric companion animal populations are driving chronic pain management device demand in metropolitan veterinary clinics. The Ministry of Agriculture, Forestry and Fisheries regulates veterinary medical devices through the Agricultural Chemicals Regulation Law. Tokyo and Osaka veterinary teaching hospitals are piloting multi-wavelength LED arrays for comparative efficacy studies.
Australia
Equine rehabilitation facilities in New South Wales and Victoria are expanding musculoskeletal pain management device adoption. The Therapeutic Goods Administration's exclusion of veterinary devices from medical device regulations creates streamlined market entry for imported equipment. Sydney-based veterinary distributors are developing subscription-based equipment access models for regional practice groups.
Pet Light Therapy Devices Market Competitive Landscape
Listed leaders compete with private specialists across distribution channel control and training infrastructure deployment. The vendor base concentrates around audit-ready production facilities holding ISO 13485 certification for veterinary medical devices. Three archetypes dominate: captive direct sales organizations targeting university teaching hospitals, veterinary distributor-dependent generalists, and direct-to-consumer LED specialists. Consolidation pressures are elevating M&A activity among mid-tier manufacturers while capacity expansion concentrates in East Asian optical component clusters.
Within the direct sales archetype, Companion Animal Health and LiteCure occupy positions defined by training infrastructure ownership and protocol development control. Among distributor-dependent manufacturers, K-Laser represents the European specialist tier. These named entities exemplify how competitive positioning in this market depends on channel relationship depth rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Companion Animal Health |
| LiteCure |
| K-Laser |
| Respond Systems |
| Multi Radiance Medical |
| THOR Photomedicine |
| Erchonia |
| MedcoVet |
| BioPhotas |
| Others |
Pricing and Supply Chain Analysis
LED diode substitution for surgical-class laser platforms is redrawing component sourcing maps from East Asian precision manufacturing clusters toward domestic assembly facilities, compressing landed costs while fragmenting supplier bargaining power across tiered certification categories.
Pricing Analysis
Certification level (ISO 13485/FDA 510(k)/CE-MDR tier) creates the primary spread between professional and consumer device price bands. Subscription-based equipment access models for multi-location veterinary groups displace per-unit transactional structures, with corporate consolidators preferring per-treatment fee arrangements. Cost compression in home-use LED tiers intensifies as wavelength verification standards diverge between Amazon-direct and veterinary distributor channels. Price sensitivity concentrates among independent general practice veterinarians, while university teaching hospitals exhibit lowest sensitivity due to grant-funded procurement protocols.
Supply Chain Analysis
East Asian optical component chokepoints in Taiwan, South Korea, and Japan concentrate high-precision laser diode fabrication for therapeutic wavelengths. Manufacturing draws from gallium arsenide substrates, sapphire wafers, and precision optical coatings as critical inputs. Single-source vulnerability in 980 nm diode production exposes lead time volatility for surgical-class device manufacturers. Distribution runs through captive direct sales teams for high-power systems and veterinary distributor networks for mid-tier equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pet light therapy devices occupy an early-cycle expansion phase where home-use LED protocol validation and telemedicine integration are accelerating penetration beyond traditional clinical boundaries.
For Market Incumbents: Shield installed base relationships by deepening ISO 13485 audit-ready production capacity and embedding training infrastructure within university teaching hospital networks. Counter emerging direct-to-consumer LED specialists through exclusive protocol development partnerships with certified veterinary technician education providers. Channel control remains the critical defensive lever against subscription-model disruptors. For New Entrants and Emerging Players: Remote veterinary consultation platform integration represents an underserved service layer where incumbents lack software-native capabilities. Target equine rehabilitation facilities and large-animal veterinary practices as the most penetrable segment outside saturated companion animal corridors. Pursue prescription-pathway partnerships with telemedicine providers as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier manufacturers holding dual FDA-EU technical file capabilities but lacking direct sales infrastructure. Long-term viability hinges on regulatory pathway ownership rather than manufacturing scale alone. Watch state-level veterinary practice act amendments in California, Texas, and Florida as the signal for channel economics inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Advancement | FDA Center for Veterinary Medicine clearance unlocks reimbursement coding and university hospital placement. |
| Telemedicine Platform Integration | Remote consultation protocols bridge prescription requirements with direct-to-consumer convenience. |
| ISO 13485 Certification Investment | Audit-ready quality management systems consolidate supplier tiers and exclude non-compliant competitors. |
| Equine Segment Expansion | Large-animal musculoskeletal applications offer underpenetrated demand outside companion animal saturation. |
| Subscription Equipment Access | Per-treatment fee structures align capital outlay with revenue generation for corporate veterinary consolidators. |
Research Methodology
Initial hypotheses were tested against primary input from veterinary practice owners, biomedical equipment procurement managers, certified veterinary technicians, and regulatory affairs specialists at FDA Center for Veterinary Medicine, then refined through secondary validation across FDA 510(k) filings, EU MDR technical file databases, American Animal Hospital Association protocol documentation, and pet insurance reimbursement code repositories. Bottom-up equipment shipment estimates triangulated against top-down veterinary practice spending surveys.
Variance decomposition across product type, application indication, end-user facility tier, and distribution channel anchored the analytical framework over the projection horizon. CAGRs derived from segment-level adoption curves weighted by veterinary practice consolidation rates and pet insurance penetration trajectories. Forecast inputs incorporated photobiomodulation protocol standardization timelines and state-level veterinary practice act amendment tracking.
Forecasts assume regulatory continuity in FDA Center for Veterinary Medicine oversight and EU MDR harmonization pathways; material policy shifts in prescription requirements or wavelength documentation standards would require re-modeling. Practitioners should keep alternative scenarios live as home-use LED efficacy evidence accumulation and telemedicine platform regulatory classification evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Global Veterinary MRI Market
Veterinary
Spain Veterinary Healthcare Market
Veterinary
Global Veterinary Artificial Insemination Market
Veterinary
Pet Hypothyroidism Therapy Market
Veterinary
Veterinary Respiratory Disease Treatment Market
Veterinary
Veterinary Thermography Market
Veterinary
Global Orthopedic Veterinary Implants Market
Veterinary
Clostridium Vaccine (Animal Health) Market
Veterinary
Europe Veterinary Healthcare Market
Veterinary
Veterinary Disinfectants Market
Veterinary
Mexico Veterinary Healthcare Market
Veterinary
Veterinary Endodontics Market
Veterinary
Global Veterinary Hematology Analyzers Market
Veterinary
Canine Arthritis Market
Veterinary
Milking Salve Market
Veterinary
Global Companion Animal Specialty Drugs Market