
 Canine Separation Anxiety Treatment Market | 2026-2036
Canine Separation Anxiety Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Canine Separation Anxiety Treatment Market Outlook
Buyer concentration across the canine separation anxiety treatment landscape is rebalancing, with pet owners gaining purchasing power relative to traditional veterinary gatekeepers while telehealth platforms fragment the prescriber base. Zoetis Inc. leverages its veterinary distribution infrastructure to sustain channel dominance in North American clinics. Elanco Animal Health anchors its position through R&D intensity in behavioral pharmacology. Virbac SA competes via geographic dominance across European veterinary networks.
Canine separation anxiety treatment encompasses pharmacological interventions, nutraceutical formulations, conditioning devices, and behavioral modification protocols designed to modulate stress responses in dogs exhibiting distress upon owner departure; formulations typically involve selective serotonin reuptake inhibitors, tricyclic antidepressants, or pheromone analogs administered orally or via environmental diffusers, with efficacy measured through validated behavioral scoring systems. Medications command the deepest margin pools due to prescription barriers and refill economics, while Training Tools represent the fastest-expanding category as owners seek non-pharmaceutical first-line interventions. Behavioral Aids occupy a mature niche with limited formulation innovation but stable replacement demand.
FDA Center for Veterinary Medicine oversight governs drug approval pathways, while EPA registration requirements constrain pheromone device marketing claims; the EU Veterinary Medicines Regulation and EMA Committee for Medicinal Products for Veterinary Use shape transatlantic product development standards. Stakeholders must monitor evolving telehealth prescribing rules and compounding pharmacy enforcement as regulatory fragmentation between jurisdictions intensifies compliance complexity.
Market Dynamics
Telehealth veterinary prescribing is fragmenting prescriber authority away from traditional clinic gatekeepers, while FDA Center for Veterinary Medicine oversight maintains prescription barriers that protect pharmaceutical margin pools against commoditization pressures from over-the-counter alternatives.
Growth Catalysts
- Humanization of Pet Relationships:Pet owners in the United States now spend more per household on veterinary behavioral health than any other major market, creating pull-through demand for anxiety interventions previously considered discretionary.
- EPA Pheromone Device Registration Pathway:Environmental diffuser products bypass prescription requirements while maintaining therapeutic claims, expanding addressable buyer segments beyond clinic-dependent pharmaceutical channels.
- Telehealth Platform Expansion:Remote veterinary consultation services enable prescription fulfillment without physical clinic visits, reducing friction for maintenance refills of chronic behavioral medications.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Sourcing of fluoxetine and clomipramine hydrochloride for veterinary formulations depends on a limited supplier base concentrated in Asian manufacturing clusters, exposing formulators to input cost volatility and supply continuity risk.
- FDA Compounding Enforcement:Increased scrutiny of 503B outsourcing facilities producing veterinary behavioral medications from bulk drug substances creates compliance friction for personalized dosing regimens outside approved label indications.
- Behavioral Modification Substitution:Certified applied animal behaviorists and board-certified veterinary behaviorists offer protocol-based interventions that reduce pharmaceutical dependency for mild-to-moderate cases, compressing first-line medication rates.
Strategic Opportunities
- Underpenetrated European Markets:France and Germany maintain lower veterinary behavioral medication penetration rates than the United States, presenting expansion potential for EMA-registered formulations through Virbac SA's established clinic networks.
- Wearable Biometric Monitoring Convergence:Integration of accelerometer-based stress detection collars with automated dispenser systems enables closed-loop intervention delivery, creating subscription revenue models beyond single-product sales.
- Direct-to-Consumer Nutraceutical Channels:E-commerce platforms bypass veterinary prescription requirements for L-theanine and alpha-casozepine supplements, capturing price-sensitive owners seeking non-pharmaceutical first-line options.
Industry Challenges
- Veterinary Behaviorist Talent Scarcity:Board certification through the American College of Veterinary Behaviorists requires residency training programs with limited annual matriculation, constraining diagnostic capacity for complex separation anxiety cases requiring multimodal protocols.
- Cross-Border Regulatory Divergence:EMA and FDA diverge on acceptable excipients and stability testing requirements for extended-release formulations, forcing dual-track development that extends time-to-market and inflates registration costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canine Separation Anxiety Treatment Market |
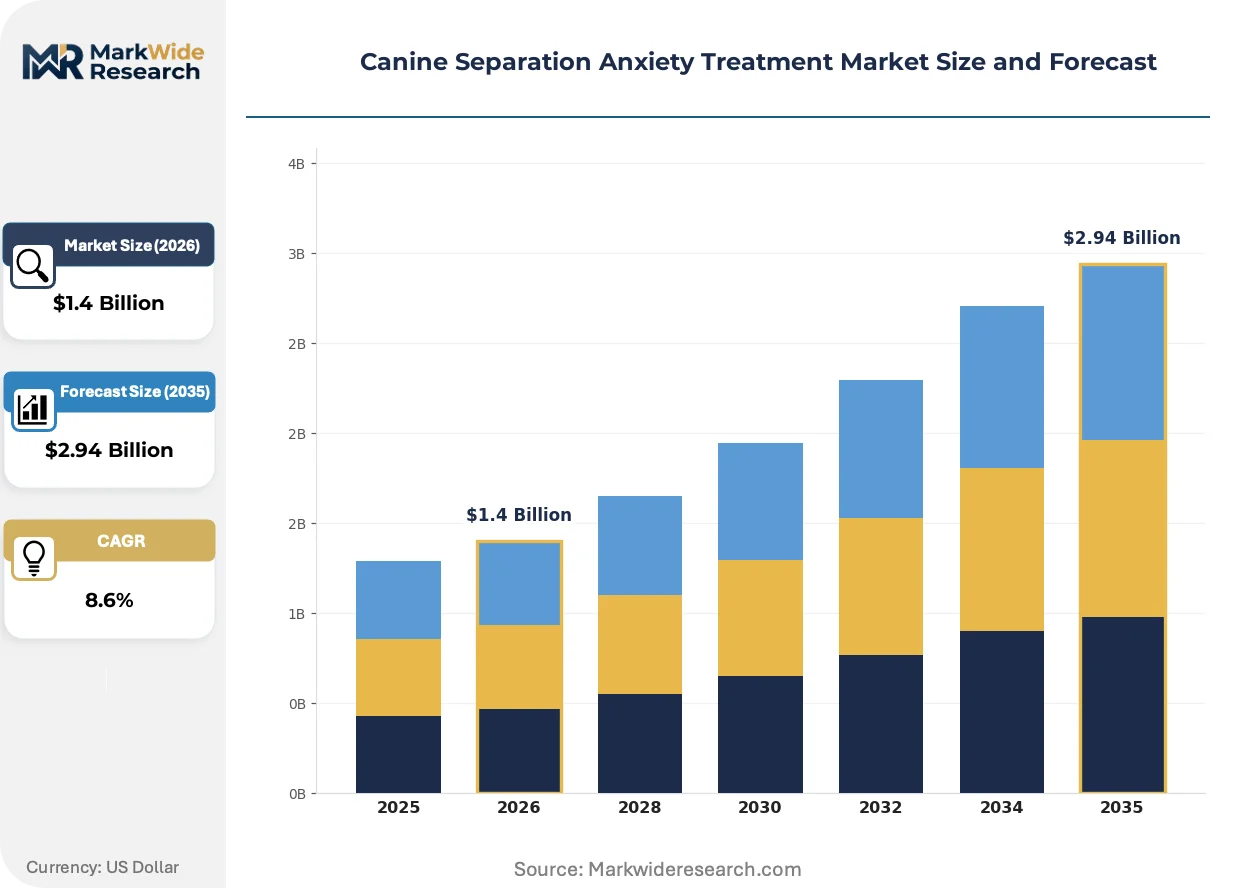
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Supplements, Training Tools, Behavioral Aids End User: Pet Owners, Veterinarians, Pet Trainers, Animal Behaviorists Distribution Channel: Online Stores, Veterinary Clinics, Pet Shops, Pharmacies Application: Short-Term Relief, Long-Term Management, Training Programs, Counseling Services |
| Companies Covered | Virbac SA, Teva Pharmaceutical Industries Ltd., Elanco Animal Health, Mizner Bioscience LLC, Pegasus Laboratories Inc. (PRN Pharmacal), Zoetis Inc., Dechra Pharmaceuticals PLC, Apotex Inc., Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canine Separation Anxiety Treatment Market Strategic Shifts
Artificial intelligence and connected hardware are redefining how canine separation anxiety is detected, diagnosed, and treated, shifting value capture from episodic pharmaceutical sales toward continuous monitoring and intervention platforms.
Smart collar systems equipped with heart rate variability sensors and machine learning algorithms is decentralizing diagnostic authority from veterinary clinics to owner-managed home environments. Pet technology adopters in the United States and United Kingdom are deploying these devices at accelerating rates, generating longitudinal behavioral datasets that enable predictive intervention timing before distress escalates to destructive behavior. This decentralizing of diagnostic control compresses the addressable market for traditional veterinary consultation while expanding recurring revenue opportunities for subscription-based monitoring services.
The EU Veterinary Medicines Regulation implementation is harmonizing pharmacovigilance requirements across member states, forcing manufacturers to consolidate previously fragmented national registration strategies into centralized EMA procedures. This regulatory consolidation elevates compliance costs for mid-sized formulators while creating competitive advantage for established players with dedicated regulatory affairs infrastructure. Transatlantic product development timelines are elongating as companies synchronize EMA and FDA submission packages to avoid market access gaps.
Subscription-based medication delivery is displacing single-transaction pharmacy fulfillment for chronic behavioral conditions. Direct-to-consumer platforms are capturing refill loyalty through automated dosing schedules and telehealth follow-up integration, particularly among millennial pet owners in urban United States markets. This channel migration threatens traditional veterinary clinic dispensing economics while enabling price transparency that pressures manufacturer list pricing strategies.
Canine Separation Anxiety Treatment Market Segmentation
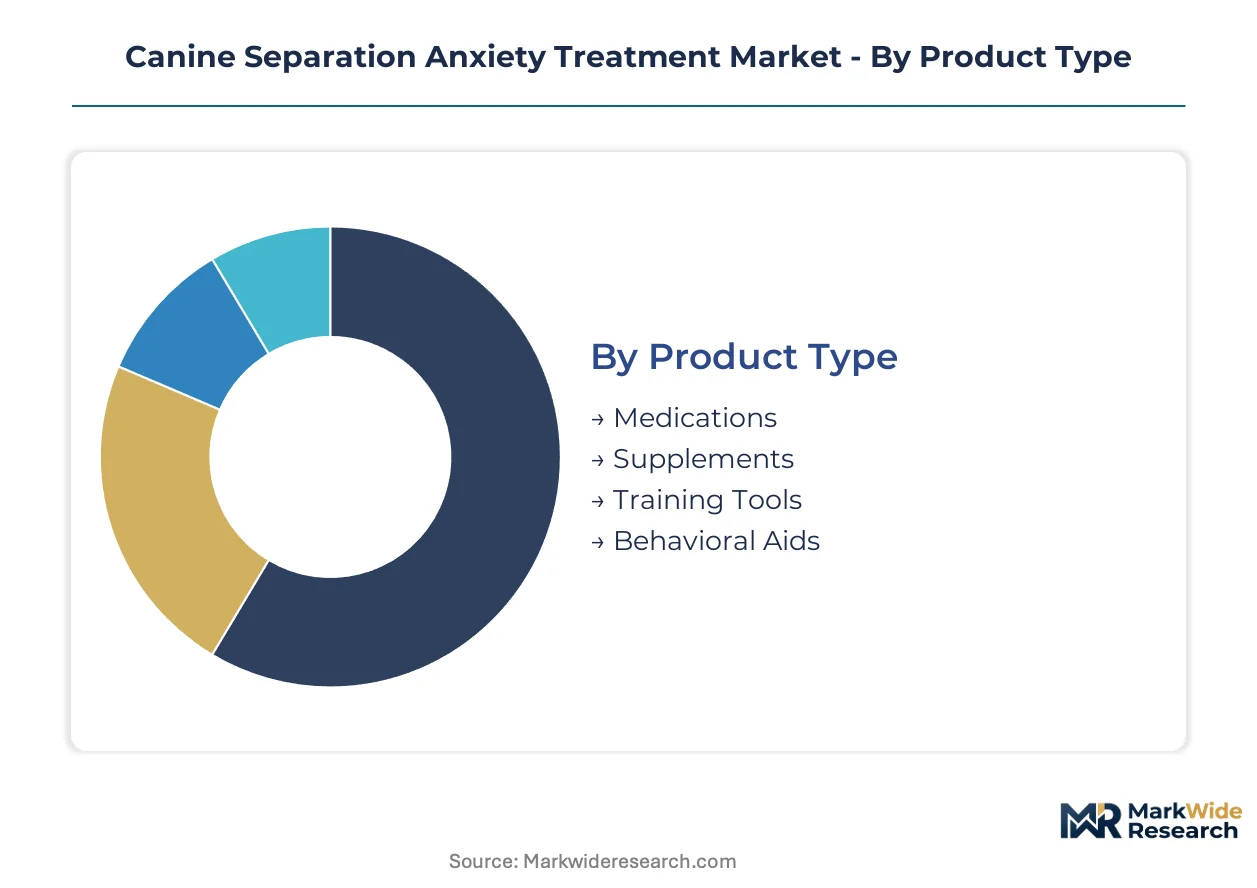
Canine separation anxiety treatment segments diverge sharply in regulatory burden, with prescription pharmaceuticals requiring FDA Center for Veterinary Medicine approval while nutraceuticals and training devices face lighter oversight. This bifurcation shapes margin structures, channel access, and competitive entry barriers across the market landscape.
Product Type:
FDA Center for Veterinary Medicine governs pharmaceutical segments through New Animal Drug Application pathways, while EPA registration constrains pheromone-based behavioral aids; supplements bypass prescription requirements entirely under DSHEA-like frameworks, creating tiered compliance economics.
- Medications:Fluoxetine hydrochloride and clomipramine formulations dominate prescription volumes, delivered through chewable tablets or transdermal gels. Demand concentrates in United States veterinary clinics where chronic refill economics sustain manufacturer margins. FDA approval timelines and limited API sourcing from Asian manufacturing clusters constrain supply elasticity.
- Training Tools:Automated treat dispensers, interactive cameras, and smart crates integrate sensor-based feedback loops for desensitization protocols. Urban millennial pet owners in United States coastal metros drive adoption as first-line interventions before pharmaceutical escalation. Subscription revenue models displace single-transaction hardware sales.
- Supplements:L-theanine, alpha-casozepine, and casein hydrolysate formulations target GABAergic modulation without prescription barriers.
- Behavioral Aids:Synthetic pheromone diffusers and calming wraps occupy mature demand with limited formulation innovation.
Leading the category by volume: Medications. Growing fastest: Training Tools.
End User:
Customer archetypes span credential-dependent professionals and autonomous consumers, with telehealth platforms eroding traditional gatekeeper authority and fragmenting purchasing influence across the value chain.
- Pet Owners:Direct purchasers now command majority share through e-commerce and telehealth-enabled prescription fulfillment. United States households with dual-income professionals exhibit highest willingness-to-pay for multimodal intervention bundles. Humanization trends deepen emotional investment in behavioral outcomes.
- Veterinarians:General practice clinics retain diagnostic authority for severe cases requiring pharmaceutical intervention. Prescription dispensing economics face erosion from direct-to-consumer platform competition. Board-certified veterinary behaviorist referrals concentrate in metropolitan academic medical centers.
- Pet Trainers:Certified professionals integrate anxiety protocols into obedience and socialization curricula.
- Animal Behaviorists:Applied animal behaviorists and veterinary behaviorists deliver protocol-based interventions reducing pharmaceutical dependency.
Dominant by spending: Pet Owners. Expanding most quickly: Pet Owners via telehealth channels.
Distribution Channel:
Channel configuration reflects regulatory stratification, with prescription products locked to credentialed intermediaries while OTC segments migrate to digital-native fulfillment.
- Veterinary Clinics:Physical dispensing retains prescription medication dominance despite telehealth encroachment. Clinic economics depend on chronic refill loyalty for behavioral medications. United States independent practices face corporate consolidation pressure.
- Online Stores:Chewy, Amazon, and direct-to-consumer platforms capture supplement and training tool volumes. Automated subscription scheduling locks in recurring revenue for chronic conditions. Price transparency pressures manufacturer list pricing strategies.
- Pet Shops:Brick-and-mortar retail concentrates behavioral aid and basic supplement sales.
- Pharmacies:Human pharmacy chains increasingly stock veterinary behavioral medications through compounding partnerships.
Highest volume throughput: Veterinary Clinics. Steepest expansion trajectory: Online Stores.
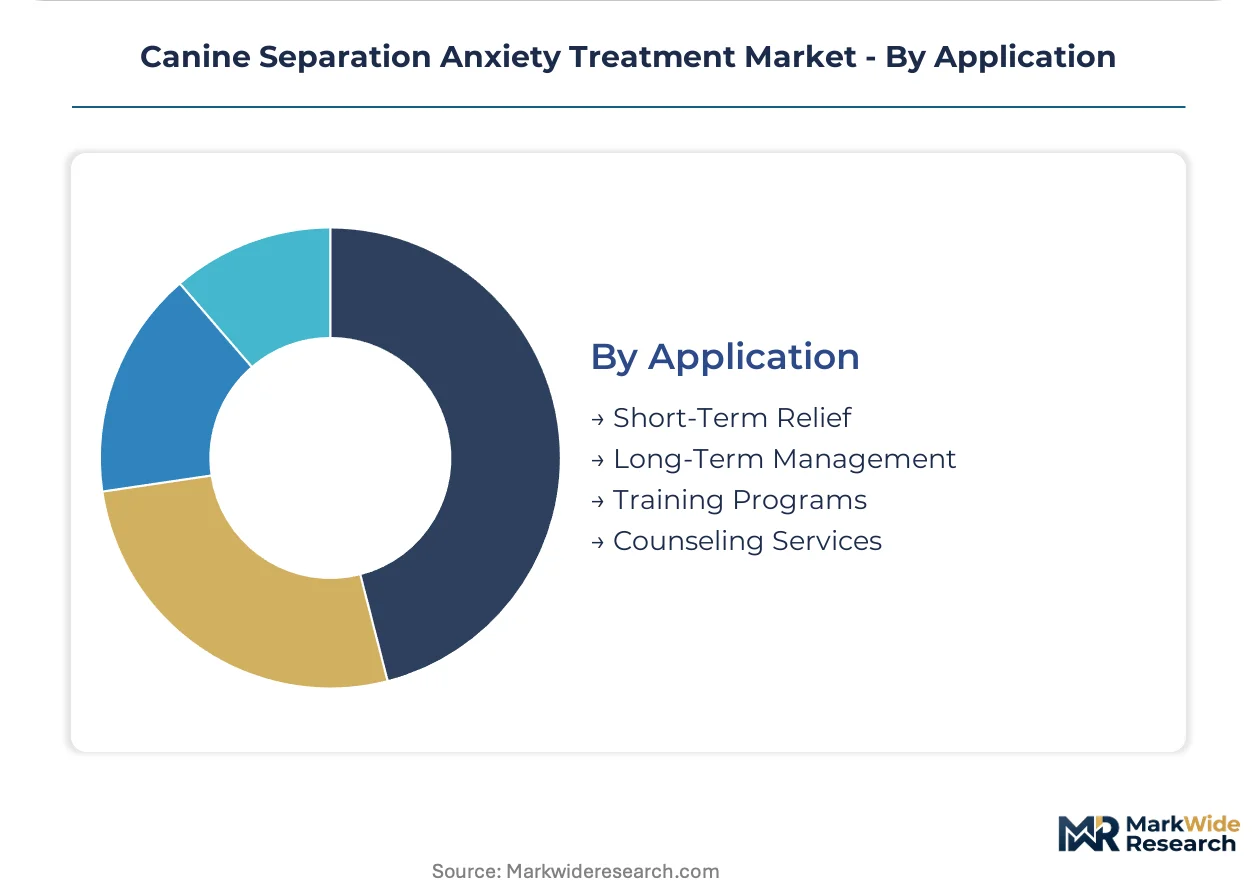
Application:
Clinical intent segments separate acute intervention from chronic management, with protocol duration determining revenue recurrence and customer lifetime value.
- Long-Term Management:Chronic pharmaceutical regimens for severe separation anxiety generate sustained refill economics. United States veterinary practices optimize dosing schedules through therapeutic drug monitoring. FDA-approved extended-release formulations reduce administration friction.
- Training Programs:Structured desensitization and counterconditioning protocols address mild-to-moderate cases without pharmaceutical escalation. Certified professional dog trainers and veterinary behaviorists deliver multimodal interventions. Outcome-based pricing models emerge in premium urban markets.
- Short-Term Relief:Situational interventions target travel, relocation, or environmental stressors.
- Counseling Services:Behavioral consultation addresses underlying attachment dynamics.
Largest addressable base: Training Programs. Gaining share fastest: Long-Term Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient sourcing for veterinary behavioral medications concentrates in Asian manufacturing clusters, yet demand-side value capture and regulatory innovation anchor in North American and Western European markets where pet humanization trends drive premium pricing.
United States
Dual-income professional households in urban coastal metros generate the highest per-capita veterinary behavioral health spending worldwide. FDA Center for Veterinary Medicine oversight maintains prescription barriers that protect pharmaceutical margins against OTC commoditization. The Greater Boston and San Francisco Bay Area corridors concentrate board-certified veterinary behaviorist practices and telehealth platform headquarters.
Germany
Lower pharmaceutical penetration rates relative to North American markets present expansion headroom for EMA-registered formulations. The EU Veterinary Medicines Regulation harmonizes pharmacovigilance requirements, elevating compliance costs for mid-sized formulators. Bavaria and North Rhine-Westphalia host dense networks of small-animal veterinary clinics with growing behavioral service adoption.
France
Veterinary behavioral medication adoption lags behind anglophone markets despite comparable pet ownership density. ANSM oversight of compounding pharmacies creates friction for personalized dosing regimens outside approved indications. The Île-de-France region anchors Virbac SA's European distribution infrastructure and clinical trial coordination.
United Kingdom
Pet technology adoption accelerates fastest among millennial owners in London and Southeast England, driving smart collar and automated dispenser deployment. The Veterinary Medicines Directorate maintains alignment with EMA standards post-Brexit, preserving market access continuity. Manchester and Edinburgh emerging as hubs for applied animal behaviorist certification programs.
Canada
Health Canada and PMRA oversight parallel FDA pathways for veterinary drug approval, enabling synchronized North American launches. Veterinary spending per household trails the United States but exceeds European benchmarks. The Ontario-Quebec corridor concentrates corporate veterinary practice consolidation and telehealth platform expansion.
Canine Separation Anxiety Treatment Market Competitive Environment
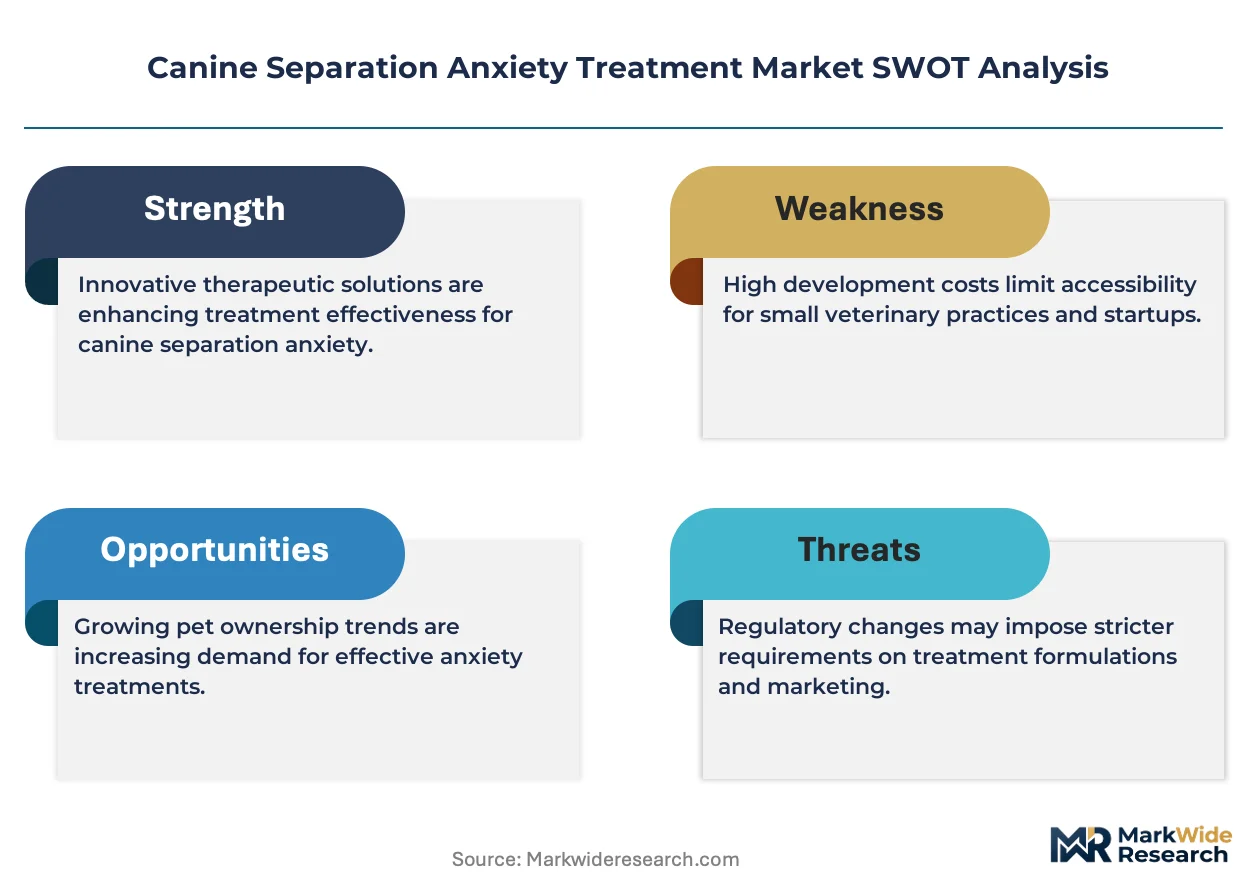
Established producers occupy the standard tier; emerging entrants pursue wearable biometric monitoring and direct-to-consumer nutraceutical channels. Market structure consolidates around pharmaceutical incumbents with regulatory affairs infrastructure, while hardware specialists and supplement formulators fragment the non-prescription segments. Three archetypes dominate: FDA-approved drug manufacturers with veterinary distribution networks, connected device developers with subscription revenue models, and nutraceutical brands with e-commerce-native fulfillment. Competitive moves center on M&A to acquire telehealth capabilities and strategic partnerships to integrate hardware-software stacks.
Within the pharmaceutical archetype, Zoetis Inc., Elanco Animal Health, and Virbac SA occupy positions representing distinct geographic anchors and regulatory specialization. Zoetis exemplifies North American clinic channel dominance through veterinary distribution infrastructure. Elanco represents R&D intensity in behavioral pharmacology with transatlantic registration capabilities. Virbac anchors European market access through established clinic networks across France, Germany, and adjacent markets. These three entities collectively illustrate how regulatory affairs scale and geographic footprint determine competitive positioning in prescription-dependent segments.
| Leading Market Players |
|---|
| Virbac SA |
| Teva Pharmaceutical Industries Ltd. |
| Elanco Animal Health |
| Mizner Bioscience LLC |
| Pegasus Laboratories Inc. (PRN Pharmacal) |
| Zoetis Inc. |
| Dechra Pharmaceuticals PLC |
| Apotex Inc. |
| Pfizer Inc. |
| Others |
Value Chain & Pricing Dynamics
Captive API sourcing from Asian manufacturing clusters anchors both cost structures and margin defense for veterinary behavioral drug formulators. This integration pattern concentrates pricing power with FDA-approved manufacturers while exposing non-integrated supplement brands to raw material volatility.
Pricing Analysis
Service bundling separates prescription pharmaceutical tiers from unbundled nutraceutical alternatives in this market. Three-tier pricing structure across premium, standard, and economy levels prevails: FDA-approved extended-release formulations command premium positioning through veterinary dispensing channels, while compounded alternatives and direct-to-consumer supplements compete on price transparency. Price differentiation rests on certification grade and after-sales monitoring integration. Cost compression in the supplement tier is intensifying because e-commerce platforms expose list pricing to owner comparison shopping. Telehealth-enabled millennial pet owners exhibit highest price sensitivity, whereas chronic medication households show lowest elasticity due to therapeutic drug monitoring dependencies.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and France coordinate hub-and-spoke patterns for temperature-sensitive pharmaceutical fulfillment. Active pharmaceutical ingredient production concentrates in India and China, with fluoxetine and clomipramine hydrochloride sourcing tethered to limited supplier bases. Finished formulation depends on cold-chain logistics partners and veterinary clinic inventory management systems. Single-source vulnerability in API procurement exposes formulators to regulatory inspection disruptions and shipping chokepoints. Distribution runs through Zoetis and Virbac captive networks for prescription products, while third-party logistics providers handle direct-to-consumer supplement fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API manufacturing capacity constraints prop pricing power for integrated pharmaceutical incumbents, while compounding pharmacy enforcement tightens supply for personalized dosing alternatives.
For Market Incumbents: Deepen backward integration into API sourcing to defend against Asian supplier concentration risk and FDA compounding scrutiny. Acquire telehealth platform capabilities to lock in refill loyalty before subscription-based competitors capture chronic medication households. Channel control through veterinary distribution infrastructure remains the critical defensive lever against direct-to-consumer platform erosion. For New Entrants and Emerging Players: Launch via direct-to-consumer nutraceutical channels to bypass prescription barriers and capture price-sensitive owner segments seeking first-line interventions. Target underpenetrated European veterinary behavioral medication markets through EMA-registered formulations and established clinic network partnerships. Wearable biometric monitoring integration offers the most penetrable white-space for hardware-software stack convergence. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by pharmaceutical incumbents seeking telehealth capabilities and connected device platforms. Long-term viability favors companies with regulatory affairs scale spanning FDA and EMA jurisdictions. Watch FDA enforcement intensity against 503B outsourcing facilities as the inflection signal for compounding pharmacy market share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Acquisition | Veterinary prescribing authority fragments away from physical clinic gatekeepers toward remote consultation models. |
| API Sourcing Diversification | Indian and Chinese supplier concentration exposes formulators to regulatory inspection disruptions and cost volatility. |
| Wearable Biometric Integration | Smart collar stress detection enables closed-loop intervention delivery and subscription revenue beyond single-product sales. |
| EMA Registration Acceleration | Harmonized EU Veterinary Medicines Regulation elevates compliance barriers while opening underpenetrated French and German markets. |
| Direct-to-Consumer Channel Buildout | E-commerce platforms bypass veterinary prescription requirements for L-theanine and alpha-casozepine supplement categories. |
Study Parameters
FDA filings, EMA submission databases, and veterinary pharmaceutical trade publications formed the secondary backbone of this analysis. Primary interviews with veterinary behaviorists, regulatory affairs directors at animal health companies, clinic procurement managers, and telehealth platform operators supplied ground-truth validation. Bottom-up prescription volume modeling and top-down market sizing triangulated across these sources to produce segmentation outputs.
Historical trendline analysis of FDA approval timelines and refill economics informed projection mechanics across the analysis window. Segmentation dimensions included product type, end user archetype, distribution channel, and application intent. CAGRs were derived from therapeutic drug monitoring adoption curves and telehealth penetration trajectories. API sourcing concentration indices and veterinary clinic consolidation rates supplied industry-specific forecast inputs.
Regulatory enforcement shifts, API supply disruptions, and behavioral modification substitution rates are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding telehealth prescribing rule evolution and EMA-FDA harmonization progress. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Global Dog Vaccines Market
Veterinary
Global Veterinary Telemetry Systems Market
Veterinary
Bovine Respiratory Disease Treatment Market
Veterinary
Global Equine Supplement Products Market
Veterinary
Global Companion Animal Specialty Drugs Market
Veterinary
Veterinary Excipients Market
Veterinary
Asia-Pacific Veterinary Vaccine Market
Veterinary
Veterinary Vaccine Adjuvants Market
Veterinary
Global Veterinary Monitoring Equipment Market
Veterinary
Bovine Mastitis Treatment System Market
Veterinary
Veterinary Thermography Market
Veterinary
Veterinary Faecal Filters Market
Veterinary
North America and Europe Veterinary Telehealth Market
Veterinary
Europe Veterinary Healthcare Market
Veterinary
Veterinary Antibiotics Market
Veterinary
Veterinary Biomarkers Market