
 Veterinary Ophthalmic Equipment Market | 2026-2036
Veterinary Ophthalmic Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Ophthalmic Equipment Market Analytics
North American veterinary diagnostic manufacturers is expanding production capacity for portable slit lamp systems as clinic chains consolidate purchasing. Alcon Inc. leverages its human ophthalmology heritage to transfer surgical microscope architectures into veterinary-specific configurations. HEINE Optotechnik GmbH & Co. KG anchors the European market with precision-engineered direct ophthalmoscopes calibrated for brachycephalic breed examinations. Bausch + Lomb competes through aftermarket lens and consumable ecosystems that lock in recurring revenue from tonometer and diagnostic imaging installations.
Veterinary ophthalmic equipment encompasses specialized diagnostic and surgical instruments engineered for ocular examination, measurement, and intervention in non-human species, typically operating at modified focal lengths and illumination spectra adapted to varied corneal curvatures and retinal structures across mammalian, avian, and exotic patient categories. The primary commercial purpose centers on enabling accurate detection of cataracts, glaucoma, and progressive retinal atrophy to preserve working animal function and companion animal quality of life. Ophthalmoscopes and tonometers constitute the mature revenue base where replacement cycles are predictable and margin compression is most acute. Digital imaging and optical coherence tomography represent the fastest-expanding technology segments as referral practices invest in subspecialty differentiation and telemedicine-ready documentation workflows. Slit lamps occupy a concentrated margin pool among premium-tier manufacturers serving academic and specialty hospital procurement channels.
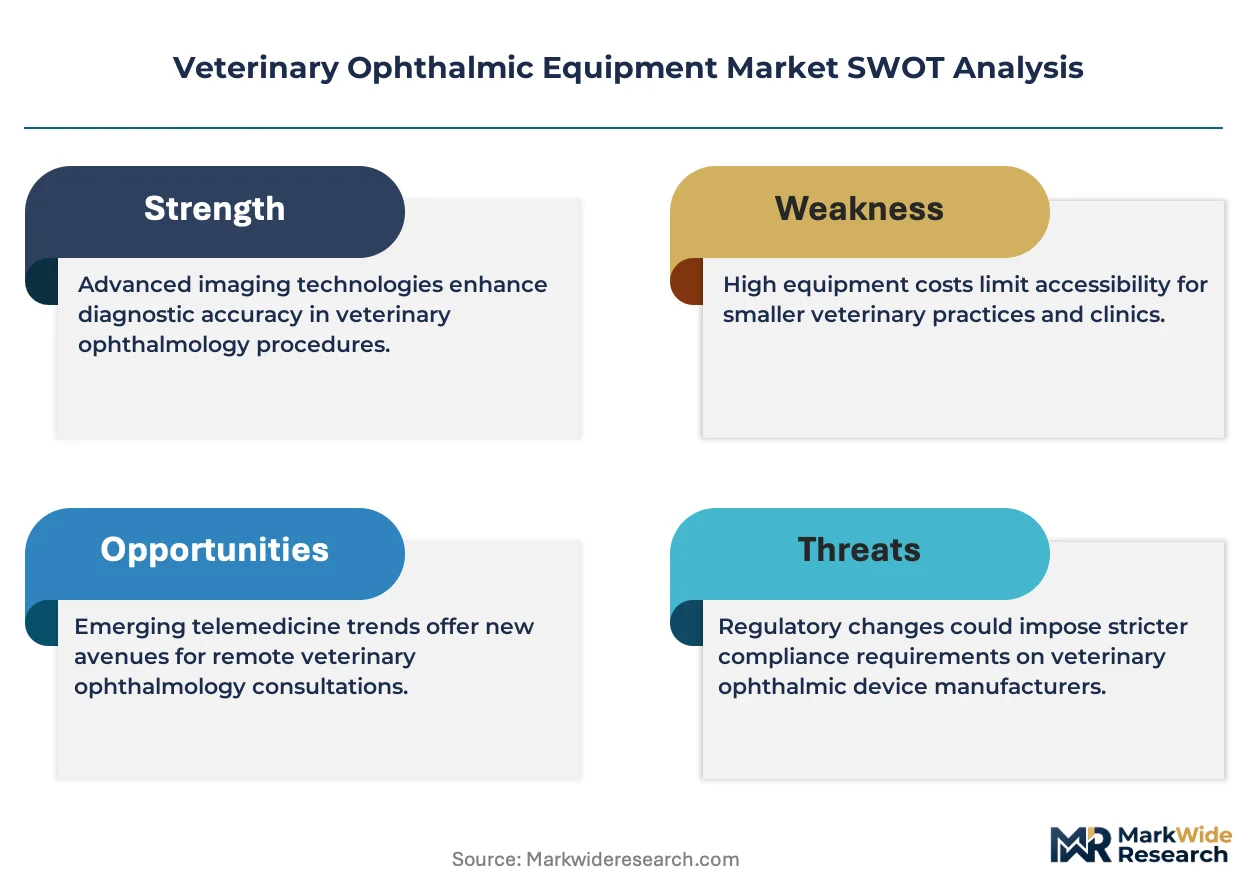
The FDA Center for Veterinary Medicine and the EPA jointly influence device clearance and disinfection chemistry approvals, while ISO 10993 biocompatibility standards constrain material selection for instruments contacting mucosal surfaces. The EU Medical Device Regulation creates parallel conformity requirements for manufacturers exporting into European veterinary channels, effectively harmonizing quality systems across human and animal device portfolios. Stakeholders must monitor evolving telemedicine reimbursement rulings and state veterinary practice act amendments that will determine whether remote diagnostic image interpretation becomes a billable service capable of justifying capital equipment deployment.
Market Dynamics
Pet insurance penetration in the United States and Western Europe is expanding the addressable client base for specialty ophthalmology services, forcing clinic chains to standardize diagnostic suites across multi-site networks and concentrate procurement decisions around validated imaging platforms.
Growth Catalysts
- Telemedicine reimbursement expansion:State veterinary practice act amendments in the United States are enabling remote diagnostic image interpretation as a billable service, justifying capital deployment for digital imaging systems.
- ISO 10993 biocompatibility standards:Harmonized material safety requirements across human and veterinary device portfolios reduce regulatory friction for manufacturers exporting into European channels.
- Companion animal specialty hospitals:Corporate clinic chains in North America are scaling dedicated ophthalmology service lines to capture insured pet owner spending on advanced ocular care.
Market Restraints
- Optical component supply concentration:Precision lens and sensor fabrication for OCT platforms depends on a limited supplier base concentrated in Germany and Japan, creating input bottlenecks.
- EPA disinfection chemistry approvals:Joint EPA and FDA Center for Veterinary Medicine oversight of device clearance and sterilization protocols extends time-to-market for instrument modifications.
- High-resolution imaging cost floors:Optical coherence tomography systems require specialized detector arrays and precision optomechanical assemblies that resist commoditization.
Strategic Opportunities
- Avian and exotic species applications:Modified focal length configurations for avian retinal structures represent an underserved technical segment within specialty practice equipment portfolios.
- EU Medical Device Regulation alignment:Veterinary device exporters into Europe benefit from quality system harmonization with human medical device requirements, streamlining conformity assessment pathways.
- Portable slit lamp distribution:Mobile diagnostic platforms enable field service delivery to equine and agricultural veterinary operations outside traditional clinic infrastructure.
Industry Challenges
- Veterinary ophthalmology specialist scarcity:Residency-trained diplomates represent a limited talent pool, constraining the operational scaling of equipment-intensive service lines.
- Multi-site equipment standardization:Corporate clinic chains face integration complexity when harmonizing diagnostic workflows across acquired practices with legacy instrument configurations.
- FDA Center for Veterinary Medicine clearance timelines:Novel imaging modalities face extended premarket review periods compared to human ophthalmology device pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Ophthalmic Equipment Market |
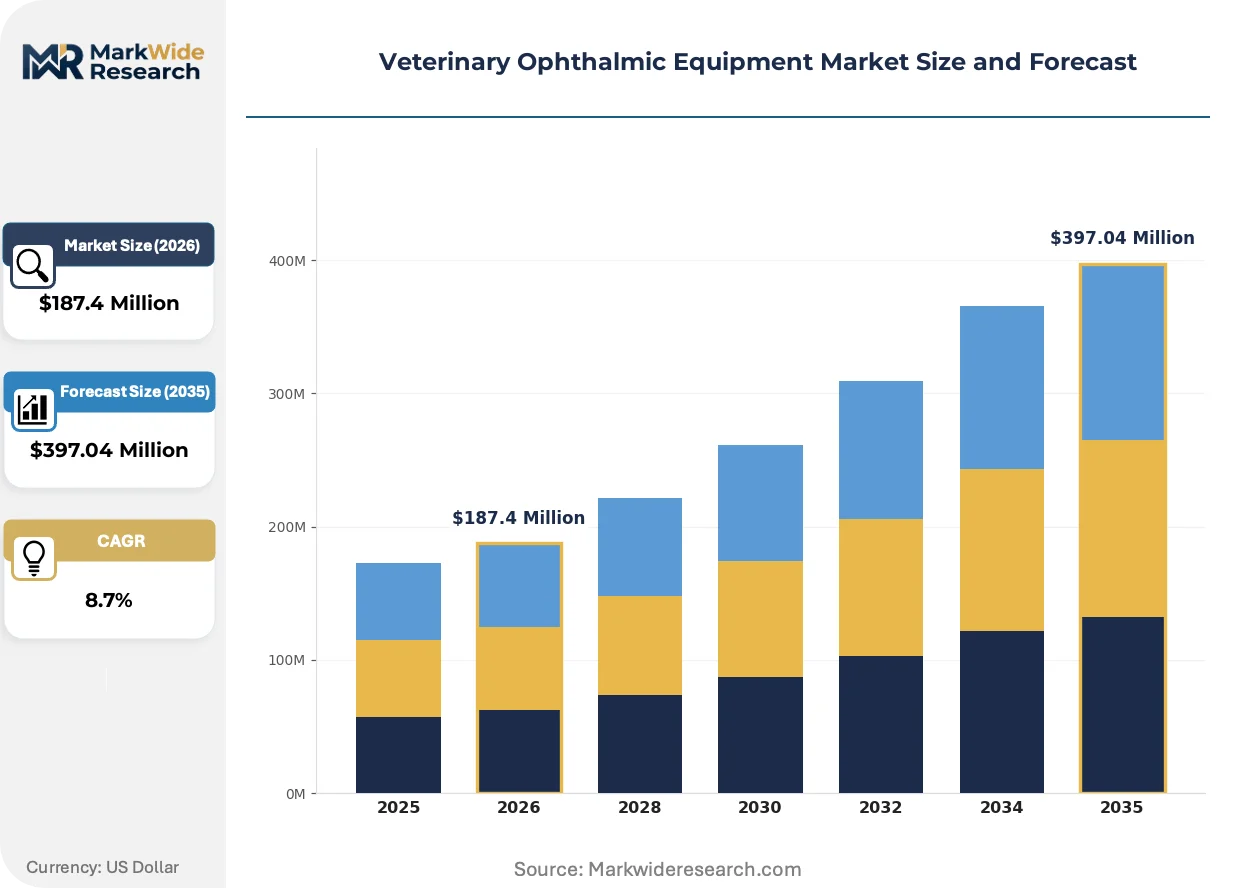
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ophthalmoscopes, Autorefractors, Tonometers, Slit Lamps End User: Veterinary Clinics, Animal Hospitals, Research Institutions, Mobile Veterinary Services Technology: Digital Imaging, Optical Coherence Tomography, Fluorescein Angiography, Laser Surgery Application: Diagnosis, Surgical Procedures, Treatment Monitoring, Preventive Care |
| Companies Covered | Alcon Inc., HEINE Optotechnik GmbH & Co. KG, Bausch + Lomb, Iridex Corporation, LKC Technologies, Inc., Revenio Group Oyj, Reichert, Inc., Optomed Plc, Keeler Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Ophthalmic Equipment Market Evolving Landscape
Digital documentation workflows and subspecialty differentiation are compressing replacement cycles for mature diagnostic categories while elevating premium-tier surgical platforms.
Optical coherence tomography is unifying anterior and posterior segment imaging into single-platform configurations. University veterinary teaching hospitals in the United States are adopting these systems at accelerated pace. This convergence is compressing capital budgets previously allocated to separate diagnostic instruments.
EU Medical Device Regulation creates parallel conformity requirements for manufacturers exporting into European veterinary channels. This regulatory alignment effectively harmonizes quality systems across human and animal device portfolios. Premium-tier manufacturers serving academic procurement channels are responding by consolidating certification documentation.
Corporate clinic chains are consolidating purchasing decisions at the network level rather than individual practice autonomy. Specialty hospital procurement channels are displacing independent distributor relationships in the United States. This concentration is most visible in multi-site network standardization across university-affiliated and corporate-owned facilities.
Veterinary Ophthalmic Equipment Market Segmentation
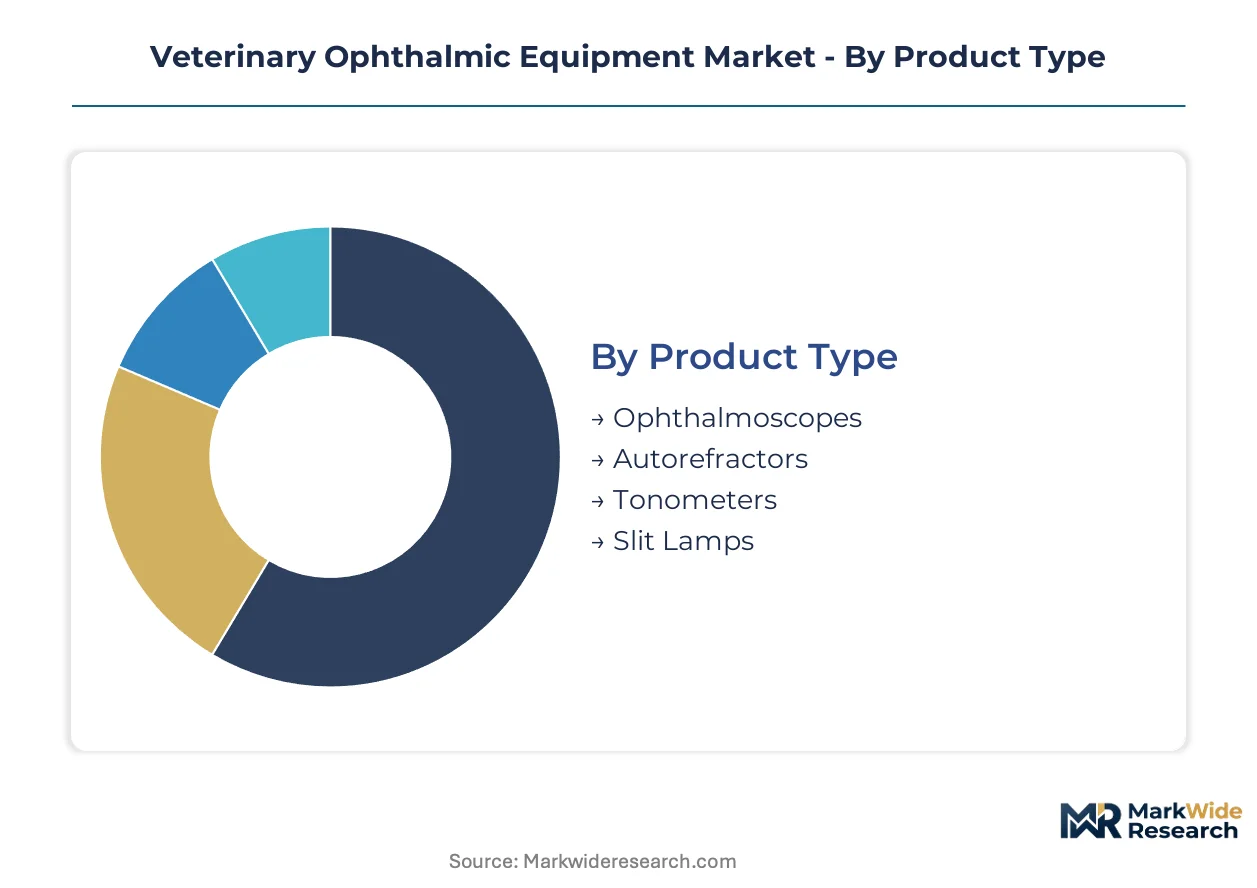
Veterinary ophthalmic equipment segments reflect divergent procurement patterns between mature diagnostic categories with predictable replacement cycles and emerging imaging platforms that command premium capital allocation. Equipment type and technology tier determine margin structure, while end-user channel concentration shapes distribution economics across academic, corporate, and field-service deployments.
Product Type:
Supply concentration among precision optics manufacturers in Germany and Japan creates tiered availability across diagnostic categories, with premium-tier slit lamp systems commanding dedicated production lines while commoditized direct ophthalmoscopes face margin compression from Asian assembly houses.
- Slit Lamps:Precision-engineered biomicroscopy platforms with adjustable illumination angles and magnification ranges calibrated for varied corneal curvatures across canine, feline, and equine species. Demand concentrates in university veterinary teaching hospitals and corporate specialty chains in the United States, where multi-site standardization protocols favor validated optical configurations from established European manufacturers.
- Tonometers:Intraocular pressure measurement devices utilizing applanation, rebound, or indentation methodologies adapted to non-human scleral rigidity and corneal thickness parameters. Procurement in North American companion animal hospitals is accelerating as glaucoma screening becomes standard-of-care in insured pet populations, driving replacement of mechanical Schiøtz instruments with electronic tonometry platforms.
- Ophthalmoscopes:Direct and indirect examination instruments with modified focal lengths for brachycephalic breed retinal assessment.
- Autorefractors:Automated refractive measurement systems adapted to veterinary patient cooperation constraints and species-specific optical pathways.
Slit lamps absorb the bulk of installed capacity in academic procurement channels; tonometers are expanding most quickly as screening protocols penetrate general practice.
End User:
Customer type determines equipment specification intensity, with capital-rich institutional buyers driving technology adoption while mobile operators prioritize portability and field durability over diagnostic depth.
- Animal Hospitals:Multi-specialty referral institutions with dedicated ophthalmology service lines and residency training programs. These facilities in the United States and Germany are consolidating equipment suites around optical coherence tomography platforms capable of anterior and posterior segment imaging, supported by pet insurance reimbursement for advanced diagnostic codes.
- Veterinary Clinics:General practice and primary care settings where ophthalmic equipment serves episodic rather than core service delivery. Clinics across corporate chains in North America are standardizing tonometry and digital imaging capabilities as network-level procurement displaces independent purchasing autonomy.
- Research Institutions:University laboratories and pharmaceutical testing facilities utilizing specialized instrumentation for toxicology studies and therapeutic efficacy trials.
- Mobile Veterinary Services:Field-deployable operations serving equine, agricultural, and remote companion animal populations with battery-powered diagnostic platforms.
Animal hospitals command the highest equipment expenditure per site; mobile veterinary services are gaining share fastest as telemedicine infrastructure extends specialty reach beyond fixed clinic networks.
Technology:
Technology tier stratifies around detector array sophistication and software integration depth, with digital documentation requirements compressing replacement cycles for analog platforms while laser surgical systems remain concentrated in diplomate-staffed referral centers.
- Optical Coherence Tomography:Non-invasive cross-sectional imaging systems utilizing low-coherence interferometry to resolve retinal layer architecture and optic nerve head morphology. Adoption is concentrating in United States university teaching hospitals and Western European specialty networks, where telemedicine-ready image archives justify capital deployment despite six-figure system costs.
- Digital Imaging:Fundus photography and anterior segment capture systems with integrated electronic medical record connectivity. Corporate clinic chains in North America are mandating these platforms across acquired practices to enable remote consultation workflows and standardized documentation for insurance preauthorization.
- Fluorescein Angiography:Vascular perfusion imaging utilizing intravenous dye injection and filtered excitation photography for retinal disease characterization.
- Laser Surgery:Photocoagulation and photodisruption platforms for retinal detachment repair and glaucoma filtration procedure adjuncts.
Digital imaging holds the largest installed base across general practice; optical coherence tomography is climbing the fastest as referral centers differentiate subspecialty capabilities.
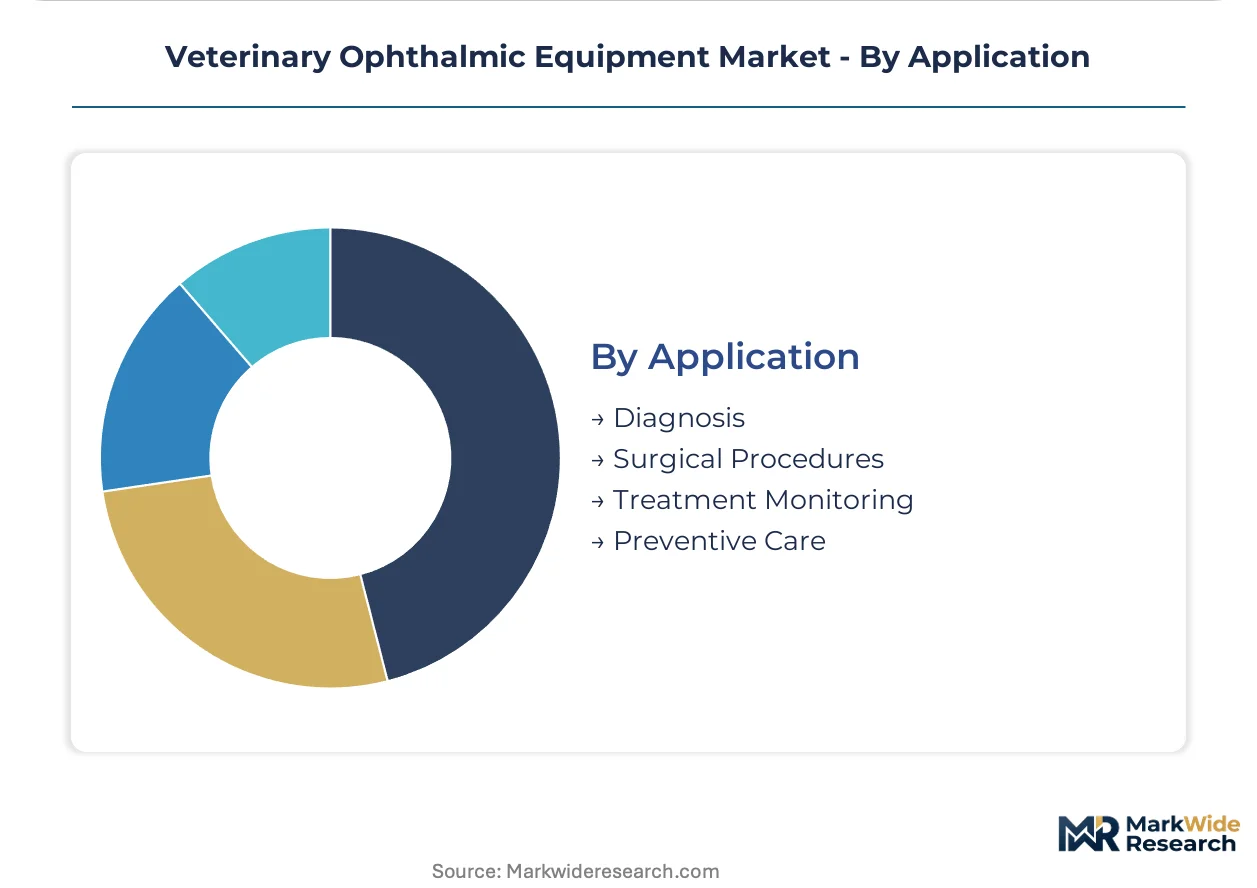
Application:
Application focus determines equipment utilization intensity and amortization economics, with diagnostic platforms achieving higher duty cycles than surgical systems limited by procedure volume and specialist availability.
- Diagnosis:Screening and disease characterization workflows encompassing tonometry, slit lamp biomicroscopy, and retinal examination for cataract, glaucoma, and progressive retinal atrophy detection. This application dominates equipment utilization in United States companion animal practices, where insured pet owners expect systematic ocular assessment as component of wellness protocols.
- Surgical Procedures:Cataract phacoemulsification, keratectomy, and glaucoma shunt placement requiring operating microscopes and phacoemulsification systems. Demand concentrates in diplomate-staffed specialty hospitals, where residency-trained ophthalmologists command procedure volumes sufficient to justify capital-intensive surgical suites.
- Treatment Monitoring:Serial imaging and pressure measurement for therapeutic response assessment in chronic ocular disease management.
- Preventive Care:Screening protocols for inherited ocular disorders in breeding populations and working animal fitness certification.
Diagnosis accounts for the majority of equipment operating hours; surgical procedures generate the highest revenue per procedure despite lower utilization frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision optical component fabrication in Germany and Japan anchors equipment supply chains for veterinary diagnostic platforms, while end-user demand concentrates in markets with expanding pet insurance penetration and corporate clinic consolidation.
United States
Corporate clinic chains and university veterinary teaching hospitals drive equipment standardization across multi-site networks. The FDA Center for Veterinary Medicine oversees premarket clearance for novel imaging modalities, extending review timelines for optical coherence tomography platforms. The Ithaca, New York corridor hosts Cornell University's veterinary college, where residency-trained ophthalmologists validate surgical microscope configurations for industry partners.
Germany
Specialty hospitals in Munich and Berlin invest in anterior-posterior segment imaging convergence as the EU Medical Device Regulation harmonizes quality systems with human device portfolios. The country's national pharmaceutical regulator enforces ISO 10993 biocompatibility standards for instruments contacting mucosal surfaces. Precision optics manufacturers in the Black Forest region supply slit lamp assemblies to veterinary distributors across Western Europe.
Japan
PMDA clearance pathways for diagnostic imaging devices tighten performance benchmarks, concentrating procurement around validated detector array platforms. METI industrial policy supports domestic optomechanical assembly capacity for OCT systems. The Tokyo-Yokohama corridor houses veterinary specialty hospitals adopting telemedicine-ready documentation workflows for insurance reimbursement.
United Kingdom
Companion animal referral practices in London and the Southeast expand ophthalmology service lines as pet insurance products broaden addressable client bases. The Medicines and Healthcare products Regulatory Agency applies EU-legacy device conformity requirements to veterinary channel imports. The Cambridge cluster connects university research programs with diagnostic imaging validation studies.
Canada
Health Canada and the Pest Management Regulatory Agency jointly influence device clearance and disinfection chemistry approvals for imported instruments. Corporate clinic acquisitions in Ontario and British Columbia drive network-level procurement standardization. The Guelph, Ontario veterinary college anchors equipment evaluation partnerships with North American distributors.
Veterinary Ophthalmic Equipment Market Competitive Landscape
Global majors compete with regional champions across precision optics fabrication and distribution reach. The vendor base stratifies into three tiers: diversified human ophthalmology conglomerates with veterinary product lines, European precision instrument specialists, and diagnostic imaging technology developers. Competitive moves center on multi-site procurement contract consolidation and telemedicine platform integration partnerships.
Within the diversified ophthalmology tier, Alcon Inc. and Bausch + Lomb represent archetypes leveraging human medical heritage for veterinary market entry. HEINE Optotechnik GmbH & Co. KG exemplifies the European precision specialist model. These three anchors occupy positions across diagnostic and surgical equipment categories, with geographic origins in Switzerland, the United States, and Germany respectively.
| Leading Market Players |
|---|
| Alcon Inc. |
| HEINE Optotechnik GmbH & Co. KG |
| Bausch + Lomb |
| Iridex Corporation |
| LKC Technologies, Inc. |
| Revenio Group Oyj |
| Reichert, Inc. |
| Optomed Plc |
| Keeler Ltd |
| Others |
Value Network & Pricing Analysis
Captive precision optics fabrication in Germany and Japan anchors both supply security and pricing power for premium-tier manufacturers, while outsourced assembly of commoditized direct ophthalmoscopes in Asian contract facilities compresses margins at the economy tier. This integration split creates divergent profitability profiles across equipment categories.
Pricing Analysis
Warranty and calibration service bundling separates premium slit lamp configurations from unbundled economy alternatives, with three-tier pricing structure across premium, standard, and economy levels prevailing across diagnostic categories. Price differentiation hinges on ISO 10993 certification tier and after-sales service depth. Pricing pressure stems from corporate clinic chain procurement consolidation demanding volume discounts. General practice clinics exhibit highest price sensitivity; university teaching hospitals prioritize performance validation over unit cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart and Osaka feed hub-and-spoke patterns serving Western European and East Asian veterinary channels. Manufacturing concentrates in Germany, Japan, and Switzerland. Precision lens grinding and detector array fabrication rests on specialized germanium substrates and CMOS sensors. Single-source vulnerability runs through Japanese detector suppliers. Distribution runs through authorized dealer networks with direct-to-hospital contracts displacing independent distributors in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where regulatory compliance burdens and multi-site procurement concentration force weaker players toward exit or acquisition.
For Market Incumbents: Deepen backward integration into precision optics fabrication to defend margin position against supply bottlenecks from German and Japanese component suppliers. Secure FDA Center for Veterinary Medicine premarket clearance for converged anterior-posterior imaging platforms before corporate clinic chains finalize network-standardization decisions. For New Entrants and Emerging Players: Capture mobile veterinary service channels with battery-powered slit lamp configurations for equine and agricultural field deployment. Avian and exotic species modified focal length systems represent the most penetrable technical white space. Pursue telemedicine platform integration partnerships to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified human ophthalmology conglomerates seeking veterinary product line expansion. Five-to-ten year viability favors manufacturers with ISO 13485 quality systems aligned to EU Medical Device Regulation requirements. Monitor FDA premarket notification submission volumes for OCT platforms as inflection indicator for specialty hospital capital deployment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR alignment streamlines veterinary device access across 27 member states. |
| Hospital System Partnership | Cornell and Guelph veterinary colleges validate equipment configurations for industry partners. |
| Software Companion Development | Telemedicine-ready image archives justify six-figure OCT system capital deployment. |
| Reimbursement Strategy | Pet insurance preauthorization workflows mandate digital documentation platform adoption. |
| Backward Integration | In-house precision optics production insulates against German-Japanese supplier concentration. |
Research Methodology
Independent corroboration across equipment procurement managers at corporate clinic chains, biomedical engineers at university veterinary teaching hospitals, and regulatory affairs specialists at FDA Center for Veterinary Medicine underwrites the qualitative findings. Secondary validation drew from FDA 510(k) premarket notification database, EU MDR conformity assessment documentation, and ISO 10993 biocompatibility testing records. Bottom-up equipment shipment data triangulated against top-down pet insurance reimbursement code utilization.
Comparable-period anchoring utilized historical replacement cycle patterns for mature diagnostic categories and technology adoption curves for emerging imaging platforms across the projection horizon. Segmentation dimensions modeled encompassed equipment type, technology tier, end-user channel, and application intensity. CAGRs derived from installed base growth rates and average selling price trajectory assumptions. Forecast inputs incorporated veterinary ophthalmology specialist residency graduation rates and corporate clinic acquisition velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to telemedicine reimbursement rulings and state veterinary practice act amendments. Outputs reflect documented assumptions regarding pet insurance penetration trajectories and regulatory clearance timeline stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Ultrasound Market
Veterinary
Veterinary CRO and CDMO Market
Veterinary
USA Animal Model Market
Veterinary
Animal Microchip Implant Market
Veterinary
Animal Drug Compounding Market
Veterinary
Europe Dog Dewormers Market
Veterinary
Asia-Pacific Veterinary Healthcare Market
Veterinary
Wearable Sensors for Animal Health Management Market
Veterinary
Veterinary Consumables Market
Veterinary
Global Animal Sedative Market
Veterinary
Spain Veterinary Healthcare Market
Veterinary
Global Canine Influenza Vaccine Market
Veterinary
Global Livestock Vaccines Market
Veterinary
Global Animal Model Market
Veterinary
Veterinary Immunodiagnostics Market
Veterinary
Canine Parvovirus Market