
 USA Animal Model Market | 2026-2036
USA Animal Model Market Size, Share, and Industry Trends Forecast 2026-2036
USA Animal Model Market Analytics
Humanized immune system mice are repositioning preclinical oncology economics as these models replace traditional xenografts for immuno-oncology screening. Charles River Laboratories International leverages its captive breeding infrastructure to control supply continuity for high-complexity strains. The Jackson Laboratory anchors academic research demand through its extensive repository of genetically defined mouse lines. Taconic Biosciences specializes in custom genetically engineered models that command premium positioning in the contract research segment.
Animal models comprise living organisms—predominantly rodents, zebrafish, pigs, and non-human primates—bred or modified to exhibit specific physiological, genetic, or pathological conditions for biomedical research, with rodent models constituting the majority of specimens due to short gestation cycles, well-characterized genomes, and established surgical protocols. These organisms serve as predictive surrogates for human disease progression, drug metabolism, and toxicological response prior to clinical translation. Rodent models occupy the largest value share given their scalability and regulatory acceptance, while zebrafish models represent the fastest-expanding category driven by optical transparency enabling real-time developmental imaging and reduced husbandry costs. Oncology applications generate the deepest margin pools as pharmaceutical sponsors prioritize immuno-oncology and cell therapy pipelines requiring sophisticated humanized platforms.
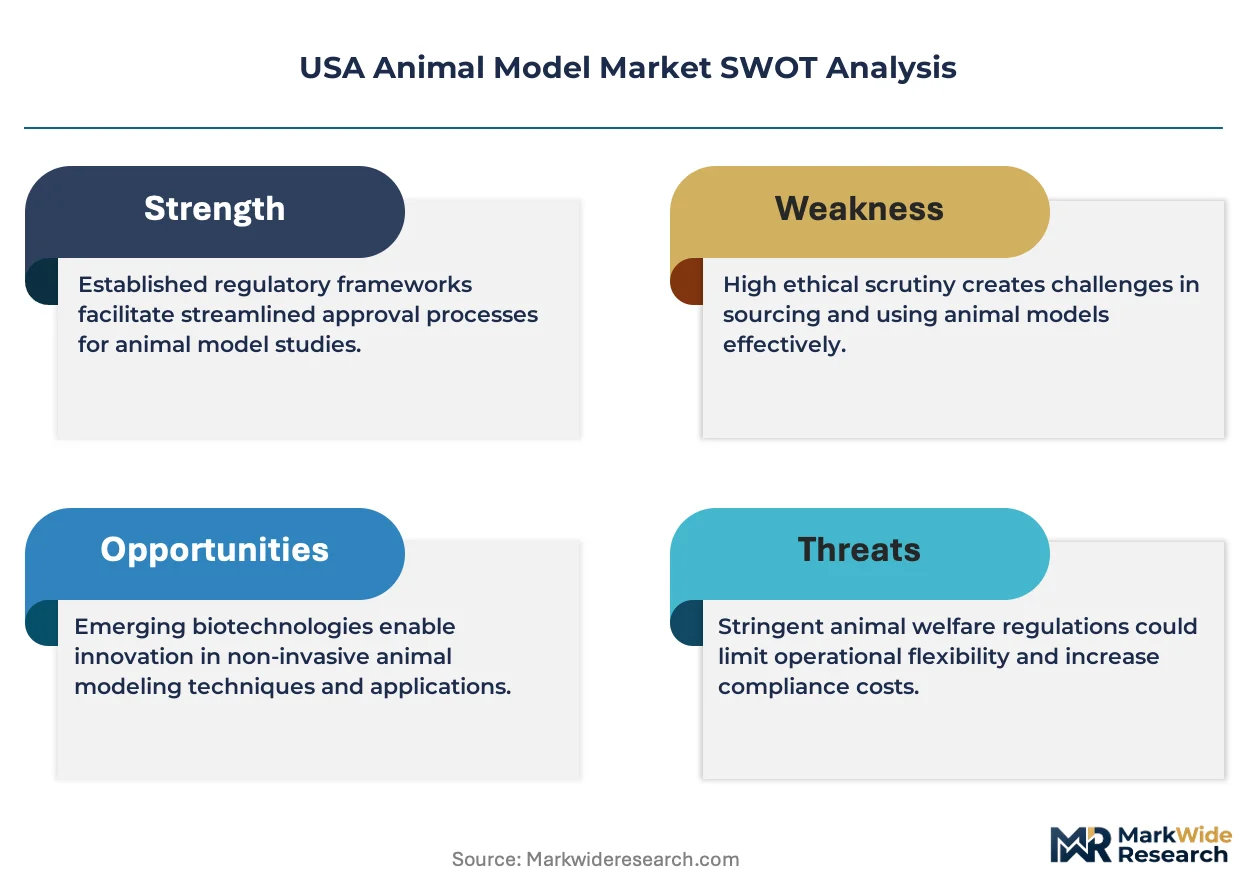
The FDA governs Good Laboratory Practice standards for preclinical safety studies under 21 CFR Part 58, while the USDA enforces Animal Welfare Act compliance across research facilities, and the NIH mandates Institutional Animal Care and Use Committee oversight for federally funded protocols. These frameworks elevate operational costs but simultaneously restrict market entry to accredited providers capable of maintaining compliant infrastructure. Stakeholders must monitor emerging EPA guidance on genetically modified organism environmental release as CRISPR-edited strains proliferate beyond containment facilities.
Market Dynamics
Humanized immune system mice are compressing traditional xenograft timelines as immuno-oncology pipelines demand predictive platforms that mirror human immune responses. This technological pivot forces breeding infrastructure investments while elevating validation standards across contract research organizations.
Growth Catalysts
- 21 CFR Part 58 Compliance:FDA-mandated Good Laboratory Practice standards for preclinical safety studies institutionalize demand for accredited breeding facilities capable of supporting IND-enabling toxicology work.
- Oncology Pipeline Expansion:Pharmaceutical sponsors accelerating cell therapy and bispecific antibody programs require sophisticated humanized platforms for mechanistic proof-of-concept studies.
- Boston-Cambridge Cluster Density:Overlapping academic and commercial research institutions in Massachusetts concentrate purchasing power and drive strain customization demand.
Market Restraints
- Pathogen-Free Husbandry Costs:Specialized barrier facility construction and biosecurity maintenance consume capital that smaller research institutions cannot deploy.
- Genetic Drift in Outbred Stocks:Phenotypic inconsistency across commercial colonies undermines reproducibility and extends study timelines for longitudinal research.
- USDA Animal Welfare Act Enforcement:Expanding veterinary staffing and environmental enrichment mandates elevate per-animal operational costs without commensurate pricing power.
Strategic Opportunities
- CRISPR-Edited Germline Services:Direct-to-researcher genome engineering bypasses traditional breeding cycles and captures premium pricing for complex immunodeficient backgrounds.
- San Diego Biotech Corridor:Underpenetrated contract research capacity relative to Boston creates whitespace for regional breeding facility expansion.
- NIH Funding Priorities:Congressional appropriations favoring infectious disease and pandemic preparedness redirect demand toward non-rodent models including non-human primates.
Industry Challenges
- Veterinary Pathologist Shortage:Diagnostic expertise gaps in laboratory animal medicine constrain study throughput and extend histopathology reporting timelines.
- Genotype-Phenotype Validation:Ensuring engineered alleles express expected disease characteristics requires molecular and behavioral screening infrastructure that many facilities lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA Animal Model Market |
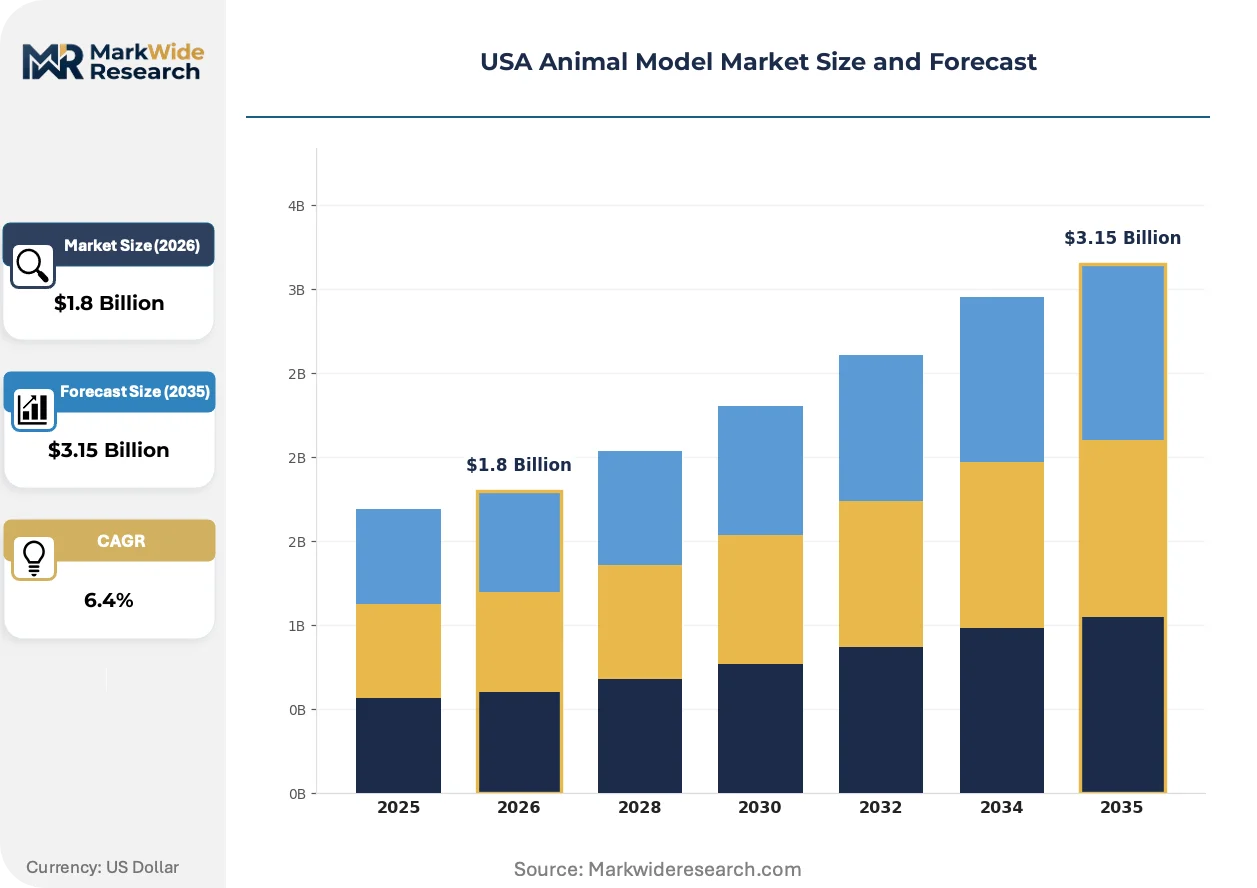
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rodents, Zebrafish, Pigs, Primates Application: Oncology, Neuroscience, Cardiovascular, Toxicology End User: Pharmaceutical Companies, Academic Institutions, Biotechnology Firms, Contract Research Organizations Delivery Mode: In-Vivo, Ex-Vivo, Alternative, Others |
| Companies Covered | Charles River Laboratories International, The Jackson Laboratory, Taconic Biosciences, Inotiv, Crown Bioscience, Envigo, genOway, Janvier Labs, BioModels, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA Animal Model Market Evolving Landscape
Preclinical research workflows are fragmenting as sponsors internalize early discovery while outsourcing specialized toxicology, creating bifurcated demand patterns across the supplier base.
Patient-derived xenograft platforms is overtaking established cell line xenografts for oncology screening. Biopharma sponsors now mandate PDX panels for mechanism-of-action studies prior to IND submission. This shift compresses demand for traditional subcutaneous tumor models while elevating contract breeding complexity for immunodeficient hosts.
The FDA's Animal Rule pathway for bioterror countermeasures continues tightening validation requirements for efficacy studies in lethal challenge models. Sponsors developing medical countermeasures must demonstrate survival endpoints in two animal species prior to human dosing. This regulatory architecture sustains demand for non-human primate and rabbit facilities capable of BSL-3 containment operations.
Consortium-based purchasing is consolidating procurement leverage among mid-tier academic medical centers. Shared service agreements for genetically modified strains reduce per-institution colony maintenance burdens while concentrating volume with multi-site breeding vendors. This pattern is most pronounced across Texas Medical Center institutions seeking operational scale without captive infrastructure investment.
USA Animal Model Market Segmentation
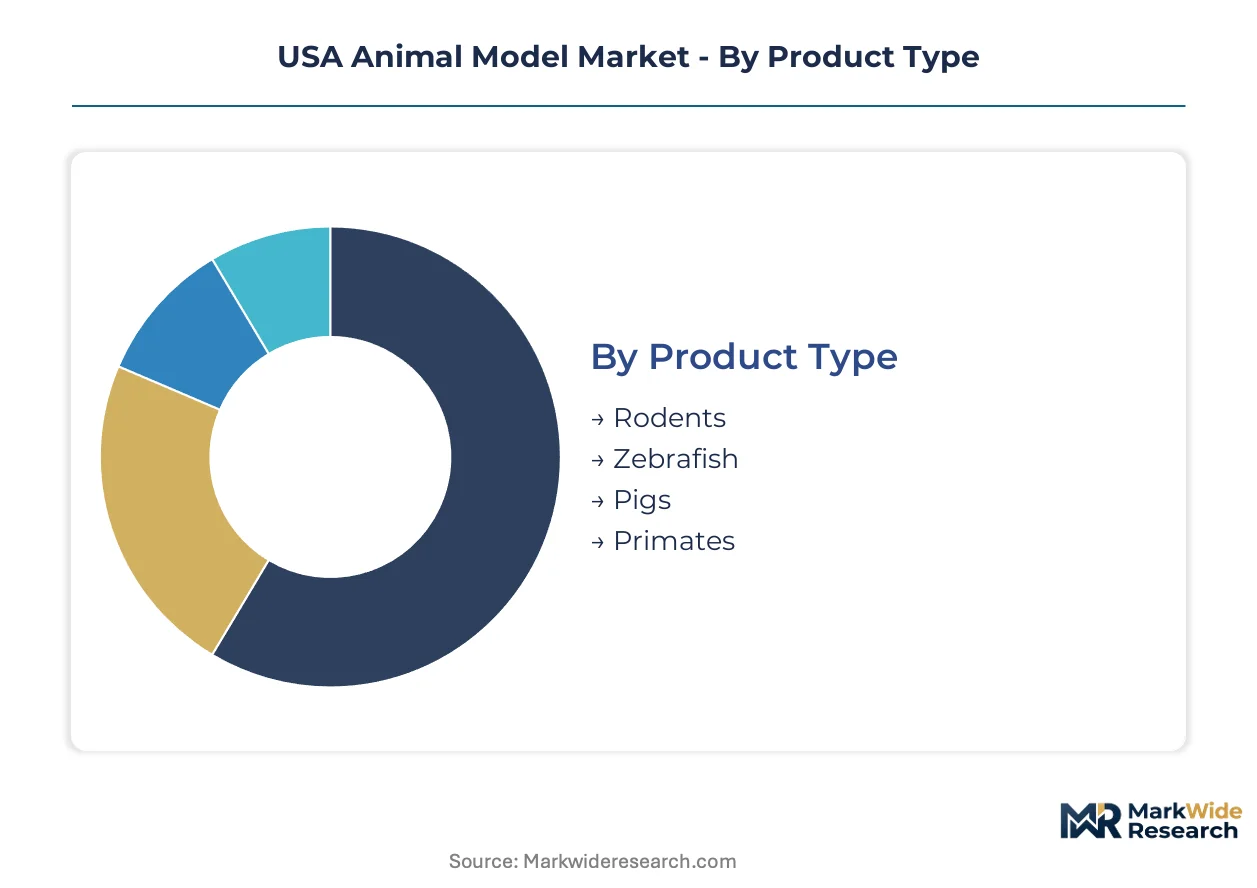
Segmentation in the USA Animal Model Market reveals how procurement decisions split between standardized, high-volume strains and specialized, premium-tier models requiring custom engineering. Understanding these divides exposes where breeding infrastructure investments concentrate and where contract research organizations capture margin.
Product Type:
Rodent models operate as standalone research platforms with established protocols, while larger species embed into multi-site collaborative studies requiring specialized containment.
- Rodents:Mice and rats constitute the foundational layer of preclinical research, offering short breeding cycles and well-characterized immunodeficient backgrounds for xenograft studies. Pharmaceutical sponsors in the Boston-Cambridge corridor source these at scale for high-throughput oncology screening, though genetic drift in outbred stocks complicates longitudinal reproducibility.
- Zebrafish:Optical transparency during embryonic development enables real-time imaging of vascular formation and tumor metastasis without invasive procedures. Academic institutions prioritize these models for developmental biology and toxicology screening, driven by reduced husbandry costs and high fecundity rates that accelerate genetic screening workflows.
- Pigs:Anatomical similarities to human cardiovascular and dermal systems position these models for surgical training and device validation studies.
- Primates:Non-human primates serve as mandatory second-species validation under FDA Animal Rule pathways for bioterror countermeasures and complex neurological research.
Volume placements concentrate in Rodents; the faster expansion belongs to Zebrafish.
Application:
Application segments stratify by therapeutic area maturity, with established fields commanding predictable demand and emerging modalities requiring bespoke model development.
- Oncology:Immuno-oncology pipelines demand humanized immune system mice that recapitulate human T-cell responses against tumor microenvironments. Cell therapy sponsors in Massachusetts and California commission these strains for mechanism-of-action studies prior to IND submission, compressing traditional xenograft timelines.
- Neuroscience:Gene-edited models of Alzheimer's and Parkinson's pathology require extended longitudinal observation and sophisticated behavioral phenotyping infrastructure. Academic medical centers concentrate purchasing here, constrained by veterinary pathologist shortages that extend histopathology reporting.
- Cardiovascular:Large-animal surgical models support interventional device testing and regenerative medicine approaches.
- Toxicology:FDA 21 CFR Part 58 compliance mandates drive institutional demand for standardized rodent strains in GLP safety pharmacology studies.
Revenue depth pools in Oncology; Neuroscience climbs the fastest as gene therapy vectors mature.
End User:
End user categories diverge by internal capability, with integrated sponsors maintaining captive colonies and externalized researchers relying on vendor-managed supply chains.
- Pharmaceutical Companies:Large sponsors internalize early discovery breeding while outsourcing specialized toxicology to accredited contract research organizations. Genetically modified strain demand concentrates here, particularly for bispecific antibody and CAR-T cell therapy programs.
- Academic Institutions:NIH-funded researchers access genetically defined lines through repository networks like The Jackson Laboratory, reducing per-laboratory colony maintenance burdens. Institutional Animal Care and Use Committee oversight shapes procurement toward shared service agreements.
- Biotechnology Firms:Venture-backed developers prioritize flexible access to CRISPR-edited germline services without fixed infrastructure investment.
- Contract Research Organizations:Multi-site breeding vendors capture volume through consortium-based purchasing agreements among mid-tier medical centers.
Procurement scale favors Pharmaceutical Companies; Biotechnology Firms are expanding most quickly as cell therapy pipelines proliferate.
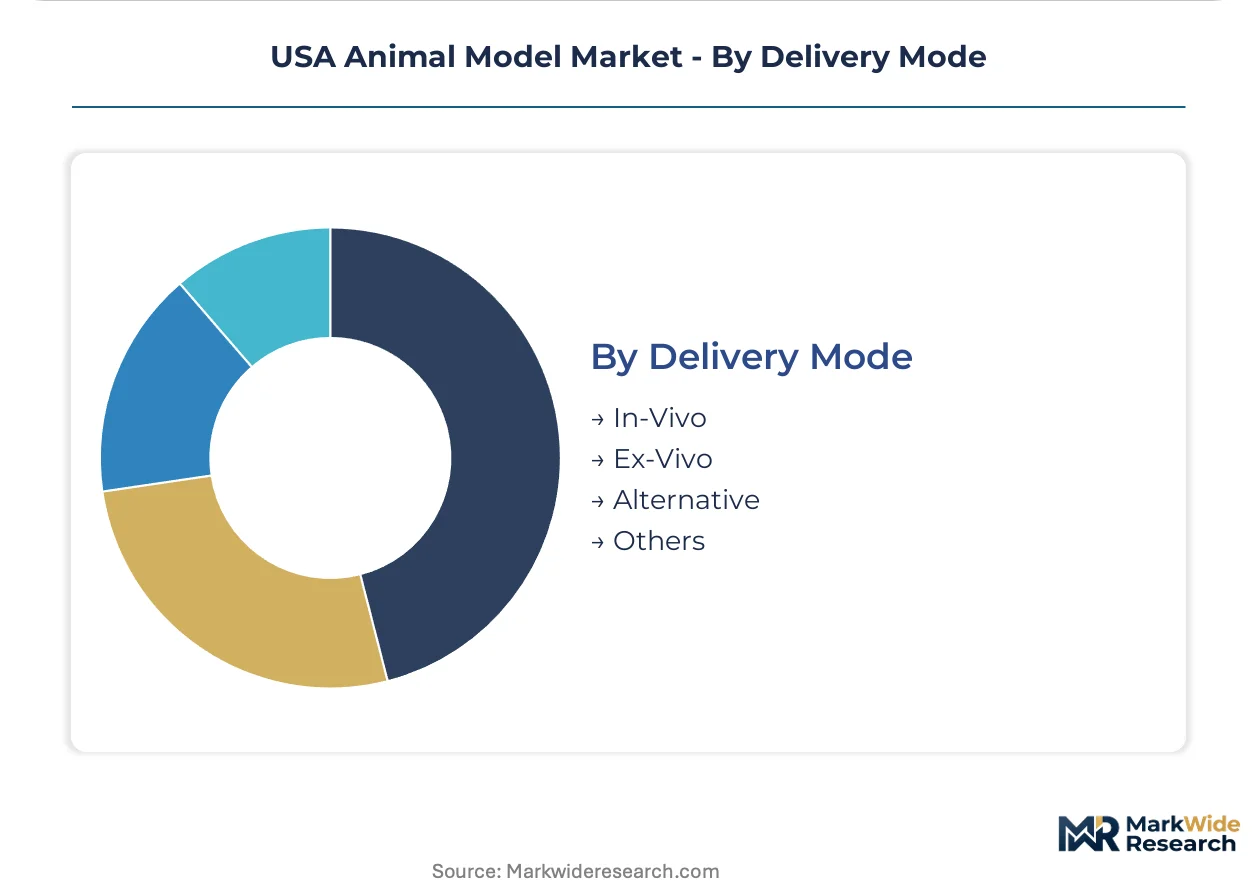
Delivery Mode:
Delivery modes distinguish between living specimen provision and derived tissue platforms, with regulatory acceptance determining commercial viability.
- In-Vivo:Living animal studies remain the regulatory gold standard for IND-enabling toxicology and efficacy endpoints under FDA and USDA oversight. Barrier facility construction and biosecurity maintenance elevate operational costs, restricting market entry to accredited providers.
- Ex-Vivo:Precision-cut tissue slices and organoid cultures from resected specimens enable mechanistic studies without systemic confounding variables. These platforms gain traction for hepatotoxicity screening and neurodegenerative disease modeling where longitudinal in-vivo observation proves impractical.
- Alternative:Computer modeling and in-silico toxicology prediction tools complement but rarely replace living systems in regulatory submissions.
- Others:Hybrid approaches combining in-vivo validation with ex-vivo mechanistic follow-up optimize resource allocation across study phases.
Regulatory acceptance anchors In-Vivo dominance; Ex-Vivo methods gain share fastest as 3R principles (replacement, reduction, refinement) reshape institutional purchasing criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for genetically modified rodent models concentrates in coastal metropolitan clusters where academic medical centers and pharmaceutical sponsors overlap. NIH funding distributions and FDA regulatory proximity shape regional procurement patterns across the United States.
Greater Boston
Massachusetts hosts the densest concentration of immuno-oncology research, with Harvard Medical School and MIT driving demand for humanized immune system mice. The FDA's Boston District Office maintains close oversight of preclinical IND-enabling studies conducted at local contract research organizations. Kendall Square and the Longwood Medical Area anchor breeding facility investments from Charles River Laboratories and Taconic Biosciences.
San Francisco Bay Area
California's stem cell research initiative and venture capital availability accelerate cell therapy pipeline development requiring sophisticated xenograft platforms. The California Institute for Regenerative Medicine directs state funding toward disease-specific model development. South San Francisco and Menlo Park biotech clusters source genetically engineered strains through regional distribution hubs.
San Diego
Southern California's underpenetrated contract research capacity relative to Boston creates whitespace for breeding facility expansion. The Salk Institute and UC San Diego drive academic demand for zebrafish developmental models. Torrey Pines and Sorrento Valley biotech corridors rely on outsourced supply chains for immunodeficient backgrounds.
Research Triangle
North Carolina's concentration of agricultural biotechnology and infectious disease research sustains demand for large-animal and non-rodent models. NIH's National Institute of Environmental Health Sciences mandates rigorous toxicology protocols using standardized rodent strains. Durham and Chapel Hill academic consortia pursue shared service agreements to reduce per-institution colony burdens.
Mid-Atlantic Corridor
Maryland and Virginia house federal research institutions including NIH headquarters and FDA's Center for Biologics Evaluation and Research. The USDA's Animal and Plant Health Inspection Service enforces interstate transport regulations for genetically modified organisms. Bethesda and Rockville research parks maintain captive breeding infrastructure for biodefense countermeasure development under Animal Rule pathways.
USA Animal Model Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated breeding vendors capturing premium positioning in genetically modified strains while regional distributors serve standardized high-volume demand. Market structure tilts toward consolidation at the top tier, where captive infrastructure investments and regulatory accreditation create entry barriers. Three archetypes dominate: multi-site breeding conglomerates with GLP-accredited facilities, academic repository networks with non-profit status, and nimble germline engineering boutiques. Competitive dynamics center on capacity expansion in underpenetrated geographies and strategic partnerships for CRISPR-edited strain development.
Within the integrated breeding tier, Charles River Laboratories International and The Jackson Laboratory exemplify scale-driven operational models. Taconic Biosciences occupies a position among specialized germline engineering providers. These three entities anchor the competitive landscape through distinct archetype representation: Charles River Laboratories as a multi-site contract research organization, The Jackson Laboratory as an academic repository with commercial extension, and Taconic Biosciences as a custom engineering specialist serving biotechnology sponsors.
| Leading Market Players |
|---|
| Charles River Laboratories International |
| The Jackson Laboratory |
| Taconic Biosciences |
| Inotiv |
| Crown Bioscience |
| Envigo |
| genOway |
| Janvier Labs |
| BioModels |
| Others |
Value Network & Pricing Analysis
CRISPR-edited germline services are compressing traditional breeding cycles while simultaneously concentrating production economics among facilities capable of maintaining pathogen-free barrier infrastructure. This technological pivot elevates fixed-cost thresholds for market entry while fragmenting margin capture between high-volume standardized strains and premium custom-engineered models.
Pricing Analysis
High-volume outbred rodent strains operate on thin margins while humanized immune system mice and CRISPR-edited custom models command substantial premiums. Price differentiation rests on genetic complexity certification and GLP-accredited breeding facility status rather than commodity volume. Pricing pressure stems from consortium-based purchasing agreements consolidating procurement leverage among mid-tier academic medical centers. Biotechnology firms exhibit highest price sensitivity given constrained venture funding cycles, whereas pharmaceutical sponsors prioritize strain validation reliability over unit cost.
Supply Chain Analysis
Domestic-content mandates under the NIH's domestic preference guidelines and USDA interstate transport regulations are reshaping sourcing patterns toward captive US-based breeding infrastructure. Supply concentrates in Massachusetts, California, and North Carolina where academic-commercial research clusters overlap. Raw material dependencies center on specialized rodent diets, pathogen-free bedding substrates, and veterinary diagnostic reagents. Single-source vulnerability runs through concentrated barrier facility capacity in the Boston-Cambridge corridor. Distribution runs through regional distribution hubs serving contract research organizations and direct institutional sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue backward control over CRISPR-edited germline engineering capabilities to escape commoditized outbred strain pricing.
For Market Incumbents: Anticipate margin compression in standardized rodent strains as consortium purchasing consolidates volume among fewer accredited vendors. Defensive moves require deepening captive supply of humanized immune system mice and expanding GLP-accredited toxicology breeding capacity in underpenetrated geographies like San Diego. Threat substitution from ex-vivo organoid platforms demands investment in hybrid service models combining in-vivo validation with derived tissue platforms. For New Entrants and Emerging Players: The price-point gap between premium CRISPR-edited custom models and economy-tier outbred stocks creates entry whitespace for regional breeding facilities serving mid-tier academic consortia. Target the Research Triangle and Texas Medical Center where shared service agreements reduce per-institution colony burdens. A niche germline engineering boutique model bypasses capital-intensive barrier infrastructure through partnership with existing accredited facilities. For Investors and Strategic Acquirers: Re-rating potential sits with specialized germline engineering providers given FDA Animal Rule pathway expansion for bioterror countermeasures and cell therapy pipeline proliferation. Long-term viability favors assets with CRISPR editing capabilities and established relationships with NIH-funded researchers. Signal to watch: NIH infectious disease funding appropriations redirecting demand toward non-rodent models including non-human primates.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Germline Engineering Capability | Direct-to-researcher genome editing bypasses traditional breeding cycles and captures premium pricing. |
| GLP-Accredited Facility Expansion | FDA 21 CFR Part 58 compliance institutionalizes demand for IND-enabling toxicology breeding infrastructure. |
| Humanized Immune System Platform Development | Immuno-oncology pipeline requirements compress traditional xenograft timelines and elevate validation standards. |
| Consortium-Based Purchasing Agreements | Shared service arrangements among mid-tier medical centers concentrate volume with multi-site breeding vendors. |
| Non-Rodent Model Capacity Investment | NIH funding priorities favoring pandemic preparedness redirect demand toward non-human primate facilities. |
Research Methodology
Independent corroboration across primary interviews with laboratory animal veterinarians, contract research organization procurement directors, and NIH program officers underwrites the qualitative findings. Secondary validation draws from FDA 21 CFR Part 58 guidance documents, USDA Animal Welfare Act enforcement records, NIH RePORTER funding databases, and institutional IACUC protocol filings. Bottom-up strain-level demand modeling triangulates against top-down pharmaceutical R&D expenditure allocation across therapeutic areas.
Comparable-period anchoring to historical breeding facility capacity utilization and pharmaceutical pipeline progression rates shapes the projection horizon. The analytical framework segments by species type, genetic modification complexity, application area, and end-user institutional category. CAGRs derive from regression analysis against NIH funding appropriations, FDA IND submission trends, and contract research organization revenue mix shifts. Forecast inputs incorporate CRISPR editing technology diffusion rates and humanized model validation timeline compression.
Underlying measurement precision varies by segment; standardized outbred rodent strains carry tighter precision than emerging zebrafish and non-human primate categories. Forecasts reflect assumptions regarding continued FDA Animal Rule pathway utilization and sustained NIH funding for infectious disease countermeasures. Gene therapy vector safety failures or alternative model regulatory acceptance could revise demand projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Global Veterinary Hematology Analyzers Market
Veterinary
Veterinary Endodontics Market
Veterinary
Global Veterinary Rapid Test Market
Veterinary
Global Pet Obesity Management Market
Veterinary
Veterinary Ophthalmic Equipment Market
Veterinary
Global Dog Vaccines Market
Veterinary
Veterinary Excipients Market
Veterinary
Veterinary Hospitals Market
Veterinary
Global Companion Animal Specialty Drugs Market
Veterinary
Veterinary Clostridium Vaccine Market
Veterinary
Bovine Mastitis Treatment System Market
Veterinary
Otc Pet Medication Market
Veterinary
Compression Veterinary Bandages Market
Veterinary
Asia-Pacific Veterinary Healthcare Market
Veterinary
Veterinary Supplements Market
Veterinary
Global Equine Supplement Products Market