
 Veterinary Wound Sprays Market | 2026-2036
Veterinary Wound Sprays Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Wound Sprays Market Analytics
Companion animal practice is shifting toward outpatient wound management protocols that reduce hospitalization time. Zoetis leverages its diagnostics-to-therapeutics platform to bundle wound sprays with antimicrobial stewardship programs. Virbac anchors its position through species-specific formulations that address both equine lacerations and small-animal surgical sites. Innovacyn, Inc. specializes in hypochlorous acid-based sprays that compete on tissue compatibility without antibiotic resistance concerns.
Veterinary wound sprays are topical aqueous or hydroalcoholic formulations containing antiseptic, antimicrobial, or tissue-regenerative actives, designed for application to dermal injuries in animals without mechanical debridement. These products typically deliver chlorhexidine, povidone-iodine, silver ions, or botanical extracts at concentrations calibrated for species-specific epithelial sensitivity, with pH ranges optimized to maintain moist wound healing environments. Antimicrobial sprays command the widest clinical adoption due to their dual role in infection control and biofilm disruption, while healing sprays represent the fastest-expanding margin pool as regenerative ingredients such as medical-grade honey and hyaluronic acid gain veterinary formulary inclusion. Pump bottles dominate packaging for clinic dispensing, whereas aerosol cans retain share in equine and livestock settings where uniform coverage over large surface areas matters.
The FDA Center for Veterinary Medicine governs topical antiseptic claims and manufacturing standards for products entering the United States, while the EMA coordinates centralized assessments for novel veterinary medicinal sprays across EU member states. BIS certification requirements in India and GB standards administered by SAMR in China add compliance layers for manufacturers seeking access to Asia-Pacific volume. Stakeholders must monitor evolving antimicrobial resistance policies that could reclassify certain active ingredients from over-the-counter to prescription-only status, reshaping distribution economics and formulation R&D priorities.
Market Dynamics
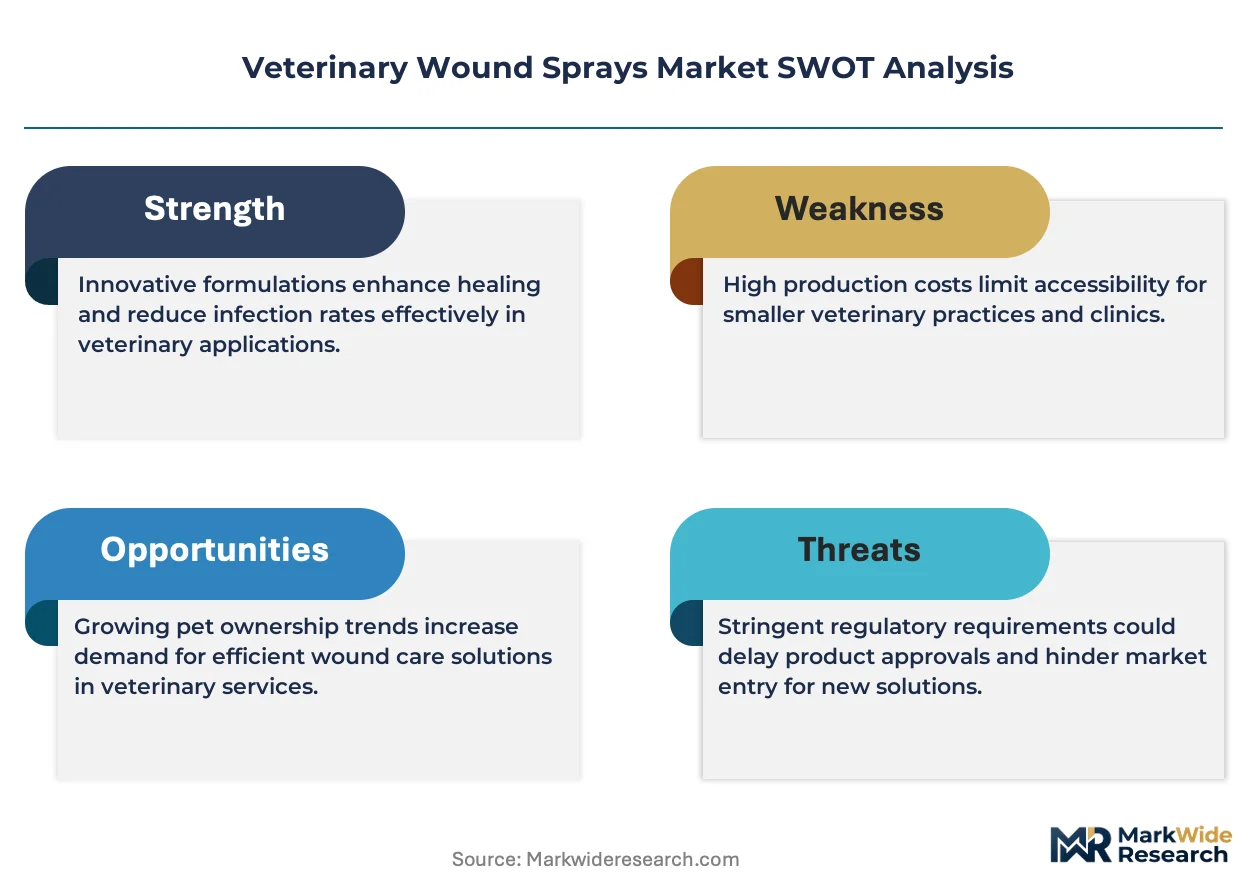
Antimicrobial resistance protocols are compressing the regulatory window for legacy active ingredients, forcing reformulation cycles and reshaping competitive positioning across veterinary wound care portfolios.
Growth Catalysts
- Companion animal outpatient protocols:Clinics in the United States and Germany are expanding same-day wound management to reduce hospitalization costs and improve pet owner compliance.
- EMA centralized assessment pathways:Streamlined novel veterinary medicinal product approvals accelerate market entry for species-specific spray formulations across EU member states.
- Hypochlorous acid chemistry:Tissue-compatible antiseptic platforms eliminate antibiotic resistance concerns while maintaining broad-spectrum efficacy against biofilm-forming pathogens.
Market Restraints
- Silver ion input volatility:Precious metal supply concentration in select mining jurisdictions creates formulation cost instability for antimicrobial spray manufacturers.
- Chlorhexidine regulatory friction:FDA Center for Veterinary Medicine scrutiny of residual tissue accumulation limits concentration ranges and label claims.
- Botanical extract standardization gaps:Inconsistent phytochemical potency across honey and plant-based suppliers complicates batch-to-batch healing spray performance.
Strategic Opportunities
- Brazil livestock health modernization:Federal tightening of cattle and equine welfare standards creates demand for large-volume wound spray dispensers in ranching operations.
- Telemedicine-tethered home care:Remote veterinary consultation platforms enable direct-to-consumer spray distribution bypassing traditional clinic procurement.
- ISO 10993 biocompatibility convergence:Medical device-grade testing protocols borrowed from human wound care open premium pricing tiers for veterinary equivalents.
Industry Challenges
- Veterinary pharmaceutical formulation talent scarcity:Cross-species epithelial sensitivity expertise sits concentrated within a limited pool of specialists.
- Multi-jurisdiction label harmonization:Divergent FDA, EMA, and BIS purity requirements force parallel manufacturing runs and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Wound Sprays Market |
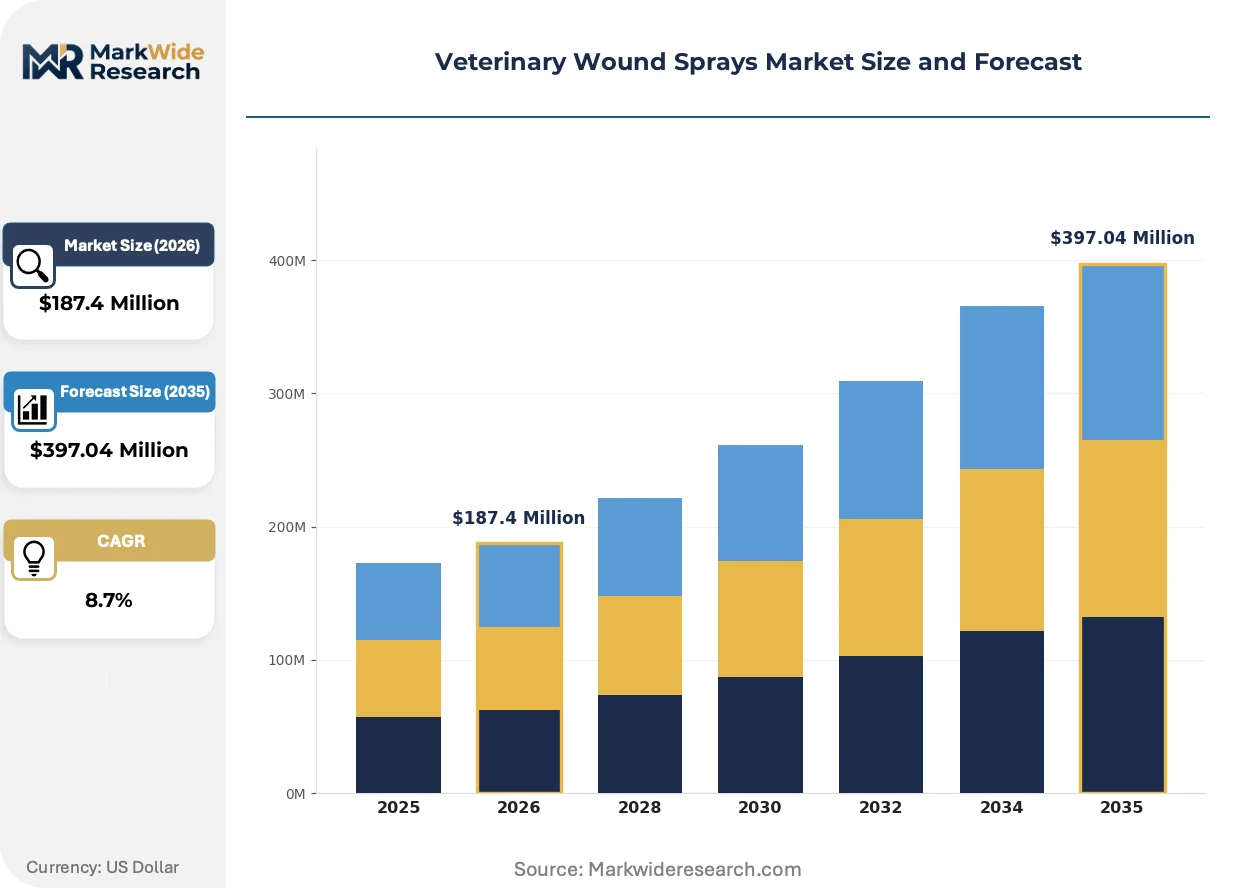
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiseptic Sprays, Hydrating Sprays, Antimicrobial Sprays, Healing Sprays Application: First Aid, Post-Surgical Care, Wound Management, Infection Control Animal Type: Dogs, Cats, Horses, Livestock Packaging Type: Aerosol Cans, Pump Bottles, Sachets, Bulk Containers |
| Companies Covered | Zoetis, Elanco, Virbac, Vetoquinol, Innovacyn, Inc., Dechra Pharmaceuticals, Neogen Corporation, Axio Biosolutions Pvt Ltd, Jorgen Kruuse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Wound Sprays Market Evolving Landscape
Formulation science and distribution architecture are undergoing simultaneous transformation as regenerative actives displace conventional antiseptics and digital channels fragment historical procurement relationships.
Hypochlorous acid-based wound sprays are converging with point-of-care diagnostic platforms, enabling real-time infection assessment followed by immediate topical intervention. Equine clinics in Germany and companion animal practices in the United States are piloting bundled spray-and-test protocols. This convergence is compressing the traditional diagnostic-to-treatment timeline from days to minutes while elevating spray products from commodity antiseptics to integrated care components.
REACH antimicrobial substance restrictions are forcing active ingredient substitutions ahead of sunset dates for legacy biocides. Manufacturers serving EU markets face reformulation deadlines that compress R&D pipelines and accelerate partnerships with specialty chemical suppliers. Healing spray categories containing medical-grade honey and hyaluronic acid gain relative advantage as they fall outside biocidal regulatory scope.
Subscription-based replenishment models are displacing clinic bulk purchasing for high-volume wound spray users. Large veterinary hospital networks in the United States negotiate automated restocking agreements tied to procedure volume forecasts. This shift concentrates procurement leverage among distributor platforms capable of predictive inventory management, marginalizing smaller wholesale intermediaries.
Veterinary Wound Sprays Market Segmentation
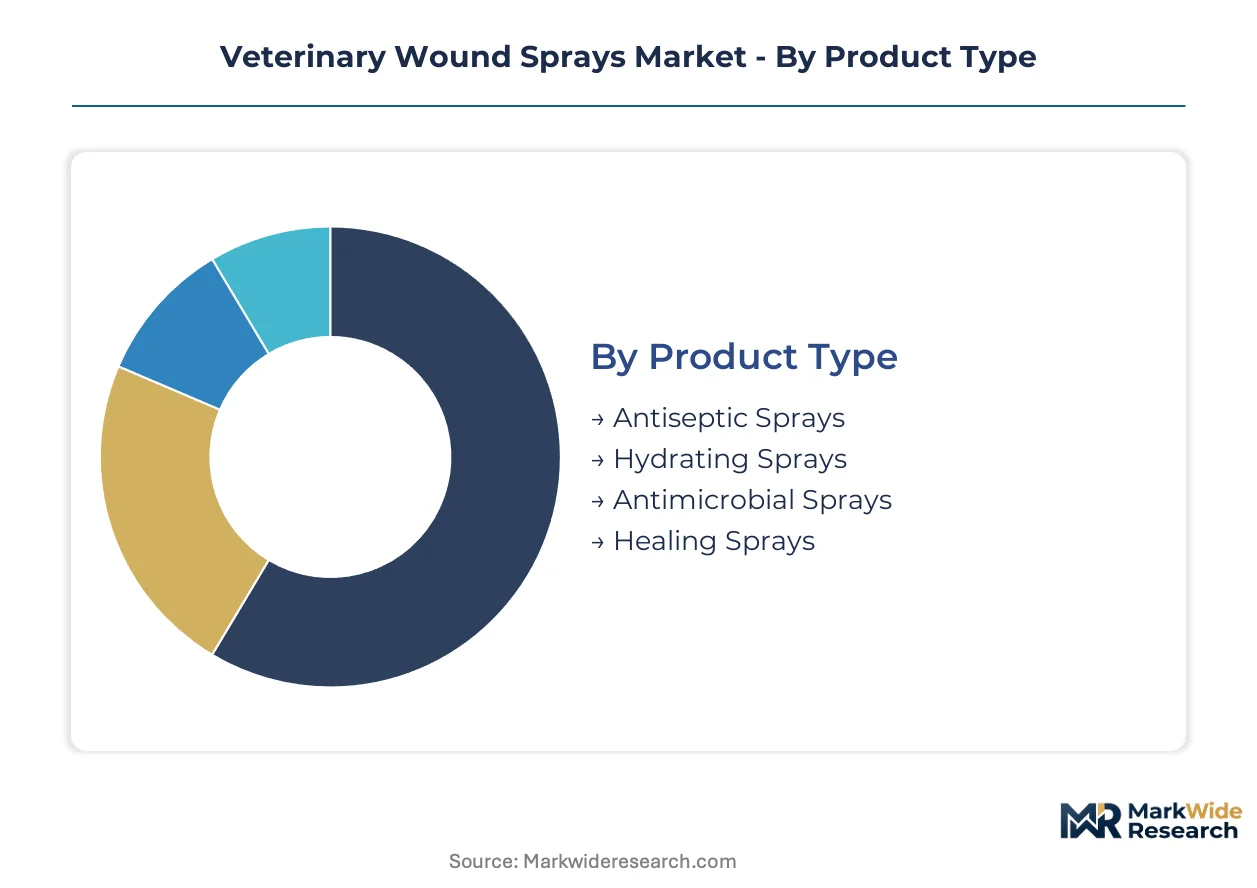
Veterinary wound spray manufacturers calibrate formulation chemistry, delivery mechanisms, and packaging formats against distinct species sensitivities and care settings. Segmentation discipline separates commodity antiseptics from premium regenerative therapies and determines regulatory pathway selection across jurisdictions.
Product Type:
Standardized active ingredient platforms compete with species-customized formulations across this category, with regulatory classification driving margin structure more than manufacturing complexity.
- Antiseptic Sprays:Chlorhexidine and povidone-iodine solutions dominate outpatient protocols. Demand concentrates in United States companion animal clinics seeking same-day discharge compliance. Chlorhexidine concentration limits imposed by FDA Center for Veterinary Medicine compress label claim flexibility.
- Antimicrobial Sprays:Silver ion and hypochlorous acid formulations disrupt biofilm-forming pathogens without antibiotic resistance pathways. German equine clinics and Brazilian livestock operations drive volume for large-surface-area coverage applications. REACH biocide sunset dates in Europe force active ingredient substitution cycles.
- Hydrating Sprays:Isotonic electrolyte solutions maintain moist wound environments for epithelial migration. Veterinary dermatology practices in Japan specify pH-calibrated formulations for feline patients.
- Healing Sprays:Medical-grade honey and hyaluronic acid accelerate granulation tissue formation. Regenerative ingredient costs limit adoption to specialty referral hospitals.
Leading the category by volume: Antimicrobial Sprays. Growing fastest: Healing Sprays.
Application:
Acute intervention protocols differ structurally from chronic wound management programs in procurement cadence and pricing tolerance.
- Wound Management:Chronic and traumatic injury protocols require repeated application over extended healing windows. Large veterinary hospital networks in the United States negotiate subscription-based replenishment tied to procedure forecasts.
- Post-Surgical Care:Incision site protection demands sterile, single-use packaging formats. German and Swiss companion animal practices prioritize ISO 10993 biocompatibility certification for premium positioning.
- First Aid:Field-deployable formats serve equine emergency response and remote livestock operations. ANVISA registration requirements in Brazil complicate import logistics for international suppliers.
- Infection Control:Biofilm disruption protocols integrate with point-of-care diagnostic platforms. Pilot programs in Germany compress diagnostic-to-treatment timelines from days to minutes.
Dominating procurement volume: Wound Management. Expanding most quickly: Infection Control.
Animal Type:
Species-specific epithelial sensitivity and regulatory filing requirements fragment formulation development across distinct veterinary specialties.
- Dogs:Highest absolute volume segment with established reimbursement pathways. United States pet insurance expansion drives demand for premium healing formulations.
- Cats:Feline skin pH sensitivity requires specialized pH-calibrated formulations. Japanese and Australian markets concentrate demand for low-irritant antiseptic platforms.
- Horses:Large surface area injuries necessitate high-volume dispensers and aerosol delivery. German equine clinics pilot bundled spray-and-test diagnostic protocols.
- Livestock:Federal welfare standard tightening in Brazil creates demand for cost-effective bulk packaging. Cattle and swine operations prioritize rapid return-to-production outcomes.
Commanding absolute volume: Dogs. Steepest expansion trajectory: Livestock.
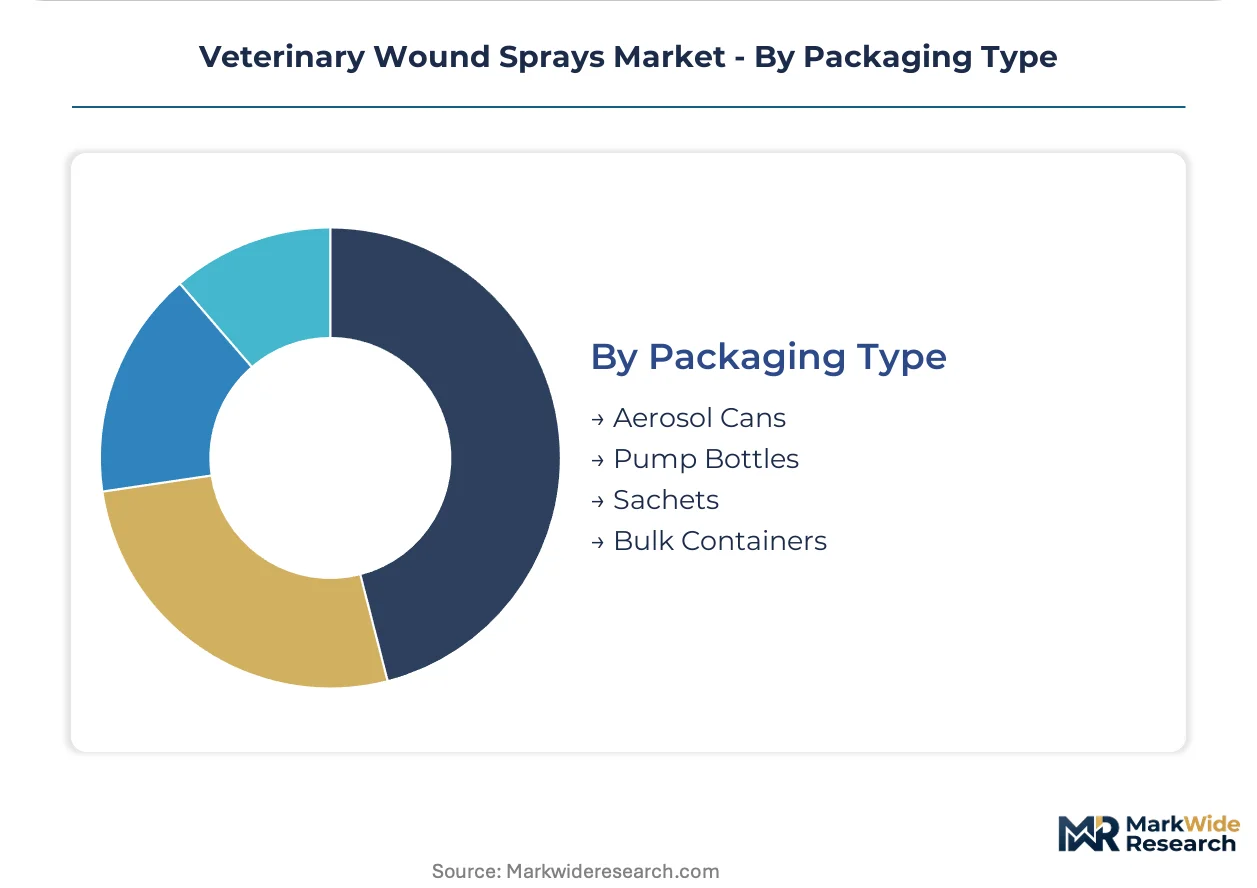
Packaging Type:
Delivery format selection trades clinical precision against operational efficiency and environmental compliance.
- Pump Bottles:Controlled-dose dispensing dominates clinic settings requiring precise application. United States companion animal practices favor recyclable PET formats for sustainability compliance.
- Aerosol Cans:Uniform coverage over large surface areas serves equine and livestock applications. Propellant regulations under EU F-Gas Directive force reformulation investments for European market access.
- Sachets:Single-use sterile units eliminate cross-contamination risk in surgical suites. Premium pricing limits adoption to specialty referral centers.
- Bulk Containers:Ranch and agricultural operations in Brazil and Australia drive demand for multi-liter refill systems. Concentrated active formulations reduce per-dose shipping costs.
Highest shipment volume: Pump Bottles. Gaining share fastest: Sachets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in Shanghai and Shenzhen concentrate veterinary pharmaceutical manufacturing for Asia-Pacific export markets. Tax incentives for medical device-grade production attract multinational spray formulation facilities. These zones process raw actives for redistribution to companion animal clinics across East Asia.
United States
Pet insurance expansion drives demand for premium healing formulations in specialty referral hospitals. FDA Center for Veterinary Medicine governs topical antiseptic claims and manufacturing standards for products entering domestic distribution. Greater Boston hosts diagnostic-to-therapeutics platform developers bundling wound sprays with antimicrobial stewardship programs.
Germany
Equine clinics pilot bundled spray-and-test protocols compressing diagnostic-to-treatment timelines. EMA centralized assessment pathways streamline novel veterinary medicinal product approvals across EU member states. Baden-Württemberg concentrates species-specific formulation development addressing both equine lacerations and small-animal surgical sites.
Brazil
Federal tightening of cattle and equine welfare standards creates demand for large-volume wound spray dispensers in ranching operations. ANVISA registration requirements complicate import logistics for international suppliers seeking access to livestock health modernization programs. São Paulo state anchors veterinary pharmaceutical distribution networks serving southeastern ranching concentrations.
China
GB standards administered by SAMR add compliance layers for manufacturers seeking access to Asia-Pacific volume. Dual carbon goals accelerate propellant reformulation investments for sustainable packaging alternatives. Yangtze River Delta manufacturing clusters produce pump bottle assemblies for regional clinic dispensing markets.
Japan
Feline skin pH sensitivity requires specialized pH-calibrated formulations for low-irritant antiseptic platforms. METI coordinates industrial standards for veterinary medical devices entering domestic distribution. Kanto region veterinary dermatology practices specify isotonic electrolyte solutions for epithelial migration support in cat patients.
Veterinary Wound Sprays Market Competitive Landscape
Top-tier vendors anchor diagnostics-to-therapeutics platforms, while mid-tier specialists compete on species-specific formulation chemistry. The vendor base stratifies across three archetypes: integrated animal health conglomerates, regional pharmaceutical specialists, and hypochlorous acid chemistry pure-plays. Portfolio diversification and strategic partnerships dominate competitive moves as regulatory windows compress for legacy active ingredients.
Within the integrated animal health tier, Zoetis and Elanco exemplify platform bundling strategies that combine wound sprays with diagnostic stewardship programs. Virbac occupies a position among European pharmaceutical specialists emphasizing species-customized formulations. Innovacyn, Inc. anchors the hypochlorous acid segment, representing tissue-compatible chemistry platforms that circumvent antibiotic resistance concerns.
| Leading Market Players |
|---|
| Zoetis |
| Elanco |
| Virbac |
| Vetoquinol |
| Innovacyn, Inc. |
| Dechra Pharmaceuticals |
| Neogen Corporation |
| Axio Biosolutions Pvt Ltd |
| Jorgen Kruuse |
| Others |
Value Network & Pricing Analysis
Silver ion spot prices and chlorhexidine API costs cascade through veterinary wound spray pricing tiers, compressing margins for antimicrobial formulations while regenerative healing sprays capture premium positioning through medical-grade honey supply scarcity.
Pricing Analysis
Short lead-time premiums separate contract manufacturing arrangements from spot procurement in veterinary wound spray supply. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 10993 biocompatibility certification and species-specific formulation complexity. Pricing pressure stems from REACH biocide sunset dates forcing accelerated reformulation cycles. Large veterinary hospital networks exhibit lowest price sensitivity due to subscription-based replenishment contracts, while independent Brazilian livestock operations drive hardest bargain negotiations.
Supply Chain Analysis
ISO 10993 and FDA Center for Veterinary Medicine qualification requirements gate supplier entry, elongating onboarding timelines for new active ingredient sources. Manufacturing concentrates in China, India, and Germany for pump bottle assemblies and API synthesis. Raw material dependencies span silver nitrate, hypochlorous acid precursors, and medical-grade Manuka honey. Single-source vulnerability concentrates in Australian and New Zealand honey suppliers. Distribution runs through veterinary distributor platforms and direct-to-clinic replenishment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compression on legacy biocides is consolidating veterinary wound spray supply, eliminating formulators lacking reformulation capital or species-specific expertise.
For Market Incumbents: Hedge antimicrobial portfolio exposure by accelerating hypochlorous acid platform investments before chlorhexidine concentration limits tighten further. Secure captive supply of medical-grade honey through backward integration into Australian apiary partnerships or long-term offtake agreements. Vertical integration into pump bottle manufacturing insulates against PET resin volatility and sustainability compliance costs. For New Entrants and Emerging Players: Hypochlorous acid chemistry platforms offer the most penetrable wedge for veterinary wound spray market entry, circumventing established antibiotic resistance concerns while bypassing REACH biocide restrictions. Target Brazilian livestock operations with bulk-container formats optimized for ranch-level wound management protocols. Pursue ANVISA registration partnerships with established local distributors to overcome import complexity. For Investors and Strategic Acquirers: EMA centralized assessment pathway approvals for novel species-specific formulations are the leading indicator that mid-tier specialists possess defensible regulatory capabilities worth acquisition premiums. Five-to-ten-year viability favors formulators with dual human-veterinary medical device expertise and regenerative active portfolios. Monitor ANVISA registration backlogs as inflection signal for Brazil market access bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| Species-Specific Formulation Development | EMA streamlined approvals accelerate EU market entry for equine and feline calibrated sprays. |
| Backward Integration into Honey Supply | Australian apiary partnerships secure medical-grade Manuka access for regenerative healing portfolios. |
| Hypochlorous Acid Platform Expansion | Tissue-compatible chemistry circumvents REACH biocide sunset dates and antibiotic resistance scrutiny. |
| Subscription-Based Replenishment Contracts | United States veterinary hospital networks concentrate procurement leverage through automated restocking agreements. |
| ISO 10993 Biocompatibility Certification | Medical device-grade testing opens premium pricing tiers in German and Swiss companion animal practices. |
Research Methodology
Document review covered FDA Center for Veterinary Medicine guidance documents, EMA centralized assessment procedures, and ANVISA registration databases, complemented by interviews with veterinary pharmaceutical formulation scientists, regulatory affairs specialists, companion animal clinic procurement managers, and livestock ranch supply coordinators. Secondary validation drew from customs trade data for silver ion imports, SEC 10-K filings for animal health conglomerates, and REACH biocide sunset date notifications. Bottom-up volume modeling triangulated against top-down market sizing from veterinary procedure frequency estimates.
Output projections span the analysis window across product type, animal species, application setting, and packaging format segmentation dimensions. CAGRs were derived from regression analysis of historical veterinary procedure volumes, pet insurance penetration trajectories, and livestock welfare regulation implementation timelines. Forecast inputs incorporated chlorhexidine regulatory friction scenarios and hypochlorous acid adoption curves from point-of-care diagnostic platform pilots.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt antimicrobial resistance policy reclassifications or precious metal supply disruptions. Model assumptions reflect current regulatory trajectories and species-specific formulation R&D productivity. A model refresh is warranted upon material change in EMA biocide assessment timelines or Brazilian federal welfare standard enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Clostridium Vaccine (Animal Health) Market
Veterinary
Global Porcine Vaccine Market
Veterinary
USA Animal Model Market
Veterinary
United Kingdom Veterinary Healthcare Market
Veterinary
Bovine Respiratory Disease Treatment Market
Veterinary
Veterinary Contract Development and Manufacturing Organizations (CDMO) Market
Veterinary
Global Veterinary Artificial Insemination Market
Veterinary
Spain Veterinary Healthcare Market
Veterinary
US Surgical Pet Collar Market
Veterinary
Spay and Neuter Market
Veterinary
Global Animal Parasiticides Market
Veterinary
Global Veterinary Monitoring Equipment Market
Veterinary
Canine Separation Anxiety Treatment Market
Veterinary
Global Animal Sedative Market
Veterinary
Bovine Mastitis Treatment System Market
Veterinary
Veterinary Supplements Market