
 Pet Veterinary Diet Market | 2026-2036
Pet Veterinary Diet Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Veterinary Diet Market Outlook
Subscription-based auto-delivery of prescription diets is rebalancing how manufacturers capture lifetime value from chronic-condition patients. Mars Petcare leverages its Banfield veterinary hospital network to anchor direct-to-consumer fulfillment channels. Hill's Pet Nutrition sustains deep clinical trial partnerships that differentiate its therapeutic formulations from over-the-counter alternatives. Nestlé Purina PetCare competes through specialized renal and gastrointestinal product lines that occupy premium shelf space in veterinary practices.
Pet veterinary diets are clinically formulated nutrition products manufactured to precise macronutrient profiles, typically produced via extrusion or retort processing under veterinary oversight to manage diagnosed health conditions. Their primary purpose is to deliver measurable physiological outcomes—such as reduced serum phosphorus in renal patients or controlled glycemic response in diabetic animals—under professional supervision. Dry food formulations dominate volume due to shelf stability and lower per-feeding cost, while wet food commands stronger margins among aging pet populations with dental compromise. The obesity management segment within health concern categorization leads absolute prescription volume, though novel protein ingredients are accelerating fastest as food allergy diagnoses multiply in companion animal practice.
The FDA Center for Veterinary Medicine enforces strict differentiation between therapeutic claims and standard pet food marketing, shaping product registration requirements and label substantiation protocols. State veterinary medical boards in the US further regulate the dispensing relationship, limiting direct retail access and preserving the clinic channel. AAFCO nutrient profiles and feeding trial standards provide the baseline compliance framework against which therapeutic formulations position their enhanced specifications. Stakeholders must monitor evolving telehealth regulations that could relax or tighten the veterinary-client-patient relationship requirements governing prescription diet authorization.
Market Dynamics
Veterinary clinic consolidation is compressing the distribution channel for prescription diets, concentrating purchasing power among fewer buyers while telehealth regulations threaten to loosen the veterinary-client-patient relationship requirements that currently gate direct retail access.
Growth Catalysts
- Pet Humanization Trajectory:Companion animal owners in the United States allocate escalating portions of household expenditure toward clinical nutrition, treating therapeutic diets as essential medical interventions rather than discretionary purchases.
- Chronic Condition Prevalence:Diabetes mellitus, chronic kidney disease, and obesity diagnoses in dogs and cats multiply across veterinary practices, generating sustained demand for condition-specific macronutrient formulations.
- FDA Center for Veterinary Medicine Enforcement:Strict differentiation between therapeutic claims and standard pet food marketing preserves professional channel exclusivity, protecting margin structures for prescription-grade manufacturers.
Market Restraints
- Veterinary Labor Scarcity:The American Veterinary Medical Association documents persistent shortages of board-certified nutritionists and general practitioners, constraining the diagnostic capacity required to authorize prescription diets.
- Input Cost Volatility:Novel protein sources including hydrolyzed soy, rabbit, and kangaroo face supply interruptions from Australian drought cycles and export restrictions, destabilizing formulation costs.
- Substitution Pressure:Over-the-counter "veterinary exclusive" diets without therapeutic claims capture price-sensitive owners seeking clinical-adjacent nutrition without examination fees.
Strategic Opportunities
- Telehealth Regulatory Evolution:State veterinary medical boards in California, Texas, and Florida experiment with relaxed VCPR requirements, potentially enabling direct-to-consumer subscription models bypassing clinic dispensing.
- Geriatric Pet Population Expansion:Cats aged eleven-plus years represent the fastest-growing demographic segment, creating demand for renal support and cognitive function formulations with enhanced palatability profiles.
- Microbiome Modulation Science:Fecal transplant therapies and targeted prebiotic fibers converge with traditional extrusion processing, opening formulation differentiation beyond macronutrient ratios.
Industry Challenges
- Clinical Trial Recruitment Bottlenecks:AAFCO feeding trial standards require controlled populations of diagnosed animals, extending product development timelines when veterinary practices prioritize revenue-generating services over research participation.
- Legacy System Integration Friction:Practice management software from IDEXX and Mars lacks API standardization with manufacturer auto-delivery platforms, complicating inventory synchronization and prescription renewal workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Veterinary Diet Market |
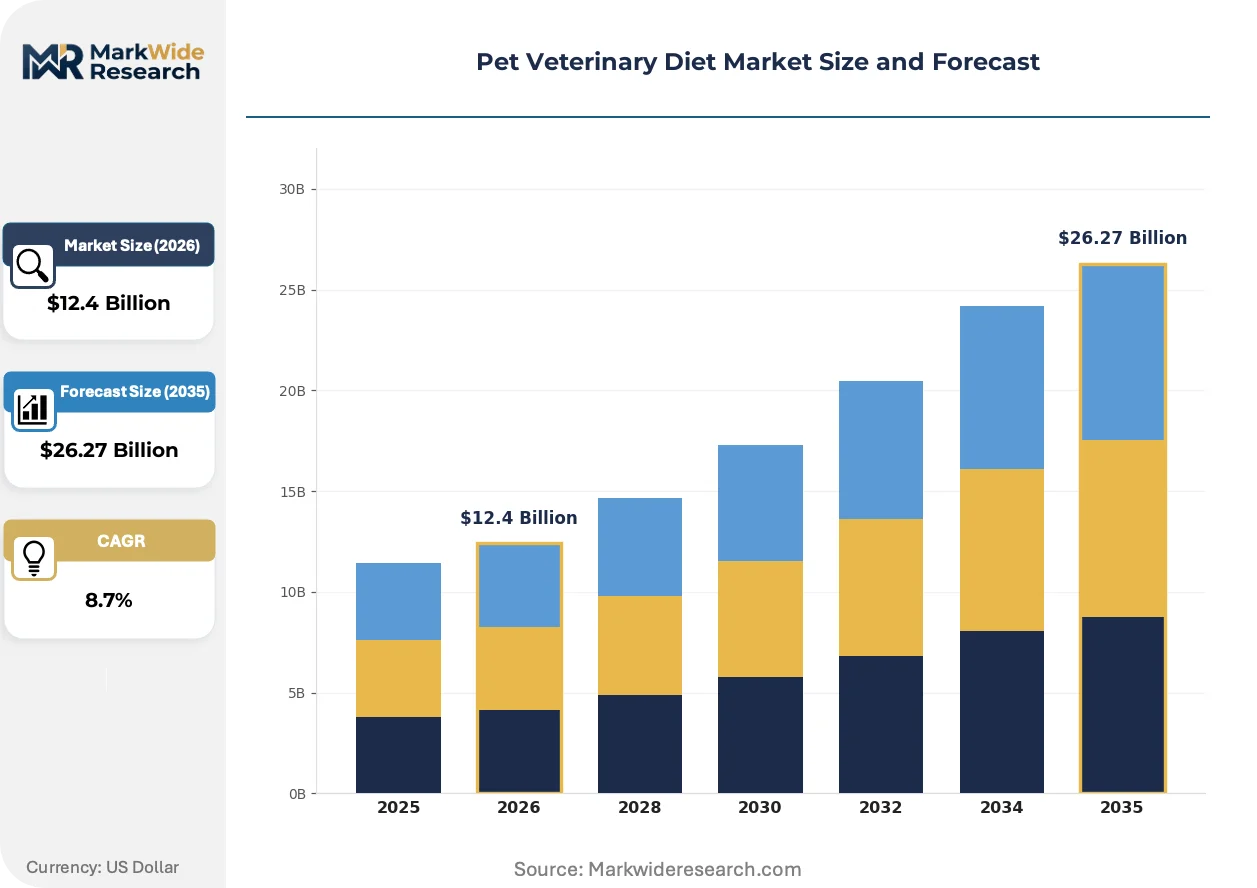
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements End User: Pet Owners, Veterinary Clinics, Animal Shelters, Pet Shops Ingredients: Meat-Based, Grain-Free, Novel Proteins, Preservative-Free Health Concern: Obesity Management, Allergies, Digestive Health, Kidney Support |
| Companies Covered | Diamond Pet Foods, J.M. Smucker, Mars Petcare, Champion Petfoods, WellPet, Nestlé Purina PetCare, General Mills, Nature’s Variety, Hill's Pet Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Veterinary Diet Market Strategic Shifts
Biomarker-driven personalization is displacing one-size-fits-all therapeutic formulations, while regulatory scrutiny of sustainability claims and packaging waste intensifies pressure on manufacturing footprints.
Hydrolyzed protein technology is converging with advanced extrusion processing to eliminate allergenic epitopes while preserving essential amino acid bioavailability. Veterinary dermatology practices in Germany and the United Kingdom adopt these formulations at accelerating rates for atopic dermatitis management. This convergence is compressing the market for elimination diet trials based on unprocessed novel proteins, favoring faster diagnostic protocols.
The European Commission's Packaging and Packaging Waste Regulation imposes extended producer responsibility mandates on pet food manufacturers, requiring recyclable mono-material structures by 2030. Industrial consequence includes accelerated capital deployment toward retort pouch redesign and metallized film replacement. Wet food manufacturers serving Nordic veterinary markets face the most acute compliance timelines, with Denmark and Sweden already enforcing stricter national standards.
Subscription auto-delivery is displacing clinic-based replenishment among urban pet owners managing chronic conditions. Mars Petcare's Banfield network and independent telehealth platforms capture this behavioral shift, replacing quarterly clinic visits with algorithm-driven reorder cycles. This pattern concentrates most visibly in United States metropolitan corridors where same-day delivery infrastructure saturates and veterinary appointment availability constrains.
Pet Veterinary Diet Market Segmentation
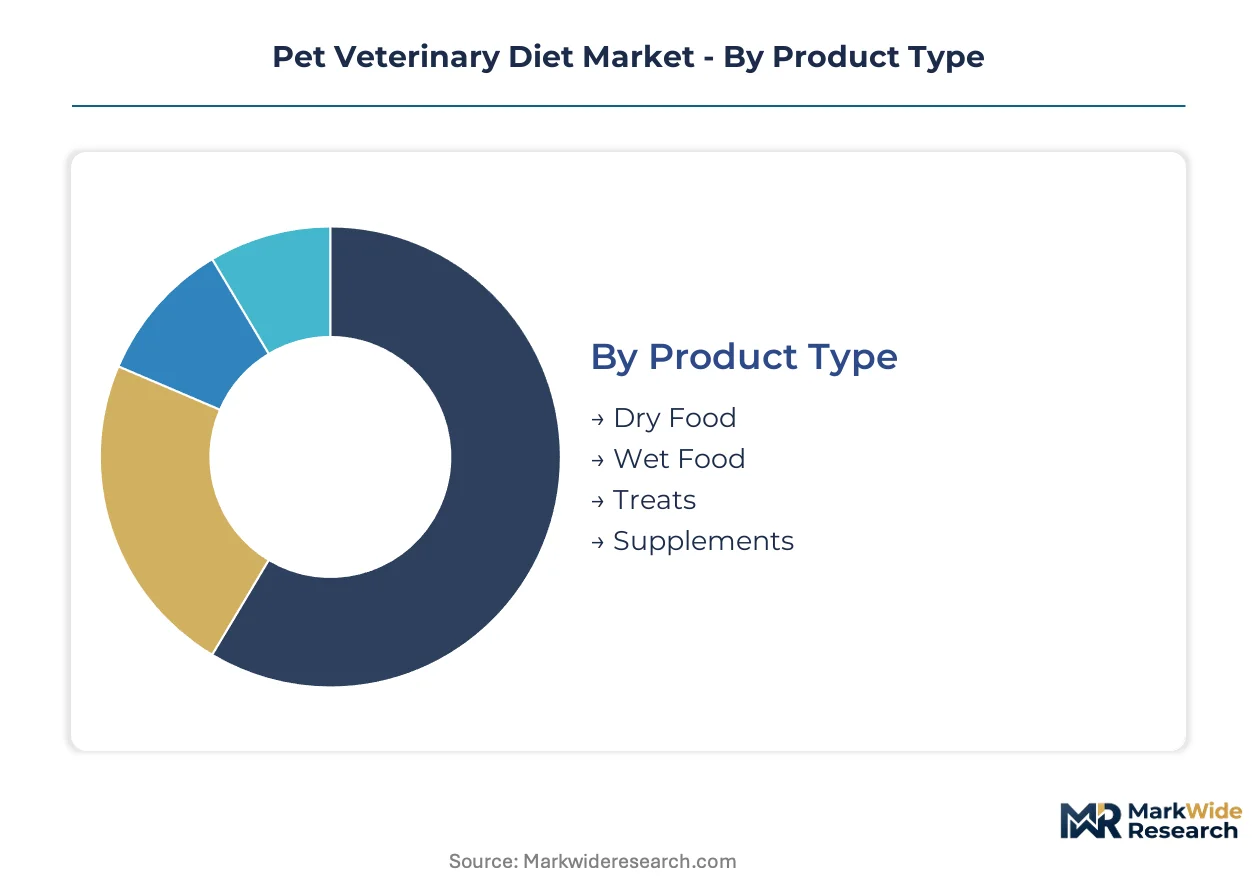
Veterinary diet segmentation reflects divergent clinical workflows: chronic condition management demands sustained prescription volume, while acute diagnostic protocols favor trial-sized formats. Channel exclusivity requirements and reimbursement structures further stratify purchasing behavior across institutional and retail buyers.
Product Type:
Cost tier differentiates buyers through feeding economics and shelf-life calculations.
- Dry Food:Extruded kibble formulations achieve extended stability through moisture reduction below 10%, enabling bulk dispensing in multi-pet veterinary settings. United States metropolitan practices favor 25-40 pound bags for diabetic and renal maintenance populations, constrained by warehouse space and inventory turnover requirements.
- Wet Food:Retort-processed cans and pouches deliver enhanced palatability via higher fat emulsion and aromatic volatiles, commanding premium positioning in geriatric feline applications. Nordic regulatory pressure on packaging recyclability accelerates mono-material pouch development, raising unit costs while satisfying extended producer responsibility mandates.
- Treats:Bite-sized therapeutic formats enable compliance reinforcement during clinical examinations without disrupting prescribed macronutrient ratios.
- Supplements:Powder and gel formulations provide adjunctive omega-3, probiotic, or joint support outside complete-and-balanced feeding protocols.
Volume sits with dry formulations; growth tilts toward wet food as feline geriatric populations expand.
End User:
Application context determines authorization requirements and replenishment cadence.
- Pet Owners:Direct purchasers operating under valid veterinary-client-patient relationships, increasingly channeled toward auto-delivery subscriptions for chronic conditions. California and Texas telehealth experiments relax examination requirements, enabling direct-to-consumer fulfillment bypassing clinic inventory.
- Veterinary Clinics:Institutional dispensaries capturing margin through in-house retail, consolidating purchasing power as corporate ownership concentrates. Mars Petcare's Banfield network exemplifies vertical control from formulation through point-of-care dispensing.
- Animal Shelters:High-volume procurement of therapeutic diets for intake populations with undocumented health histories, prioritizing cost containment over condition-specific precision.
- Pet Shops:Limited-access channels for "veterinary exclusive" over-the-counter lines lacking therapeutic claims, serving price-sensitive owners seeking clinical-adjacent positioning.
Procurement authority concentrates in clinic networks; expansion tilts toward subscription-enabled direct channels.
Ingredients:
Supply concentration and allergenic risk profile shape formulation strategies.
- Meat-Based:Conventional poultry and beef proteins dominate baseline therapeutic formulations, sourced through established rendering and slaughter by-product channels with price volatility tied to human food commodity cycles.
- Grain-Free:Carbohydrate substitution with legumes and tubers addresses perceived gluten sensitivity, though FDA investigations into dilated cardiomyopathy associations have tempered growth trajectories in canine applications.
- Novel Proteins:Hydrolyzed soy, rabbit, and kangaroo sources eliminate allergenic epitopes for elimination diet protocols. Australian drought cycles and export restrictions destabilize kangaroo supply, compressing availability for dermatology practices in Germany and the United Kingdom.
- Preservative-Free:Retort and aseptic processing replaces chemical stabilization, satisfying owner preference narratives while shortening shelf life and raising distribution complexity.
Baseline volume rests with meat-based formulations; allergen-driven substitution accelerates most quickly in novel protein categories.
Health Concern:
Condition prevalence and diagnostic penetration determine addressable market depth.
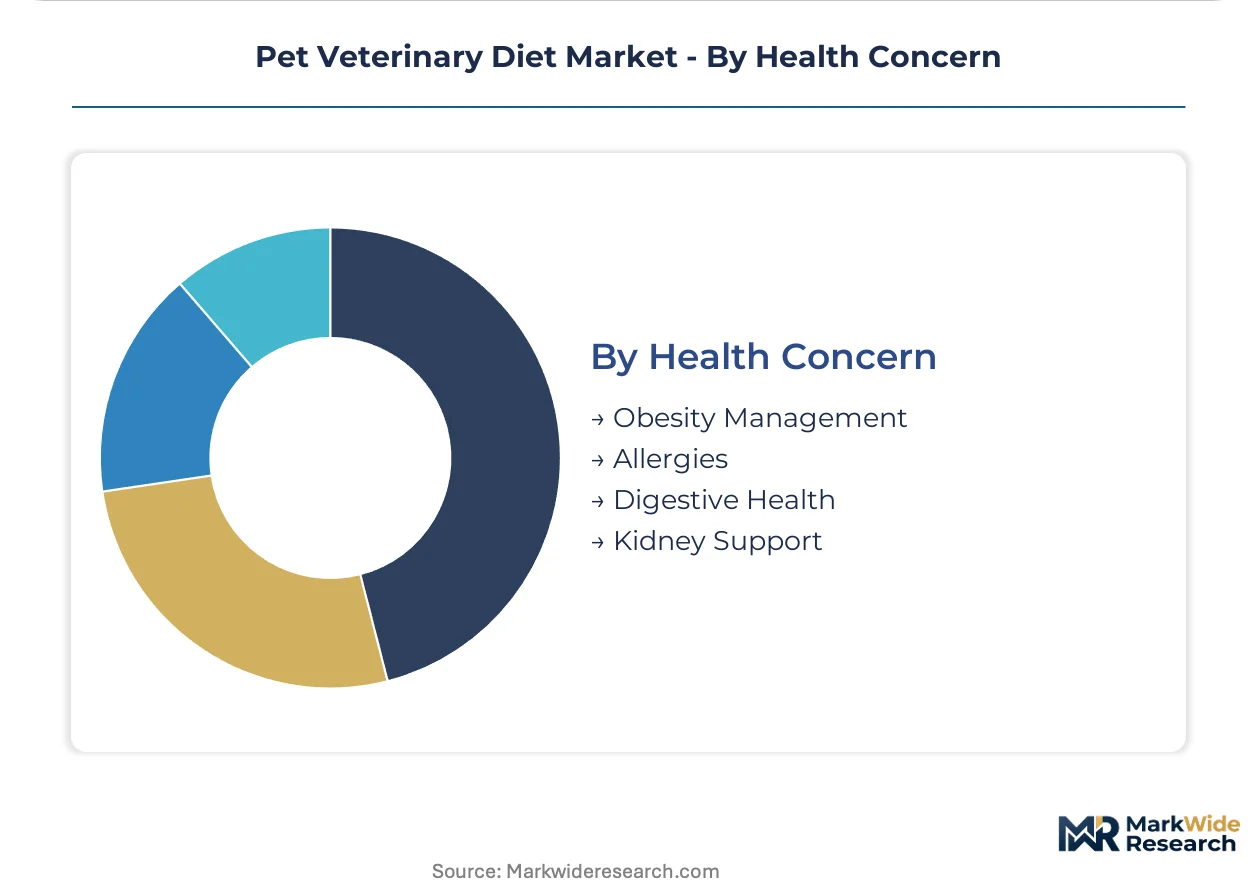
- Obesity Management:High-fiber, reduced-calorie density formulations address the most frequently diagnosed chronic condition in companion animal practice. Sustained compliance challenges limit lifetime value capture despite high initial prescription rates.
- Allergies:Atopic dermatitis and adverse food reaction diagnoses multiply across veterinary dermatology referrals, driving hydrolyzed protein and limited-antigen diet volume. German and UK practices adopt accelerated diagnostic protocols favoring hydrolyzed formulations over unprocessed novel protein trials.
- Digestive Health:Highly digestible and microbiome-modulating fibers target acute gastroenteritis and chronic enteropathy populations, converging with prebiotic and fecal transplant therapy adjacencies.
- Kidney Support:Restricted phosphorus and enhanced omega-3 formulations serve progressive renal insufficiency populations, with palatability engineering critical to maintaining intake in azotemic cats.
Absolute prescription volume concentrates in obesity management; steepest expansion trajectory belongs to allergy protocols as diagnostic specificity improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in North American and European extrusion facilities, while consumption growth tilts toward urban centers in Asia-Pacific and Latin America where pet humanization accelerates fastest. Veterinary clinic density and regulatory frameworks for prescription authorization determine effective market penetration in each geography.
United States
Veterinary clinic consolidation and Banfield's vertical network dominate distribution, with California and Texas experimenting with relaxed VCPR requirements for telehealth prescriptions. The FDA Center for Veterinary Medicine enforces strict therapeutic claim differentiation, preserving professional channel exclusivity. Metropolitan corridors from Boston to Seattle drive subscription auto-delivery adoption for chronic condition management.
Germany
Dermatology practices in Munich and Hamburg accelerate hydrolyzed protein formulation adoption for atopic dermatitis protocols. The European Commission's Packaging and Packaging Waste Regulation imposes 2030 extended producer responsibility mandates, forcing retort pouch redesign investments. Industrial clusters in Bavaria concentrate extrusion technology suppliers serving Central European veterinary markets.
United Kingdom
London and Manchester veterinary referral hospitals drive novel protein elimination diet volume despite supply interruptions from Australian export restrictions. The Veterinary Medicines Directorate aligns with EU regulatory frameworks post-Brexit, maintaining prescription authorization requirements. Telehealth platforms in Southeast England experiment with direct-to-consumer fulfillment models.
Japan
Tokyo and Osaka metropolitan areas generate concentrated demand for geriatric feline renal support formulations as cat longevity extends. The Ministry of Agriculture, Forestry and Fisheries regulates functional pet food claims, requiring clinical substantiation for therapeutic positioning. Kanto region veterinary chains consolidate purchasing power, compressing manufacturer margin negotiations.
Australia
Sydney and Melbourne clinics face acute kangaroo protein supply volatility from drought cycles affecting novel protein formulation availability. The Department of Agriculture, Fisheries and Forestry oversees pet food export certification, constraining regional supply flexibility. Queensland processing facilities serve as primary rendering hubs for Asia-Pacific novel protein sourcing.
Pet Veterinary Diet Market Competitive Environment
Capital-heavy producers with captive extrusion and retort facilities compete with asset-light brand marketers outsourcing manufacturing to contract processors. The market structure consolidates around three multinational nutrition conglomerates controlling veterinary clinic networks and prescription authorization workflows. Strategic archetypes include vertically integrated clinic-network operators, clinical-trial-driven formulation specialists, and private-label contract manufacturers serving price-sensitive channels. Dominant competitive moves encompass backward integration into rendering and protein processing, plus exclusive distribution agreements with consolidating veterinary practice groups.
Among North American nutrition conglomerates, Mars Petcare, Nestlé Purina PetCare, and Hill's Pet Nutrition occupy distinct strategic positions. Mars Petcare exemplifies the clinic-network-integrated archetype through its Banfield hospital ownership, enabling captive distribution from formulation through point-of-care dispensing. Nestlé Purina PetCare represents the portfolio-diversified competitor with specialized renal and gastrointestinal lines commanding premium shelf positioning. Hill's Pet Nutrition anchors the clinical-evidence tier through sustained veterinary school partnerships and feeding trial investments that differentiate its therapeutic formulations from over-the-counter alternatives. These three structures collectively define competitive intensity in prescription diet authorization and chronic patient lifetime value capture.
| Leading Market Players |
|---|
| Diamond Pet Foods |
| J.M. Smucker |
| Mars Petcare |
| Champion Petfoods |
| WellPet |
| Nestlé Purina PetCare |
| General Mills |
| Nature's Variety |
| Hill's Pet Nutrition |
| Others |
Value Chain & Pricing Dynamics
Hydrolyzed protein extrusion technology adoption simultaneously compresses manufacturing unit economics and concentrates supplier power among equipment specialists in Germany and the United States. This convergence reshapes how manufacturers balance formulation premiumization against input cost volatility.
Pricing Analysis
Margin tightening in wet food formulations reflects retort pouch redesign investments driven by European extended producer responsibility mandates. Three-tier pricing structure across premium, standard, and economy levels differentiates buyers by certification grade and volume scale. Pricing pressure stems from novel protein supply interruptions. Price-sensitive animal shelters prioritize cost containment over condition-specific precision.
Supply Chain Analysis
Single-source vulnerability sits with Australian kangaroo protein exports subject to drought cycle disruptions. Rendering capacity concentrates in the United States, Germany, and Thailand. Raw material dependencies include hydrolyzed soy isolates, omega-3 marine oils, and specialized vitamin premixes. Tariff exposure on European packaging materials threatens retort pouch cost structures. Distribution runs through vertically integrated veterinary clinic networks and emerging direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pet veterinary diet sector is transitioning from macronutrient-based formulations toward microbiome-modulated personalized nutrition, displacing legacy one-size-fits-all therapeutic protocols.
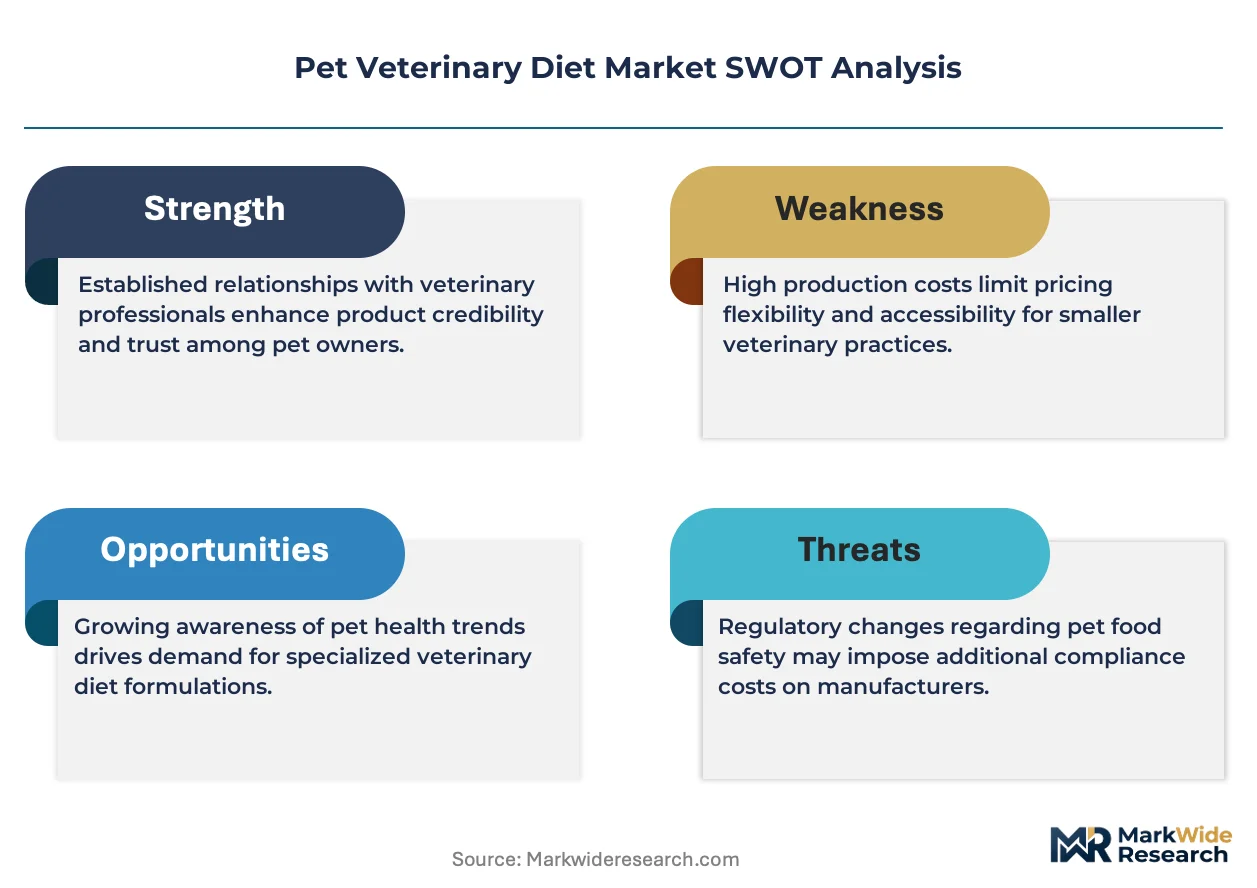
For Market Incumbents: Hedge against telehealth regulatory relaxation by securing exclusive distribution agreements with consolidating veterinary practice groups before state veterinary medical boards in California and Texas normalize direct-to-consumer channels. Deepen backward integration into novel protein rendering to insulate margin structures from Australian supply volatility. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting urban geriatric feline populations in United States metropolitan corridors where same-day delivery infrastructure saturates and veterinary appointment availability constrains. White-space opportunity concentrates in microbiome modulation science converging with traditional extrusion processing. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational nutrition conglomerates seeking captive clinic-network distribution. Long-term viability hinges on telehealth regulatory evolution and chronic condition diagnostic penetration. The signal to watch is state veterinary medical board VCPR requirement relaxation enabling direct retail authorization.| Strategic Initiative | Industry Significance |
|---|---|
| Microbiome Modulation R&D Investment | Fecal transplant therapies and targeted prebiotic fibers open formulation differentiation beyond macronutrient ratios. |
| Retort Pouch Redesign Program | European Commission Packaging and Packaging Waste Regulation mandates recyclable mono-material structures by 2030. |
| Veterinary Clinic Network Acquisition | Vertical control from formulation through point-of-care dispensing preserves margin structures and patient lifetime value. |
| Novel Protein Supply Agreement | Long-term offtake contracts with Australian and South American rendering facilities reduce drought cycle exposure. |
| Telehealth Platform Integration | Algorithm-driven reorder cycles replace quarterly clinic visits for chronic condition management in urban corridors. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this pet veterinary diet market assessment. Primary interviews with veterinary nutritionists, clinic procurement managers, manufacturer R&D directors, and telehealth platform operators combined with FDA Center for Veterinary Medicine substantiation documents, AAFCO feeding trial standards, and European Commission packaging regulations. Bottom-up patient population modeling and top-down manufacturer revenue triangulation validated segmentation outputs.
Data-stream reconciliation across prescription volume tracking, ingredient cost indices, and channel margin structures informed the analytical framework across the analysis window. Segmentation dimensions modeled include product type, health concern indication, end-user channel, and geographic regulatory cluster. CAGRs derived from chronic condition prevalence trajectories and pet humanization expenditure elasticity. Forecast inputs incorporated veterinary labor availability constraints and telehealth regulatory evolution scenarios.
Regulatory enforcement intensity, novel protein supply disruption severity, and telehealth VCPR relaxation pace are the dominant revision risks to projection assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Immunodiagnostics Market
Veterinary
Asia-Pacific Veterinary Healthcare Market
Veterinary
Companion Animal Arthritis Market
Veterinary
Global Animal Vaccine Market
Veterinary
Japan Veterinary Healthcare Market
Veterinary
Global Veterinary Drugs Market
Veterinary
Veterinary Healthcare Market
Veterinary
Veterinary and Animal Healthcare Logistics Market
Veterinary
Veterinary Point-Of-Care Diagnostics Market
Veterinary
Veterinary Endodontics Market
Veterinary
Rabies Veterinary Vaccines Market
Veterinary
Global Veterinary Telehealth Market
Veterinary
Europe Dog Dewormers Market
Veterinary
Europe Veterinary Vaccine Market
Veterinary
Global Animal Antimicrobials and Antibiotics Market
Veterinary
Veterinary Excipients Market