
 Asia-Pacific Optical Fibers in Endoscopy Market | 2026-2036
Asia-Pacific Optical Fibers in Endoscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Optical Fibers in Endoscopy Market Insights
The performance gap between premium silica-core bundles and commodity plastic optical fibers is hardening as clinical settings demand higher resolution imaging. Olympus Corporation leverages captive fiber-drawing capabilities to control specification consistency across its endoscope lines. Fujifilm Holdings Corporation anchors its position through vertical integration into lens-coating and fiber-termination processes. Shanghai Aohua Endoscopy competes on localized service networks and faster turnaround for hospital maintenance contracts.
Asia-Pacific optical fibers in endoscopy transmit coherent light through graded-index silica or perfluorinated polymer cores to illuminate and return images from internal body cavities, with core diameters typically ranging from 50 to 200 micrometers and numerical apertures optimized for bending tolerance in flexible scopes. Specialty fibers command margin premiums due to customized spectral transmission windows for narrow-band imaging and fluorescence-guided procedures. Hospitals dominate end-user procurement through centralized capital equipment budgets, while gastrointestinal procedures absorb the largest application share driven by colorectal and upper-GI screening protocols across aging populations in Japan and South Korea.
Japan's PMDA enforces JIS T 0601 biocompatibility and sterilization durability standards that filter out lower-tier suppliers, while China's NMPA accelerates review timelines for domestically manufactured fiber components under innovation-track pathways. India's CDSCO aligns with ISO 13485 quality management requirements for imported endoscope fiber bundles, creating compliance cost barriers for new entrants. Stakeholders must monitor how PMDA's evolving optical performance benchmarks and NMPA's localization incentives reshape supplier qualification criteria and procurement award patterns across the region's hospital systems.
Market Dynamics
Japan's PMDA biocompatibility tightening for flexible endoscopes is forcing manufacturers toward higher-grade silica formulations, compressing margins for commodity fiber suppliers while rewarding captive production capabilities.
Growth Catalysts
- Colorectal screening protocols:Aging demographics across Japan and South Korea are expanding procedure volumes in tertiary hospital systems, pulling demand for coherent illumination bundles.
- PMDA's JIS T 0601 standards:Stricter sterilization durability requirements are filtering out lower-tier suppliers and consolidating procurement toward qualified vendors with certified fiber-drawing operations.
- Eastern China hospital clusters:Provincial procurement budgets for minimally invasive diagnostic suites in Jiangsu and Zhejiang are expanding faster than national averages, concentrating capital equipment demand.
Market Restraints
- High-purity silica supply concentration:Specialty fiber-grade silica precursor availability depends on limited Japanese and German chemical suppliers, creating input cost volatility.
- CDSCO import compliance costs:India's alignment with ISO 13485 quality management requirements for fiber bundles creates certification barriers for new entrants without established local representation.
- Plastic optical fiber substitution ceiling:Perfluorinated polymer cores face resolution limitations in narrow-band imaging applications, blocking adoption in fluorescence-guided procedures.
Strategic Opportunities
- NMPA innovation-track pathways:China's accelerated review timelines for domestically manufactured fiber components create regulatory tailwinds for local production investments.
- Fluorescence-guided surgery convergence:Customized spectral transmission windows for tumor-margin detection are expanding into urological and thoracic applications beyond gastrointestinal.
- Maintenance contract unbundling:Hospital clusters in India are separating fiber bundle replacement from OEM service agreements, opening independent aftermarket channels.
Industry Challenges
- Fiber-termination technician scarcity:Precision polishing and connector alignment for sub-100-micrometer cores requires specialized training programs that regional technical institutes have not scaled.
- Legacy endoscope compatibility:Graded-index silica upgrades must interface with existing light-source couplings, creating integration complexity for hospital capital planning committees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Optical Fibers in Endoscopy Market |
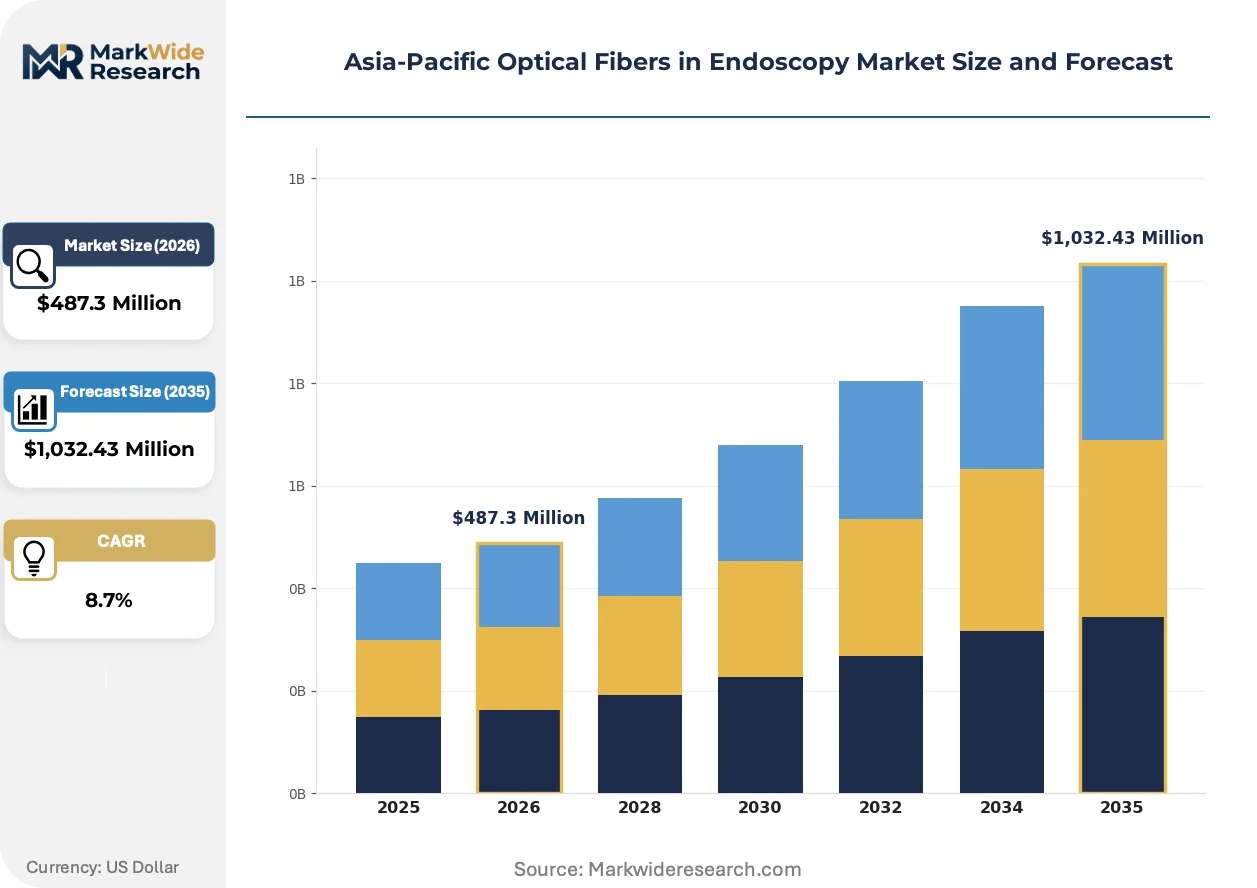
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Mode Fibers, Multi-Mode Fibers, Specialty Fibers, Plastic Optical Fibers End User: Hospitals, Clinics, Diagnostic Centers, Research Institutions Installation: On-site Installation, Off-site Installation, Integrated Solutions, Maintenance Services Application: Gastrointestinal Procedures, Urological Procedures, Respiratory Procedures, Surgical Applications |
| Companies Covered | Olympus Corporation, Hoya Corporation, Fujifilm Holdings Corporation, Karl Storz SE & Co. KG, Boston Scientific Corporation, Stryker Corporation, Richard Wolf GmbH, Shanghai Aohua Endoscopy, Medtronic plc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Optical Fibers in Endoscopy Market Trends and Innovations
Coherent imaging demands are reshaping material selection and procurement patterns across the Asia-Pacific endoscopy supply base, with three distinct vectors now visible in product development and buyer behavior.
Multicore fiber bundles with reduced pixel crosstalk are expanding into high-definition gastrointestinal scopes, enabling sub-cellular resolution without increasing outer diameter. Tertiary hospitals in Seoul and Tokyo are adopting these configurations for early neoplasia detection, compressing demand for conventional single-core illumination.
NMPA's dual carbon goals are tightening energy efficiency benchmarks for medical device manufacturing, pushing fiber-drawing facilities toward electric melting furnaces. Domestic Chinese suppliers are responding with localized silica purification to reduce import-dependent thermal processing, while Japanese competitors retrofit existing gas-fired operations.
Centralized capital equipment budgets in China's provincial hospital systems are consolidating vendor relationships around full-suite suppliers capable of lens-coating, fiber-drawing, and termination. This concentration is displacing component-only vendors in procurement awards, particularly in Jiangsu province's diagnostic suite expansion programs.
Asia-Pacific Optical Fibers in Endoscopy Market Segmentation
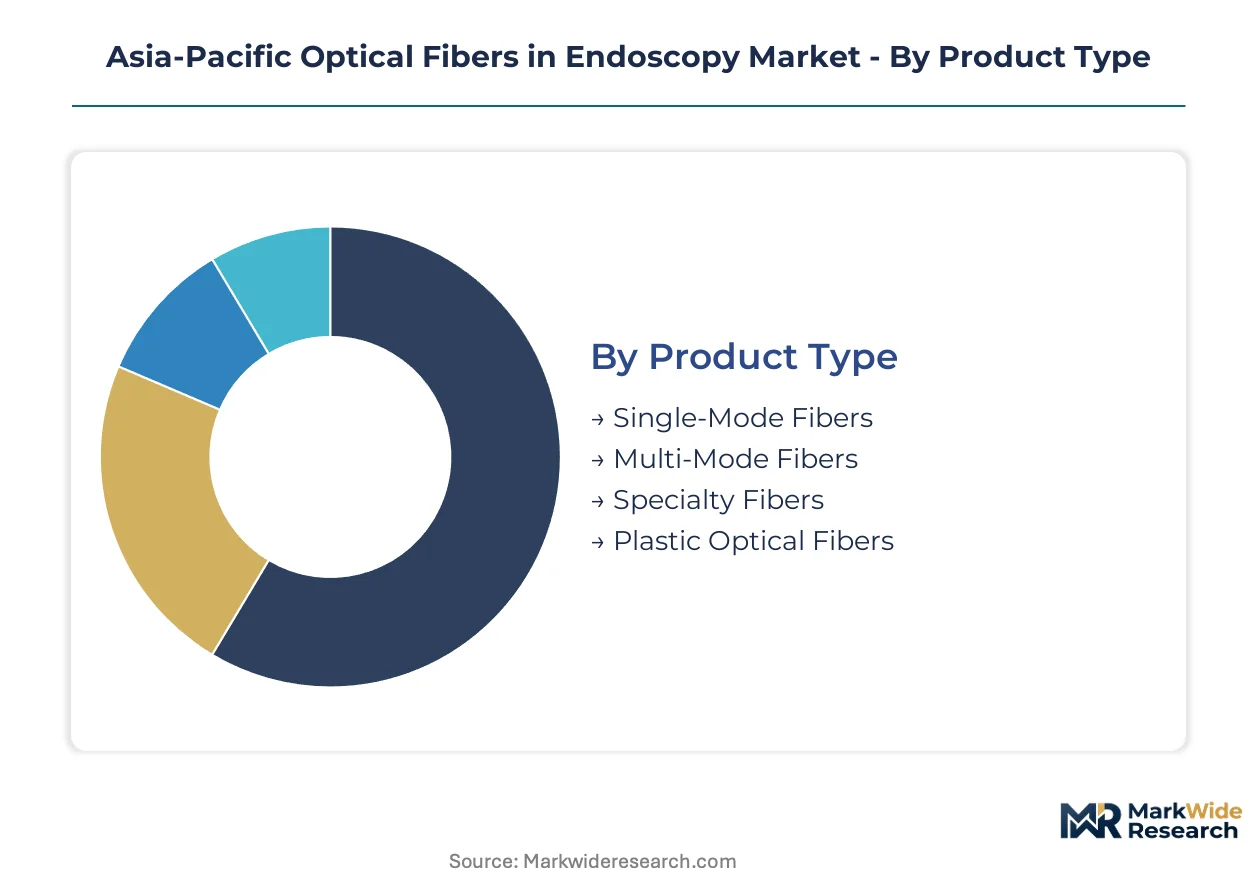
Optical fiber segmentation in Asia-Pacific endoscopy tracks how illumination and imaging bundles integrate into capital equipment versus standalone replacement cycles. Procurement committees weight bundle performance against total system compatibility when awarding contracts across hospital clusters in China, Japan, and South Korea.
Product Type:
Integration depth varies sharply: specialty and multi-mode fibers embed permanently into flexible scope assemblies, while plastic optical fibers serve standalone illumination accessories and training equipment.
- Specialty Fibers:Customized spectral transmission windows with perfluorinated polymer or doped-silica cores enable narrow-band imaging and fluorescence-guided tumor-margin detection. Tertiary hospitals in Tokyo and Seoul specify these for early neoplasia screening protocols, with PMDA biocompatibility certification filtering supplier pools.
- Multi-Mode Fibers:Graded-index silica cores with 50-200 micrometer diameters transmit coherent white light for standard gastrointestinal illumination. Demand concentrates in China's eastern province hospital clusters where Jiangsu and Zhejiang procurement budgets are expanding fastest for diagnostic suite upgrades.
- Single-Mode Fibers:Laser-grade coherence properties support confocal endomicroscopy systems in Japanese academic medical centers.
- Plastic Optical Fibers:Perfluorinated polymer cores face resolution ceilings that block adoption in fluorescence procedures, limiting use to basic training scopes and disposable accessories.
Multi-mode fibers lead volumes today; specialty fibers are gaining share fastest.
End User:
Capital equipment concentration versus consumable replacement demand splits procurement patterns across institutional tiers, with centralized budgets dominating high-value fiber bundle awards.
- Hospitals:Tertiary medical centers in China, Japan, and India wield centralized capital equipment budgets that consolidate vendor relationships around full-suite suppliers capable of lens-coating, fiber-drawing, and termination. NMPA innovation-track pathways accelerate domestic qualification for these high-volume accounts.
- Diagnostic Centers:Specialized gastrointestinal screening facilities in South Korea's national cancer prevention program drive procedure volume without owning complete endoscope systems, purchasing replacement bundles on shorter cycles.
- Clinics:Private ambulatory centers in India's urban corridors face CDSCO import compliance barriers that favor local distributors with established ISO 13485 certification.
- Research Institutions:Academic medical centers in Japan pilot multicore fiber configurations for sub-cellular resolution studies ahead of clinical adoption.
Hospitals command the largest procurement value; diagnostic centers are expanding most quickly.
Installation:
Service unbundling is reshaping how fiber bundles reach end-users, with maintenance contract separation creating independent aftermarket channels.
- Integrated Solutions:Full-system procurement bundles fiber illumination with video processors and light sources, favored by China's provincial hospital clusters consolidating vendor relationships.
- Maintenance Services:Hospital clusters in India are separating fiber bundle replacement from OEM service agreements, opening channels for independent technicians capable of precision polishing and connector alignment.
- On-site Installation:Direct technical support ensures compatibility verification with existing light-source couplings in legacy endoscope fleets.
- Off-site Installation:Regional refurbishment centers in Japan handle sterilization-durable bundle reconditioning under PMDA JIS T 0601 standards.
Integrated solutions dominate new equipment sales; maintenance services are climbing fastest.
Application:
Procedure-specific imaging requirements drive material selection, with gastrointestinal volume anchoring demand while fluorescence convergence expands fiber specifications into adjacent specialties.
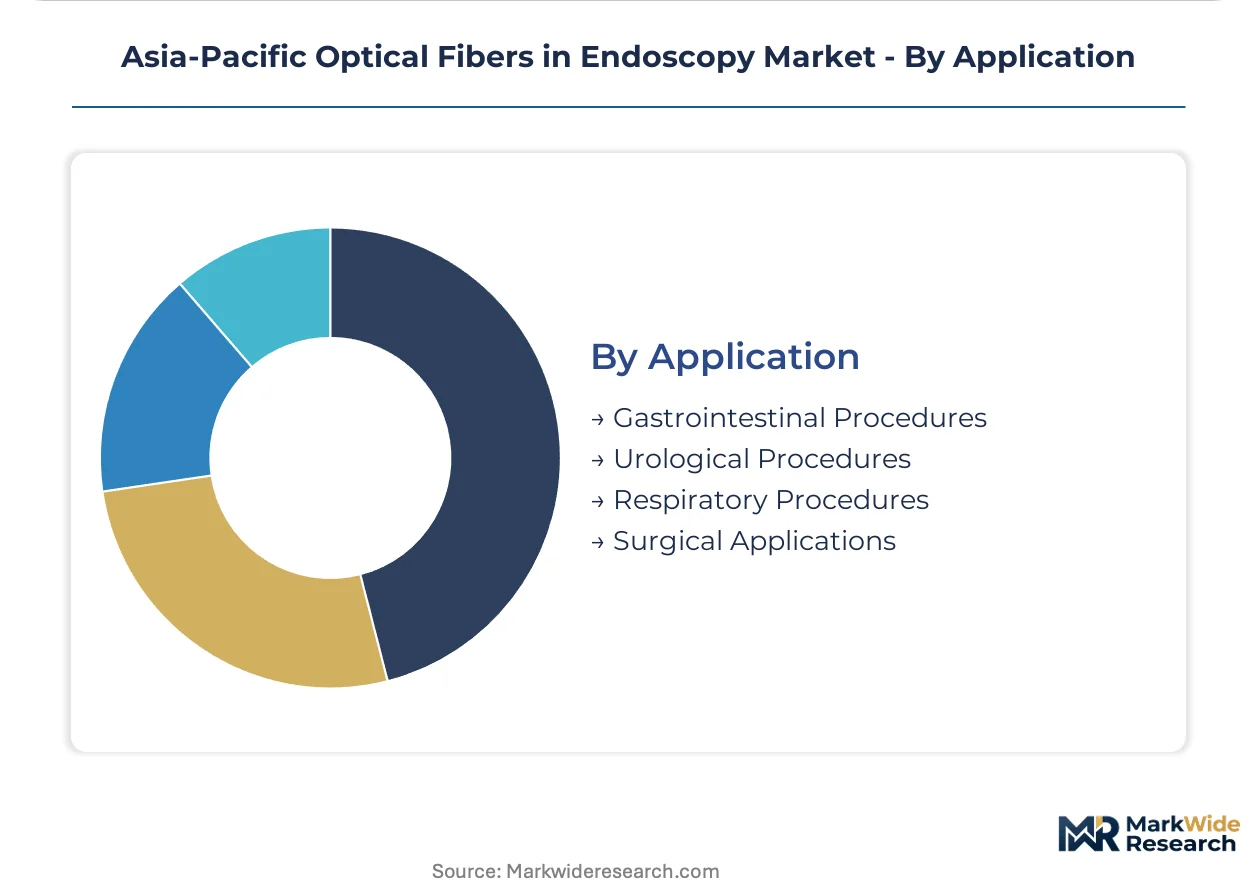
- Gastrointestinal Procedures:Colorectal and upper-GI screening protocols across aging populations in Japan and South Korea absorb the largest fiber bundle volumes, with coherent illumination requirements standardized across national health insurance reimbursement schedules.
- Urological Procedures:Cystoscopy and ureteroscopy applications in China's tier-one cities are adopting customized spectral windows for tumor-margin detection, extending fluorescence-guided surgery convergence beyond gastrointestinal origins.
- Respiratory Procedures:Bronchoscopy suites in Indian tertiary hospitals face CDSCO alignment requirements for imported fiber bundles that create compliance cost barriers.
- Surgical Applications:Thoracic and laparoscopic procedures in South Korean academic centers pilot multicore bundles for high-definition tissue differentiation.
Gastrointestinal procedures anchor volume today; urological applications show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fiber-drawing technicians and precision-polishing specialists concentrate in Japan's Nagoya corridor and China's Jiangsu province, anchoring regional supply capabilities for coherent illumination bundles.
China
Eastern province hospital clusters in Jiangsu and Zhejiang are expanding procurement budgets for minimally invasive diagnostic suites faster than national averages. NMPA innovation-track pathways accelerate review timelines for domestically manufactured fiber components, creating regulatory tailwinds for local production. Shanghai Aohua Endoscopy leverages localized service networks to capture maintenance contract unbundling in tier-one city hospital systems.
Japan
Aging demographics are expanding colorectal and upper-GI screening procedure volumes in Tokyo and Osaka tertiary medical centers. PMDA enforces JIS T 0601 biocompatibility and sterilization durability standards that filter out lower-tier suppliers and consolidate procurement toward qualified vendors. Olympus Corporation controls specification consistency through captive fiber-drawing capabilities in the Chubu industrial region.
South Korea
The national cancer prevention program drives gastrointestinal screening volume through specialized diagnostic centers in Seoul without requiring complete endoscope system ownership. MFDS alignment with international quality management standards shapes import compliance for fiber bundle suppliers. Academic medical centers in the capital region pilot multicore fiber configurations for sub-cellular resolution studies ahead of clinical adoption.
India
Private ambulatory centers in Mumbai and Delhi urban corridors face CDSCO import compliance barriers that favor local distributors with established ISO 13485 certification. Tertiary hospitals are separating fiber bundle replacement from OEM service agreements, opening channels for independent technicians. Bronchoscopy suites in Bangalore and Hyderabad medical institutions absorb imported fiber bundles under tightened quality alignment requirements.
Australia
Research institutions in Melbourne and Sydney academic medical centers pilot fluorescence-guided surgery applications extending beyond gastrointestinal origins. TGA medical device regulations govern fiber bundle importation for thoracic and laparoscopic procedure expansion. Diagnostic networks in New South Wales and Victoria concentrate capital equipment procurement for aging population screening protocols.
Asia-Pacific Optical Fibers in Endoscopy Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Asia-Pacific optical fiber endoscopy supply base, creating a tiered structure where captive manufacturing capabilities separate premium-tier suppliers from component-only vendors. The market consolidates around full-suite suppliers capable of lens-coating, fiber-drawing, and termination processes. Three archetypes dominate: integrated endoscope manufacturers with captive fiber operations, specialized fiber component suppliers, and regional service-focused distributors. Competitive dynamics center on backward integration into silica purification and strategic partnerships for fluorescence-guided surgery convergence.
Among Japanese-headquartered integrated manufacturers, Olympus Corporation and Fujifilm Holdings Corporation exemplify the captive-production archetype through in-house control over specification consistency across endoscope lines. Shanghai Aohua Endoscopy occupies a position within the regional service-specialist tier, leveraging proximity to eastern China hospital clusters for faster maintenance turnaround. Hoya Corporation represents the optical-component heritage archetype, with corporate origins in precision glass and lens manufacturing that translate into fiber bundle positioning.
| Leading Market Players |
|---|
| Olympus Corporation |
| Hoya Corporation |
| Fujifilm Holdings Corporation |
| Karl Storz SE & Co. KG |
| Boston Scientific Corporation |
| Stryker Corporation |
| Richard Wolf GmbH |
| Shanghai Aohua Endoscopy |
| Medtronic plc |
| Others |
Pricing and Supply Chain Analysis
Electric melting furnace conversion across NMPA-regulated fiber-drawing facilities is compressing thermal processing costs while simultaneously redrawing procurement geography toward domestic silica purification in Jiangsu province. This production-method transition concentrates margin control among suppliers with captive energy infrastructure, forcing component-only vendors toward price concession or exit.
Pricing Analysis
Bundled full-system procurement dominates China's eastern province hospital clusters, while maintenance contract unbundling in India opens transactional replacement channels. Pricing stratifies across PMDA-certified premium tiers, NMPA innovation-track domestic tiers, and CDSCO-compliant import tiers, with certification level and volume scale as primary differentiation drivers. Cost compression in commodity plastic optical fibers intensifies as resolution limitations block fluorescence-guided adoption. Diagnostic centers in South Korea exhibit highest price sensitivity due to shorter replacement cycles without capital equipment ownership.
Supply Chain Analysis
Regional distribution centers in Shanghai and Singapore coordinate hub-and-spoke fulfillment to hospital clusters across the Asia-Pacific rim. Specialty fiber-grade silica precursor draws from Japanese and German chemical suppliers, creating single-source vulnerability for high-purity inputs. Precision polishing equipment and connector alignment tooling hinge on Nagoya corridor manufacturing. Distribution runs through OEM-integrated channels for new equipment and independent technician networks for replacement bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific optical fibers in endoscopy market functions as a geographic-arbitrage play where NMPA innovation-track regulatory cost advantages in China offset PMDA biocompatibility compliance premiums in Japan.
For Market Incumbents: Anchor specification consistency through backward integration into fiber-drawing operations, mirroring Olympus Corporation's captive production model in the Chubu industrial region. Defend against emerging domestic Chinese suppliers by accelerating lens-coating and termination capability consolidation in Jiangsu province. Prioritize PMDA JIS T 0601 certification maintenance as the primary barrier to entry lever. For New Entrants and Emerging Players: Multicore fiber configurations with reduced pixel crosstalk offer a technology-first wedge into academic medical center pilot programs in Seoul and Tokyo ahead of clinical adoption curves. Target India's maintenance contract unbundling trend through precision polishing technician training partnerships with Bangalore and Hyderabad tertiary hospitals. Pursue fluorescence-guided surgery convergence beyond gastrointestinal origins as the most penetrable application expansion vector. For Investors and Strategic Acquirers: Roll-up economics work for regional service-specialist distributors because hospital procurement consolidation around full-suite suppliers displaces component-only vendors, creating distressed acquisition targets with established ISO 13485 certification and local maintenance networks. Long-term viability centers on fluorescence-guided surgery platform positioning. Watch PMDA optical performance benchmark evolution as the inflection signal for premium tier margin expansion or compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Purification | Reduces import-dependent thermal processing exposure under NMPA dual carbon benchmarks. |
| PMDA JIS T 0601 Certification Investment | Filters lower-tier suppliers and consolidates procurement toward qualified fiber-drawing vendors. |
| Maintenance Contract Unbundling Capture | Opens independent aftermarket channels in India's CDSCO-regulated import environment. |
| Fluorescence-Guided Surgery Platform Development | Extends spectral transmission window applications into urological and thoracic procedures. |
| Multicore Fiber Bundle Clinical Pilot Programs | Positions for sub-cellular resolution adoption in Tokyo and Seoul tertiary screening protocols. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fiber-drawing operations managers, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation from PMDA submission databases, NMPA innovation-track approval records, CDSCO import registration filings, and hospital procurement budget disclosures. Bottom-up fiber bundle volume estimates and top-down endoscope system deployment data triangulated across the analysis window.
Comparable historical reference periods anchored the projection horizon to sterilization durability replacement cycles and capital equipment refresh timelines. Segmentation modeling tracked product type, end user tier, installation mode, and application specialty dimensions across the forecast period. CAGRs derived from procedure volume elasticity to screening protocol expansion and regulatory pathway acceleration assumptions. Industry-specific inputs included PMDA biocompatibility standard evolution and NMPA localization incentive trajectories.
The model holds under stable regulatory certification timelines and silica precursor supply continuity; deviation in PMDA standard revision timing or German-Japanese chemical supplier consolidation would shift replacement cycle and input cost assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Endoscope Detergents and Disinfectants Market
Endoscopy
Global Veterinary Endoscopes Market
Endoscopy
Disposable Bronchoscopes Market
Endoscopy
United States Endoscopy Devices Market
Endoscopy
Endoscopy Procedures Estimates Market
Endoscopy
Italy Endoscopy Devices Market
Endoscopy
South Africa Endoscopy Devices Market
Endoscopy
Endoscopy Equipment Market
Endoscopy
India Endoscopy Devices Market
Endoscopy
Global Endoscopic Clips Market
Endoscopy
Global Colonoscopes Market
Endoscopy
Bronchoscopy Market
Endoscopy
Japan Endoscopy Devices Market
Endoscopy
Germany Endoscopy Devices Market
Endoscopy
Endoscopic Insufflators Market
Endoscopy
Global Endoscopes Market