
 Compression Veterinary Bandages Market | 2026-2036
Compression Veterinary Bandages Market Size, Share, and Industry Trends Forecast 2026-2036
Compression Veterinary Bandages Market Outlook
EU MDR is realigning the cost-of-entry calculus for veterinary bandage suppliers serving European clinics. 3M Company leverages its polymer science platform to sustain certification breadth across human and veterinary product lines. Medline Industries LP anchors North American distribution through direct-to-clinic logistics networks. Paul Hartmann AG competes on wound-care specialization, drawing technology from its human medical portfolio into veterinary formats.
Compression veterinary bandages are textile-based mechanical support devices engineered with specified elasticity gradients, typically 30-40% stretch capacity, to manage edema, stabilize soft-tissue injuries, and protect surgical sites in animals. Cohesive bandages lead product-type volume due to self-adherent properties that eliminate clip dependency, while nylon-polyester blends displace cotton in material selection for superior moisture management and reusability. Veterinary clinics dominate distribution channel value capture, though online retail segments are accelerating as tele-veterinary consultations normalize remote wound-care guidance.
FDA Center for Veterinary Medicine oversees material safety claims for animal health devices in the United States, while ISO 10993 biocompatibility standards shape supplier testing protocols across export markets. REACH chemical restrictions in Europe constrain latex formulation options, pushing manufacturers toward synthetic elastomer substitutes. Stakeholders must monitor how veterinary telehealth reimbursement policies reshape point-of-care versus direct-to-consumer channel economics.
Market Dynamics
The EU Veterinary Medicines Regulation is tightening material traceability requirements, forcing suppliers to reconfigure supply chains and documentation systems for animal health products entering European clinics.
Growth Catalysts
- Equine sports medicine expansion:University veterinary hospitals in Germany's Baden-Württemberg region are scaling procurement of compression wraps for tendon rehabilitation programs.
- Tele-veterinary normalization:Remote wound-care guidance is accelerating direct-to-consumer channel development for cohesive bandage products.
- Synthetic elastomer substitution:REACH chemical restrictions are pushing manufacturers toward advanced polymer formulations that outperform latex in moisture management.
Market Restraints
- Biocompatibility testing burden:ISO 10993 compliance requirements extend certification timelines and raise R&D fixed costs for export-market entry.
- Raw material concentration:Nylon-polyester blend supply chains cluster in Asian textile manufacturing hubs, creating single-source vulnerability.
- Reusable product durability:Cotton displacement by synthetic blends limits price premium capture in cost-sensitive rural veterinary practices.
Strategic Opportunities
- Telehealth reimbursement alignment:Veterinary telehealth policy evolution in North America creates channel economics for remote fitting guidance and subscription replenishment models.
- Small-animal segment penetration:Compression wrap applications in companion animal post-surgical care remain underdeveloped relative to equine adoption.
- Cohesive-self-adherent convergence:Integration of elastic compression with antimicrobial textile coatings opens premium positioning in surgical site protection.
Industry Challenges
- Veterinary textile engineering talent:Cross-functional expertise spanning polymer science and animal anatomy remains scarce in manufacturing centers.
- Dual human-veterinary certification:Suppliers serving both medical verticals face divergent FDA Center for Veterinary Medicine and FDA Center for Devices and Radiological Health documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compression Veterinary Bandages Market |
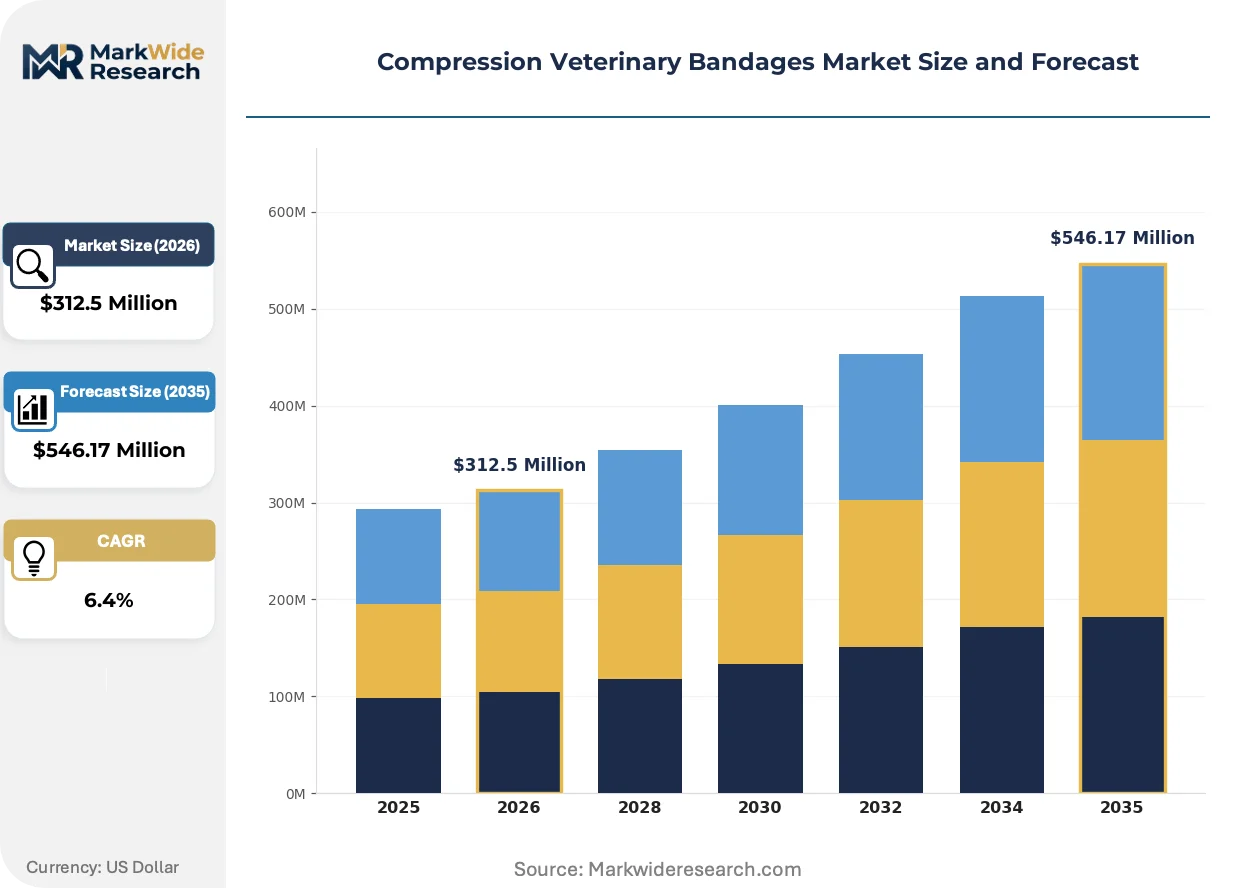
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elastic Bandages, Cohesive Bandages, Adhesive Bandages, Compression Wraps Material: Cotton, Nylon, Polyester, Latex Application: Wound Care, Post-operative Support, Injury Prevention, Training Aids Distribution Channel: Veterinary Clinics, Online Retail, Pharmacies, Pet Specialty Stores |
| Companies Covered | Andover Healthcare Inc., Dynarex Corporation, 3M Company, Essity, Medline Industries LP, Smith & Nephew plc, Robinson Healthcare Ltd., Paul Hartmann AG, Milliken Healthcare Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compression Veterinary Bandages Market Strategic Shifts
Material science advances and regulatory harmonization pressures are compressing product development cycles while elevating performance benchmarks for compression veterinary bandages across clinical and at-home applications.
Antimicrobial silver-ion textile technology is absorbing into nylon-polyester weave structures to deliver sustained pathogen suppression during extended wear periods. Equine rehabilitation centers in Germany and companion animal surgical wards in the United States are piloting these enhanced wraps at accelerated procurement rates. The technology is absorbing margin pressure from commodity cohesive bandages by justifying premium positioning through measurable infection-rate reduction.
REACH chemical restrictions are eliminating natural latex formulation options for European market entry, compelling suppliers to validate synthetic elastomer alternatives through extended biocompatibility testing protocols. Manufacturers with existing polymer science platforms leverage this transition to consolidate certification breadth across human and veterinary product lines. Small-mid suppliers lacking in-house materials laboratories face exclusion from EU procurement channels as documentation requirements intensify.
Direct-to-clinic logistics networks are compressing traditional distributor markups as tele-veterinary platforms normalize remote diagnostic workflows. Veterinary practices in suburban North American markets are consolidating purchasing through integrated supply platforms that bundle compression products with pharmaceutical orders. This channel compression is most visible in multi-site corporate veterinary groups negotiating volume-tier pricing directly with manufacturers.
Compression Veterinary Bandages Market Segmentation
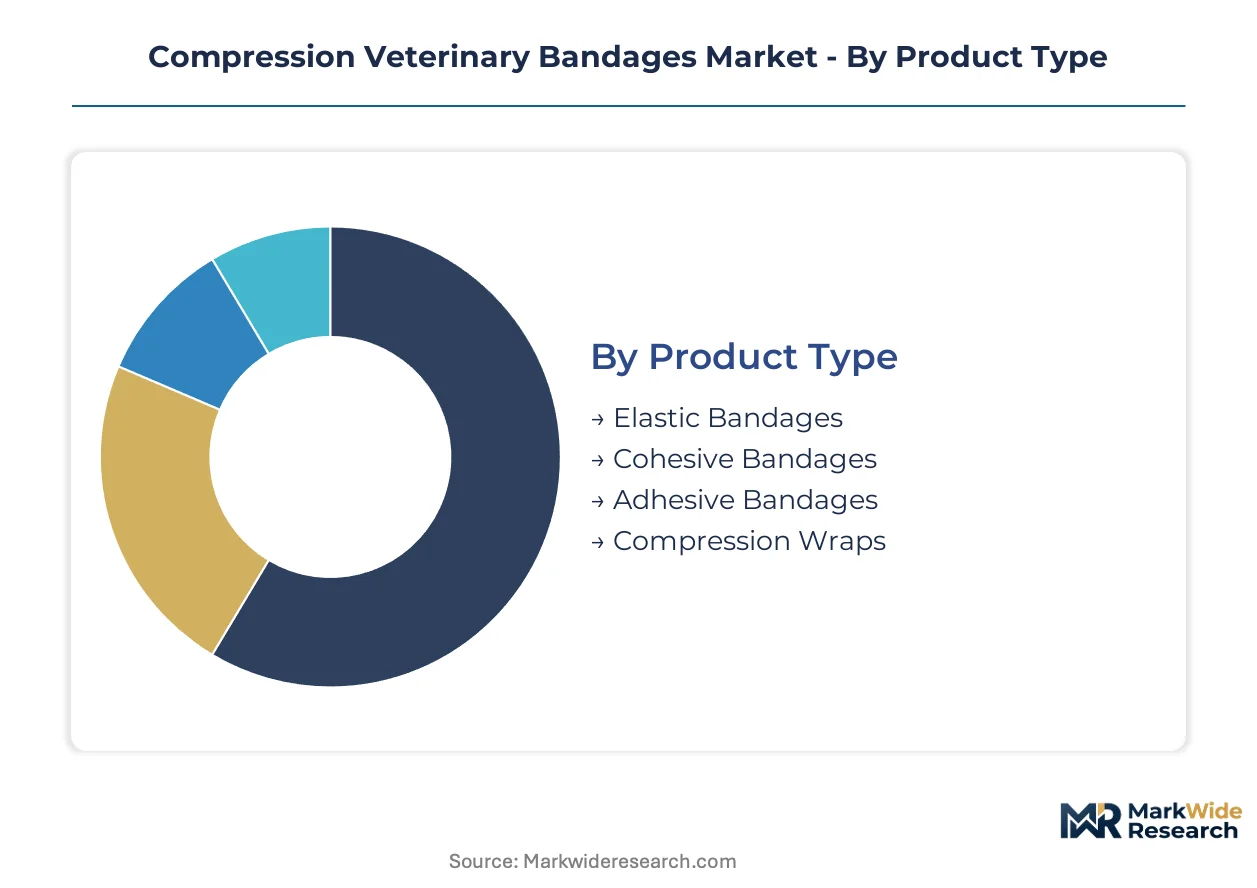
Compression veterinary bandage manufacturers configure production lines around elasticity specifications and adhesion chemistry that vary sharply by animal size and clinical setting. Segmentation discipline separates commodity cohesive wraps from premium antimicrobial-coated systems commanding divergent margin structures.
Product Type:
Supply concentration in polymer-coating capacity favors manufacturers with integrated elastomer compounding operations.
- Cohesive Bandages:Self-adherent wraps utilizing synthetic rubber-latex blends that bond to themselves without clips or fasteners. Equine rehabilitation centers in Germany's Baden-Württemberg region are scaling procurement for tendon stabilization protocols, displacing traditional elastic systems that require additional securing hardware.
- Elastic Bandages:Woven cotton-synthetic blends with specified stretch capacity, typically 30-40% elongation, secured with metal clips or hook-and-loop fasteners. Rural veterinary practices in cost-sensitive markets favor these systems for reusability despite inferior moisture management versus cohesive alternatives.
- Adhesive Bandages:Pressure-sensitive adhesive-coated strips for minor wound coverage in companion animals.
- Compression Wraps:Multi-layer systems engineered for edema management and post-surgical stabilization in large-animal applications.
Cohesive bandages absorb the bulk of installed capacity; compression wraps are expanding most quickly through university veterinary hospital procurement programs.
Material:
REACH chemical restrictions in Europe are eliminating natural latex formulation options, forcing material substitution decisions across all production tiers.
- Nylon:Petroleum-derived polyamide fibers woven into high-tensile bandage substrates with superior abrasion resistance and shape retention through repeated laundering. Synthetic elastomer substitution programs are validating nylon-polyester blends as REACH-compliant alternatives to latex-bound cohesive systems.
- Polyester:Thermoplastic polymer fibers delivering hydrophobic moisture-wicking performance critical for extended-wear applications in equine sports medicine. Asian textile manufacturing hubs concentrate supply of medical-grade polyester filament, creating single-source vulnerability for European and North American converters.
- Cotton:Natural cellulose fiber bandages with biodegradable properties but inferior durability and moisture retention.
- Latex:Natural rubber elastomer facing phased elimination from EU market entry due to ECHA registration requirements and allergen liability exposure.
Nylon-polyester blends absorb the bulk of installed capacity; synthetic elastomer substitutes are climbing the fastest as REACH compliance deadlines approach.
Application:
Veterinary telehealth reimbursement policy evolution is redistributing application demand between clinic-administered and owner-applied protocols.
- Wound Care:Primary dressing and secondary securing applications spanning traumatic injury management and chronic lesion treatment. Antimicrobial silver-ion textile integration is penetrating this segment through measurable infection-rate reduction claims in companion animal surgical wards.
- Post-operative Support:Stabilization wraps protecting surgical sites from contamination and mechanical stress during healing intervals. University veterinary hospitals are piloting enhanced compression systems with sustained-release antimicrobial coatings at accelerated procurement rates.
- Injury Prevention:Prophylactic wrapping protocols for athletic and working animals in competitive and commercial settings.
- Training Aids:Compression systems supporting conditioning regimens and load management in equine and canine performance programs.
Wound care absorbs the bulk of installed capacity; post-operative support is gaining share fastest through surgical site protection premium positioning.
Distribution Channel:
Direct-to-clinic logistics networks are compressing traditional distributor markups as integrated supply platforms consolidate purchasing power.
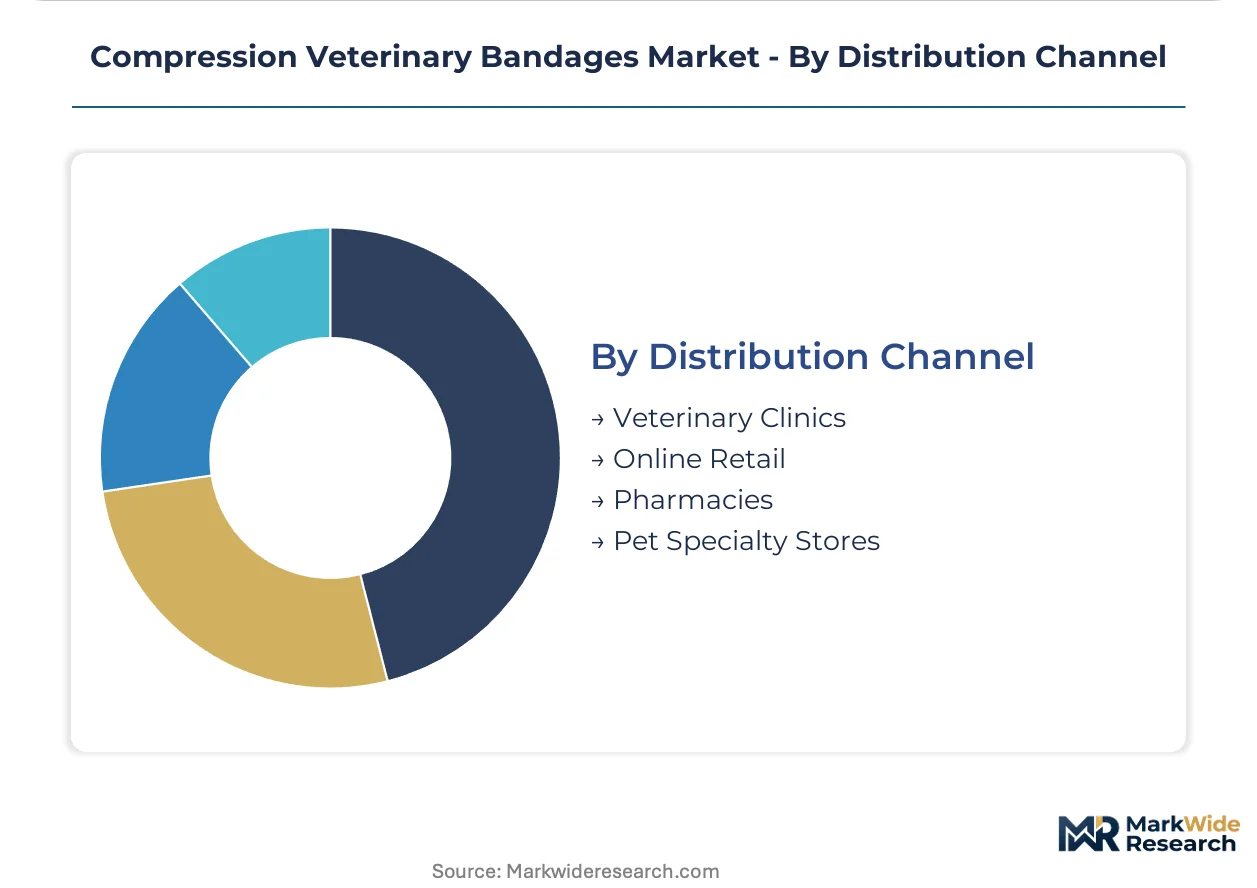
- Veterinary Clinics:Primary point-of-care channel where clinical staff apply and fit compression systems during examination or post-surgical discharge. Multi-site corporate veterinary groups in suburban North American markets are negotiating volume-tier pricing directly with manufacturers, bypassing traditional distribution.
- Online Retail:Direct-to-consumer channel accelerated by tele-veterinary platforms normalizing remote wound-care guidance and replenishment subscriptions. Remote diagnostic workflows are shifting cohesive bandage procurement toward e-commerce fulfillment with veterinary telehealth platform integration.
- Pharmacies:Secondary retail channel for standard elastic and adhesive bandage products in companion animal markets.
- Pet Specialty Stores:Mass-market channel for basic first-aid and training wrap products with limited clinical specification.
Veterinary clinics absorb the bulk of installed capacity; online retail is expanding most quickly through tele-veterinary consultation normalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for compression veterinary bandages clusters in Germany's equine rehabilitation corridors and suburban North American veterinary networks, with regulatory divergence between REACH-compliant European formulations and FDA-oversight US material standards.
Germany
Equine sports medicine programs at university veterinary hospitals in Baden-Württemberg are scaling procurement of tendon-rehabilitation wraps. ECHA registration requirements under REACH are eliminating natural latex formulations from supply chains. Stuttgart-area specialized clinics concentrate demand for cohesive bandage systems with synthetic elastomer binders.
United States
Multi-site corporate veterinary groups in suburban markets are consolidating purchasing through direct-to-clinic logistics platforms. FDA Center for Veterinary Medicine oversees material safety claims for animal health devices entering clinical channels. Tele-veterinary reimbursement policy evolution in California and Texas is accelerating remote wound-care guidance adoption.
United Kingdom
Companion animal surgical wards are piloting antimicrobial silver-ion textile integration at measurable infection-rate reduction claims. The Veterinary Medicines Directorate aligns with EU MDR traceability standards for cross-border supply. London and Southeast England veterinary networks concentrate premium wrap procurement for post-operative support.
France
ANSM pharmaceutical device regulations constrain latex-allergen liability exposure in clinical bandage selection. Île-de-France equine training centers are adopting compression wraps for athletic load management protocols. Lyon-area veterinary distributors are consolidating procurement of REACH-compliant synthetic alternatives.
Japan
PMDA biocompatibility standards shape import testing protocols for nylon-polyester blend substrates. METI industrial policy supports domestic textile converters serving veterinary device assemblers. Osaka-Kansai manufacturing clusters concentrate medical-grade filament processing for regional bandage production.
Compression Veterinary Bandages Market Competitive Environment
German producers anchor one tier of wound-care specialization; North American diversified health product manufacturers hold another. The vendor base splits between polymer science platform operators and distribution-anchored logistics specialists. Three archetypes dominate: integrated material science conglomerates, wound-care pure-plays, and direct-to-clinic supply platform operators. Capacity consolidation and certification breadth expansion represent the dominant competitive vectors.
Among diversified health product manufacturers, 3M Company and Medline Industries LP occupy positions reflecting polymer science platform scale and direct-to-clinic logistics integration respectively. Paul Hartmann AG exemplifies the wound-care specialization archetype, drawing technology migration from human medical formats. These three anchors illustrate how certification breadth across human and veterinary lines separates sustainable suppliers from REACH-excluded competitors.
| Leading Market Players |
|---|
| Andover Healthcare Inc. |
| Dynarex Corporation |
| 3M Company |
| Essity |
| Medline Industries LP |
| Smith & Nephew plc |
| Robinson Healthcare Ltd. |
| Paul Hartmann AG |
| Milliken Healthcare Products |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between REACH-compliant synthetic elastomer systems and commodity latex-bound alternatives drives parallel pricing and sourcing stratification across European and export-market supply chains. Premium antimicrobial-coated wraps command substantial markups through university veterinary hospital procurement channels in Germany, while cost-sensitive rural practices in the United States absorb economy-tier elastic bandages with inferior moisture management profiles.
Pricing Analysis
Volume capture concentrates in commodity cohesive bandages where per-unit margins compress under Asian textile converter competition, while margin expansion accrues to antimicrobial silver-ion coated systems piloted in companion animal surgical wards. Price differentiation rests on ISO 10993 biocompatibility certification tier and synthetic elastomer formulation grade. Pricing pressure intensifies in standard elastic segments as cotton displacement accelerates and reusability expectations limit replacement frequency. Corporate veterinary groups negotiating direct manufacturer contracts exhibit lowest price sensitivity; independent rural practices demonstrate highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with medical-grade polyester filament production clustered in Asian textile manufacturing hubs, particularly China and Taiwan, with secondary concentration in South Korean synthetic fiber processing. Raw material dependencies span petroleum-derived polyamide substrates, silver-ion antimicrobial coatings, and synthetic rubber elastomer binders validated for REACH compliance. Supply chain risk centers on regulatory restriction exposure as ECHA registration deadlines eliminate natural latex pathways. Distribution runs through direct-to-clinic logistics networks that bypass traditional veterinary distributor markups, accelerated by tele-veterinary platform integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where polymer science platform control and certification breadth determine sustainable participation. Incumbents and challengers alike must secure captive supply of REACH-compliant elastomer formulations or face exclusion from EU procurement channels.
For Market Incumbents: Anticipate synthetic elastomer substitution timelines by securing backward integration into polymer compounding capacity or long-term offtake agreements with certified suppliers. Defensive positioning requires simultaneous FDA Center for Veterinary Medicine and EU MDR documentation breadth to serve dual human-veterinary product lines. Channel consolidation among multi-site corporate veterinary groups threatens distributor-dependent revenue streams. For New Entrants and Emerging Players: Enter via antimicrobial textile coating specialization targeting underpenetrated companion animal post-surgical segments, where infection-rate reduction claims justify premium positioning against commodity cohesive alternatives. White-space concentration appears in tele-veterinary-integrated replenishment subscriptions for remote wound-care guidance protocols. Go-to-market execution should anchor in direct e-commerce fulfillment partnerships with veterinary telehealth platforms rather than traditional clinic distributor networks. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier wound-care specialists possessing polymer science laboratory infrastructure and existing ISO 10993 validation frameworks, given REACH compliance deadline acceleration and synthetic elastomer substitution capex requirements. Long-term viability favors suppliers with certification breadth spanning human medical and veterinary device pathways. The signal to watch is university veterinary hospital procurement pilot conversion rates for antimicrobial-coated compression wraps.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Elastomer Platform Development | REACH compliance deadlines in Europe eliminate natural latex pathways, forcing validated substitution programs. |
| Antimicrobial Silver-Ion Textile Integration | Companion animal surgical wards in the United Kingdom pilot infection-rate reduction claims at premium pricing. |
| Direct-to-Clinic Logistics Network Expansion | Corporate veterinary groups in suburban North American markets negotiate volume-tier manufacturer contracts. |
| Tele-Veterinary Platform Partnership | Remote wound-care guidance normalizes subscription replenishment models for cohesive bandage products. |
| Dual Human-Veterinary Certification Investment | FDA Center for Veterinary Medicine and EU MDR documentation breadth separates sustainable from excluded suppliers. |
Study Parameters
Document review covered FDA Center for Veterinary Medicine guidance documents, ECHA REACH registration databases, ISO 10993 biocompatibility standards, and university veterinary hospital procurement records, complemented by interviews with veterinary supply chain managers, equine rehabilitation clinicians, biomedical textile engineers, and GPO contracts administrators. Secondary validation drew from customs trade data, SEC filings of diversified health product manufacturers, and veterinary telehealth platform disclosure materials. Bottom-up segment sizing triangulated against top-down market construction across product type, material composition, application, and distribution channel dimensions.
Cross-referencing historical procurement velocity against expert panel input shaped the analytical framework across the projection horizon. Segmentation modeling captured product type elasticity specifications, material substitution trajectories, application setting clinical requirements, and channel economics evolution. CAGRs derived from installed capacity expansion rates, university hospital pilot program conversion timelines, and tele-veterinary reimbursement policy trajectory assumptions. Industry-specific forecast inputs incorporated REACH compliance deadline acceleration curves and synthetic elastomer validation protocol durations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under veterinary telehealth reimbursement policy reversal or ECHA registration deadline extension scenarios. Forecasts reflect documented assumptions regarding material substitution timelines and channel consolidation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Animal Antibiotics Market
Veterinary
North America Veterinary Healthcare Market
Veterinary
Global Canine Atopic Dermatitis Market
Veterinary
Veterinary Scales Market
Veterinary
Veterinary Vaccines Market
Veterinary
Veterinary Ultrasound Market
Veterinary
Homeopathic Veterinary Medicines Market
Veterinary
Canine Arthritis Market
Veterinary
Spain Veterinary Healthcare Market
Veterinary
Veterinary Consumables Market
Veterinary
Veterinary Hospitals Market
Veterinary
Animal Drug Compounding Market
Veterinary
Orthopedic Dog Bed Market
Veterinary
Veterinary Thermography Market
Veterinary
Global Porcine Vaccine Market
Veterinary
Asia-Pacific Veterinary Vaccine Market