
 Feline Atopic Dermatitis Treatment Market | 2026-2036
Feline Atopic Dermatitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Feline Atopic Dermatitis Treatment Market Foresight
Aftermarket service revenue from chronic disease management protocols is tilting toward biologic maintenance therapies over episodic corticosteroid rescue. Zoetis Inc. dominates the injectable biologic segment with its cytokine-targeting platform for feline allergic disease. Boehringer Ingelheim International GmbH leverages its European manufacturing footprint to supply veterinary clinics across Germany and France. Elanco Animal Health anchors its position through sustained investment in transdermal delivery research.
Feline atopic dermatitis treatment encompasses pharmaceutical and biological interventions designed to modulate type I and type IV hypersensitivity responses in cats, including monoclonal antibodies targeting interleukin-31 and allergen-specific immunotherapy formulated at standardized concentrations. These therapies aim to interrupt pruritic cascades while minimizing the adverse metabolic effects associated with long-term corticosteroid exposure. Injectable biologics command premium positioning due to extended dosing intervals and superior owner compliance compared to daily oral regimens. Topical formulations retain significant share in home care settings where owner-administered therapy reduces clinic visit burden. Veterinary clinics represent the dominant channel for initial diagnosis and prescription, though home care segments are gaining traction as telemedicine protocols expand.
The FDA Center for Veterinary Medicine evaluates novel biologics under the New Animal Drug Application pathway, while the USDA Center for Veterinary Biologics oversees immunotherapy product licensure, creating a dual-track regulatory environment that shapes development timelines and commercial strategy. The EU Veterinary Medicines Regulation and EMA Committee for Medicinal Products for Veterinary Use establish centralized marketing authorization requirements that manufacturers must navigate for European market access. Stakeholders must monitor evolving pharmacovigilance obligations and the potential for conditional approval pathways to accelerate novel mechanism therapies.
Market Dynamics
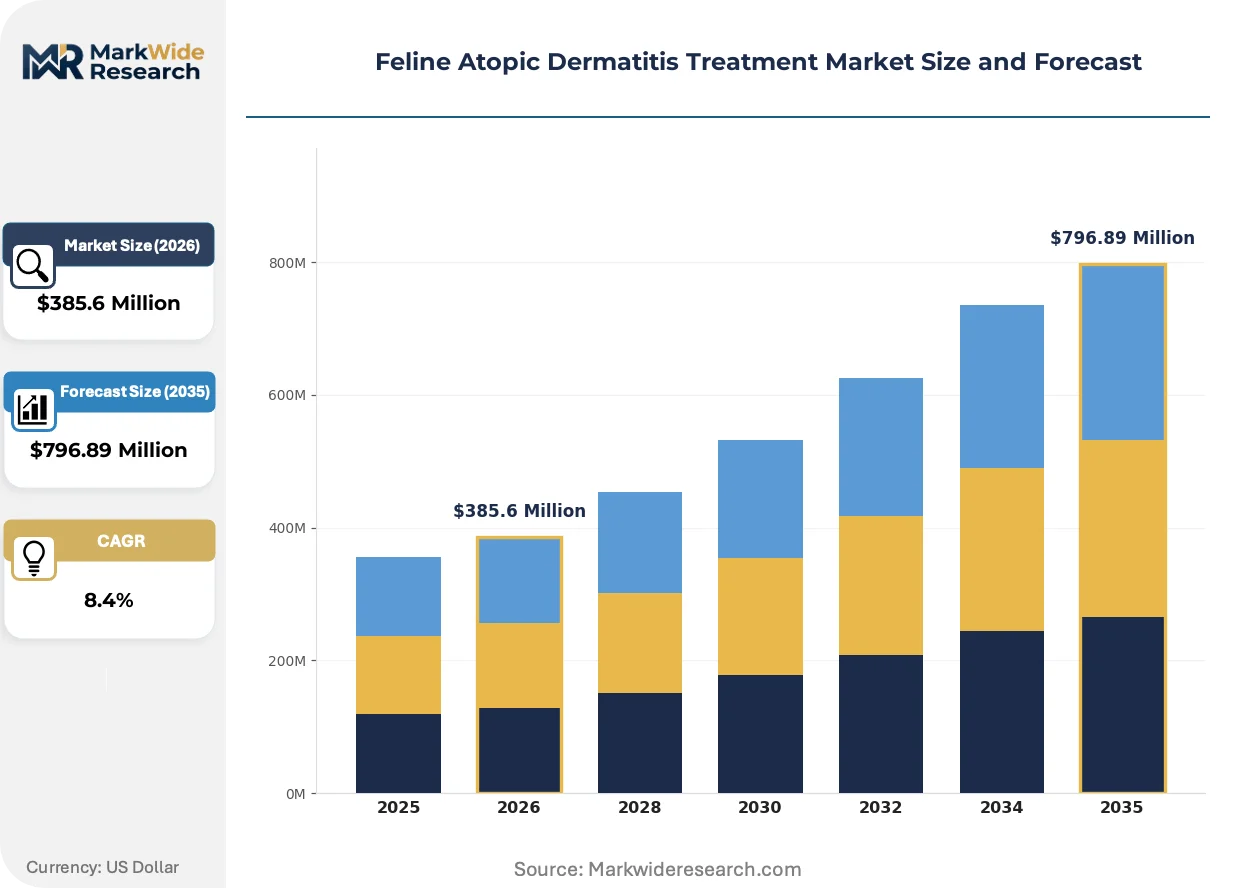
The transition from episodic corticosteroid rescue toward biologic maintenance protocols is restructuring treatment economics and clinic revenue models across veterinary dermatology. Injectable cytokine-targeting therapies with extended dosing intervals are capturing owner preference while reshaping pharmaceutical development priorities.
Growth Catalysts
- Biologics pathway acceleration:The FDA Center for Veterinary Medicine has streamlined review timelines for monoclonal antibody submissions targeting interleukin pathways, compressing development-to-market cycles for novel feline therapeutics.
- Telemedicine protocol expansion:Veterinary clinics across Germany and France are deploying remote monitoring platforms that enable home-based disease management, extending specialist reach beyond metropolitan referral hospitals.
- Owner compliance premium:Injectable formulations with quarterly administration schedules command preference over daily oral regimens, driving clinic adoption of long-acting biologic platforms.
Market Restraints
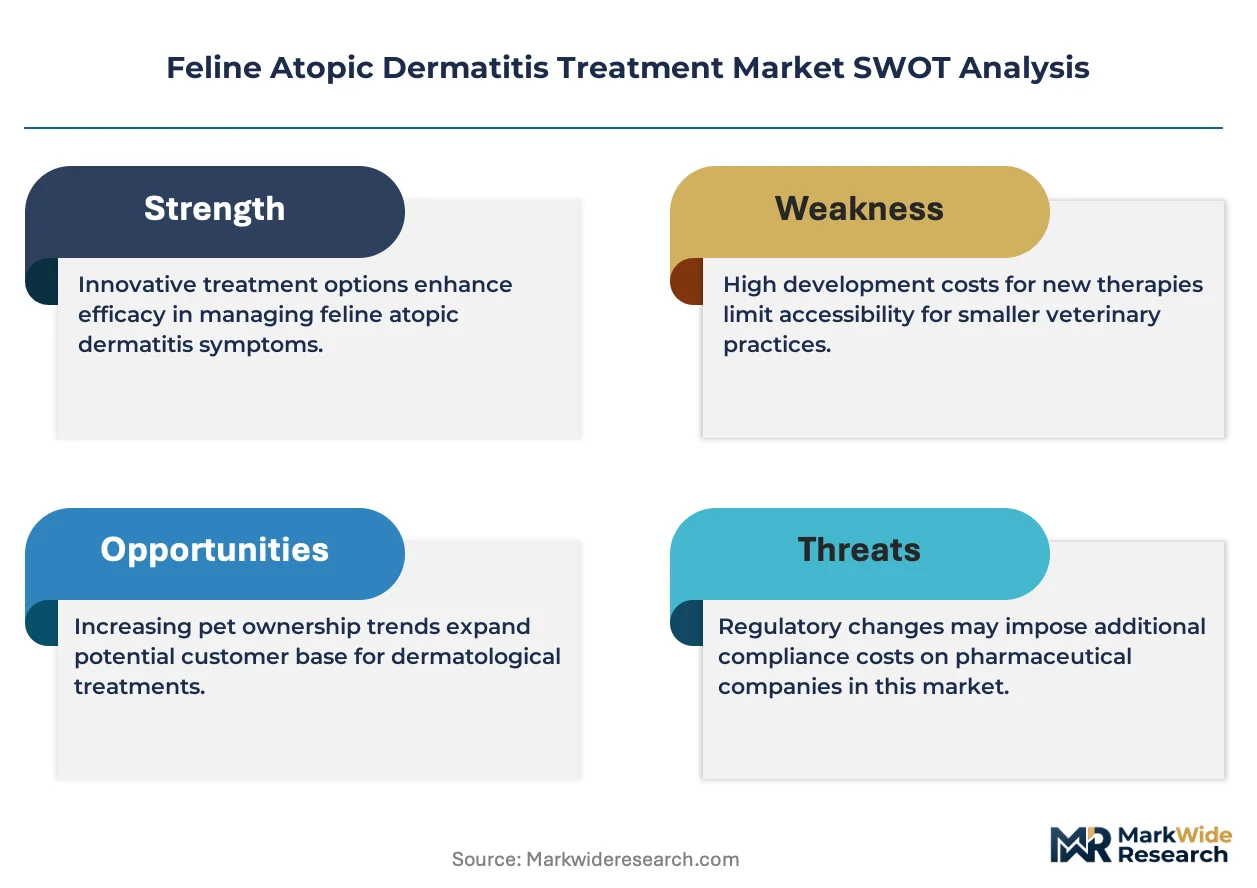
- Cold chain infrastructure gaps:Biologic stability requirements strain veterinary clinic storage capacity in rural United States markets, limiting penetration beyond specialty referral networks.
- Regulatory bifurcation:The dual-track FDA-USDA oversight environment creates approval pathway uncertainty, with the Center for Veterinary Biologics and Center for Veterinary Medicine maintaining divergent immunotherapy licensure standards.
- Substitution persistence:Generic corticosteroid formulations retain significant share in price-sensitive owner segments, compressing biologic uptake velocity in non-specialty practice settings.
Strategic Opportunities
- Transdermal delivery advancement:Research programs targeting passive diffusion through feline skin barriers could unlock home-administered alternatives to injectable biologics, expanding addressable owner segments.
- EU harmonization tailwind:The EU Veterinary Medicines Regulation centralizes marketing authorization across member states, reducing redundant filing burdens for manufacturers seeking European market entry.
- Telehealth channel maturation:Virtual consultation platforms are creating direct-to-owner prescription pathways that bypass traditional clinic gatekeeping in United States metropolitan markets.
Industry Challenges
- Veterinary dermatology specialization scarcity:Board-certified specialists concentrate in coastal United States academic medical centers, creating diagnostic bottleneck constraints for biologic-eligible patient identification.
- Pharmacovigilance system integration:Post-market adverse event reporting requirements under evolving FDA and EMA frameworks demand data infrastructure investments that strain mid-sized manufacturer resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feline Atopic Dermatitis Treatment Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Treatments, Antihistamines, Immunotherapy, Corticosteroids Administration Route: Oral, Topical, Injectable, Transdermal End User: Veterinary Clinics, Animal Hospitals, Home Care, Research Institutions Formulation: Liquid, Spray, Ointment, Tablet |
| Companies Covered | Boehringer Ingelheim International GmbH, Bausch Health Companies Inc., Bayer AG, Pfizer Inc., Novartis AG, Eli Lilly and Company, Sanofi, Zoetis Inc., Elanco Animal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feline Atopic Dermatitis Treatment Market Shifts & Advancements
Biologic platform refinement and delivery mechanism innovation are converging to displace legacy corticosteroid protocols, while regulatory adaptation and owner behavior shifts accelerate protocol transformation across veterinary practice settings.
Monoclonal antibody engineering is hybridizing recombinant cytokine receptor technology with Fc-fusion protein architectures to extend serum half-life in feline patients. Specialty referral hospitals in the United States are adopting these platforms as first-line therapy for moderate-to-severe atopic cases. The structural consequence is compression of corticosteroid rescue revenue while establishing recurring biologic maintenance revenue streams.
The EU Veterinary Medicines Regulation implementation is harmonizing pharmacovigilance obligations across member states, creating centralized adverse event databases that manufacturers must navigate for market access. This regulatory consolidation is elevating compliance infrastructure requirements for biologic developers. German and French veterinary clinics are responding by consolidating purchasing through distributor networks with established regulatory documentation capabilities.
Subscription-based chronic disease management programs are displacing episodic visit billing in United States specialty practices, bundling diagnostic monitoring with biologic therapy administration. Telemedicine platforms are capturing follow-up consultations that previously required physical clinic presence. This shift is most visible in California and New York metropolitan corridors where owner time constraints drive preference for reduced visit burden.
Feline Atopic Dermatitis Treatment Market Segmentation
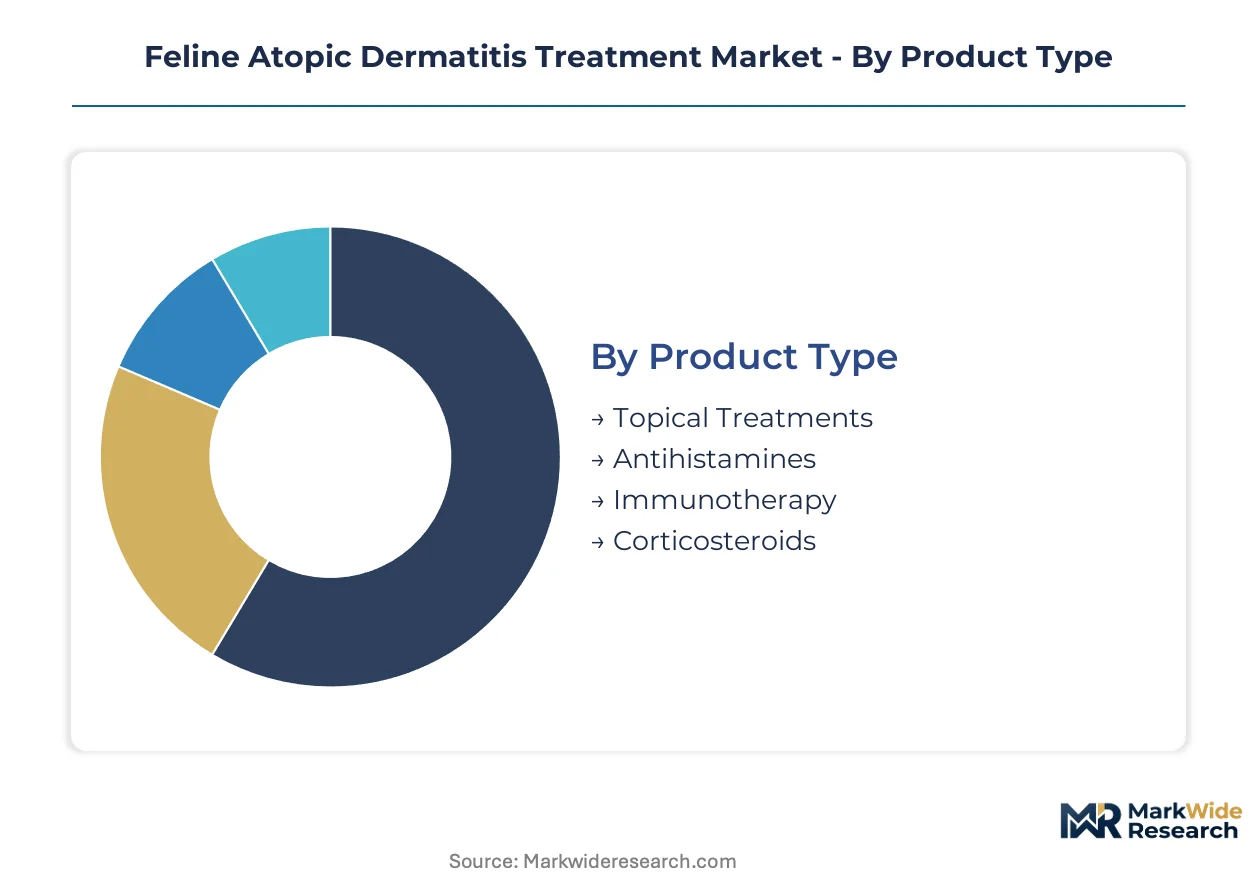
Treatment modality selection in feline atopic dermatitis hinges on disease severity, owner compliance capacity, and clinic infrastructure. Segmentation reveals how pharmaceutical innovation is redistributing value across administration routes and care settings.
Product Type:
The use-case spectrum spans acute flare management through chronic immune modulation, with each product class occupying distinct positions in the therapeutic algorithm.
- Topical Treatments:Formulations incorporating ceramide complexes and essential fatty acids restore epidermal barrier function while delivering localized anti-inflammatory action. Demand concentrates in home care settings across United States suburban markets, where owners prefer non-systemic intervention for mild, localized presentations.
- Immunotherapy:Allergen-specific immunotherapy employs standardized allergen extracts administered via subcutaneous injection or sublingual drops to induce immune tolerance. Specialty veterinary dermatology practices in Germany and France drive adoption, supported by EU regulatory harmonization that streamlines extract formulation standardization.
- Antihistamines:Second-generation H1 receptor antagonists with reduced sedative profiles serve as adjunctive therapy in multi-modal protocols.
- Corticosteroids:Synthetic glucocorticoids remain the rescue therapy mainstay in price-sensitive owner segments and rural clinic networks lacking cold chain infrastructure.
Established volume favors corticosteroids; emerging adoption favors immunotherapy.
Administration Route:
Cost tier differentiation separates premium biologic platforms from commodity oral formulations, with delivery mechanism directly shaping treatment economics and owner retention.
- Injectable:Monoclonal antibody platforms targeting interleukin-31 and other cytokine pathways achieve extended dosing intervals through Fc-fusion protein engineering. United States specialty referral hospitals anchor demand, where quarterly administration schedules command premium pricing and superior compliance metrics.
- Transdermal:Research-stage passive diffusion systems aim to bypass feline hepatic first-pass metabolism while enabling owner-administered delivery. Development programs concentrate in California and Massachusetts biotechnology corridors, attracted by proximity to veterinary academic medical centers.
- Oral:Tablet and liquid formulations dominate general practice prescribing for their pharmacy accessibility and owner familiarity.
- Topical:Direct skin application serves localized disease presentations and maintenance protocols between systemic dosing cycles.
Injectable platforms capture margin expansion; transdermal research programs capture pipeline investment priority.
End User:
Customer type stratification reflects the divergence between episodic general practice care and subscription-based chronic disease management.
- Veterinary Clinics:Primary care and specialty practices generate initial diagnoses and maintain prescription authority over biologic therapy selection. United States metropolitan corridor clinics are consolidating purchasing through distributor networks with established FDA documentation capabilities.
- Home Care:Telemedicine-enabled remote monitoring platforms extend specialist protocol adherence beyond physical clinic walls. German veterinary groups are deploying these systems to serve dispersed rural owner populations.
- Animal Hospitals:Academic medical centers and multi-specialty referral institutions concentrate advanced diagnostic capacity and immunotherapy formulation services.
- Research Institutions:Veterinary schools and contract research organizations support clinical trial execution for novel mechanism therapies.
Veterinary clinics retain prescription gatekeeping; home care segments are climbing the fastest.
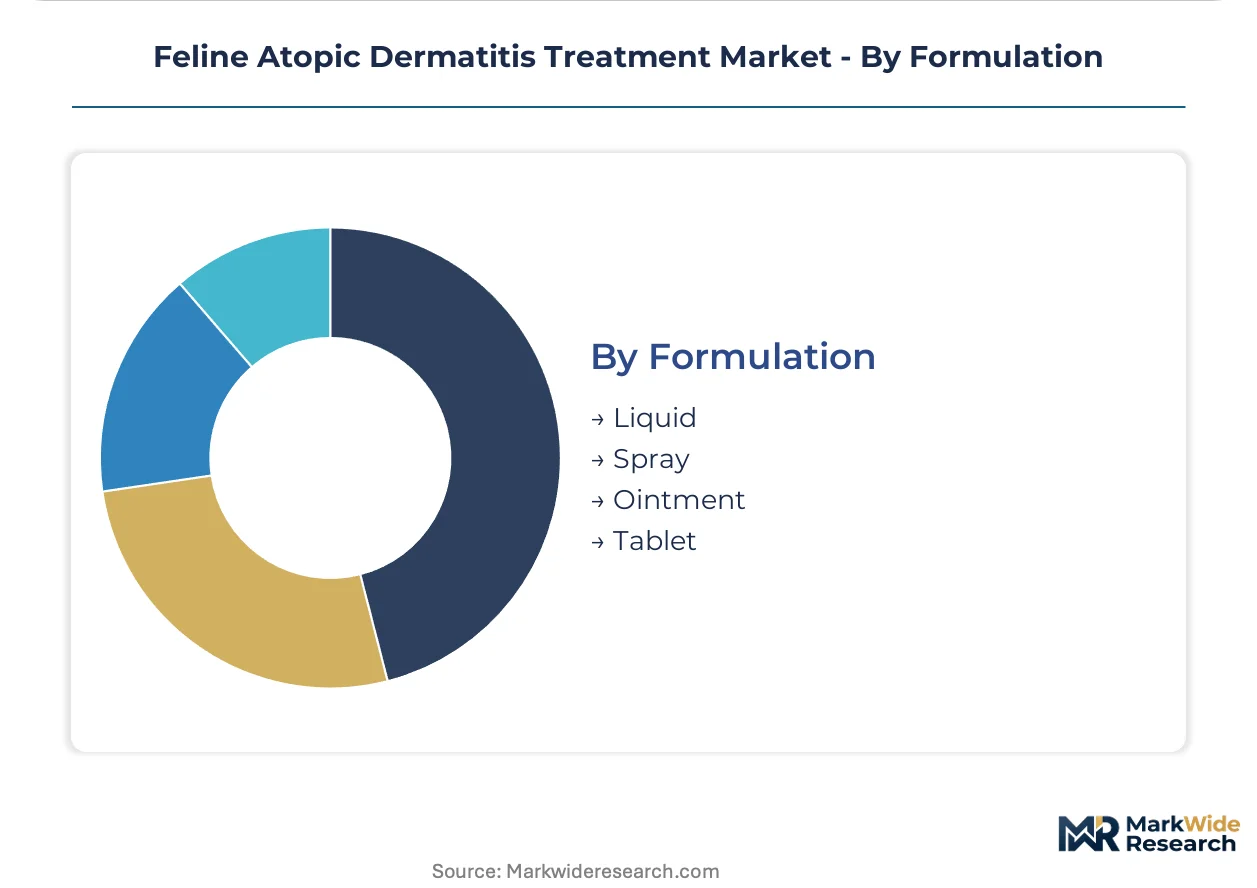
Formulation:
Supply concentration in liquid manufacturing favors large-scale pharmaceutical operations, while spray and ointment production accommodates mid-tier compounders.
- Liquid:Oral suspensions and injectable solutions enable precise dose titration across feline weight ranges. Manufacturing concentrates in FDA-registered facilities with validated aseptic processing lines.
- Tablet:Compressed dosage forms support mass-market distribution through veterinary pharmacy channels.
- Spray:Metered-dose topical delivery suits fractile patients resistant to manual application.
- Ointment:Semi-solid bases provide prolonged skin contact for localized anti-inflammatory effect.
Liquid formulations dominate biologic production; spray formats gain share in behaviorally challenging patient populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Owner willingness to pay premium pricing for biologic therapies varies sharply across veterinary markets, with United States metropolitan corridors showing highest elasticity while Southern European and Latin American markets retain corticosteroid dependence due to reimbursement gaps.
United States
Specialty referral hospitals in California and New York anchor biologic adoption, where quarterly injectable protocols command premium pricing. The FDA Center for Veterinary Medicine maintains dual-track oversight with the USDA Center for Veterinary Biologics, creating pathway complexity for immunotherapy developers. Massachusetts biotechnology clusters host monoclonal antibody engineering programs targeting extended feline serum half-life.
Germany
Veterinary dermatology practices in Bavaria and North Rhine-Westphalia drive allergen-specific immunotherapy volume through standardized extract protocols. The EU Veterinary Medicines Regulation harmonizes pharmacovigilance obligations across member states, streamlining manufacturer compliance. Munich-based distributor networks consolidate clinic purchasing with established regulatory documentation capabilities.
France
Telemedicine-enabled remote monitoring platforms extend specialist reach to dispersed rural owner populations in Auvergne-Rhône-Alpes and Nouvelle-Aquitaine. ANSM maintains veterinary biologic safety surveillance alongside EMA centralized authorization requirements. Paris metropolitan corridor clinics are adopting subscription-based chronic disease management programs bundling diagnostics with therapy administration.
United Kingdom
London and Southeast England concentrate board-certified veterinary dermatologists, creating diagnostic bottlenecks that limit biologic-eligible patient identification. The Veterinary Medicines Directorate enforces UK-specific marketing authorization requirements post-Brexit, diverging from EU harmonization timelines. Midlands-based veterinary groups are deploying telehealth platforms to bypass specialist concentration constraints.
Japan
Pet insurance penetration in Tokyo and Osaka metropolitan areas supports premium therapy uptake, though feline-specific biologic development lags canine-focused portfolios. PMDA evaluates novel veterinary therapeutics under accelerated review pathways for species-specific unmet needs. Kansai region academic medical centers maintain immunotherapy formulation services for refractory atopic cases.
Feline Atopic Dermatitis Treatment Market Competitive Landscape
Capability concentration sits with biologic platform developers; scale advantage sits with diversified animal health conglomerates. The market structures around three tiers: injectable cytokine-targeting specialists, transdermal delivery researchers, and legacy pharmaceutical manufacturers with corticosteroid portfolios. Strategic moves center on telehealth partnership formation and cold chain infrastructure investment to extend biologic reach beyond specialty referral networks.
Within the diversified animal health tier, Zoetis Inc., Boehringer Ingelheim International GmbH, and Elanco Animal Health exemplify contrasting geographic and capability positioning. Zoetis anchors North American biologic adoption through cytokine-targeting platforms. Boehringer Ingelheim leverages its European manufacturing footprint to supply standardized immunotherapy extracts. Elanco occupies a research-intensive position focused on transdermal delivery alternatives to injectable regimens.
| Leading Market Players |
|---|
| Boehringer Ingelheim International GmbH |
| Bausch Health Companies Inc. |
| Bayer AG |
| Pfizer Inc. |
| Novartis AG |
| Eli Lilly and Company |
| Sanofi |
| Zoetis Inc. |
| Elanco Animal Health |
| Others |
Supply & Pricing Matrix
Cold chain undercapacity across rural United States veterinary markets compresses biologic availability while elevating pricing power for distributors with validated storage infrastructure. This utilization asymmetry rewards consolidated purchasing networks and penalizes fragmented clinic operators unable to meet FDA stability requirements.
Pricing Analysis
Aftermarket service revenue from chronic disease management subscriptions now exceeds episodic visit billing in United States specialty practices. Three-tier pricing structure across premium injectable biologics, standard immunotherapy protocols, and economy corticosteroid rescue serves divergent owner compliance capacities. Pricing pressure stems from generic corticosteroid substitution in price-sensitive segments. Rural general practice owners exhibit highest price sensitivity; metropolitan specialty referral clients show lowest elasticity.
Supply Chain Analysis
Export-control restrictions on recombinant cytokine receptor technology limit cross-border transfer of monoclonal antibody engineering platforms. Manufacturing concentrates in United States FDA-registered facilities, German EMA-compliant sites, and Swissmedic-certified Swiss operations. Production draws from fetal bovine serum, pharmaceutical-grade excipients, and single-use bioreactor systems. Single-source vulnerability concentrates in Fc-fusion protein suppliers. Distribution runs through veterinary distributor networks with cold chain documentation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as telemedicine protocols fragment prescription gatekeeping and enable non-specialist clinic participation in biologic therapy administration. Owner demand for reduced visit burden creates niche entry points for remote-enabled service models.
For Market Incumbents: Insulate subscription revenue by locking clinic networks into exclusive biologic supply agreements with embedded cold chain service. Acquire telemedicine platform capabilities to preempt virtual consultation competitors. Priority lever rests on backward integration into aseptic manufacturing to secure Fc-fusion protein supply against single-source risk.
For New Entrants and Emerging Players: Build out transdermal delivery research programs targeting home-administered alternatives to injectable regimens. White-space concentration sits in United States suburban markets where owners prefer non-clinic administration. Most penetrable segment: general practice clinics lacking specialty referral relationships. Go-to-market angle: partner with telehealth platforms for direct-to-owner prescription pathways.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across monoclonal antibody manufacturing infrastructure. Long-term viability favors platforms with validated pharmacovigilance systems and EU regulatory documentation capabilities. Acquisition target archetype: mid-tier biologic developers with FDA New Animal Drug Application progress and distressed cold chain infrastructure. Signal to watch: conditional approval pathway utilization rates for novel mechanism therapies.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Streamlined FDA Center for Veterinary Medicine review compresses development-to-market cycles for cytokine-targeting platforms. |
| Regulatory Approval Pathway | Dual-track FDA-USDA oversight navigation determines immunotherapy commercialization timelines and market access sequencing. |
| Manufacturing Scale-Up | Aseptic processing line investment extends biologic reach beyond specialty referral networks into general practice settings. |
| Strategic Partnership | Telemedicine platform alliances create direct-to-owner prescription channels that bypass traditional clinic gatekeeping. |
| Pipeline Diversification | Transdermal delivery research programs unlock home-administered alternatives to capture owner compliance premium. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA Center for Veterinary Medicine filings, EMA Committee for Medicinal Products for Veterinary Use submissions, and EU Veterinary Medicines Regulation guidance documents. Primary interviews engaged veterinary dermatology specialists, clinic procurement managers, pharmaceutical regulatory affairs leads, and distributor network operators. Secondary validation drew from pharmacovigilance databases, clinical trial registries, and customs trade data. Bottom-up patient volume estimates triangulated against top-down pharmaceutical revenue analysis.
Forecast inputs span treatment modality adoption curves, administration route preference shifts, and end-user channel evolution across the projection horizon. Segmentation dimensions modeled include product type, administration route, end-user category, and regional regulatory cluster. CAGRs were derived from spline interpolation of historical adoption rates calibrated to specialist interview consensus. Industry-specific inputs incorporate monoclonal antibody dosing interval extension trends and telemedicine protocol penetration assumptions.
Stress conditions across biologic cold chain infrastructure investment, regulatory approval pathway delays, and generic corticosteroid substitution persistence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding owner compliance behavior and clinic specialization concentration. Material shifts in FDA-USDA regulatory harmonization or EU pharmacovigilance obligation evolution would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Companion Animal Vaccines Market
Veterinary
Veterinary CRO and CDMO Market
Veterinary
Global Veterinary Hematology Analyzers Market
Veterinary
Veterinary Vaccines Market
Veterinary
Animal Microchip Implant Market
Veterinary
Spain Veterinary Healthcare Market
Veterinary
Veterinary Vaccine Adjuvants Market
Veterinary
Asia-Pacific Veterinary Vaccine Market
Veterinary
Rabies Veterinary Vaccines Market
Veterinary
Homeopathic Veterinary Medicines Market
Veterinary
Veterinary Anesthesia Drugs Market
Veterinary
Global Porcine Vaccine Market
Veterinary
Global Animal Vaccine Market
Veterinary
France Veterinary Healthcare Market
Veterinary
Veterinary Scales Market
Veterinary
Veterinary Excipients Market