

GCC Functional Food & Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Functional Food & Beverage Market Insights
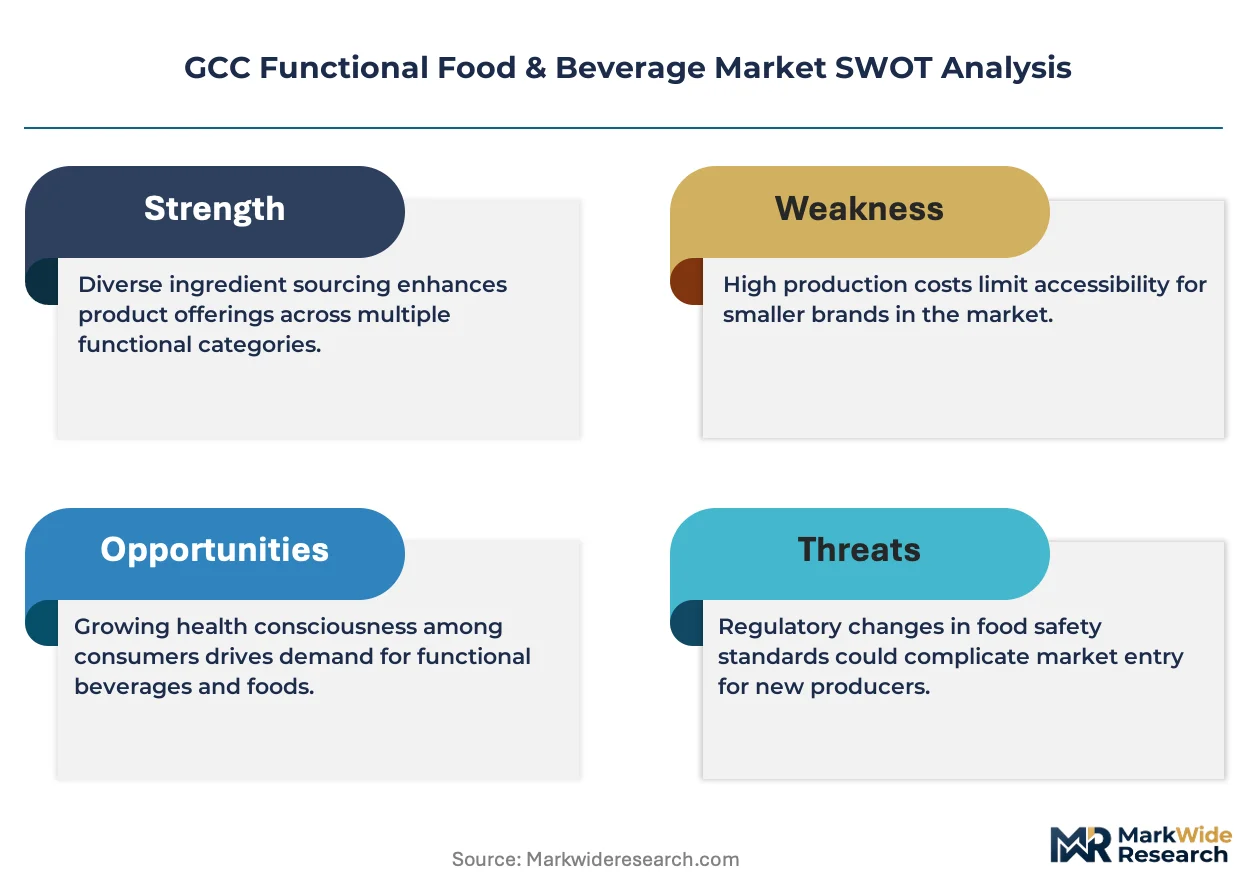
Premium probiotic and high-protein specification tiers is bifurcating the GCC Functional Food & Beverage landscape into mass-market fortification and clinically positioned wellness offerings. Almarai Company leverages its dairy supply chain dominance across Saudi Arabia to anchor refrigerated probiotic distribution. Agthia Group competes through bottled functional water and vitamin-fortified juice specialization in the UAE. Nestlé Middle East FZE sustains R&D intensity for pediatric and elderly nutrition formats tailored to Gulf dietary patterns.
GCC functional food and beverage encompasses edible and drinkable products engineered with bioactive compounds, live microbial cultures, or micronutrient fortification at specified dosage thresholds to deliver physiological benefits beyond basic nutrition. Manufacturing employs cold-chain stabilization for probiotic viability and microencapsulation for heat-sensitive vitamin retention in ambient distribution climates. Probiotics and fortified beverages command the largest revenue pools given established consumer familiarity and pharmacy channel penetration, while protein supplements and prebiotics represent the fastest-expanding segments among fitness enthusiasts and digestive-health seekers. Nutritional bars occupy a narrower margin position due to import dependency and limited local production scale.
Saudi Food and Drug Authority labeling mandates and UAE Ministry of Economy halal-certification requirements shape product formulation standards and cross-border market access protocols across the Gulf. Emirates Authority for Standardization and Metrology nutrient-content thresholds for "functional" claims force reformulation of borderline products and elevate compliance costs for new entrants. Stakeholders must monitor evolving Gulf Cooperation Council harmonization talks on health-claim substantiation, as unified standards would reshape competitive barriers and sourcing strategies across Saudi Arabia, the UAE, and Qatar.
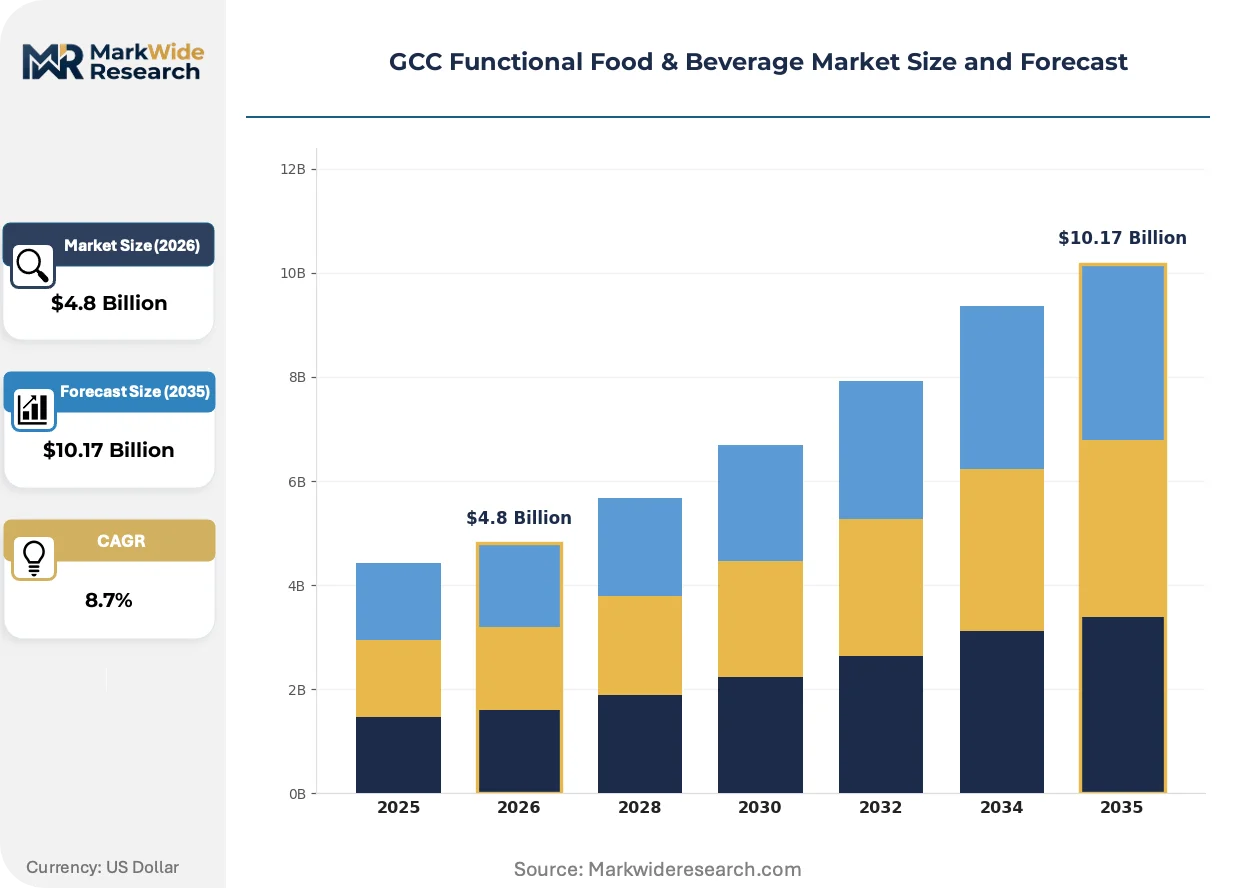
Market Dynamics
Saudi Food and Drug Authority tightening of nutrient-content labeling rules is forcing manufacturers toward cleaner formulations and transparent ingredient sourcing across the Gulf supply base.
Growth Catalysts
- Fitness Culture Expansion:Protein supplements gain traction among health-conscious working professionals in Saudi Arabia and the UAE seeking muscle recovery and weight management solutions.
- SFDA Labeling Mandates:Regulatory pressure for clearer nutritional declarations accelerates reformulation investments and elevates product credibility with Gulf consumers.
- Pharmacy Channel Penetration:Probiotics and fortified beverages leverage established distribution through UAE and Saudi pharmacy networks to reach digestive-health seekers.
Market Restraints
- Import Dependency for Nutritional Bars:Limited local production scale elevates landed costs and compresses margin positions for bar-format functional foods.
- Heat-Stabilization Costs:Microencapsulation requirements for vitamin retention in ambient Gulf climates add processing complexity and capital intensity.
- Halal-Certification Friction:UAE Ministry of Economy certification protocols create cross-border documentation burdens and timeline delays for multi-country launches.
Strategic Opportunities
- Pediatric Nutrition White Space:Tailored formats for Gulf dietary patterns in infant and child segments remain underdeveloped relative to adult offerings.
- Prebiotic Segment Expansion:Digestive-health positioning beyond established probiotics targets fitness enthusiasts seeking gut microbiome optimization.
- Refrigerated Distribution Infrastructure:Cold-chain investments in Dubai and Abu Dhabi corridors enable probiotic viability claims previously constrained by logistics gaps.
Industry Challenges
- Reformulation Timeline Compression:SFDA and Emirates Authority for Standardization and Metrology threshold adjustments force rapid product relaunches with limited notice periods.
- Live Culture Viability Management:Probiotic manufacturers face technical complexity maintaining CFU counts through Gulf ambient distribution and retail display conditions.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Functional Food & Beverage Market Trends and Innovations
Manufacturing technology and regulatory transparency requirements are reshaping competitive positioning across probiotic, protein, and fortified beverage segments in the Gulf.
Microencapsulation technology for heat-sensitive vitamin retention is displacing conventional spray-drying methods in ambient-stable functional beverage production. Mid-tier manufacturers in the UAE are adopting this process to meet Emirates Authority for Standardization and Metrology nutrient-content thresholds without refrigerated distribution. The technology is displacing legacy fortification approaches that degraded bioactive potency in Gulf climate conditions.
SFDA tightening of nutrient-content labeling rules is compressing formulation flexibility for borderline functional claims. Manufacturers must now substantiate physiological benefit assertions with documented bioactive dosage thresholds or reclassify as conventional food. Pediatric and elderly nutrition formats face the highest compliance scrutiny given vulnerable-population positioning.
Direct-to-consumer subscription models for protein supplements are fragmenting traditional pharmacy and hypermarket channel dominance. Fitness enthusiasts in Dubai and Abu Dhabi corridors now prioritize personalized delivery schedules and flavor customization over retail immediacy. Saudi Arabia's Riyadh and Jeddah clusters show similar behavioral migration among working professionals with limited store-visit windows.
GCC Functional Food & Beverage Market Segmentation
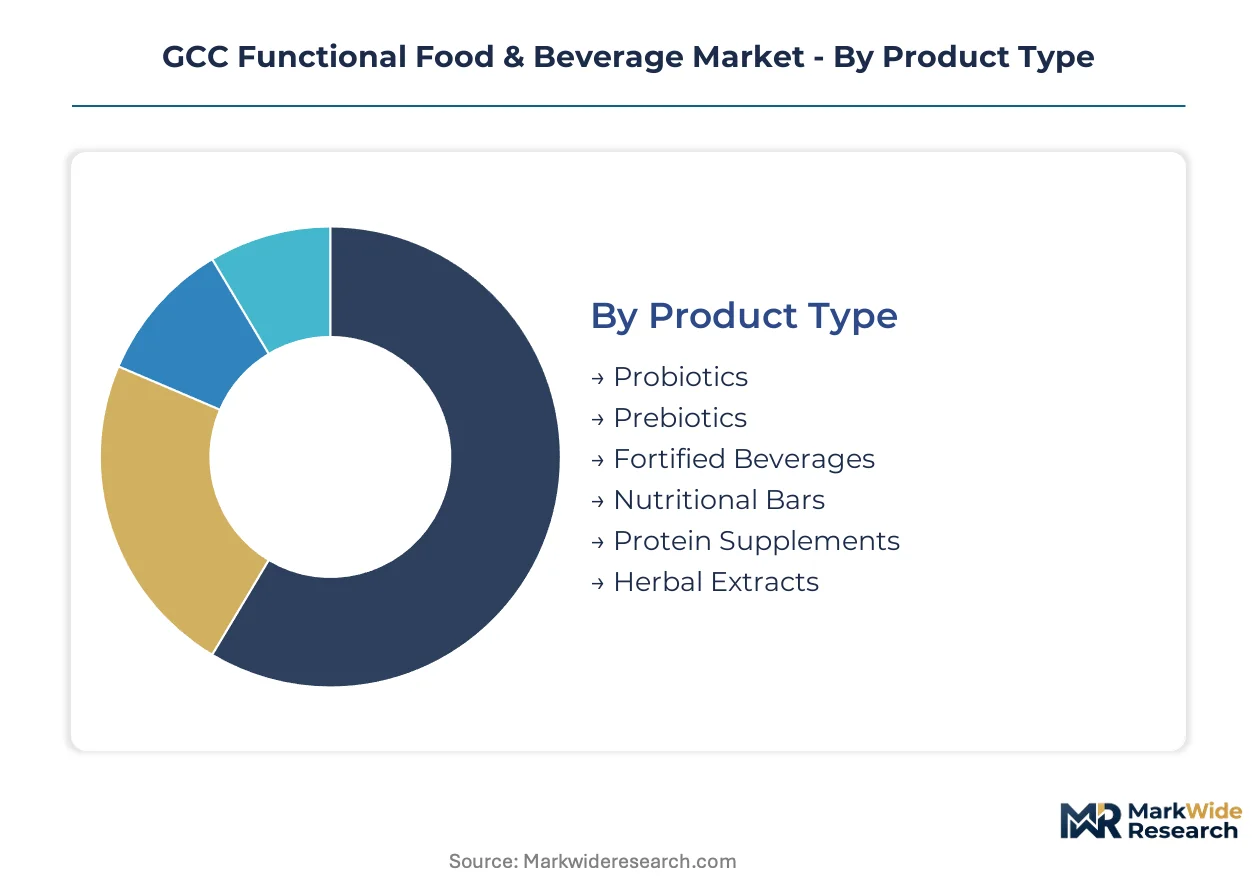
GCC functional food and beverage segmentation reflects divergent regulatory thresholds across Saudi Arabia and the UAE, with product format and distribution channel choices directly shaped by SFDA labeling mandates and halal-certification protocols. Manufacturers must align segment-specific formulations with Emirates Authority for Standardization and Metrology nutrient-content thresholds to maintain functional claims status.
Product Type:
SFDA tightening of nutrient-content labeling rules forces manufacturers to document bioactive dosage thresholds for each format or reclassify as conventional food, elevating compliance investment for borderline functional claims.
- Probiotics:Live microbial cultures delivered through dairy and non-dairy matrices at specified CFU thresholds. Demand concentrates in Dubai and Abu Dhabi corridors where refrigerated distribution infrastructure enables viability claims previously constrained by ambient Gulf logistics. Pharmacy channel penetration anchors volume through established UAE and Saudi networks.
- Fortified Beverages:Vitamin and mineral-enriched drinks employing microencapsulation for heat-sensitive nutrient retention. Saudi Arabia's health-conscious working professionals drive volume for workplace consumption formats, with Emirates Authority for Standardization and Metrology thresholds forcing reformulation of borderline vitamin waters.
- Prebiotics:Non-digestible fiber compounds feeding beneficial gut microbiota. Fitness enthusiasts in Riyadh and Jeddah clusters seek digestive-health positioning beyond established probiotics.
- Nutritional Bars:Compressed nutrient-dense formats facing import dependency and limited local production scale. Landed costs compress margin positions for bar-format functional foods across the Gulf.
- Protein Supplements:Whey, casein, and plant-based isolates targeting muscle recovery. Direct-to-consumer subscription models fragment traditional pharmacy and hypermarket channel dominance among Dubai fitness communities.
- Herbal Extracts:Botanical bioactive compounds positioned for traditional medicine alignment. UAE Ministry of Economy halal-certification requirements create documentation burdens for multi-country launches.
Established volume favors probiotics and fortified beverages; emerging adoption favors protein supplements and prebiotics.
Application:
Cost tier differentiation separates clinically positioned wellness offerings from mass-market fortification, with pediatric and elderly formats commanding premium pricing due to vulnerable-population compliance scrutiny.
- Digestive Health:Gut microbiome optimization through probiotics and prebiotics. Pharmacy networks in Saudi Arabia and the UAE anchor distribution for digestive-health seekers seeking clinician validation.
- Immune Support:Vitamin C, D, zinc, and botanical formulations. Working professionals in Riyadh prioritize convenient fortification for immune resilience amid demanding schedules.
- Weight Management:Protein-rich and fiber-enhanced products targeting satiety and metabolic support. Fitness enthusiasts in Dubai and Abu Dhabi corridors drive demand for meal-replacement formats.
- Heart Health:Omega-3, plant sterol, and antioxidant formulations. Elderly segments in Jeddah show preference for cardiovascular-positioned functional foods.
- Bone Strengthening:Calcium and vitamin D fortification for skeletal health. Children and adolescents in Saudi Arabia represent underdeveloped white space relative to adult offerings.
- Skin Care:Collagen, hyaluronic acid, and antioxidant ingestibles. Premium retail infrastructure in Dubai supports beauty-from-within positioning at elevated price points.
Digestive health and immune support capture current volume concentration; weight management and skin care exhibit steepest expansion trajectory among premium-tier consumers.
Distribution Channel:
Customer type concentration varies sharply by channel, with fitness enthusiasts dominating online subscription models while elderly consumers remain anchored to pharmacy and health clinic touchpoints.
- Supermarkets & Hypermarkets:Mass-market fortification formats with broad household penetration. Ambient-stable products predominate given cold-chain limitations in traditional retail.
- Specialty Stores:Premium probiotic and protein supplement curation for informed consumers. Dubai's wellness-focused retail corridors outpace other Gulf cities in specialty format density.
- Pharmacies:Clinically positioned probiotics and fortified beverages leveraging pharmacist recommendation authority. Established UAE and Saudi pharmacy networks reach digestive-health seekers with credibility.
- Online Retailers:Direct-to-consumer protein supplements with personalized delivery schedules. Saudi Arabia's Riyadh and Jeddah clusters show behavioral migration among working professionals with limited store-visit windows.
- Convenience Stores:Single-serve fortified beverages for immediate consumption. Ambient distribution requirements favor heat-stabilized vitamin formats.
- Health Clinics:Medical-grade nutrition for pediatric and elderly vulnerable populations. SFDA compliance scrutiny elevates entry barriers for clinic-channel distribution.
Pharmacy and supermarket channels defend established volume; online retail gains share fastest among fitness enthusiasts and working professionals.
Customer Type:
Margin structure varies dramatically across customer segments, with pediatric and elderly formats facing highest compliance costs while fitness enthusiasts accept premium pricing for performance positioning.
- Fitness Enthusiasts:Protein supplement and prebiotic demand concentrated in Dubai, Abu Dhabi, Riyadh, and Jeddah gym-adjacent retail. Personalized flavor customization and subscription delivery prioritize convenience over retail immediacy.
- Children & Adolescents:Pediatric nutrition formats tailored to Gulf dietary patterns remain underdeveloped relative to adult offerings. SFDA vulnerable-population compliance scrutiny elevates formulation standards.
- Elderly:Bone strengthening and heart health applications with pharmacy channel preference. Clinician validation carries disproportionate influence in purchase decisions.
- Working Professionals:Fortified beverages and protein supplements for workplace consumption and limited store-visit windows. Saudi Arabia and UAE urban centers drive format innovation for convenience.
- Pregnant Women:Folate, iron, and DHA fortification with medical supervision requirements. Health clinic and pharmacy channels predominate.
- Students:Cognitive performance and immune support positioning. Price sensitivity favors mass-market fortification tiers.
Working professionals and fitness enthusiasts anchor current revenue concentration; children and adolescents present the most significant white space for segment-specific format development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia exports functional dairy and probiotic formulations to UAE retail corridors, establishing the dominant intra-GCC trade flow in fortified nutrition products. This bilateral corridor channels refrigerated distribution infrastructure investments toward Dubai and Abu Dhabi logistics hubs.
Saudi Arabia
Health-conscious working professionals in Riyadh and Jeddah drive demand for protein supplements and workplace fortification formats. Saudi Food and Drug Authority labeling mandates force manufacturers toward cleaner formulations with documented bioactive dosage thresholds. The Eastern Province dairy processing clusters anchor Almarai Company's refrigerated probiotic distribution network.
United Arab Emirates
Premium retail infrastructure in Dubai and Abu Dhabi corridors outpaces other Gulf cities in wellness-focused consumer spending. Emirates Authority for Standardization and Metrology nutrient-content thresholds compel reformulation of borderline vitamin waters and functional claims. Dubai's pharmacy networks and specialty wellness retail corridors concentrate clinically positioned probiotic distribution.
Qatar
High per-capita income demographics support premium-tier functional beverage adoption among expatriate professionals in Doha. Gulf Cooperation Council harmonization talks on health-claim substantiation would reshape Qatari market access protocols for Saudi and UAE manufacturers. Lusail and West Bay districts host emerging specialty retail formats for imported fortified nutrition.
Kuwait
Affluent consumer segments in Kuwait City prioritize immune-support and digestive-health positioning in pharmacy-channel purchases. The country's national food regulator enforces halal-certification documentation burdens that delay multi-country product launches from Saudi suppliers. Salmiya and Sharq retail corridors concentrate hypermarket distribution for mass-market fortification tiers.
Oman
Limited local production scale elevates import dependency for nutritional bars and specialized protein formats. Omani standards bodies generally follow Saudi Food and Drug Authority precedent on nutrient-content labeling compliance. Muscat's pharmacy and supermarket channels remain underdeveloped relative to UAE retail density for functional food penetration.
GCC Functional Food & Beverage Market Competitive Landscape
Listed leaders compete with private specialists across refrigerated distribution infrastructure and halal-certification compliance capabilities. The GCC functional food sector exhibits consolidated dairy dominance alongside fragmented protein supplement and nutritional bar segments. Three archetypes prevail: integrated dairy conglomerates with captive cold-chain networks, beverage specialists leveraging microencapsulation technology, and multinational nutrition platforms with pediatric R&D intensity. Competitive moves concentrate on strategic partnerships for halal supply chain verification and geographic expansion into underpenetrated Gulf markets.
Within the integrated dairy tier, Almarai Company represents supply chain verticality across Saudi Arabia's refrigerated distribution corridors. Agthia Group exemplifies UAE-based beverage specialization with bottled functional water and vitamin-fortified juice positioning. Nestlé Middle East FZE anchors multinational R&D intensity for pediatric and elderly nutrition formats adapted to Gulf dietary patterns.
| Leading Market Players |
|---|
| Almarai Company |
| Agthia Group |
| Nestlé Middle East FZE |
| Danone Middle East |
| Baladna |
| IFFCO |
| Savola Foods Company |
| National Food Products Company |
| Arla Foods |
| Others |
Pricing and Supply Chain Analysis
Almarai Company's captive dairy processing capacity across Saudi Arabia's Eastern Province generates scale economies that compress unit costs for refrigerated probiotic formats while establishing price floors that smaller UAE beverage specialists struggle to match. This concentration of cold-chain infrastructure simultaneously anchors premium-tier pricing power in Dubai and Abu Dhabi corridors and limits margin flexibility for import-dependent nutritional bar entrants.
Pricing Analysis
Microencapsulation technology adoption creates a pronounced pricing gap between legacy spray-dried vitamin fortification and next-generation heat-stable formulations. Three-tier pricing structure across premium clinically positioned, standard mass-market, and economy private-label tiers dominates the GCC landscape. Price differentiation hinges on SFDA compliance certification tier and cold-chain reliability guarantees. Pricing pressure stems from direct-to-consumer subscription models fragmenting traditional pharmacy channel markups. Working professionals in Riyadh and Jeddah show highest price sensitivity for workplace fortification formats, while fitness enthusiasts in Dubai accept premium positioning for personalized protein delivery.
Supply Chain Analysis
Saudi Arabia and the UAE anchor functional dairy and probiotic production, with Qatar and Kuwait drawing from these hubs for refrigerated distribution. Raw material dependencies center on whey protein isolates, probiotic culture strains, and microencapsulation shell materials. Supply chain risk concentrates in single-source vulnerability for heat-sensitive vitamin imports subject to Emirates Authority for Standardization and Metrology documentation delays. Distribution runs through pharmacy networks and direct-to-consumer platforms, with refrigerated logistics investments in Dubai and Abu Dhabi corridors enabling viability claims previously constrained by ambient Gulf conditions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Conventional food and beverage manufacturers represent a persistent substitution threat as SFDA labeling mandates force clearer differentiation between functional claims and basic nutrition, compelling incumbents to defend clinical credibility against commoditization.
For Market Incumbents: Fortify refrigerated distribution infrastructure in Saudi Arabia's Eastern Province to anchor probiotic viability claims against ambient-stable substitute formats. Deepen halal-certification compliance capabilities to preempt UAE Ministry of Economy documentation friction. Prioritize pediatric nutrition R&D investment as vulnerable-population positioning commands premium pricing and elevates competitive barriers. For New Entrants and Emerging Players: SFDA fast-track approval for documented bioactive dosage thresholds opens immediate positioning against borderline functional claims. Target prebiotic formats in Riyadh and Jeddah fitness communities as the most penetrable white space beyond established probiotics. Pursue direct-to-consumer subscription go-to-market to bypass pharmacy channel saturation in Dubai and Abu Dhabi corridors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors microencapsulation-capable beverage specialists over legacy spray-dried fortification players. Long-term viability over the projection horizon rests on cold-chain infrastructure ownership and regulatory compliance automation. Acquisition target archetype: UAE-based functional water specialists with Emirates Authority for Standardization and Metrology threshold expertise. Monitor Gulf Cooperation Council harmonization talks on health-claim substantiation as the critical inflection signal for cross-border scaling economics.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Refrigerated probiotic viability claims in Dubai and Abu Dhabi corridors depend on dedicated logistics investments. |
| Halal-Certification Automation | UAE Ministry of Economy documentation requirements create timeline delays that automated compliance systems compress. |
| Pediatric Nutrition Format Development | SFDA vulnerable-population scrutiny elevates entry barriers for clinically positioned infant and child offerings. |
| Direct-to-Consumer Platform Launch | Subscription models fragment pharmacy channel dominance among Riyadh working professionals with limited store-visit windows. |
| Microencapsulation Technology Licensing | Heat-stable vitamin retention enables ambient distribution without Emirates Authority for Standardization and Metrology reformulation mandates. |
Research Methodology
Initial hypotheses were tested against primary input from dairy processing executives, pharmacy chain procurement directors, regulatory affairs specialists at SFDA and Emirates Authority for Standardization and Metrology, and fitness community subscription platform operators, then refined through secondary validation. Bottom-up triangulation combined Nielsen retail audit data, customs import records for nutritional bars, SFDA filing databases, and Gulf Cooperation Council trade flow statistics with top-down macroeconomic absorption modeling.
Variance decomposition across product type, application, distribution channel, and customer type segmentation dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level volume and value build-ups cross-referenced against regulatory timeline assumptions and cold-chain infrastructure deployment schedules. Forecast inputs incorporated SFDA labeling mandate implementation pace and pharmacy channel share erosion rates from direct-to-consumer migration.
Underlying assumptions cover stable Gulf Cooperation Council trade protocols and continued SFDA enforcement intensity, with deviation risk concentrated in harmonization talk outcomes and heat-stabilization technology cost curves. Forecasts reflect these assumptions with explicit sensitivity to regulatory threshold adjustments and probiotic culture supply reliability. Recalibration cycles align with material shifts in Gulf regulatory harmonization progress and refrigerated logistics investment announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.