
 Low-Calorie Chocolate Market | 2026-2036
Low-Calorie Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Calorie Chocolate Market Foresight
The low-calorie chocolate category is pivoting between premium artisan positioning and mass-market sugar-reduced commodity lines, with cocoa butter equivalence and clean-label sweetener claims defining the split. Nestle S.A. leverages its global R&D network to reformulate heritage brands with allulose and fiber blends. The Hershey Company anchors its position through controlled distribution in North American pharmacy and grocery channels. Mondelez International competes on manufacturing scale across European and Latin American plants.
Low-calorie chocolate denotes confectionery products with reduced caloric density achieved through sugar substitution, cocoa mass optimization, or bulking agent incorporation, typically containing fewer than 40% of the sucrose found in standard formulations while maintaining rheological properties for tempering and molding. Dark chocolate segments lead in clean-label positioning due to naturally lower baseline sugar and higher cocoa polyphenol content that supports reduced-calorie claims without extensive reformulation. Online retailers represent the fastest-growing distribution channel as subscription models and direct-to-consumer sampling reduce trial barriers for unfamiliar sweetener systems. Milk chocolate remains the largest volume pool but carries thinner margins due to intensive reformulation costs and consumer taste-panel failure rates.
FDA nutrition labeling requirements and the EU Nutrition and Health Claims Regulation shape permissible reduced-calorie and sugar-free claims, with EFSA evaluations determining which sweetener combinations qualify for functional health statements. Health Canada and Japan's Consumer Affairs Agency enforce additional compositional thresholds that determine whether products may carry diabetes-friendly or calorie-control designations. Stakeholders must monitor evolving sweetener approval pipelines and front-of-pack warning label expansions to anticipate which reformulation investments will retain market access.
Market Dynamics
Sugar taxation regimes and front-of-pack labeling mandates are forcing accelerated reformulation across the confectionery sector, compressing development timelines while expanding permissible sweetener portfolios.
Growth Catalysts
- EU Nutrition and Health Claims Regulation:EFSA-approved sweetener combinations unlock functional health statements, enabling premium positioning for reduced-calorie dark chocolate lines in German and French retail.
- Stevia-leaf bioprocessing:Enzymatic glycosylation improvements are lowering bitter aftertaste thresholds, accelerating adoption in milk chocolate formulations previously resistant to sugar substitution.
- Japan's Consumer Affairs Agency:Calorie-control designation thresholds are creating a regulatory pathway for diabetes-friendly chocolate segments in Tokyo and Osaka pharmacy channels.
Market Restraints
- Cocoa butter equivalent (CBE) cost volatility:Palm kernel and shea butter price swings constrain margin stability for reduced-calorie milk chocolate producers dependent on fat fraction manipulation.
- West African supply concentration:Ivory Coast and Ghana cocoa sourcing dominance exposes reformulation pipelines to bean quality inconsistency affecting polyphenol retention in clean-label claims.
- Tempering rheology limitations:Allulose and erythritol blends exhibit inferior snap and gloss characteristics compared to sucrose baselines, restricting artisan chocolate applications.
Strategic Opportunities
- Subscription direct-to-consumer:Online sampling models reduce trial barriers for unfamiliar monk fruit-sweetened products, capturing repeat purchase data for flavor optimization.
- US FDA allulose guidance:Exclusion from added sugars labeling creates a regulatory tailwind for American manufacturers seeking clean-label reduced-calorie positioning.
- Functional fiber incorporation:Inulin and resistant starch convergence with sweetener systems enables dual fiber-plus-reduced-calorie claims in wellness-oriented retail.
Industry Challenges
- Sensory panelist recruitment:Trained taste assessors familiar with non-nutritive sweetener flavor profiles remain scarce, delaying product validation cycles.
- Legacy equipment retrofitting:Conching and refining machinery designed for sucrose-based viscosity requires capital-intensive modification to handle bulking agent rheology.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Calorie Chocolate Market |
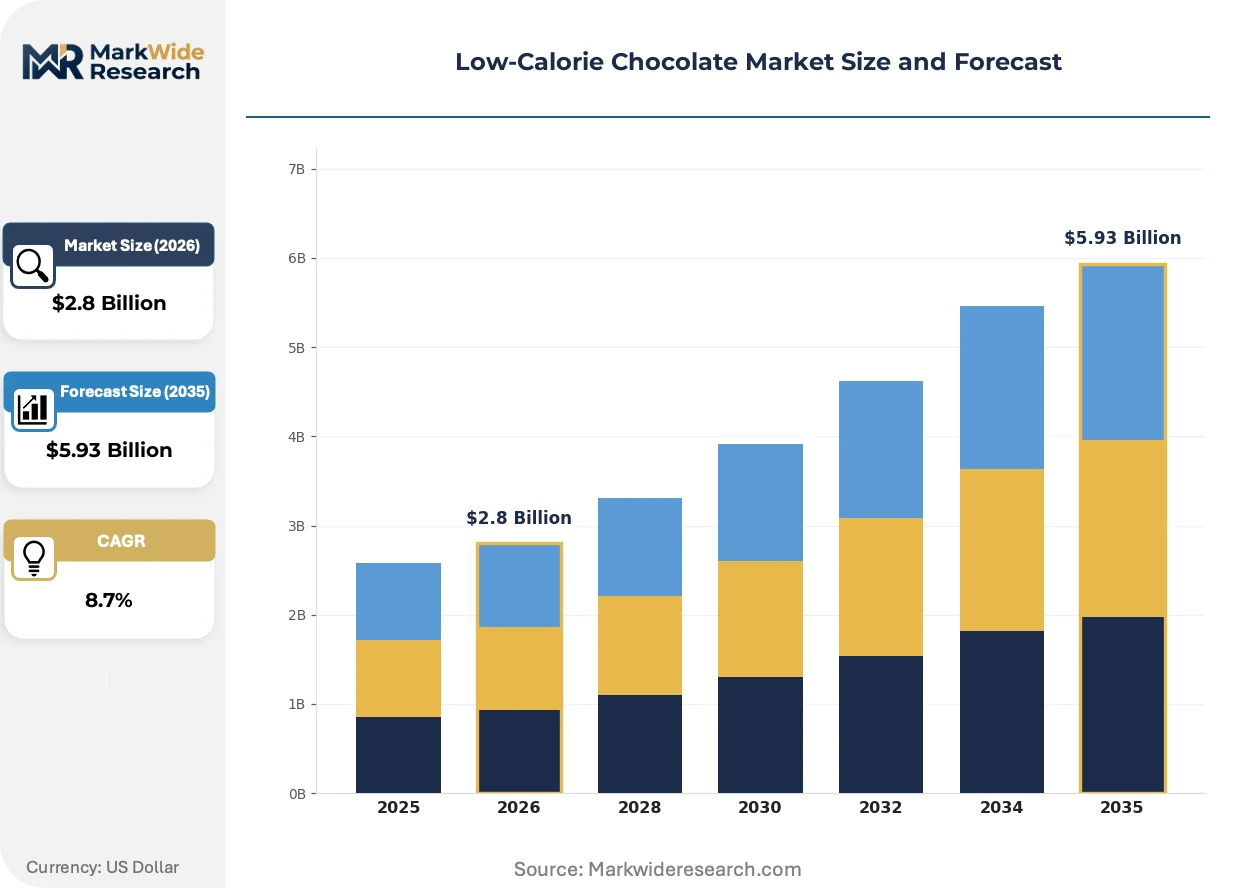
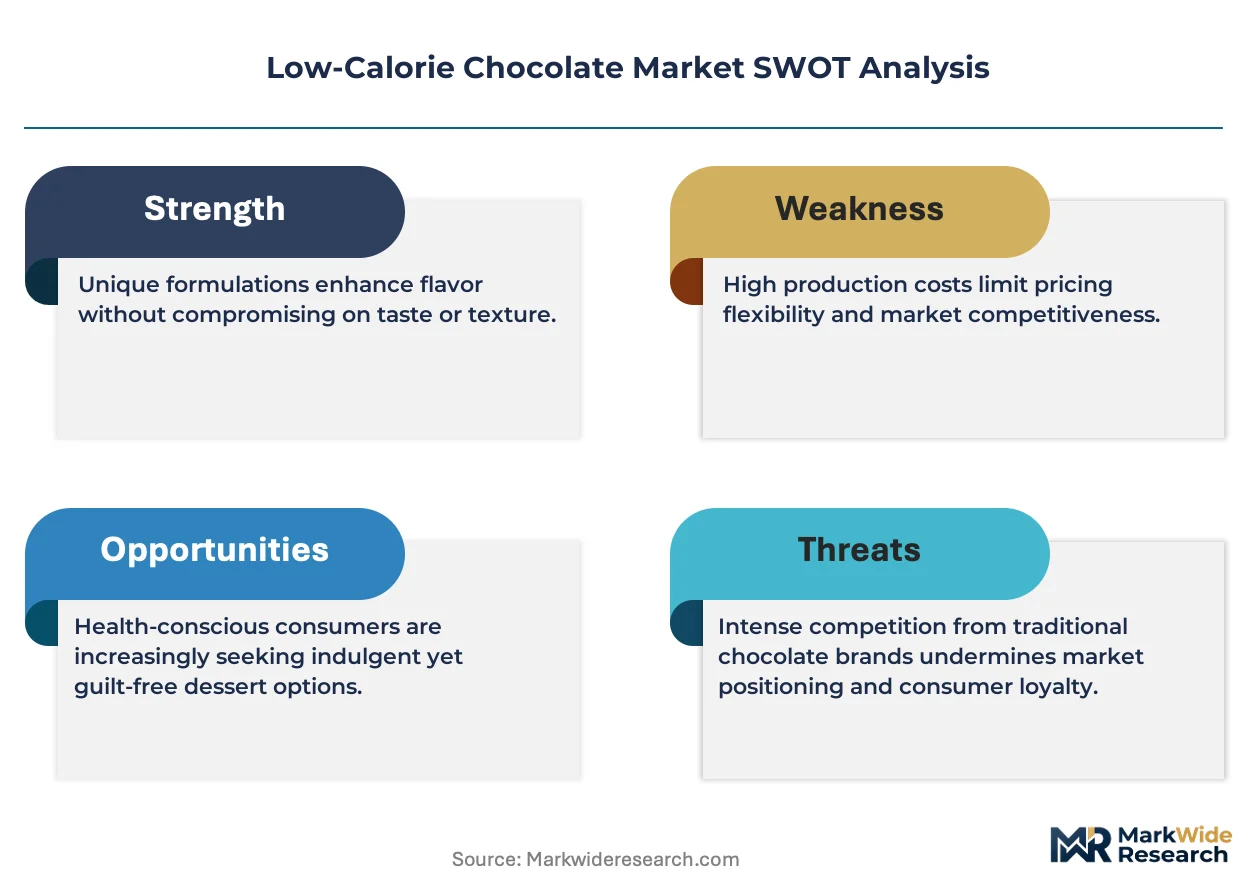
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Coated Chocolates End User: Health-Conscious Consumers, Diabetics, Weight Watchers, Athletes Distribution Channel: Supermarkets, Online Retailers, Health Stores, Convenience Stores Packaging Type: Bars, Pouches, Boxes, Segmented Packs |
| Companies Covered | Nestle S.A., The Hershey Company, Mondelez International, Barry Callebaut AG, Blommer Chocolate Company, Lindt & Sprungli, Ferrero SpA, Kraft Heinz Company, Cargill Cocoa & Chocolate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Calorie Chocolate Market Shifts & Advancements
Clean-label sweetener systems are displacing artificial alternatives across premium and mass-market tiers simultaneously, compressing the historical price-performance gap between reduced-calorie and conventional chocolate.
Allulose production via enzymatic fructose epimerization is consolidating supply chain control among biotechnology firms with proprietary yeast strains. North American confectioners are adopting this rare sugar at pace previously reserved for high-intensity sweeteners. The technology is consolidating manufacturing scale around integrated sweetener-chocolate producers capable of captive ingredient supply.
EFSA evaluations under the EU Nutrition and Health Claims Regulation are determining which polyol combinations qualify for laxative-warning exemptions, directly affecting permissible serving sizes on packaging. This regulatory gatekeeping is compressing formulation portfolios toward EFSA-preferred sweetener ratios. Dark chocolate segments with naturally lower sugar baselines are responding fastest by leveraging existing polyphenol health claims.
Pharmacy channel placement is displacing traditional grocery as the primary trial environment for diabetes-friendly chocolate variants. German and Japanese drugstore chains are expanding shelf space for calorie-control designated products, replacing impulse-checkout confectionery. This channel rotation is most visible in urban centers where front-of-pack warning labels have trained consumers to seek explicit health designations.
Low-Calorie Chocolate Market Segmentation
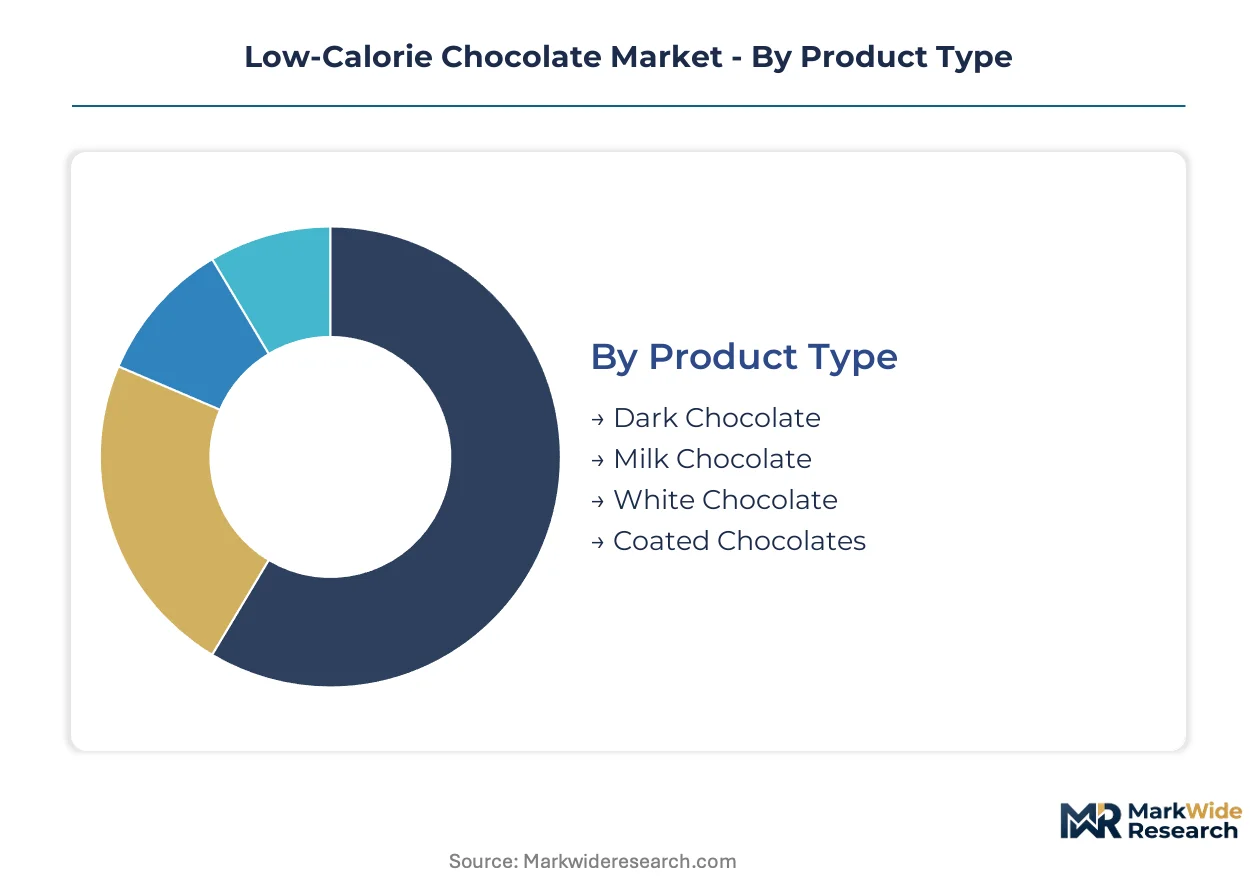
Segmentation in low-calorie chocolate reveals how reformulation complexity, regulatory positioning, and channel access fragment commercial opportunity across distinct consumer missions and technical specifications. Manufacturers must align sweetener portfolios and packaging formats to specific purchasing contexts rather than pursuing undifferentiated mass-market penetration.
Product Type:
The customization-vs-standardization spectrum across product types spans artisan tempering requirements at one extreme and commodity-scale molding at the other, with cocoa polyphenol content and sucrose replacement ratios determining manufacturing flexibility.
- Dark Chocolate:Naturally elevated cocoa mass provides a lower baseline sugar content, enabling reduced-calorie claims through modest reformulation rather than aggressive sweetener substitution. German and French retail channels concentrate demand for EFSA-approved polyphenol health claims combined with stevia-sweetened positioning. Clean-label credentials command premium shelf placement in pharmacy and wellness-oriented grocery.
- Milk Chocolate:Higher lactose and milk fat fractions necessitate intensive bulking agent incorporation to maintain mouthfeel, driving reformulation costs upward. Japanese pharmacy channels show concentrated uptake for calorie-control designated variants targeting diabetes-friendly positioning. Taste-panel failure rates remain elevated due to protein-sweetener interaction challenges.
- White Chocolate:Cocoa butter dominance without cocoa solids creates a blank sensory canvas for monk fruit and allulose systems. Premium confectionery boutiques in urban centers drive niche demand.
- Coated Chocolates:Enrobing processes accommodate fiber-enriched centers with reduced-calorie shell formulations. Seasonal gifting occasions sustain volume.
Most installed capacity flows through Milk Chocolate. Expansion is steepest in Dark Chocolate.
End User:
Cost tier stratification across end users separates premium-priced clinical positioning from mass-market wellness claims, with reimbursement pathways and subscription economics defining margin structures.
- Health-Conscious Consumers:Broadest addressable base seeking permissive indulgence without dietary compromise. Online subscription models in North America reduce trial barriers for unfamiliar allulose-sweetened lines. Front-of-pack labeling awareness drives explicit calorie-reduction seeking behavior.
- Diabetics:Medically motivated purchasing with explicit glycemic control requirements. Japanese drugstore chains and German pharmacy channels validate products through calorie-control designations. Regulatory compliance costs elevate pricing but secure repeat purchase loyalty.
- Weight Watchers:Portion-controlled consumption patterns favor segmented packaging formats. Fitness-oriented retail in metropolitan areas concentrates demand.
- Athletes:Protein-fiber hybrid positioning targets recovery and satiation use cases. Sports nutrition specialty channels sustain niche volume.
Volume concentrates in Health-Conscious Consumers. Steepest expansion trajectory appears in Diabetics.
Distribution Channel:
Application-specific channel strategies align impulse purchasing mechanics with deliberate health-seeking missions, requiring distinct packaging and merchandising investments.
- Supermarkets:Primary volume channel where front-of-pack warning labels and sugar taxation have repositioned reduced-calorie variants from niche to mainstream shelf space. German and United States mass-market retailers allocate expanded planogram sections to clean-label sweetener systems. Promotional intensity compresses margins but builds brand recognition.
- Online Retailers:Direct-to-consumer sampling and subscription replenishment models overcome taste uncertainty for novel monk fruit formulations. Data capture enables rapid flavor optimization cycles. Urban centers with limited specialty retail access show disproportionate penetration.
- Health Stores:Curated assortment environments validate premium positioning through staff recommendation and ingredient transparency. Natural channel exclusivity supports margin defense.
- Convenience Stores:Impulse-driven single-serve formats with immediate consumption positioning. Grab-and-go placement competes with conventional confectionery.
Most installed capacity flows through Supermarkets. Gaining share fastest is Online Retailers.
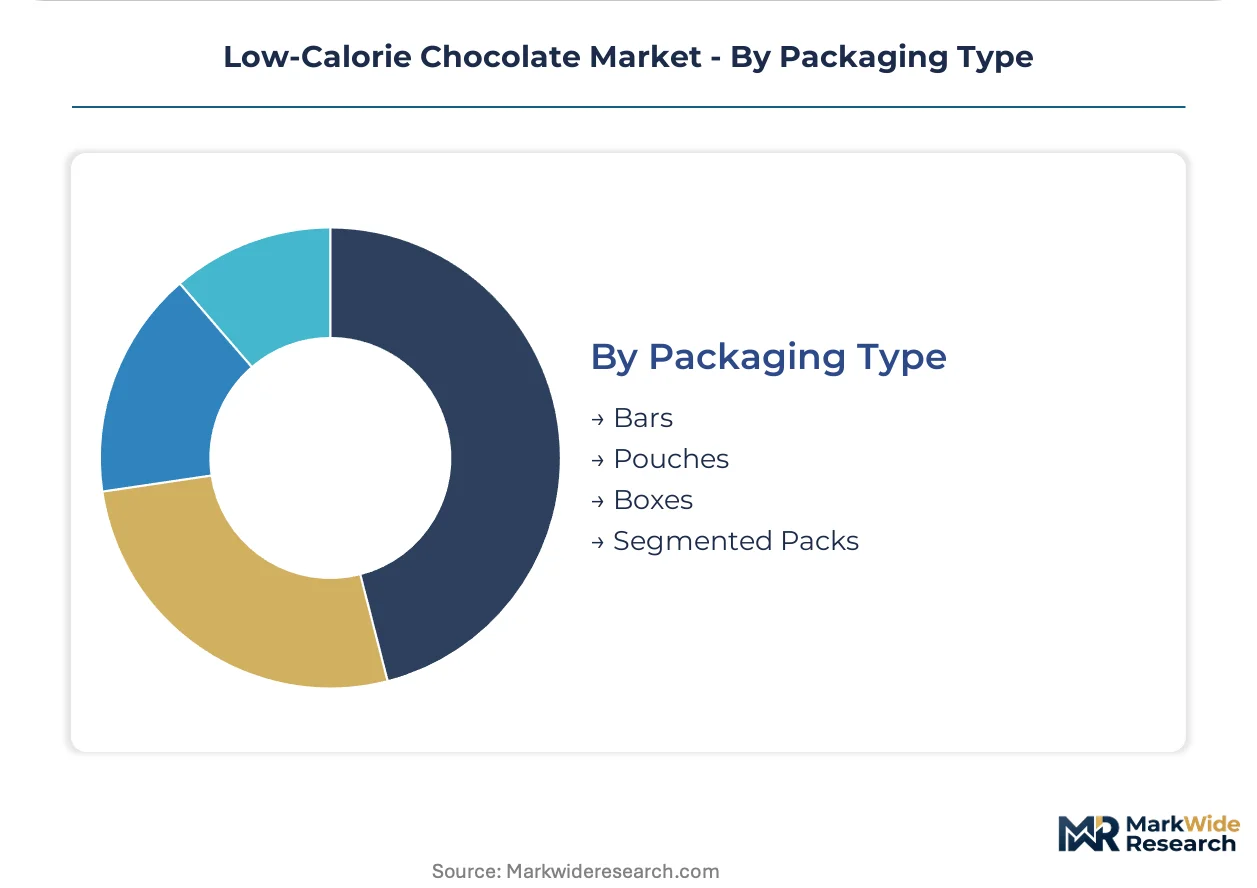
Packaging Type:
Volume-to-margin tradeoffs across packaging formats reflect consumption occasion fragmentation, from immediate gratification to planned gifting and controlled portioning.
- Bars:Standard format for tempering-dependent artisan and mass-market production alike. German and United States grocery channels sustain baseline volume for everyday consumption.
- Pouches:Flexible resealable formats accommodate bite-sized pieces and portion-control messaging. Japanese pharmacy channels favor this configuration for diabetes-friendly lines.
- Boxes:Gifting and seasonal occasion positioning commands premium pricing. Limited edition assortments test novel sweetener systems.
- Segmented Packs:Pre-portioned individual wrappers support explicit calorie-counting claims. Weight management programs and clinical nutrition contexts drive adoption.
Most installed capacity flows through Bars. Expansion is steepest in Segmented Packs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ingredient technologists and confectionery formulators cluster in Germany, the United States, and Japan where sugar taxation and front-of-pack labeling regimes have institutionalized reformulation expertise. These talent concentrations anchor regional innovation pipelines for clean-label sweetener systems.
Germany
Health-conscious consumers in Berlin and Munich drive demand for EFSA-approved polyphenol health claims combined with stevia-sweetened dark chocolate positioning. The EU Nutrition and Health Claims Regulation determines which sweetener combinations qualify for functional statements, compressing formulation portfolios toward regulator-preferred ratios. The Cologne-Düsseldorf corridor hosts concentrated pharmacy channel distribution for calorie-control designated products.
United States
Mass-market retailers allocate expanded planogram sections to allulose-sweetened lines following FDA guidance excluding the rare sugar from added sugars labeling. The FDA nutrition labeling requirements shape permissible reduced-calorie claims, creating regulatory tailwinds for clean-label positioning. Chicago and Hershey, Pennsylvania anchor manufacturing scale for reformulated heritage brands with fiber blends.
Japan
Diabetes-friendly chocolate segments concentrate in Tokyo and Osaka pharmacy channels validated by Consumer Affairs Agency calorie-control designations. Japan's explicit glycemic control thresholds elevate pricing but secure repeat purchase loyalty among medically motivated consumers. The Kanto region hosts specialized taste-panel facilities for monk fruit and erythritol formulation validation.
Switzerland
Premium artisan positioning for white chocolate variants with monk fruit systems concentrates in Zurich and Geneva boutique channels. Swissmedic enforcement of compositional thresholds determines diabetes-friendly designation eligibility, filtering permissible sweetener portfolios. The Lake Geneva corridor maintains heritage conching expertise adapted for bulking agent rheology.
United Kingdom
Online subscription models for novel sweetener sampling show disproportionate penetration in London and Manchester where specialty retail access remains limited. Front-of-pack warning labels have trained consumers to seek explicit health designations in pharmacy and wellness-oriented grocery. The Midlands region hosts contract manufacturing capacity for stevia-leaf bioprocessing integration.
Low-Calorie Chocolate Market Competitive Landscape
Top-tier vendors anchor mass-market scale, while mid-tier specialists and artisan boutiques occupy differentiated positioning. The vendor base stratifies across integrated sweetener-chocolate producers, heritage brand reformulators, and clean-label pure-plays. Three archetypes dominate: biotechnology firms with captive allulose supply, multinational confectioners leveraging global R&D networks, and regional artisans exploiting tempering flexibility for premium positioning. Competitive moves concentrate on strategic partnerships for sweetener access and portfolio diversification into functional fiber claims.
Within the integrated multinational tier, Nestle S.A., The Hershey Company, and Mondelez International exemplify divergent strategic postures. Nestle S.A. occupies a position representing global R&D network deployment for heritage brand reformulation. The Hershey Company exemplifies controlled distribution anchoring through pharmacy and grocery channel concentration. Mondelez International sits within the manufacturing scale archetype across European and Latin American production footprints. These three entities collectively represent the spectrum from captive ingredient supply to outsourced sweetener sourcing, illustrating how reformulation complexity fragments competitive advantage across supply chain control points.
| Leading Market Players |
|---|
| Nestle S.A. |
| The Hershey Company |
| Mondelez International |
| Barry Callebaut AG |
| Blommer Chocolate Company |
| Lindt & Sprungli |
| Ferrero SpA |
| Kraft Heinz Company |
| Cargill Cocoa & Chocolate |
| Others |
Supply & Pricing Matrix
Enzymatic allulose production via proprietary yeast strain fermentation is consolidating supply chain control among biotechnology firms while simultaneously compressing unit economics for reduced-calorie chocolate manufacturers. This technological shift concentrates captive ingredient supply among integrated producers who internalize sweetener costs, fragmenting pricing power between those with backward integration into rare sugar production and those dependent on spot market procurement.
Pricing Analysis
Bundled allulose-sweetened formulations command premium positioning against unbundled commodity chocolate lines where sweetener sourcing remains outsourced. Three-tier pricing structure across premium artisan, standard mass-market, and economy private-label levels stratifies by cocoa polyphenol certification and clean-label claim density. Pricing pressure stems from stevia-leaf bioprocessing capacity expansion lowering input costs for mid-tier competitors. Health-conscious consumers in online subscription channels show lowest price sensitivity, while supermarket bulk purchasers exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements for cocoa butter equivalents mandate multi-supplier qualification across Ivory Coast, Ghana, and Ecuador to mitigate West African supply concentration risk. Raw material dependencies center on palm kernel and shea butter fractions, allulose enzymatic feedstock, and monk fruit extract from Chinese cultivation regions. Single-source vulnerability in proprietary yeast strain supply creates bottleneck exposure for integrated manufacturers. Distribution runs through pharmacy and grocery channels in Germany, the United States, and Japan where regulatory compliance validates premium positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low-calorie chocolate market functions as a stable compounder anchored by irreversible regulatory momentum toward sugar taxation and front-of-pack labeling that institutionalizes reformulation demand across developed economies.
For Market Incumbents: Anchor manufacturing scale through captive allulose supply agreements or in-house enzymatic production capacity, defending against biotechnology firm margin capture. Expand pharmacy channel shelf space in German and Japanese urban centers where calorie-control designations command pricing power. Prioritize EFSA-preferred sweetener ratio portfolios to lock in functional health claim eligibility. For New Entrants and Emerging Players: Diabetes-friendly chocolate segments in Japanese drugstore chains represent the most penetrable white-space target, with explicit glycemic control thresholds creating regulatory moats against mass-market competitors. White chocolate variants with monk fruit positioning in Swiss boutique channels offer premium artisan entry with lower tempering complexity. Direct-to-consumer sampling models reduce trial barriers for unfamiliar sweetener systems before grocery scale-up. For Investors and Strategic Acquirers: Valuations sit cheapest among regional contract manufacturers with stevia-leaf bioprocessing integration and pharmacy channel relationships. Long-term viability over a five-to-ten year window hinges on regulatory approval pipelines for novel sweetener systems. Monitor FDA allulose guidance evolution and EFSA polyol combination evaluations as inflection indicators for portfolio reformulation investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Allulose Production | Captive rare sugar supply secures margin control against biotechnology firm pricing power. |
| Pharmacy Channel Expansion | Calorie-control designation placement in German and Japanese drugstore chains validates premium positioning. |
| EFSA-Preferred Sweetener Portfolio Concentration | Regulator-preferred polyol ratios unlock functional health claims and permissible serving sizes. |
| Direct-to-Consumer Subscription Launch | Online sampling models capture repeat purchase data for monk fruit flavor optimization cycles. |
| Functional Fiber Claim Convergence | Inulin and resistant starch incorporation enables dual fiber-plus-reduced-calorie wellness positioning. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down sweetener supply tracking forms the analytical core of this study. Primary interviews with confectionery R&D directors, pharmacy category buyers, regulatory affairs specialists at ingredient technology firms, and supermarket planogram managers combined with secondary validation from FDA guidance documents, EFSA health claim evaluations, Japan Consumer Affairs Agency designations, and customs trade data for cocoa butter equivalent imports. Triangulation across these sources calibrates volume estimates against actual production capacity and channel flow-through.
Historical trendline analysis of reformulation adoption rates and sweetener price trajectories informs projection mechanics across the analysis window. Segmentation dimensions modeled include product type, end-user mission, distribution channel, and packaging format, with additional granularity on regulatory framework clusters. CAGRs derive from fitted growth curves adjusted for sugar taxation implementation schedules and front-of-pack labeling expansion timelines. Forecast inputs incorporate stevia-leaf bioprocessing yield improvements and allulose enzymatic production scale-up curves.
Underlying measurement precision varies by segment; dark chocolate and pharmacy channel flows carry tighter precision than white chocolate boutique volumes. Forecasts reflect documented assumptions regarding EFSA evaluation timelines and FDA guidance stability. Cocoa bean quality inconsistency and sweetener approval pipeline delays represent specific revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Low-Fat Dark Chocolate Market
Confectionery
Caramel Market
Confectionery
Low Calorie Keto Desserts Market
Confectionery
Mooncake Market
Confectionery
Global Non-Cocoa Confectionery Market
Confectionery
US Confectionery Market
Confectionery
Green Tea Chocolate Market
Confectionery
Low-Calorie Candy Market
Confectionery
Dietary Chocolate Products Market
Confectionery
Sugar-Free Confectionery Market
Confectionery
Asia-Pacific Sugar Free Mints Market
Confectionery
Brain Mint Market
Confectionery
North America Sugar-Free Chewing Gum Market
Confectionery
Vegan Candies Market
Confectionery
Sugarless Chocolate Market
Confectionery
Confectionery Fillings Market