
 Low Carb and Low Fat Diet Market | 2026-2036
Low Carb and Low Fat Diet Market Size, Share, and Industry Trends Forecast 2026-2036
Low Carb and Low Fat Diet Market Analytics
The split between premium organic positioning and mass-market private label is realigning shelf space allocation across retail formats. Nestlé S.A. leverages its refrigerated portfolio to anchor European distribution networks. Unilever Plc sustains plant-based R&D pipelines that compete on clean-label credentials. Atkins Nutritionals Inc. specializes in ketogenic formulations that dominate the low-carb sub-category in North American grocery channels.
Low carb and low fat diets restrict carbohydrate or fat intake to modify metabolic fuel utilization, typically keeping carbohydrates below 20-50 grams daily or fat below 30% of caloric intake, with formulations engineered to preserve palatability through protein fortification and fiber substitution. The product category dimension shows meal replacements capturing margin pools through subscription delivery models, while snack bars face commoditization pressure from private-label entrants. The diet type dimension reveals keto positioning leading growth trajectories, whereas Mediterranean formats occupy mature shelf-stable segments with slower velocity but higher repeat rates.
The FDA enforces nutritional labeling standards that shape permissible health claims on packaging, while the USDA Dietary Guidelines influence institutional procurement criteria for school and hospital foodservice. The EFSA in Europe evaluates novel food applications for alternative proteins used in low-fat reformulations, creating divergent approval timelines across Atlantic markets. Stakeholders must monitor how front-of-pack labeling mandates in multiple jurisdictions will force reformulation investments or portfolio pruning.
Market Dynamics
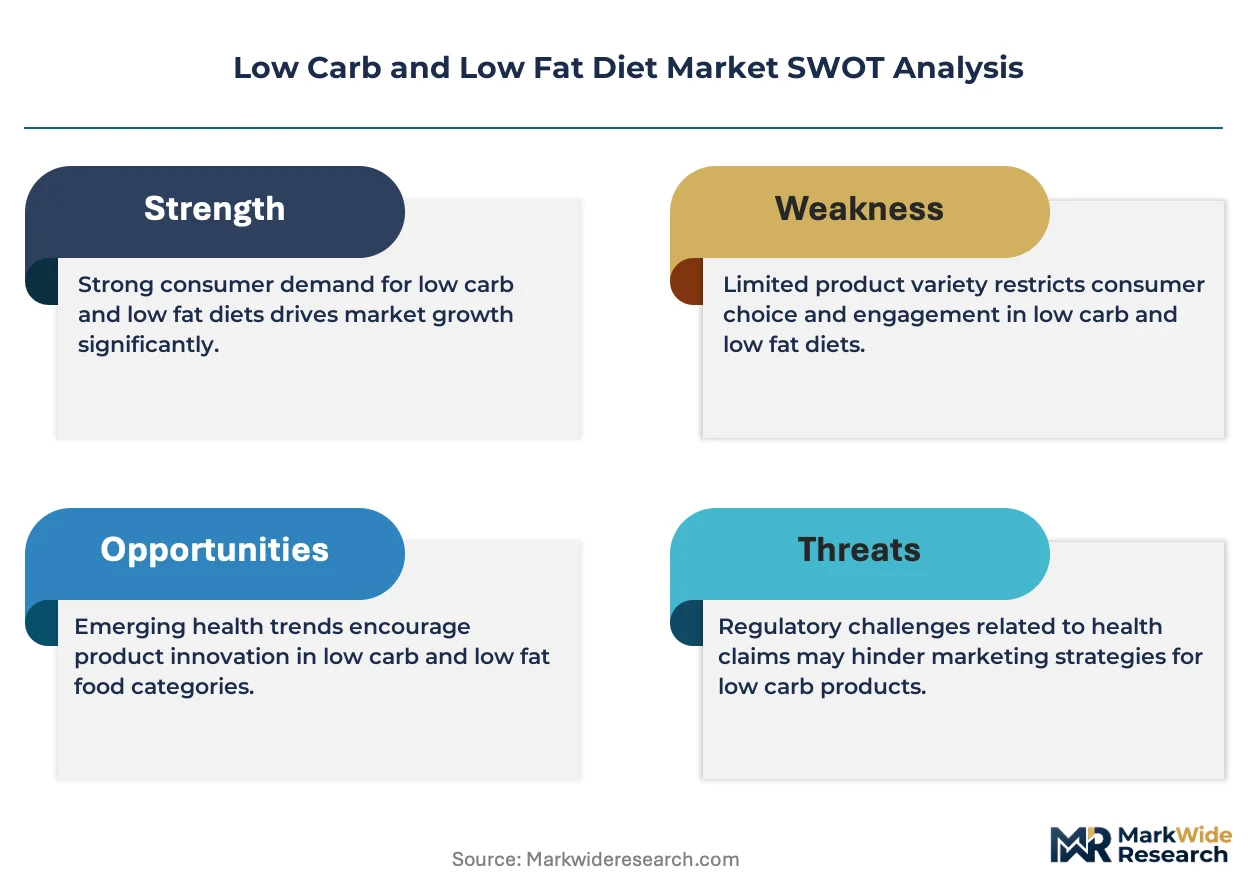
Protein fortification technologies and front-of-pack labeling mandates are forcing simultaneous reformulation investments across refrigerated and shelf-stable portfolios, compressing margin structures for mid-tier manufacturers.
Growth Catalysts
- USDA Dietary Guidelines:Institutional procurement criteria for school and hospital foodservice now prioritize reduced-fat and low-carbohydrate options, redirecting volume toward compliant suppliers.
- Ketogenic positioning:Metabolic health protocols in North American wellness clinics are normalizing carbohydrate restriction below 50 grams daily, expanding addressable demand for specialized meal formats.
- German retail channel concentration:Discounter penetration of private-label diet products in Bavaria and North Rhine-Westphalia is validating price-accessible formulation architectures.
Market Restraints
- Alternative protein input volatility:Pea and fava bean protein isolate costs fluctuate with Canadian and Australian harvest cycles, destabilizing low-fat reformulation economics.
- EFSA novel food timelines:European approval pathways for fermentation-derived proteins extend 18-36 months, freezing product pipeline velocity for Atlantic market entrants.
- Clean-label substitution:Whole-foods-based meal prep services capture experimental users before they convert to packaged diet products, truncating lifetime value.
Strategic Opportunities
- Subscription delivery models:Direct-to-consumer refrigerated logistics in the United States bypass slotting fee barriers that constrain conventional retail entry.
- Cellular agriculture convergence:Precision fermentation of dairy proteins enables fat-free cheese analogues with superior melt characteristics versus starch-based alternatives.
- India FSSAI functional food pathway:Emerging regulatory clarity for protein-fortified meal replacements opens formal channel access for reformulated export portfolios.
Industry Challenges
- Sensory science talent scarcity:Formulation chemists capable of masking alternative protein off-notes in low-fat matrices command premium compensation, inflating R&D overhead.
- Dual certification complexity:Simultaneous USDA Organic and Non-GMO Project verification extends quality assurance timelines, delaying seasonal product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Carb and Low Fat Diet Market |
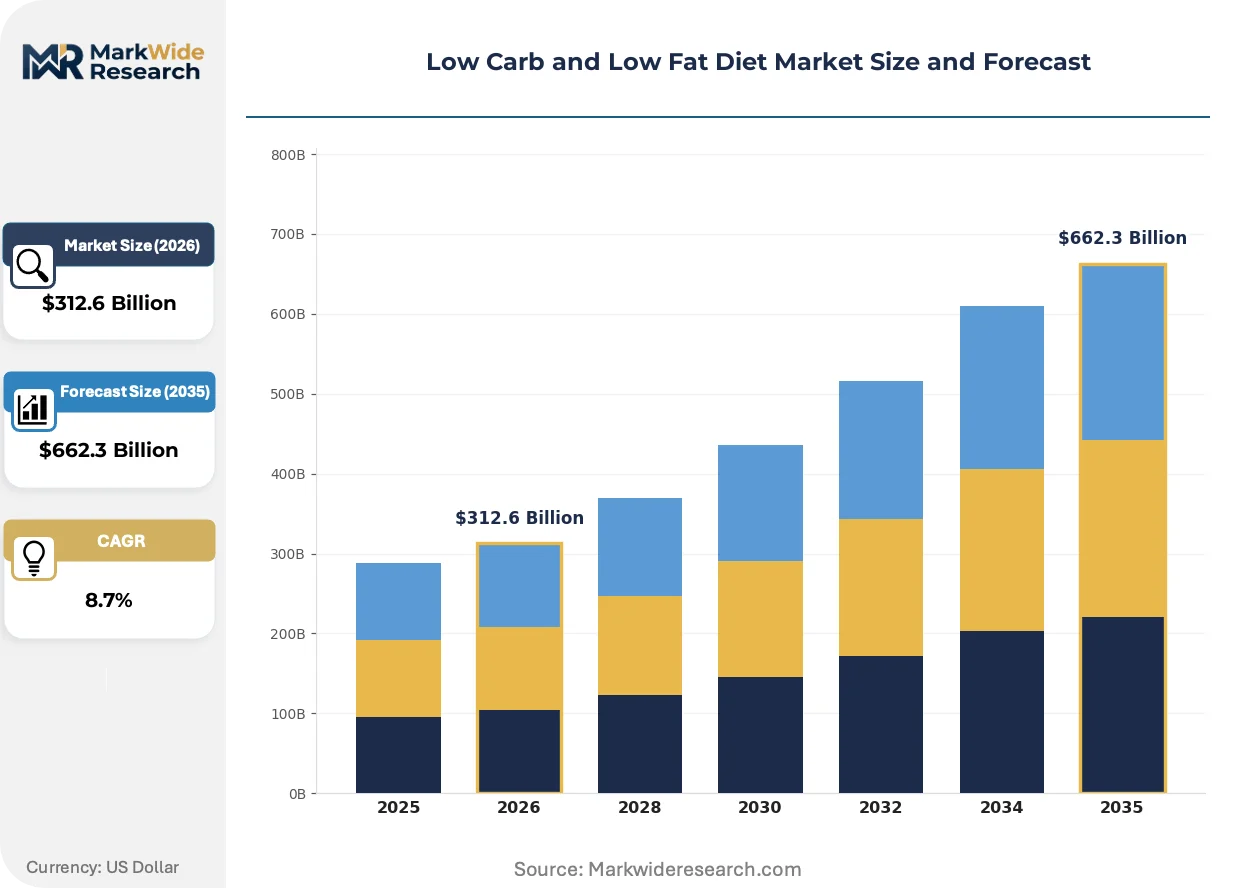
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Diet Type: Keto, Paleo, Atkins, Mediterranean Product Category: Snack Bars, Meal Replacements, Supplements, Frozen Meals Consumption Setting: Home, Gym, Office, Travel Target Demographic: Fitness Enthusiasts, Weight Watchers, Athletes, Health-Conscious Consumers |
| Companies Covered | Nestlé S.A., Unilever Plc, General Mills Inc., The Kraft Heinz Company, Danone S.A., PepsiCo Inc., Conagra Brands, Atkins Nutritionals Inc., Cargill Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Carb and Low Fat Diet Market Evolving Landscape
Digital traceability infrastructure and precision nutrition platforms are reconfiguring how consumers evaluate macronutrient claims, shifting competitive advantage toward data-transparent supply chains.
Extrusion texturization of high-moisture protein isolates is automating the production of whole-muscle meat analogues with sub-5% fat content. European foodservice distributors are adopting these systems for institutional catering contracts. The technology is automating labor-intensive forming processes that previously limited scale in plant-based low-fat categories.
EFSA front-of-pack nutrition labeling mandates entering force across EU member states are compelling reformulation of products exceeding salt or saturated fat thresholds. Manufacturers face portfolio pruning or ingredient substitution decisions by enforcement deadlines. Mediterranean diet-positioned SKUs with heritage recipes are most exposed, accelerating clean-label renovation cycles.
Healthcare provider endorsement protocols are replacing influencer marketing as the primary trust mechanism for metabolic diet adoption. Endocrinology clinics in the United States now prescribe specific meal replacement brands, bypassing retail discovery friction. This channel consolidation concentrates volume with suppliers maintaining clinical trial dossiers and pharmacy distribution agreements.
Low Carb and Low Fat Diet Market Segmentation
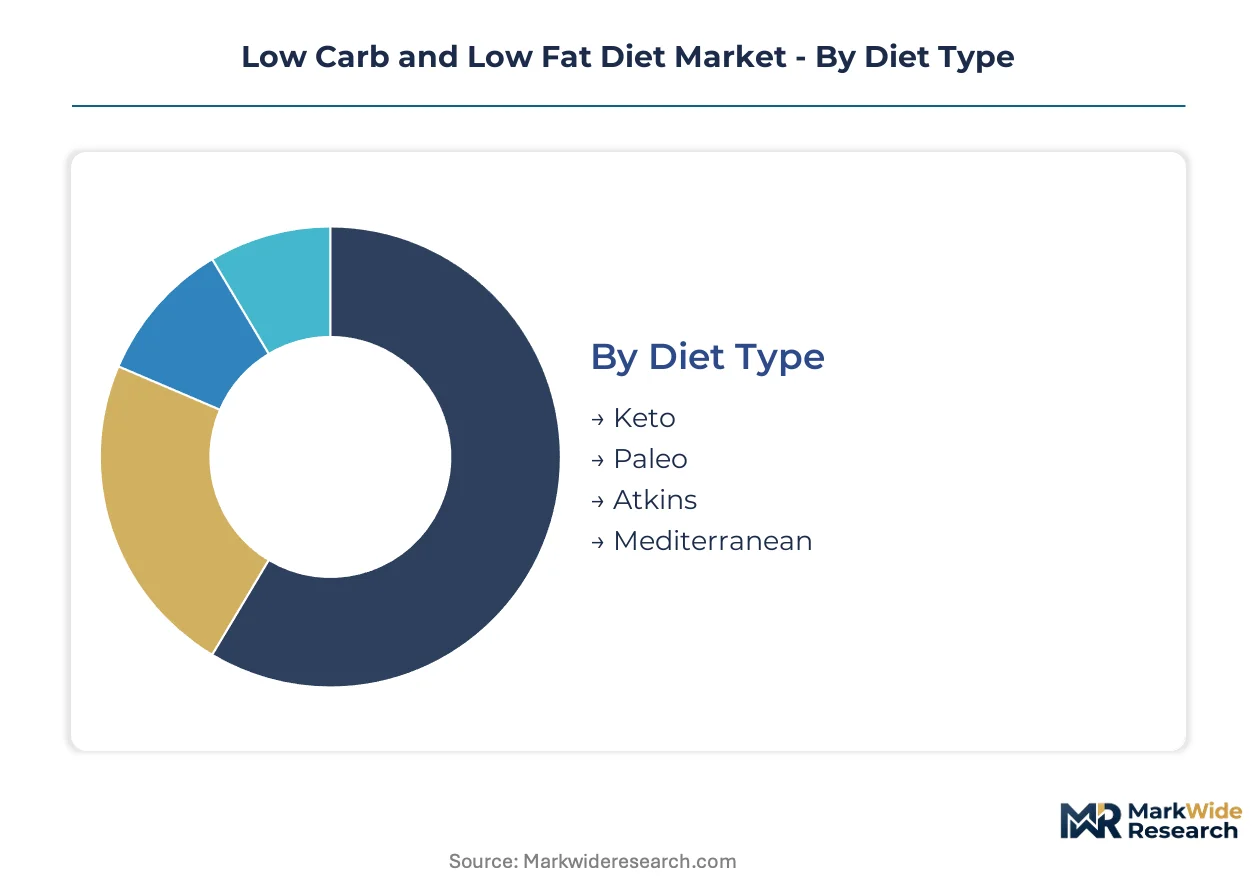
Segmentation in the low carb and low fat diet market reveals divergent margin structures across metabolic protocols and consumption occasions. Manufacturers must align formulation investments with the specific compliance requirements and sensory expectations of each diet type and product format.
Diet Type:
Volume concentrates in ketogenic positioning while Mediterranean formats command premium shelf-stable pricing.
- Keto:Carbohydrate restriction below 50 grams daily drives demand for high-fat, moderate-protein formulations with specific ketone-inducing macronutrient ratios. United States wellness clinics and direct-to-consumer subscription channels concentrate volume for this segment.
- Atkins:Phased carbohydrate reintroduction protocols require product lines spanning induction-phase shakes through maintenance-phase snacks. North American grocery channels maintain dedicated planogram space for this established brand architecture.
- Paleo:Grain-free, dairy-free positioning appeals to ancestral health consumers seeking whole-food ingredient lists without synthetic additives.
- Mediterranean:Olive oil and seafood-centric formulations occupy mature retail segments with slower velocity but established repeat purchase patterns among aging demographics.
Mature deployment sits with Mediterranean formats in European retail. Newer deployment is concentrated in keto positioning across United States digital health platforms.
Product Category:
Application context determines whether consumers prioritize convenience, satiety duration, or macronutrient precision.
- Meal Replacements:Complete nutrition shakes and powders engineered for 200-400 calorie servings with controlled glycemic response. Subscription delivery models in the United States bypass conventional retail slotting fees and capture recurring revenue pools.
- Snack Bars:Portion-controlled formats face commoditization pressure from private-label entrants, compressing margin structures for mid-tier manufacturers dependent on conventional grocery distribution.
- Supplements:Exogenous ketones, MCT oils, and micronutrient fortifications address specific metabolic support needs.
- Frozen Meals:Refrigerated logistics requirements limit distribution radius but enable superior texture versus shelf-stable alternatives.
Meal replacements are gaining share fastest through direct-to-consumer channels. Snack bars remain the volume anchor in conventional retail.
Consumption Setting:
Occasion-based positioning determines packaging format, shelf stability requirements, and permissible price points.
- Home:Bulk formats and multi-serve containers dominate pantry stocking behavior with lower per-serving cost thresholds.
- Gym:Single-serve protein shakes and bars optimized for immediate post-workout consumption with portable packaging.
- Office:Desk-drawer storable formats with minimal preparation requirements and discrete consumption profiles.
- Travel:Shelf-stable, TSA-compliant packaging with extended ambient temperature tolerance for airport and hotel consumption.
Home consumption anchors volume for frozen meal and bulk supplement formats. Travel-oriented packaging is expanding most quickly through airport retail and hospitality partnerships.
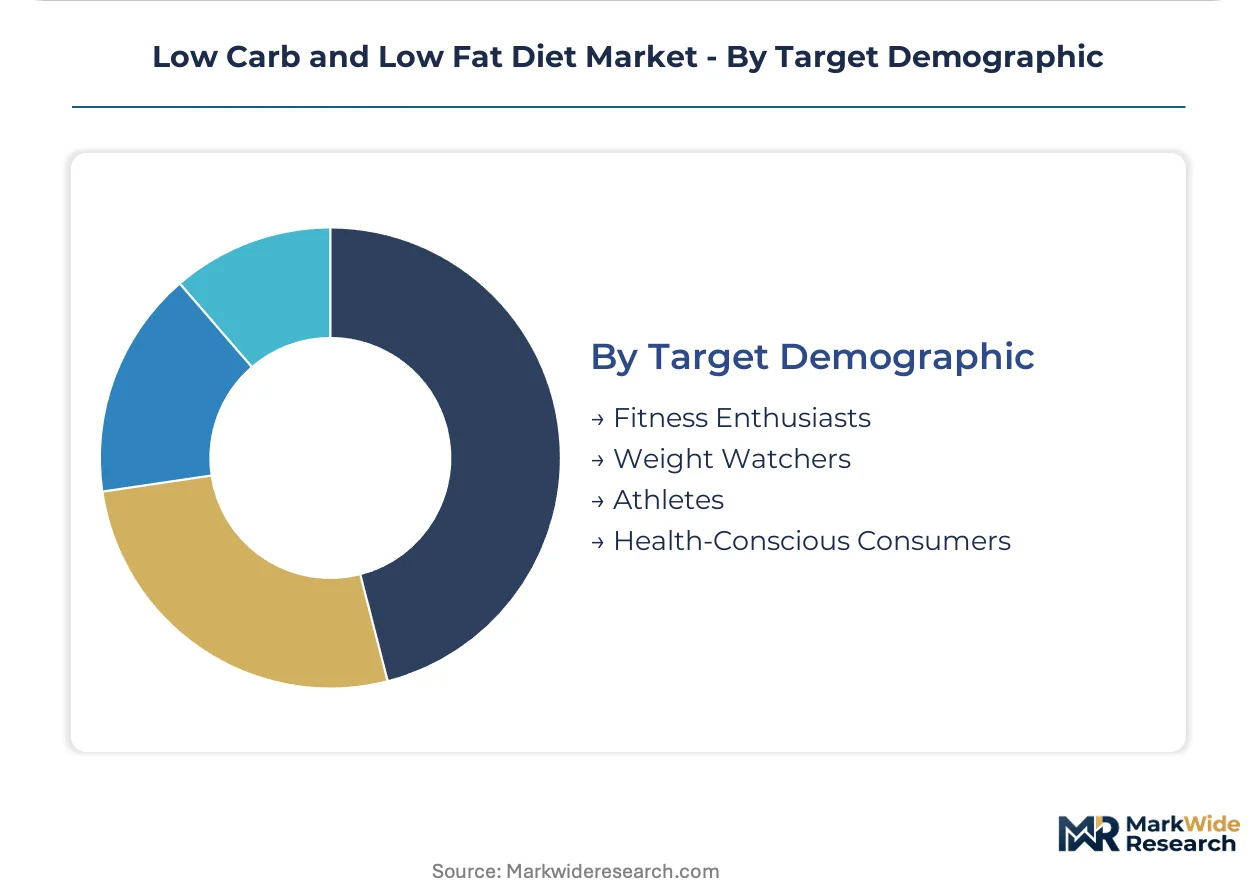
Target Demographic:
Customer lifetime value varies sharply between transient weight-loss seekers and sustained lifestyle adopters.
- Weight Watchers:Calorie-conscious consumers prioritizing portion control and behavioral tracking tools with higher churn rates but larger initial addressable population.
- Fitness Enthusiasts:Body composition-focused buyers seeking protein optimization and recovery support with strong brand loyalty and repeat purchase velocity.
- Athletes:Performance-oriented consumers requiring batch-tested formulations with specific ergogenic claims and third-party certification.
- Health-Conscious Consumers:Preventive wellness adopters integrating diet products into broader lifestyle modifications with highest lifetime value but longest conversion funnels.
Fitness enthusiasts represent the most concentrated revenue pool for premium positioning. Health-conscious consumers are climbing the fastest as metabolic health awareness expands beyond clinical populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European low-carb formulation activity through Bavarian retail concentration and proximity to EFSA regulatory infrastructure. Discounter penetration in Germany validates price-accessible architectures before Atlantic export.
United States
Wellness clinics in California and Texas normalize ketogenic protocols below 50 grams daily carbohydrate intake. FDA labeling requirements tighten permissible health claims on packaging. Direct-to-consumer subscription channels in Austin and Los Angeles bypass conventional grocery slotting fees through refrigerated logistics networks.
Germany
Bavaria and North Rhine-Westphalia concentrate private-label diet product demand through discounter retail density. EFSA front-of-pack nutrition labeling mandates compel reformulation of salt and saturated fat thresholds. Cologne-Düsseldorf corridor hosts formulation R&D clusters serving Atlantic market export requirements.
India
Maharashtra and Karnataka drive protein-fortified meal replacement demand through urban health-conscious consumers. FSSAI functional food pathway clarity opens formal channel access for reformulated export portfolios. Mumbai-Pune industrial belt concentrates contract manufacturing capacity for international brand licensing.
United Kingdom
London and Southeast England concentrate premium organic positioning demand through health-conscious aging demographics. NHS procurement criteria for reduced-fat hospital foodservice redirect institutional volume toward compliant suppliers. Cambridge-Oxford corridor anchors metabolic health research partnerships with meal replacement brands.
Japan
Tokyo and Osaka metropolitan areas sustain mature Mediterranean-format shelf-stable segments with established repeat purchase patterns. METI standards influence clean-label renovation timelines for export-oriented manufacturers. Kanto region hosts precision fermentation R&D for dairy protein analogues.
Low Carb and Low Fat Diet Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and clinical validation tiers. The vendor base stratifies between multinational CPG conglomerates with refrigerated distribution networks and specialized metabolic health brands with direct-to-consumer infrastructure. Three archetypes dominate: diversified nutrition conglomerates leveraging cross-category R&D, ketogenic specialists anchoring clinical endorsement protocols, and private-label suppliers capturing discounter volume. Competitive moves concentrate on portfolio diversification into precision fermentation and geographic expansion through regulatory pathway arbitrage.
Within the diversified conglomerate tier, Nestlé S.A. and Unilever Plc exemplify scale-driven formulation investment across refrigerated and shelf-stable portfolios. Atkins Nutritionals Inc. occupies a specialized position representing ketogenic archetype concentration in North American clinical and grocery channels. These three entities anchor competitive intensity through divergent margin structures and channel access strategies.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Unilever Plc |
| General Mills Inc. |
| The Kraft Heinz Company |
| Danone S.A. |
| PepsiCo Inc. |
| Conagra Brands |
| Atkins Nutritionals Inc. |
| Cargill Incorporated |
| Others |
Value Network & Pricing Analysis
Formulation chemists with sensory masking expertise in the Cologne-Düsseldorf corridor command premium compensation packages that widen spreads between clinical-grade and mass-market pricing tiers. Labor scarcity in protein texturization R&D inflates overhead for mid-tier manufacturers while conglomerates absorb these costs through cross-category scale.
Pricing Analysis
Outcome-based pricing anchored to metabolic health metrics dominates clinical endorsement channels, with meal replacement subscriptions commanding recurring revenue premiums over transactional snack bar purchases. Certification grade separates USDA Organic and Non-GMO Project verified SKUs from conventional formulations, while volume scale drives discounter private-label economics in German retail. Cost compression in snack bar tiers intensifies because private-label entrants erode brand premiums. Weight Watchers segments exhibit highest price sensitivity; fitness enthusiasts and clinic-prescribed users show lowest elasticity due to performance-linked perceived value.
Supply Chain Analysis
Refrigerated logistics costs constrain distribution radii for high-moisture protein formats, privileging regional production hubs over centralized manufacturing. Canada and Australia anchor pea and fava bean protein isolate supply, while precision fermentation capacity concentrates in the United States and Netherlands for dairy protein analogues. Input volatility from Canadian harvest cycles creates commodity price exposure for low-fat reformulators. Distribution runs through direct-to-consumer subscription networks in Austin and Los Angeles, bypassing conventional grocery slotting fees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where sensory science talent scarcity props pricing power for validated clinical brands. Capacity bottlenecks in alternative protein texturization sustain margin premiums for incumbents with captive R&D pipelines.
For Market Incumbents: Anticipate private-label encroachment in snack bar categories by accelerating clean-label renovation cycles ahead of EFSA enforcement deadlines. Defensive consolidation through backward integration into Canadian pea protein processing secures input cost stability. Channel control via pharmacy distribution agreements with endocrinology clinics insulates volume from retail commoditization.
For New Entrants and Emerging Players: Launch via direct-to-consumer refrigerated logistics in the United States wellness corridor, bypassing slotting fee barriers that constrain conventional grocery entry. White-space targets include India FSSAI-compliant meal replacements for urban Maharashtra health-conscious consumers and precision fermentation-derived fat-free cheese analogues for European foodservice. Go-to-market leverage rests on clinical trial dossiers enabling healthcare provider endorsement protocols.
For Investors and Strategic Acquirers: The window for entry favors specialized metabolic health brands with direct-to-consumer infrastructure and existing pharmacy distribution agreements. Long-term viability centers on acquisition targets possessing clinical validation pipelines rather than pure retail velocity. Watch EFSA novel food approval timelines as the signal for Atlantic market pipeline velocity inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Enables fat-free dairy analogues with superior melt characteristics versus starch-based alternatives. |
| Clinical Trial Investment | Generates prescriber endorsement protocols that bypass retail discovery friction in metabolic health. |
| Direct-to-Consumer Launch | Captures recurring revenue pools through subscription models insulated from grocery slotting fees. |
| Regulatory Pathway Arbitrage | Exploits divergent EFSA and FDA timelines to accelerate product velocity across Atlantic markets. |
| Backward Integration | Secures captive supply of Canadian pea protein isolates against harvest cycle volatility. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with formulation R&D directors, retail category buyers, clinic procurement managers, and alternative protein supply specialists. FDA labeling guidance documents, EFSA novel food application databases, USDA procurement criteria, and FSSAI functional food pathway advisories provided regulatory context. Bottom-up volume modeling across diet type and product category segments triangulated against top-down macroeconomic indicators.
Granularity-level modeling operated at the SKU-positioning tier, capturing ketogenic, Atkins, Paleo, and Mediterranean protocol splits alongside meal replacement, snack bar, supplement, and frozen meal format distinctions. Consumption setting and target demographic dimensions layered occasion-based and lifetime-value segmentation across the projection horizon. CAGRs derived from historical velocity patterns in subscription versus transactional channels, with protein fortification technology adoption curves and front-of-pack labeling compliance costs as industry-specific forecast inputs.
Regulatory timeline delays, alternative protein input cost spikes, and clean-label substitution acceleration are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about enforcement consistency and consumer adherence persistence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Global CBD Beverages Market
Functional Food and Beverage
Europe Functional Water Market
Functional Food and Beverage
Protein Water Market
Functional Food and Beverage
Liquid Breakfast Products Market
Functional Food and Beverage
Functional Powdered Lipids Market
Functional Food and Beverage
Marine Functional Ingredients Market
Functional Food and Beverage
Tobacco Alternative Gum Market
Functional Food and Beverage
Functional Soda Market
Functional Food and Beverage
Middle East and Africa Protein Bar Market
Functional Food and Beverage
Adaptogen Drink Market
Functional Food and Beverage
Europe Prebiotics Market
Functional Food and Beverage
Saudi Arabia Protein Bar Market
Functional Food and Beverage
Keto Diet Market
Functional Food and Beverage
Flavored and Functional Water Market
Functional Food and Beverage
RTD Protein Beverages Market
Functional Food and Beverage
Low Fat Smoothies Market