
 Global CBD Beverages Market | 2026-2036
Global CBD Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Global CBD Beverages Market Analysis
Single-serve can formats and variety-pack bundling is expanding as the dominant configuration pattern across CBD beverages, reducing trial barriers for new consumers. Canopy Growth Corporation leverages its beverage partnership infrastructure to secure shelf placement in regulated channels. Tilray anchors its position through vertical control from cultivation to canning. Molson Coors competes by applying mainstream beverage distribution muscle to CBD-infused sparkling water lines.
CBD beverages constitute non-alcoholic drinks infused with cannabidiol extract, typically dosed between 10 and 25 milligrams per serving, manufactured through nanoemulsion or liposomal encapsulation to improve bioavailability and shelf stability. These products serve consumers seeking functional relaxation, recovery, or stress modulation without intoxication. Infused sparkling water captures the largest volume share among product types due to its parity with mainstream wellness positioning. Broad-spectrum formulations are gaining formulation share as brands navigate THC threshold regulations across jurisdictions. Online retail channels command premium pricing power, while supermarkets represent the structural battleground for mass-market conversion.
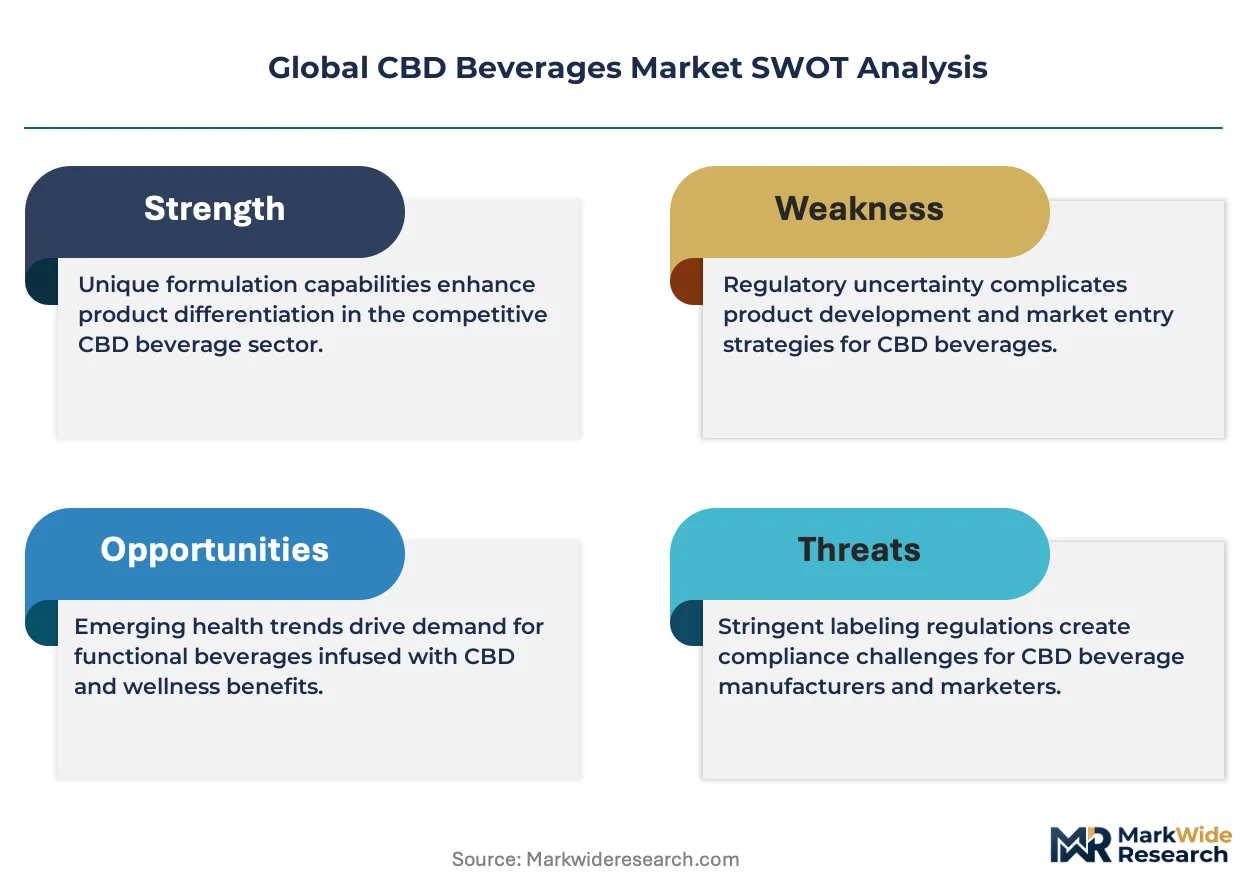
The FDA maintains prohibitions against CBD in dietary supplements and conventional foods under the Federal Food, Drug, and Cosmetic Act, creating jurisdictional tension with state-level hemp programs. EFSA's Novel Food authorization requirements in Europe impose multi-year safety dossier obligations that filter market entrants. Health Canada's Cannabis Act framework permits CBD beverages through provincial liquor boards, establishing a template for government-controlled distribution. Stakeholders must monitor regulatory divergence between federal caution and state or provincial permissiveness as the decisive variable for geographic rollout sequencing.
Market Dynamics
Federal prohibition against CBD in conventional foods under the US Federal Food, Drug, and Cosmetic Act collides with state-level hemp permissiveness, fragmenting compliance pathways and forcing manufacturers to maintain parallel formulation and labeling systems across jurisdictions.
Growth Catalysts
- State-level hemp liberalization:The 2018 Farm Bill's hemp descheduling triggered a cascade of state programs permitting CBD commerce, creating legal footholds for beverage manufacturing and retail distribution in jurisdictions like Colorado and California.
- Wellness-seeking consumption pivot:Functional beverage buyers are displacing traditional supplement regimens with drinkable formats, expanding the addressable base beyond core cannabis consumers into mainstream stress-management and recovery categories.
- Nanoemulsion bioavailability advances:Liposomal and nanoemulsion encapsulation technologies now achieve water-soluble CBD stability at commercial scale, enabling clear beverages with consistent dosing and extended shelf life previously unattainable with oil-based infusions.
Market Restraints
- FDA interstate commerce prohibition:The agency's enforcement posture against CBD in dietary supplements and conventional foods blocks mainstream retail channels, confining distribution to state-regulated hemp programs and creating liability exposure for national brands.
- Raw extract supply concentration:Hemp biomass processing clusters in Kentucky and Oregon, exposing finished beverage manufacturers to single-region weather risk and extraction capacity bottlenecks during harvest windows.
- THC threshold detection uncertainty:Broad-spectrum formulations risk hot-batch contamination from residual THC, triggering product recalls and regulatory sanctions in jurisdictions with zero-tolerance enforcement.
Strategic Opportunities
- Canadian provincial liquor board channels:Health Canada's Cannabis Act framework permits CBD beverages through government-controlled distribution, offering a template for regulated retail access that bypasses private channel friction.
- Sports recovery application expansion:Athletic consumers seeking non-intoxicating anti-inflammatory support represent an underserved vertical, with endurance sports and CrossFit communities showing early adoption velocity.
- Variety-pack trial formats:Multi-flavor can assortments reduce first-purchase risk for hesitant consumers, accelerating household penetration in suburban markets where single-SKU commitment remains high.
Industry Challenges
- Novel Food dossier compilation:EFSA's multi-year safety data requirements for CBD in Europe demand toxicology investment beyond mid-cap reach, filtering market entrants and delaying EU rollout timelines.
- Co-manufacturer qualification scarcity:Beverage production facilities capable of handling hemp-derived ingredients while maintaining THC segregation protocols remain limited, constraining scale-up capacity for emerging brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global CBD Beverages Market |
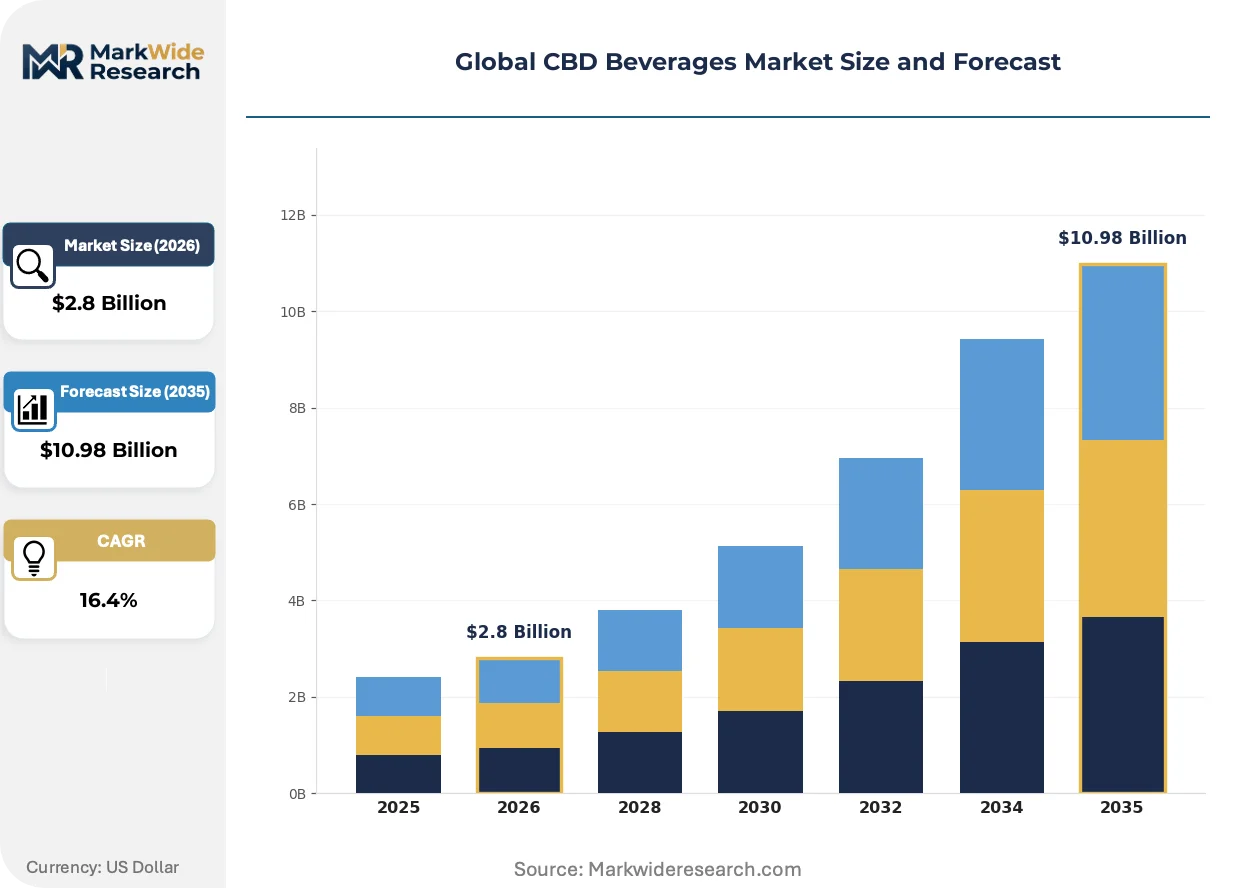
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infused Sparkling Water, CBD Tea, CBD Coffee, CBD Energy Drinks Formulation: Full-Spectrum, Broad-Spectrum, Isolate, Enhanced CBD Consumer Type: Health-Conscious, Recreational Users, Athletes, Wellness Seekers Distribution Channel: Online Retail, Specialty Stores, Convenience Stores, Supermarkets |
| Companies Covered | Canopy Growth Corporation, Tilray, Aurora Cannabis, Cronos Group, Alkaline88, Molson Coors, Hexo, BevCanna, Cannara Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global CBD Beverages Market Emerging Trajectories
Formulation science and channel configuration are converging to reshape competitive positioning, with bioavailability engineering and regulatory arbitrage defining which products achieve shelf stability and geographic reach.
Nanoemulsion technology is integrating into mainstream production workflows, converting lipophilic CBD isolates into water-compatible micelles that remain suspended in carbonated matrices. Sparkling water manufacturers adopting these systems report shelf-stable clarity at 12-month horizons. The structural consequence is compressing the quality gap between craft and mass-market entrants, as bioavailability benchmarks become table stakes rather than differentiators.
EFSA's Novel Food authorization pathway is forcing European aspirants into multi-year toxicology investment cycles, with full safety dossiers requiring reproductive and chronic exposure studies. Industrial consequence includes market consolidation around capitalized players capable of absorbing regulatory lag. German and Dutch brands with early filing advantages are capturing limited retail authorization slots before dossier backlogs extend review timelines further.
Subscription direct-to-consumer models are displacing conventional retail trial patterns, with wellness platforms bundling CBD beverages into monthly recovery regimens alongside supplements and functional foods. California and New York urban consumers show highest conversion rates, where delivery infrastructure and cannabis normalization reduce purchase friction. The channel shift is compressing brand building timelines, as digital-native entrants achieve national reach without conventional distributor relationships.
Global CBD Beverages Market Segmentation
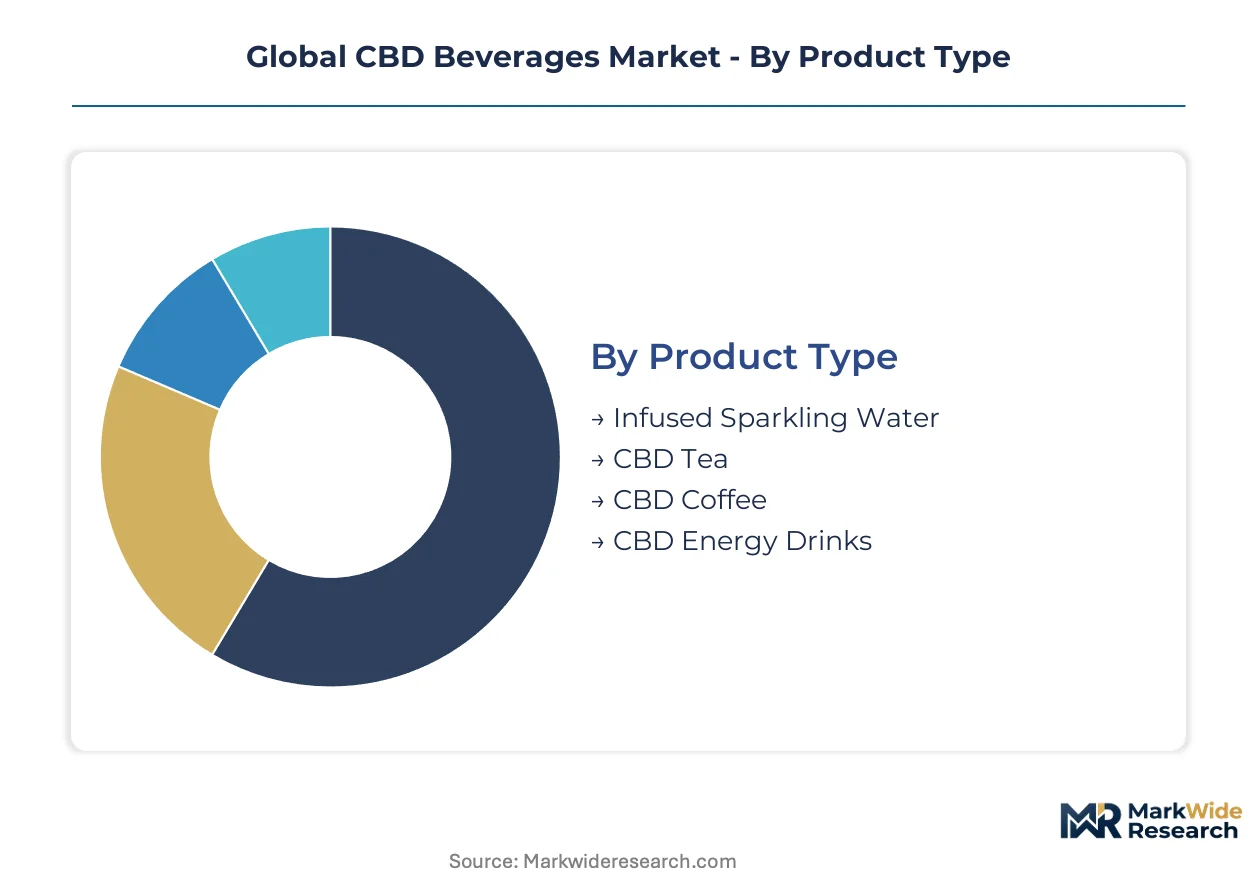
Product configuration and consumer targeting determine shelf placement and margin capture in CBD beverages. Formulation science and channel access create divergent competitive moats across each dimension.
Product Type:
Supply concentration in canning infrastructure favors carbonated formats, while extraction partnerships shape still-beverage economics.
- Infused Sparkling Water:Nanoemulsion-stabilized CBD in carbonated matrices achieves 12-month shelf clarity. Demand concentrates in United States suburban households seeking alcohol alternatives, with variety-pack bundling accelerating trial rates. State-level hemp programs in Colorado and California provide regulatory footholds for shelf-stable distribution.
- CBD Tea:Hot-fill bottling requirements and flavor degradation curves complicate manufacturing scale. Wellness seekers in Germany and Netherlands drive European demand through pharmacy and specialty channels, constrained by EFSA Novel Food authorization timelines.
- CBD Coffee:Roasted bean oil interference with CBD bioavailability demands specialized encapsulation. Ready-to-drink formats cluster in Pacific Northwest coffee culture markets.
- CBD Energy Drinks:Caffeine-CBD interaction claims face heightened regulatory scrutiny. Athletes in CrossFit and endurance communities show early adoption velocity in Canada and Australia.
Today's leader: Infused Sparkling Water. Tomorrow's challenger: CBD Energy Drinks.
Formulation:
Margin structures diverge sharply between commoditized isolates and premium-positioned spectrum offerings.
- Broad-Spectrum:THC-free formulations with retained minor cannabinoids navigate zero-tolerance enforcement jurisdictions. United States state hemp programs in Kentucky and Oregon supply biomass, with extractors investing in chromatographic THC remediation. Health-Conscious consumers pay premiums for perceived entourage effect without legal exposure.
- Isolate:Crystalline CBD offers formulation consistency and regulatory simplicity. Cost-tier positioning enables mass-market penetration in Supermarkets where THC detection risk blocks spectrum alternatives.
- Full-Spectrum:Federal prohibition under FDA enforcement posture confines distribution to intrastate hemp commerce. California and Colorado maintain viable channels.
- Enhanced CBD:Adaptogen and nootropic co-formulations target biohacker and wellness platform subscribers. Online Retail commands pricing power for these functional stacks.
Broad-Spectrum commands current premium positioning. Enhanced CBD climbs fastest on functional beverage integration.
Consumer Type:
Customer acquisition costs vary fourfold between mainstream wellness converts and legacy cannabis users.
- Wellness Seekers:Former supplement users migrating to drinkable formats represent the steepest expansion trajectory. Subscription bundling in New York and California urban corridors reduces purchase friction.
- Health-Conscious:Organic and clean-label requirements filter supplier pools. Specialty Stores in Germany and Switzerland capture this cohort through pharmacy-adjacent positioning.
- Recreational Users:Cannabis-normalized consumers seek non-intoxicating alternatives for daytime use. Convenience Stores in Canadian provincial liquor board channels serve this segment.
- Athletes:Anti-inflammatory and recovery claims require substantiation investment. Sports nutrition distributors in Australia and United States endurance markets pilot placement.
Wellness Seekers anchor volume growth. Athletes present the highest untitled lifetime value opportunity.
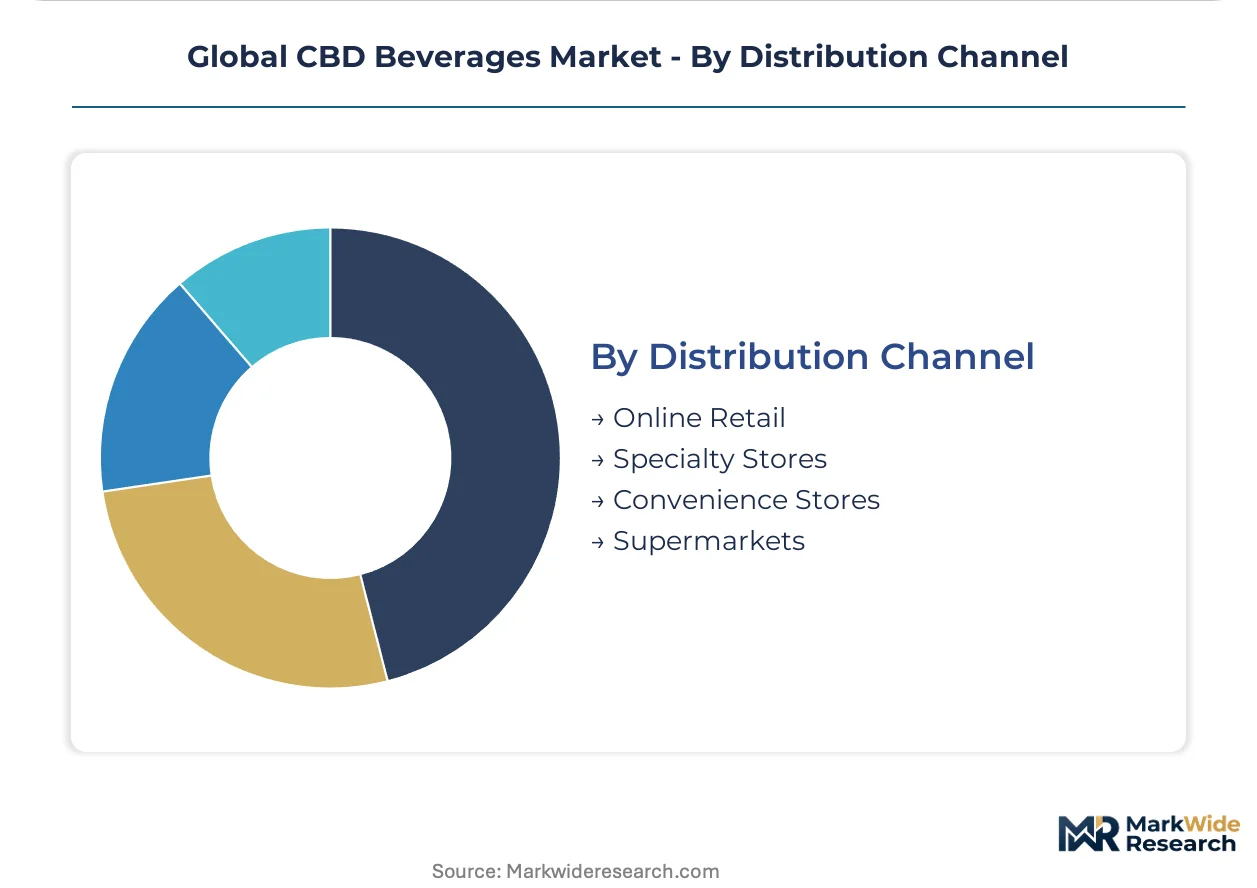
Distribution Channel:
Channel configuration determines compliance burden and customer data access tradeoffs.
- Online Retail:Direct-to-consumer models bypass FDA interstate commerce prohibition. California and New York delivery infrastructure supports subscription bundling at premium price points.
- Supermarkets:Mass-market conversion requires THC threshold documentation and liability indemnification. Canadian provincial liquor boards offer template for government-controlled distribution.
- Specialty Stores:Pharmacy and wellness retailers provide educational touchpoints for hesitant consumers. German and Dutch markets concentrate authorization slots.
- Convenience Stores:Impulse purchase dynamics favor single-serve can formats. United States state hemp program alignment determines geographic viability.
Online Retail owns current margin structure. Supermarkets determine ultimate market ceiling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The CBD beverages industry traces its commercial roots to Colorado's early state-level hemp liberalization following the 2018 Farm Bill, with subsequent scaling through California's wellness consumer base and Canada's federal cannabis framework.
United States
Wellness seekers in suburban households and CrossFit communities drive category expansion, with variety-pack formats accelerating trial rates. FDA prohibition against interstate CBD commerce in conventional foods fragments distribution to state-regulated hemp programs. Colorado and California maintain the densest manufacturing clusters, where Denver and Los Angeles area facilities pioneer nanoemulsion stabilization at commercial scale.
Canada
Recreational consumers seeking non-intoxicating daytime alternatives anchor demand through provincial liquor board channels. Health Canada's Cannabis Act framework permits CBD beverages via government-controlled distribution, bypassing private retail friction. Ontario and British Columbia concentrate production capacity, with Toronto-area canning facilities serving the Atlantic provinces.
Germany
Health-conscious consumers in pharmacy-adjacent specialty channels propel demand for organic and clean-label formulations. EFSA Novel Food authorization requirements impose multi-year safety dossier obligations that filter market entrants. North Rhine-Westphalia and Bavaria host the primary extraction and bottling infrastructure, with Cologne-area facilities navigating dossier compilation timelines.
Australia
Athletes in endurance sports and CrossFit communities represent an emerging vertical for recovery-positioned products. TGA scheduling and state-level hemp licensing create layered compliance pathways for beverage manufacturers. New South Wales and Victoria concentrate early brand development, with Sydney and Melbourne serving as test markets for sports nutrition distributor placement.
Switzerland
Pharmacy and wellness retailers provide educational touchpoints for hesitant consumers seeking THC-free broad-spectrum options. Swissmedic oversight of novel food ingredients operates with greater latitude than EFSA, enabling faster market access for compliant dossiers. Zurich and Geneva anchor the premium positioning cluster, with Lucerne-area facilities specializing in adaptogen co-formulations for biohacker segments.
Global CBD Beverages Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation sophistication and channel access tiers, with nanoemulsion patent holders and provincial board licensees commanding pricing power. The vendor base stratifies into three archetypes: legacy cannabis cultivators extending into beverages, mainstream beverage conglomerates applying distribution muscle, and digital-native wellness brands bypassing conventional retail. Consolidation pressure intensifies as capitalized players absorb regulatory compliance costs that exclude mid-tier entrants. Dominant competitive moves include strategic partnerships for shelf placement and backward integration into extraction capacity.
Within the legacy cultivator tier, Canopy Growth Corporation and Tilray occupy positions defined by beverage partnership infrastructure and vertical control from biomass to canning. Molson Coors exemplifies the mainstream beverage archetype, leveraging existing sparkling water production and distribution networks. Aurora Cannabis and Cronos Group sit within the mid-cap specialist segment, where EFSA dossier investment and Canadian provincial board access determine geographic reach.
| Leading Market Players |
|---|
| Canopy Growth Corporation |
| Tilray |
| Aurora Cannabis |
| Cronos Group |
| Alkaline88 |
| Molson Coors |
| Hexo |
| BevCanna |
| Cannara Biotech |
| Others |
Supply Flow & Price Mechanics
Isolate-to-broad-spectrum formulation divergence creates a three-tier pricing structure across premium, standard, and economy levels, with nanoemulsion patent holders in Colorado and California commanding premiums while commodity extractors in Kentucky compete on volume. This tiering maps directly onto supply chain configurations: premium players maintain captive extraction and canning infrastructure, while economy entrants rely on toll manufacturers with limited THC segregation protocols.
Pricing Analysis
Subscription-direct-to-consumer models anchored in California and New York urban corridors sustain premium pricing power through bundled wellness regimens. Price differentiation hinges on bioavailability certification and provincial board licensing, with Health Canada-authorized products commanding shelf placement premiums. Cost compression in the isolate tier intensifies as toll manufacturers add capacity, while broad-spectrum formulations face margin tightening from chromatographic THC remediation investments. Wellness seekers show lowest price sensitivity; convenience store impulse buyers drive volume at economy tiers.
Supply Chain Analysis
Health Canada and FDA facility certifications gate access to mainstream retail channels, filtering co-manufacturer pools to a handful of qualified sites. Hemp biomass supply concentrates in Kentucky, Oregon, and Colorado, with extraction capacity clustering around harvest windows. Finished beverage production draws from nanoemulsion technology licensors in California and Colorado, creating single-source vulnerability for clear-format stability. Tariff exposure on European flavor imports compounds input cost volatility. Distribution runs through provincial liquor boards in Canada and state-regulated hemp programs in the United States, with online retail bypassing interstate commerce prohibitions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global CBD Beverages Market functions as a stable compounder, with wellness-seeking consumption displacement of traditional supplements providing durable demand tailwinds across economic cycles.
For Market Incumbents: Anchor shelf position through backward integration into Kentucky and Oregon extraction capacity, securing biomass supply ahead of harvest bottlenecks. Invest in Health Canada provincial board licensing to lock government-controlled distribution channels against emerging brand encroachment. Defend against digital-native wellness platforms by co-developing subscription bundling infrastructure with existing retail partners. For New Entrants and Emerging Players: The mid-tier price-point gap between nanoemulsion-certified premiums and isolate commoditization offers entry space for sports recovery positioning. Target Australian endurance athlete communities and United States CrossFit affiliates where anti-inflammatory claims face lighter substantiation burdens. Pursue direct-to-consumer trial formats with variety-pack assortments to reduce household penetration friction before supermarket scale-up. For Investors and Strategic Acquirers: Consolidation pressure builds where EFSA Novel Food dossier investment excludes mid-cap European aspirants. Frame long-term viability around regulatory arbitrage capabilities across FDA, Health Canada, and Swissmedic jurisdictions. Acquisition target archetype: German or Dutch brands with early EFSA filing advantages and limited capital to complete toxicology cycles. Watch Health Canada provincial board expansion announcements as inflection signal for government-controlled channel growth.| Strategic Initiative | Industry Significance |
|---|---|
| Provincial Board Licensing | Health Canada authorization unlocks government-controlled retail access unavailable to private channel competitors. |
| Nanoemulsion Patent Acquisition | Liposomal stabilization technology from Colorado licensors enables 12-month shelf clarity for sparkling water formats. |
| EFSA Dossier Investment | Multi-year toxicology data compilation secures Novel Food authorization slots before European review backlogs extend. |
| Subscription Platform Integration | California and New York delivery infrastructure supports monthly bundling with supplements and functional foods. |
| Athlete Vertical Partnership | Sports nutrition distributor relationships in Australia and Canada pilot recovery-positioned placement before mass expansion. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with beverage manufacturing executives, regulatory affairs specialists at hemp processors, provincial liquor board procurement managers, and wellness platform subscription directors with secondary validation. FDA enforcement posture documentation, Health Canada Cannabis Act regulatory filings, EFSA Novel Food submission databases, and state-level hemp program statutes anchored supply-side assessment. Bottom-up SKU-level volume aggregation and top-down category spend analysis provided triangulation checks.
Segment-weighting approaches applied differential growth assumptions across formulation tiers, consumer archetypes, and channel configurations throughout the forecast period. Product type splits, geographic regulatory clusters, and distribution model penetration curves structured the analytical framework. CAGRs derived from segment-level volume trajectories and price elasticity modeling, with nanoemulsion technology adoption curves and provincial board expansion timelines as industry-specific inputs.
The model assumes a particular technology adoption path; alternative pathways for liposomal encapsulation or THC remediation chemistry would alter the outlook. Forecasts reflect documented assumptions regarding FDA enforcement continuity, EFSA review timeline stability, and Health Canada provincial board expansion pacing. Deviation in federal CBD rescheduling or interstate commerce authorization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Global Functional Foods Market
Functional Food and Beverage
Asia-Pacific Protein Bar Market
Functional Food and Beverage
Functional Shots Market
Functional Food and Beverage
Global Functional Mushrooms Market
Functional Food and Beverage
Vegan Protein Bars Market
Functional Food and Beverage
Functional Coffee Market
Functional Food and Beverage
North America Protein Bar Market
Functional Food and Beverage
Asia-Pacific Functional Beverages Market
Functional Food and Beverage
Keto Ice Cream Market
Functional Food and Beverage
Functional Powdered Lipids Market
Functional Food and Beverage
Low Fat and Low Cholesterol Diet Foods Market
Functional Food and Beverage
Vitamin Functional Water Market
Functional Food and Beverage
Low-Fat and Low Protein Diet Market
Functional Food and Beverage
Low Fat Protein Market
Functional Food and Beverage
Functional Food and Beverage Market
Functional Food and Beverage
Galacto Oligosaccharides (GOS) Market