
 Keto Diet Market | 2026-2036
Keto Diet Market Size, Share, and Industry Trends Forecast 2026-2036
Keto Diet Market Analysis
Registered dietitian expertise is collapsing across retail nutrition channels, constraining credible consumer guidance and forcing brands to build in-house clinical validation. Perfect Keto leverages physician-formulated content to sustain direct-to-consumer trust. Abbott Laboratories anchors hospital and outpatient channels with medical-grade ketogenic therapy protocols. Danone competes in dairy-adjacent ketogenic beverages through specialized fermentation processes.
The ketogenic diet induces nutritional ketosis through macronutrient ratios of approximately 70-80% fat, 15-20% protein, and 5-10% carbohydrates, primarily for metabolic management and weight control. Snacks and supplements capture the highest margin pools due to repeat purchase frequency and portability advantages. Meal plans show structural growth among diabetics seeking glycemic stability through supervised carbohydrate restriction. Ready-to-eat and bar formulations dominate convenience-oriented channels, while powdered products retain cost-sensitive fitness enthusiasts.
The US FDA monitors structure-function claims on ketogenic supplements, while the EU EFSA evaluates novel food applications for exogenous ketone ingredients. Health Canada and the UK's Food Standards Agency impose distinct compositional thresholds that fragment cross-border formulation strategies. Stakeholders must monitor evolving clinical evidence on long-term cardiovascular outcomes to anticipate potential regulatory repositioning of ketogenic positioning claims.
Market Dynamics
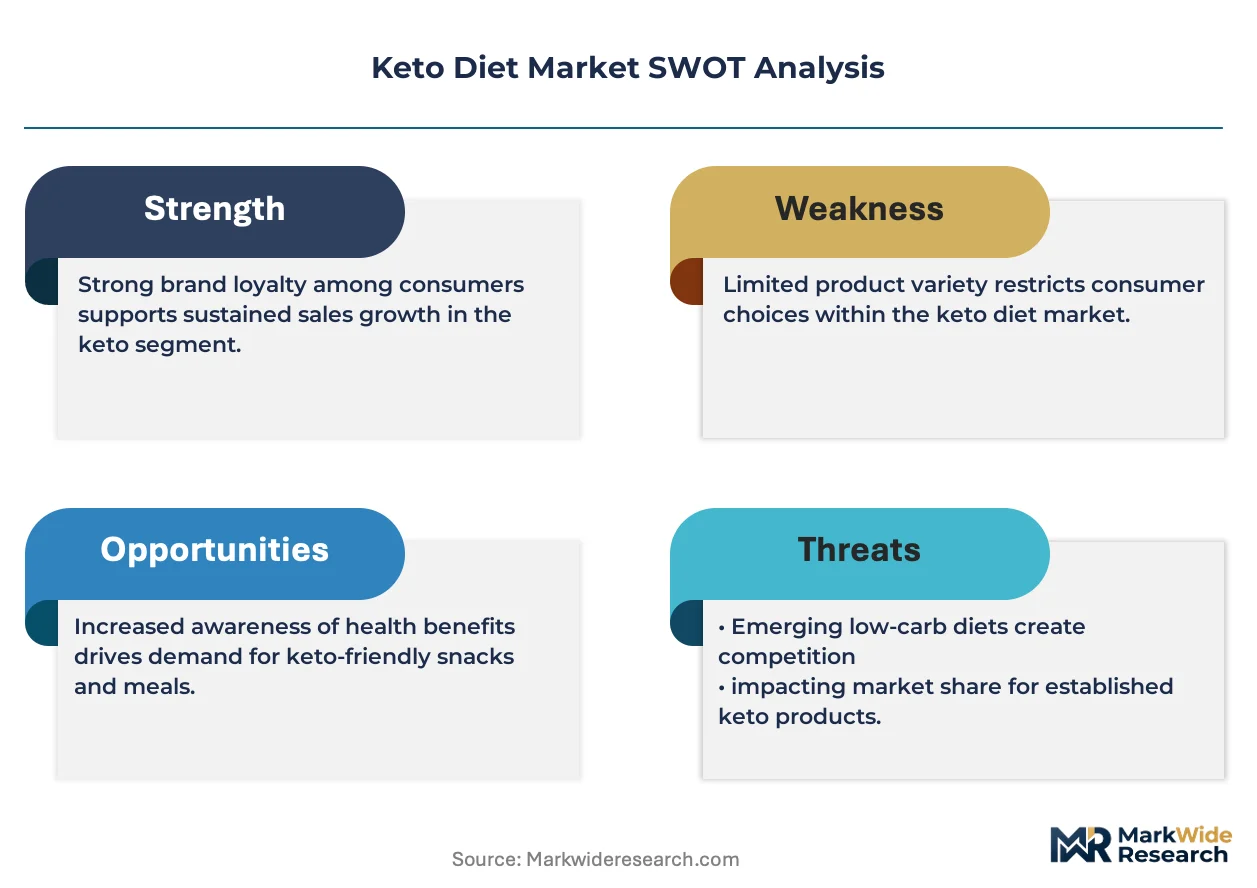
The Keto Diet Market confronts a structural compression between clinical credibility demands and mass-market convenience expectations, forcing formulation trade-offs between medical-grade precision and shelf-stable palatability.
Growth Catalysts
- Metabolic syndrome prevalence:Rising diabetes and obesity diagnoses in the United States drive physician-supervised ketogenic protocols into outpatient care, expanding reimbursable indication scope.
- EFSA novel food pathways:Streamlined approvals for exogenous ketone salts in the European Union accelerate cross-border formulation standardization and reduce regulatory duplication costs.
- Fitness platform integration:Wearable glucose monitors and continuous ketone tracking apps embed dietary adherence into quantified-self ecosystems, creating feedback-loop stickiness.
Market Restraints
- MCT oil price volatility:Coconut-derived medium-chain triglyceride supply concentrates in Southeast Asian processing clusters, exposing margin structures to weather-driven harvest shocks.
- Cardiovascular liability exposure:Long-term saturated fat intake studies generate mixed clinical signals, constraining structure-function claims and inviting FDA warning letter risk.
- Registered dietitian scarcity:Credential collapse across retail pharmacy and grocery channels eliminates credible point-of-sale guidance, elevating customer acquisition costs.
Strategic Opportunities
- Japan's functional food corridor:METI's Foods with Function Claims framework permits disease-risk reduction language unavailable in Western jurisdictions, opening premium positioning.
- Hospital-to-home transition:Epilepsy and oncology discharge protocols create recurring demand for medical-grade ketogenic meal delivery services.
- Precision fermentation convergence:Microbial lipid production platforms reduce dependency on agricultural feedstocks while enabling custom fatty acid profiles.
Industry Challenges
- Clinical validation timelines:Randomized controlled trials for weight maintenance claims require 12-24 month endpoints, compressing product development cadence against investor return expectations.
- Cross-jurisdictional labeling friction:Carbohydrate net-calculation methodologies diverge between FDA, Health Canada, and FSSAI standards, fragmenting packaging workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Keto Diet Market |
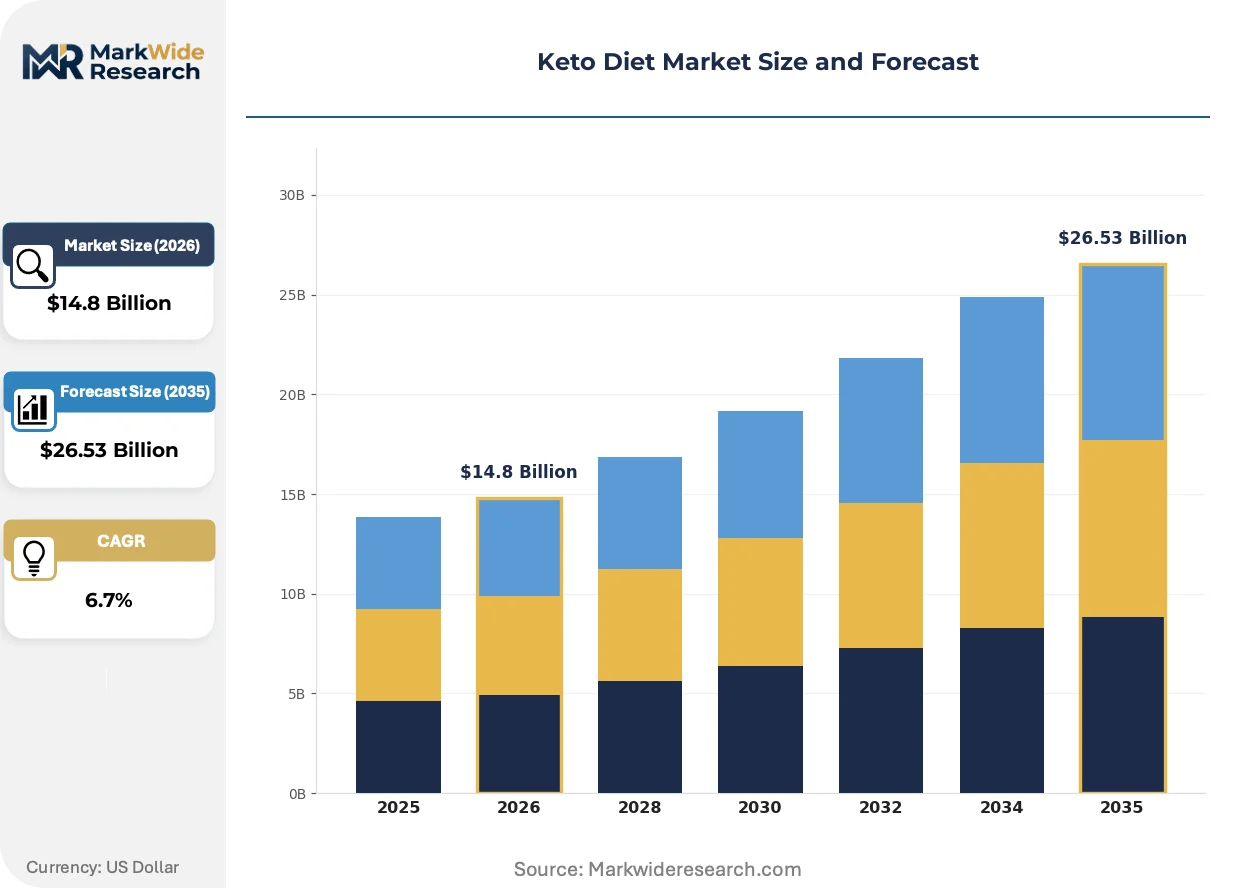
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Supplements, Meal Plans, Beverages Customer Type: Fitness Enthusiasts, Weight Loss Seekers, Health-Conscious Consumers, Diabetics Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops Formulation Type: Ready-to-Eat, Powdered, Frozen, Bar |
| Companies Covered | Nestlé, Perfect Keto, Abbott Laboratories, Danone, Bulletproof 360, Pruvit Ventures, Glanbia, Herbalife Nutrition, Zenwise Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Keto Diet Market Emerging Trajectories
Formulation science and distribution architecture are diverging sharply, with medical-grade protocols hardening at one pole and convenience-driven snackification accelerating at the other.
Exogenous ketone esters are fragmenting performance nutrition applications. Bioavailability advantages over ketone salts attract elite endurance athletes and military research programs. Cost curves remain prohibitive for mass-market penetration, concentrating adoption in sponsored athletic and clinical trial populations.
REACH-compliant novel food dossiers are reshaping European ingredient pipelines. EFSA's expanded safety assessments for synthetic ketone bodies extend approval timelines but elevate barrier-to-entry for non-compliant suppliers. German and Dutch formulators are consolidating pre-submission toxicology partnerships to amortize regulatory costs.
Subscription-based meal kit models are displacing conventional retail velocity. Direct-to-consumer platforms capture recurring revenue through personalized macro calculations and physician oversight tiers. The United States and United Kingdom show the highest subscription attach rates among English-speaking markets.
Keto Diet Market Segmentation
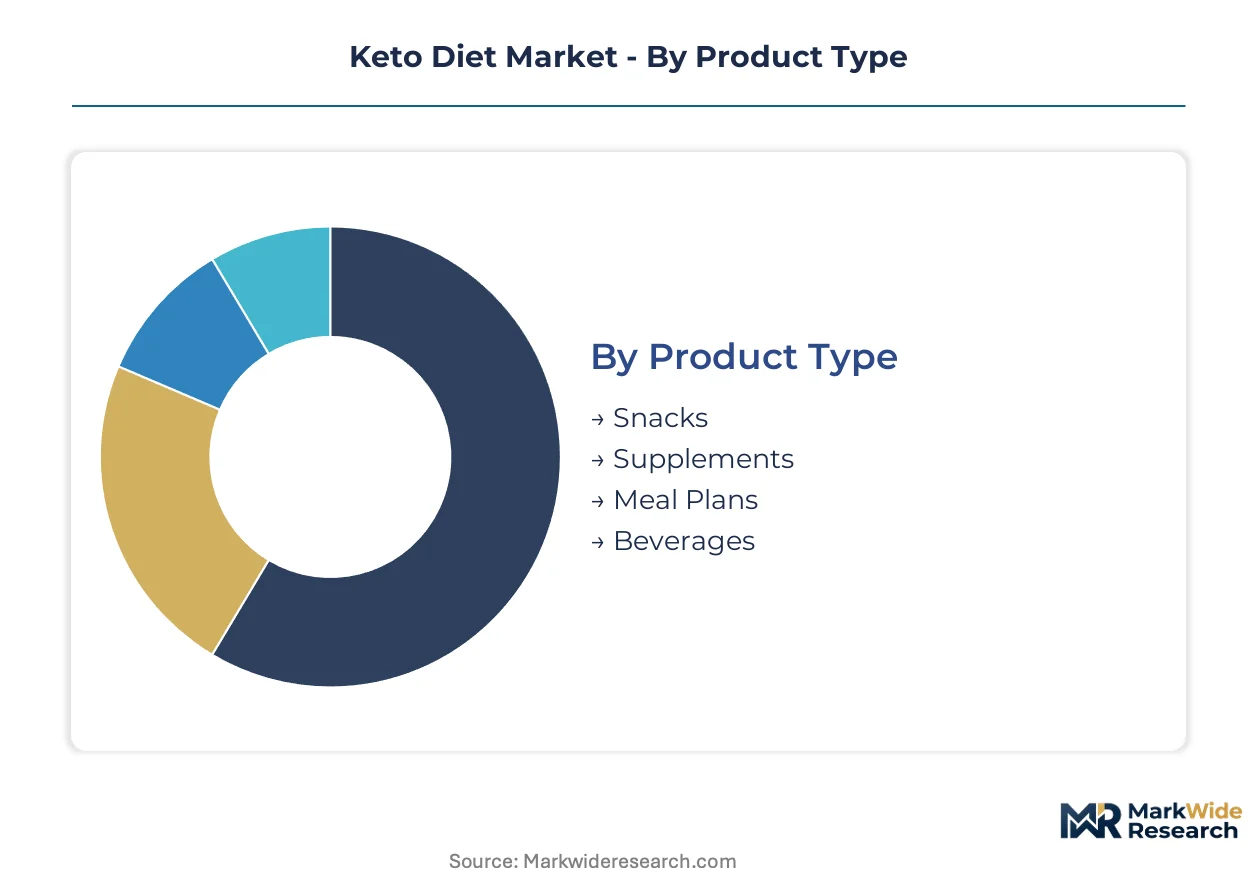
Keto diet segmentation reveals divergent margin architectures across convenience and clinical endpoints. Product form and distribution channel selection determine whether brands capture fitness-driven repeat purchases or medical-grade protocol adherence.
Product Type:
Snacks face the most acute substitution pressure from mainstream low-carb alternatives, forcing differentiation through ketone-specific functional claims.
- Snacks:Portable fat-dominant formulations including cheese crisps, nut clusters, and chocolate-fat bombs. Demand concentrates among United States office workers seeking desk-compatible adherence tools, though clean-label expectations elevate ingredient costs.
- Supplements:Exogenous ketones, MCT oils, and electrolyte complexes. Fitness enthusiasts in California and Texas drive volume through pre-workout stacking protocols, with bioavailability claims serving as the primary purchase filter.
- Meal Plans:Pre-portioned ketogenic meals with macro-calculated ratios. Diabetics seeking glycemic stability generate recurring subscription revenue.
- Beverages:Ready-to-drink ketone coffees and fat-adapted shakes. Shelf-stable formulations expand convenience store penetration.
Snacks anchors the volume base while Supplements gains share at the steepest rate.
Customer Type:
Cost tier stratification separates premium clinical oversight from mass-market self-directed adoption.
- Fitness Enthusiasts:Quantified-self adopters tracking ketone levels through wearable biosensors. Military and collegiate athletic programs in the United States sponsor exogenous ketone trials for endurance protocols.
- Weight Loss Seekers:The largest addressable cohort, though churn rates exceed other segments due to adherence difficulty. Social media influencer content drives trial conversion.
- Health-Conscious Consumers:Preventive wellness adopters integrating keto into broader metabolic optimization. United Kingdom and Australian markets show higher longevity-framing versus United States weight-loss framing.
- Diabetics:Physician-supervised patients requiring carbohydrate restriction for glycemic management. Hospital discharge protocols in Germany and the Netherlands create institutional demand.
Weight Loss Seekers delivers the broadest reach while Diabetics commands the highest per-customer lifetime value.
Distribution Channel:
Volume concentration tilts toward digital direct-to-consumer platforms, though retail placement sustains trial among non-committed purchasers.
- Online Retail:Subscription models with personalized macro coaching. Amazon and specialized keto platforms capture United States and United Kingdom recurring revenue.
- Supermarkets:Mainstream grocers in the United States expanding low-carb shelf space. Placement adjacent to diabetic-friendly products elevates credibility.
- Health Stores:GNC and Vitamin Shoppe staff recommendations influence supplement selection. In-store ketone testing drives conversion.
- Specialty Shops:Independent retailers and functional medicine clinics. Medical-grade meal plans distribute through hospital outpatient networks.
Online Retail captures margin expansion while Supermarkets provides the broadest awareness surface.
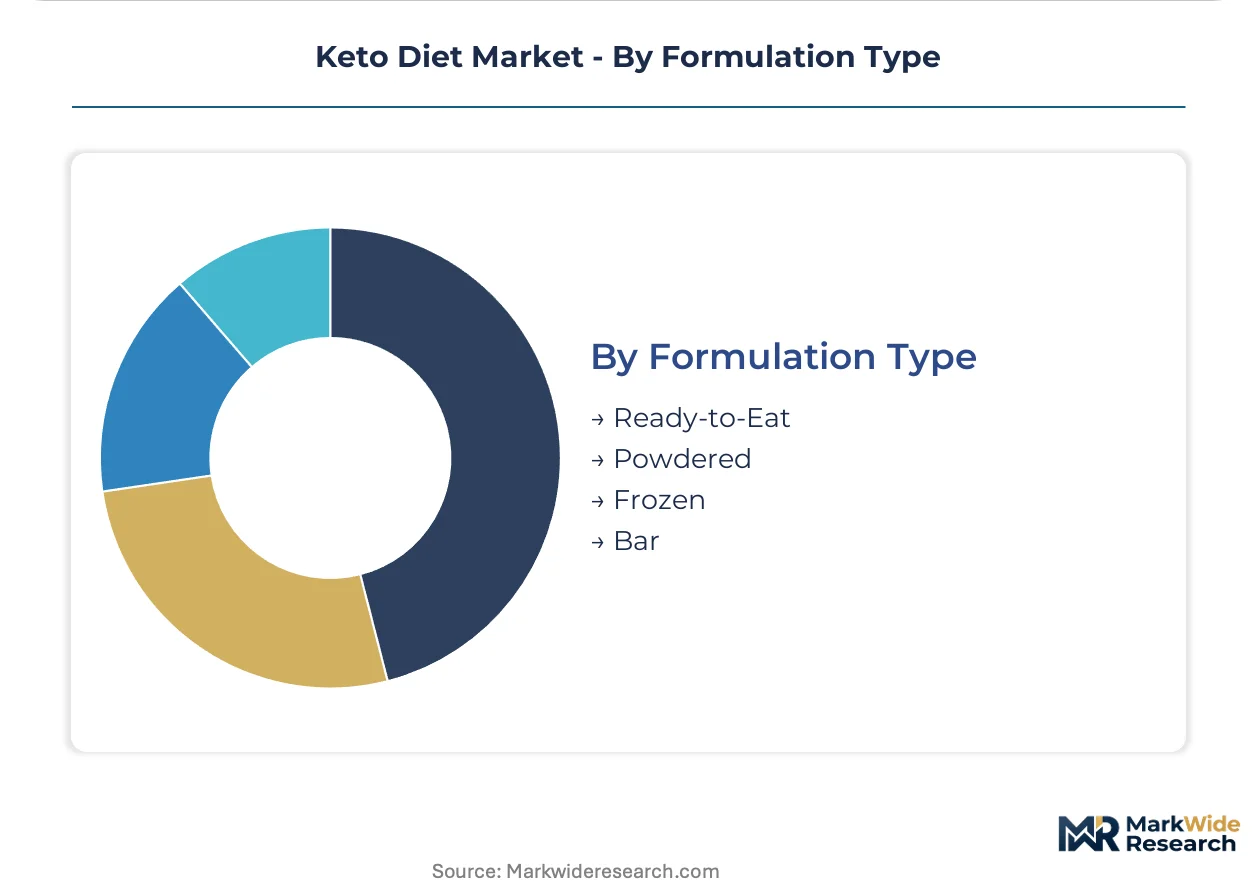
Formulation Type:
Supply concentration in Southeast Asian MCT processing clusters favors powdered and bar formats over frozen alternatives.
- Ready-to-Eat:Shelf-stable meals requiring no preparation. Travel and workplace consumption in Japan and South Korea drives format innovation.
- Powdered:Cost-sensitive fitness enthusiasts blend MCT and exogenous ketone powders. Bulk purchasing reduces per-serving economics.
- Frozen:Premium meal kits with fresh ingredients. Cold-chain logistics constrain geographic expansion.
- Bar:Macro-balanced fat-dominant nutrition bars. Convenience channel velocity in the United States and Canada sustains manufacturing scale.
Bar formulations dominate channel breadth while Powdered climbs fastest among price-sensitive adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA labeling requirements for structure-function claims anchor the United States as the regulatory reference point for ketogenic product commercialization. EFSA novel food assessments and Japan's METI Foods with Function Claims framework create divergent compliance pathways across developed markets. Regional demand patterns concentrate where metabolic syndrome prevalence intersects with digital health infrastructure.
United States
Fitness enthusiasts and diabetics drive parallel demand streams through wearable ketone tracking and physician-supervised protocols. FDA warning letters on cardiovascular structure-function claims constrain marketing language for saturated fat-dominant formulations. California and Texas host the densest concentration of exogenous ketone trials through collegiate athletic and military research programs.
Germany
Hospital discharge protocols for epilepsy and oncology patients generate institutional demand for medical-grade ketogenic meal delivery. EFSA's expanded safety assessments for synthetic ketone bodies extend ingredient approval timelines but elevate entry barriers for non-compliant suppliers. The Cologne-Düsseldorf corridor consolidates pre-submission toxicology partnerships for REACH-compliant novel food dossiers.
Japan
METI's Foods with Function Claims framework permits disease-risk reduction language unavailable in Western jurisdictions, enabling premium functional food positioning. Office workers seeking desk-compatible adherence tools accelerate ready-to-eat format innovation in Tokyo and Osaka. Domestic fermentation expertise supports specialized ketogenic dairy-adjacent beverage development.
United Kingdom
Health-conscious consumers frame ketogenic adoption around metabolic optimization and longevity rather than weight loss alone. The Food Standards Agency imposes distinct carbohydrate net-calculation methodologies that fragment cross-border packaging workflows with EU suppliers. London and Manchester show the highest subscription attach rates for personalized macro coaching platforms among English-speaking markets.
Australia
TGA oversight of complementary medicines shapes exogenous ketone supplement registration pathways distinct from food-grade positioning. Preventive wellness adopters integrate keto into broader metabolic health protocols, with Sydney and Melbourne hosting the densest functional medicine clinic networks. Bulk MCT powder purchasing among cost-sensitive fitness enthusiasts concentrates in Queensland and Victoria.
Keto Diet Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with medical-grade protocol precision commanding premium positioning against mass-market convenience optimization. The vendor base stratifies across three tiers: multinational nutrition conglomerates with hospital channel access, direct-to-consumer specialists with physician-formulated content engines, and private-label manufacturers serving price-sensitive retail placement. Dominant competitive moves include subscription-based recurring revenue model deployment and cross-jurisdictional regulatory compliance infrastructure buildout.
Within the medical-grade tier, Abbott Laboratories and Nestlé occupy positions anchored by hospital and outpatient channel relationships. Among direct-to-consumer specialists, Perfect Keto exemplifies physician-formulated content strategies for trust-based customer acquisition. Danone represents dairy-adjacent fermentation expertise applied to ketogenic beverage formats.
| Leading Market Players |
|---|
| Nestlé |
| Perfect Keto |
| Abbott Laboratories |
| Danone |
| Bulletproof 360 |
| Pruvit Ventures |
| Glanbia |
| Herbalife Nutrition |
| Zenwise Health |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts for Southeast Asian coconut-derived MCT oil lock in both supply access and forward price visibility for ketogenic formulation houses, insulating margin structures from weather-driven harvest volatility while committing capital to fixed-volume obligations.
Pricing Analysis
United States shelf-stable ketogenic snacks command 40-60% premiums over equivalent European formulations due to FDA structure-function claim compliance costs and domestic clean-label ingredient sourcing. Three-tier pricing structure across premium, standard, and economy levels separates physician-supervised meal plans from mass-market bars and private-label powders. Price differentiation hinges on clinical validation depth and geographic delivery cost. Pricing pressure stems from registered dietitian scarcity elevating customer acquisition expenses. Weight Loss Seekers exhibit highest price sensitivity; Diabetics demonstrate lowest due to reimbursable medical-grade protocol framing.
Supply Chain Analysis
Strait of Malacca transit underwrites 70% of global MCT oil movement from Indonesian and Philippine processing clusters to formulation facilities in Germany and the Netherlands. Raw material dependencies center on coconut plantation output, ketone salt precursors from Chinese chemical manufacturers, and precision fermentation feedstocks from Danish biotech platforms. Single-source vulnerability concentrates in Southeast Asian MCT fractionation capacity. Distribution runs through direct-to-consumer subscription platforms and hospital outpatient networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clinical validation expertise and cross-jurisdictional regulatory infrastructure represent acute capability scarcities, constraining new entrant viability and consolidating competitive advantage among established players with pre-built compliance architectures.
For Market Incumbents: Shield margin structures by deepening backward integration into MCT oil fractionation capacity in Indonesia and the Philippines, insulating against weather-driven supply shocks. Fortify hospital channel relationships through medical-grade ketogenic therapy protocol standardization, creating switching costs against emerging direct-to-consumer specialists. For New Entrants and Emerging Players: Differentiate on Japan's METI Foods with Function Claims framework, exploiting disease-risk reduction language unavailable in FDA or EFSA jurisdictions to command premium positioning. Target Australia's TGA-registered complementary medicines pathway for exogenous ketone supplements, leveraging lower regulatory barriers than United States FDA drug-grade positioning. For Investors and Strategic Acquirers: Capital is best deployed toward direct-to-consumer platforms with proven subscription attach rates and physician-formulated content engines, as these assets compound customer lifetime value through recurring revenue and trust-based acquisition. Watch EFSA novel food approval timelines for synthetic ketone bodies as inflection indicator for European market accessibility.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Investment | Randomized controlled trials for weight maintenance claims satisfy FDA structure-function scrutiny and differentiate from unverified competitors. |
| Cross-Jurisdictional Compliance Buildout | Parallel FDA, EFSA, and METI dossier preparation captures premium positioning in United States, European Union, and Japanese markets simultaneously. |
| Precision Fermentation Partnership | Microbial lipid production platforms reduce agricultural feedstock dependency and enable custom fatty acid profiles for medical-grade applications. |
| Subscription Model Deployment | Recurring revenue through personalized macro coaching and physician oversight tiers elevates customer lifetime value beyond transactional retail. |
| Hospital Channel Integration | Institutional relationships for epilepsy and oncology discharge protocols create predictable demand for medical-grade ketogenic meal delivery. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with regulatory affairs directors at ketogenic supplement manufacturers, clinical nutrition specialists at German and Dutch hospitals, and subscription platform executives; and secondary validation through FDA warning letter databases, EFSA novel food registers, and METI Foods with Function Claims approvals. Bottom-up and top-down triangulation cross-checked volume estimates against customs records for MCT oil imports and hospital procurement databases for medical-grade meal plan contracts.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product form, customer archetype, distribution channel, and formulation type, with CAGRs derived from trend extrapolation of wearable ketone tracker adoption rates and physician-supervised protocol expansion. Industry-specific inputs incorporated metabolic syndrome prevalence trajectories and continuous glucose monitor penetration curves.
Forecasts assume regulatory continuity in FDA structure-function claim enforcement and EFSA novel food assessment protocols; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as long-term cardiovascular outcome data and saturated fat liability exposure evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Tobacco Alternative Gum Market
Functional Food and Beverage
Global Functional Drinks Market
Functional Food and Beverage
Functional Coffee Market
Functional Food and Beverage
Vegan Protein Bars Market
Functional Food and Beverage
Vitamin Functional Water Market
Functional Food and Beverage
Middle East and Africa Functional Beverages Market
Functional Food and Beverage
GCC Functional Food Market
Functional Food and Beverage
Global Functional Proteins Market
Functional Food and Beverage
Functional Beverage Market
Functional Food and Beverage
Oat Beta-Glucan Market
Functional Food and Beverage
Very Low Calorie Desserts Market
Functional Food and Beverage
Asia-Pacific Functional Water Market
Functional Food and Beverage
Asia-Pacific Functional Mushroom Market
Functional Food and Beverage
North America Functional Water Market
Functional Food and Beverage
Middle East and Africa Protein Bar Market
Functional Food and Beverage
Asia-Pacific Functional Beverages Market