
 North America Electroencephalography Devices Market | 2026-2036
North America Electroencephalography Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electroencephalography Devices Market Analytics
Software-defined seizure detection algorithms is shifting how EEG vendors monetize hardware, converting one-time device sales into recurring diagnostic service contracts. Natus Medical leverages its installed base of hospital EEG systems to sustain long-term maintenance agreements across North American neurology departments. Medtronic anchors its position through deep integration of implantable and surface EEG monitoring workflows. Cadwell Laboratories specializes in ambulatory EEG configurations that compete on portability for sleep study and home monitoring applications.
Electroencephalography devices measure electrical activity via scalp electrodes, typically sampling neural signals at 256–1024 Hz with 16–256 channel configurations for clinical and research use. These systems serve primary purposes in epilepsy diagnosis, sleep architecture analysis, and intraoperative neurophysiological monitoring. Portable systems dominate unit volumes in North America as outpatient neurology clinics expand remote monitoring capabilities, while multi-channel systems command premium positioning in academic medical centers conducting complex brain research. Wireless EEG technology represents the fastest-growing segment as latency improvements enable real-time cognitive monitoring applications outside traditional clinical settings.
FDA software-as-medical-device guidelines and HIPAA data security requirements shape product development timelines and commercialization pathways for EEG manufacturers operating in the United States. Health Canada's Medical Devices Bureau imposes parallel but distinct approval standards that Canadian market entrants must navigate separately from US regulatory pathways. Stakeholders must monitor how reimbursement codes for remote EEG interpretation evolve across provincial and private payer systems throughout North America.
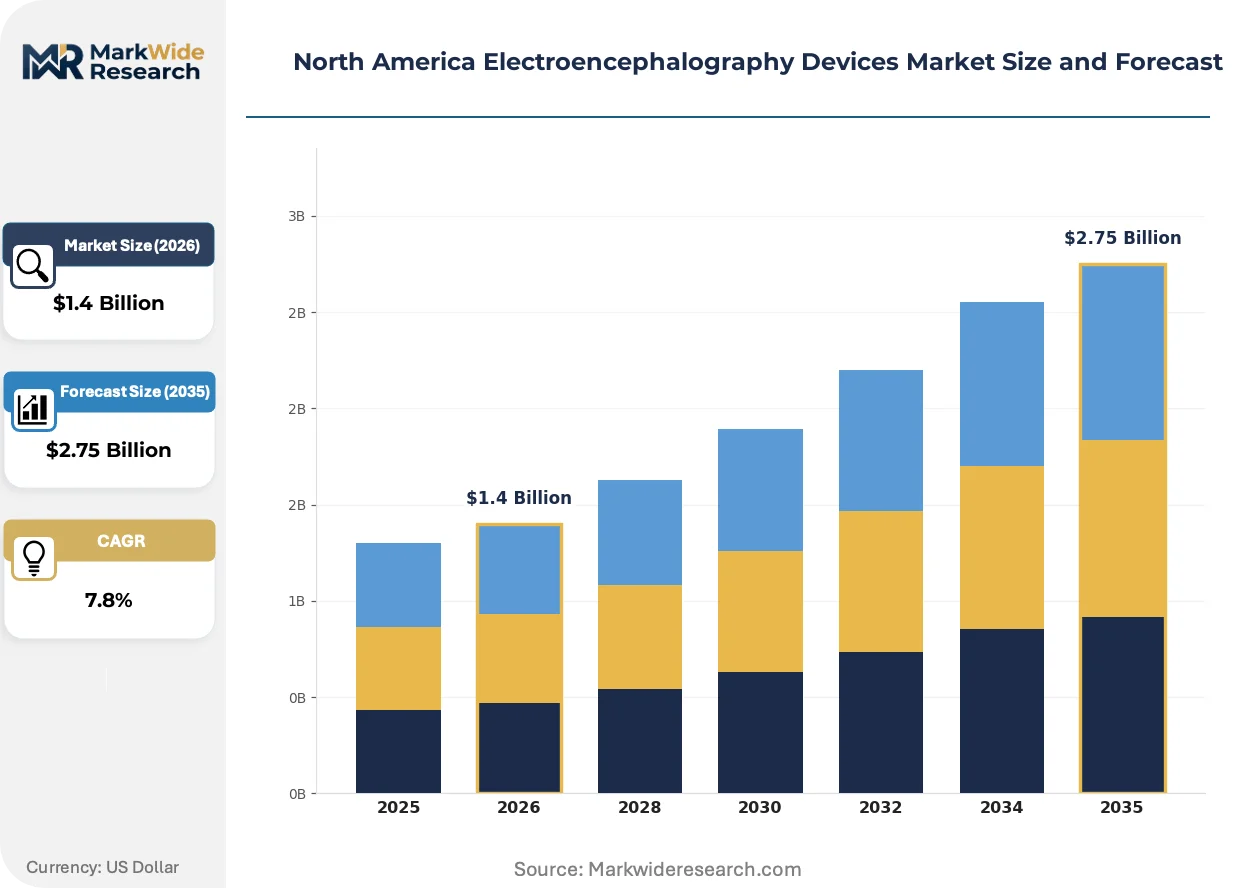
Market Dynamics
Wireless EEG platforms are compressing the traditional hospital-centric deployment model into distributed ambulatory networks, forcing hardware vendors to restructure revenue around software subscriptions and remote interpretation services rather than capital equipment sales.
Growth Catalysts
- FDA Software-as-Medical-Device Framework:Algorithm-based seizure detection tools now enter commercial use through streamlined pathways, accelerating neurodiagnostic software deployment across US hospital systems.
- California Biomedical Corridor Concentration:Research institutions and venture capital clusters in San Diego and San Francisco drive demand for high-channel-count EEG systems in precision neuroscience applications.
- Home Monitoring Technology Maturation:Latency improvements in wireless transmission enable real-time cognitive monitoring outside clinical settings, expanding addressable patient populations for ambulatory EEG vendors.
Market Restraints
- Electrode Supply Concentration:Silver-silver chloride electrode manufacturing concentrates among specialty chemical suppliers in East Asia, exposing North American EEG device makers to input cost volatility and single-source risk.
- HIPAA Data Security Compliance:Cloud-based EEG interpretation services face stringent encryption and access-control mandates that extend product development timelines and inflate operational overhead for software vendors.
- Substitute Modalities:Magnetoencephalography and functional near-infrared spectroscopy capture share in pre-surgical epilepsy mapping and brain-computer interface research, constraining premium EEG system pricing power.
Strategic Opportunities
- Canadian Provincial Expansion:Underpenetrated remote EEG interpretation services across Ontario and Quebec's rural health networks offer first-mover advantages for US-based telemedicine platform operators.
- Sleep Architecture Monitoring Convergence:Integration of EEG with polysomnography workflows in home sleep apnea testing creates new reimbursement pathways through US Medicare remote patient monitoring codes.
- AI-Assisted Diagnostic Mandates:Emerging payer requirements for algorithmic quality assurance in neurological interpretation favor vendors with validated machine-learning pipelines over legacy hardware-only suppliers.
Industry Challenges
- Clinical Neurophysiologist Shortage:Board-certified epileptologists and technologists remain scarce across US Midwest and Mountain West regions, creating bottlenecks for EEG service expansion regardless of hardware availability.
- Legacy System Integration Friction:Hospital IT departments struggle to synchronize proprietary EEG data formats from installed base equipment with modern cloud analytics platforms, delaying upgrade cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electroencephalography Devices Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.75 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Systems, Desktop Systems, Wireless Systems, Multi-Channel Systems End User: Hospitals, Research Institutions, Neurology Clinics, Home Care Settings Technology: Digital EEG, Analog EEG, Wireless EEG, Software-Based EEG Application: Seizure Detection, Sleep Studies, Brain Research, Cognitive Monitoring |
| Companies Covered | Natus Medical, Medtronic, Nihon Kohden, Electrical Geodesics, Cadwell Laboratories, Compumedics, NeuroWave Systems, NeuroSky, Lifelines Neuro, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electroencephalography Devices Market Evolving Landscape
Algorithmic diagnostic capabilities are decoupling from hardware form factors, enabling software vendors to capture value through recurring service contracts while commoditizing the underlying electrode and amplifier assemblies.
Dry electrode arrays are modularizing the traditional wet-electrode preparation workflow, eliminating conductive gel application time and reducing technician labor costs. Outpatient neurology clinics in Texas and Florida are adopting these systems for rapid seizure screening protocols. This technology is modularizing the patient throughput economics of ambulatory monitoring, compressing appointment durations from ninety minutes to under thirty minutes per study.
Health Canada's Medical Devices Bureau is tightening software validation requirements for EEG-based diagnostic algorithms, mandating clinical evidence packages that parallel FDA premarket submission standards. Canadian market entrants now face parallel but distinct approval pathways that extend commercialization timelines. Sleep medicine and epilepsy monitoring applications are most affected, with vendors restructuring regulatory affairs teams to manage dual-track submissions.
Telemedicine platforms are unbundling traditional EEG interpretation from hardware acquisition, enabling community hospitals to access specialist reads without maintaining on-site neurophysiology departments. This channel shift displaces conventional distributor relationships in secondary and tertiary US markets. The transformation is most visible across the US Southeast, where rural health systems consolidate neurological services through centralized reading centers.
North America Electroencephalography Devices Market Segmentation
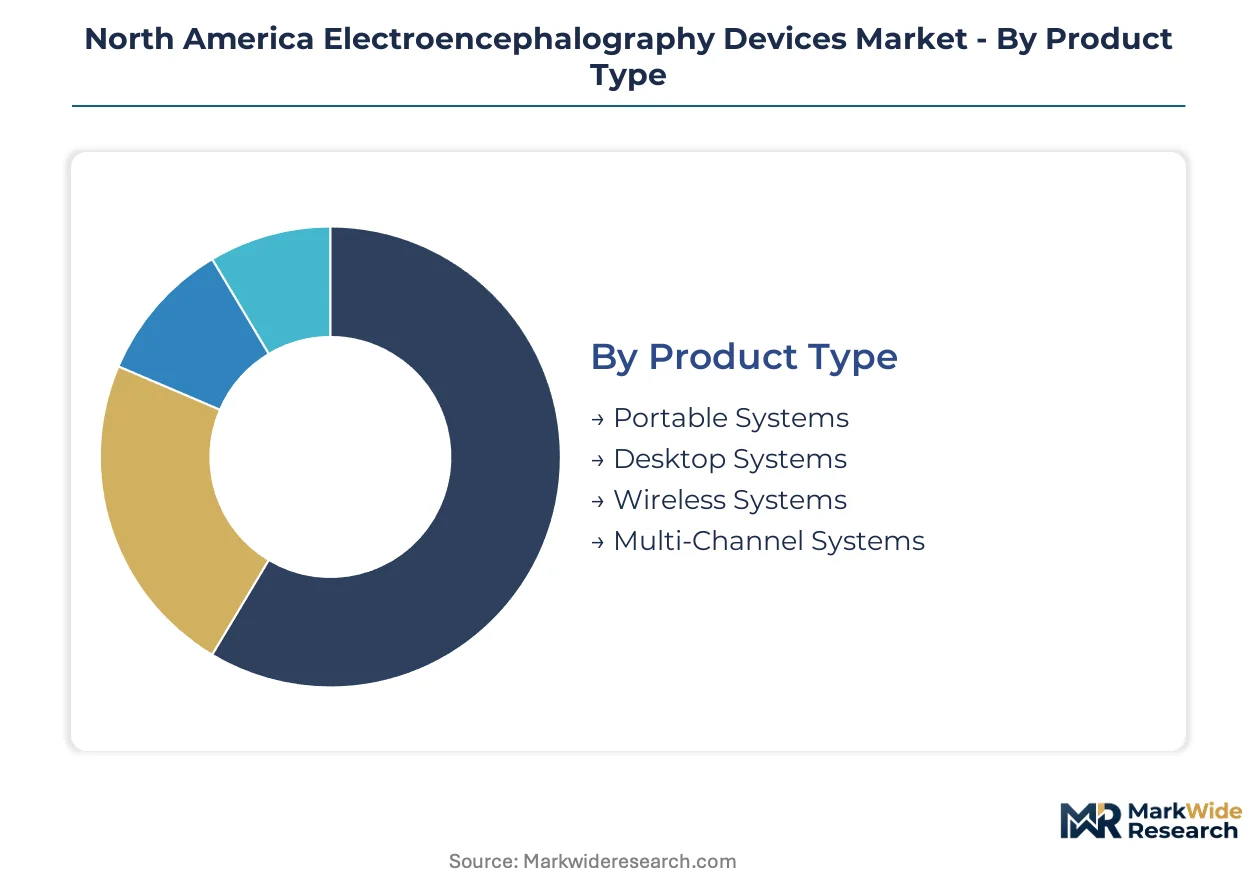
EEG device purchasing in North America follows distinct decision hierarchies across clinical, research, and ambulatory settings. Product configuration, reimbursement pathways, and integration requirements fragment demand into specialized sub-markets with diverging vendor selection criteria.
Product Type:
Capital allocation intensity separates hospital procurement committees from outpatient clinic buyers.
- Portable Systems:Battery-powered units with 16-32 channel amplifiers and tablet-based interfaces dominate unit shipments. Demand concentrates in Texas and Florida outpatient neurology clinics where rapid seizure screening protocols compress appointment throughput. Medicare remote patient monitoring reimbursement codes accelerate ambulatory deployment.
- Wireless Systems:Bluetooth and proprietary radio-frequency transmission modules eliminate tethered patient constraints. California's biomedical corridor and Boston-Cambridge neurotechnology cluster drive premium positioning for latency-critical brain-computer interface research applications.
- Desktop Systems:Stationary cart-mounted configurations with integrated video monitoring serve epilepsy monitoring units in academic medical centers.
- Multi-Channel Systems:128-256 channel high-density arrays command specialized positioning in pre-surgical mapping and precision neuroscience research.
Volume sits with Portable Systems; growth tilts toward Wireless Systems.
End User:
Reimbursement complexity and specialist availability reshape addressable populations across care settings.
- Hospitals:Inpatient epilepsy monitoring units and operating room neurophysiology suites require FDA-cleared devices with enterprise IT integration. The US Midwest and Mountain West face technologist shortages that constrain service expansion regardless of hardware availability.
- Neurology Clinics:Private practice neurologists prioritize rapid-turnaround ambulatory systems with cloud-based interpretation support. Dry electrode arrays eliminate conductive gel preparation time, compressing study durations from ninety minutes to under thirty minutes.
- Research Institutions:Academic medical centers in San Diego and San Francisco demand high-channel-count configurations for precision neuroscience applications.
- Home Care Settings:Direct-to-patient distribution models bypass traditional clinical workflows, though HIPAA encryption mandates inflate operational overhead for platform operators.
Revenue concentrates in Hospitals; expansion tilts toward Home Care Settings.
Technology:
Software-hardware decoupling restructures vendor value capture from equipment sales to recurring service contracts.
- Software-Based EEG:Algorithmic seizure detection and cloud interpretation platforms monetize through diagnostic service subscriptions rather than capital equipment transfers. FDA software-as-medical-device framework streamlines commercialization pathways for algorithm vendors.
- Wireless EEG:Low-latency transmission protocols enable real-time cognitive monitoring outside traditional clinical settings. Latency improvements expand addressable patient populations for ambulatory vendors competing on portability.
- Digital EEG:Integrated analog-to-digital conversion with artifact rejection algorithms serves standard clinical diagnostic workflows.
- Analog EEG:Legacy amplifier architectures persist in price-sensitive replacement cycles and international markets.
Installed base remains with Digital EEG; value capture migrates toward Software-Based EEG.
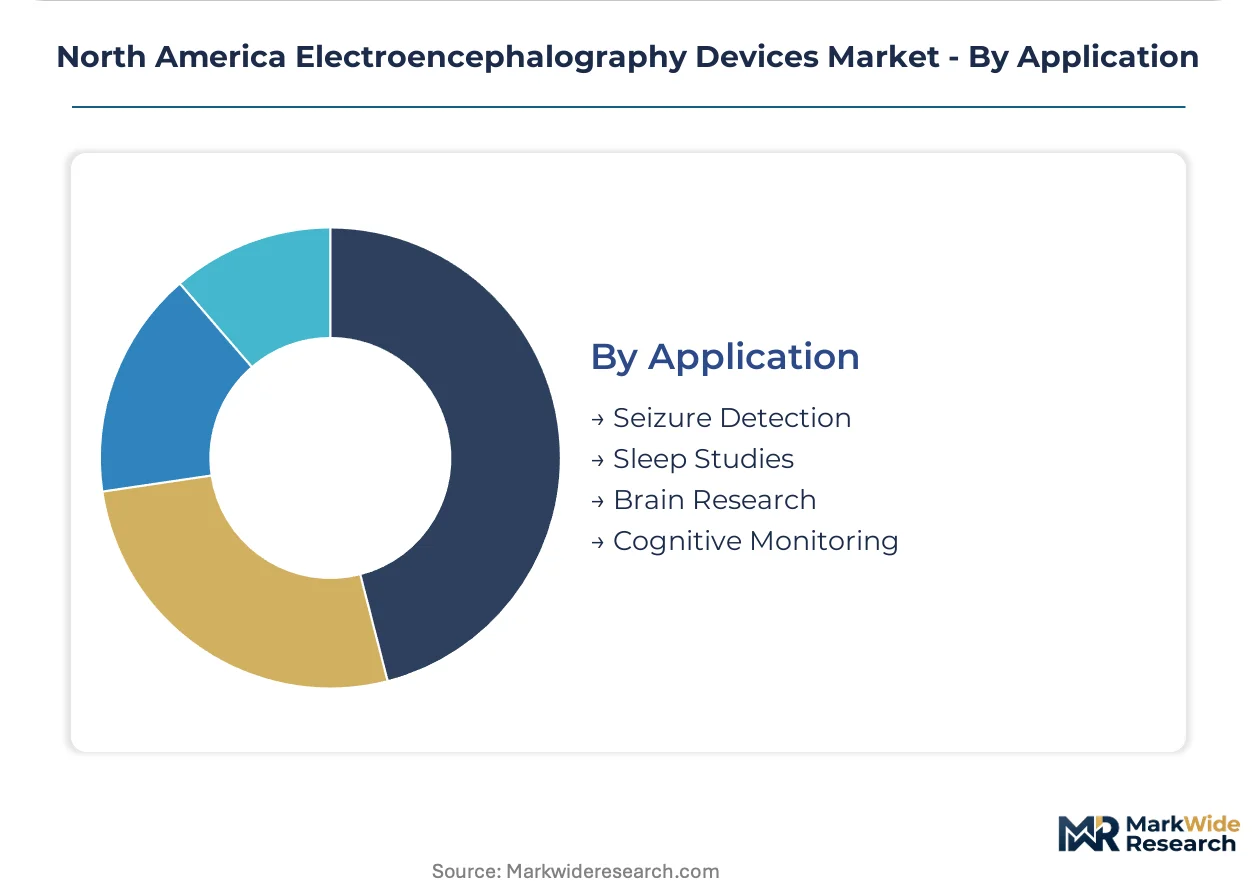
Application:
Diagnostic specificity and reimbursement code alignment determine commercial viability across use cases.
- Seizure Detection:Algorithm-based spike and rhythm analysis tools integrate with electronic health record systems for automated reporting. FDA premarket submission standards for software-as-medical-device accelerate neurodiagnostic deployment across US hospital systems.
- Sleep Studies:Polysomnography-integrated EEG channels create new reimbursement pathways through Medicare remote patient monitoring codes. Home sleep apnea testing convergence expands addressable populations beyond traditional sleep center referrals.
- Brain Research:High-density mapping for pre-surgical epilepsy evaluation and brain-computer interface development commands premium system pricing.
- Cognitive Monitoring:Real-time attention and workload assessment applications emerge in defense and aviation human factors research.
Procedure volume centers on Seizure Detection; code expansion favors Sleep Studies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of EEG device components concentrates in East Asian electrode manufacturing clusters, while consumption and clinical deployment centers on the United States and select Canadian metropolitan health networks. The United States absorbs the majority of high-channel research systems and ambulatory monitoring platforms. Canada follows with provincial health system procurement concentrated in Ontario and Quebec.
United States
Hospital epilepsy monitoring units and outpatient neurology clinics drive hardware procurement across California, Texas, and Florida. FDA software-as-medical-device guidelines accelerate commercialization of algorithm-based seizure detection tools. The Boston-Cambridge neurotechnology cluster anchors demand for wireless EEG systems in brain-computer interface research applications.
Canada
Provincial health authorities in Ontario and Quebec underwrite multi-channel system acquisitions for academic medical centers. Health Canada's Medical Devices Bureau imposes software validation requirements that parallel FDA premarket standards. Toronto and Montreal biomedical corridors concentrate research demand for high-density EEG arrays in precision neuroscience.
Mexico
Private hospital chains in Mexico City and Monterrey import portable EEG systems for neurology department expansion. Federal Commission for the Protection against Sanitary Risk (COFEPRIS) regulates medical device registration with timelines extending commercialization for foreign vendors. Northern border states access US-based telemedicine interpretation services for rural neurological care.
North America Electroencephalography Devices Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the North American EEG market. The vendor base splits between integrated hospital system suppliers and specialized ambulatory platform developers. Three archetypes dominate: legacy hardware manufacturers with installed base maintenance agreements, wireless technology specialists competing on portability, and software vendors monetizing algorithmic diagnostics through subscription contracts. M&A activity concentrates on digital health platforms acquiring remote interpretation capabilities, while strategic partnerships link electrode suppliers to device assemblers seeking supply security.
Within the integrated systems tier, Natus Medical and Medtronic occupy positions sustained by hospital maintenance agreements and implantable-surface workflow integration. Cadwell Laboratories exemplifies the ambulatory specialization archetype, competing on portability configurations for sleep study and home monitoring applications. These three entities anchor distinct competitive vectors without overlapping core positioning.
| Leading Market Players |
|---|
| Natus Medical |
| Medtronic |
| Nihon Kohden |
| Electrical Geodesics |
| Cadwell Laboratories |
| Compumedics |
| NeuroWave Systems |
| NeuroSky |
| Lifelines Neuro |
| Others |
Value Network & Pricing Analysis
Board-certified clinical neurophysiologists concentrated in California and Massachusetts command wage premiums that widen pricing spreads between premium research-grade systems and economy ambulatory configurations. Labor-cost differentials between coastal specialist hubs and Midwest technician markets translate directly into tiered service pricing for remote EEG interpretation.
Pricing Analysis
Cost-down pressure on economy-tier portable systems accelerates as Medicare remote patient monitoring reimbursement compresses margins for outpatient clinic buyers. Three-tier pricing structure across premium, standard, and economy levels separates high-channel research arrays from 32-channel clinical workhorses and 16-channel screening units. FDA software-as-medical-device certification tier and after-sales service bundling drive price differentiation. Hospital procurement committees show lowest price sensitivity; independent neurology clinics in Texas and Florida exhibit highest.
Supply Chain Analysis
ISO 13485 and FDA 21 CFR Part 820 quality system certification gates electrode suppliers before they enter North American device manufacturer supply bases. Silver-silver chloride electrode production concentrates in Japan, South Korea, and Taiwan, with amplifier assembly anchored in Mexico and Malaysia. Supply chain risk centers on single-source vulnerability for specialized conductive gel formulations. Distribution runs through GPO contracts with hospital systems and direct-to-clinic telesales for ambulatory platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Upstream electrode supply security and downstream algorithmic service revenue are becoming the twin levers in a vertical-integration race across North American EEG markets. Players capturing both ends of this value chain will command sustainable positioning.
For Market Incumbents: To counter software-only entrants disintermediating hardware margins, deepen backward integration into silver-silver chloride electrode production and lock hospital systems into long-term maintenance agreements with embedded algorithm upgrades. FDA software-as-medical-device premarket submission capabilities serve as the critical defensive moat. For New Entrants and Emerging Players: Rural health networks in Ontario and Quebec represent the most penetrable buyer archetype, underserved by specialist interpretation services and receptive to cloud-based diagnostic platforms. Target home sleep apnea testing convergence with dry electrode arrays and Medicare remote patient monitoring code alignment as the go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with algorithm-validated software vendors given emerging payer mandates for AI-assisted diagnostic quality assurance. Five-to-ten-year viability favors platforms with dual FDA and Health Canada submission capabilities. The signal to watch is provincial reimbursement code expansion for remote EEG interpretation across Canadian rural networks.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Accelerates commercialization timelines for algorithm-based seizure detection tools across US hospital systems. |
| Health Canada Parallel Approval Pathway | Unlocks provincial procurement contracts in Ontario and Quebec academic medical centers. |
| Hospital System GPO Partnership | Secures enterprise IT integration slots and multi-year maintenance agreement renewals. |
| Dry Electrode Array Development | Compresses appointment throughput economics from ninety minutes to under thirty minutes per study. |
| Reimbursement Strategy Alignment | Captures Medicare remote patient monitoring codes for home sleep apnea testing convergence applications. |
Research Methodology
FDA 510(k) premarket notification database, Health Canada Medical Devices Active Licence Listing, and CMS Medicare reimbursement code repositories formed the secondary backbone for regulatory pathway and commercial timeline validation. Primary interviews with clinical neurophysiologists, hospital biomedical engineers, GPO contracts managers, and ambulatory clinic operators combined with secondary sources through bottom-up shipment modeling and top-down expenditure reconciliation. Triangulation across these approaches anchored volume and value estimates.
Historical trendline analysis of hospital capital expenditure cycles and outpatient clinic formation rates informed the projection framework. Segmentation dimensions modeled include product configuration, end-user setting, technology architecture, and application specificity across the analysis window. CAGRs derived from weighted-average growth contributions across these segments, with specific inputs from wireless transmission latency improvement trajectories and software-as-medical-device approval velocity assumptions.
Revisions become necessary when FDA software-as-medical-device guidance scope expands, Health Canada tightens algorithm validation requirements, or Medicare remote patient monitoring reimbursement codes shift materially. A model refresh is warranted upon material change in silver electrode commodity pricing or clinical neurophysiologist workforce availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Abdominal Closure Systems Market
Medical Devices
Global Breast Implants Market
Medical Devices
Global Cardiopulmonary Bypass Accessory Equipment Market
Medical Devices
Global Microcatheter Market
Medical Devices
Global Intravenous (IV) Equipment Market
Medical Devices
North America Cataract Surgery Devices Market
Medical Devices
US Prefilled Syringes Market
Medical Devices
China Artificial Organs and Bionic Implants Market
Medical Devices
Aortic Valve Replacement Devices Market
Medical Devices
Syndesmosis Repair System Market
Medical Devices
Global Organs-On-Chips Market
Medical Devices
Autotransfusion Devices Market
Medical Devices
Facial Pumps Market
Medical Devices
Artificial Disc Replacement Market
Medical Devices
Global Medical Implants Market
Medical Devices
China Aesthetic Devices Market