
 United Kingdom Aesthetic Devices Market | 2026-2036
United Kingdom Aesthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Aesthetic Devices Market Analytics
CE marking under the Medical Devices Regulation is reorganizing competitive access across the United Kingdom aesthetic devices landscape, forcing distributors to rebuild conformity portfolios. Alma Lasers sustains technology leadership in multi-wavelength platforms for skin rejuvenation applications. Cynosure leverages its installed base of laser hair removal systems to defend clinic relationships. Merz Pharma anchors its position through specialized injectable filler formulations that dominate medical center procurement.
Aesthetic devices comprise electromechanical and energy-delivery systems engineered to output controlled thermal, optical, or acoustic energy at tissue-specific wavelengths and pulse durations, primarily serving cosmetic improvement and minimally invasive dermatological intervention. Laser devices command the largest revenue pool due to capital intensity and recurring consumable attachment, while radiofrequency platforms represent the fastest-expanding technology segment as clinicians adopt non-ablative tightening protocols. Injectable fillers occupy concentrated margin pools through premium hyaluronic acid cross-linking formulations that command repeat purchase cycles.
The Medicines and Healthcare products Regulatory Agency enforces post-market surveillance for energy-based aesthetic systems, while MHRA vigilance requirements and evolving UKCA marking timelines shape product registration strategies for EU-originated device portfolios. The Care Quality Commission inspects clinic settings where these devices deploy, creating dual compliance burdens that filter smaller operators. Stakeholders must monitor convergence between MHRA software-as-medical-device guidance and AI-enabled diagnostic attachments now entering aesthetic platforms.
Market Dynamics
CE marking reorganization under the Medical Devices Regulation is forcing distributors to rebuild conformity portfolios, while MHRA vigilance requirements and UKCA marking timelines reshape registration strategies for EU-originated device portfolios across the United Kingdom aesthetic devices landscape.
Growth Catalysts
- Non-ablative tightening protocols:Radiofrequency platforms attract clinic investment as patients seek minimal-downtime skin laxity treatments without surgical intervention.
- Harley Street medical district concentration:London's premium cosmetic corridor drives capital deployment toward multi-wavelength laser systems serving high-net-worth patient bases.
- Care Quality Commission inspection standards:Regulatory clarity on clinic accreditation reduces operational uncertainty for device-dependent dermatology practices.
Market Restraints
- UKCA marking transition friction:Dual-track conformity assessment for EU-originated portfolios extends product registration timelines and strains distributor working capital.
- Capital intensity concentration:Laser device procurement requires substantial upfront investment that filters smaller independent clinic operators from technology access.
- Consumable supply dependency:Recurring hyaluronic acid filler attachment locks clinics into single-source supply relationships with limited price negotiation leverage.
Strategic Opportunities
- West Midlands clinic expansion:Private dermatology practices in Greater Manchester and surrounding counties present underpenetrated demand for energy-based rejuvenation platforms.
- AI-enabled diagnostic attachments:Convergence between software-as-medical-device guidance and aesthetic platforms creates new revenue streams for integrated imaging systems.
- Home counties satellite demand:Affluent commuter belts surrounding London generate patient flow for secondary clinic locations without prime real estate costs.
Industry Challenges
- Energy-based device vigilance reporting:MHRA tightened surveillance requirements demand enhanced adverse event documentation that strains smaller clinic administrative capacity.
- Multi-jurisdiction compliance burden:Dual alignment with residual EU MDR obligations and emerging UKCA standards fragments quality management system resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Aesthetic Devices Market |
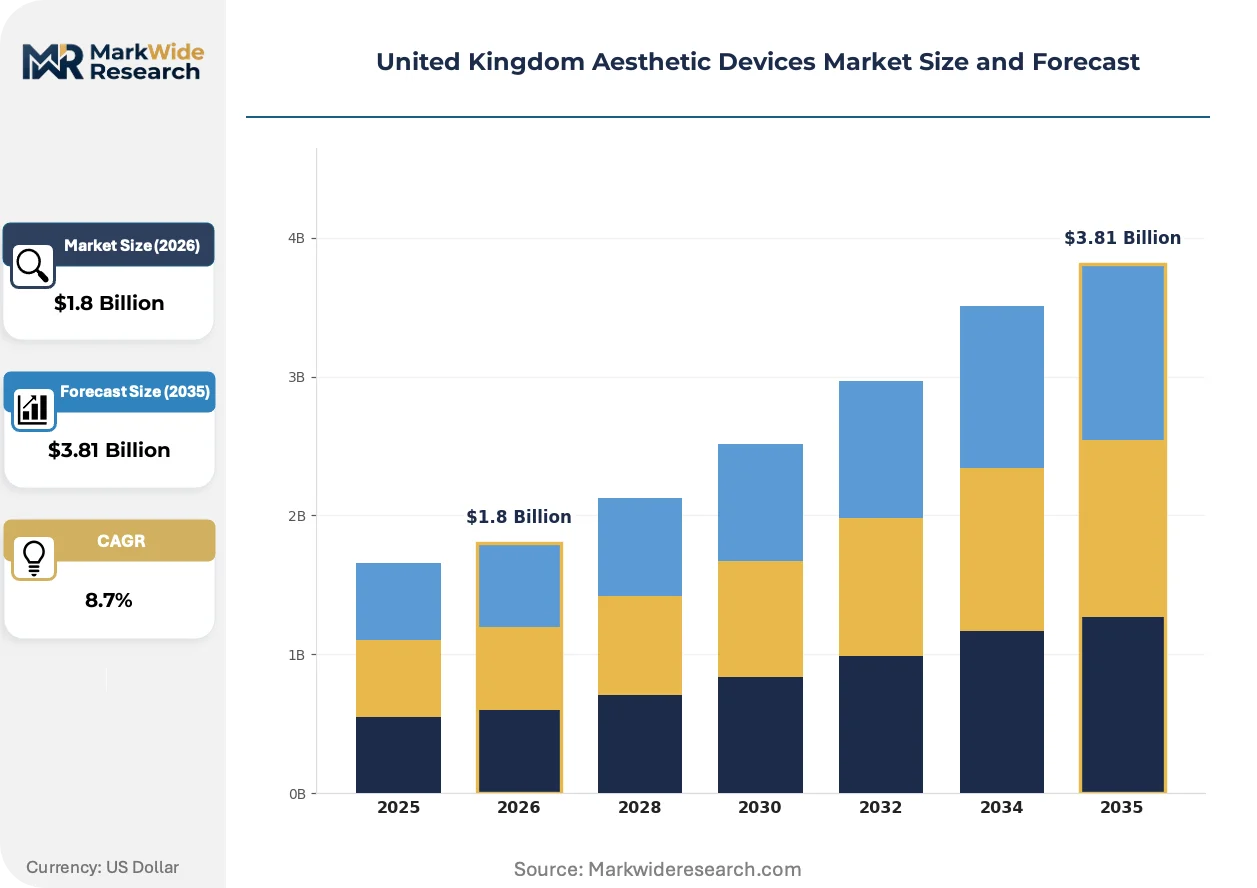
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, Injectable Fillers, Microdermabrasion Equipment, Light Therapy Devices End User: Clinics, Medical Centers, Beauty Salons, Home Users Technology: Pulsed Light, Radiofrequency, Ultrasound, Chemical Peels Application: Skin Rejuvenation, Hair Removal, Pigmentation Treatment, Wrinkle Reduction |
| Companies Covered | BTL Aesthetics, Cynosure, Galderma, Lumenis, AbbVie, Alma Lasers, Sciton, Syneron Candela, Merz Pharma, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Aesthetic Devices Market Evolving Landscape
Technology convergence and regulatory reorganization are compressing traditional device procurement cycles while opening new competitive vectors across the United Kingdom aesthetic devices market.
Fractional laser technology is fragmenting established skin resurfacing protocols by enabling tunable thermal injury depths that match patient downtime tolerance. Harley Street dermatology clinics adopt these platforms at accelerated replacement cycles compared to standard ablative systems. The technology is fragmenting capital allocation between single-modality purchases and multi-wavelength integrated platforms that command premium positioning.
Medical Devices Regulation CE marking reorganization is forcing distributors to duplicate technical documentation for parallel UKCA conformity routes. This regulatory friction compresses margin structures for EU-originated device portfolios while favoring manufacturers with established British authorized representative networks. Energy-based aesthetic systems face the steepest compliance burden given their classification under active implantable and high-risk device categories.
Clinic procurement patterns now emphasize lease-to-own structures over outright capital purchase, particularly for radiofrequency and ultrasound platforms with rapid obsolescence risk. Independent dermatology practices in Greater Manchester and the West Midlands favor equipment-as-a-service arrangements that bundle maintenance and consumable supply. This financing rotation is most visible among mid-scale operators seeking technology access without balance-sheet concentration.
United Kingdom Aesthetic Devices Market Segmentation
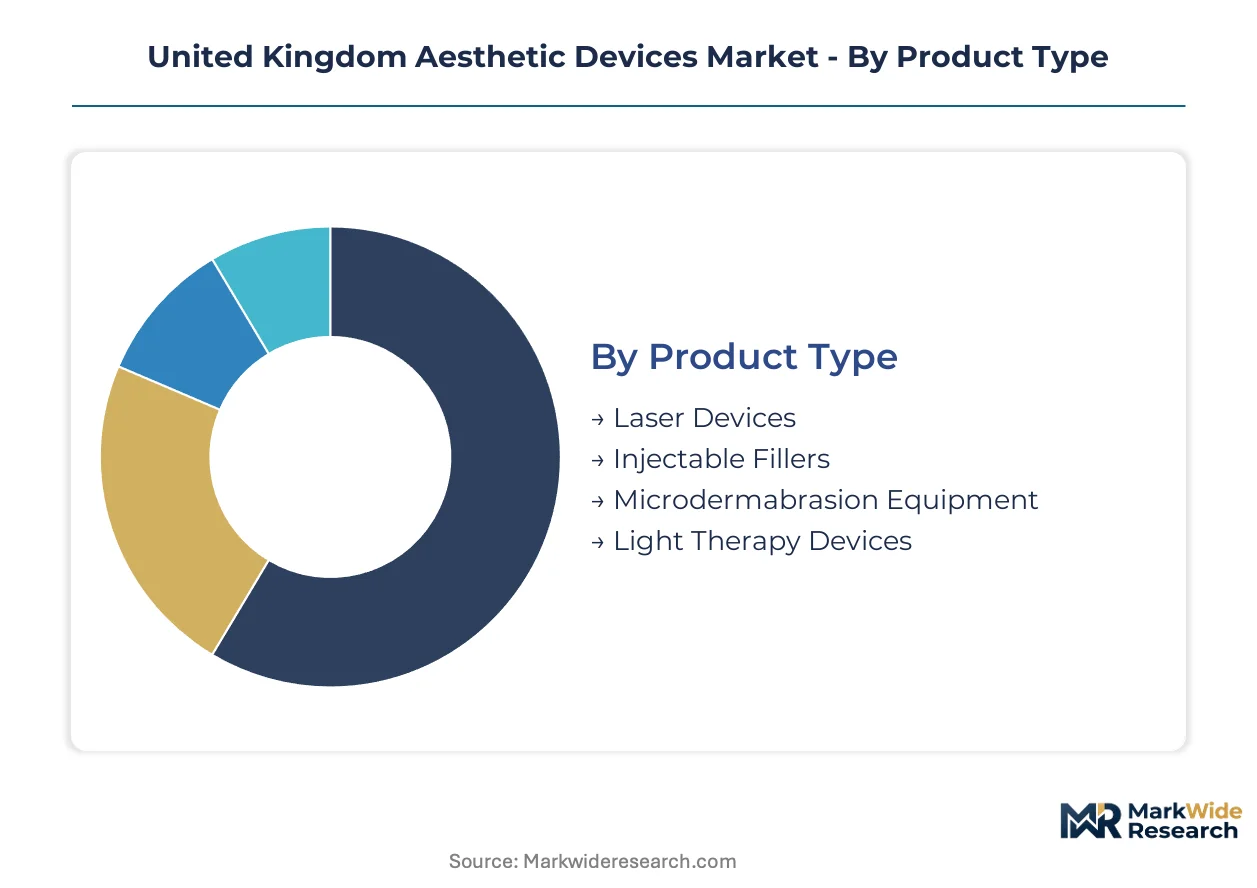
Segmentation in the United Kingdom aesthetic devices market reveals how procurement priorities diverge between premium London medical corridors and cost-conscious regional clinics. Understanding these splits enables targeted positioning across capital-intensive laser systems versus consumable-driven injectable portfolios.
Product Type:
Domestic demand concentrates in capital equipment serving Harley Street dermatology practices, while export-oriented manufacturers balance UKCA conformity costs against continental European market access.
- Laser Devices:Multi-wavelength electromechanical systems output controlled optical energy at tissue-specific wavelengths for ablative and non-ablative resurfacing. Harley Street clinics drive replacement cycles for fractional platforms that match high-net-worth patient downtime tolerance against capital intensity barriers filtering smaller operators.
- Injectable Fillers:Cross-linked hyaluronic acid formulations delivered via syringe systems for volume restoration and wrinkle correction. Greater Manchester private practices generate repeat purchase cycles through premium formulation procurement, though single-source supply relationships limit price negotiation leverage.
- Microdermabrasion Equipment:Mechanical exfoliation systems utilizing crystal or diamond-tip abrasion for superficial skin resurfacing, predominantly deployed in West Midlands beauty salons seeking lower capital entry points.
- Light Therapy Devices:LED and IPL-based systems for acne management and photorejuvenation, expanding fastest among home users in London commuter belt counties.
Laser devices hold the largest share; momentum sits with injectable fillers.
End User:
Customer-type fragmentation creates distinct procurement rhythms between regulated medical settings and consumer-facing beauty establishments.
- Clinics:CQC-inspected dermatology and cosmetic surgery practices across Greater Manchester and the West Midlands deploy energy-based systems under dual compliance burdens. These operators favor lease-to-own structures that bundle maintenance and consumable supply without balance-sheet concentration.
- Medical Centers:Hospital-affiliated cosmetic departments and specialist treatment centers with dedicated aesthetic wings. Procurement prioritizes multi-wavelength platforms serving diverse patient populations under institutional purchasing frameworks.
- Beauty Salons:Non-medical aesthetic establishments operating below medical device regulatory thresholds. These operators select lower-intensity light therapy and microdermabrasion equipment to avoid MHRA vigilance reporting obligations.
- Home Users:Consumer-direct purchasers of handheld LED masks and low-power laser devices, concentrated in affluent home counties surrounding London where disposable income supports premium at-home treatment protocols.
Clinics dominate revenue contribution; home users are climbing the fastest.
Technology:
Technology selection maps directly to patient downtime tolerance and clinician training investment across the United Kingdom market.
- Pulsed Light:IPL systems delivering broad-spectrum optical energy for hair removal and photorejuvenation. West Midlands clinic expansion drives demand for versatile platforms serving multiple indications without dedicated laser infrastructure.
- Radiofrequency:Non-ablative thermal energy delivery for skin tightening protocols with minimal recovery requirements. Harley Street adoption accelerates as patients seek surgical alternatives, making this the steepest expansion trajectory among energy modalities.
- Ultrasound:Micro-focused and high-intensity focused ultrasound systems for deep tissue lifting and body contouring. Capital intensity and specialized operator training concentrate deployment in premium London medical centers.
- Chemical Peels:Acid-based exfoliation formulations controlled by concentration and contact duration rather than electromechanical systems. Beauty salons favor this modality for regulatory simplicity and lower equipment overhead.
Pulsed light maintains installed base leadership; radiofrequency gains share fastest.
Application:
Application focus determines consumable attachment rates and patient revisit frequency across United Kingdom aesthetic practices.
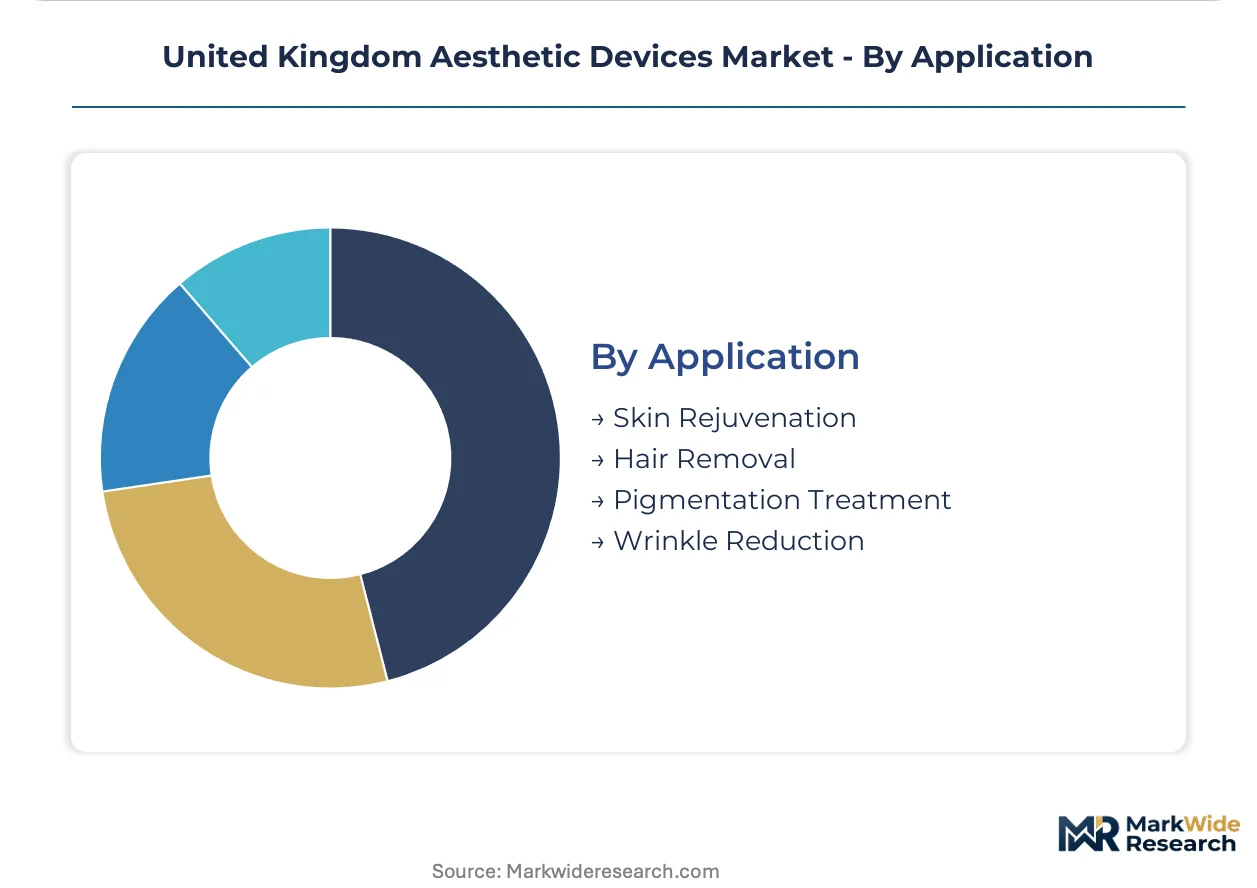
- Skin Rejuvenation:Comprehensive resurfacing, tightening, and texture improvement protocols combining multiple energy modalities. Harley Street clinics command premium positioning through integrated treatment planning spanning laser, radiofrequency, and injectable sequences.
- Hair Removal:Laser and IPL-based permanent hair reduction treatments with established efficacy profiles. This application generates predictable revisit schedules and cross-selling opportunities for complementary rejuvenation services.
- Pigmentation Treatment:Targeted laser and light therapy for solar lentigines, melasma, and vascular lesions. Demand concentrates among aging demographics in affluent home counties with high sun exposure awareness.
- Wrinkle Reduction:Neuromodulator and filler-based correction of dynamic and static rhytides. Medical centers prioritize this application for its repeat purchase economics and lower capital requirements versus energy-based alternatives.
Skin rejuvenation captures the largest procedure volume; wrinkle reduction shows the strongest margin profile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The M1 motorway corridor and West Coast Main Line rail link position England's central spine as the primary distribution channel for aesthetic device deployment across British clinic networks.
London and the Southeast
Harley Street's medical district concentrates capital deployment for multi-wavelength laser platforms serving high-net-worth patient bases. The Care Quality Commission inspects clinic settings here with particular scrutiny on energy-based system documentation. Home counties satellite demand in Surrey and Buckinghamshire generates secondary clinic locations without prime real estate costs.
Greater Manchester
Private dermatology practices in this northern hub expand device portfolios for skin rejuvenation and injectable protocols. MHRA vigilance reporting requirements filter smaller operators from energy-based technology access. The Trafford and Salford clinic clusters drive procurement of lease-to-own radiofrequency platforms.
West Midlands
Birmingham and surrounding counties present underpenetrated demand for energy-based rejuvenation systems. The Medicines and Healthcare products Regulatory Agency enforces post-market surveillance that strains administrative capacity in mid-scale independent practices. Coventry and Solihull beauty salons favor lower-intensity light therapy equipment to avoid regulatory thresholds.
Scotland
Edinburgh and Glasgow medical centers prioritize institutional purchasing frameworks for hospital-affiliated cosmetic departments. UKCA marking transition timelines extend product registration for EU-originated device portfolios entering Scottish procurement channels. Aberdeen's affluent patient base supports premium hyaluronic acid filler repeat purchase cycles.
Wales
Cardiff and Swansea clinic operators navigate dual alignment with residual EU MDR obligations and emerging UKCA standards. The Welsh Government's healthcare procurement frameworks influence device selection in NHS-affiliated aesthetic services. Smaller operators here concentrate on microdermabrasion and chemical peel modalities to minimize compliance burden.
United Kingdom Aesthetic Devices Market Competitive Landscape
Listed leaders compete with private specialists across technology platform breadth and regulatory compliance infrastructure. The vendor base splits between multi-modality platform houses and focused injectable formulation specialists. Three archetypes dominate: capital equipment manufacturers with installed base leverage, consumable-driven filler houses with repeat purchase economics, and integrated platform vendors bundling device and consumable supply. Competitive moves center on lease-to-own financing structures and authorized representative network expansion for UKCA conformity.
Among Israeli-origin laser specialists, Alma Lasers and Lumenis exemplify multi-wavelength platform leadership. Merz Pharma anchors the consumable-driven tier through specialized injectable formulations. These three occupy positions across the technology-consumable spectrum, reflecting how procurement priorities diverge between capital-intensive Harley Street clinics and repeat-purchase-focused regional practices.
| Leading Market Players |
|---|
| BTL Aesthetics |
| Cynosure |
| Galderma |
| Lumenis |
| AbbVie |
| Alma Lasers |
| Sciton |
| Syneron Candela |
| Merz Pharma |
| Others |
Value Network & Pricing Analysis
Ninety-day lead times for EU-originated laser platforms arriving through Rotterdam port congestion simultaneously compress distributor working capital and concentrate pricing power with UKCA-authorized representatives holding bonded inventory. This inventory bottleneck forces Harley Street clinics toward premium lease-to-own structures while filtering smaller Greater Manchester operators from technology access entirely.
Pricing Analysis
Volume-discount tiering structures separate Harley Street flagship installations from West Midlands satellite deployments through bundled maintenance and consumable attachment. Price differentiation hinges on UKCA certification completion status and after-sales service bundling rather than base hardware specifications. Cost compression in mid-tier radiofrequency platforms is intensifying as Israeli and German manufacturers compete for Trafford clinic contracts. Independent dermatology practices in the West Midlands exhibit the highest price sensitivity due to constrained balance sheets, while London medical centers prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Port congestion on the Rotterdam-Immingham container lane elevates inbound logistics costs for German-manufactured laser resonators and Israeli-designed optical delivery systems. Manufacturing concentration in Germany, Israel, and the United States feeds UK distribution through a fragmented authorized representative network. Single-source vulnerability in hyaluronic acid raw material supply from Chinese fermentation facilities creates formulation batch risk for Merz Pharma and Galderma filler portfolios. Distribution runs through CQC-inspected clinic procurement committees rather than open market channels, privileging established vendor relationships over price competition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom aesthetic devices market tracks a cyclical recovery pattern anchored to post-MDR regulatory clarity and deferred capital expenditure release from CQC-accredited clinic networks. Patient appointment backlogs and pent demand for non-surgical tightening protocols justify this cyclical framing.
For Market Incumbents: Secure UKCA marking completion for multi-wavelength platforms before residual EU MDR obligations fragment quality management resources further. Incumbent manufacturers should anchor vertical integration into hyaluronic acid filler supply chains to defend margin position against emerging Korean entrants with cost-advantaged cross-linking technology. Lease-to-own financing infrastructure represents the priority capability investment for defending clinic relationships in Greater Manchester expansion zones.
For New Entrants and Emerging Players: UKCA fast-track pathways through established British authorized representatives offer the most penetrable entry vector for EU-originated radiofrequency platform manufacturers. West Midlands independent dermatology practices present underpenetrated demand for equipment-as-a-service arrangements bundling maintenance and consumable supply. New entrants should target home counties satellite locations through direct-to-clinic sales models that bypass London distributor margin stacking.
For Investors and Strategic Acquirers: Long-term, this sits as a consumable-attachment play because hyaluronic acid filler repeat purchase economics generate predictable cash flows insulated from capital expenditure cyclicality. Acquisition targets should concentrate on mid-scale clinic networks with captive patient bases in Birmingham and Manchester corridors. The signal to watch is MHRA software-as-medical-device guidance finalization, which will determine AI-enabled diagnostic attachment revenue recognition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| UKCA Marking Pathway | Accelerated conformity assessment through British authorized representative networks unlocks clinic procurement channels before competitors complete dual-track documentation. |
| Hospital System Partnership | Institutional purchasing frameworks with NHS-affiliated cosmetic departments in Edinburgh and Glasgow secure volume commitments for multi-wavelength platform deployment. |
| Software Companion Development | AI-enabled diagnostic attachments aligned with MHRA software-as-medical-device guidance create recurring revenue streams beyond hardware sale margins. |
| Reimbursement Strategy | Private medical insurance coding for non-ablative tightening protocols in Harley Street clinics expands addressable patient base beyond self-pay segments. |
| Geographic Expansion | Secondary clinic locations in Surrey and Buckinghamshire commuter belts capture satellite demand without prime London real estate overhead. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CQC-registered clinic directors, biomedical equipment procurement officers at Greater Manchester hospital trusts, and regulatory affairs leads at German and Israeli device manufacturers. Secondary validation drew from MHRA vigilance databases, Care Quality Commission inspection reports, and UKCA marking registration filings. Bottom-up procedure volume estimates from Harley Street and West Midlands clinic networks were triangulated against top-down manufacturer shipment data.
Across the analysis window, the forecasting framework modeled demand trajectories by product type, end-user setting, technology modality, and application focus. CAGRs were derived from segment-specific growth rate assumptions calibrated to regulatory milestone timelines and capital expenditure release patterns. Forecast inputs incorporated CQC inspection capacity constraints, UKCA marking completion rates for EU-originated portfolios, and patient demographic shifts in London commuter belt counties.
Decision-makers should treat outputs as directional under assumptions of stable MHRA vigilance enforcement and unimpeded EU-UK trade lane access; material deviation would warrant model refresh. Specific risk factors include UKCA marking timeline extensions, hyaluronic acid raw material supply disruptions, and Care Quality Commission inspection backlogs delaying clinic accreditation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Plastic Surgery Scaffolds Market
Medical Devices
Cranial Orthoses Market
Medical Devices
Batteries for Skin Patches Market
Medical Devices
Global Electronic Stethoscope Market
Medical Devices
Infant Radiant Warmer Market
Medical Devices
South Korea ECG Market
Medical Devices
Global 3D Printed Surgical Models Market
Medical Devices
Crescent Ultrasonic Cleansers Market
Medical Devices
Brazil Medical Devices Market
Medical Devices
Global Pressure Relief Devices Market
Medical Devices
Robotic Biopsy Devices Market
Medical Devices
Electrosurgical Generators Market
Medical Devices
Global Catheter Stabilization Devices Market
Medical Devices
Brachytherapy Market
Medical Devices
Photopheresis Products Market
Medical Devices
Radial Access Catheter Market