
 Vehicle Simulation Software Market | 2026-2036
Vehicle Simulation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Simulation Software Market Insights
Modular bundling of finite element analysis with real-time driving scenario libraries is consolidating buyer procurement patterns around integrated platforms rather than point solutions. Ansys leverages deep physics solver heritage to anchor premium positioning in safety-critical validation workflows. Siemens sustains broad geographic coverage through its digital twin ecosystem spanning design-to-manufacturing continuity. Dassault Systèmes differentiates via 3DEXPERIENCE platform integration that extends simulation data into downstream production engineering.
Vehicle simulation software comprises computational environments that replicate vehicle dynamics, powertrain behavior, aerodynamic response, and sensor performance using mathematical models executed across local workstations or distributed cloud infrastructure. These tools process multi-physics interactions at microsecond time steps to predict real-world performance without physical prototype dependency. Cloud-based simulation represents the fastest-expanding delivery mode as automotive engineering teams distribute computational workloads across elastic server resources. Among end users, OEMs occupy the largest committed spending share while tier-1 suppliers are building captive simulation competencies to reduce external validation costs. Machine learning technology is displacing traditional parametric optimization in autonomous driving application development, where neural network training demands massive synthetic scenario generation.
NHTSA in the United States mandates standardized crashworthiness documentation that elevates finite element analysis to a regulatory submission requirement. The EU AI Act imposes conformity assessment protocols on autonomous driving algorithms, forcing simulation traceability and reproducibility standards throughout Europe. ISO 26262 functional safety certification shapes product development priorities across automotive software vendors worldwide. Stakeholders must evaluate whether their current toolchain architectures can absorb emerging cybersecurity and AI governance obligations without fragmenting validation workflows.
Market Dynamics
Machine learning training pipelines for autonomous driving are compressing validation cycles from months to weeks, forcing automotive OEMs to rebuild simulation infrastructure around synthetic data generation rather than physical test fleets.
Growth Catalysts
- NHTSA crashworthiness mandates:Standardized documentation requirements elevate finite element analysis to regulatory submission necessity across US automotive development programs.
- EU AI Act conformity protocols:Autonomous driving algorithm assessments impose simulation traceability standards that expand software procurement budgets throughout European engineering centers.
- Cloud elasticity:Distributed server architectures enable microsecond-resolution multi-physics workloads without capital-intensive on-premise supercomputing investments.
Market Restraints
- Computational cost concentration:GPU cluster provisioning for neural network training consumes 40-60% of program budgets, squeezing mid-tier suppliers without cloud volume discounts.
- Legacy toolchain fragmentation:Decades of point-solution accumulation creates interoperability gaps that stall unified validation workflows.
- Skill scarcity in physics-ML hybridization:The intersection of classical solver expertise and machine learning engineering remains critically underpopulated across hiring markets.
Strategic Opportunities
- South Korean battery-electric platforms:Hyundai and Kia's dedicated EV architectures create captive demand for thermal-runaway simulation and cell-level electrochemical modeling.
- Digital twin-to-production continuity:Siemens and Dassault Systèmes ecosystems enable simulation data handoff into manufacturing execution systems, compressing design-to-tooling timelines.
- ISO 26262 certification services:Functional safety documentation automation represents unmet white space as ASIL-D requirements proliferate through autonomous feature stacks.
Industry Challenges
- Cross-domain talent integration:Recruiting teams capable of bridging vehicle dynamics, sensor fusion, and software engineering remains the primary bottleneck for tier-1 suppliers building captive simulation teams.
- Validation toolchain consolidation:Merging acquired point solutions into coherent platforms without disrupting active programs demands capital reserves and architectural discipline that mid-market vendors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Simulation Software Market |
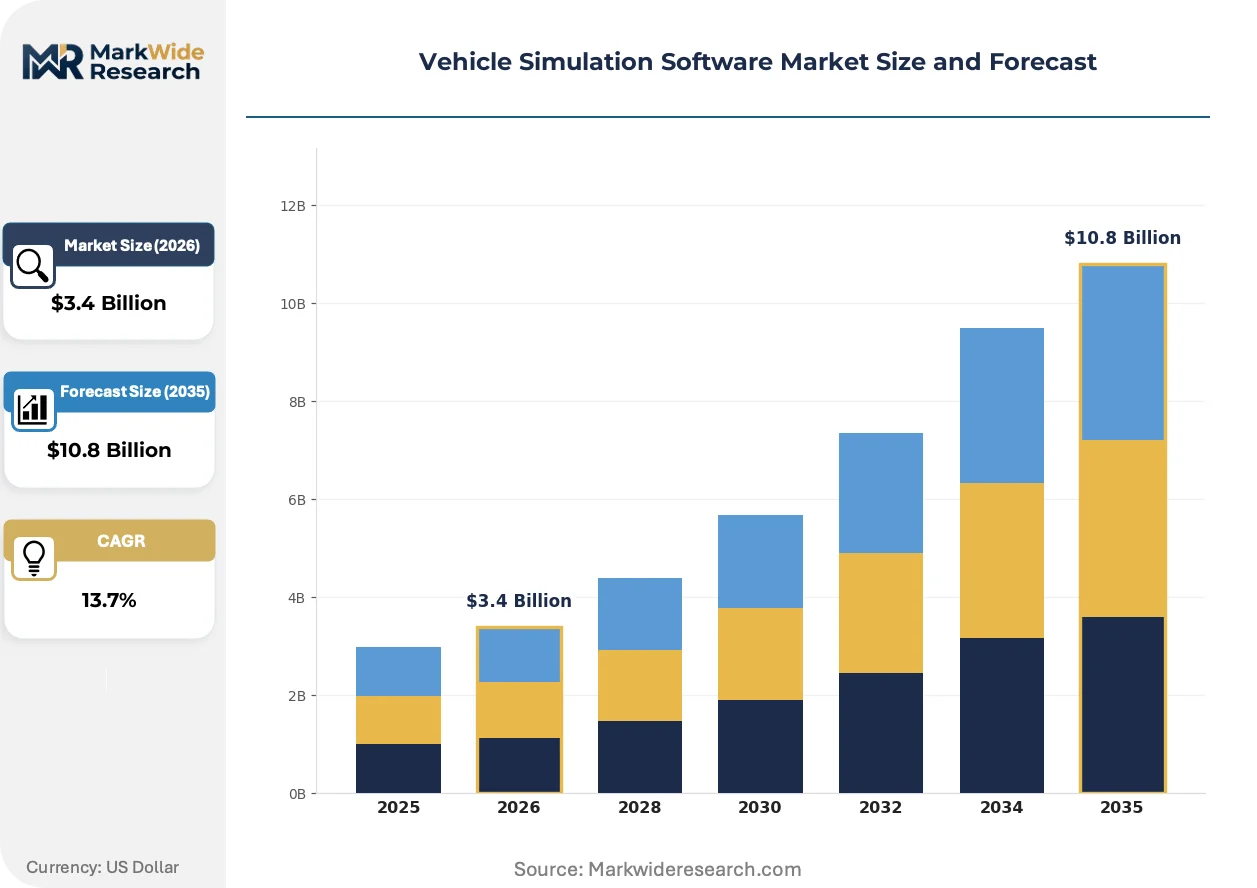
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $10.8 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Simulation, 3D Simulation, Real-Time Simulation, Cloud-Based Simulation End User: OEMs, Tier-1 Suppliers, Research Institutions, Aftermarket Providers Technology: Agent-Based Modeling, Finite Element Analysis, Computational Fluid Dynamics, Machine Learning Application: Performance Analysis, Safety Testing, Autonomous Driving, Design Validation |
| Companies Covered | Autodesk, Altair Engineering, Ansys, Tecknotrove, Unity Technologies, Siemens, PTC, FlexSim, Dassault Systèmes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Simulation Software Market Trends and Innovations
Physics-informed neural networks are collapsing the traditional separation between high-fidelity offline solvers and real-time runtime models, enabling single-source-of-truth architectures that propagate validated parameters across development stages.
Physics-informed machine learning is converging with traditional finite element methods to create hybrid solvers that retain interpretability while accelerating convergence times. German automotive engineering centers at BMW and Porsche are deploying these architectures for chassis load prediction. The structural consequence is collapsing the distinction between design-phase simulation and hardware-in-the-loop validation, compressing iteration cycles.
The EU AI Act's algorithmic conformity assessment framework is mandating reproducible simulation traces for autonomous system submissions. This regulatory pressure forces vendors to implement version-controlled scenario libraries with audit trails. European OEMs are responding by consolidating supplier relationships around platforms with built-in governance tooling rather than assembling point solutions.
Engineering procurement teams are bundling solver licenses with synthetic scenario generation services under multi-year platform commitments. The traditional à-la-carte software purchase is yielding to integrated subscriptions that include cloud compute credits and regulatory documentation support. This pattern concentrates most visibly among US-based OEMs managing distributed R&D footprints across Michigan, California, and Texas engineering centers.
Vehicle Simulation Software Market Segmentation
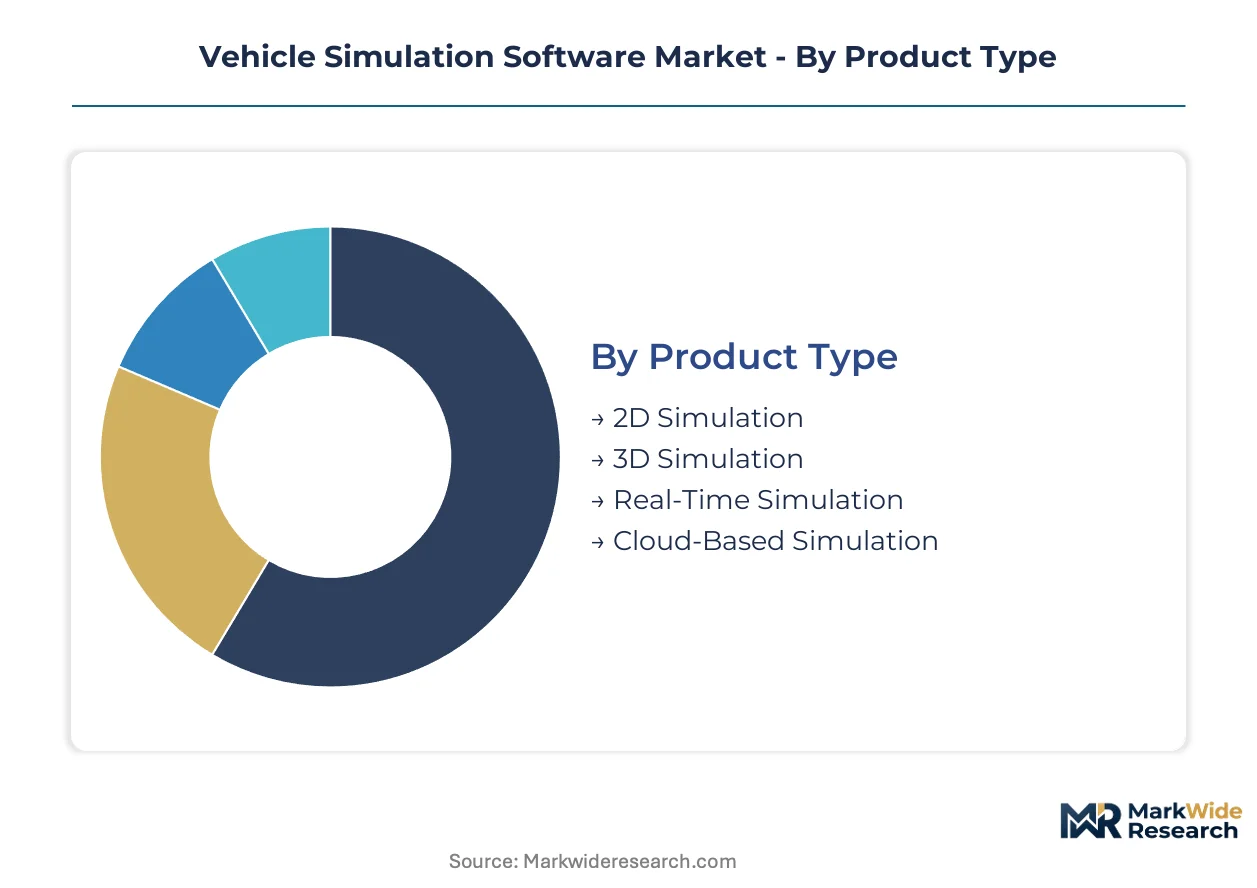
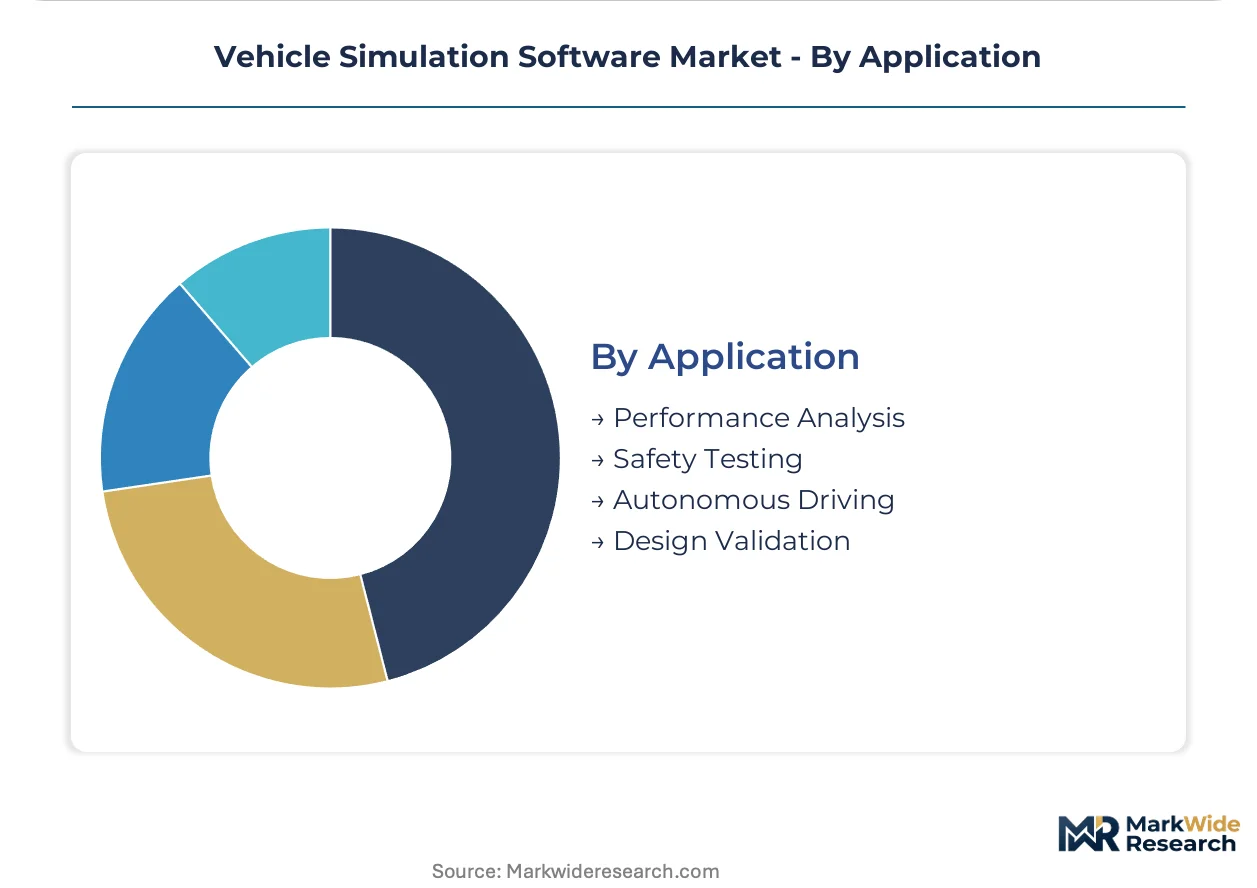
Segmentation in vehicle simulation software reveals how procurement concentrates around integrated platforms versus point solutions, with cloud delivery modes and autonomous driving applications commanding disproportionate engineering budgets across automotive development centers.
Product Type:
Supply concentration in cloud infrastructure has reshaped how simulation workloads reach engineering teams, with hyperscaler partnerships determining competitive access to elastic compute.
- Cloud-Based Simulation:Distributed server architectures process multi-physics workloads across elastic GPU clusters, eliminating capital-intensive on-premise supercomputing. Procurement concentrates among US-based OEMs managing distributed R&D footprints across Michigan, California, and Texas engineering centers where NHTSA documentation requirements demand scalable finite element analysis capacity.
- Real-Time Simulation:Hardware-in-the-loop systems execute vehicle dynamics models at microsecond resolution for controller validation and sensor fusion testing. German automotive engineering centers at BMW and Porsche deploy these architectures for chassis load prediction, collapsing the distinction between design-phase simulation and physical validation.
- 3D Simulation:High-fidelity geometric modeling environments replicate complex vehicle assemblies with detailed material property definitions for crashworthiness and aerodynamic assessment.
- 2D Simulation:Planar kinematic and simplified dynamic models serve early-stage concept exploration and powertrain layout optimization where computational efficiency outweighs geometric precision.
Today's leader: Cloud-Based Simulation. Tomorrow's challenger: Real-Time Simulation.
End User:
Cost tier differentiation separates enterprise-scale platform commitments from modular point-solution procurement, with captive competency building reshaping supplier relationships.
- OEMs:Original equipment manufacturers occupy the largest committed spending share, consolidating validation workflows around integrated platforms with built-in regulatory documentation support. Engineering procurement teams bundle solver licenses with synthetic scenario generation services under multi-year subscriptions spanning design-to-manufacturing continuity.
- Tier-1 Suppliers:Component and system integrators are building captive simulation competencies to reduce external validation costs, though GPU cluster provisioning for neural network training consumes disproportionate program budgets without cloud volume discounts.
- Research Institutions:Academic and government laboratories advance foundational solver methodologies and train specialized talent at the physics-ML intersection.
- Aftermarket Providers:Retrofit and performance modification specialists apply simulation tools for component compatibility verification and regulatory compliance documentation.
Enterprise platform commitments dominate OEM procurement. Tier-1 suppliers represent the fastest-expanding captive investment category.
Technology:
Application urgency in autonomous driving development has elevated machine learning pipelines above classical solver methodologies, compressing validation cycles from months to weeks.
- Machine Learning:Neural network training pipelines demand massive synthetic scenario generation, displacing traditional parametric optimization in autonomous driving development. The EU AI Act imposes conformity assessment protocols forcing simulation traceability and reproducibility standards throughout European engineering centers.
- Finite Element Analysis:Physics-based structural solvers anchor safety-critical validation workflows, with NHTSA mandates elevating crashworthiness documentation to regulatory submission necessity across US automotive programs.
- Computational Fluid Dynamics:Aerodynamic and thermal simulation tools predict airflow patterns, cooling system performance, and battery thermal management for electric vehicle architectures.
- Agent-Based Modeling:Multi-entity behavioral simulation generates traffic scenarios and pedestrian interactions for autonomous system training and edge-case exploration.
Physics solvers retain regulatory anchoring. Machine learning claims the steepest expansion trajectory.
Application:
Customer type segmentation reflects divergent certification requirements, with safety-critical applications demanding higher documentation automation investment than performance optimization.
- Autonomous Driving:Algorithm validation requires synthetic scenario libraries with version-controlled audit trails for regulatory submission, with ISO 26262 functional safety certification shaping product development priorities across automotive software vendors worldwide.
- Safety Testing:Crashworthiness and occupant protection validation depends on standardized finite element analysis documentation meeting NHTSA submission protocols.
- Design Validation:Multi-physics integration verifies component interactions across structural, thermal, and electromagnetic domains prior to prototyping commitment.
- Performance Analysis:Powertrain efficiency, vehicle dynamics, and energy consumption optimization supports competitive benchmarking and regulatory compliance demonstration.
Safety documentation commands premium platform investment. Autonomous driving is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vehicle simulation software emerged from German automotive engineering traditions in the 1980s, where BMW and Porsche pioneered finite element methods for chassis development. The industry subsequently scaled through US aerospace computing heritage and Japanese precision manufacturing demands. Today, procurement concentrates in engineering centers spanning Germany, the United States, Japan, China, and South Korea.
United States
NHTSA crashworthiness mandates elevate finite element analysis to regulatory submission necessity across Michigan and California engineering centers. OEM procurement teams bundle solver licenses with synthetic scenario generation under multi-year platform commitments. Detroit and Austin clusters process distributed R&D workloads across elastic GPU infrastructure.
Germany
BMW and Porsche engineering centers deploy physics-informed neural networks for chassis load prediction, collapsing design-phase and hardware-in-the-loop validation cycles. The EU AI Act imposes simulation traceability standards that expand software procurement budgets throughout Bavaria and Baden-Württemberg. Stuttgart and Munich anchor premium platform consolidation.
Japan
Tokyo and Nagoya engineering centers sustain deep physics solver heritage for safety-critical validation workflows. METI industrial policy supports digital twin adoption across Toyota and Honda supplier networks. Osaka clusters specialize in real-time simulation for controller validation.
China
MIIT standards mandate simulation documentation for new energy vehicle type approval, compressing validation timelines for domestic EV platforms. Yangtze River Delta and Pearl River Delta engineering teams distribute computational workloads across hyperscaler partnerships. Shenzhen and Shanghai clusters lead autonomous driving algorithm development.
South Korea
Hyundai and Kia's dedicated EV architectures create captive demand for thermal-runaway simulation and cell-level electrochemical modeling. Seoul Capital Area engineering centers build machine learning training pipelines for autonomous system validation. Busan-Ulsan clusters integrate simulation data into battery manufacturing execution systems.
Vehicle Simulation Software Market Competitive Landscape
The competitive structure tilts toward integrated platform providers with deep physics heritage. Consolidation pressure favors vendors offering bundled solver licenses with cloud compute credits and regulatory documentation support. Two archetypes dominate: heritage engineering software houses with multi-decade solver development and cloud-native entrants with synthetic data generation capabilities. M&A activity targets point-solution vendors for toolchain integration, while strategic partnerships with hyperscalers secure elastic compute access.
Within the heritage platform tier, Ansys, Siemens, and Dassault Systèmes occupy positions anchored by decades of physics solver development and manufacturing ecosystem integration. Ansys exemplifies premium positioning in safety-critical validation workflows. Siemens represents broad geographic coverage through digital twin continuity spanning design-to-manufacturing. Dassault Systèmes sits within the 3DEXPERIENCE integration archetype, extending simulation data into downstream production engineering.
| Leading Market Players |
|---|
| Autodesk |
| Altair Engineering |
| Ansys |
| Tecknotrove |
| Unity Technologies |
| Siemens |
| PTC |
| FlexSim |
| Dassault Systèmes |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between ISO 26262-compliant enterprise platforms and modular point solutions manifests in both subscription pricing structures and hyperscaler partnership requirements. NHTSA documentation mandates in the United States and EU AI Act traceability standards in Europe concentrate procurement budgets around bundled offerings that include cloud compute credits and regulatory automation tooling.
Pricing Analysis
Subscription-based platform licensing with integrated cloud compute credits anchors the dominant pricing structure across automotive OEM procurement teams. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified safety-critical workflows from design-phase exploration tools. Cost compression in the mid-tier supplier segment is intensifying because GPU cluster provisioning for neural network training consumes disproportionate program budgets without volume discounts. Tier-1 suppliers exhibit the highest price sensitivity, while German and US-based OEMs prioritize platform consolidation over unit cost optimization.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for integrated simulation platforms, while tier-1 suppliers access tools through value-added resellers with embedded engineering services. Software development concentrates in the United States, Germany, and France, with cloud infrastructure provisioning drawing from hyperscaler data centers across South Korea, Ireland, and Singapore. NVIDIA GPU hardware, elastic server orchestration, and synthetic data generation pipelines constitute critical input dependencies. Single-source vulnerability in GPU semiconductor supply creates concentration risk for neural network training workloads. Distribution runs through strategic partnerships with AWS, Microsoft Azure, and Google Cloud Platform that secure elastic compute access for multi-physics workloads.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vehicle simulation software functions as a stable compounder anchored by regulatory mandates that embed validation tooling into automotive development cycles. NHTSA crashworthiness documentation and EU AI Act conformity protocols ensure replacement demand regardless of vehicle production cyclicality.
For Market Incumbents: Hedge against cloud-native entrants by embedding synthetic data generation capabilities directly into solver architectures rather than relying on third-party partnerships. Acquire point-solution vendors specializing in battery electrochemical modeling to capture Hyundai and Kia's EV platform demand. Prioritize ISO 26262 certification automation as a defensive moat against mid-tier competitors lacking documentation tooling.
For New Entrants and Emerging Players: Hyperscaler marketplace partnerships offer the lowest-friction channel for reaching tier-1 suppliers building captive simulation competencies. Target South Korean battery-electric platform engineering centers where thermal-runaway simulation demand outpaces incumbent capacity. Position around physics-ML hybridization services that address the critical talent scarcity blocking supplier internalization efforts.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized synthetic scenario generation vendors serving autonomous driving algorithm developers. Long-term viability rests on regulatory compliance automation capabilities that deepen customer switching costs. Watch for inflection when EU AI Act enforcement triggers consolidation of point-solution procurement around governance-integrated platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Ansys and Siemens anchor premium positioning through solver-to-manufacturing data continuity. |
| Strategic Partnership | Hyperscaler alliances with AWS and Azure secure elastic GPU access for distributed R&D workloads. |
| Acquisition of Specialist Firm | Battery electrochemical modeling vendors capture Hyundai-Kia EV architecture captive demand. |
| Product Launch | Physics-informed neural networks collapse design-phase and hardware-in-the-loop validation cycles. |
| Geographic Expansion | South Korean engineering centers build machine learning pipelines for autonomous system validation. |
Research Methodology
Bottom-up OEM and tier-1 supplier modeling reconciled against top-down hyperscaler infrastructure tracking forms the analytical core of this study. Primary interviews with platform engineering directors, automotive procurement leads, regulatory affairs specialists, and cloud partnership managers combined with secondary validation from SEC 10-K filings, hyperscaler capex disclosures, NHTSA documentation databases, and EU regulatory submission records. Triangulation across deployment model, organization size, vertical application, and regional adoption patterns ensured segmentation integrity.
Historical trendline analysis of solver license growth and cloud compute consumption established baseline momentum indicators across the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user tier, technology methodology, and application urgency with regional production cluster overlays. CAGRs derived from elasticity-adjusted adoption curves incorporating NHTSA mandate implementation timelines and EU AI Act enforcement phasing. Neural network training pipeline proliferation and physics-ML hybridization penetration served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to GPU semiconductor supply constraints, autonomous driving regulatory delays, and tier-1 supplier captive competency buildout rates. Forecasts reflect documented assumptions regarding hyperscaler pricing trajectories and ISO 26262 certification scope expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Advanced Driver Assistance Systems Testing Equipment Market
Automotive Testing and Simulation
Automotive Exhaust Analyzer Market
Automotive Testing and Simulation
On-Board Data Logger and Road Test Equipment System Market
Automotive Testing and Simulation
Automotive Crash Test Dummies Market
Automotive Testing and Simulation
Automotive Emission Test Equipment Market
Automotive Testing and Simulation
Automotive Test Equipment Market
Automotive Testing and Simulation
Automotive Diagnostic Tools Market
Automotive Testing and Simulation
Vehicle Chassis Dynamometers Market
Automotive Testing and Simulation
Diagnostic Tools for Evs Market
Automotive Testing and Simulation
Vehicle Radar Test System Market
Automotive Testing and Simulation
Rail Track and Rolling Stock Advanced NDT Inspection Systems Market
Automotive Testing and Simulation
Global Track Geometry Measurement System (TGMS) Market
Automotive Testing and Simulation
Autonomous Valet Parking System Scenario-Based Test Equipment Market
Automotive Testing and Simulation
Chassis Dynamometers Market
Automotive Testing and Simulation
Torque Gauge Market
Automotive Testing and Simulation
Automotive Durability Testing Market