
 Vegetarian Tacos Market | 2026-2036
Vegetarian Tacos Market Size, Share, and Industry Trends Forecast 2026-2036
Vegetarian Tacos Market Analytics
Fast-casual dining is rebalancing toward plant-forward menus as full-service restaurants lose share among weekday lunch crowds. Chipotle Mexican Grill leverages its sofritas platform to anchor vegetarian throughput in dense urban locations. Taco Bell competes through value-tier pricing and craveable limited-time offerings that normalize meatless ordering. QDOBA Mexican Eats differentiates via customizable bowls and tacos with guacamole included, removing the punitive upsell that deters vegetarian trial.
Vegetarian tacos comprise wheat or corn-based vessels enclosing plant-derived fillings such as seasoned beans, grilled vegetables, fermented proteins, or dairy alternatives, with primary commercial purpose of delivering protein-complete, culturally familiar meals without animal meat. Hard shell formats sustain the largest volume share due to operational simplicity and extended hold times in quick-service kitchens, while lettuce wrap variants capture the fastest growth among carb-restricted and raw-food segments. Gourmet serving styles command the widest margin pools through chef-driven ingredients and premium pricing, whereas street-style formats dominate transaction frequency in urban food-truck corridors.
The FDA oversees allergen labeling and GRAS determinations for novel plant proteins entering taco fillings, while the USDA regulates organic certification claims on corn and wheat tortillas. EFSA's updated novel food guidance in Europe shapes approval timelines for fermented protein ingredients sourced by suppliers serving multinational chains. Stakeholders must monitor how evolving protein-labeling standards and carbon-footprint disclosure mandates will reshape ingredient sourcing and menu transparency requirements.
Market Dynamics
Extrusion and fermentation advances in plant-protein processing are compressing ingredient costs while closing the texture gap with animal proteins, forcing quick-service chains to accelerate meat-free menu development or cede weekday lunch traffic to specialized competitors.
Growth Catalysts
- FDA GRAS Pathways:Streamlined determinations for novel fermented proteins are accelerating ingredient approvals, reducing time-to-market for taco filling innovations by suppliers serving multinational chains.
- Flexitarian Demographics:Younger consumers in the United States, Mexico, and the United Kingdom are normalizing meatless ordering through repeated exposure to craveable limited-time vegetarian offerings.
- Street-Food Culture Convergence:Urban food-truck corridors in Los Angeles, Mexico City, and London are generating high transaction frequency for handheld vegetarian formats, validating operational models for brick-and-mortar expansion.
Market Restraints
- Input Cost Volatility:Organic-certified corn and wheat tortilla supplies face pricing pressure from climate-driven harvest variability, squeezing margin pools for premium-positioned menu tiers.
- Supply Concentration Risk:Fermented protein ingredient production clusters among a narrow set of biotechnology suppliers, creating vulnerability to single-source disruption for chains scaling meat-free platforms.
- Technical Limitation:Extended hold times for soft corn tortillas in quick-service kitchens degrade texture parity, limiting format expansion beyond hard-shell variants in high-throughput locations.
Strategic Opportunities
- Underpenetrated Geography:Germany and the Netherlands present white space for fast-casual vegetarian taco concepts, where EFSA novel-food guidance has established clearer approval pathways than Southern European markets.
- Regulatory Tailwind:The EU Green Deal's carbon-footprint disclosure mandates are creating procurement preference for plant-based proteins, rewarding early supply-chain transparency investments.
- Technology Convergence:Precision fermentation combined with high-moisture extrusion is enabling whole-muscle texture replication, opening premium positioning previously reserved for animal proteins.
Industry Challenges
- Talent Gap in Sensory Science:Shortage of flavor chemists specializing in plant-protein masking is delaying product iteration cycles for chains competing on craveability metrics.
- Capex Intensity for Kitchen Retooling:Dedicated vegetarian prep stations require equipment redundancy in tight quick-service footprints, complicating franchisee adoption.
- Certification Timeline Compression:USDA organic certification for tortilla supply chains is lagging menu-development velocity, forcing temporary sourcing compromises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegetarian Tacos Market |
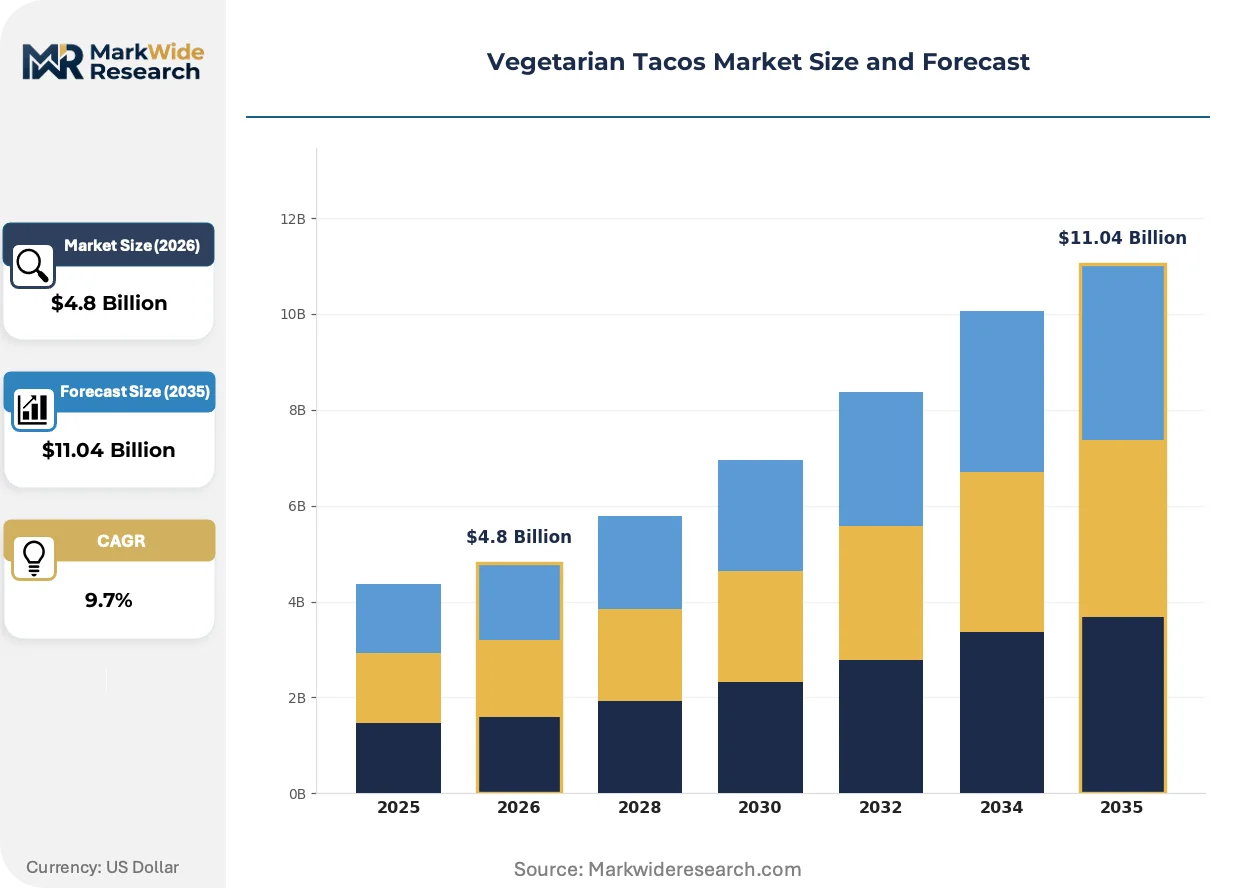
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Shell, Soft Shell, Tortilla, Lettuce Wrap Filling Type: Beans, Cheese, Tofu, Grains Serving Style: Street Style, Gourmet, Fast Casual, Family Meal Distribution Channel: Restaurants, Food Trucks, Retail Stores, Online |
| Companies Covered | QDOBA Mexican Eats, Tacotarian, Taco Bell, Todo Verde, The Veggie Grill, Chipotle Mexican Grill, Moe's Southwest Grill, Knockout T@KOs, Del Taco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegetarian Tacos Market Evolving Landscape
Active protein-texture engineering and carbon-accountability mandates are redefining competitive differentiation, while distribution channels fragment between ghost-kitchen delivery and experience-driven food-hall formats.
High-moisture extrusion paired with post-extrusion shear-cell processing is unifying fibrous texture with scalable throughput. Fast-casual chains in dense urban locations are adopting these systems to reduce dependence on third-party fermented protein suppliers. This convergence is compressing the premium-to-mass-market timeline for whole-cut plant protein tacos, eroding the first-mover advantage of specialized vegan concepts.
EFSA's updated novel-food guidance is tightening safety-data requirements for fermented protein ingredients entering European supply chains. Suppliers serving multinational quick-service networks are front-loading toxicology studies to preempt approval delays. The United Kingdom, operating under retained EU frameworks post-Brexit, is experiencing parallel scrutiny, forcing reformulation commitments before menu launches.
Direct-to-consumer subscription boxes for assemble-at-home vegetarian taco kits are capturing trial from time-constrained households in the United States. Grocery retail is responding with refrigerated sets dedicated to plant-based street-food components, displacing some traffic from quick-service lunch occasions. This channel rotation is most visible in suburban markets where delivery-radius economics favor centralized production models over neighborhood kitchen density.
Vegetarian Tacos Market Segmentation
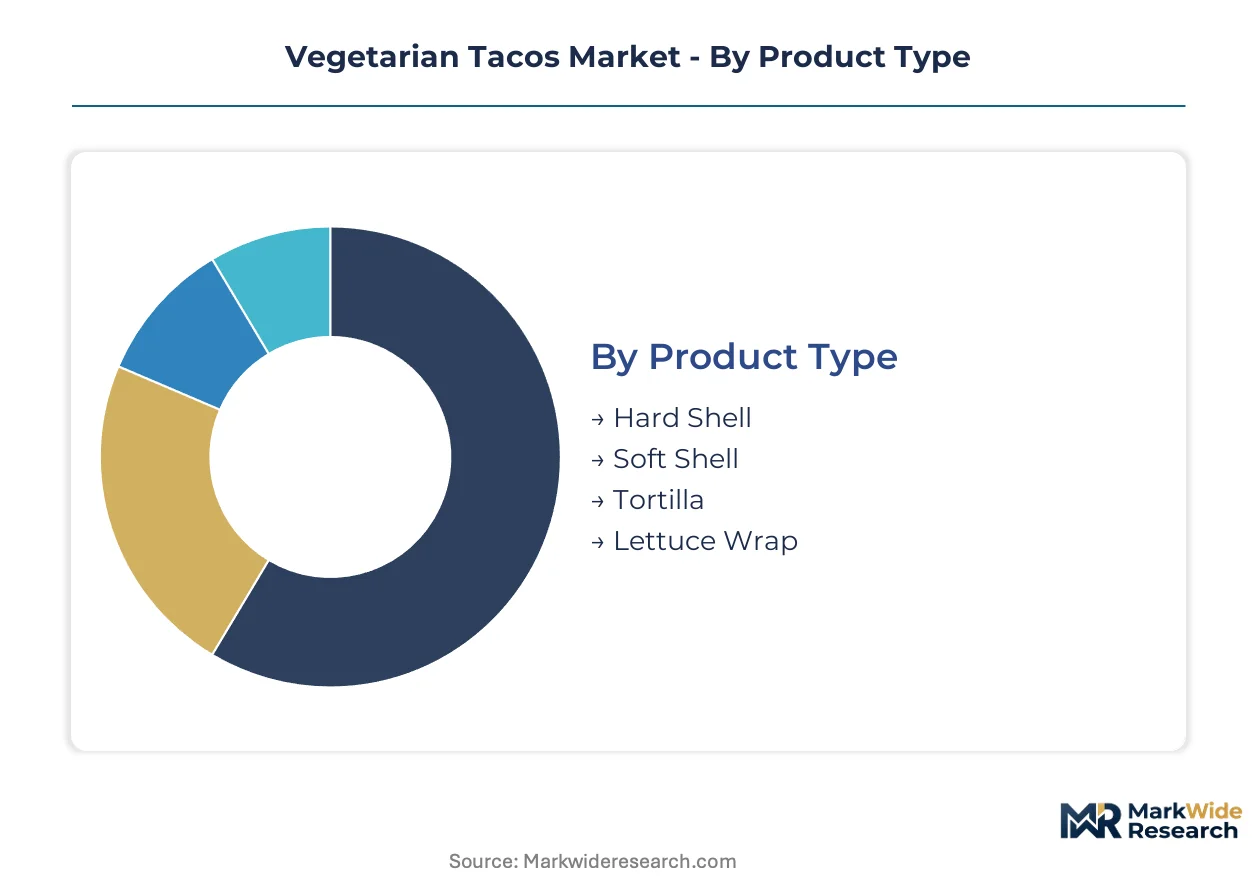
Segmentation in vegetarian tacos reveals how format, filling, and channel choices map to distinct operational economics and consumer occasions. Understanding these splits allows suppliers and operators to align production capacity with where margin and volume actually concentrate.
Product Type:
Format selection determines equipment needs, hold-time tolerance, and throughput ceiling in quick-service kitchens.
- Hard Shell:Corn-based vessels withstand extended warming cycles without textural degradation. Quick-service chains in the United States deploy these for high-volume lunch rushes where speed trumps authenticity.
- Soft Shell:Wheat or corn tortillas deliver pliability and foldability prized in street-style applications. Demand clusters in Mexico City and Los Angeles food-truck corridors where hand-held immediacy matters.
- Tortilla:Flatbread formats enable open-faced or rolled preparations beyond the traditional U-shape. Fast-casual concepts use these for bowl-to-taco flexibility with shared ingredient bins.
- Lettuce Wrap:Carb-restricted carriers capture raw-food and keto-diet adherents. Growth concentrates in suburban United States markets where dietary restriction drives format substitution.
Hard Shell sits at the top of the volume ranking, with Lettuce Wrap climbing the fastest.
Filling Type:
Protein and starch selection shapes ingredient cost structures and allergen management protocols across kitchen footprints.
- Beans:Black and pinto varieties provide fiber-complete nutrition at commodity price points. Taco Bell and Chipotle anchor value menus with seasoned bean formulations that require no cold-chain deviation.
- Cheese:Dairy and fermented alternatives deliver umami depth and visual melt appeal. QDOBA includes guacamole and cheese without upsell to remove price friction on vegetarian trial.
- Tofu:Soy-based curds absorb spice marinades and achieve Maillard browning on flat-top surfaces. Extrusion-textured tofu blocks are displacing crumbles in premium fast-casual locations.
- Grains:Quinoa, farro, and rice blends extend fillings while adding chew resistance. Street vendors in London use grain-forward mixes to signal health positioning without fermented protein costs.
Beans generate the highest transaction frequency, though Tofu is gaining share fastest among flexitarian converts seeking protein parity.
Serving Style:
Occasion positioning separates convenience-driven weekday lunch from experience-driven weekend dining.
- Street Style:Minimalist handheld formats with cilantro, onion, and salsa verde. Urban food-truck corridors in Mexico City and Los Angeles validate this model for brick-and-mortar replication.
- Gourmet:Chef-driven ingredients, house-fermented salsas, and plated presentation. These command the widest margin pools through premium pricing and wine-beer attachment.
- Fast Casual:Customizable assembly lines with transparent prep areas. Chipotle sofritas and QDOBA bowls exemplify this tier where throughput and personalization coexist.
- Family Meal:Multi-portion formats with deconstructed components for at-home assembly. Direct-to-consumer subscription boxes in the United States are capturing this occasion from restaurant delivery.
Fast Casual dominates transaction count, while Family Meal shows the steepest expansion trajectory as suburban households seek convenience without platform fees.
Distribution Channel:
Channel choice determines capital intensity, geographic reach, and customer data ownership for operators.
- Restaurants:Fixed-location dining with full kitchen infrastructure and dine-in or takeout service. Branded chains leverage these for menu innovation testing before broader rollout.
- Food Trucks:Mobile units with commissary dependencies and event-based scheduling. These dominate urban lunch corridors with lower rent burdens than permanent storefronts.
- Retail Stores:Grocery refrigerated sets with assemble-at-home kits and pre-packaged components. This channel is displacing some quick-service traffic in suburban United States markets.
- Online:Direct-to-consumer subscription and third-party delivery platform sales. Ghost kitchens and centralized production models favor this channel where delivery-radius economics beat neighborhood density.
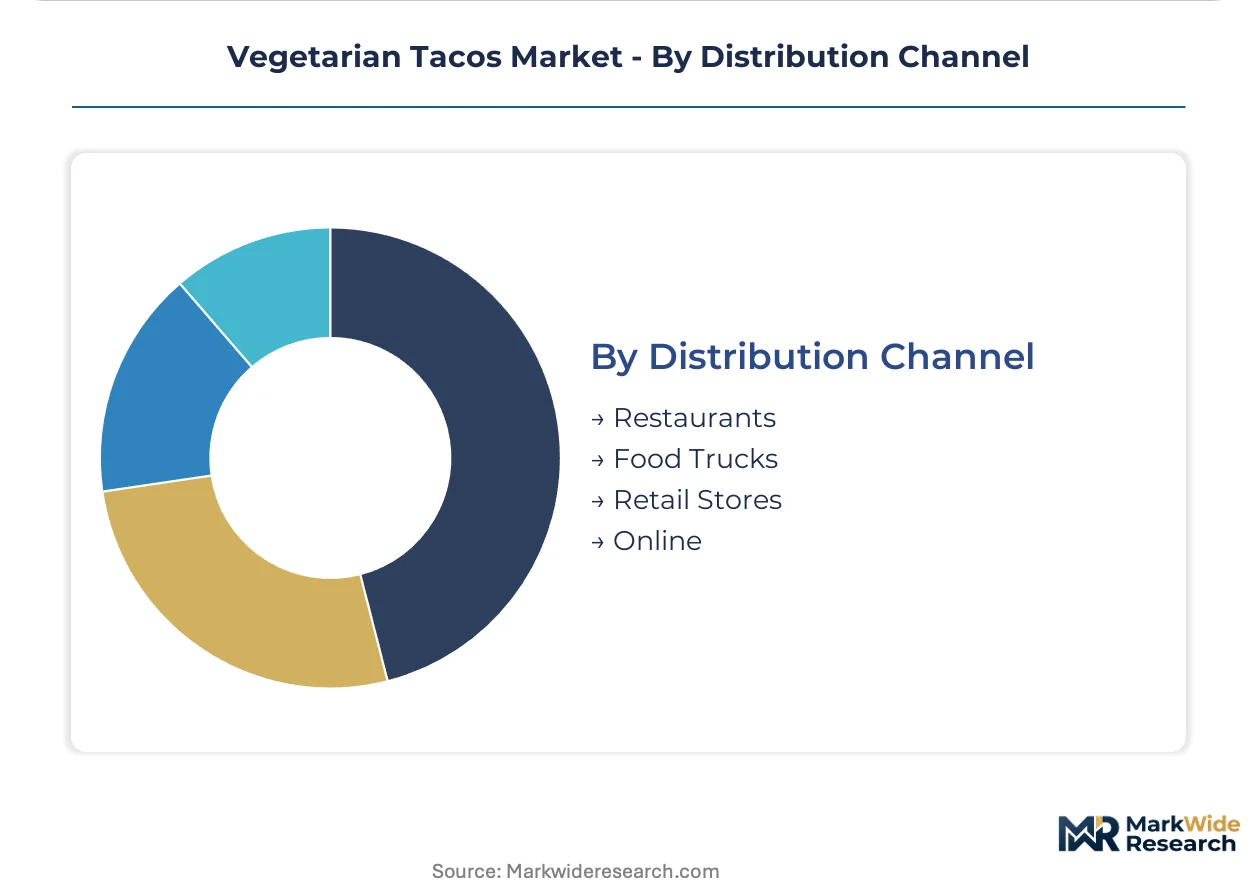
Restaurants retain the largest revenue base, though Online is expanding most quickly as platform logistics mature and consumer habit shifts persist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting supply-chain investments toward jurisdictions where novel protein approvals move faster and carbon-footprint disclosure mandates create procurement preference. The United States, Mexico, United Kingdom, Germany, and Netherlands concentrate demand density and policy experimentation.
United States
Flexitarian ordering normalizes through repeated exposure to limited-time meatless offerings at quick-service chains. FDA GRAS pathways for fermented proteins accelerate ingredient approvals, compressing supplier time-to-market. Los Angeles and Austin food-truck corridors validate street-style operational models for brick-and-mortar replication.
Mexico
Street-food culture sustains high transaction frequency for handheld vegetarian formats in dense urban zones. Domestic regulators align with international standards for organic tortilla certification, though enforcement varies by state. Mexico City anchors national demand, with Guadalajara and Monterrey emerging as fast-casual expansion targets.
United Kingdom
Retained EU novel-food frameworks post-Brexit maintain parallel scrutiny for fermented protein ingredients. EFSA-aligned safety-data requirements force reformulation commitments before menu launches. London's food-hall and ghost-kitchen density supports premium positioning for plant-based street-food concepts.
Germany
EFSA approval clarity exceeds Southern European markets, creating white space for fast-casual vegetarian taco concepts. EU Green Deal carbon-footprint disclosure mandates reward early supply-chain transparency investments. Berlin and Hamburg clusters show strongest trial rates for fermented protein fillings among flexitarian demographics.
Netherlands
Precision fermentation expertise concentrates near Wageningen and Rotterdam port logistics. National regulators enforce EU novel-food guidance with predictable timelines, reducing approval risk for multinational chain suppliers. Amsterdam's experience-driven dining scene supports premium gourmet taco formats with wine-beer attachment.
Vegetarian Tacos Market Competitive Landscape
Menu-platform expansion dominates the current landscape as quick-service chains accelerate meat-free development to defend weekday lunch traffic. The vendor base stratifies across three tiers: multinational fast-casual operators with dedicated vegetarian throughput systems, regional specialists optimizing street-style authenticity, and emerging ghost-kitchen concepts exploiting delivery-radius economics. Strategic archetypes include scale-driven format standardizers, premium-positioned ingredient innovators, and subscription-model direct-to-consumer entrants. Competitive intensity concentrates on M&A for fermented protein supply security and capacity expansion in high-moisture extrusion systems.
Within the multinational fast-casual tier, Chipotle Mexican Grill, QDOBA Mexican Eats, and Taco Bell exemplify divergent positioning strategies. Chipotle anchors vegetarian throughput through its sofritas platform in dense urban locations. QDOBA occupies a position emphasizing customizable bowls with guacamole inclusion to remove price friction on meatless trial. Taco Bell represents value-tier normalization of craveable limited-time vegetarian offerings. Among regional specialists, Tacotarian and Todo Verde exemplify chef-driven formats targeting experience-driven dining occasions.
| Leading Market Players |
|---|
| QDOBA Mexican Eats |
| Tacotarian |
| Taco Bell |
| Todo Verde |
| The Veggie Grill |
| Chipotle Mexican Grill |
| Moe's Southwest Grill |
| Knockout T@KOs |
| Del Taco |
| Others |
Value Network & Pricing Analysis
Organic corn futures volatility in the United States and Mexico cascades through tortilla manufacturing into three distinct pricing tiers for vegetarian taco operators, compressing margins for premium-positioned concepts while reinforcing cost advantages for commodity-scale quick-service chains.
Pricing Analysis
Distributor markups on fermented protein ingredients range from 15 to 35 percent depending on volume commitments and certification status. Three-tier pricing structure across premium, standard, and economy levels separates gourmet fast-casual concepts using house-fermented proteins from value-tier chains relying on commodity bean formulations. Pricing pressure stems from organic-certified corn and wheat input cost escalation, forcing temporary sourcing compromises. Price-sensitive consumers cluster in suburban family meal segments, while urban flexitarian demographics show lowest sensitivity to premium positioning.
Supply Chain Analysis
Single-source vulnerability sits with biotechnology suppliers concentrated in the Netherlands and United States for precision-fermented protein inputs. Raw material dependencies include organic yellow corn from Mexico and the United States, high-protein wheat from Canada, and fermented protein isolates from Dutch biotech clusters. Tariff exposure on organic corn imports creates margin instability for tortilla manufacturers serving multinational chains. Distribution runs through commissary-dependent food trucks in urban corridors and centralized ghost kitchens for suburban delivery radius optimization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vegetarian tacos market functions as a regulatory compounder where EU Green Deal carbon-footprint disclosure mandates are rewriting procurement preferences and rewarding early supply-chain transparency investments with preferential channel access.
For Market Incumbents: Anchor vegetarian throughput through dedicated prep station equipment redundancy in high-volume urban locations, defending against specialized vegan concepts eroding weekday lunch traffic. Secure backward integration into high-moisture extrusion systems to reduce dependence on narrow biotechnology supplier bases for fermented protein security.
For New Entrants and Emerging Players: EFSA novel-food guidance in Germany and the Netherlands opens a window for fast-casual concepts leveraging clearer approval pathways than Southern European markets. Target underpenetrated suburban family meal occasions with direct-to-consumer subscription models, exploiting delivery-radius economics that favor centralized production over neighborhood kitchen density.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists possessing chef-driven format expertise and established food-truck operational models ready for brick-and-mortar replication. Watch for FDA GRAS determination timelines on novel fermented proteins as the inflection signal indicating which supplier networks will secure multinational chain procurement contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Secures textured protein supply for Chipotle sofritas-scale throughput expansion. |
| Organic Certification Fast-Track | Accelerates USDA organic tortilla sourcing to match menu-development velocity. |
| Ghost Kitchen Network Buildout | Captures suburban delivery-radius economics displacing neighborhood quick-service traffic. |
| High-Moisture Extrusion Capacity Addition | Reduces third-party supplier dependence for whole-cut plant protein texture replication. |
| Carbon-Transparency Platform Launch | Aligns procurement with EU Green Deal disclosure mandates for competitive preference. |
Research Methodology
Coverage spans the United States, Mexico, United Kingdom, Germany, and Netherlands, with primary inputs from each market combining executive interviews with quick-service chain menu development directors, biotechnology supplier regulatory affairs leads, food-truck operators, and tortilla manufacturing procurement managers. Secondary validation draws from FDA GRAS determination databases, EFSA novel-food submission records, USDA organic certification registries, and customs trade data on corn and wheat imports. Bottom-up transaction modeling and top-down market sizing triangulate volume estimates.
Rate-of-change decomposition isolates volume drivers across product format, filling protein source, serving style positioning, and distribution channel evolution throughout the forecast period. Segmentation dimensions include hard shell versus soft shell versus lettuce wrap formats, bean versus tofu versus fermented protein fillings, and restaurant versus food truck versus online channel splits. CAGRs derive from historical trajectory analysis adjusted for regulatory milestone impacts and technology adoption curves in extrusion and fermentation processing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under climate-driven harvest variability for organic corn and wheat supplies. Forecasts reflect assumptions on flexitarian demographic conversion rates and EFSA approval timeline predictability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
White Fungus Market
Specialty Foods
Low Calorie Veggie Dip Market
Specialty Foods
Military Forces Ready to Eat Meals Market
Specialty Foods
Asia-Pacific Hummus Market
Specialty Foods
Triphala Powder Market
Specialty Foods
Almond-Based Spreads Market
Specialty Foods
Kosher Food Market
Specialty Foods
Cannabis Infused Drinks Market
Specialty Foods
Asia-Pacific Alcohol-Infused Ice Cream Market
Specialty Foods
Fruit Dessert Market
Specialty Foods
Asia Pacific Cat Food Market
Specialty Foods
Luxury Cigar Market
Specialty Foods
Wet Grain-Free Pet Food Market
Specialty Foods
Aloe Vera Gel Market
Specialty Foods
Wheatgrass Products Market
Specialty Foods
Low Calorie Desserts Market