
 Kosher Food Market | 2026-2036
Kosher Food Market Size, Share, and Industry Trends Forecast 2026-2036
Kosher Food Market Intelligence
Plant-based protein alternatives is pivoting toward kosher certification as mainstream food economics shift. Cargill leverages its grain-processing infrastructure to supply certified-kosher feedstock to protein processors. Nestlé anchors a global portfolio of kosher-certified confectionery and prepared meals across multiple continents. Manischewitz specializes in heritage kosher products that sustain brand loyalty through retail and direct channels.
Kosher food comprises products prepared under rabbinical supervision according to kashrut dietary laws, requiring separation of meat and dairy, inspection of ingredients for non-kosher contaminants, and ritual slaughter (shechita) for animal proteins. The certification process involves ongoing facility audits, ingredient verification, and rabbinical oversight to maintain compliance for industrial and commercial food production. Meat and dairy segments command premium pricing due to intensive supervision requirements, while snacks represents the fastest-expanding category as convenience-oriented kosher options multiply. Certification type structures competitive access, with Orthodox Union and Star-K marks dominating retail shelf presence and influencing buyer trust thresholds.
The USDA oversees slaughterhouse standards that intersect with shechita protocols, while FDA labeling rules govern how kosher claims appear on packaged goods. State-level kosher consumer protection laws in New York and New Jersey impose additional enforcement layers that affect interstate commerce. Stakeholders must monitor how evolving plant-based ingredient classifications challenge traditional kosher categorization frameworks.
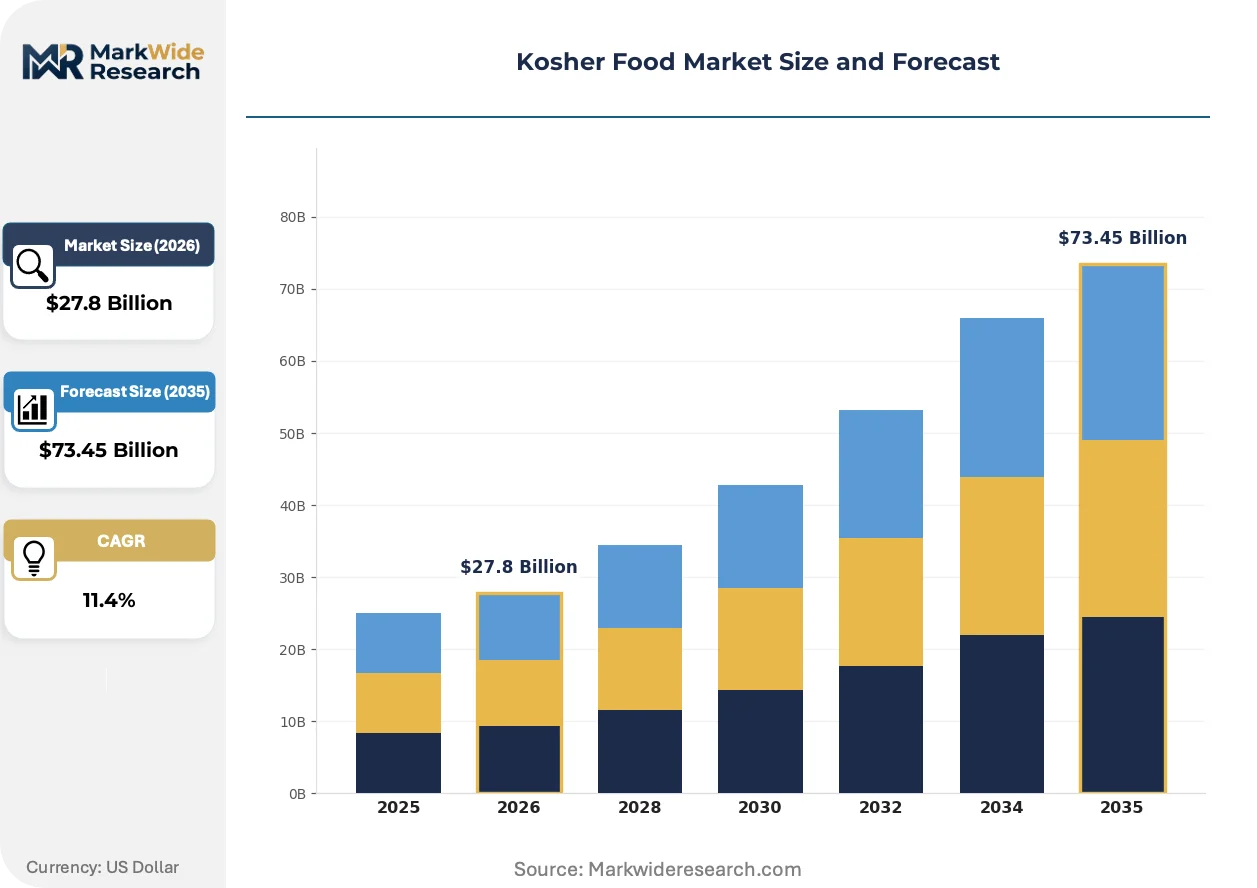
Market Dynamics
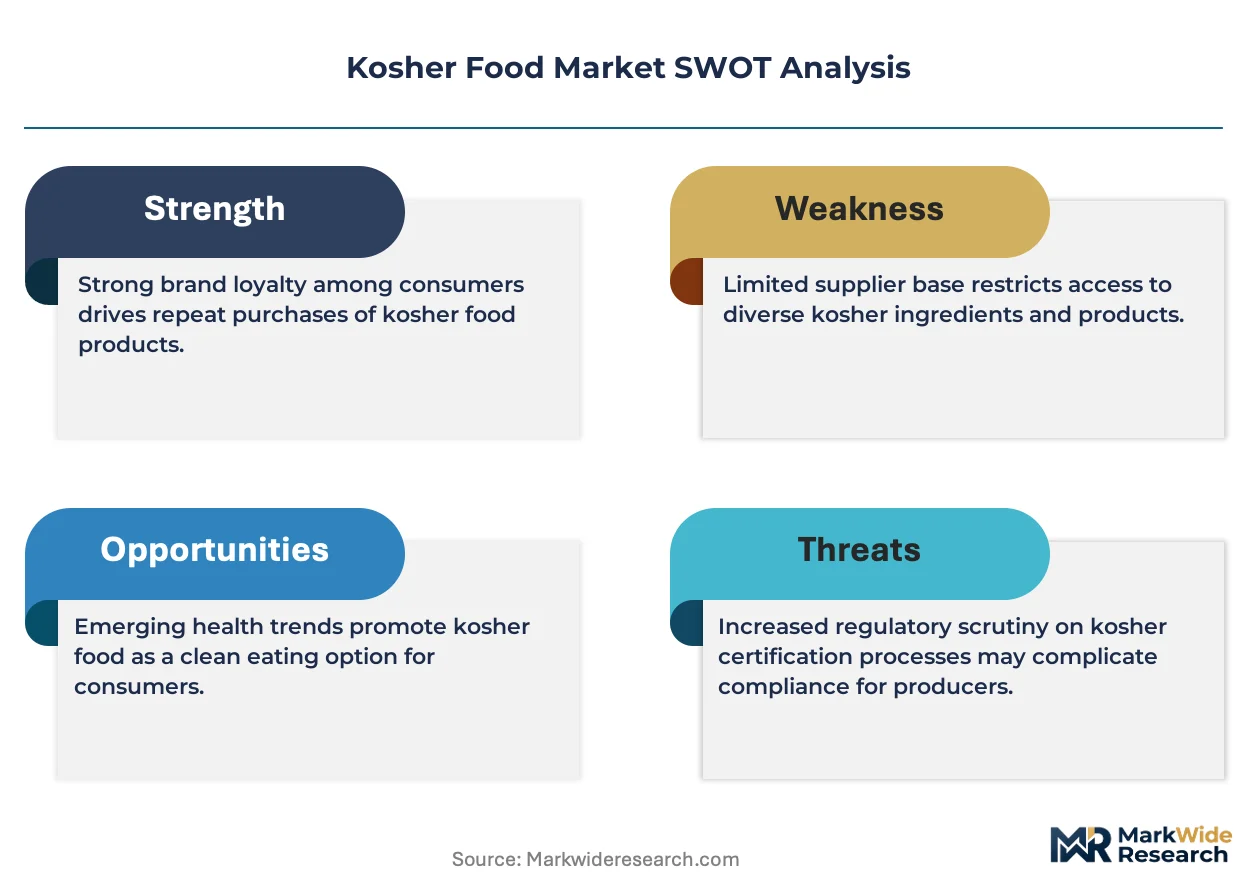
Supermarket chains are consolidating kosher shelf space under private-label banners, compressing margins for legacy brands while expanding certification demand to new ingredient categories including plant-based proteins and alternative sweeteners.
Growth Catalysts
- Dual-Label Certification:USDA organic standards increasingly overlap with kosher supervision protocols, enabling streamlined compliance for manufacturers targeting health-conscious consumers in metropolitan clusters.
- Plant-Based Protein Expansion:Pea and mycelium protein processors are pursuing kosher certification to access institutional foodservice channels serving Jewish day schools and hospital systems.
- Shechita Infrastructure Modernization:Ritual slaughter facilities in Argentina and Uruguay are installing EU-compliant traceability systems to maintain export eligibility for European kosher meat distributors.
Market Restraints
- Supervision Cost Escalation:Mashgiach labor rates in Brooklyn and Jerusalem have risen sharply, squeezing margins on commodity items with thin pricing headroom.
- Ingredient Supply Concentration:Kosher-certified gelatin and glycerin production concentrates in Brazil and India, creating vulnerability to port disruptions and currency volatility.
- Regulatory Friction:EU member states apply divergent interpretations of shechita stunning exemptions, fragmenting compliance requirements for cross-border meat trade.
Strategic Opportunities
- Direct-to-Consumer Channels:Subscription box services specializing in kosher meal kits are capturing younger consumers in Tel Aviv and London who bypass traditional retail.
- Cell-Cultured Protein Convergence:Precision fermentation and cultivated meat technologies may bypass conventional shechita requirements, opening certification pathways for novel protein categories.
- Indian Subcontinent Penetration:Mumbai and Delhi present underdeveloped markets where kosher-certified spice and processed food exports could serve tourism and expatriate demand.
Industry Challenges
- Rabbinical Auditor Shortage:The pool of qualified mashgichim with industrial food science training has failed to keep pace with certification volume growth.
- Legacy Equipment Retrofit Costs:Converting existing dairy plants for kosher production requires steam-cleaning infrastructure and dedicated storage segregation that strains capex budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kosher Food Market |
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $73.45 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat, Dairy, Baked Goods, Snacks End User: Households, Restaurants, Catering Services, Retail Stores Distribution Channel: Online Stores, Supermarkets, Specialty Stores, Wholesale Certification Type: Orthodox Union, Star-K, Kof-K, Others |
| Companies Covered | PepsiCo, Cargill, Nestlé, Manischewitz, ADM, Conagra Brands, Unilever, Empire Kosher Poultry, General Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kosher Food Market Strategic Shifts & Innovations
Digital traceability and automated supervision tools are compressing certification timelines while expanding the geographic reach of reliable kosher verification beyond traditional rabbinical centers.
Blockchain-based supply chain tracking is automating ingredient provenance verification for multinational food manufacturers. Nestlé and Unilever procurement divisions have piloted distributed ledger systems to reduce audit preparation time. The technology is automating documentation workflows that previously required weeks of manual rabbinical review.
EU F-Gas Regulation phase-down mandates are reshaping refrigeration infrastructure in kosher slaughterhouses and cold storage facilities across France and Germany. Compliance deadlines are accelerating capital replacement cycles for ammonia-based systems. Polish and Hungarian meat processors are most exposed due to aging facility bases and limited access to retrofit financing.
Certification-driven preference consolidation is compressing buyer decision cycles in institutional channels. Hospital and university foodservice directors increasingly specify Orthodox Union or Star-K marks as sole-source requirements. This pattern is most visible in the northeastern United States, where contract consolidation at purchasing cooperatives has halved the number of approved kosher suppliers since 2019.
Kosher Food Market Segmentation
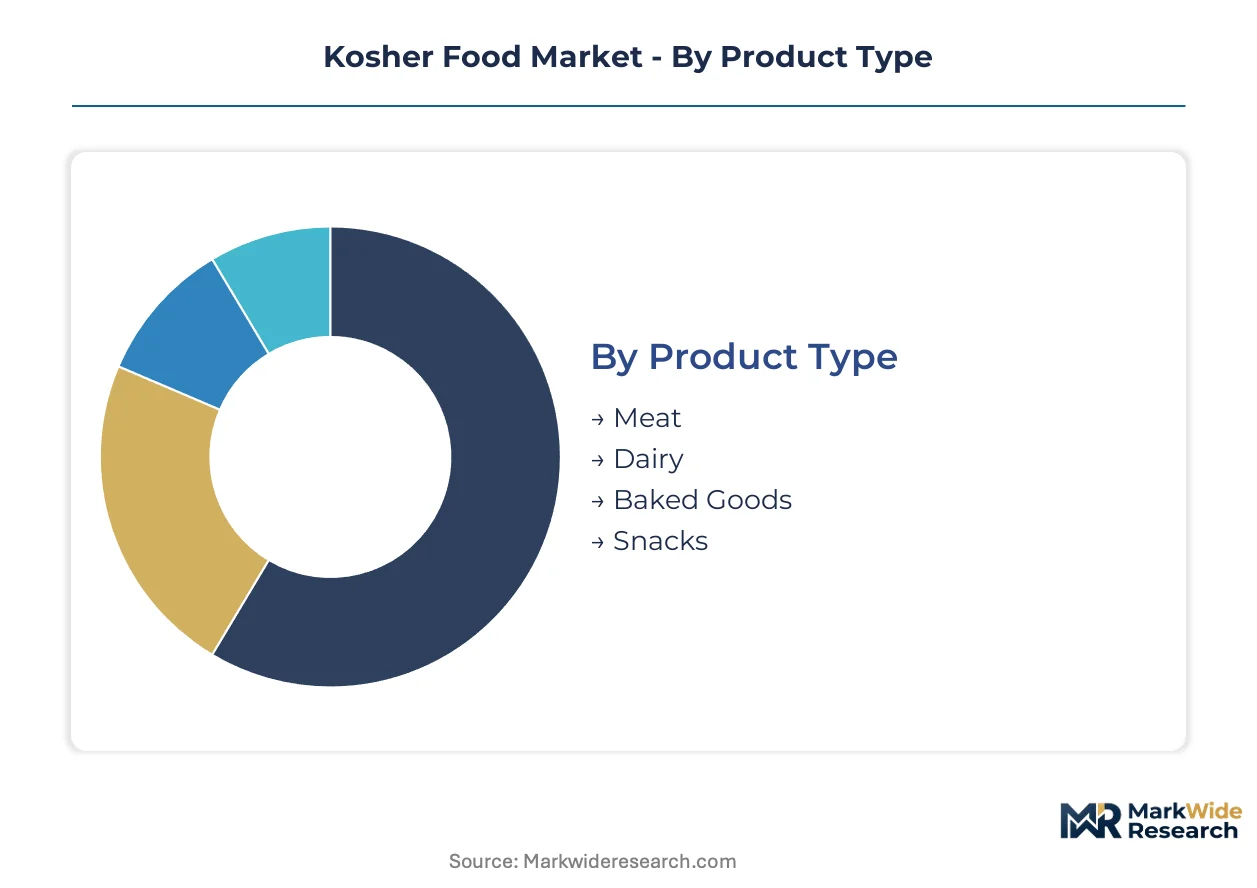
Segmentation in kosher food markets tracks how certification intensity and supervision costs distribute across product categories and buyer channels. Understanding these divides reveals where margin pressure concentrates and where premium pricing sustains profitability.
Product Type:
Certification burden varies sharply by product type, with live-animal processing demanding continuous mashgiach presence while packaged goods require only periodic facility audits.
- Meat:Requires shechita ritual slaughter with on-site rabbinical supervision throughout processing. Brooklyn and Jerusalem processing facilities absorb elevated labor costs that compress margins on commodity cuts.
- Dairy:Demands equipment kosherization and ingredient verification to prevent meat-dairy cross-contamination. Industrial cheese production in the Midwest United States concentrates volume due to proximity to kosher-certified milk pooling operations.
- Baked Goods:Parve (neutral) status expands distribution flexibility across meat and dairy meal occasions.
- Snacks:Convenience-oriented formats with simplified certification pathways are multiplying in metropolitan retail clusters.
Snacks sits at the top of the volume ranking, with Snacks climbing the fastest.
End User:
End-user segments separate by purchase frequency and certification stringency, with institutional buyers imposing stricter mark requirements than individual consumers.
- Households:Weekly grocery purchasers prioritize recognizable certification marks and parve versatility for meal planning flexibility.
- Restaurants:Full-service establishments in Tel Aviv and London maintain dedicated mashgichim to satisfy Orthodox Union or Star-K contractual requirements.
- Catering Services:High-volume event producers face compressed preparation windows that strain real-time supervision capacity.
- Retail Stores:Supermarket chains specify dual-label organic-kosher products to capture health-conscious metropolitan shoppers.
Households generates the largest revenue base, while Restaurants expands most quickly as kosher dining concepts proliferate in secular urban markets.
Distribution Channel:
Channel structure determines how certification documentation flows from manufacturer to final buyer, with direct channels compressing compliance verification steps.
- Online Stores:Subscription meal-kit services bypass traditional retail mark-up while maintaining chain-of-custody documentation through digital tracking.
- Supermarkets:Private-label consolidation in the northeastern United States has halved approved kosher supplier counts since 2019.
- Specialty Stores:Neighborhood markets in Brooklyn and Jerusalem sustain heritage brand loyalty through curated product selection.
- Wholesale:Institutional distributors specify sole-source Orthodox Union or Star-K requirements in hospital and university foodservice contracts.
Supermarkets commands the highest throughput, with Online Stores gaining share fastest among younger consumer cohorts.
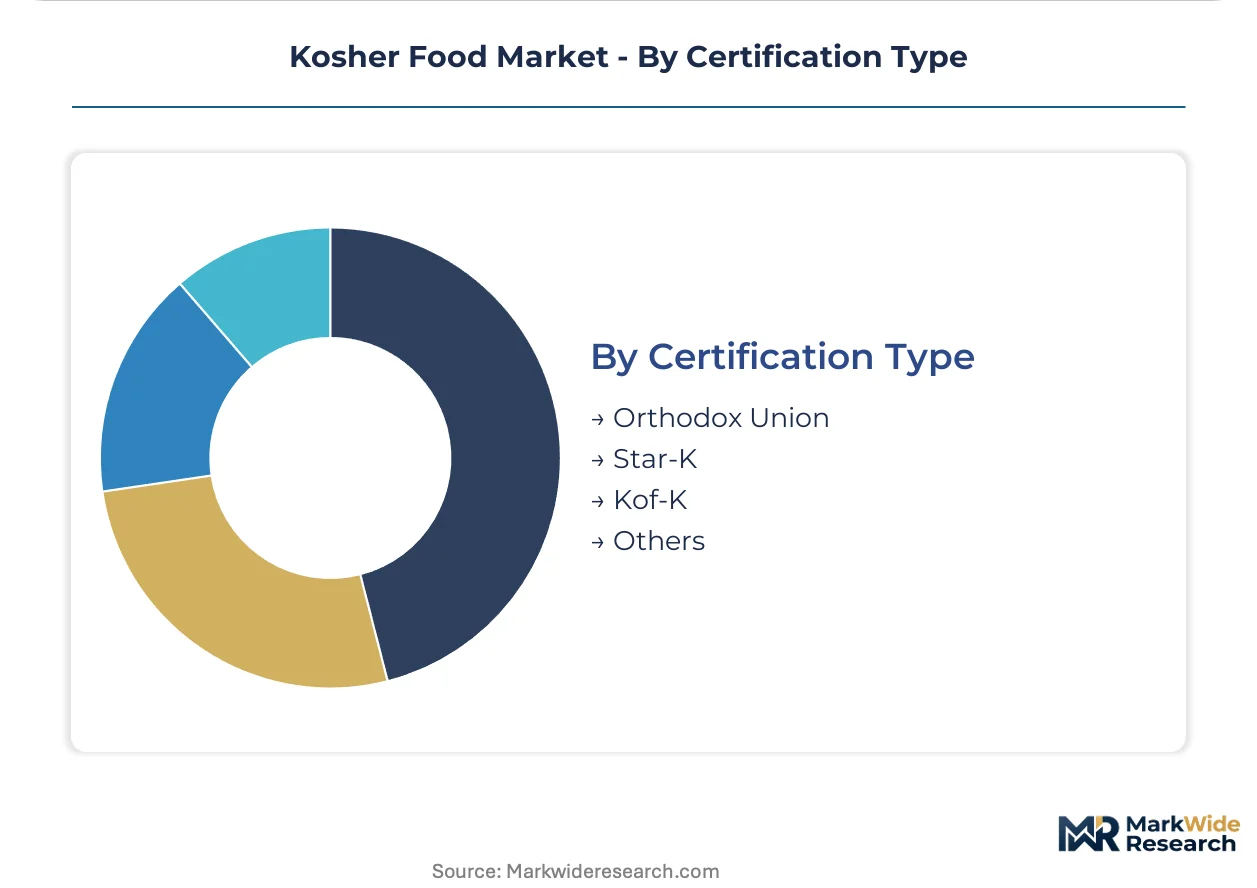
Certification Type:
Certification type structures competitive access to retail shelf space and institutional procurement channels, with mark recognition varying by geography and buyer denomination.
- Orthodox Union:The most widely recognized mark dominates retail presence across North American supermarket chains and influences trust thresholds for mainstream consumers.
- Star-K:Baltimore-based supervision maintains strong institutional foodservice penetration through technical food science expertise and industrial facility specialization.
- Kof-K:New Jersey headquarters supports dense metropolitan coverage in the northeastern United States with responsive local mashgiach deployment.
- Others:Regional and denominational marks serve specific community requirements in Israel, Europe, and smaller North American markets.
Orthodox Union holds the broadest geographic footprint, with Star-K deepening penetration fastest in institutional channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brooklyn's kosher industrial corridor generates the densest concentration of certified food manufacturing infrastructure outside Israel, with metropolitan New York anchoring North American certification demand and processing capacity.
United States
Orthodox Union and Star-K certification marks dominate supermarket shelf placement across the northeastern corridor. FDA labeling rules govern kosher claim presentation on interstate packaged goods. Brooklyn and Monsey processing clusters absorb elevated mashgiach labor costs while supplying kosher meat and dairy to institutional channels.
Israel
Domestic kashrut enforcement by the Chief Rabbinate creates unified national standards unmatched elsewhere. State-level kosher consumer protection frameworks in New York and New Jersey influence export compliance documentation for Israeli processors. Tel Aviv direct-to-consumer meal-kit startups bypass traditional retail markup through digital subscription channels.
Argentina
EU F-Gas Regulation compliance deadlines accelerate refrigeration infrastructure replacement in Buenos Aires and Rosario slaughterhouse facilities. Ritual slaughter operations install traceability systems to maintain European export eligibility. Pampas region cattle supply chains feed both domestic kosher consumption and international distribution networks.
United Kingdom
London's restaurant sector maintains dedicated mashgiach staffing to satisfy Orthodox Union contractual requirements for full-service establishments. Divergent EU member state interpretations of shechita stunning exemptions fragment cross-border meat trade compliance. Manchester and Stamford Hill neighborhood markets sustain heritage brand loyalty through curated kosher product selection.
India
Mumbai and Delhi present underdeveloped kosher-certified spice and processed food export opportunities serving tourism and expatriate demand segments. The country's national food safety regulator oversees baseline manufacturing standards that intersect with rabbinical supervision protocols. Gujarat and Maharashtra industrial zones concentrate glycerin and gelatin production critical to global kosher ingredient supply.
Kosher Food Market Key Industry Players
Global majors compete with regional champions across certification infrastructure and distribution reach, with multinational food conglomerates leveraging scale against heritage specialists defending niche loyalty. The vendor base separates into three tiers: diversified conglomerates with kosher as portfolio segment, dedicated kosher specialists with rabbinical supply relationships, and private-label contractors serving supermarket chains. Consolidation pressure concentrates in institutional channels where purchasing cooperatives halve approved supplier counts. Competitive moves center on backward integration into certified ingredient sourcing and geographic expansion of supervision networks.
Within the diversified conglomerate tier, Nestlé and PepsiCo occupy positions exemplifying global certification portfolio management across multiple continents. Cargill represents the upstream control archetype, supplying certified feedstock to downstream protein processors from grain-processing infrastructure. Manischewitz anchors the heritage specialist category, sustaining brand loyalty through retail and direct channels with rabbinically supervised traditional product lines.
| Leading Market Players |
|---|
| PepsiCo |
| Cargill |
| Nestlé |
| Manischewitz |
| ADM |
| Conagra Brands |
| Unilever |
| Empire Kosher Poultry |
| General Mills |
| Others |
Cost & Logistics Intelligence
EU F-Gas Regulation phase-down mandates gate both qualified refrigeration supply and premium-tier pricing access for kosher meat processors, as compliance deadlines in France and Germany accelerate capital replacement cycles that concentrate margin pressure on aging Polish and Hungarian facilities.
Pricing Analysis
Input-cost pass-through from mashgiach labor and certified ingredient premiums shapes contract structures across meat and dairy tiers. Pricing stratifies across premium shechita-supervised cuts, standard industrial dairy, and economy parve snacks based on supervision intensity and certification mark recognition. Cost compression in commodity meat segments intensifies because supermarket private-label consolidation halves approved supplier counts. Institutional foodservice buyers at hospital purchasing cooperatives show least price sensitivity, while household grocery purchasers in metropolitan clusters drive hardest bargain on parve convenience items.
Supply Chain Analysis
Domestic-content mandates in Israeli kashrut enforcement and US state-level consumer protection laws reshape sourcing documentation requirements for cross-border trade. Geographic supply concentration centers on Argentina and Uruguay for ritual slaughter infrastructure, Brazil and India for certified gelatin and glycerin, and the United States for industrial dairy processing. Raw material dependencies rest on Pampas region cattle, Indian subcontinent spice extracts, and Midwest kosher-certified milk pooling. Single-source vulnerability concentrates in Brazilian glycerin corridors exposed to port disruption. Distribution runs through institutional wholesale cooperatives in the northeastern United States and direct-to-consumer subscription channels in Tel Aviv and London.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The kosher food market reads as a late-cycle quality story, justified by demand-shift toward dual-label organic-kosher specifications that reward certified supply chain transparency with shelf space access.
For Market Incumbents: Extend certification infrastructure into plant-based protein categories before ingredient classification frameworks solidify. Anchor backward integration into certified feedstock sourcing to defend margin position against Cargill's grain-processing leverage. Prioritize Orthodox Union mark retention at hospital purchasing cooperatives where sole-source requirements are tightening. For New Entrants and Emerging Players: Blockchain-enabled supply chain verification offers a technology-first wedge into multinational manufacturer procurement divisions seeking audit preparation compression. Target Mumbai and Delhi spice export corridors where kosher-certified processing capacity remains underdeveloped. Pursue direct-to-consumer meal-kit subscription models bypassing retail mark-up concentration in Tel Aviv and London. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier private-label contractors serving supermarket chains facing margin compression from shelf space consolidation. Long-term viability over the coming decade hinges on cell-cultured protein certification pathway clarity. Watch EU member state shechita stunning exemption rulings as inflection indicator for cross-border meat trade fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Label Certification Investment | USDA organic overlap with kosher supervision streamlines compliance for health-conscious metropolitan clusters. |
| Blockchain Supply Chain Deployment | Nestlé and Unilever pilots reduce rabbinical audit preparation from weeks to automated documentation workflows. |
| Cell-Cultured Protein Certification | Precision fermentation technologies may bypass conventional shechita requirements for novel protein categories. |
| Direct-to-Consumer Channel Launch | Subscription meal-kit services capture younger Tel Aviv and London consumers bypassing traditional retail markup. |
| Indian Subcontinent Export Expansion | Mumbai and Delhi spice processing capacity addresses underdeveloped tourism and expatriate demand segments. |
Research Approach
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with mashgiach supervisors, kosher certification agency technical directors, supermarket category buyers, and institutional foodservice procurement managers combined with secondary validation from FDA labeling guidance documents, USDA organic certification databases, EU F-Gas Regulation compliance filings, and customs trade data. Triangulation across these sources anchored volume and value estimates.
Input-output matrices mapped certification intensity, supervision labor costs, and ingredient provenance requirements across product categories and buyer channels. Segmentation dimensions modeled include product type, end-user archetype, distribution channel, and certification mark tier across the projection horizon. CAGRs derived from trend extrapolation of certification volume growth, private-label expansion rates, and plant-based protein adoption curves, cross-checked against shechita infrastructure capacity constraints and mashgiach labor pool expansion limits.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU shechita regulatory fragmentation, cell-cultured protein classification rulings, and blockchain supervision technology adoption rates. Forecasts reflect documented assumptions about certification mark consolidation patterns and supermarket private-label trajectory. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Brahmi Market
Specialty Foods
Cat Food Flavors Market
Specialty Foods
North American Jam, Jelly, and Preserve Market
Specialty Foods
Asia-Pacific Tofu Market
Specialty Foods
Global Cocoa Nibs Market
Specialty Foods
Organic Skin Care Market
Specialty Foods
Fermented Black Beans Market
Specialty Foods
Postbiotic Pet Food Market
Specialty Foods
Global Hispanic Foods Market
Specialty Foods
Global Diet Food and Beverages Market
Specialty Foods
Low Calorie Vegetable Dip Market
Specialty Foods
Yeast-Based Spreads Market
Specialty Foods
Edible Cutlery Market
Specialty Foods
Moringa Products Market
Specialty Foods
Soft Tofu Market
Specialty Foods
Low Salt Low Fat Meals Market