
 Wet Grain-Free Pet Food Market | 2026-2036
Wet Grain-Free Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Wet Grain-Free Pet Food Market Insights
AAFCO nutrient profiles is unwinding competitive barriers for new entrants seeking shelf placement in North American retail. Mars Incorporated leverages captive supply chains for fresh protein sourcing across its wet grain-free lines. Nestlé Purina PetCare Company anchors its position through veterinary channel exclusivity and prescription diet crossover formulations. Blue Buffalo Co., Ltd. differentiates via LifeSource Bits inclusion technology and limited-ingredient positioning.
Wet grain-free pet food comprises moisture-rich formulations exceeding sixty percent water content, utilizing tapioca, pea starch, or potato as carbohydrate binders rather than wheat, corn, or rice, manufactured through retort sterilization or aseptic filling to achieve commercial sterility while preserving protein integrity. The ingredient type dimension shows meat-based recipes commanding the dominant margin pool as fresh and raw protein claims justify price premiums, while fish-based offerings capture fastest-growing demand driven by novel protein positioning for allergy-prone pets. Pouch packaging is displacing traditional cans among urban apartment dwellers seeking portion control and reduced refrigeration burden.
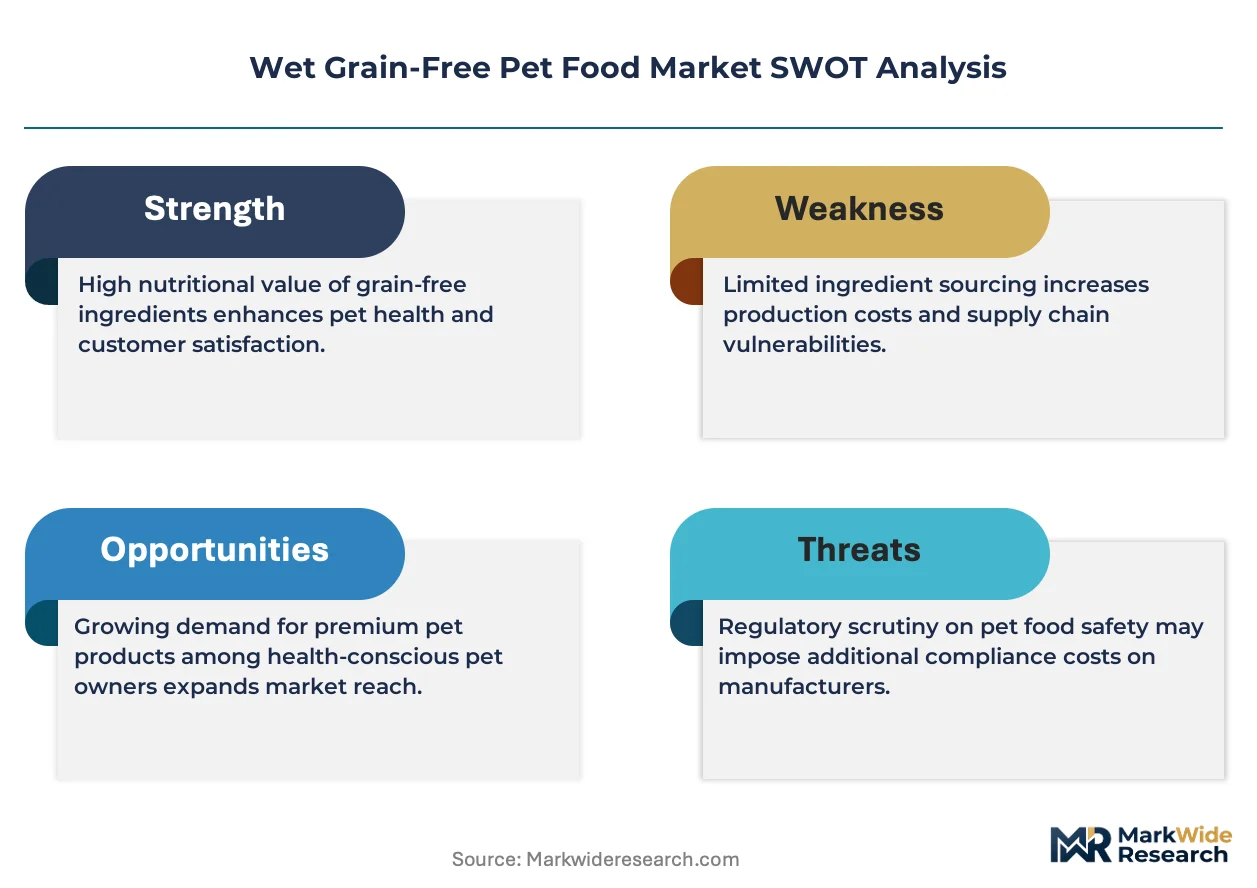
The US FDA Center for Veterinary Medicine scrutinizes grain-free diets for potential dilated cardiomyopathy linkages, pressuring reformulation toward taurine supplementation and transparent cardiac safety disclosures. State feed control officials enforce AAFCO model bill compliance, creating patchwork labeling requirements that complicate national distribution. Stakeholders must monitor emerging veterinary epidemiology and preemptively adapt formulation and communication strategies before regulatory thresholds harden into mandatory standards.
Market Dynamics
Urban pet ownership density is compressing distribution economics and forcing format innovation as apartment-dwelling consumers reject bulky can multipacks in favor of single-serve portability.
Growth Catalysts
- AAFCO Nutrient Profiles:The AAFCO model bill standardization is reducing regulatory friction for new entrants seeking retail shelf placement across US state lines.
- Retort Pouch Technology:Flexible retort pouch manufacturing lines enable portion-controlled SKUs that reduce per-meal cost perception among price-sensitive premium buyers.
- Metropolitan Coastal Corridors:Concentrated demand in Boston-to-Washington and Seattle-to-San Diego corridors creates route-density efficiencies for cold-chain logistics providers.
Market Restraints
- Fresh Protein Input Volatility:Spot market pricing for human-grade chicken and turkey breast creates margin compression during commodity spikes.
- Retort Sterilization Capacity Concentration:Third-party retort tolling capacity clusters in the Midwest, forcing coastal brands to absorb inbound freight costs on finished goods.
- Dilated Cardiomyopathy Uncertainty:The FDA Center for Veterinary Medicine's ongoing investigation into grain-free cardiac linkages creates formulation risk and disclosure liability.
Strategic Opportunities
- Veterinary Channel Crossover:Prescription diet adjacencies allow brands to capture therapeutic positioning and reimbursement-adjacent purchasing.
- Novel Protein Positioning:Rabbit, venison, and kangaroo formulations address allergy-prone pet populations underserved by chicken-beef dominance.
- Subscription Direct-to-Consumer:Auto-replenishment models bypass slotting fee barriers and capture lifetime value through predictable consumption cadences.
Industry Challenges
- Retort Engineering Talent Scarcity:Specialized thermal process authorities capable of validating aseptic filling protocols command premium compensation and extended search timelines.
- State-by-State Labeling Patchwork:California's Proposition 65 warnings and New York's agricultural labeling requirements force SKU proliferation or lowest-common-denominator compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wet Grain-Free Pet Food Market |
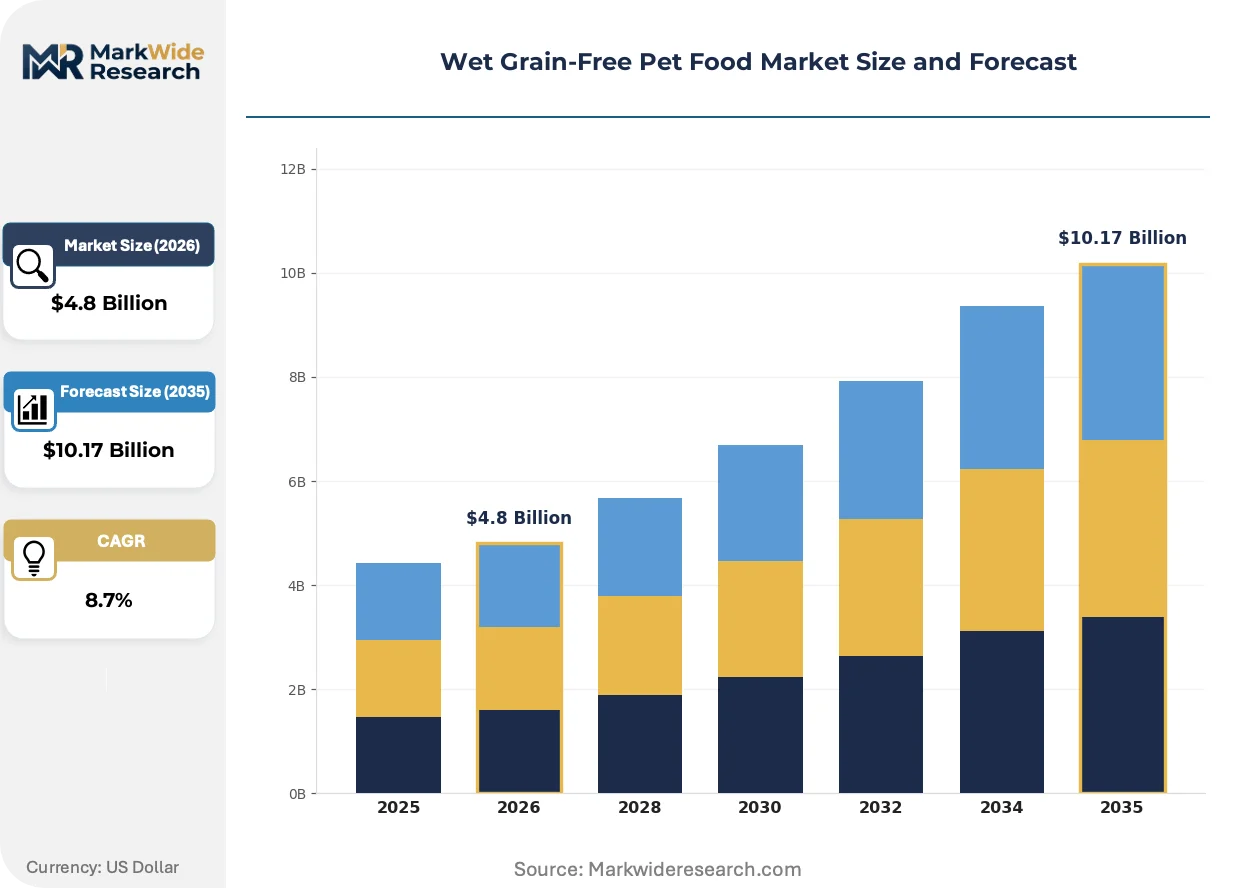
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned Food, Pouches, Tubs, Jars Ingredient Type: Meat-Based, Fish-Based, Vegetable-Based, Fruit-Based Pet Type: Dogs, Cats, Ferrets, Rabbits Packaging Type: Single-Serve, Multi-Pack, Bulk, Eco-Friendly |
| Companies Covered | Nestlé Purina PetCare Company, Mars Incorporated, General Mills, Blue Buffalo Co., Ltd., Hill's Pet Nutrition, The J.M. Smucker Company, Wellness Pet Company, Champion Petfoods LP, WellPet LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wet Grain-Free Pet Food Market Trends and Innovations
Formulation transparency and packaging format innovation are compressing traditional competitive moats as ingredient storytelling becomes the primary purchase trigger in premium channels.
Aseptic filling technology for wet grain-free formulations is fragmenting the manufacturing base by enabling smaller-batch production with reduced thermal degradation of heat-sensitive vitamins. Mid-sized regional brands in Texas and Florida are adopting European-imported aseptic lines to launch limited-ingredient SKUs without committing to high-volume retort runs. This technology is fragmenting capacity concentration away from legacy Midwest retort clusters toward distributed coastal production.
The FDA Center for Veterinary Medicine's taurine supplementation guidance is pressuring reformulation across all grain-free wet lines regardless of protein base. Manufacturers must now validate amino acid profiles through third-party laboratory certification, adding fixed compliance costs per SKU. Small and mid-sized brands in the Pacific Northwest are responding fastest, preemptively disclosing cardiac safety testing to differentiate against slower-moving national portfolios.
Urban subscription buyers are consolidating purchase decisions around veterinary endorsement and transparent supply chain documentation rather than price-per-ounce comparison. Independent pet specialty retailers in Denver and Austin are unbundling traditional distributor relationships to source directly from regional manufacturers with verifiable protein provenance. This behavioral shift is most visible among millennial pet owners in secondary metropolitan markets where veterinary influence on feeding decisions exceeds national averages.
Wet Grain-Free Pet Food Market Segmentation
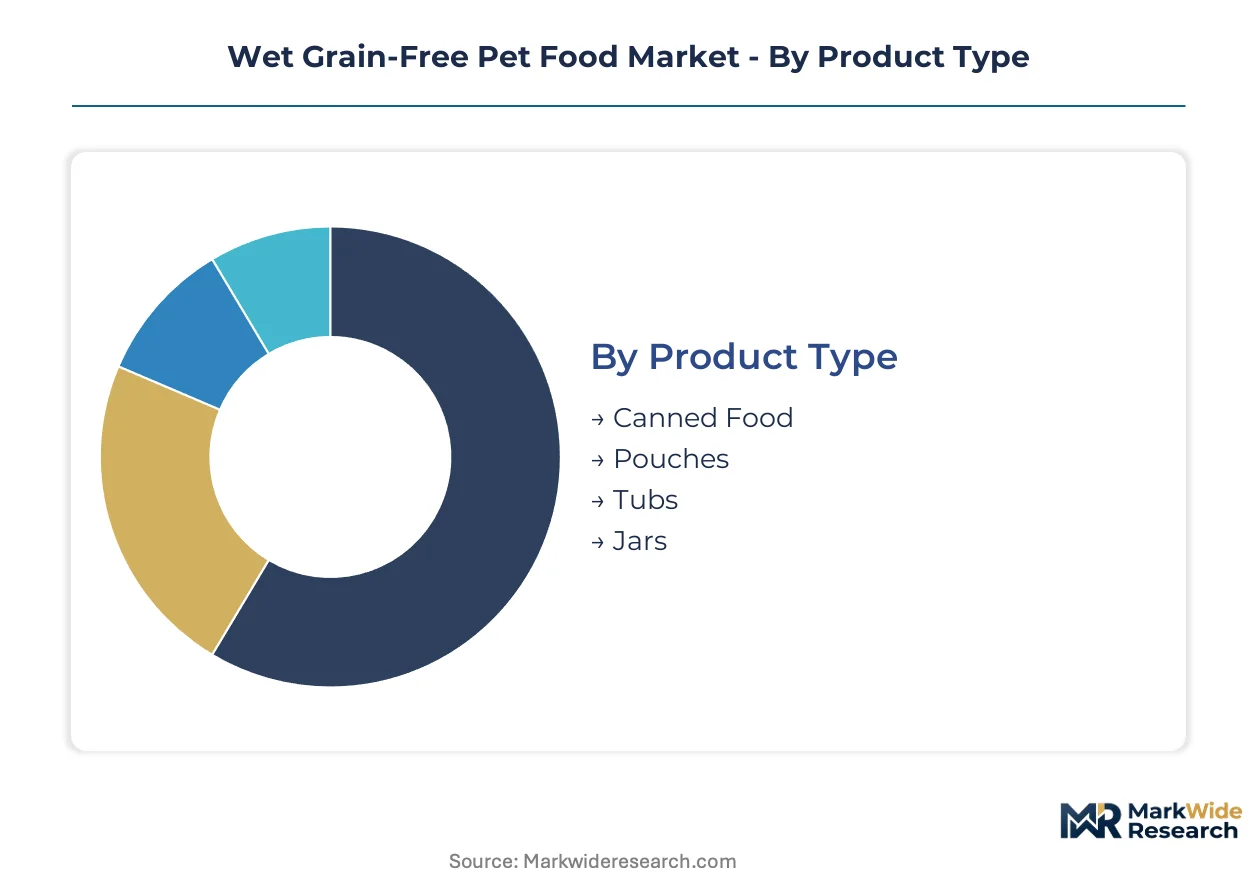
Wet grain-free pet food segmentation reveals how packaging format and protein sourcing decisions cascade through regulatory compliance costs and cold-chain logistics. Manufacturers must align SKU architecture with AAFCO nutrient profile requirements while serving distinct urban household constraints.
Product Type:
AAFCO labeling harmonization has compressed regulatory differentiation across retort-processed formats, forcing manufacturers to compete on portion economics and storage convenience rather than compliance arbitrage.
- Canned Food:Traditional aluminum can formats withstand aggressive retort sterilization cycles while maintaining twelve-to-twenty-four month shelf stability. Demand concentrates in suburban households with dedicated pantry storage and multi-pet feeding routines where unit cost efficiency outweighs portability concerns.
- Pouches:Flexible multilayer retort pouches reduce shipping cube and refrigeration burden for apartment-dwelling consumers in Boston, Seattle, and San Diego corridors. The format commands price premiums through single-serve convenience despite higher per-ounce manufacturing costs.
- Tubs:Refrigerated fresh-tub formats bypass retort thermal degradation but require continuous cold-chain distribution and seven-to-fourteen day consumption windows.
- Jars:Glass jar packaging serves premium positioning in specialty retail channels with visible ingredient layering and resealability for intermittent feeders.
Canned food handles the majority of throughput; pouches are expanding most quickly on share.
Ingredient Type:
Cost tier stratification separates commodity protein inputs from novel sourcing premiums, with veterinary endorsement increasingly determining reimbursement-adjacent purchasing decisions.
- Meat-Based:Chicken, turkey, and beef formulations dominate volume through established supply chains and AAFCO nutrient profile compliance. Fresh protein claims from human-grade breast meat justify twenty-to-forty percent price premiums in coastal metropolitan markets.
- Fish-Based:Salmon, whitefish, and tuna recipes capture fastest-growing demand among allergy-prone pet populations seeking novel protein rotation. The segment faces mercury testing burdens and sustainability certification requirements that smaller brands struggle to satisfy.
- Vegetable-Based:Pea protein and lentil formulations serve vegetarian positioning and cost-sensitive premium buyers, though FDA cardiac safety scrutiny has pressured taurine supplementation mandates.
- Fruit-Based:Limited-ingredient recipes incorporating pumpkin, blueberry, and cranberry target digestive health and urinary tract positioning with restricted distribution in veterinary channels.
Meat-based recipes anchor volume throughput; fish-based offerings are gaining share fastest.
Pet Type:
Customer type concentration in urban millennial households drives species-specific format innovation, with feline feeding patterns forcing distinct moisture-content and texture specifications.
- Dogs:Larger portion formats and chewable texture profiles accommodate higher daily caloric requirements. Demand clusters in multi-dog households along the I-95 corridor from Washington to Boston.
- Cats:Obligate carnivore physiology requires elevated protein density and specific amino acid profiles, with pate and shredded textures driving repeat purchase loyalty in single-cat apartments.
- Ferrets:High-metabolism formulations with thirty-five percent minimum protein content serve niche exotic pet ownership concentrated in Pacific Northwest and Florida markets.
- Rabbits:Timothy hay-inclusive recipes with controlled calcium levels address dental health requirements in growing small-mammal specialty channels.
Dog formulations handle the majority of throughput; cat-specific recipes are climbing the fastest on share.
Packaging Type:
Supply concentration in Midwest retort capacity forces coastal brands to absorb inbound freight costs, making packaging-light formats economically decisive for margin preservation.
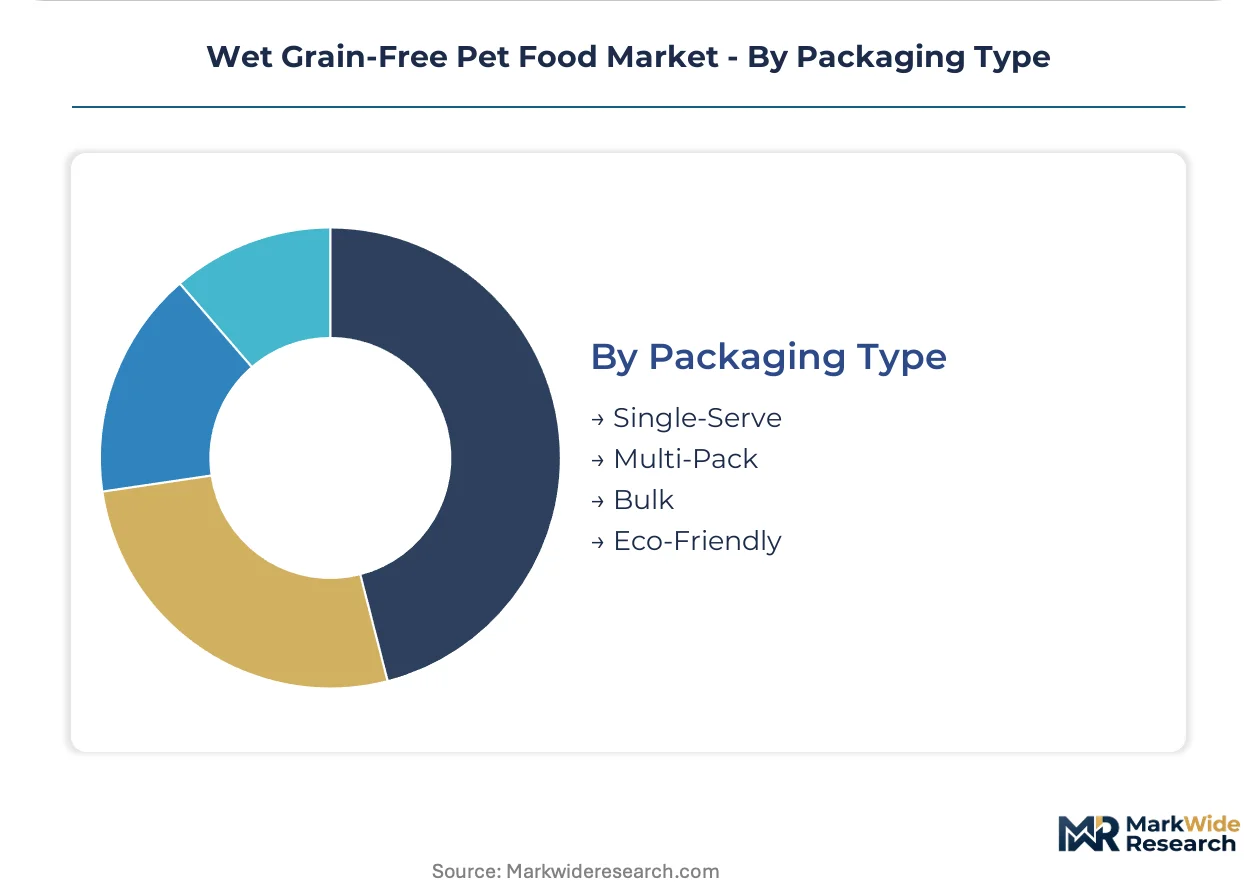
- Single-Serve:Individual pouches and small cans reduce spoilage risk for intermittent feeders and support subscription auto-replenishment models with predictable consumption cadences.
- Multi-Pack:Four-to-twelve unit configurations balance per-meal cost perception with storage efficiency for established feeding routines in suburban households.
- Bulk:Institutional pails and food-service formats serve breeding operations, shelters, and veterinary hospitals with price-sensitive volume purchasing.
- Eco-Friendly:Recyclable aluminum, post-consumer recycled content, and compostable materials capture sustainability-motivated buyers in Denver, Austin, and Portland markets.
Single-serve configurations handle the majority of throughput; eco-friendly alternatives are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban millennial households with premium pet ownership drive geographic concentration, clustering demand in coastal metropolitan corridors where apartment density and veterinary channel access intersect.
United States
Metropolitan corridors from Boston to Washington and Seattle to San Diego concentrate demand through cold-chain logistics efficiencies. The FDA Center for Veterinary Medicine enforces taurine supplementation guidance for grain-free cardiac safety. Mars Incorporated leverages captive supply chains across its wet grain-free lines in these coastal markets.
Germany
Pet humanization trends in Berlin and Munich drive premium wet food adoption among single-person households. EFSA guidelines on pet food labeling harmonize with national feed regulations through the German Federal Ministry of Food and Agriculture. Regional manufacturers in Bavaria specialize in novel protein formulations for allergy-prone pets.
United Kingdom
London and Southeast England anchor demand through veterinary channel crossover purchasing and subscription direct-to-consumer models. The Food Standards Agency coordinates with DEFRA on pet food safety standards post-Brexit. Specialty retailers in Greater Manchester source directly from regional manufacturers with verifiable protein provenance.
Japan
Tokyo's dense apartment living compresses distribution economics toward single-serve pouch formats. METI oversees pet food quality labeling standards that exceed baseline international requirements. Osaka-based manufacturers adopt aseptic filling technology to serve premium positioning in Kansai metropolitan markets.
Australia
Sydney and Melbourne drive fish-based recipe demand through novel protein positioning for allergy management. The TGA coordinates with state agriculture departments on imported pet food biosecurity. Queensland manufacturers face sustainability certification requirements for tuna and salmon sourcing that smaller brands struggle to satisfy.
Wet Grain-Free Pet Food Market Competitive Landscape
Player mix skews toward multinational consumer goods conglomerates with captive veterinary channels and captive supply chains. Tier-one positions cluster around three strategic archetypes: diversified food conglomerates with pet care divisions, pure-play premium specialists with limited-ingredient positioning, and veterinary-exclusive prescription diet crossovers. Dominant competitive moves include backward integration into fresh protein sourcing and geographic expansion through acquisition of regional aseptic filling capacity.
Within the diversified conglomerate tier, Nestlé Purina PetCare Company and Mars Incorporated exemplify scale-driven positioning through captive supply chains and veterinary channel exclusivity. Blue Buffalo Co., Ltd. occupies the pure-play premium specialist archetype with technology-driven differentiation. These three anchors demonstrate how formulation transparency and packaging innovation compress traditional competitive moats in coastal metropolitan markets.
| Leading Market Players |
|---|
| Nestlé Purina PetCare Company |
| Mars Incorporated |
| General Mills |
| Blue Buffalo Co., Ltd. |
| Hill's Pet Nutrition |
| The J.M. Smucker Company |
| Wellness Pet Company |
| Champion Petfoods LP |
| WellPet LLC |
| Others |
Pricing and Supply Chain Analysis
AAFCO nutrient profile compliance gates both supplier qualification and price tier differentiation simultaneously, as brands lacking third-party laboratory certification face exclusion from premium retail placement regardless of ingredient sourcing quality.
Pricing Analysis
Cost-plus contracts with Chicago Mercantile Exchange poultry indexation dominate protein input agreements, transferring commodity volatility directly to finished goods pricing. Three-tier pricing structure across premium, standard, and economy levels separates veterinary-endorsed therapeutic lines from mass-market grain-free alternatives, with after-sales service bundling commanding additional margin. Pricing pressure stems from spot market spikes in human-grade chicken breast, compressing margins for mid-tier brands lacking backward integration into captive protein supply. Subscription auto-replenishment buyers exhibit lowest price sensitivity, while shelter and breeding operations in bulk channels negotiate aggressively on per-pound economics.
Supply Chain Analysis
Inbound logistics costs from Midwest retort clusters to coastal metropolitan markets absorb twelve-to-fifteen percent of landed cost, with container availability constraints on Chicago-to-Seattle rail lanes exacerbating working capital cycles. Manufacturing concentrates in the United States Midwest, with secondary aseptic filling capacity emerging in Texas and Florida. Fresh protein inputs draw from Georgia, Arkansas, and North Carolina poultry operations, while tapioca and pea starch binders source from Thailand and Canada respectively. Single-source vulnerability in third-party retort tolling creates bottleneck risk during capacity crunches. Distribution runs through veterinary-exclusive wholesalers, pet specialty distributors, and direct-to-consumer fulfillment centers serving subscription households.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wet grain-free pet food represents high-growth disruption as aseptic filling technology fragments manufacturing concentration and enables regional brands to bypass legacy retort capacity constraints. FDA taurine supplementation guidance accelerates this inflection by imposing fixed compliance costs that favor agile mid-tier players over slower-moving national portfolios.
For Market Incumbents: Consolidate backward integration into fresh protein sourcing to defend margin position against commodity volatility, while preemptively acquiring regional aseptic filling capacity in Texas and Florida to neutralize emerging coastal competitors. Threat substitution from direct-to-consumer subscription models demands channel control through veterinary-exclusive formulations and captive distributor relationships. Priority lever rests on certification investment for third-party cardiac safety testing to maintain shelf placement advantage.
For New Entrants and Emerging Players: Lead with novel protein positioning in Pacific Northwest and Rocky Mountain metropolitan corridors, where veterinary influence on feeding decisions exceeds national averages and allergy-prone pet populations remain underserved by chicken-beef dominance. Most penetrable segment clusters around single-serve pouch formats for urban apartment dwellers seeking portion control and reduced refrigeration burden. Go-to-market angle emphasizes transparent supply chain documentation and preemptive taurine disclosure to differentiate against slower-moving incumbents.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates seeking to divest non-core pet care divisions amid portfolio restructuring pressures. Long-term viability frames around five-to-ten year consolidation toward brands with captive veterinary channels and proven subscription retention economics. Acquisition archetype prioritizes regional aseptic filling specialists with European-imported lines and established coastal distribution. Signal to monitor involves FDA cardiac safety guidance hardening into mandatory testing standards, which would accelerate compliance cost advantages for pre-invested portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fresh Protein Sourcing | Mars Incorporated leverages captive Georgia poultry operations to stabilize input costs against CME index volatility. |
| Aseptic Filling Technology Adoption | European-imported lines enable Texas and Florida brands to launch limited-ingredient SKUs without high-volume retort commitments. |
| Veterinary Channel Crossover Formulations | Nestlé Purina PetCare Company captures therapeutic positioning and reimbursement-adjacent purchasing through prescription diet adjacencies. |
| Subscription Direct-to-Consumer Launch | Auto-replenishment models bypass slotting fee barriers and capture lifetime value through predictable consumption cadences in Denver and Austin. |
| Novel Protein Portfolio Expansion | Rabbit, venison, and kangaroo formulations address allergy-prone pet populations in Seattle-to-San Diego coastal corridors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA Center for Veterinary Medicine guidance documents, AAFCO model bill regulatory filings, and USDA poultry production statistics. Primary interviews engaged brand managers at multinational pet care divisions, procurement leads at third-party retort tolling facilities, veterinary channel sales heads, and category buyers at independent pet specialty retailers in Denver and Austin. Secondary validation drew from Nielsen retail audit data, customs records for tapioca and pea starch imports, and SEC 10-K disclosures from diversified food conglomerates with pet care segments. Bottom-up SKU-level volume modeling triangulated against top-down market sizing across ingredient type and packaging format dimensions.
Segmentation dimensions modeled include product type, ingredient sourcing, pet species, and packaging configuration across the analysis window. CAGRs derive from regression analysis of historical consumption patterns projected through stated regulatory and technological assumptions. Industry-specific forecast inputs incorporate veterinary endorsement influence coefficients by metropolitan market density and cold-chain logistics cost curves for refrigerated fresh-tub formats.
The analysis sits within stated boundaries; outcomes outside sustained AAFCO compliance cost structures and continued FDA cardiac safety scrutiny would require recalibration. Forecasts reflect assumptions regarding aseptic filling technology adoption rates and coastal metropolitan demand concentration. Specific risk factors that could revise projections include mandatory taurine testing standards, retort capacity consolidation in the Midwest, and substitution toward fresh-frozen raw alternatives. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Hot and Sour Noodles Market
Specialty Foods
Guacamole Market
Specialty Foods
Manuka Honey Market
Specialty Foods
High Protein Cat Food Market
Specialty Foods
Low Salt Low Fat Meals Market
Specialty Foods
Global Cocoa Nibs Market
Specialty Foods
Low Fat and Low Carb Foods Market
Specialty Foods
US Jam Jelly and Preserves Market
Specialty Foods
Konjac Noodles Market
Specialty Foods
Cat Food Flavors Market
Specialty Foods
Aloe Vera Gel Market
Specialty Foods
Superfood Bars Market
Specialty Foods
Low Calorie Hummus Market
Specialty Foods
Fermented Black Beans Market
Specialty Foods
Fruit Dessert Market
Specialty Foods
North America Popping Boba/Juice Balls Market