
 Fruit Dessert Market | 2026-2036
Fruit Dessert Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit Dessert Market Foresight
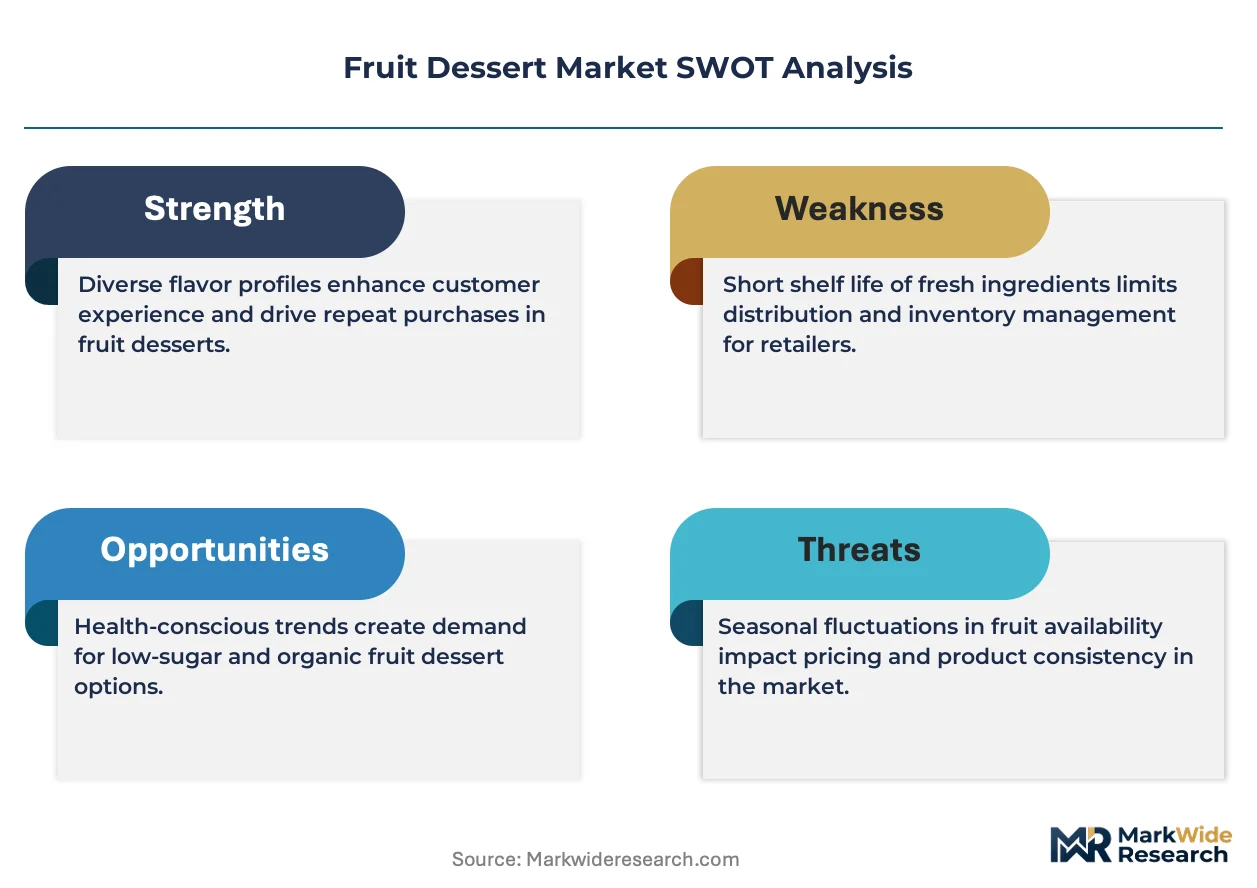
EU Green Deal implementation is rebalancing cost-of-entry calculus for fruit dessert manufacturers serving European markets. Nestlé leverages its frozen dessert infrastructure across multiple climate zones to sustain volume leadership. Unilever anchors its competitive position through plant-based formulation R&D that navigates evolving clean-label requirements.
Fruit desserts comprise prepared food products featuring fruit as the primary ingredient, typically preserved through freezing, chilling, or controlled-atmosphere packaging to maintain organoleptic properties and nutritional integrity. These products serve commercial and retail channels requiring convenient, portion-controlled offerings with visible fruit content. Frozen fruit desserts dominate value capture due to extended shelf stability and established cold-chain logistics, while fruit sorbets represent the fastest-expanding margin pool as dairy-free demand accelerates. Solid-form products occupy the mature volume core, whereas gel and creamy formats are gaining traction in specialty retail and hospitality channels where texture differentiation commands premium positioning.
FDA standards for frozen dessert identity and labeling shape product composition requirements in the United States, while EFSA guidelines on added sugars and novel ingredients determine formulation thresholds across European markets. BIS certification requirements in India affect import access and local manufacturing specifications for multinational suppliers. Stakeholders must monitor diverging regulatory timelines for sugar reduction mandates and single-use packaging restrictions that will reshape ingredient sourcing and format prioritization decisions.
Market Dynamics
Clean-label reformulation mandates under the EU Green Deal are compressing formulation timelines for fruit dessert manufacturers while simultaneously opening premium positioning for compliant producers. This regulatory pressure cascades through supply chains, forcing ingredient substitution decisions and packaging redesign commitments years ahead of enforcement deadlines.
Growth Catalysts
- EU Green Deal packaging mandates:The phased reduction of single-use plastics in prepared foods is accelerating investment in biodegradable and fiber-based alternatives across European manufacturing facilities.
- Food service channel expansion:Commercial kitchens in Southeast Asian hospitality markets are scaling tropical fruit dessert procurement as tourism infrastructure rebounds and menu differentiation intensifies.
- High-pressure processing:Cold-pasteurization technology is extending refrigerated fruit dessert shelf life without thermal degradation, enabling broader retail distribution for chilled formats.
Market Restraints
- Input cost volatility:Climate-driven irregularity in mango, passion fruit, and berry harvests concentrates price risk for processors dependent on specific tropical and temperate growing regions.
- Supply concentration risk:Frozen fruit pulp processing capacity clusters in Vietnam, Thailand, and Ecuador, creating vulnerability to regional weather events and port congestion.
- Technical limitation:Current clean-label stabilizer alternatives fail to replicate the freeze-thaw stability of modified starches in fruit gel applications, constraining texture innovation.
Strategic Opportunities
- Underpenetrated geography:India's organized retail expansion and cold-chain infrastructure investment create accessible white space for branded frozen fruit dessert entry.
- Regulatory tailwind:The EU Deforestation Regulation's traceability requirements favor vertically integrated fruit suppliers with documented supply chain transparency.
- Technology convergence:Precision fermentation-derived fruit flavor compounds combined with cellular agriculture texturizers enable novel dairy-free mousse formats with authentic mouthfeel.
Industry Challenges
- Reformulation expertise gap:Food technologists with cross-functional knowledge of clean-label stabilizers, fruit chemistry, and thermal process optimization command scarcity premiums.
- Capex intensity:Cold-chain expansion for chilled fruit desserts requires refrigeration infrastructure investment that exceeds frozen distribution economics.
- Certification timeline compression:Organic and carbon-neutral certification audits for fruit sourcing are extending lead times, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit Dessert Market |
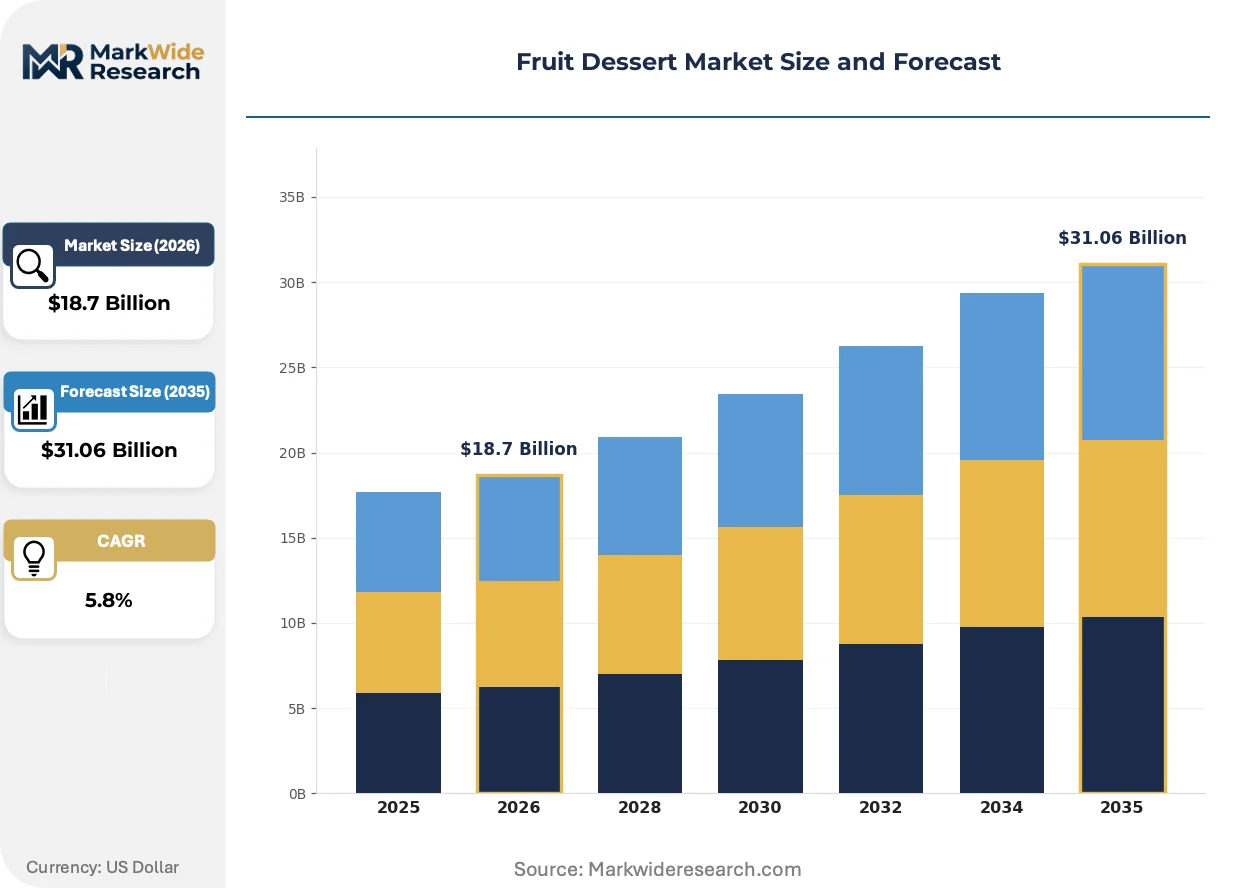
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Fruit Desserts, Fresh Fruit Salads, Fruit Parfaits, Fruit Sorbets, Fruit Tarts Form: Solid, Semi-Solid, Gel, Liquid, Creamy Application: Retail, Food Service, Hospitality, Catering, Event Management Customer Type: Individual Consumers, Food Manufacturers, Specialty Stores, Online Retailers |
| Companies Covered | Natural Fruit Corporation, JonnyPops, Nestlé, Beyond Better Foods LLC, Whole Fruit, Wells Enterprises, Inc., Paleteria La Michoacana, GoodPop, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit Dessert Market Shifts & Advancements
Active packaging technologies and precision fermentation are converging to redefine preservation and formulation boundaries in fruit desserts. These developments intersect with shifting procurement patterns that favor traceable, low-carbon supply chains.
Hurdle technology combining modified atmosphere packaging with natural antimicrobial coatings is integrating into premium chilled fruit dessert lines. Specialty retailers in Germany and France are adopting these formats to reduce spoilage and extend shelf presence. The technology is integrating quality assurance protocols that previously required frozen distribution, compressing the cost gap between chilled and frozen segments.
EFSA's evolving guidance on novel ingredients and added sugar thresholds is tightening formulation constraints for European manufacturers. This regulatory pressure is accelerating R&D investment in fruit juice concentrate reduction and fiber-based bulking agents. Chilled fruit cups and fruit-based snacks targeting school nutrition programs face the most immediate compliance deadlines.
Direct sourcing contracts between fruit dessert manufacturers and grower cooperatives are displacing traditional commodity procurement in the premium segment. Food service operators in Nordic markets are prioritizing single-origin fruit provenance in their supplier qualification criteria. This shift is most visible in strawberry and raspberry dessert applications where varietal differentiation commands measurable price premiums.
Fruit Dessert Market Segmentation
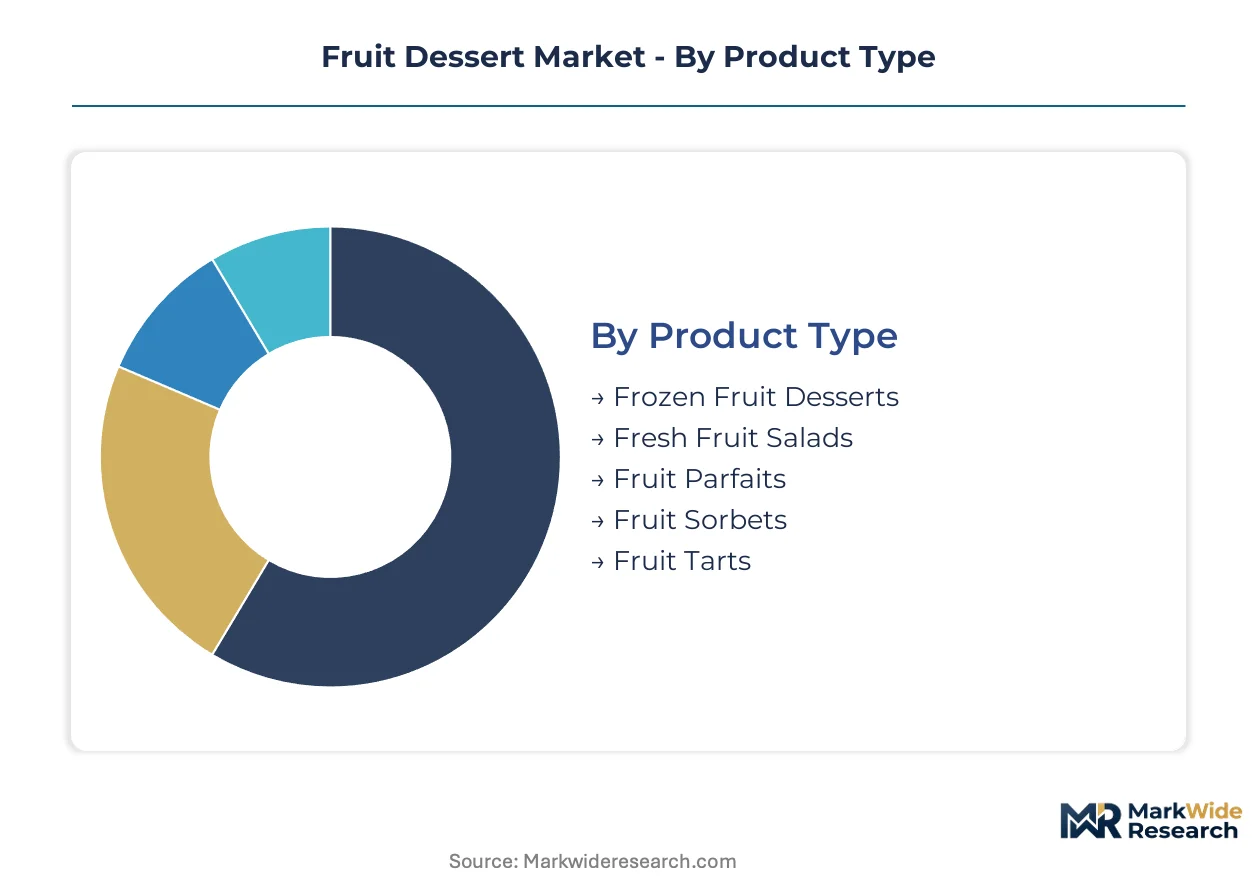
Segmentation in fruit desserts reveals divergent margin profiles across preservation technologies and channel access models. Manufacturers prioritize format selection based on cold-chain infrastructure maturity and clean-label compliance thresholds in target markets.
Product Type:
Replacement cycles in fruit dessert categories accelerate as hospitality operators refresh menus seasonally and retailers rotate stock to capture novelty-seeking consumers.
- Frozen Fruit Desserts:These products combine fruit pulp with stabilizers in sub-zero preservation systems, extending shelf life to 12-18 months. Demand concentrates in German and French retail chains where freezer aisle expansion supports premium positioning, though energy costs for cold storage compress margins.
- Fruit Sorbets:Dairy-free formulations using high fruit content and minimal added sugars target lactose-intolerant and vegan consumer segments. Southeast Asian hospitality procurement in Bangkok and Singapore hotels is climbing fastest as tourism infrastructure recovers and menu differentiation intensifies.
- Fresh Fruit Salads:Chilled, ready-to-eat combinations requiring controlled-atmosphere packaging and rapid distribution.
- Fruit Parfaits:Layered assemblies of fruit, yogurt, and granola targeting grab-and-go retail channels.
- Fruit Tarts:Pastry-based formats with fresh or preserved fruit toppings, dominant in European patisserie and cafe segments.
Volume placements concentrate in Frozen Fruit Desserts; the faster expansion belongs to Fruit Sorbets.
Form:
Cost tier differentiation in fruit dessert formats separates premium texture engineering from commodity bulk offerings.
- Solid:Frozen bars, fruit leathers, and dried fruit confections with extended ambient stability. Mass-market retail in India and Brazil favors these for distribution economics.
- Semi-Solid:Spoonable preparations including compotes and fruit mousses with intermediate moisture content.
- Gel:Pectin or agar-set fruit matrices requiring precise thermal control. Japanese convenience stores and Korean cafe chains are expanding gel-format procurement for visual appeal and portion control.
- Liquid:Drinkable fruit purees and smoothie bases, gaining traction in food service beverage programs.
- Creamy:Emulsion-based formats combining fruit with dairy or plant-based fats. Precision fermentation texturizers from California and Netherlands biotech suppliers are enabling cleaner-label creamy products.
Solid forms dominate unit volume; creamy formats are climbing the fastest as plant-based dairy alternatives mature.
Application:
Application segmentation tracks how procurement authority and quality specifications diverge between self-directed consumers and institutional buyers.
- Retail:Branded packaged goods sold through supermarkets, hypermarkets, and convenience stores. EFSA sugar reduction mandates are forcing reformulation across European retail SKUs.
- Food Service:Bulk and portion-controlled supplies to restaurants, cafes, and institutional kitchens. Vietnam and Thailand hotel chains are scaling tropical fruit dessert procurement as tourism rebounds.
- Hospitality:Premium-positioned offerings in hotels, resorts, and cruise lines with emphasis on provenance storytelling.
- Catering:Event-scale production requiring consistency at volume and transport stability.
- Event Management:Customized, presentation-focused desserts for weddings, corporate functions, and exhibitions.
Retail channel volume leads; food service is gaining share fastest as out-of-home consumption normalizes post-pandemic.
Customer Type:
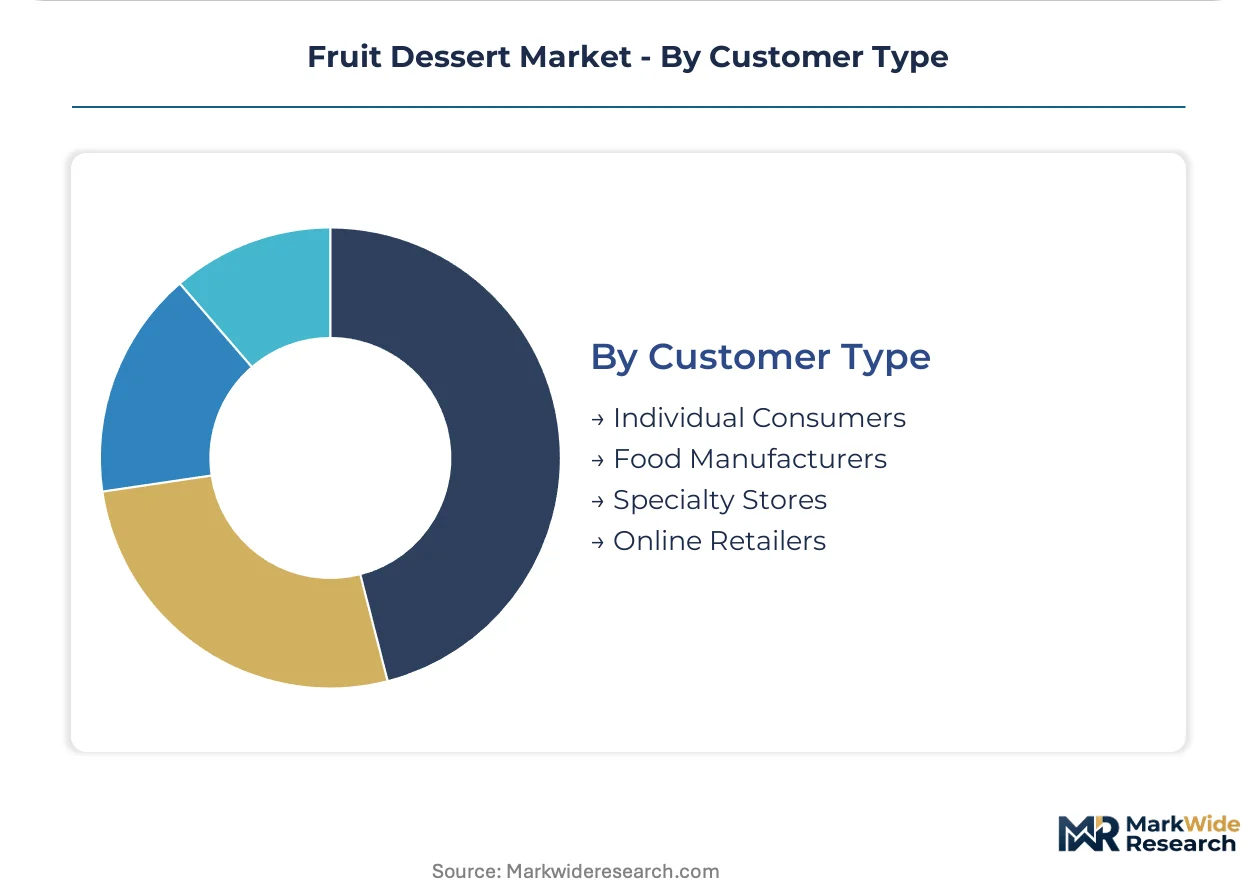
Customer segmentation in fruit desserts separates fragmented end-user demand from concentrated manufacturing procurement with divergent specification requirements.
- Individual Consumers:Household purchasers selecting based on price, convenience, and visible fruit content. Clean-label preferences in Nordic markets and Germany drive premium willingness-to-pay.
- Food Manufacturers:Industrial buyers sourcing fruit preparations as ingredients for composite products. BIS certification requirements in India constrain import access for multinational suppliers.
- Specialty Stores:Curated retail formats emphasizing organic, local, or exotic fruit provenance.
- Online Retailers:Direct-to-consumer and platform-mediated sales requiring cold-chain last-mile solutions.
Individual consumers represent the largest volume base; online retailers are expanding most quickly as delivery infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Vietnam and Thailand concentrate tropical fruit processing infrastructure. Government-backed cold-chain investments in India and regulatory tightening across the EU are redrawing competitive maps. Mexico's export-oriented manufacturing corridors and Germany's retail consolidation complete the geographic spread.
Germany
Discounter freezer aisle expansion drives private-label fruit dessert volume. EFSA sugar reduction mandates force reformulation across retail SKUs. The Cologne-Düsseldorf corridor hosts concentrated dairy-alternative R&D facilities serving Central European markets.
Vietnam
Mekong Delta mango and passion fruit harvests supply processing clusters for export markets. Government infrastructure programs target port modernization at Hai Phong and Cai Mep. Da Nang industrial zones attract cold-storage investment from regional hospitality suppliers.
United States
FDA frozen dessert identity standards shape product composition requirements. Clean-label preferences in coastal metro areas sustain premium pricing for reduced-additive formats. California's Central Valley fruit processors supply both domestic retail and Asian export channels.
India
BIS certification requirements constrain import access for multinational suppliers. Organized retail expansion in Mumbai and Delhi creates accessible white space for branded frozen entry. Maharashtra cold-chain infrastructure investment accelerates chilled format distribution reach.
Thailand
Bangkok and Phuket hotel chains scale tropical fruit dessert procurement as tourism rebounds. Board of Investment incentives target food processing zone development in Rayong. Samut Sakhon processing clusters concentrate durian and mangosteen pulp capacity for export.
Fruit Dessert Market Competitive Landscape
European producers anchor one tier; Southeast Asian specialists hold processing cost advantages in tropical formats. The market structure consolidates around multinational CPG conglomerates with frozen infrastructure, mid-scale regional players with provenance positioning, and emerging plant-based pure-plays. Three archetypes dominate: scale-driven volume manufacturers, clean-label specialists, and hospitality-focused premium suppliers. Competitive moves concentrate on cold-chain capacity expansion and strategic sourcing partnerships with grower cooperatives.
Among diversified consumer goods conglomerates, Nestlé and Unilever occupy positions spanning multiple preservation technologies and climate zones. JonnyPops represents the emerging archetype of premium clean-label specialists targeting hospitality and specialty retail channels with simplified ingredient panels. These three exemplify how scale infrastructure, formulation R&D, and channel-specific positioning create defensible market presence.
| Leading Market Players |
|---|
| Natural Fruit Corporation |
| JonnyPops |
| Nestlé |
| Beyond Better Foods LLC |
| Whole Fruit |
| Wells Enterprises, Inc. |
| Paleteria La Michoacana |
| GoodPop |
| Unilever |
| Others |
Supply & Pricing Matrix
EU Green Deal packaging mandates gate qualified supply access for fruit dessert manufacturers while simultaneously creating premium-tier pricing eligibility for compliant producers. Buyers with verified biodegradable packaging credentials command measurable price premiums in German and French retail channels, whereas non-compliant suppliers face margin compression from reformulation and redesign commitments.
Pricing Analysis
Lead-time-driven pricing stratification separates contract-based procurement from spot-market purchasing in tropical fruit pulp sourcing. Short-lead-time orders for mango and passion fruit concentrates from Vietnam and Thailand command 15-25% premiums over forward-contracted volumes, while spot inventory clearance from Ecuadorian processors trades at discounts. Price differentiation rests on certification tier—organic and carbon-neutral credentials sustain premium positioning—though cost compression in standard-tier frozen desserts is intensifying due to energy price volatility in European cold storage. Food service operators in Southeast Asian hospitality markets exhibit lowest price sensitivity, whereas Indian organized retail buyers prioritize volume-scale discounts.
Supply Chain Analysis
Dual-sourcing requirements from European retail buyers mandate multi-supplier qualification for tropical fruit processors, forcing manufacturers to maintain relationships across Vietnam, Thailand, and Ecuador simultaneously. Raw material dependencies center on mango pulp, passion fruit concentrate, and berry purees, with harvest timing concentrated in narrow seasonal windows. Supply chain risk concentrates in single-source vulnerability at the port level—Hai Phong and Cai Mep congestion disrupts delivery reliability for Mekong Delta processors. Distribution runs through temperature-controlled logistics networks with frozen formats utilizing established cold-chain infrastructure while chilled formats require expedited last-mile solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fruit dessert market functions as a cost-of-compliance story where EU Green Deal additive and packaging standards erect barrier-to-entry moats favoring incumbent players with established certification infrastructure and reformulation R&D capabilities.
For Market Incumbents: Acquire cold-storage infrastructure in Southeast Asian processing zones to anchor tropical fruit supply security. Nestlé and Unilever should expand backward integration into Vietnamese and Thai grower cooperatives before EU Deforestation Regulation traceability deadlines harden, while simultaneously investing in precision fermentation texturizer partnerships to defend margin position against plant-based pure-plays. For New Entrants and Emerging Players: Begin with white-space penetration in India's organized retail expansion, where BIS certification requirements constrain multinational import access and domestic cold-chain infrastructure investment creates distribution accessibility. Target food service channel entry in Bangkok and Phuket hospitality markets through single-origin tropical fruit provenance positioning, leveraging direct sourcing contracts with Mekong Delta cooperatives as the primary go-to-market angle. For Investors and Strategic Acquirers: EU Deforestation Regulation audit completion announcements from target suppliers are the leading indicator that premium-tier pricing power is crystallizing for acquisition candidates. Mid-scale regional players with documented supply chain transparency and clean-label formulation capabilities present the strongest long-term viability profile, with precision fermentation technology convergence representing the critical inflection signal for portfolio repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grower Cooperatives | EU Deforestation Regulation traceability requirements favor suppliers with documented single-origin fruit provenance. |
| Precision Fermentation Partnership | Cellular agriculture texturizers from Netherlands biotech suppliers enable cleaner-label creamy format innovation. |
| Cold-Chain Infrastructure Expansion | Da Nang industrial zone cold-storage investment reduces port congestion vulnerability for Mekong Delta processors. |
| Clean-Label Certification Investment | Organic and carbon-neutral audit completion opens premium positioning in German and French retail channels. |
| Food Service Channel Prioritization | Bangkok and Phuket hotel procurement scaling creates hospitality-focused revenue diversification. |
Research Methodology
Multi-period observation of EFSA sugar reduction mandate implementation timelines, EU Green Deal packaging phase-out schedules, and Southeast Asian tourism recovery indicators anchored the trend analysis, supplemented by interviews with fruit dessert category managers at European retail chains, procurement directors at Thai and Vietnamese hospitality operators, food technology R&D leads at multinational CPG conglomerates, and cold-chain logistics specialists in Indian organized retail. Secondary validation drew from FDA frozen dessert identity standards documentation, EFSA novel ingredient guidance updates, BIS certification requirement publications, and customs trade data for tropical fruit pulp imports. Bottom-up volume modeling across preservation technologies and channel access modes was triangulated against top-down macroeconomic consumption pattern analysis.
Input-output matrix framing structured the forecast construction across product type, form, application, and customer type segmentation dimensions, with additional modeling of regulatory compliance tier as an industry-specific stratification variable. CAGRs were derived through trend extrapolation of historical consumption patterns adjusted for enforcement timeline impacts of EU packaging mandates and sugar reduction thresholds. Forecast inputs incorporated cold-chain infrastructure investment trajectories in India, precision fermentation technology maturation curves, and food service channel normalization rates in Southeast Asian tourism markets.
Climate-driven harvest volatility in tropical growing regions, regulatory timeline acceleration for additive restrictions, and cold-chain infrastructure deployment delays are the dominant revision risks to the projection framework. Deviation in EU Green Deal enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Yeast-Based Spreads Market
Specialty Foods
Cultures Market
Specialty Foods
Vegetarian Taquitos Market
Specialty Foods
Malaysia Manuka Honey Market
Specialty Foods
Low Calorie Oatmeal Market
Specialty Foods
Honey Spread Market
Specialty Foods
Vegan Salad Dressing Market
Specialty Foods
Dill Juice Market
Specialty Foods
Halal Market
Specialty Foods
Postbiotic Pet Food Market
Specialty Foods
Sweet Spreads Market
Specialty Foods
Keto Low-Calorie Meals Market
Specialty Foods
Halal Products Market
Specialty Foods
Vegan Dressing Market
Specialty Foods
Sea Moss Market
Specialty Foods
Middle East and Africa Hummus Market