
 Cannabis Infused Drinks Market | 2026-2036
Cannabis Infused Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Cannabis Infused Drinks Market Analysis
The EU Green Deal's sustainability benchmarks for food and beverage packaging is realigning procurement priorities across cannabis beverage supply chains. Canopy Growth Corporation leverages its domestic cultivation infrastructure to control raw material quality from seed to shelf. Tilray Brands anchors its competitive position through pharmaceutical-grade extraction standards applied to consumer beverages. Truss Beverage Co. navigates provincial distribution monopolies in Canada with licensed production partnerships.
Cannabis infused drinks constitute non-alcoholic beverages incorporating tetrahydrocannabinol, cannabidiol, or full-spectrum hemp extract, typically dosed at 2.5–10 mg THC per serving through nano-emulsion technology for enhanced bioavailability. These products serve recreational and functional consumption occasions where consumers seek psychoactive or therapeutic effects without alcohol. Alcohol alternatives command premium shelf positioning as social occasion substitutes, while wellness-oriented teas attract health-conscious consumers seeking functional botanical formulations. Citrus and berry flavor profiles dominate trial purchases, though herbal infusions sustain repeat buying among experienced users.
FDA oversight of CBD as a food additive remains unresolved in the United States, creating compliance uncertainty that shapes formulation decisions and interstate commerce. Health Canada establishes explicit THC limits and packaging requirements that determine product viability in provincial markets. State-level cannabis regulators in California, Colorado, and Illinois impose additional testing protocols for contaminants and potency verification. Stakeholders must monitor regulatory convergence between alcohol beverage control boards and cannabis agencies as licensing frameworks evolve.
Market Dynamics
Nano-emulsion technology has compressed onset times from 90 minutes to 15 minutes, fundamentally altering consumer expectations around predictability and session control in social consumption settings.
Growth Catalysts
- Millennial wellness migration:Health-conscious consumers aged 25-40 are displacing alcohol calories with functional botanical formulations, creating pull-through for low-dose THC and CBD beverages in fitness-adjacent retail channels.
- California distribution density:Recreational dispensary networks in Los Angeles, San Francisco, and San Diego corridors favor ready-to-drink formats over edibles, concentrating shelf-space allocation and trial velocity.
- EU Green Deal packaging mandates:Sustainability benchmarks for recyclable and bio-based materials are accelerating supplier qualification programs that favor established beverage manufacturers with compliance infrastructure.
Market Restraints
- FDA CBD food-additive freeze:Unresolved oversight status creates interstate commerce barriers, forcing national brands to maintain separate state-level formulation and labeling systems.
- THC input cost volatility:Cultivation yield sensitivity to climate and energy costs transmits directly to finished-goods margin pressure, particularly for full-spectrum extract-dependent products.
- Provincial distribution monopolies:Canada's provincial liquor boards control retail access, constraining direct-to-consumer channel development and compressing brand margin capture.
Strategic Opportunities
- German pharmacy channel opening:Regulatory frameworks for cannabis-derived wellness products are creating shelf-access pathways for pharmaceutical-grade extraction standards in Europe's largest economy.
- On-premise hospitality integration:Licensed consumption lounges in Colorado and Illinois are emerging as experiential venues where beverage service replaces traditional smoking formats.
- Dual cannabinoid convergence:Precision blending of THC with minor cannabinoids like CBN and CBG is enabling occasion-specific positioning for sleep, focus, and recovery use cases.
Industry Challenges
- Nano-emulsion technical talent scarcity:Formulation chemists with lipid-delivery system expertise command premium compensation, constraining mid-tier manufacturer R&D velocity.
- State-by-state testing protocol fragmentation:California, Colorado, and Illinois impose non-harmonized contaminant and potency verification requirements, multiplying quality-assurance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabis Infused Drinks Market |
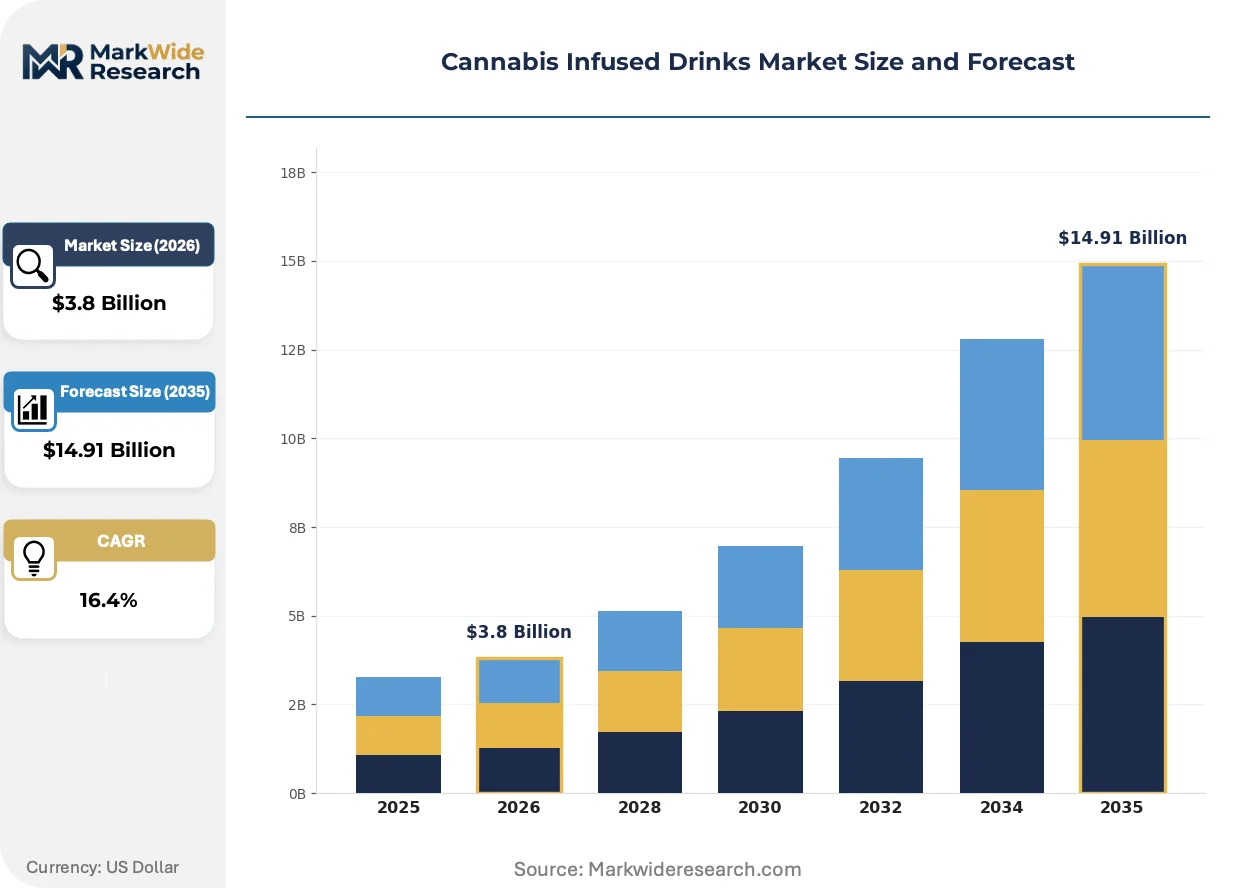
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodas, Teas, Juices, Alcohol Alternatives Flavor Profile: Citrus, Berry, Herbal, Spicy Consumption Occasion: Social Gathering, Relaxation, Party, Wellness Target Consumer: Health-Conscious, Millennials, Recreational Users, Seniors |
| Companies Covered | Canopy Growth Corporation, Tilray Brands, Aurora Cannabis, Truss Beverage Co., Keef Brands, Lagunitas, Curaleaf, Cronos Group, Brēz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabis Infused Drinks Market Emerging Trajectories
Formulation science and regulatory navigation are converging to redefine competitive advantage, with speed-to-shelf and compliance precision separating scalable operators from regional players.
Nano-emulsion systems using lipid-surfactant matrices are rewriting bioavailability benchmarks by achieving water-compatible THC dispersion at particle sizes below 100 nanometers. Beverage manufacturers with captive emulsion capabilities are capturing shelf space from contract-dependent competitors. This technology compression is collapsing the efficacy gap between inhalation and ingestion routes, expanding addressable occasions.
Health Canada's explicit THC potency caps and child-resistant packaging mandates are forcing product architecture decisions that prioritize single-serve precision over multi-dose flexibility. Licensed producers are redesigning bottle geometries and closure systems to satisfy provincial monopolies. The regulatory stringency most affects value-tier SKUs where packaging cost ratios are highest.
Social-occasion substitution is displacing traditional alcohol-centric gatherings in wellness-oriented urban clusters. Dispensary tasting events and cannabis-friendly hospitality venues in Denver and Portland are normalizing beverage-forward consumption rituals. This behavioral pivot concentrates demand in metropolitan statistical areas with mature recreational frameworks and elevated health-consciousness indices.
Cannabis Infused Drinks Market Segmentation
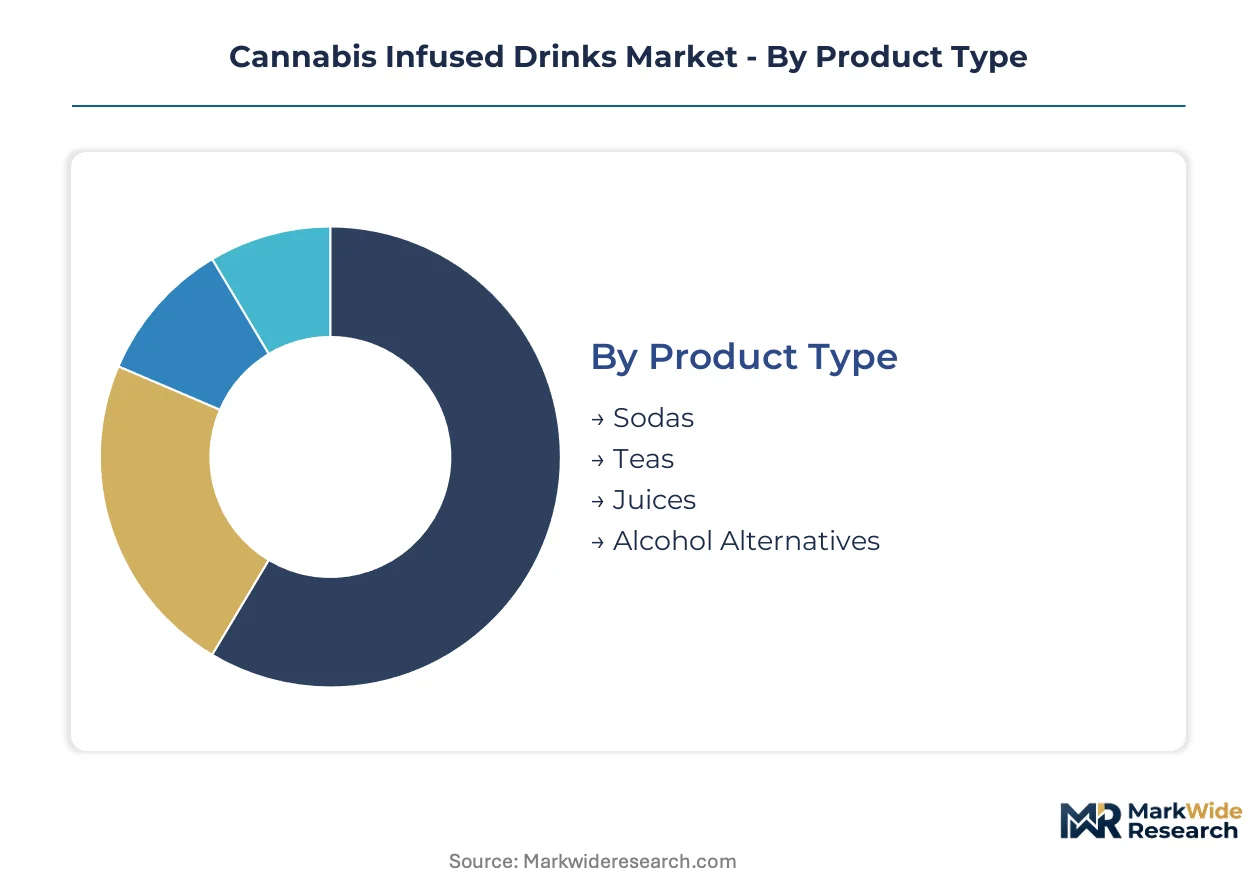
Cannabis infused drinks demand fragments across consumption rituals and physiological expectations, forcing manufacturers to align formulation architecture with precise occasion-state matching rather than one-size-fits-all positioning.
Product Type:
Supply concentration in ready-to-drink manufacturing infrastructure favors liquid formats with existing co-packing relationships, tilting competitive advantage toward beverage incumbents over cannabis-native startups.
- Alcohol Alternatives:Non-alcoholic spirits and seltzers delivering 2.5–5 mg THC per serving through nano-emulsion systems. Demand clusters in California's Los Angeles and San Francisco corridors where dispensary networks prioritize social-substitute positioning. Regulatory clarity from state-level cannabis agencies enables on-premise hospitality trials in Colorado and Illinois.
- Teas:Functional botanical formulations combining CBD or low-dose THC with adaptogenic ingredients. Wellness-oriented millennials in fitness-adjacent retail channels drive repeat purchase velocity. Health Canada potency caps force single-serve precision in provincial distribution systems.
- Sodas:Carbonated beverages with rapid onset emulsion technology targeting session-control occasions.
- Juices:Cold-pressed fruit bases with full-spectrum hemp extract for morning and recovery rituals.
Today's leader: Alcohol Alternatives. Tomorrow's challenger: Teas.
Flavor Profile:
Ingredient sourcing networks for natural flavor compounds concentrate in established beverage supply corridors, with citrus and berry commanding premium extraction contracts.
- Citrus:Lemon, lime, and grapefruit formulations dominate trial purchases through familiar taste anchoring. California dispensary data shows highest shelf-turn velocity in ready-to-drink formats. Nano-emulsion masking requirements favor citrus oils for bitterness suppression.
- Berry:Blueberry, raspberry, and acai profiles sustain repeat buying among experienced users seeking antioxidant adjacency. Demand concentrates in Pacific Northwest metropolitan clusters with mature recreational frameworks.
- Herbal:Lavender, chamomile, and botanical infusions for sleep and relaxation positioning.
- Spicy:Ginger, turmeric, and pepper formulations targeting functional inflammation narratives.
Volume concentrates in Citrus. Margin expansion favors Berry.
Consumption Occasion:
Channel access permissions vary sharply by occasion state, with social gathering formats facing stricter licensing than private consumption.
- Social Gathering:Sessionable low-dose products designed for extended interaction without impairment accumulation. Licensed consumption lounges in Denver and Portland normalize beverage-forward rituals. FDA unresolved CBD status limits interstate brand building.
- Wellness:Functional formulations with precise cannabinoid ratios for sleep, focus, and recovery use cases. Health-conscious millennials displace alcohol calories with fitness-adjacent positioning. EU Green Deal packaging mandates accelerate supplier qualification.
- Relaxation:Evening-oriented products emphasizing CBN and CBD combinations for wind-down rituals.
- Party:Higher-dose formats for celebratory contexts with rapid onset claims.
Wellness commands the steepest expansion trajectory. Social Gathering faces regulatory headwinds.
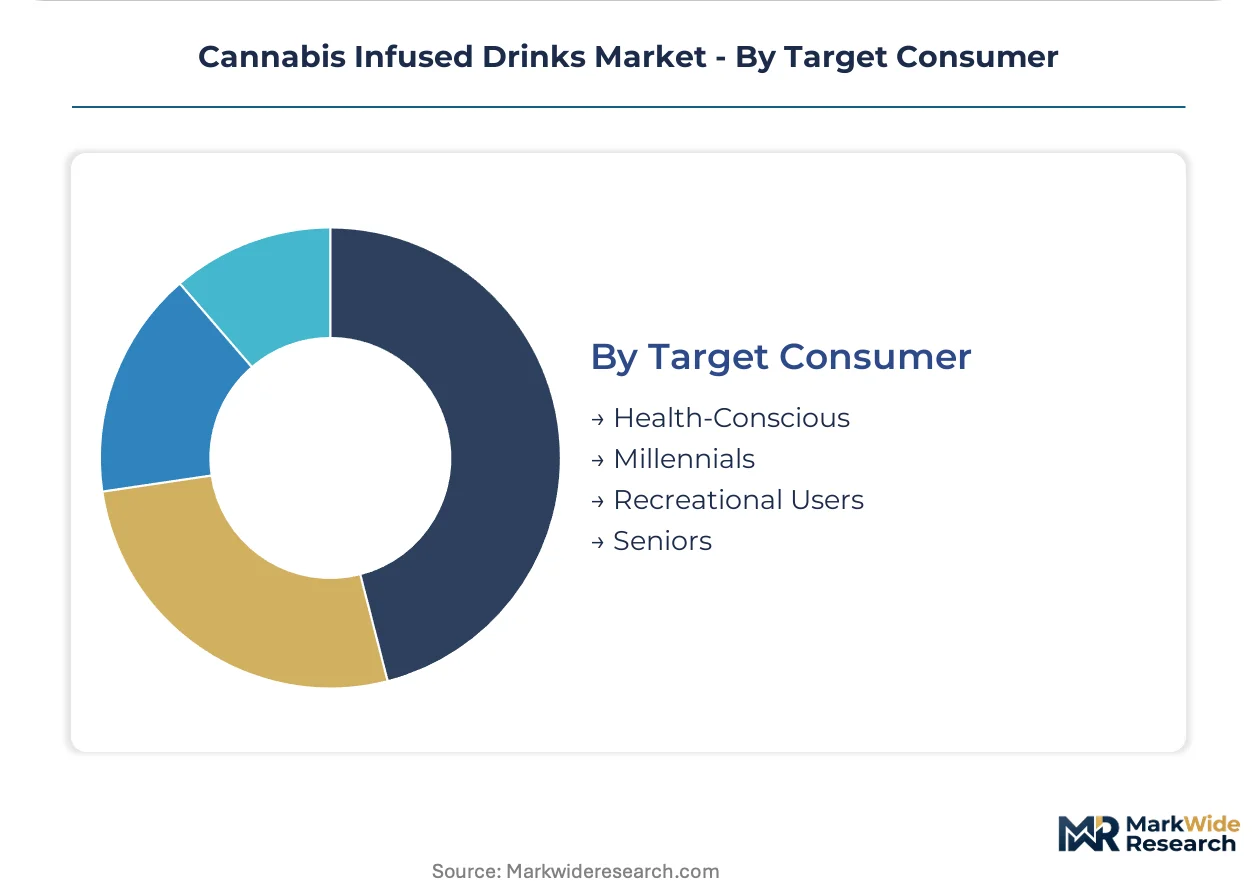
Target Consumer:
Purchasing power and risk tolerance diverge sharply across generational cohorts, with millennials absorbing price premiums for quality verification that seniors resist.
- Millennials:Consumers aged 25–40 with established cannabis literacy and willingness to experiment with novel formats. California recreational corridor density enables trial velocity through dispensary network penetration. Dual cannabinoid convergence attracts this cohort to occasion-specific positioning.
- Health-Conscious:Fitness-oriented buyers prioritizing functional botanical formulations over psychoactive effects. EU sustainability benchmarks reshape procurement priorities for this segment. Nano-emulsion bioavailability claims resonate strongly.
- Recreational Users:Experienced consumers seeking reliable potency and rapid onset predictability.
- Seniors:Aging demographics exploring therapeutic applications with physician guidance.
Millennials anchor current revenue. Health-Conscious consumers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Proposition 64 legalization in 2016 established the first large-scale recreational cannabis beverage infrastructure, creating the template for regulatory frameworks and distribution networks subsequently adopted across North America and Europe.
United States
California's Los Angeles and San Francisco corridors concentrate dispensary density and ready-to-drink shelf allocation, while Colorado and Illinois impose additional state-level testing protocols for contaminants. FDA oversight of CBD as a food additive remains unresolved, forcing national brands to maintain separate formulation systems. Denver and Portland licensed consumption lounges are normalizing beverage-forward social rituals.
Canada
Health Canada's explicit THC potency caps and child-resistant packaging mandates determine product viability across provincial markets. Ontario and British Columbia anchor manufacturing capacity, though provincial liquor board monopolies constrain direct-to-consumer channel development. Truss Beverage Co. navigates these distribution constraints through licensed production partnerships.
Germany
Regulatory frameworks for cannabis-derived wellness products are creating pharmacy channel access for pharmaceutical-grade extraction standards in Europe's largest economy. The EU Green Deal's sustainability benchmarks for packaging are accelerating supplier qualification programs. Berlin and Munich metropolitan clusters concentrate early adoption of functional botanical formulations.
United Kingdom
Novel food authorization requirements from the Food Standards Agency create compliance pathways for CBD-infused beverages while excluding THC products from mainstream retail. London's wellness-oriented consumer base drives demand for adaptogenic tea formulations. The regulatory ambiguity surrounding psychoactive cannabinoids limits recreational format development.
Australia
TGA scheduling frameworks permit low-dose CBD products through pharmacy distribution while maintaining strict controls on THC-containing beverages. Sydney and Melbourne fitness-adjacent retail channels show early traction for functional cannabinoid formulations. State-level licensing variations between New South Wales and Victoria complicate national brand architecture.
Cannabis Infused Drinks Market Vendor Landscape
Capital-heavy licensed producers with captive cultivation infrastructure compete with asset-light beverage formulators relying on contract manufacturing and white-label supply agreements. The market exhibits tiered concentration, with a handful of vertically integrated operators controlling upstream raw material quality while mid-tier players compete on flavor innovation and channel access. Three strategic archetypes dominate: domestic cultivators with beverage line extensions, legacy alcohol producers with cannabis partnerships, and specialized emulsion technology firms. Competitive intensity centers on nano-emulsion capability acquisition and provincial distribution license securing.
Within the licensed producer tier, Canopy Growth Corporation leverages its domestic cultivation infrastructure to control seed-to-shelf quality, representing the vertically integrated archetype. Tilray Brands anchors the pharmaceutical-grade extraction segment through standards applied to consumer beverage formats. Truss Beverage Co. occupies a position exemplifying partnership-dependent navigation of provincial distribution monopolies. These three entities collectively illustrate the strategic divergence between upstream control, regulatory compliance precision, and channel access optimization.
| Leading Market Players |
|---|
| Canopy Growth Corporation |
| Tilray Brands |
| Aurora Cannabis |
| Truss Beverage Co. |
| Keef Brands |
| Lagunitas |
| Curaleaf |
| Cronos Group |
| Brēz |
| Others |
Supply Flow & Price Mechanics
Dispensary procurement managers in California's recreational corridor concentrate buying power for ready-to-drink formats, anchoring a three-tier pricing structure across premium, standard, and economy levels that reflects nano-emulsion sophistication and brand equity rather than raw THC content alone.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by emulsion bioavailability certification and provincial distribution access. Premium tiers command position through pharmaceutical-grade extraction standards and rapid-onset technology claims, while economy SKUs compete on THC yield per dollar. Cost compression in mid-tier formulations is intensifying because Health Canada packaging mandates disproportionately burden single-serve units with lower absolute margins. Health-conscious millennials show lowest price sensitivity, prioritizing quality verification and onset predictability over per-milligram THC economics.
Supply Chain Analysis
Regional distribution centers in Ontario, British Columbia, and California anchor hub-and-spoke patterns that feed provincial liquor board monopolies and licensed dispensary networks. Raw material flows draw from domestic cannabis cultivation in Canada and California, with nano-emulsion surfactant chemicals sourced from specialty chemical producers in Germany and the United States. Single-source vulnerability concentrates in lipid-surfactant matrix suppliers, where formulation chemist scarcity constrains alternative qualification. Distribution runs through provincially controlled wholesale layers in Canada and vertically integrated seed-to-shelf operators in California's recreational corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cannabis infused drinks market compounds steadily as regulatory clarity in major economies normalizes dispensary and pharmacy channel access, converting latent consumer interest into repeatable purchase velocity.
For Market Incumbents: To counter nano-emulsion technical talent scarcity, Canopy Growth Corporation and Tilray Brands should deepen captive emulsion capabilities through targeted R&D hiring in Ontario and British Columbia, while securing provincial distribution license renewals ahead of Health Canada packaging mandate expansions that favor compliance-heavy incumbents. For New Entrants and Emerging Players: The gap between premium pharmaceutical-grade positioning and economy THC-yield formats creates white-space opportunity in functional wellness teas for fitness-adjacent retail channels, particularly in Germany's pharmacy channel where regulatory frameworks favor pharmaceutical-grade extraction standards over recreational positioning. For Investors and Strategic Acquirers: Legacy alcohol beverage producers are the most active acquirer in this space, seeking sessionable low-dose formats that displace social alcohol occasions. Long-term viability hinges on FDA CBD food-additive resolution in the United States, with acquisition target archetypes centering on nano-emulsion technology firms with Health Canada compliance track records. Watch Health Canada THC potency cap adjustments as the critical inflection signal for margin expansion or compression across product tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Nano-Emulsion Capability Acquisition | Captive lipid-delivery expertise separates scalable operators from contract-dependent competitors in California and Canada. |
| Provincial Distribution License Securing | Ontario and British Columbia liquor board access determines shelf-space allocation velocity in Canada's controlled retail environment. |
| Pharmaceutical-Grade Extraction Investment | Germany's pharmacy channel opening rewards TGA and Health Canada compliance precision with premium positioning. |
| Sustainable Packaging Qualification | EU Green Deal benchmarks accelerate supplier programs that favor established beverage manufacturers with compliance infrastructure. |
| Dual Cannabinoid Formulation Development | Precision THC-CBN-CBG blending enables occasion-specific positioning for sleep, focus, and recovery use cases among millennials. |
Methodological Framework
Multiple input streams — interviews with beverage formulation chemists, provincial liquor board procurement officers, and dispensary category managers, alongside regulatory filing analysis and customs trade data — were reconciled through bottom-up SKU enumeration and top-down market sizing triangulation across the analysis window.
Historical volume trajectories in California, Colorado, and Canada were cross-referenced against expert panel assessments of nano-emulsion adoption curves and provincial distribution expansion timelines. Segmentation modeling captured product type, flavor profile, consumption occasion, and target consumer dimensions, with CAGRs derived from regression analysis against THC potency cap adjustments and FDA regulatory pathway assumptions.
The model assumes a particular technology adoption path; alternative pathways for nano-emulsion bioavailability claims would alter the outlook if onset-time compression stalls or consumer skepticism persists. Stakeholders should weight assumptions against their own operating context, particularly regarding Health Canada packaging mandate compliance costs and state-by-state testing protocol fragmentation in the United States.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
GCC Halal Food Market
Specialty Foods
US Jam Jelly and Preserves Market
Specialty Foods
Global Cocoa Nibs Market
Specialty Foods
High Protein Cat Food Market
Specialty Foods
Tahini Market
Specialty Foods
Hot Pot Market
Specialty Foods
Wet Grain-Free Pet Food Market
Specialty Foods
Moringa Products Market
Specialty Foods
Thai Cuisine Market
Specialty Foods
Malaysia Manuka Honey Market
Specialty Foods
Middle East and Africa Hummus Market
Specialty Foods
Halal Products Market
Specialty Foods
Konjac Noodles Market
Specialty Foods
Asia Pacific Pet Milk Replacers Market
Specialty Foods
Fermented Black Beans Market
Specialty Foods
Asia-Pacific Free from Food Market