
 Seafood Takeout Market | 2026-2036
Seafood Takeout Market Size, Share, and Industry Trends Forecast 2026-2036
Seafood Takeout Market Analytics
Multi-source procurement across regional fish markets is recalibrating how national chains secure daily inventory. Red Lobster leverages its scale to negotiate direct contracts with Gulf Coast suppliers. Captain D's Seafood Kitchen anchors its value proposition through frozen fillet consistency that withstands distribution variance. Long John Silver's competes via standardized batter-fry operations that reduce per-unit kitchen labor.
Seafood takeout comprises prepared aquatic protein dishes—finfish, shellfish, and mollusks cooked to order and packaged for off-premise consumption, typically held at temperatures between 140°F hot-holding and 40°F cold-chain thresholds to prevent histamine formation and Vibrio proliferation. Its primary commercial purpose is delivering restaurant-quality marine protein meals to consumers without dine-in time commitment. Sushi commands premium price tiers in dense metropolitan markets where raw-fish handling certification limits competitor entry. Food delivery apps now generate the fastest order velocity among distribution channels, though walk-in customers still sustain higher average ticket sizes through impulse add-ons. Budget-tier value meals dominate volume in suburban and rural locations where price sensitivity shapes weekly rotation choices.
The FDA enforces seafood-specific HACCP protocols that mandate hazard controls from harvest through final service, while state health departments conduct unannounced cold-storage inspections that can trigger immediate closure for temperature violations. The EU's EFSA standards for marine biotoxin limits indirectly shape US import sourcing when domestic suppliers compete against European-certified Norwegian salmon farms. Stakeholders must monitor emerging state-level plastic packaging bans that could force rapid conversion to fiber-based clamshells across California, New York, and Washington operations.
Market Dynamics
Food delivery apps have compressed order cycles from same-day to sub-hour windows, forcing seafood chains to rebuild kitchen workflows around thermal packaging that maintains HACCP thresholds through last-mile handoff.
Growth Catalysts
- Urban millennial consumption patterns:Dense coastal metros from Seattle to Miami now sustain same-day delivery models where fresh catch proximity enables premium sushi velocity that suburban markets cannot replicate.
- FDA HACCP enforcement:Mandatory hazard controls from harvest through final service compel chains to upgrade cold-chain packaging, creating barrier-to-entry advantages for compliant operators.
- Cloud kitchen infrastructure:Delivery-optimized production facilities strip dine-in overhead and position seafood concepts in micro-fulfillment nodes that reduce delivery radius and thermal degradation risk.
Market Restraints
- Wild catch input volatility:Gulf Coast shrimp and Alaskan pollock quotas fluctuate with seasonal biomass assessments, compressing margin predictability for batter-fry specialists dependent on standardized fillet costs.
- Single-source supply concentration:Norwegian salmon farms dominate Atlantic raw-fish supply, exposing sushi chains to currency and tariff exposure that frozen fillet competitors avoid through multi-species sourcing.
- Histamine formation physics:Scombroid toxin risk in tuna and mackerel imposes unforgiving 40°F cold-chain ceilings that last-mile thermal packaging struggles to maintain in summer ambient conditions.
Strategic Opportunities
- State plastic packaging bans:California, New York, and Washington regulatory timelines force rapid conversion to fiber-based clamshells, rewarding early movers with preferred supplier status in municipal procurement.
- Raw-fish handling certification scarcity:Limited qualified sushi chefs in secondary metros creates white space for training-forward chains to establish preemptive market presence before competitor entry.
- Subscription meal kit convergence:Portion-controlled seafood boxes with pre-measured sauces and timed cooking instructions merge restaurant quality with home preparation rituals in coastal suburbs.
Industry Challenges
- HACCP plan maintenance burden:FDA-mandated hazard analysis documentation requires continuous monitoring of receiving temperatures, cooking logs, and cooling rates that strain manager bandwidth in high-turnover locations.
- Last-mile thermal packaging capex:Phase-change material inserts and insulated bag fleets demand upfront investment that cash-constrained independents cannot deploy against scaled chain competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seafood Takeout Market |
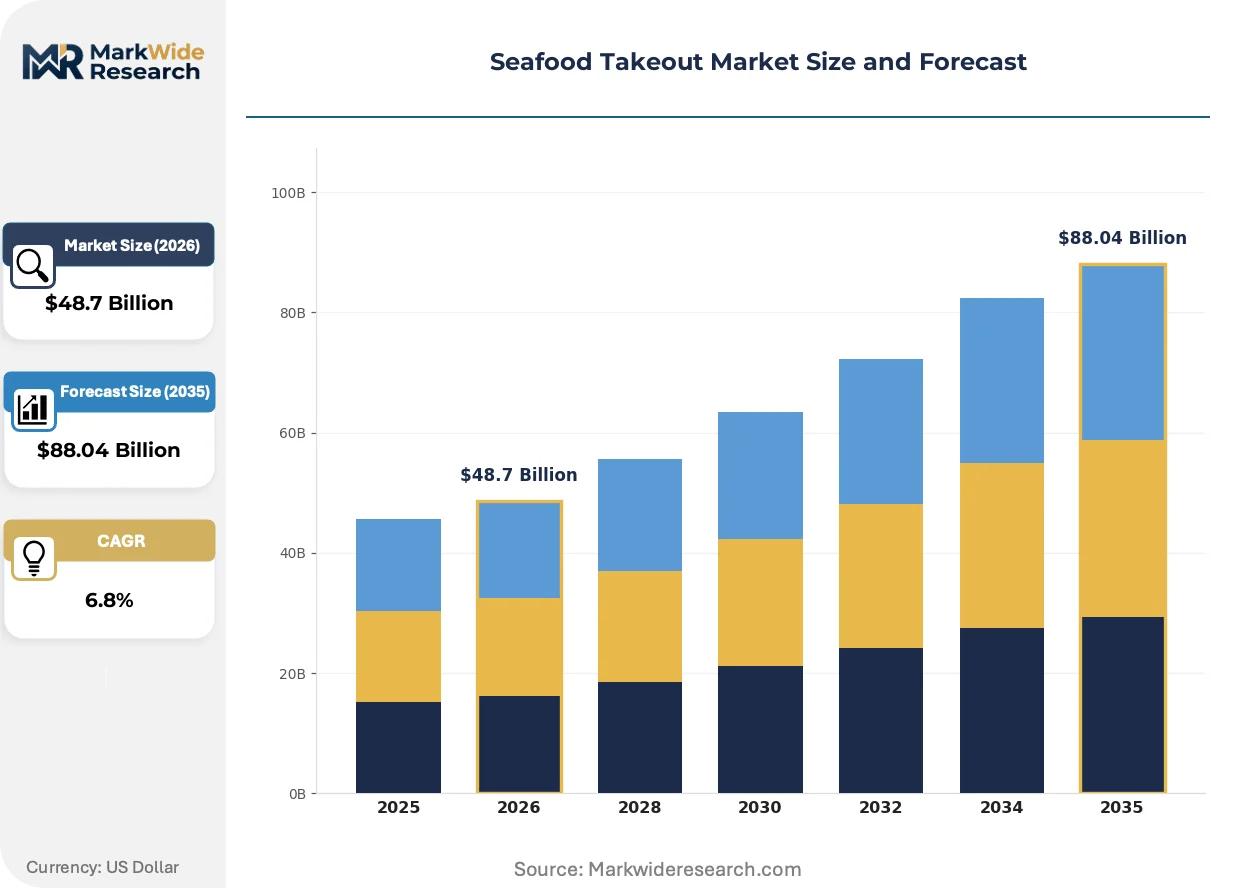
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sushi, Fish & Chips, Seafood Platters, Clam Chowder Distribution Channel: Online Orders, Food Delivery Apps, Walk-in Customers, Third-Party Deliveries Price Tier: Premium, Mid-Range, Budget, Value Meals Cuisine Style: Asian, Mediterranean, American, Traditional |
| Companies Covered | P.F. Changs, Red Lobster, Bonefish Grill, Bubba Gump Shrimp Co., Joe's Crab Shack, Long John Silver's, Captain D's Seafood Kitchen, Bahama Breeze Island Grille, Rubio's, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seafood Takeout Market Evolving Landscape
Active packaging systems and predictive logistics are compressing the time between dock and doorstep, while regulatory pressure on single-use materials forces simultaneous redesign of food safety and sustainability protocols.
Phase-change material inserts embedded in clamshell bases is decentralizing cold-chain responsibility from centralized commissaries to individual driver vehicles. Third-party delivery platforms in dense metros deploy these inserts at scale, enabling sushi concepts to extend raw-fish delivery radius without kitchen replication. The structural consequence is fragmenting production geography, allowing micro-kitchens to serve territories previously requiring full-service restaurant investment.
California's SB 54 extended producer responsibility mandates compel seafood chains to fund fiber-based packaging transition or face per-container fees. Operators must redesign clamshell dimensions to maintain structural integrity in humid conditions while meeting compostability standards. Quick-service seafood brands with standardized box sizes adapt faster than sushi concepts with irregular platter configurations.
Subscription ordering via app-native loyalty programs now locks in weekly seafood consumption rituals that walk-in traffic cannot replicate. Young professional households in Boston and San Francisco pre-schedule Friday sushi deliveries, displacing impulse purchase patterns. This behavioral shift concentrates demand forecasting accuracy for chains with robust first-party data infrastructure, disadvantaging franchisees dependent on third-party platform opacity.
Seafood Takeout Market Segmentation
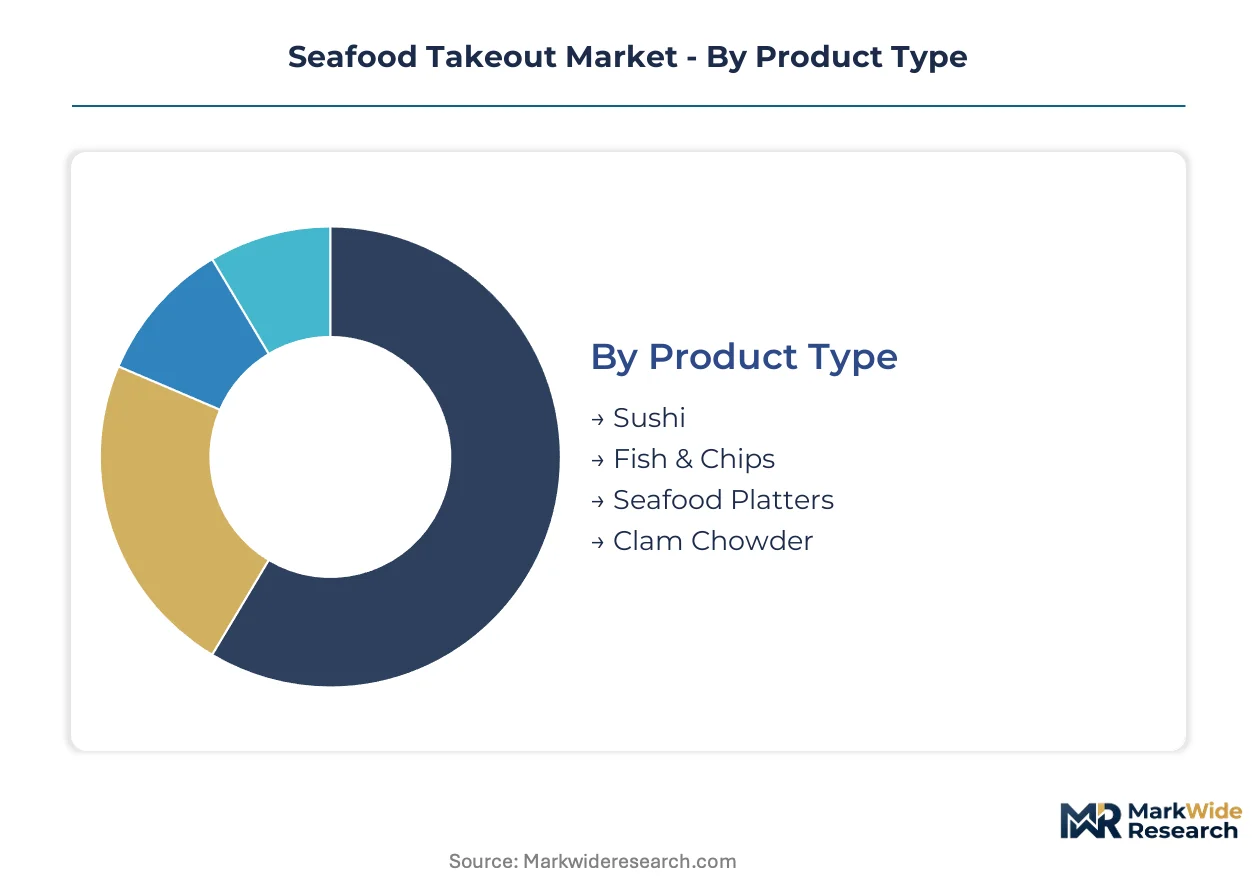
Seafood takeout operators calibrate production workflows and packaging specifications against distinct consumption occasions that span raw-fish handling, hot-holding protocols, and impulse versus planned purchase behaviors. Segment boundaries determine cold-chain capex allocation, kitchen equipment mix, and last-mile thermal packaging requirements.
Product Type:
Upgrade cycles for seafood takeout equipment and packaging systems map directly to product-specific handling requirements, with raw-fish concepts demanding the most frequent cold-chain infrastructure refreshes.
- Sushi:Raw-fish preparations requiring continuous 40°F cold-chain maintenance from cutting board to customer handoff. Dense coastal metros from Seattle to Miami sustain same-day delivery velocity that inland markets cannot replicate due to certification scarcity and proximity constraints.
- Fish & Chips:Batter-fried finfish held at 140°F hot-holding thresholds with shorter consumption windows. Suburban and rural locations dominate volume through standardized portion consistency that withstands distribution variance without premium packaging.
- Seafood Platters:Multi-item combinations mixing hot and cold components that complicate thermal packaging design.
- Clam Chowder:Soup-based format requiring spill-proof sealed containers and extended heat retention for commuter consumption patterns.
Fish & Chips sits at the top of the volume ranking, with Sushi climbing the fastest.
Distribution Channel:
Cost tier differentiation across channels shapes margin architecture, with platform-mediated orders compressing per-ticket profitability through commission structures while walk-in traffic sustains higher attachment rates.
- Online Orders:Direct-to-consumer digital transactions capturing first-party data for demand forecasting. Chains with robust infrastructure lock in weekly consumption rituals that third-party opacity prevents.
- Food Delivery Apps:Platform-mediated sub-hour delivery windows forcing kitchen workflow rebuilds around thermal packaging. Phase-change material inserts embedded in clamshell bases extend raw-fish delivery radius without kitchen replication.
- Walk-in Customers:Impulse-driven traffic generating higher average tickets through add-on beverages and sides.
- Third-Party Deliveries:Courier fleets operating outside brand-controlled cold-chain protocols.
Walk-in Customers capture the highest per-order margin contribution, with Food Delivery Apps expanding most quickly.
Price Tier:
Application-based segmentation reveals how occasion type—celebratory, convenience, or routine sustenance—determines willingness to pay for certification, provenance claims, and packaging aesthetics.
- Premium:Sushi-grade raw fish with handling certification and traceable sourcing commanding metropolitan price acceptance. FDA HACCP compliance creates barrier-to-entry advantages that frozen fillet competitors bypass.
- Mid-Range:Cooked seafood with quality signifiers falling between commodity and luxury positioning.
- Budget:Standardized portions emphasizing caloric value over provenance narrative.
- Value Meals:Combo pricing engineered for weekly rotation choices in price-sensitive suburban and rural locations.
Value Meals anchor weekly volume in secondary markets, with Premium gaining share fastest in coastal employment centers.
Cuisine Style:
Customer type clustering around ethnic preference and preparation tradition influences equipment investment cycles, with Asian formats requiring specialized raw-fish infrastructure that American batter-fry concepts avoid.
- Asian:Sushi, sashimi, and tempura formats demanding raw-fish handling certification and specialized cold-chain protocols. Limited qualified chefs in secondary metros creates white space for training-forward chains.
- Mediterranean:Grilled fish and seafood salads with lighter batter requirements and moderate temperature sensitivity.
- American:Batter-fried and broiled preparations standardized for speed and consistency across franchise networks.
- Traditional:Regional preparations tied to specific coastal heritage markets.
American formats dominate national footprint scale, with Asian concepts showing the steepest expansion trajectory in dense coastal employment clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal metropolitan corridors from Seattle to Miami concentrate seafood takeout velocity where fresh catch proximity and dense millennial populations intersect. Same-day delivery models require cold-chain infrastructure investments that inland markets cannot economically replicate.
United States
Urban millennial households in Boston, San Francisco, and Seattle sustain subscription-based sushi delivery rituals through app-native loyalty programs. The FDA enforces seafood-specific HACCP protocols mandating hazard controls from harvest through final service. The Pacific Northwest corridor from Portland to Vancouver anchors wild-catch procurement networks that supply same-day raw-fish concepts.
Japan
Tokyo and Osaka metropolitan areas maintain the highest per-capita sushi consumption globally, with convenience-store chains operating dedicated raw-fish counters. METI standards for cold-chain logistics shape equipment specifications that export to regional markets. The Kanto region's Tsukiji successor facilities in Toyosu sustain wholesale distribution gravity for premium tuna auctions.
Norway
Atlantic salmon farming operations around Bergen and Trondheim supply raw-fish grade product to European and North American sushi chains. EFSA marine biotoxin limits indirectly shape competitive positioning when Norwegian-certified farms compete against domestic suppliers. The country's aquaculture clusters leverage fjord-based production systems that command traceability premiums in metropolitan markets.
Australia
Sydney and Melbourne coastal suburbs drive demand for fish-and-chip concepts with extended commuter consumption windows. The country's national food safety regulator enforces strict temperature control requirements for raw-fish handling that limit competitor entry. Queensland's tropical fisheries supply barramundi and prawn volumes to quick-service formats across the eastern seaboard.
South Korea
Seoul Capital Area density supports delivery-optimized seafood concepts operating from micro-fulfillment nodes. MFDS certification requirements for raw-fish handling create barrier-to-entry advantages for compliant operators. Busan-Ulsan's port infrastructure anchors import distribution for Norwegian salmon and Alaskan pollock serving domestic chains.
Seafood Takeout Market Competitive Landscape
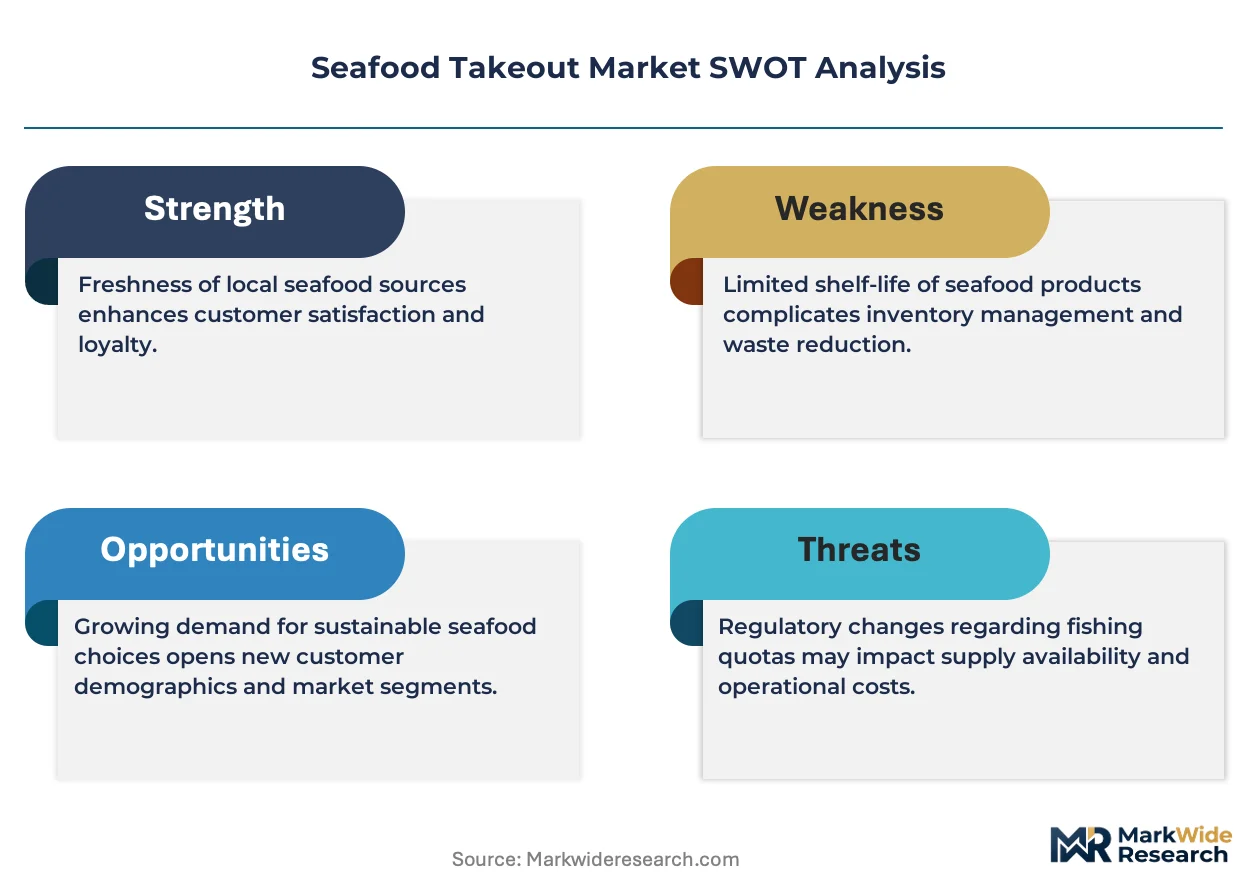
Established producers occupy the standard tier; emerging entrants pursue cloud-kitchen delivery specialization. The vendor base fragments across full-service restaurant conversions, quick-service formats, and virtual brands without dine-in footprint. Three strategic archetypes dominate: scaled chains with direct supplier contracts, batter-fry specialists optimizing kitchen labor, and sushi concepts limited by raw-fish certification scarcity. Competitive moves concentrate on cold-chain packaging upgrades and geographic expansion through micro-kitchen nodes.
Within the scaled chain tier, Red Lobster and Captain D's Seafood Kitchen exemplify procurement differentiation strategies. Red Lobster leverages direct Gulf Coast supplier contracts that bypass regional market volatility. Captain D's Seafood Kitchen anchors value positioning through frozen fillet consistency that withstands distribution variance. Long John Silver's occupies the standardized batter-fry segment where kitchen labor reduction drives per-unit economics. These three represent distinct competitive vectors rather than direct substitutability.
| Leading Market Players |
|---|
| P.F. Changs |
| Red Lobster |
| Bonefish Grill |
| Bubba Gump Shrimp Co. |
| Joe's Crab Shack |
| Long John Silver's |
| Captain D's Seafood Kitchen |
| Bahama Breeze Island Grille |
| Rubio's |
| Others |
Value Network & Pricing Analysis
Urban millennial households in Boston, San Francisco, and Seattle anchor the dominant subscription-based pricing model through app-native loyalty programs that lock in weekly seafood consumption rituals. This buyer concentration enables chains to capture predictable revenue streams while compressing per-unit acquisition costs against walk-in traffic dependent on impulse purchase patterns.
Pricing Analysis
Input-cost pass-through from Gulf Coast shrimp and Alaskan pollock quota volatility shapes margin architecture across the value tier. Three-tier pricing structure across premium, standard, and economy levels separates sushi-grade raw fish with FDA HACCP certification from frozen fillet consistency and batter-fry commodity portions. Cost compression in the budget tier is intensifying because wild catch biomass assessments fluctuate seasonally. Suburban and rural locations exhibit highest price sensitivity through weekly rotation choices, while coastal metropolitan sushi concepts command lowest elasticity due to raw-fish handling certification scarcity.
Supply Chain Analysis
Single-source vulnerability sits with Norwegian salmon farms that dominate Atlantic raw-fish grade supply for North American sushi chains. Geographic concentration spans Norway, the Gulf Coast United States, and Alaska for wild-catch inputs, with phase-change material inserts and fiber-based clamshell packaging sourcing from domestic converters. Tariff exposure on Atlantic farmed salmon creates margin unpredictability that frozen fillet competitors avoid through multi-species sourcing. Distribution runs through third-party delivery platforms deploying insulated bag fleets at scale, alongside direct-to-consumer digital channels capturing first-party demand data.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as urban professional households displace impulse purchase patterns with pre-scheduled subscription ordering that concentrates demand forecasting accuracy around premium sushi specifications.
For Market Incumbents: To counter cloud-kitchen delivery specialists stripping dine-in overhead, scaled chains should deepen backward integration into Gulf Coast direct supplier contracts that bypass regional market volatility. Cold-chain packaging capex in phase-change material inserts creates barrier-to-entry advantages against cash-constrained independents unable to deploy insulated bag fleets at comparable scale. For New Entrants and Emerging Players: Begin with secondary metropolitan markets where raw-fish handling certification scarcity limits incumbent presence and training-forward chains can establish preemptive positioning. Cloud kitchen nodes in micro-fulfillment territories previously requiring full-service restaurant investment offer the most penetrable expansion vector, with delivery-optimized production workflows as the primary go-to-market angle. For Investors and Strategic Acquirers: Food delivery platforms with captive logistics infrastructure are the most active acquirer in this space, consolidating vertically integrated seafood concepts that merge restaurant quality with last-mile thermal control. Long-term viability hinges on first-party data infrastructure enabling demand forecasting accuracy that third-party platform opacity prevents. Watch subscription meal kit convergence with portion-controlled seafood boxes as the inflection signal indicating mainstream adoption of home preparation rituals.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Packaging Upgrade | Phase-change material inserts embedded in clamshell bases extend raw-fish delivery radius without kitchen replication. |
| Cloud Kitchen Expansion | Micro-fulfillment nodes in dense metros reduce delivery radius and thermal degradation risk for sushi concepts. |
| Direct Supplier Contracting | Red Lobster leverages Gulf Coast contracts that bypass regional market volatility batter-fry specialists face. |
| Fiber-Based Packaging Transition | California SB 54 extended producer responsibility mandates force rapid conversion from plastic clamshells. |
| Raw-Fish Certification Investment | Limited qualified sushi chefs in secondary metros creates white space for training-forward chains. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with seafood chain procurement directors, cold-chain packaging engineers, third-party delivery platform operations leads, and FDA regulatory compliance officers with secondary validation. Sources included FDA HACCP guidance documents, state health department inspection records, EU EFSA marine biotoxin standards, and customs trade data on Atlantic salmon imports. Bottom-up demand modeling across metropolitan consumption clusters triangulated against top-down value chain analysis.
Historical reference periods anchored the projection horizon to documented order velocity shifts from walk-in traffic toward platform-mediated sub-hour delivery windows. Segmentation dimensions spanned product type, distribution channel, price tier, and cuisine style, with regional regulatory clusters and cold-chain infrastructure maturity as cross-cutting variables. CAGRs derived from fitted growth curves incorporating urban millennial household formation patterns and cloud kitchen penetration rates across coastal employment centers.
Caveats apply where FDA enforcement intensity, state-level plastic packaging ban timelines, or wild catch quota fluctuations could materially shift the outlook. Forecasts reflect documented assumptions about subscription adoption curves and last-mile thermal packaging cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Herring Market
Seafood
Mussel Oil Market
Seafood
Smoked Salmon Market
Seafood
Fish Nutrition Market
Seafood
Organic Seafood Market
Seafood
Surimi by-Product Market
Seafood
Organic Shrimp Market
Seafood
Global White Shrimp Market
Seafood
Sardine and Anchovy Umami Concentrate Systems Market
Seafood
Processed Seafood and Seafood Processing Equipment Market
Seafood
Oyster Meal Market
Seafood
South America Canned Seafood Market
Seafood
United Arab Emirates Seafood Market
Seafood
Canned Sardines Market
Seafood
Canned Fishery Product Market
Seafood
Fried Dace with Salted Black Beans Market