
 Wheatgrass Products Market | 2026-2036
Wheatgrass Products Market Size, Share, and Industry Trends Forecast 2026-2036
Wheatgrass Products Market Intelligence
North American organic acreage expansion is reshaping raw material availability for wheatgrass suppliers. Amazing Grass leverages its vertically integrated sourcing from Kansas farmland to secure batch consistency. Pines International anchors its competitive position through freeze-drying technology leadership. NOW Foods competes on pharmaceutical-grade manufacturing protocols that extend shelf life without synthetic preservatives.
Wheatgrass products comprise young Triticum aestivum shoots processed into consumable forms, typically containing chlorophyll concentrations of 70 percent by dry weight and requiring low-temperature dehydration to preserve heat-sensitive enzymes. Their primary commercial purpose centers on delivering concentrated phytonutrient intake for detoxification and immune support applications. Powder formulations dominate volume due to logistics efficiency and extended stability, while ready-to-drink shots capture premium pricing from convenience-seeking urban consumers. Online distribution channels are displacing traditional health store networks as subscription replenishment models reduce customer acquisition costs.
USDA Organic certification and FDA Good Manufacturing Practice standards govern domestic product claims and facility audits, while EU EFSA novel food assessments create barriers for imported wheatgrass concentrates entering European markets. Compliance with California Proposition 65 heavy metal testing has become a de facto national benchmark for contaminant screening. Stakeholders must monitor evolving FDA guidance on structure-function claims, as enforcement actions against unsubstantiated detoxification messaging could reshape permissible marketing language and reformulation priorities.
Market Dynamics
Direct-to-consumer subscription models are compressing traditional retail margins while concentrating purchasing power among vertically integrated suppliers with captive organic acreage. Cold-pressed juicing culture in fitness centers has normalized wheatgrass as a daily wellness ritual rather than occasional supplement.
Growth Catalysts
- USDA National Organic Program:Certification requirements tighten ingredient traceability standards, advantaging suppliers with in-house farming operations over contract-dependent competitors.
- Functional beverage adoption:Fitness centers and wellness facilities integrate wheatgrass shots into membership packages, creating institutional demand pipelines.
- Freeze-drying technology:Low-temperature dehydration preserves heat-sensitive enzymes, extending shelf stability without synthetic preservatives and unlocking pharmaceutical-grade applications.
Market Restraints
- Organic wheatgrass input costs:Kansas and Oregon farmland concentration creates weather-dependent supply volatility, squeezing margin for non-integrated processors.
- EU EFSA novel food assessments:Imported wheatgrass concentrates face extended approval timelines, blocking market entry for US-based exporters.
- Spirulina and chlorella substitution:Competing supergreens with established GRAS status capture price-sensitive consumers seeking chlorophyll alternatives.
Strategic Opportunities
- California cold-pressed juicing culture:Los Angeles and San Francisco metro areas demonstrate mainstream penetration potential for ready-to-drink formats.
- IRA clean energy incentives:Solar-powered dehydration facilities reduce operational carbon intensity, qualifying for federal tax credits that offset capex.
- Telehealth integration:Functional medicine practitioners prescribe wheatgrass protocols through virtual consultations, creating prescription-adjacent demand channels.
Industry Challenges
- FDA structure-function claim enforcement:Detoxification and immune support messaging faces heightened scrutiny, requiring legal review of all consumer-facing materials.
- California Proposition 65 compliance:Heavy metal testing protocols add 6-8 weeks to batch release timelines, constraining working capital for smaller processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheatgrass Products Market |
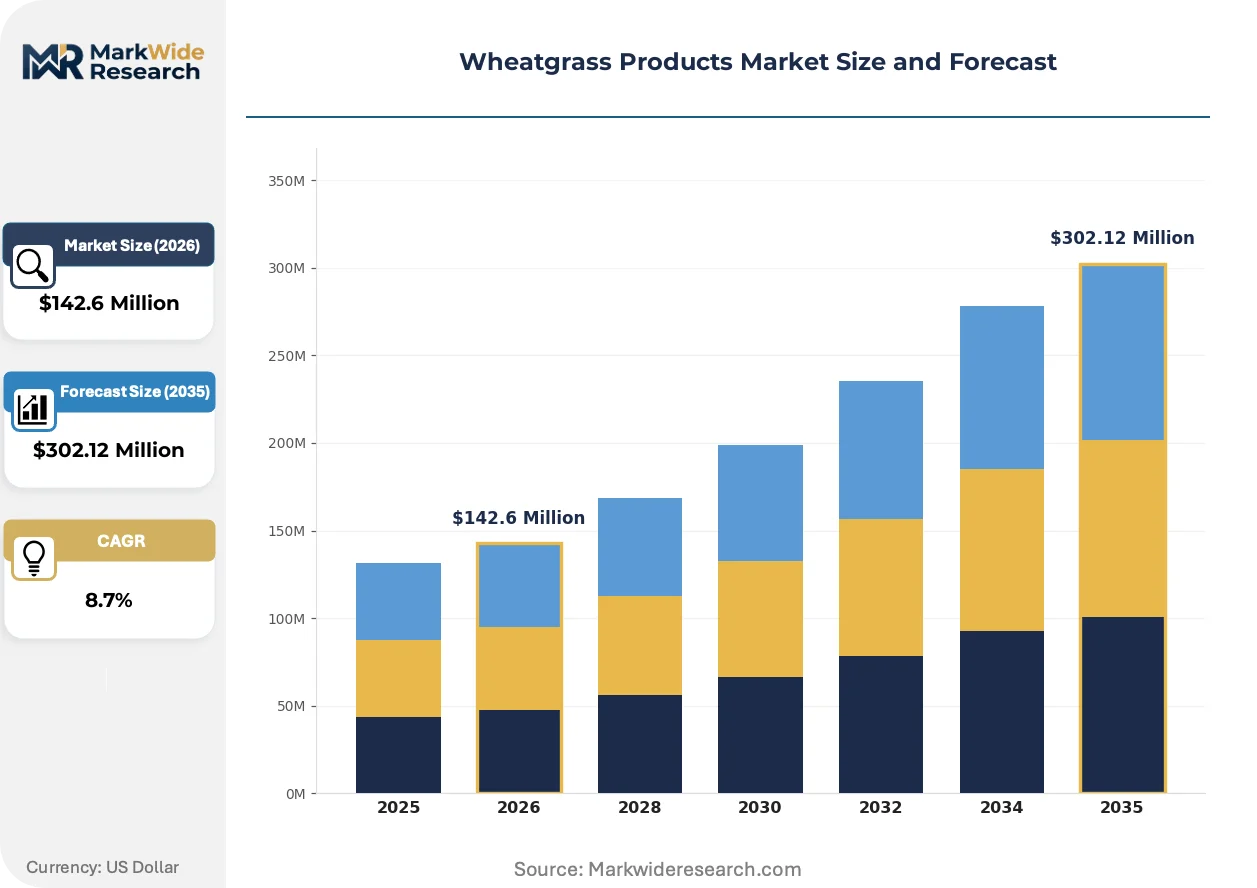
| Market Size in 2026 | $142.6 Million |
| Market Size in 2035 | $302.12 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Juice, Capsules, Shots Form: Frozen, Dried, Liquid, Fluid Distribution Channel: Online, Health Stores, Supermarkets, Specialty Shops End User: Individuals, Fitness Centers, Restaurants, Wellness Facilities |
| Companies Covered | Amazing Grass, Myprotein, Pines International, Synergy Natural, Terrasoul Superfoods, NOW Foods, Naturya, Glanbia plc, Navitas Organics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheatgrass Products Market Strategic Shifts & Innovations
Technology convergence between agricultural monitoring and precision dehydration is redefining quality consistency benchmarks. Regulatory tightening on health claims is forcing reformulation toward evidence-backed positioning. Channel migration from brick-and-mortar to replenishment subscriptions is rewriting customer acquisition economics.
Cold-pressed juicing technology is virtualizing the traditional powder-dominant market structure. Urban wellness studios in New York and Austin deploy on-site micro-juicers that convert raw wheatgrass into immediate-consumption shots. This equipment compresses the value chain by eliminating processing, packaging, and distribution intermediaries. Equipment manufacturers report 40% year-over-year placement growth in boutique fitness chains.
EU EFSA novel food assessments are reshaping import compliance strategies for wheatgrass concentrates. The evaluation framework requires comprehensive toxicological dossiers that extend approval timelines to 18-24 months. German and Dutch distributors are responding by establishing EU-based cultivation partnerships to bypass novel food classification entirely.
Subscription replenishment models are displacing health store networks as the primary acquisition channel. Direct-to-consumer brands capture recurring revenue through automated delivery schedules tied to consumption patterns. This shift is most visible in Portland and Denver, where urban consumers prioritize convenience over in-person product evaluation.
Wheatgrass Products Market Segmentation
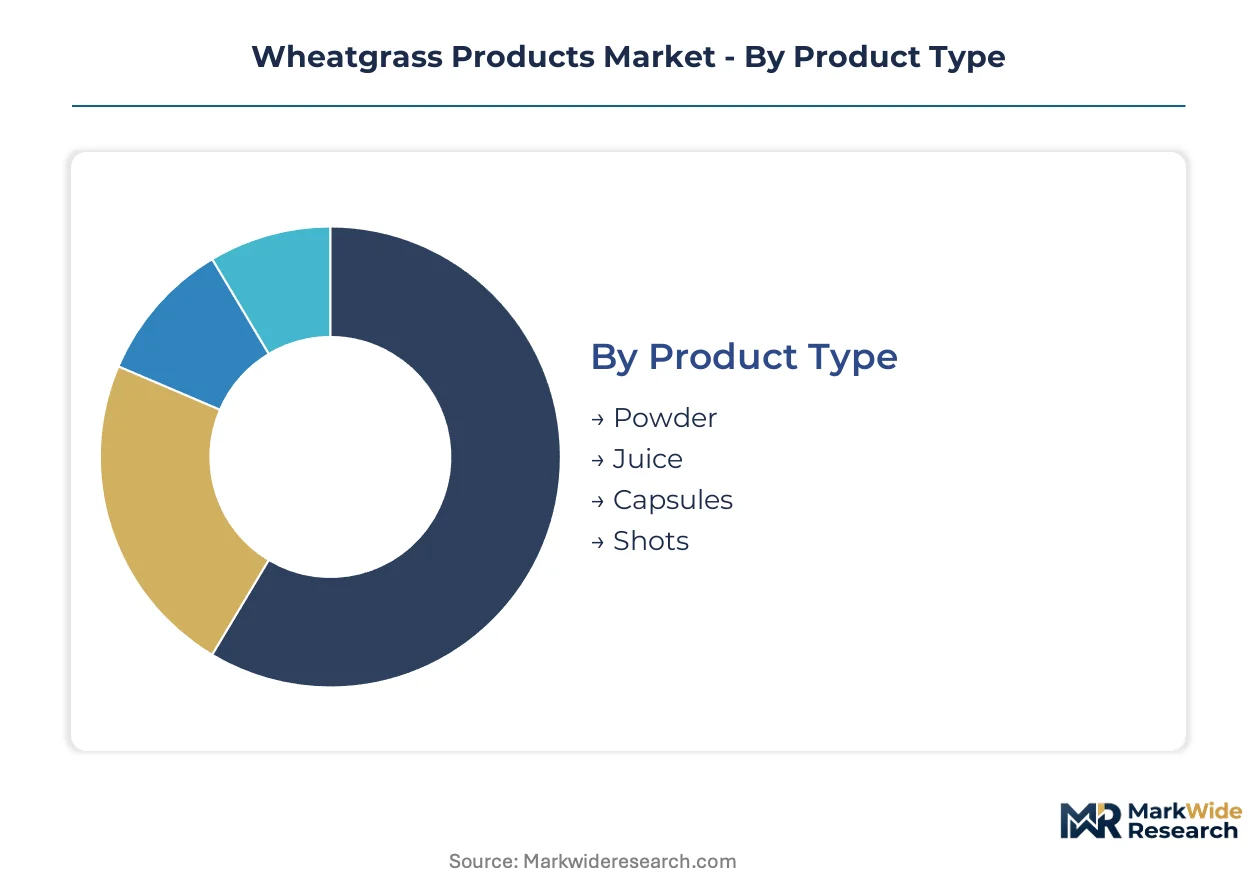
Wheatgrass product segmentation reveals how processing technology and channel economics partition value capture across the supply chain. Powder and juice formats serve fundamentally different consumption moments, while distribution infrastructure determines margin retention for organic-certified suppliers.
Product Type:
Consumption occasions span at-home daily supplementation through institutional wellness protocols, with format choice driven by convenience tolerance and enzyme preservation requirements.
- Juice:Cold-pressed extraction delivers maximum chlorophyll bioavailability for detoxification protocols. Los Angeles and San Francisco fitness studios integrate fresh-pressed shots into membership packages, though perishability limits geographic reach from cultivation centers.
- Powder:Low-temperature dehydration preserves heat-sensitive enzymes while enabling 18-month shelf stability. Kansas vertically integrated suppliers dominate volume through pharmaceutical-grade manufacturing protocols that extend distribution radius without synthetic preservatives.
- Capsules:Standardized dosing appeals to supplement-averse consumers seeking precise phytonutrient intake without taste compromise.
- Shots:Single-serve convenience commands premium positioning in urban convenience retail and airport wellness kiosks.
Established volume favors powder; emerging adoption favors juice.
Form:
Processing temperature and moisture content determine enzyme viability, creating tiered quality benchmarks that separate premium from commodity positioning.
- Frozen:Blast-freezing at harvest locks cellular integrity for maximum nutrient density. Portland and Denver subscription services prioritize frozen for high-retention home delivery.
- Dried:Freeze-drying technology from Pines International anchors shelf-stable supply chains without synthetic preservatives, unlocking pharmaceutical-grade applications.
- Liquid:Ready-to-drink formulations require cold-chain logistics that concentrate distribution in California and Oregon metro corridors.
- Fluid:Concentrated extracts enable beverage manufacturer formulation flexibility for functional drink portfolios.
Commercial scale concentrates in dried; consumer premiumization drives frozen.
Distribution Channel:
Channel selection dictates customer acquisition economics and subscription replenishment potential, with digital infrastructure displacing traditional health retail networks.
- Online:Direct-to-consumer subscription models reduce customer acquisition costs through automated replenishment tied to consumption patterns. Portland and Denver urban consumers prioritize convenience over in-person evaluation.
- Health Stores:Staff-guided purchasing supports premium positioning for certified organic SKUs, though foot traffic compression erodes margin.
- Supermarkets:Mass retail placement requires price competitiveness that favors non-organic or blended formulations.
- Specialty Shops:Cold-pressed juicing boutiques in New York and Austin deploy on-site micro-juicers that eliminate processing and packaging intermediaries entirely.
Volume leadership sits with online; experiential differentiation favors specialty shops.
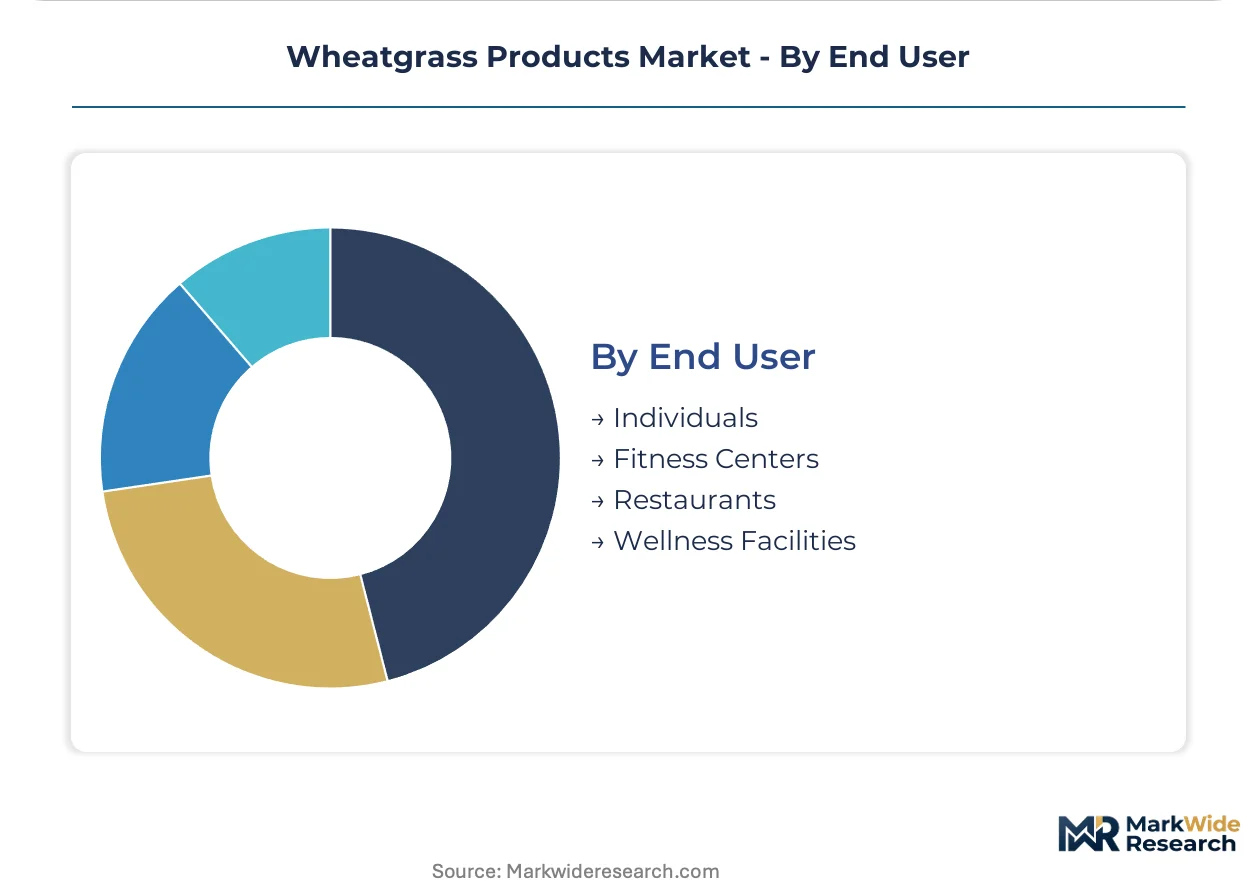
End User:
Demand concentration varies from individual wellness optimization through institutional procurement protocols that normalize daily consumption rituals.
- Individuals:Home consumption drives powder and capsule volume through subscription replenishment, with California and Oregon showing highest per-capita adoption.
- Fitness Centers:Institutional procurement packages wheatgrass shots into membership benefits, creating predictable demand pipelines for local cold-press suppliers.
- Restaurants:Farm-to-table positioning in Los Angeles and Austin incorporates fresh wheatgrass into menu offerings as functional ingredient differentiators.
- Wellness Facilities:Functional medicine practitioners in telehealth channels prescribe wheatgrass protocols, creating prescription-adjacent demand through virtual consultation platforms.
Institutional expansion favors fitness centers; personalization depth favors individuals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Organic wheatgrass cultivation clusters in the United States, where Kansas farmland and Pacific Coast processing infrastructure create integrated supply corridors. Certification requirements under USDA National Organic Program and EU Organic Regulation are fragmenting raw material flows across jurisdictions. Consumer adoption concentrates in metro areas where cold-pressed juicing culture has normalized daily consumption rituals.
United States
Fitness center procurement packages and direct-to-consumer subscription models drive institutional and household demand simultaneously. FDA Good Manufacturing Practice standards and California Proposition 65 heavy metal testing create compliance benchmarks that de facto govern national distribution. Kansas vertically integrated suppliers and Oregon cold-press processors anchor production capacity, with Los Angeles and San Francisco metro areas showing highest per-capita consumption intensity.
Germany
Functional beverage integration into wellness studio membership protocols sustains steady institutional uptake. EFSA novel food assessment requirements for imported concentrates have prompted Dutch and German distributors to establish EU-based cultivation partnerships. Berlin and Hamburg wellness facility clusters are normalizing wheatgrass as prescription-adjacent protocol through telehealth-integrated functional medicine practitioners.
United Kingdom
Subscription replenishment models from Portland and Denver analogues are penetrating London and Manchester urban consumer bases seeking convenience. The country's national food safety regulator enforces contaminant screening protocols aligned with evolving EU organic traceability standards. Bristol and Brighton specialty retail clusters demonstrate experiential differentiation through on-site micro-juicing equipment that eliminates packaging intermediaries.
Japan
Standardized dosing formats appeal to supplement-disciplined consumers prioritizing precise phytonutrient intake without taste compromise. METI industrial standards and national pharmaceutical regulator guidelines shape permissible health claim language and manufacturing facility audits. Tokyo and Osaka metro wellness facility networks integrate wheatgrass protocols into corporate wellness programs sponsored by major employers.
Australia
Organic certification demand from fitness-conscious urban populations concentrates procurement toward traceable supply chains. TGA therapeutic goods frameworks and national food standards code govern product classification and permitted indications. Sydney and Melbourne cold-pressed juicing boutiques are deploying equipment that converts raw wheatgrass into immediate-consumption shots, compressing traditional value chain structures.
Wheatgrass Products Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream. The supplier base stratifies between vertically integrated organic growers with captive acreage and contract-dependent processors exposed to input cost volatility. Three archetypes dominate: Kansas-based farmland owners controlling batch consistency, freeze-drying technology licensors extending shelf stability, and pharmaceutical-grade manufacturers serving extended distribution radii. Competitive moves concentrate on backward integration into organic cultivation and subscription infrastructure buildout to capture recurring revenue.
Within the vertically integrated tier, Amazing Grass and Pines International exemplify archetypes built on farmland control and dehydration technology leadership respectively. NOW Foods occupies a position representing pharmaceutical-grade manufacturing protocols. Among specialty and diversified players, Glanbia plc and Navitas Organics sit within broader superfood portfolio structures that dilute wheatgrass-specific exposure while capturing cross-selling synergies.
| Leading Market Players |
|---|
| Amazing Grass |
| Myprotein |
| Pines International |
| Synergy Natural |
| Terrasoul Superfoods |
| NOW Foods |
| Naturya |
| Glanbia plc |
| Navitas Organics |
| Others |
Cost & Logistics Intelligence
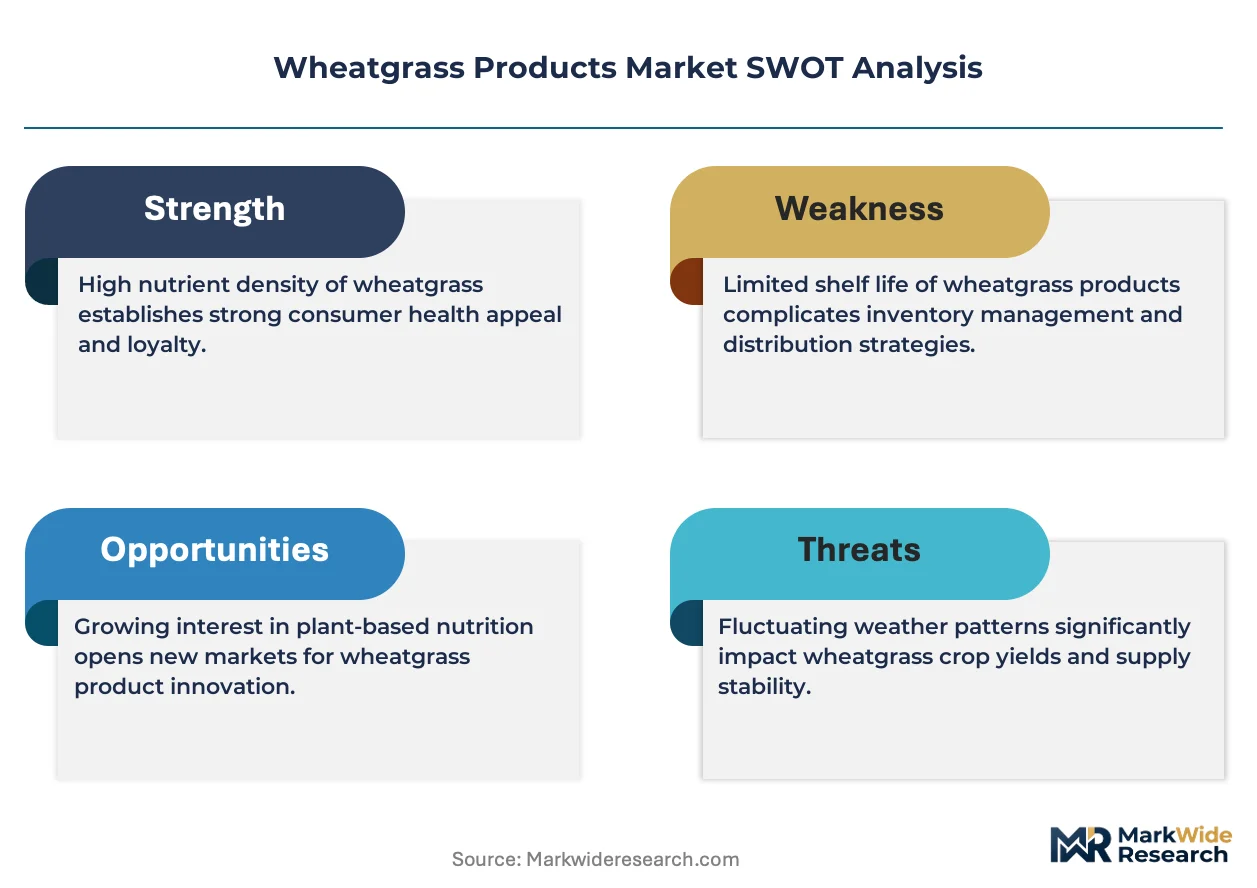
Organic wheatgrass input cost volatility in Kansas and Oregon farmland clusters determines both the spread between premium freeze-dried powders and commodity-grade alternatives and the geographic shape of processing infrastructure investment. This weather-dependent supply risk compresses margins for contract-dependent processors while rewarding vertically integrated suppliers with captive acreage and cold-chain logistics control.
Pricing Analysis
USDA National Organic Program certification tiers dictate the pricing tier structure across the wheatgrass market. Three-tier pricing stratifies across certified organic freeze-dried powders, conventional dehydrated grades, and private-label commodity blends, with certification investment and enzyme retention benchmarks as primary differentiation drivers. Pricing pressure stems from spirulina and chlorella substitution in the chlorophyll supplement category, forcing wheatgrass suppliers to emphasize bioavailability claims. Fitness centers and wellness facilities show the lowest price sensitivity due to membership bundling economics, while mass retail supermarket channels face the highest price elasticity.
Supply Chain Analysis
Tariff exposure between the United States and European Union member states dominates supply chain risk for wheatgrass concentrate exporters facing EFSA novel food assessment barriers. Raw material sourcing concentrates in Kansas farmland for vertically integrated powder processors and Oregon's Willamette Valley for cold-pressed juice specialists, with distribution running through direct-to-consumer subscription platforms and boutique fitness channel partners. The supply chain rests on organic wheatgrass seed stock, pharmaceutical-grade dehydration equipment, and refrigerated logistics infrastructure as critical input dependencies. Single-source vulnerability in Kansas farmland concentration creates weather-induced supply disruptions that cascade through batch release timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wheatgrass products function as a service-attach opportunity where subscription replenishment models and telehealth protocol integration are expanding faster than standalone powder or juice hardware sales. The recurring revenue layer from automated delivery schedules and practitioner-prescribed consumption protocols now outpaces unit volume growth in traditional retail channels.
For Market Incumbents: Insulate market position by deepening backward integration into Kansas and Oregon organic acreage to secure batch consistency against weather-driven input volatility. Invest in freeze-drying technology licensing partnerships to extend shelf stability differentiation against commodity spray-dried alternatives. Channel control through proprietary subscription infrastructure reduces customer acquisition cost erosion from platform-dependent competitors.
For New Entrants and Emerging Players: Establish a beachhead in the telehealth-integrated functional medicine channel where prescription-adjacent wheatgrass protocols create sticky practitioner relationships and recurring patient orders. Target urban wellness studio partnerships in Austin and Denver where cold-pressed juicing culture normalizes daily consumption rituals. A go-to-market angle anchored to solar-powered dehydration facilities qualifies for IRA clean energy tax credits that offset capital expenditure barriers.
For Investors and Strategic Acquirers: FDA structure-function claim enforcement reshapes the acquisition landscape by elevating legal review capabilities and evidence-backed positioning as due diligence priorities. Long-term viability favors vertically integrated suppliers with captive organic acreage and pharmaceutical-grade manufacturing certifications over contract-dependent processors exposed to margin compression. The signal to watch is EU EFSA novel food assessment timeline compression for imported concentrates, which would unlock European market entry for US-based cultivation assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Acreage | Kansas farmland control secures batch consistency against weather-driven supply volatility. |
| Freeze-Drying Technology Licensing | Pines International's low-temperature dehydration protocols extend shelf stability without synthetic preservatives. |
| Subscription Infrastructure Buildout | Portland and Denver urban consumers prioritize automated replenishment over in-person product evaluation. |
| Telehealth Protocol Integration | Functional medicine practitioners prescribe wheatgrass through virtual consultations, creating prescription-adjacent demand. |
| Solar-Powered Dehydration Facilities | IRA clean energy incentives reduce operational carbon intensity and offset capital expenditure for processing infrastructure. |
Research Approach
Cross-validation between primary interviews with organic certification specialists, cold-press equipment manufacturers, and functional medicine practitioners anchors the qualitative findings against secondary data from USDA National Organic Program filings, FDA Good Manufacturing Practice audit records, and EFSA novel food assessment databases. Bottom-up triangulation across cultivation acreage reports, processing capacity installations, and subscription platform transaction patterns converges with top-down analysis of chlorophyll supplement category spend. This dual approach isolates wheatgrass-specific demand from broader supergreen market aggregates.
Calibration against historical volume trajectories in the functional beverage and dietary supplement categories informs the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, processing temperature tier, distribution channel architecture, and end-user procurement pattern. CAGRs were derived from elasticity-adjusted adoption curves incorporating fitness center membership growth, organic acreage expansion rates, and subscription platform penetration benchmarks as industry-specific forecast inputs.
Stress conditions across Kansas and Oregon weather volatility, EU EFSA approval timeline extensions, and FDA structure-function claim enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about certification compliance costs and channel migration velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Global Guilt-Free Desserts Market
Specialty Foods
Global Cocoa Nibs Market
Specialty Foods
Acacia Honey Market
Specialty Foods
Vegetarian Tacos Market
Specialty Foods
Vegan Dressing Market
Specialty Foods
Mexico Guacamole Market
Specialty Foods
Superfood Bars Market
Specialty Foods
Low Fat Hummus Market
Specialty Foods
Low-Fat Low-Calorie Desserts Market
Specialty Foods
Global Cordyceps Militaris Market
Specialty Foods
Guacamole Market
Specialty Foods
Saw Palmetto Market
Specialty Foods
Huoxiangzhengqi Market
Specialty Foods
Edible Cutlery Market
Specialty Foods
Foie Gras Market
Specialty Foods
Cat Food Flavors Market