
 White Fungus Market | 2026-2036
White Fungus Market Size, Share, and Industry Trends Forecast 2026-2036
White Fungus Market Analysis
China is narrowing its grip on white fungus cultivation capacity as climate-controlled indoor farms multiply across Fujian and Zhejiang provinces. Shanghai Finc Bio-Tech leverages polysaccharide extraction patents to anchor its pharmaceutical-grade supply chain. Monterey Mushrooms sustains North American distribution through backward integration into substrate production. GUAN'S MUSHROOM specializes in dried and powdered formats for export markets, competing on processing scale rather than raw tonnage.
White fungus (Tremella fuciformis) is a gelatinous basidiomycete containing beta-glucans and heteropolysaccharides, traditionally cultivated on hardwood sawdust substrates under precise humidity and temperature conditions for use in soups, desserts, and therapeutic preparations. The dried segment dominates trade volumes due to shelf stability and concentrated polysaccharide content, while powder formats capture expanding nutraceutical contract manufacturing demand. Pharmaceutical applications lead margin pools through extract standardization, though food industry consumption still occupies the largest volume share across restaurant and home cook channels.
China's SAMR enforces GB standards on fungal food products, while the NMPA regulates polysaccharide extracts marketed as functional ingredients, creating dual compliance thresholds for cross-border suppliers. The EU EFSA novel food framework and FDA GRAS self-determination pathway in the United States add further market access complexity for concentrated extracts. Stakeholders must monitor evolving pharmacopeial monographs and adapt extraction documentation to preempt regulatory divergence between major import jurisdictions.
Market Dynamics
Polysaccharide extraction patent clustering in Fujian and Zhejiang provinces is compressing supply-side margins while pharmaceutical-grade certification requirements from China's NMPA and the EU EFSA novel food framework are fragmenting market access pathways.
Growth Catalysts
- Pharmaceutical extraction demand:Standardized beta-glucan isolates for immunomodulatory applications are pulling cultivation capacity toward contract manufacturing partnerships with nutraceutical formulators.
- GB 7096 food safety standards:China's SAMR enforcement of fungal product contaminant limits is accelerating facility upgrades that reduce batch rejection rates for export-bound dried formats.
- Climate-controlled indoor farming:Substrate humidity automation in Zhejiang is collapsing cultivation cycle variability and enabling year-round polysaccharide yield consistency.
Market Restraints
- Hardwood sawdust input volatility:Substrate cost fluctuations from lumber processing byproduct availability constrain margin predictability for non-integrated cultivators.
- Single-origin supply concentration:Fujian province's dominance in dried white fungus export tonnage creates geographic risk exposure for importers dependent on Chinese customs clearance timelines.
- EFSA novel food authorization delays:European market entry for concentrated extracts faces 18-24 month safety assessment queues that freeze capital deployment.
Strategic Opportunities
- North American cultivation underpenetration:Monterey Mushrooms' California substrate integration demonstrates scalable domestic production potential for US pharmaceutical contract manufacturers seeking GRAS self-determination pathways.
- Cosmeceutical topical applications:Tremella polysaccharide hydrogel formulations for dermal hydration are opening adjacent revenue streams beyond ingestible formats.
- Dual carbon policy alignment:China's MEE carbon intensity targets for agricultural processing are incentivizing solar-powered drying facilities that qualify for green export certification.
Industry Challenges
- Pharmacopeial monograph alignment:Divergent polysaccharide content measurement methods between ChP, USP, and EP standards force duplicate analytical method validation for multi-jurisdiction suppliers.
- Extraction technician scarcity:Skilled operators capable of maintaining GMP-compliant hot-water extraction parameters are concentrated in legacy pharmaceutical hubs, constraining facility expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Fungus Market |
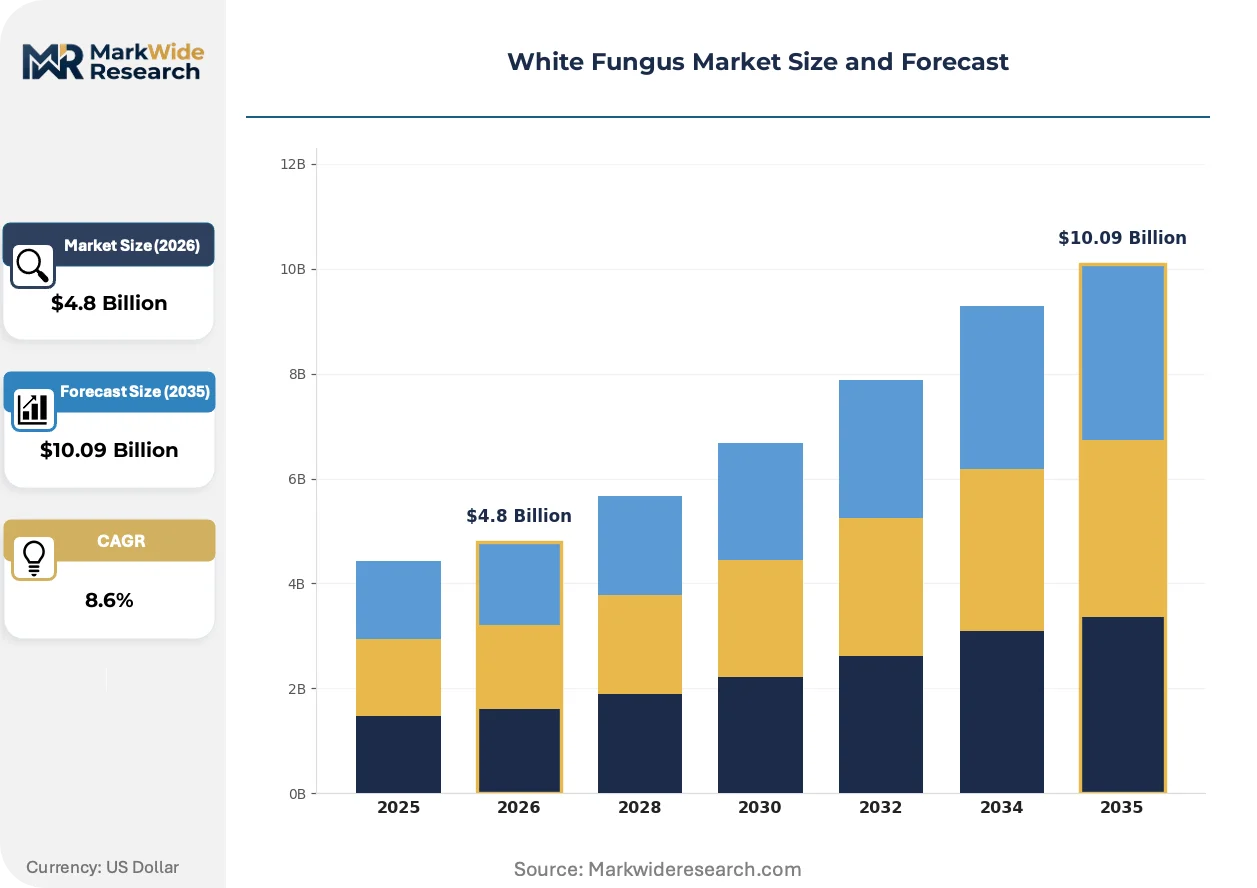
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Dried, Canned, Powder Application: Food Industry, Pharmaceutical, Cosmetics, Nutraceuticals End User: Restaurants, Home Cooks, Manufacturers, Distributors Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Monaghan Mushrooms, Bonduelle Group, Giorgio Fresh Co., Costa Group, Shanghai Finc Bio-Tech, Monterey Mushrooms, Drinkwater Mushrooms, Greenyard, GUAN'S MUSHROOM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Fungus Market Emerging Trajectories
Subcritical water extraction and ultrasonic-assisted polysaccharide recovery are compressing processing timelines while regulatory documentation automation is reducing compliance labor intensity across multi-jurisdiction suppliers.
Subcritical water extraction systems operating at 150-200°C and 5-10 MPa are recovering beta-glucan fractions with 40% shorter residence times than conventional boiling methods. Pharmaceutical-grade extract manufacturers in Zhejiang are retrofitting batch reactors with these systems to meet NMPA purity specifications. This thermal processing innovation is rendering obsolete open-vessel atmospheric extraction that cannot achieve the polysaccharide molecular weight consistency required for injectable-grade applications.
China's SAMR is harmonizing fungal food product labeling requirements with GB 7718 prepackaged food standards, forcing dried format exporters to revalidate nutritional claim substantiation. The industrial consequence is a documentation burden shift from finished product distributors back to raw material cultivators. Dried segment suppliers are responding by deploying blockchain-enabled batch traceability systems that automate GB compliance certificate generation.
Direct procurement relationships between pharmaceutical formulators and cultivation cooperatives are disintermediating traditional dried fungus trading companies in Guangzhou and Xiamen. Large nutraceutical contract manufacturers are establishing multi-year offtake agreements that specify polysaccharide content tiers and testing protocols. This channel restructuring is most visible in US and German markets where FDA GRAS notifications and EFSA novel food dossiers require cultivator-level traceability documentation that commodity traders cannot provide.
White Fungus Market Segmentation
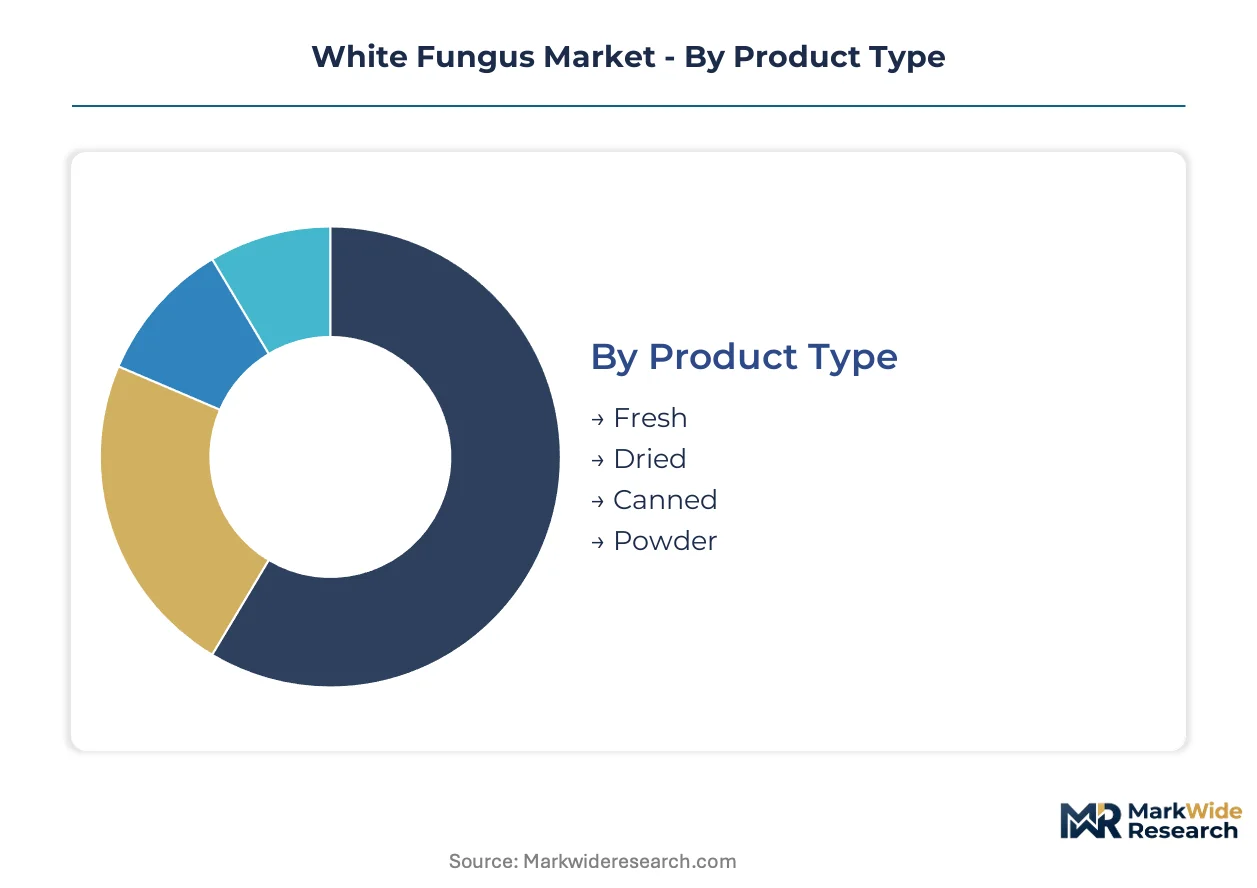
White fungus market segmentation reflects divergent value capture across preservation formats and end-use sophistication. Pharmaceutical extractors demand powder standardization while food channels trade volume through dried and canned formats. Each segment carries distinct regulatory burdens and margin structures that reshape supplier positioning.
Product Type:
Fresh formats serve immediate consumption niches while processed variants unlock shelf-stable commerce across hemispheres.
- Dried:Concentrated polysaccharide content and indefinite ambient storage dominate export economics. Fujian and Zhejiang processing clusters supply restaurant rehydration workflows across East Asian diaspora communities in the United States, Canada, and Australia.
- Powder:Finely milled particle sizes below 200 mesh enable precise dosing in capsule and tablet formulations. Contract manufacturers in Germany and the United States specify hot-water soluble fractions for nutraceutical blending, pulling cultivation capacity toward pharmaceutical-grade certification.
- Fresh:Gelatinous texture retention suits premium dessert applications in Shanghai and Taipei metropolitan restaurants with same-day supply chain coverage.
- Canned:Pre-cooked syrup preservation targets Southeast Asian retail shelves where home preparation time constraints favor convenience formats.
The dominant share belongs to Dried, while Powder is closing the gap fastest.
Application:
Margin concentration tracks extraction complexity and pharmacopeial compliance requirements rather than raw tonnage.
- Pharmaceutical:Standardized beta-glucan isolates for immunomodulatory drug development command premium pricing contingent on NMPA or FDA submission-grade documentation. Zhejiang extractors with GMP-certified hot-water facilities capture this tier.
- Nutraceuticals:Functional ingredient positioning in capsule, gummy, and beverage formats requires GRAS self-determination or EFSA novel food dossiers. US and German formulators drive specification tightening.
- Food Industry:Soup and dessert manufacturing in China, Japan, and South Korea consumes the largest raw volume through institutional procurement contracts.
- Cosmetics:Tremella polysaccharide hydrogels for dermal hydration applications are gaining traction among South Korean and Japanese skincare formulators seeking hyaluronic acid alternatives.
Food Industry retains volume leadership, though Pharmaceutical applications generate the steepest margin expansion.
End User:
Procurement sophistication separates specification-driven manufacturers from price-sensitive household purchasers.
- Manufacturers:Pharmaceutical and nutraceutical formulators in the United States, Germany, and Japan impose polysaccharide content tiers, heavy metal testing protocols, and batch traceability requirements that exclude commodity traders.
- Restaurants:Cantonese and Taiwanese cuisine establishments across Malaysia, Singapore, and North American Chinatowns drive consistent dried format demand for banquet dessert preparation.
- Distributors:Traditional trading companies in Guangzhou and Xiamen face disintermediation pressure as direct cultivator-formulator relationships proliferate.
- Home Cooks:Retail package purchasing concentrates in Chinese urban supermarkets and diaspora community specialty grocers.
Manufacturers command specification authority, while Restaurants provide the most stable volume foundation.
Distribution Channel:
Channel selection determines compliance documentation exposure and working capital intensity for suppliers.
- Wholesale:Bulk dried tonnage moves through Xiamen and Guangzhou export houses to importers in Los Angeles, Vancouver, and Sydney, with customs clearance timing risks concentrated in Fujian-origin shipments.
- Online Retail:Cross-border e-commerce platforms enable direct-to-consumer powder sales from Zhejiang extractors to US and European wellness consumers, bypassing traditional import distributor markups.
- Specialty Stores:Traditional Chinese medicine apothecaries and Asian grocery independents stock dried and canned formats for established diaspora demand.
- Supermarkets:Mainstream retail placement remains limited outside East Asian markets, with occasional premium fresh or dried offerings in North American urban centers.
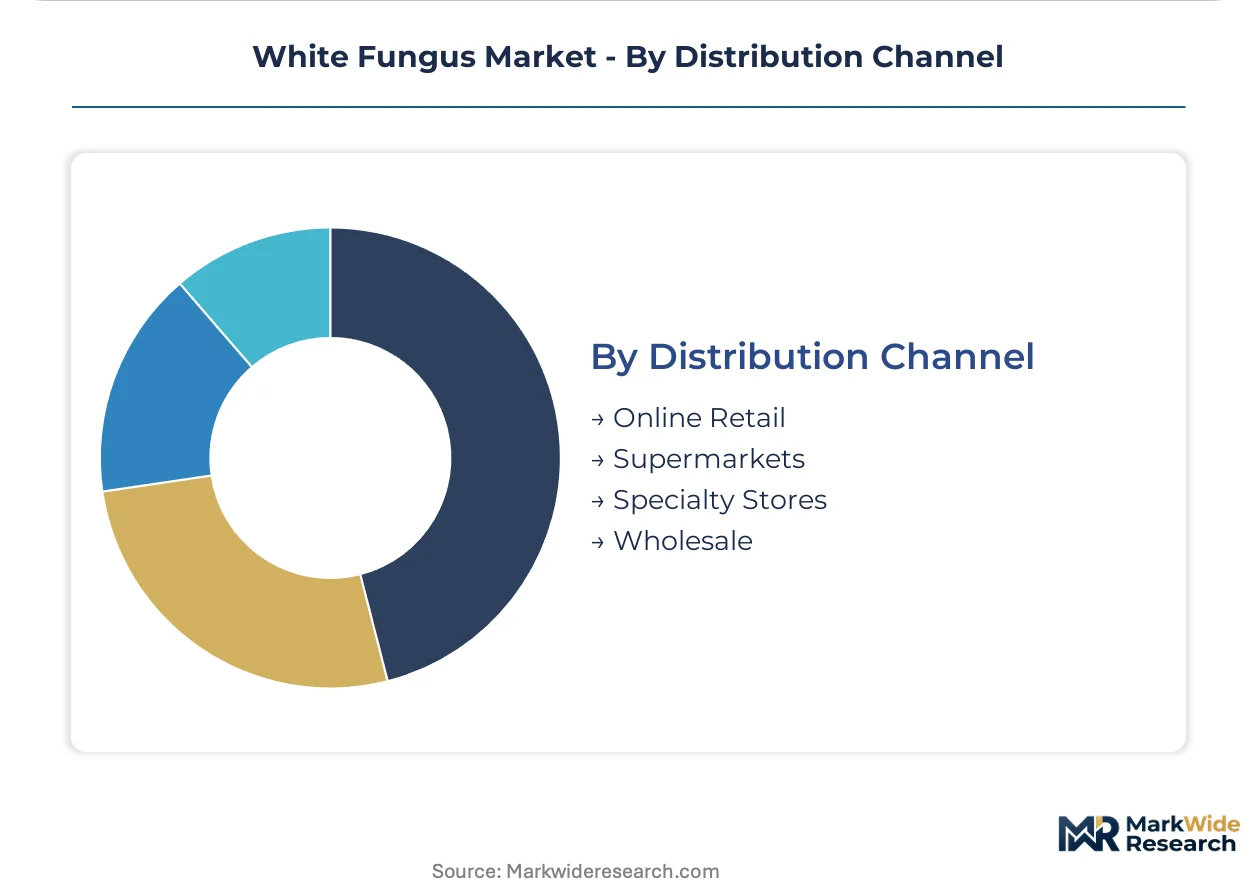
Wholesale channels dominate export volume, yet Online Retail is expanding most quickly for finished extract products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cultivation capacity clusters in East Asian climate-controlled facilities, while North American and European markets remain dependent on import flows. Regulatory divergence across FDA GRAS, EFSA novel food, and China's GB standards fragments certification pathways for extract suppliers.
China
Pharmaceutical-grade polysaccharide extraction drives Fujian and Zhejiang facility investments. SAMR enforces GB 7096 fungal food safety standards that accelerate export-bound processing upgrades. Xiamen and Guangzhou trading clusters face disintermediation as direct cultivator-formulator relationships proliferate.
United States
Nutraceutical contract manufacturers seek GRAS self-determination pathways for Tremella beta-glucan isolates. FDA submission-grade documentation requirements exclude commodity traders from pharmaceutical supply chains. Monterey Mushrooms' California substrate integration demonstrates scalable domestic cultivation potential.
Germany
EFSA novel food dossier queues extending 18-24 months freeze capital deployment for concentrated extract market entry. Functional ingredient formulators in Bavaria and Baden-Württemberg impose polysaccharide content tiers and heavy metal testing protocols. Direct procurement from Chinese cultivation cooperatives is displacing traditional Amsterdam and Rotterdam import distributors.
Japan
PMDA pharmacopeial alignment with ChP standards enables cross-border extract standardization for immunomodulatory applications. Tokyo and Osaka nutraceutical formulators drive specification tightening for hot-water soluble fractions. Kanto region skincare laboratories pioneer Tremella polysaccharide hydrogel formulations as hyaluronic acid alternatives.
South Korea
MFDS regulates functional food positioning while cosmeceutical demand accelerates for dermal hydration applications. Seoul metropolitan area formulators source dried formats for dessert manufacturing and extract processing. Busan-Ulsan logistics hubs handle re-export flows to Southeast Asian retail channels.
White Fungus Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in substrate and extraction technology. The supplier base fragments across three capability tiers: GMP-certified pharmaceutical extractors, commodity-scale dried processors, and regional fresh distributors. Strategic archetypes include backward-integrated cultivators, patent-anchored extract specialists, and trading intermediaries facing margin compression. Dominant competitive moves encompass direct offtake agreements that disintermediate traditional channels and solar-powered drying facility investments that align with China's MEE carbon intensity targets.
Within the extraction-specialist tier, Shanghai Finc Bio-Tech occupies a position exemplifying polysaccharide patent concentration in Zhejiang province. Monterey Mushrooms anchors North American supply chain integration through captive substrate production. GUAN'S MUSHROOM represents the scale-driven dried format segment competing on processing throughput rather than raw cultivation tonnage.
| Leading Market Players |
|---|
| Monaghan Mushrooms |
| Bonduelle Group |
| Giorgio Fresh Co. |
| Costa Group |
| Shanghai Finc Bio-Tech |
| Monterey Mushrooms |
| Drinkwater Mushrooms |
| Greenyard |
| GUAN'S MUSHROOM |
| Others |
Supply Flow & Price Mechanics
Fujian province's climate-controlled cultivation clusters anchor global dried white fungus tonnage, concentrating polysaccharide yield consistency that translates directly into tiered export pricing power. Pharmaceutical-grade extractors in Zhejiang leverage this supply density to command premium differentials over commodity dried processors, while hardwood sawdust input volatility constrains margin predictability for non-integrated operators.
Pricing Analysis
China's NMPA nutraceutical regulations dictate the pricing tier structure across pharmaceutical, nutraceutical, and food-grade segments. Three-tier pricing stratifies across GMP-certified extractors, GB 7096-compliant dried processors, and uncertified fresh distributors. Price differentiation hinges on polysaccharide standardization levels and batch traceability documentation. Cost compression in commodity dried tiers is intensifying because extraction patent clustering compresses supply-side margins. Food industry procurement teams exhibit highest price sensitivity, while pharmaceutical formulators absorb premium tiers for FDA submission-grade documentation.
Supply Chain Analysis
Export control regimes on polysaccharide extraction technology limit equipment flows to Chinese facilities, reinforcing Fujian and Zhejiang dominance. Raw material procurement draws from hardwood sawdust substrates, automated humidity control systems, and GMP-certified hot-water extraction reactors. Single-origin supply concentration in Fujian creates geographic risk exposure for importers dependent on Chinese customs clearance timelines. Distribution runs through Xiamen and Guangzhou trading houses to North American and European nutraceutical contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
White fungus polysaccharide extraction represents a high-growth disruption as subcritical water recovery systems compress processing timelines and NMPA certification requirements fragment market access pathways.
For Market Incumbents: Harden pharmaceutical-grade certification moats through backward integration into substrate production and captive solar-powered drying facilities that align with China's MEE carbon intensity targets. Patent-anchored extract specialists must defend against commodity-scale dried processors encroaching on nutraceutical contract manufacturing partnerships. For New Entrants and Emerging Players: North American cultivation underpenetration offers the most penetrable white-space opportunity, with Monterey Mushrooms' California substrate integration demonstrating scalable domestic production potential for US pharmaceutical formulators seeking GRAS self-determination pathways. Cosmeceutical topical applications in South Korean and Japanese skincare laboratories provide a second entry vector through Tremella polysaccharide hydrogel formulations. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EFSA novel food authorization delays and FDA GRAS documentation requirements create acquisition windows for cultivators with pre-validated compliance dossiers. Target extract specialists with GMP-certified hot-water facilities and established direct offtake agreements with German and US formulators. Monitor pharmacopeial monograph alignment between ChP, USP, and EP standards as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Certification Investment | GMP-compliant hot-water extraction facilities capture NMPA and FDA submission-grade margin pools. |
| Substrate Backward Integration | Captive hardwood sawdust production insulates margin predictability from lumber processing byproduct volatility. |
| Solar-Powered Drying Facility Buildout | China's MEE dual carbon targets incentivize green export certification for Zhejiang processing clusters. |
| Direct Cultivator-Formulator Partnerships | Multi-year offtake agreements with US and German nutraceutical manufacturers disintermediate Guangzhou trading houses. |
| Cosmeceutical Hydrogel Formulation Development | South Korean and Japanese skincare laboratories pioneer Tremella polysaccharide alternatives to hyaluronic acid. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with cultivation facility managers, polysaccharide extraction technicians, nutraceutical contract manufacturing procurement leads, and SAMR regulatory affairs specialists; and secondary validation through NMPA filing databases, EFSA novel food submission records, GB standards documentation, and customs trade flow data. Bottom-up cultivation capacity modeling triangulated against top-down pharmaceutical extract demand forecasts.
Forecast inputs incorporated product format segmentation across dried, powder, fresh, and canned variants; application tiering across pharmaceutical, nutraceutical, food industry, and cosmetics end-uses; and geographic regulatory clustering across China's GB standards, FDA GRAS pathways, and EFSA novel food frameworks. CAGRs were derived from polysaccharide yield consistency trends and extraction technology adoption curves across the analysis window.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by climate-controlled indoor farming cooperatives or accelerated EFSA approval timelines would shift outcomes. Cross-checking against NMPA pharmaceutical-grade extract certification queues and hardwood sawdust substrate price indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Wet Grain-Free Pet Food Market
Specialty Foods
Super Foods Market
Specialty Foods
Luxury Cigar Market
Specialty Foods
GCC Halal Food Market
Specialty Foods
Asia-Pacific Alcohol-Infused Ice Cream Market
Specialty Foods
Low Calorie Hummus Market
Specialty Foods
Grain Free Dog Food Market
Specialty Foods
North America Popping Boba/Juice Balls Market
Specialty Foods
Areca Bowl Market
Specialty Foods
Miso Market
Specialty Foods
Low Calorie Veggie Dip Market
Specialty Foods
Morocco Couscous Market
Specialty Foods
Yeast-Based Spreads Market
Specialty Foods
Low-Fat Low-Calorie Desserts Market
Specialty Foods
Goldenseal Market
Specialty Foods
Huoxiangzhengqi Market