
 Asia-Pacific Hummus Market | 2026-2036
Asia-Pacific Hummus Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Hummus Market Outlook
Australia's cold-chain infrastructure expansion is fragmenting as domestic hummus production scales beyond Sydney and Melbourne into Brisbane and Perth. Sabra Dipping Company leverages its refrigerated logistics network to anchor shelf presence across Coles and Woolworths banners. Strauss Group Ltd competes through localized flavor adaptation, while Bakkavor Group plc sustains manufacturing scale via ready-to-eat salad and dip co-production facilities in the region.
Hummus is a cold-processed chickpea and tahini emulsion, typically containing olive oil, lemon juice, and garlic, with a shelf life of 30–45 days under refrigerated conditions and a protein content of 6–8 grams per 100-gram serving; it functions as a plant-based dip, spread, and meal accompaniment across retail and foodservice channels. Classic variants dominate volume but command thin margins, whereas Beetroot and Spicy formulations capture premium positioning in Australian and Japanese supermarkets. Food Service distribution channels show structural momentum as hotel chains and QSR operators in Singapore and South Korea add hummus to breakfast and side-dish menus.
FSSAI import clearance protocols, Australia's FSANZ labeling standards, and Japan's JAS organic certification requirements collectively shape product formulation, packaging language, and cold-chain compliance costs for market entrants. Regulatory divergence across the region forces manufacturers to maintain multiple label variants and ingredient specifications. Stakeholders must monitor evolving plant-protein health claims regulation and convenience-store distribution partnerships as the primary vectors for competitive positioning.
Market Dynamics
Cold-chain infrastructure fragmentation across Australia, Japan, and India is redistributing manufacturing capacity and forcing logistics network redesigns as refrigerated hummus production scales beyond traditional urban hubs.
Growth Catalysts
- Urban convenience retail expansion:Japan's time-pressed consumers drive single-serve snacking format demand through 7-Eleven and Lawson banners, compressing purchase cycles and expanding refrigerated shelf space in Tokyo and Osaka.
- FSSAI labeling harmonization:India's tightening ingredient disclosure requirements for imported spreads is accelerating domestic formulation standardization and creating compliance-ready supplier pools for regional exporters.
- Plant-protein positioning:Australian supermarkets allocate expanded chilled dip sections to protein-seeking flexitarians, with Coles and Woolworths banners prioritizing chickpea-based spreads in health-aisle adjacencies.
Market Restraints
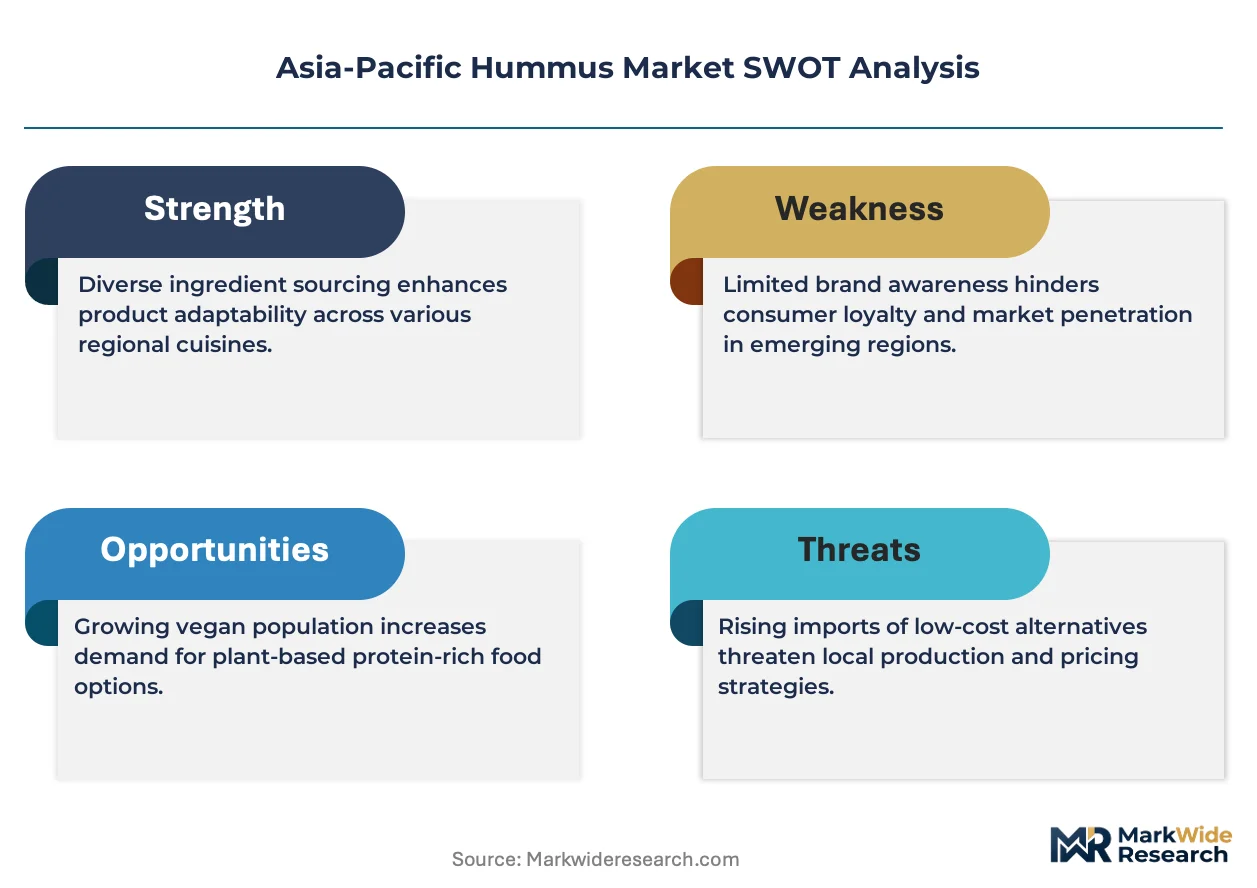
- Tahini input cost volatility:Sesame seed price swings tied to Ethiopian and Sudanese harvest variability compress margins for emulsion-dependent producers across the region.
- Refrigerated logistics concentration:Australia's cold-chain capacity clusters in Sydney and Melbourne, forcing Brisbane and Perth manufacturers to absorb intercity transport premiums or accept shelf-life erosion.
- JAS organic certification friction:Japan's stringent organic labeling requirements create 12-18 month approval timelines that deter mid-scale entrants from premium positioning attempts.
Strategic Opportunities
- South Korean foodservice white space:Hotel breakfast and QSR side-dish menu adoption remains underpenetrated relative to Singapore, creating first-mover positioning for chilled dip distributors.
- Co-manufacturing convergence:Ready-to-eat salad facilities in Australia and New Zealand enable hummus production scale without dedicated capital expenditure, lowering barrier thresholds for private-label entrants.
- FSANZ health claims pathway:Australia's evolving plant-protein nutrient content verification framework offers regulatory tailwind for protein-fortified variant launches targeting fitness-oriented demographics.
Industry Challenges
- Multi-jurisdiction label complexity:Divergent FSSAI, FSANZ, and JAS packaging language requirements force manufacturers to maintain 3-4 label variants, inflating SKU management overhead and inventory carrying costs.
- Cold-chain certification timelines:HACCP and ISO 22000 facility accreditation for refrigerated hummus production averages 8-14 months across Australian states, delaying commercialization for new manufacturing investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Hummus Market |
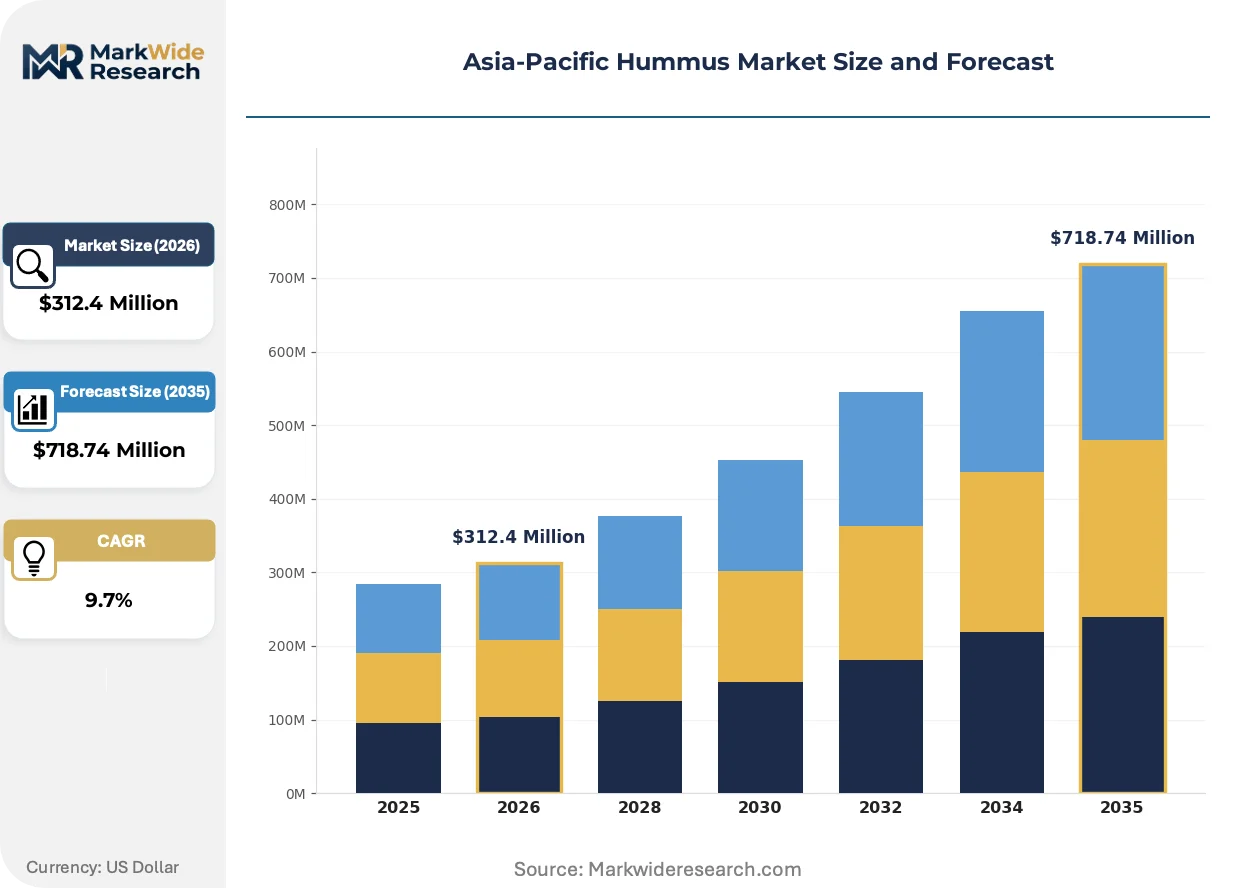
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $718.74 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic, Roasted Garlic, Spicy, Beetroot Distribution Channel: Supermarkets, Online Retail, Food Service, Convenience Stores Packaging Type: Tubs, Pouches, Glass Jars, Snack Packs End User: Households, Restaurants, Cafes, Catering Services |
| Companies Covered | Sabra Dipping Company, LLC, Cedar’s Mediterranean Foods, Inc., Haliburton International Foods, Inc., Bakkavor Group plc, Hope Foods, LLC, Strauss Group Ltd, Lantana Foods, Hormel Foods Corporation, Nestlé S.A., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Hummus Market Strategic Shifts
Digital shelf-space analytics and AI-driven demand forecasting are compressing new product development cycles while reformulation priorities shift toward extended refrigerated stability and clean-label positioning.
High-pressure processing technology is virtualizing traditional thermal pasteurization methods in Australian manufacturing facilities. Coles and Woolworths private-label suppliers adopt HPP systems to achieve 60-90 day refrigerated extension without preservative inclusion. This virtualization is compressing the shelf-life disadvantage against ambient-stable alternatives and enabling national distribution radius expansion from single production points.
Australia's FSANZ is tightening nutrient content claim substantiation requirements for plant-protein products, mandating amino acid profile disclosure for "good source of protein" labeling. Manufacturers reformulating for 8-gram protein per 100-gram serving thresholds face tahini ratio adjustments that alter emulsion stability. Premium-positioned variants in Sydney and Melbourne supermarkets are responding with dual-column labeling and third-party protein verification to maintain health-aisle placement.
Convenience-store buyers in Japan are consolidating chilled dip procurement through centralized category management at Seven & i Holdings and Lawson headquarters, displacing fragmented regional distributor relationships. This buyer concentration compresses supplier negotiation cycles from quarterly to annual frameworks and prioritizes manufacturers with national replenishment capabilities. Tokyo and Osaka metropolitan areas exhibit the most visible procurement centralization, with single-serve formats capturing disproportionate shelf allocation.
Asia-Pacific Hummus Market Segmentation
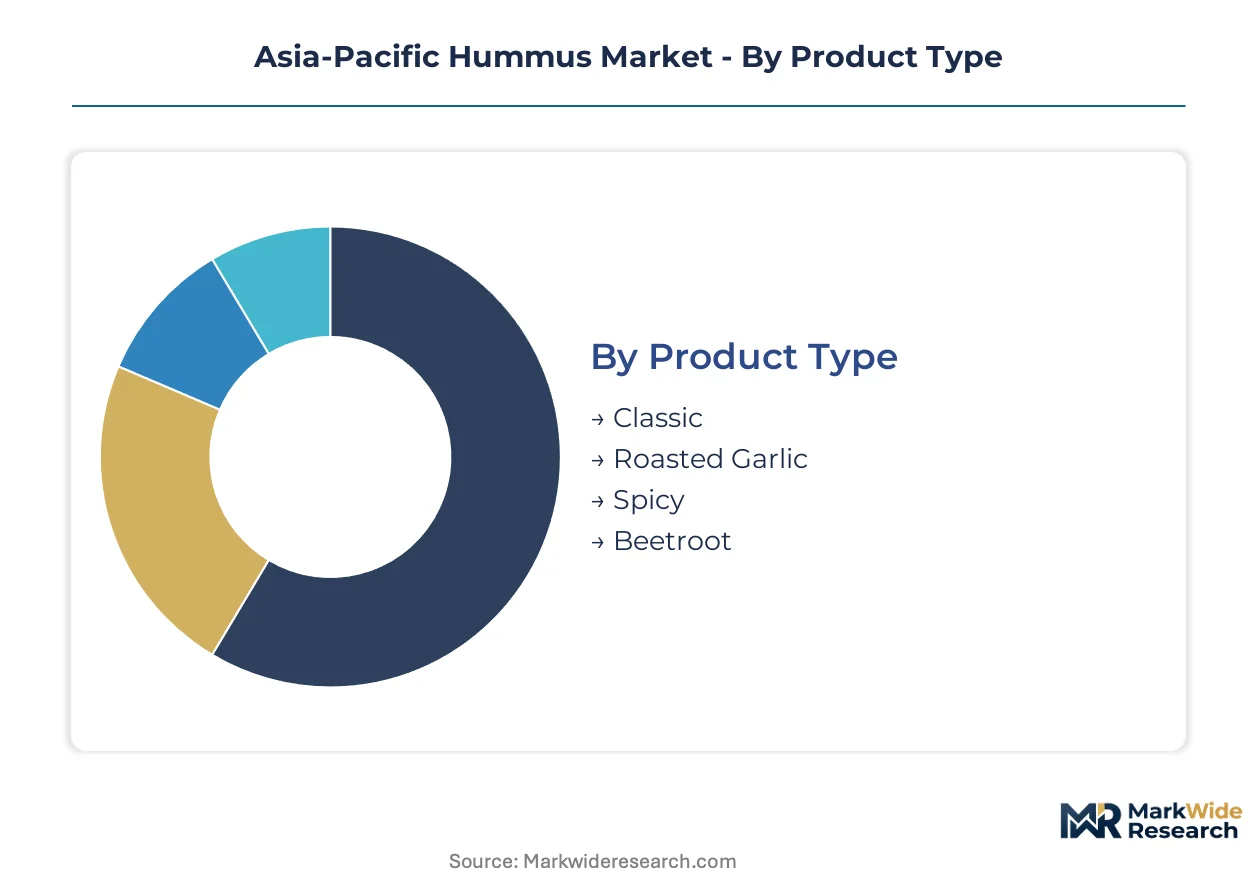
Segmentation in the Asia-Pacific hummus market reveals how cold-chain infrastructure, retail format evolution, and consumption occasion fragmentation create distinct competitive arenas. Each dimension shapes formulation priorities, packaging investments, and channel-specific margin structures differently.
Product Type:
Flavor positioning stratifies across cost tiers, with heritage formulations anchoring volume and innovation variants capturing premium shelf placement.
- Classic:The foundational chickpea-tahini emulsion with olive oil, lemon, and garlic commands baseline volume across Australian supermarkets. Sydney and Melbourne households purchase this variant for everyday meal accompaniment, though thin margins pressure manufacturers to optimize tahini input ratios.
- Roasted Garlic:A caramelized allium infusion that broadens appeal among Australian flexitarians seeking depth without heat. Coles and Woolworths banners allocate expanded chilled dip sections to this profile, recognizing its protein-positioning compatibility.
- Spicy:Chili-forward formulations gain traction in Japanese convenience retail through 7-Eleven and Lawson single-serve programs.
- Beetroot:Vegetable-infused variants with vivid color differentiation command premium positioning in Tokyo and Osaka supermarkets.
Classic commands the established base. The steepest expansion runs through Beetroot.
Distribution Channel:
Application context determines cold-chain intensity, with direct-to-consumer formats requiring shorter logistics radii than institutional supply.
- Supermarkets:Coles, Woolworths, and Japan's AEON banners dominate volume through dedicated chilled dip sections. Australian retailers are expanding shelf space for plant-based protein seekers, compressing procurement cycles to quarterly frameworks.
- Food Service:Hotel breakfast and QSR side-dish adoption in Singapore and South Korea drives institutional format demand. This channel exhibits structural momentum as operators add hummus to menus without dedicated kitchen preparation.
- Online Retail:Direct-to-door refrigerated delivery remains concentrated in Sydney and Melbourne metro zones.
- Convenience Stores:Seven & i Holdings and Lawson headquarters consolidate chilled dip procurement through centralized category management in Tokyo and Osaka.
Supermarkets anchor current throughput. Food Service is climbing the fastest.
Packaging Type:
Volume and consumption occasion dictate material selection, with single-serve formats gaining share against traditional family-size containers.
- Tubs:Polypropylene containers with resealable lids dominate Australian household pantry stocking. Brisbane and Perth manufacturers face intercity transport premiums when supplying these formats nationally.
- Snack Packs:Individual portions with companion crackers or vegetables capture Japanese convenience retail allocation. Tokyo metropolitan buyers prioritize manufacturers with national replenishment capabilities for this format.
- Pouches:Flexible film packaging reduces refrigerated freight weight for online retail channels.
- Glass Jars:Premium positioning vehicles in Australian health-food independents and Japanese organic specialty stores.
Tubs maintain the volume foundation. Snack Packs show the steepest trajectory.
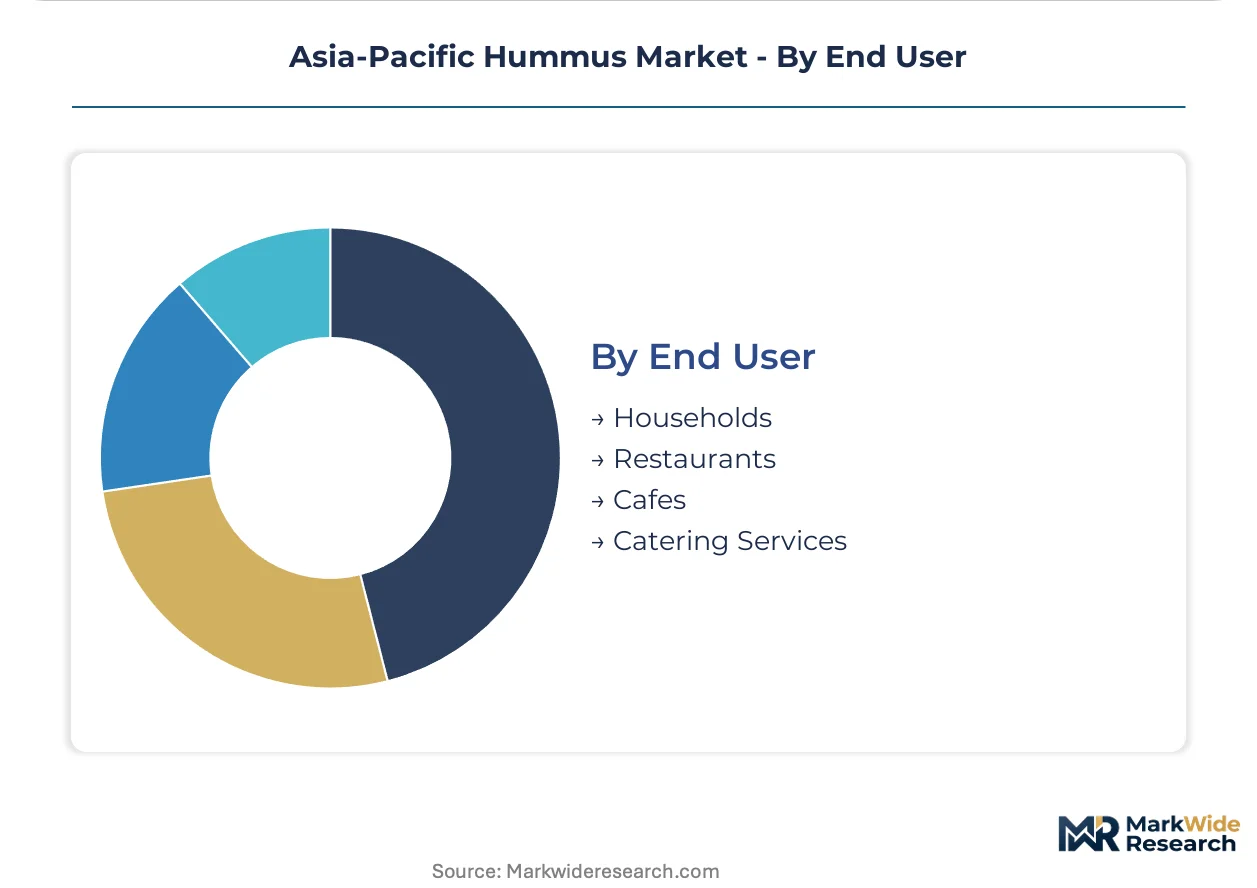
End User:
Customer type segmentation reveals divergent quality thresholds and purchase frequency patterns across consumption contexts.
- Households:Australian families in Sydney and Melbourne drive repeat purchase through weekly supermarket routines. FSANZ labeling standards shape protein claim substantiation for this price-sensitive segment.
- Restaurants:Singapore hotel chains and South Korean QSR operators specify hummus for breakfast and side-dish applications without in-house chickpea preparation.
- Cafes:Melbourne and Sydney specialty coffee shops incorporate hummus into brunch menus as plant-based protein accompaniment.
- Catering Services:Institutional event suppliers in Australian capital cities require extended refrigerated stability for off-site service.
Households represent the core revenue pool. Restaurants are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Australia's southeastern corridor, with cold-chain infrastructure expansion redistributing production toward secondary metros. Refrigerated logistics networks anchor supply radii across Japan's convenience retail sector and India's emerging import channels.
Australia
Coles and Woolworths banners drive chilled dip section expansion for protein-seeking flexitarians in Sydney and Melbourne. FSANZ labeling standards mandate amino acid profile disclosure for plant-protein health claims. Brisbane and Perth manufacturers absorb intercity transport premiums as production scales beyond traditional southeastern hubs.
Japan
Seven & i Holdings and Lawson headquarters consolidate chilled dip procurement through centralized category management in Tokyo and Osaka. JAS organic certification requirements impose 12-18 month approval timelines that filter mid-scale entrants from premium positioning. Single-serve snacking formats capture disproportionate shelf allocation in metropolitan convenience retail.
India
FSSAI import clearance protocols tighten ingredient disclosure requirements for imported spreads, accelerating domestic formulation standardization. Urban convenience retail channels remain underdeveloped relative to Australian and Japanese benchmarks. Mumbai and Delhi distribution corridors concentrate cold-chain investment for refrigerated hummus commercialization.
South Korea
Hotel breakfast and QSR side-dish menu adoption remains underpenetrated relative to Singapore, creating first-mover positioning for chilled dip distributors. MFDS food safety frameworks shape import channel compliance costs. Seoul metropolitan area concentrates foodservice procurement relationships for institutional format demand.
Singapore
Hotel chains and QSR operators add hummus to breakfast and side-dish menus without dedicated kitchen preparation, driving institutional format demand. The city-state's import-dependent supply structure prioritizes regional manufacturing partnerships over domestic production. Foodservice distribution channels exhibit structural momentum as operators seek operational simplicity.
Asia-Pacific Hummus Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in formulation and cold-chain logistics. The market structure fragments across multinational refrigerated food conglomerates, regional Mediterranean specialists, and private-label co-manufacturing facilities. Three archetypes dominate: refrigerated logistics platform operators, localized flavor adaptation specialists, and ready-to-eat salad facility co-producers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players extend manufacturing footprints beyond traditional urban clusters.
Among US-based refrigerated food conglomerates, Sabra Dipping Company and Hormel Foods Corporation exemplify platform integrators leveraging established cold-chain networks. Strauss Group Ltd, an Israel-based food and beverage company, occupies a position within the localized flavor adaptation archetype. Bakkavor Group plc, a UK-based food manufacturer, represents the co-manufacturing convergence model through ready-to-eat salad and dip production facilities.
| Leading Market Players |
|---|
| Sabra Dipping Company, LLC |
| Cedar's Mediterranean Foods, Inc. |
| Haliburton International Foods, Inc. |
| Bakkavor Group plc |
| Hope Foods, LLC |
| Strauss Group Ltd |
| Lantana Foods |
| Hormel Foods Corporation |
| Nestlé S.A. |
| Others |
Value Chain & Pricing Dynamics
Tahini input cost volatility tied to Ethiopian and Sudanese sesame seed harvest variability determines both pricing tier spreads and supply chain shape across the Asia-Pacific hummus market, compressing margins for emulsion-dependent producers while forcing geographic diversification of chickpea sourcing.
Pricing Analysis
FSANZ labeling standards dictate the pricing tier structure across Australian retail channels. Three-tier pricing separates premium-positioned beetroot and spicy variants from standard classic formulations and economy private-label lines. Price differentiation rests on JAS organic certification status and protein content verification thresholds. Cost compression in the standard tier is intensifying because tahini ratio adjustments for amino acid profile disclosure alter emulsion stability. Household consumers in Sydney and Melbourne exhibit the highest price sensitivity, while Japanese convenience retail buyers prioritize national replenishment capabilities over per-unit cost.
Supply Chain Analysis
Export-control friction on food-grade packaging materials and cold-chain equipment limits flow efficiency across regional production networks. Manufacturing capacity clusters in Australia, with secondary nodes emerging in Brisbane and Perth as domestic production scales beyond Sydney and Melbourne. Raw material dependencies center on Ethiopian and Sudanese sesame seeds for tahini, Australian and Indian chickpeas, and olive oil from Mediterranean suppliers. Single-source vulnerability in sesame seed procurement creates margin instability during harvest disruptions. Distribution runs through refrigerated logistics networks anchored by Coles and Woolworths banners in Australia and Seven & i Holdings centralized procurement in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from ambient-stable dip alternatives and private-label co-manufacturing convergence that erodes branded shelf space allocation.
For Market Incumbents: Insulate market position by securing captive tahini supply through backward integration into sesame seed processing or long-term offtake agreements with Ethiopian suppliers. Expand HPP-equipped manufacturing capacity in Brisbane and Perth to absorb intercity transport premiums and extend national distribution radii. Channel control through direct category management relationships with Lawson and Seven & i Holdings headquarters protects shelf allocation against private-label encroachment.
For New Entrants and Emerging Players: Build out co-manufacturing partnerships with ready-to-eat salad facilities in Australia and New Zealand to achieve production scale without dedicated capital expenditure. South Korean foodservice white space offers the most penetrable geography, with hotel breakfast and QSR side-dish adoption remaining underdeveloped relative to Singapore. A protein-fortified variant launch targeting FSANZ health claims verification provides differentiated positioning against incumbent classic formulations.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors refrigerated logistics platform operators with established cold-chain networks. Long-term viability hinges on multi-jurisdiction label management capabilities and HACCP-accredited facility footprints across Australian states. Acquisition targets should demonstrate centralized category management relationships with Japanese convenience retail headquarters. The signal to monitor is procurement consolidation velocity at Seven & i Holdings and Lawson, as annual framework adoption filters mid-scale entrants from premium positioning attempts.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Adoption | HPP systems at Coles and Woolworths suppliers achieve 60-90 day refrigerated extension without preservatives. |
| Co-Manufacturing Convergence | Ready-to-eat salad facilities in Australia and New Zealand lower barrier thresholds for private-label entrants. |
| Centralized Procurement Alignment | Annual framework agreements with Seven & i Holdings and Lawson prioritize national replenishment capabilities. |
| Protein Content Verification Investment | Third-party protein verification maintains health-aisle placement under tightening FSANZ substantiation requirements. |
| Cold-Chain Infrastructure Expansion | Brisbane and Perth manufacturing capacity absorbs intercity transport premiums as production scales beyond southeastern hubs. |
Study Parameters
A standing panel of category buyers at Coles and Woolworths, cold-chain logistics directors, FSSAI compliance consultants, and foodservice procurement managers at Singapore hotel chains provided ongoing calibration. Primary interviews with these stakeholders combined with secondary validation from FSANZ labeling guidance documents, FSSAI import clearance protocols, JAS organic certification standards, and refrigerated freight customs records. Bottom-up production capacity estimates and top-down retail audit data triangulated volume figures across the analysis window.
Scenario-bracketing framed projections across conservative, baseline, and expansion cases. The analytical framework modeled flavor variant, distribution channel, packaging format, and end-user segmentation dimensions throughout the forecast period. CAGRs derived from production capacity buildout timelines, cold-chain infrastructure investment trajectories, and convenience retail shelf space expansion rates. Forecast inputs incorporated tahini price volatility indices and JAS certification approval timelines.
Stress conditions across sesame seed harvest variability, FSSAI labeling harmonization velocity, and Japanese convenience retail procurement consolidation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about refrigerated logistics network expansion and plant-protein health claims regulatory evolution. Material shifts in Ethiopian sesame seed export policy or FSANZ amino acid profile disclosure requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Global Guilt-Free Desserts Market
Specialty Foods
Middle East and Africa Hummus Market
Specialty Foods
Kelp Noodles Market
Specialty Foods
Tahini Market
Specialty Foods
Low Calorie Oatmeal Market
Specialty Foods
United States Tofu Market
Specialty Foods
Dog Food Toppers Market
Specialty Foods
Silver Food Market
Specialty Foods
Maple Syrup Market
Specialty Foods
Thai Cuisine Market
Specialty Foods
Low Fat and Low Carb Foods Market
Specialty Foods
Personalized Meals Market
Specialty Foods
Guacamole Market
Specialty Foods
Keto Low-Calorie Meals Market
Specialty Foods
Dong Quai Market
Specialty Foods
Vegan Dressing Market