
 Global Microcontroller Embedded Systems Market | 2026-2036
Global Microcontroller Embedded Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microcontroller Embedded Systems Market Intelligence
The ISO 26262 functional safety standard for road vehicles is rotating supplier qualification criteria, particularly for automotive applications. Renesas Electronics specializes in providing MCU solutions that meet these stringent automotive safety integrity levels. NXP Semiconductors dominates the secure connectivity and automotive processing space, while Texas Instruments leverages its broad analog and embedded processing portfolio to compete effectively.
A microcontroller embedded system is a computer system combining a processor, memory, and input/output peripherals on a single chip or board. These systems are designed for specific, real-time control functions within a larger mechanical or electrical system. The 32-bit microcontroller segment leads new design wins, displacing older 8-bit and 16-bit architectures in complex applications. Automotive OEMs and industrial automation providers constitute high-value end-user segments due to their performance and reliability demands.
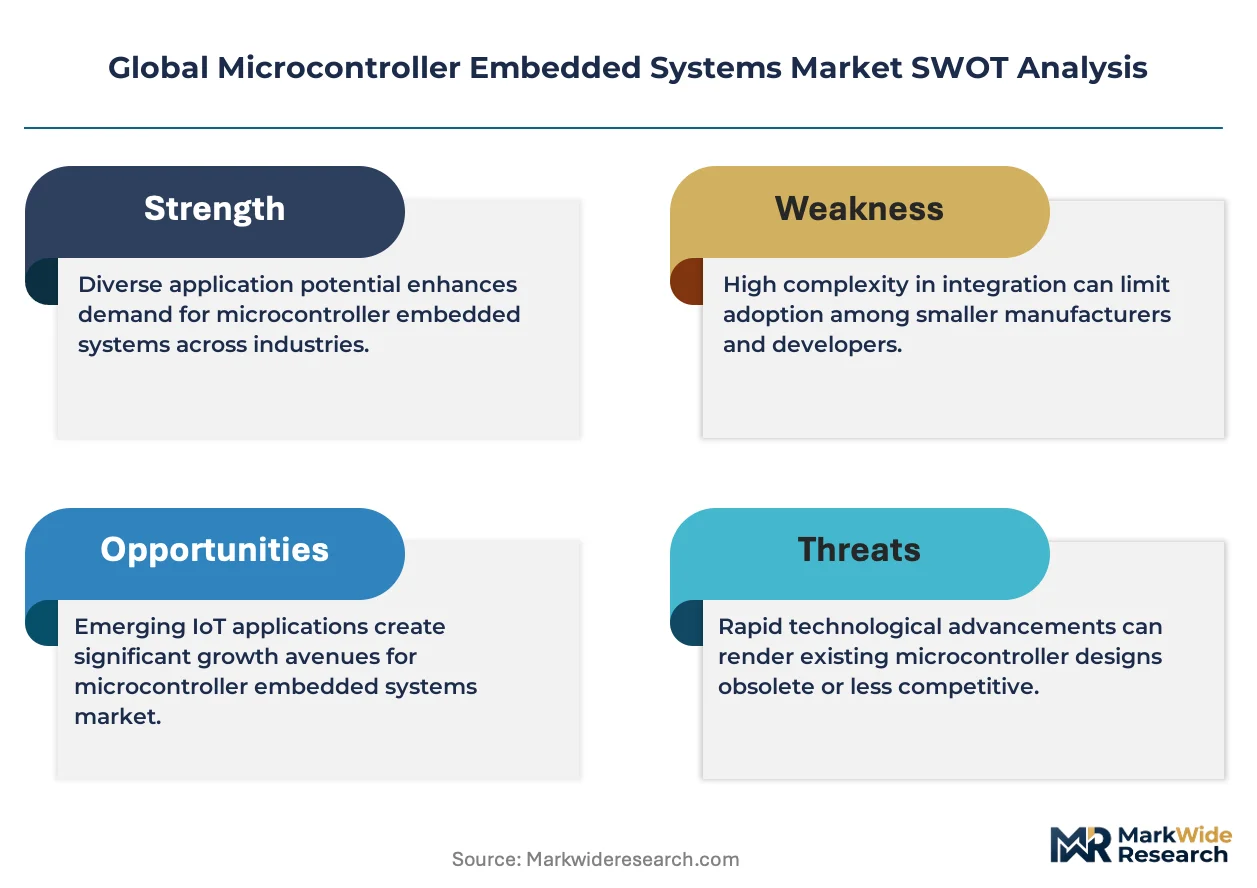
Compliance frameworks like the EU's Radio Equipment Directive and the US FDA's premarket certification for medical devices govern market access. In parallel, China's GB standards for consumer electronics mandate specific safety and interoperability protocols for embedded systems. The central strategic decision for developers and manufacturers now revolves around committing to either the licensed ARM Cortex ecosystem or the open-standard RISC-V architecture.
Market Dynamics
The central strategic decision for developers now revolves around committing to either the licensed ARM Cortex ecosystem or the open-standard RISC-V architecture. This fundamental bifurcation influences everything from talent acquisition and toolchain investment to long-term product roadmaps and supply chain security.
Growth Catalysts
- Automotive Safety Standards:The ISO 26262 functional safety standard for road vehicles mandates stringent qualification for MCUs used in ADAS and powertrain control, creating a premium-demand segment for compliant hardware.
- China's Industrial Policy:National investment in industrial automation, smart grid infrastructure, and smart city projects within China creates concentrated, high-volume demand for 32-bit MCUs capable of handling complex control and connectivity tasks.
- RISC-V Adoption:The open-source RISC-V instruction set architecture lowers the barrier to entry for custom silicon design, enabling a new wave of application-specific processors for IoT and edge computing devices without ARM licensing fees.
Market Restraints
- Semiconductor Fabrication Concentration:The reliance on a few advanced semiconductor foundries, primarily located in Taiwan and South Korea, creates significant geopolitical and supply chain vulnerabilities for the entire MCU ecosystem.
- Legacy System Inertia:The high cost and complexity of redesigning and re-validating embedded systems, particularly in industrial and medical sectors, slows the replacement cycle for older 8-bit and 16-bit architectures.
- Regulatory Compliance Overhead:Navigating disparate international standards, such as the EU's Radio Equipment Directive and China's GB standards for electronics, increases design costs and time-to-market for globally distributed products.
Strategic Opportunities
- Edge AI Acceleration:Integrating dedicated neural processing units (NPUs) into MCU designs opens new applications in on-device machine learning for predictive maintenance, voice recognition, and computer vision without cloud dependency.
- Medical Wearables and Portables:The demand for low-power, high-reliability MCUs in FDA-regulated medical devices, including continuous glucose monitors and portable diagnostic tools, represents a high-margin growth vector.
- Automotive Domain Controllers:The architectural shift in vehicles from dozens of small MCUs to centralized domain controllers creates an opportunity for powerful, multi-core 32-bit and 64-bit MCUs that manage entire vehicle functions.
Industry Challenges
- Embedded Security Expertise Gap:A shortage of engineers skilled in secure firmware development, cryptographic implementation, and threat modeling for connected devices poses a significant operational risk for manufacturers.
- Ecosystem Fragmentation:The proliferation of development tools, real-time operating systems, and software libraries for both ARM and RISC-V creates integration complexity and challenges for developers aiming for code portability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microcontroller Embedded Systems Market |
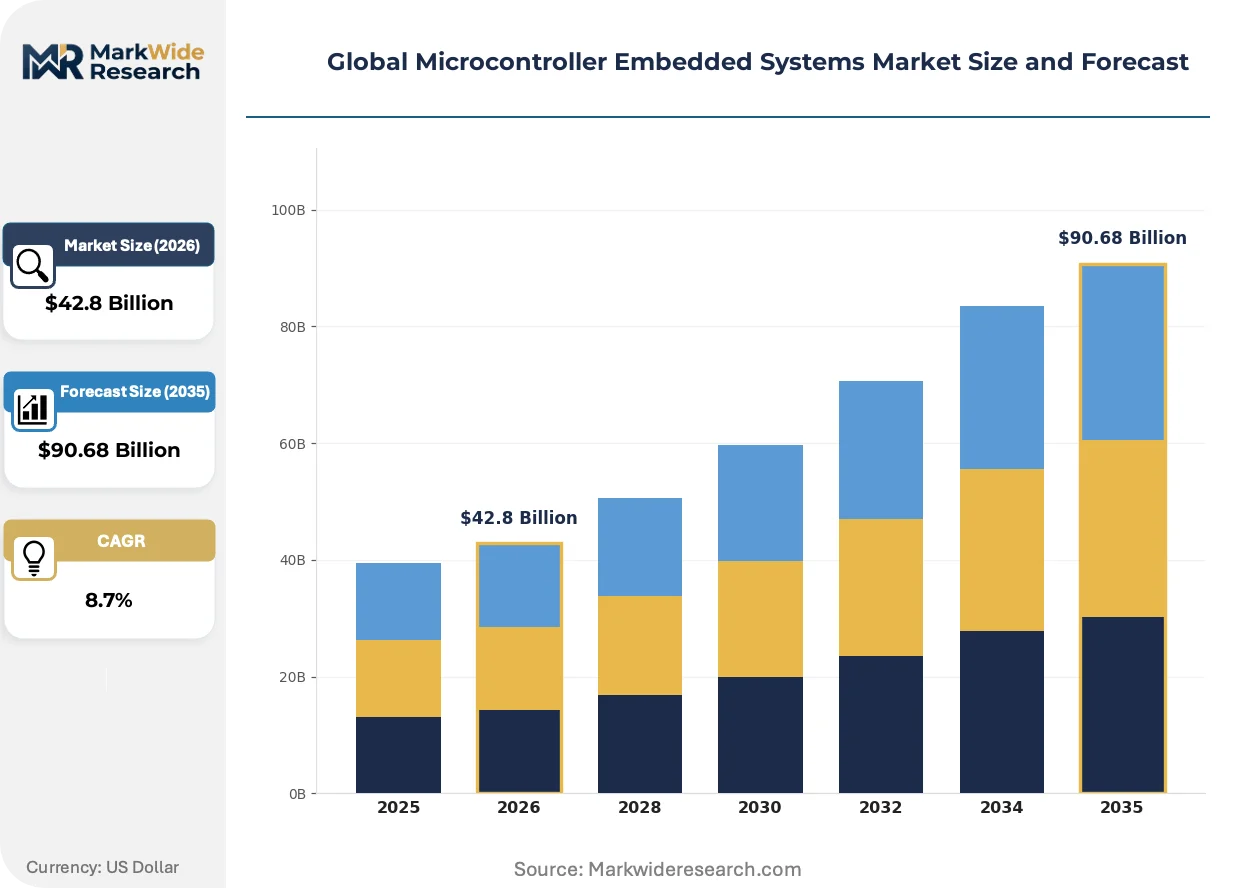
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $90.68 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 8-bit Microcontrollers, 16-bit Microcontrollers, 32-bit Microcontrollers, ARM Cortex, RISC-V Application: Consumer Electronics, Robotics, Industrial Automation, Smart Metering, Wearable Devices End User: Automotive OEMs, Aerospace & Defense, Home Automation Providers, Telecommunications, Smart Agriculture Deployment: Standalone Systems, Distributed Control Systems, Real-Time Embedded, Networked Embedded, Cloud-Connected Devices |
| Companies Covered | Renesas Electronics, Texas Instruments, STMicroelectronics, ON Semiconductor, Analog Devices, NXP Semiconductors, Microchip Technology, Toshiba, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microcontroller Embedded Systems Market Strategic Shifts & Innovations
Technological advancement is defined by a move toward specialized, application-specific silicon. This shift prioritizes power efficiency and performance for targeted workloads over the general-purpose nature of legacy microcontrollers, driven by the demands of edge computing and connected devices.
Heterogeneous integration, combining multiple specialized dies or chiplets in a single package, is a defining product evolution. Automotive and data center clients are the primary adopters of this approach to achieve higher performance. The traditional, monolithic System-on-Chip design is decomposing into a set of optimized, function-specific processing blocks for tasks like AI, security, and connectivity.
Compliance with new cybersecurity mandates is a critical development focus. The EU's Cyber Resilience Act imposes strict "secure-by-design" obligations, including vulnerability management and software bill of materials (SBOM) reporting. This directly impacts the entire embedded systems value chain, forcing MCU providers and OEMS to overhaul their software development and lifecycle support processes.
A notable behavioral change is the shift in design philosophy from using a single, powerful MCU to employing multiple, distributed, and specialized microcontrollers. This disrupts the winner-take-all model in design wins, favoring suppliers with a broad portfolio of application-tuned devices. This pattern is most pronounced in complex systems like electric vehicles and industrial robotics, where functional decomposition improves resilience and simplifies development.
Global Microcontroller Embedded Systems Market Segmentation
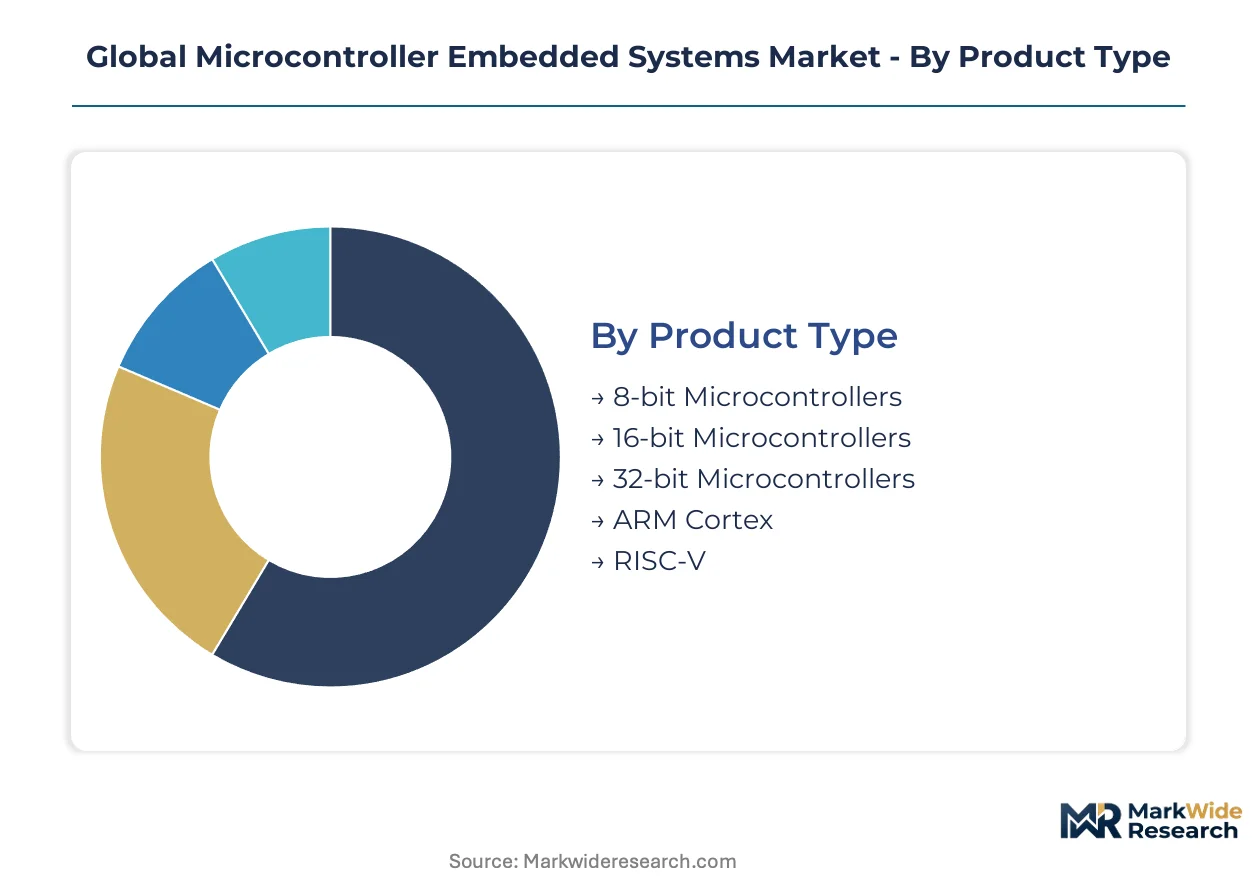
The Microcontroller Embedded Systems Market exhibits distinct characteristics across various dimensions, reflecting diverse technological requirements and end-user demands. Understanding these segmentation nuances is critical for manufacturers to align product development with specific market needs. This granular view enables strategic resource allocation and targeted market penetration.
Product Type:
The distribution channels for microcontroller product types vary significantly, with some architectures favoring direct OEM integration while others leverage broader ecosystem partnerships.
- 32-bit Microcontrollers:These processors feature a 32-bit data bus and arithmetic logic unit, offering high computational power. Demand concentrates in automotive OEMs for ADAS and industrial automation.
- ARM Cortex:This licensed instruction set architecture provides a mature ecosystem of development tools, widely adopted across diverse embedded applications. Support drives adoption in consumer electronics and medical devices.
- 8-bit Microcontrollers:Basic processors handle simple control tasks with minimal power, used in cost-sensitive applications.
- 16-bit Microcontrollers:Balance cost and performance, serving mid-range applications requiring more processing than 8-bit devices.
- RISC-V:Open-standard instruction set enables custom silicon design without licensing fees, fostering innovation in IoT and edge computing.
By volume, 32-bit Microcontrollers lead. By growth pace, RISC-V is ahead.
Application:
Cost-performance requirements for microcontroller embedded systems vary across application sectors, influencing component selection and design complexity.
- Industrial Automation:MCUs manage complex machinery, process control, and factory robotics, demanding high reliability and real-time processing. Requires durable 32-bit MCUs for precision control in manufacturing plants.
- Consumer Electronics:This segment includes smartphones and smart home appliances, requiring power-efficient MCUs with integrated connectivity. High volume and rapid refresh cycles drive demand for cost-optimized microcontrollers.
- Robotics:Microcontrollers facilitate motor control, sensor integration, and navigation for industrial and service robots.
- Smart Metering:MCUs enable data collection, communication, and processing in utility meters for electricity, gas, and water.
- Wearable Devices:Require ultra-low power MCUs with compact footprints and integrated wireless communication for health monitoring.
Industrial Automation applications command the highest average selling prices, while Wearable Devices demonstrate the steepest expansion trajectory.
End User:
End-user segments drive demand for microcontroller embedded systems at varying scales, from high-volume consumer markets to specialized industrial applications.
- Automotive OEMs:Manufacturers integrate MCUs into vehicle systems like engine control and ADAS, demanding ISO 26262 compliance. Shift to EVs and autonomous driving increases required MCU complexity and quantity.
- Home Automation Providers:Deploy MCUs in smart thermostats, lighting, and security devices for residential control. These providers require cost-effective, low-power MCUs with robust wireless connectivity.
- Aerospace & Defense:Utilizes highly reliable, often radiation-hardened, MCUs for avionics, satellite systems, and military equipment.
- Telecommunications:MCUs manage network infrastructure components, base stations, and communication devices for data routing.
- Smart Agriculture:Employs MCUs in precision farming equipment, environmental sensors, and automated irrigation for optimized crop management.
Automotive OEMs represent the largest value segment. Smart Agriculture is experiencing the fastest adoption.
Deployment:
The maturity of deployment models for microcontroller embedded systems ranges from established, independent operations to nascent, highly integrated cloud-dependent architectures.
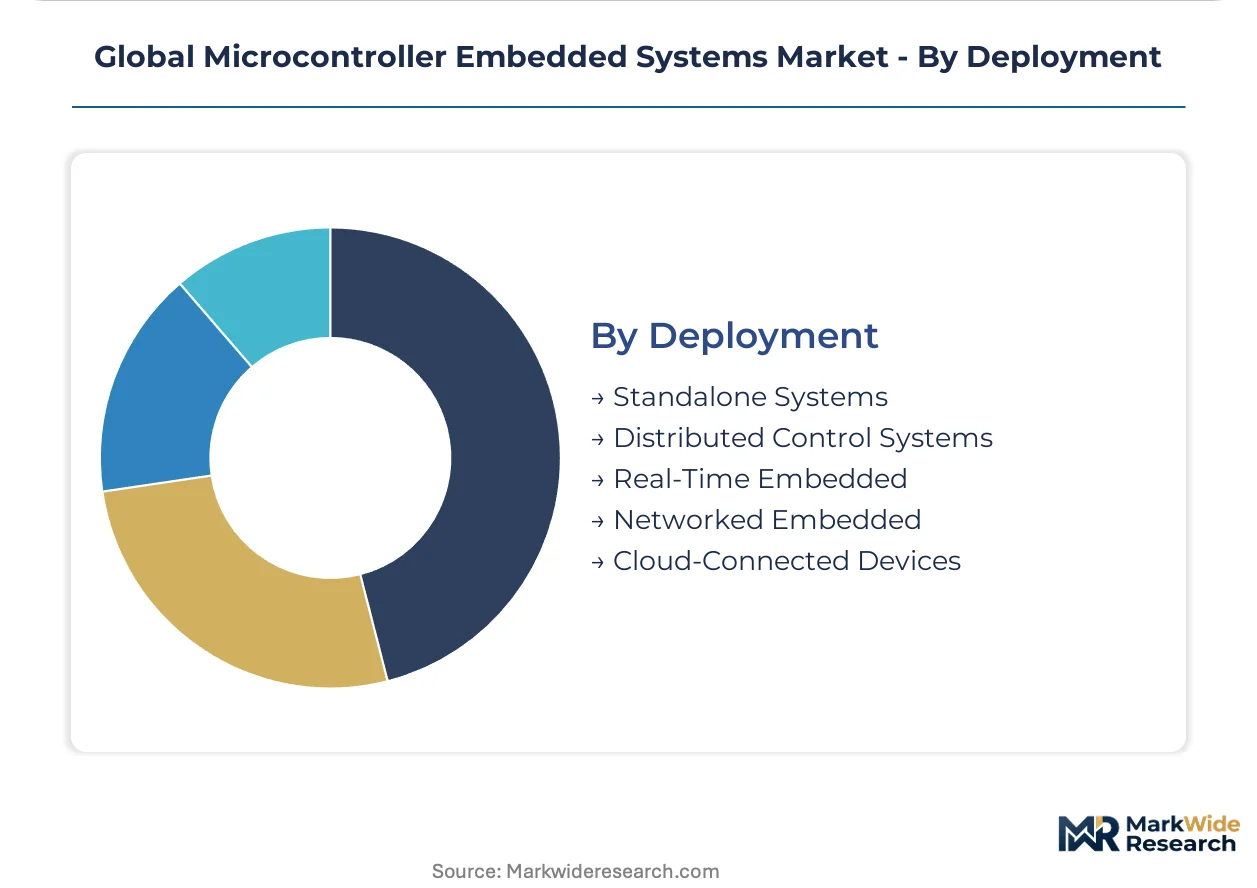
- Cloud-Connected Devices:Integrate MCUs with wireless modules to send and receive data from cloud platforms, enabling remote monitoring and analytics. Critical for IoT applications, driving demand for secure and scalable connectivity.
- Networked Embedded:MCUs communicate over local networks, facilitating coordinated operations and data exchange within a localized environment. Prevalent in industrial automation and building management for efficiency.
- Standalone Systems:Operate independently without external connectivity, performing dedicated functions within a single device.
- Distributed Control Systems:MCUs form part of a larger network managing complex industrial processes across multiple physical locations.
- Real-Time Embedded:Prioritize deterministic timing and low latency, ensuring critical operations execute within strict deadlines for safety-critical applications.
Cloud-Connected Devices exhibit the highest innovation velocity. Standalone Systems maintain a significant installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration significantly influences regional demand for microcontroller embedded systems. Automotive OEMs and industrial automation providers in developed economies drive high-value segments, while emerging markets like China exhibit concentrated, high-volume demand due to national industrial policies. Regulatory frameworks and local technological ecosystems further shape market dynamics across key regions.
United States
Demand for advanced MCUs stems from the automotive sector for ADAS and the medical device industry for portable diagnostics. The US FDA's premarket certification ensures high-reliability standards for medical embedded systems. Silicon Valley and Boston serve as key innovation hubs, fostering research and development in edge AI and specialized silicon design.
China
Industrial automation and smart city projects generate substantial demand for 32-bit MCUs capable of complex control and connectivity. China's GB standards for consumer electronics mandate specific safety and interoperability protocols for embedded systems. The Yangtze River Delta region, including Shanghai, is a major manufacturing and R&D cluster for embedded systems.
Germany
Automotive OEMs and industrial machinery manufacturers drive significant demand for ISO 26262 compliant MCUs. The KBA (Kraftfahrt-Bundesamt) oversees vehicle safety standards, impacting MCU qualification. Bavaria and Baden-Württemberg host major automotive and industrial automation companies, concentrating engineering expertise and production facilities.
Japan
Automotive electronics and robotics applications fuel the need for high-performance and reliable microcontroller solutions. METI (Ministry of Economy, Trade and Industry) promotes technological innovation and standardization in industrial sectors. The Tokyo metropolitan area and Kansai region are centers for advanced electronics manufacturing and embedded software development.
South Korea
Consumer electronics, particularly smart home appliances and mobile devices, along with automotive components, generate strong demand for power-efficient MCUs. The Korean Agency for Technology and Standards (KATS) establishes technical regulations and certification processes. The Seoul Capital Area is a hub for semiconductor design, manufacturing, and consumer electronics production.
Global Microcontroller Embedded Systems Market Key Industry Players
Player mix skews toward established semiconductor giants with extensive portfolios, alongside specialized embedded systems providers. The market exhibits a tiered structure, with a few dominant players commanding significant market share in high-value segments like automotive and industrial. Strategic partnerships for ecosystem development and continuous portfolio diversification are dominant competitive moves.
On the premium-tier vector, Renesas Electronics and NXP Semiconductors exemplify leaders in automotive-grade and secure connectivity MCUs, respectively. Texas Instruments, with its broad analog and embedded processing portfolio, occupies a strong position across various industrial and consumer applications. These companies leverage their deep intellectual property and established customer relationships to maintain their market presence.
| Leading Market Players |
|---|
| Renesas Electronics |
| Texas Instruments |
| STMicroelectronics |
| ON Semiconductor |
| Analog Devices |
| NXP Semiconductors |
| Microchip Technology |
| Toshiba |
| Infineon Technologies |
| Others |
Cost & Logistics Intelligence
Extended lead times for specialized 32-bit microcontrollers, particularly from advanced foundries, directly influence supply chain resilience and empower suppliers to maintain pricing stability for high-demand automotive and industrial segments. This concentration of manufacturing capability shapes overall market dynamics.
Pricing Analysis
Cost-plus contract models with silicon wafer indexation define pricing for high-volume microcontroller embedded systems. Price differentiation stems from ISO 26262 functional safety certification levels and the degree of software customization required. Pricing softness stems from intense competition in the general-purpose 8-bit and 16-bit microcontroller segments, particularly for consumer electronics applications. Consumer electronics buyers exhibit high price sensitivity, while automotive OEMs prioritize reliability and certification over marginal cost savings.
Supply Chain Analysis
Strategic stockpiling, rather than just-in-time delivery, characterizes the supply chain for critical microcontroller components, especially for automotive clients. Geographic supply concentration centers on Taiwan, South Korea, and China for advanced semiconductor fabrication. Key raw material dependencies include high-purity silicon wafers and specialized packaging substrates. Geopolitical instability and trade restrictions represent a significant structural risk for the entire ecosystem. Distribution runs primarily through direct OEM integration for high-value segments and specialized electronics distributors for broader market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The microcontroller embedded systems market faces a significant capability gap in embedded security expertise, necessitating strategic interventions across the value chain. This scarcity impacts product development cycles and market access.
For Market Incumbents:Compound existing intellectual property by investing heavily in RISC-V based core development and associated security IP. Acquire specialized software firms to address the embedded security expertise gap, mitigating the threat of new entrants offering secure-by-design solutions. Reinforce customer relationships through enhanced technical support and long-term supply agreements for compliant automotive-grade MCUs. Expand capacity for advanced packaging in diverse geographies to reduce single-source vulnerability.
For New Entrants and Emerging Players:Anchor in niche applications requiring open-standard flexibility and low power, such as medical wearables and smart agriculture devices. The IoT edge computing segment, particularly for custom silicon designs, represents a penetrable white space. Focus go-to-market strategies on providing comprehensive RISC-V toolchains and software development kits to lower barriers for application-specific integrated circuit adoption. Target China's industrial automation sector with cost-effective, high-performance 32-bit MCU alternatives.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upward across the advanced microcontroller manufacturing segment as foundries invest in next-generation process nodes. Long-term viability hinges on identifying firms with robust IP portfolios in Edge AI acceleration and secure embedded processing. Acquisition targets should include specialized design houses focusing on RISC-V architectures or companies with proven track records in functional safety certifications. The signal to watch is the acceleration of RISC-V design wins in high-volume, performance-critical applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in RISC-V Ecosystem Development | Expands market reach by fostering open-source innovation for new application spaces. |
| Acquire Embedded Security Software Firms | Strengthens product offerings to meet stringent cybersecurity mandates like the EU Cyber Resilience Act. |
| Expand Automotive-Grade MCU Production | Secures supply for high-demand ADAS and electric vehicle domain controller markets. |
| Develop Edge AI-Enabled Microcontrollers | Captures new revenue streams from on-device machine learning in industrial and consumer sectors. |
| Diversify Semiconductor Foundry Partnerships | Mitigates geopolitical and supply chain risks associated with concentrated fabrication. |
Research Approach
Initial hypotheses were tested against primary input from automotive OEM engineers, industrial automation procurement leads, and embedded software developers, then refined through iterative analysis. This approach combined qualitative insights from in-depth interviews with quantitative validation from secondary sources. Secondary data included SEC filings of major semiconductor firms, national industrial policy documents from China and Germany, and academic research on RISC-V architecture adoption.
Variance decomposition formed the core of the forecasting framework, disaggregating market growth drivers across the analysis window. Segmentation dimensions modeled included product type, application, end-user, deployment model, and instruction set architecture. Compound annual growth rates were derived using regression analysis and scenario modeling, informed by industry-specific inputs such as ADAS penetration rates and IoT device connectivity growth projections.
Decision-makers should treat outputs as directional under current geopolitical trade assumptions and established technological roadmaps; material deviation would warrant model refresh. Forecasts reflect assumptions concerning the continued adoption of 32-bit MCUs and the increasing influence of open-standard architectures. Revision becomes warranted when significant shifts in global semiconductor manufacturing capacity or new regulatory frameworks emerge.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Voice Controlled Devices Market
Others
Fibert Market
Others
Stand-Up Pouch Valves Market
Others
Linear Shaft Market
Others
Security Bottles Market
Others
Fluorapatite Market
Others
DNA Data Storage Market
Others
Global Electronic Filters Market
Others
Tanned Fish Skin Leather Market
Others
Smart Plug Market
Others
Semiconductor Gas Filters Market
Others
3D Printing Construction Market
Others
Underwater Communication System Market
Others
Basketball Apparel Market
Others
Global Computer Peripherals Market
Others
North America Ultraviolet Disinfection Equipment Market