
 Smart-Connected Power Plug Socket Market | 2026-2036
Smart-Connected Power Plug Socket Market Size, Share, and Industry Trends Forecast 2026-2036
Smart-Connected Power Plug Socket Market Outlook
Wi-Fi 6 and Matter-certified specification tiers are reorganizing how manufacturers compete on interoperability and latency performance. TP-Link Technologies Co. Ltd. leverages its router ecosystem to bundle plug sockets with mesh network infrastructure. Xiaomi Corporation anchors its position through aggressive cost engineering and direct-to-consumer channel control in Asia. Leviton Manufacturing Co., Inc. differentiates via commercial-grade UL listings and contractor relationships in North America.
Smart-connected power plug sockets integrate microcontrollers, relay switches, and RF modules into standard form-factor outlets to enable remote actuation and energy telemetry. Wi-Fi enabled units dominate residential volumes due to router-native compatibility, though Zigbee compatible variants capture margin pools in whole-home automation deployments where mesh stability matters. Energy management applications are expanding fastest as utility time-of-use rate structures incentivize automated load shifting. Commercial end users sustain premium pricing for sockets with sub-metering accuracy and centralized fleet management dashboards.
FCC Part 15 governs unlicensed RF emissions in the United States, while CE marking and the EU's Radio Equipment Directive shape product access across European member states. Ecodesign regulations under the EU Green Deal mandate standby power limits that directly influence chipset selection and firmware sleep-state engineering. Stakeholders must monitor whether emerging national cybersecurity labeling schemes fragment certification requirements or consolidate toward IEC baseline standards.
Market Dynamics
The EU Green Deal's standby power limits and cybersecurity labeling mandates are forcing chipset redesigns and firmware re-engineering across the supplier base. Manufacturers must now balance Matter interoperability certification against national fragmentation in RF emission rules.
Growth Catalysts
- Residential retrofit demand:Homeowners bypass electrical rewiring by installing Wi-Fi enabled units behind existing faceplates, accelerating replacement cycles in aging housing stock.
- Utility time-of-use rate structures:Automated load shifting via socket-level actuation delivers measurable bill reductions, creating pull from energy-conscious households.
- Whole-home automation deployments:Zigbee mesh networks in multi-device installations favor dedicated relay sockets over router-dependent alternatives, sustaining premium pricing tiers.
Market Restraints
- Silicon supply concentration:Microcontroller fabrication depends on concentrated Asian foundry capacity, exposing lead times to geopolitical disruption.
- RF certification fragmentation:FCC Part 15, CE marking under the Radio Equipment Directive, and emerging national cybersecurity labels multiply compliance costs for multi-market launches.
- Latency limitations in Wi-Fi variants:Router congestion degrades real-time responsiveness, constraining adoption in security-critical commercial applications.
Strategic Opportunities
- Sub-metering accuracy standards:Commercial fleets seek socket-level revenue-grade telemetry for ESG reporting and utility demand response programs.
- India's building efficiency codes:The Bureau of Energy Efficiency mandates are creating first-mover advantages for consumption-monitoring hardware in commercial real estate.
- Matter-over-Thread convergence:Low-power mesh protocols combined with unified application-layer standards reduce engineering overhead for cross-platform compatibility.
Industry Challenges
- Firmware security engineering talent:Embedded systems expertise for secure boot and encrypted telemetry transmission remains scarce relative to deployment timelines.
- Legacy electrical infrastructure integration:Contractor-installed sockets in commercial buildings require backward compatibility with 20-year-old panel configurations and load calculations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart-Connected Power Plug Socket Market |
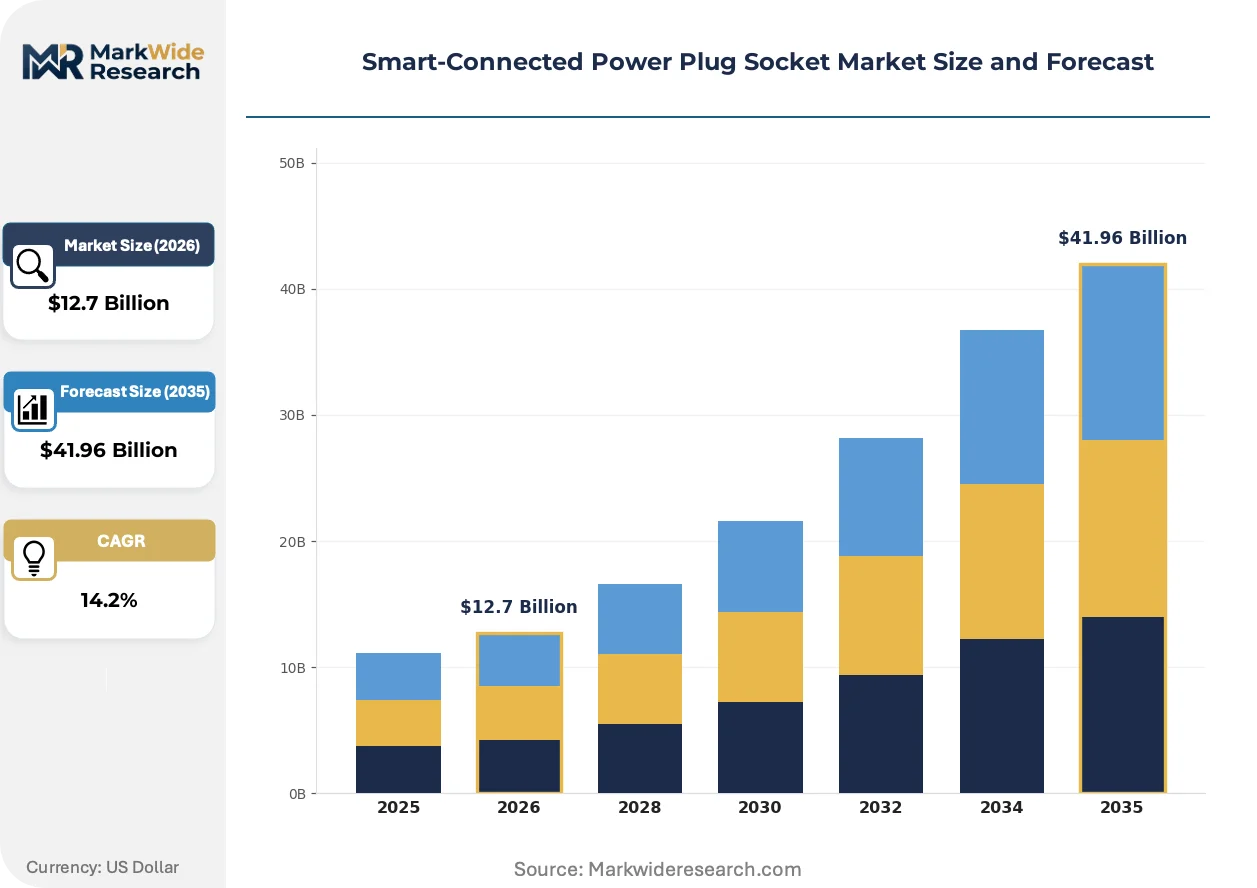
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $41.96 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wi-Fi Enabled, Bluetooth Enabled, Zigbee Compatible, Z-Wave Compatible Application: Home Automation, Energy Management, Remote Monitoring, Smart Appliances End User: Residential, Commercial, Industrial, Hospitality Connectivity: Wireless, Wired, Hybrid, IoT |
| Companies Covered | Panasonic Corporation, TP-Link Technologies Co. Ltd., Xiaomi Corporation, Belkin International, Inc., D-Link Corporation, Leviton Manufacturing Co., Inc., Lenovo Group Limited, SDI Technologies, Inc., EDIMAX Technology Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart-Connected Power Plug Socket Market Strategic Shifts
Interoperability certification and edge-computing capabilities are reorganizing how manufacturers differentiate beyond basic remote actuation. The competitive frontier has shifted toward latency performance and fleet management software depth.
Matter protocol stacks are fragmenting the competitive landscape for proprietary ecosystem lock-in. Smart home platform operators now face pressure to support open interoperability, compressing margins on hardware-tied subscription services. Retail channel buyers increasingly filter assortments by certification tier rather than brand recognition.
The EU's Ecodesign regulations under the Green Deal mandate maximum standby power consumption thresholds, directly influencing relay switch selection and sleep-state firmware architecture. Manufacturers serving European markets must redesign power supply circuits to meet sub-watt requirements. German distributors now require compliance documentation before listing new SKUs.
Commercial procurement teams are unbundling hardware purchases from software dashboards, forcing socket vendors to justify recurring fees through API reliability and data export portability. Facility managers in US multi-site retail chains negotiate socket hardware as commodity while competing on centralized fleet visibility tools. This pattern concentrates purchasing leverage among buyers with internal software development capabilities.
Smart-Connected Power Plug Socket Market Segmentation
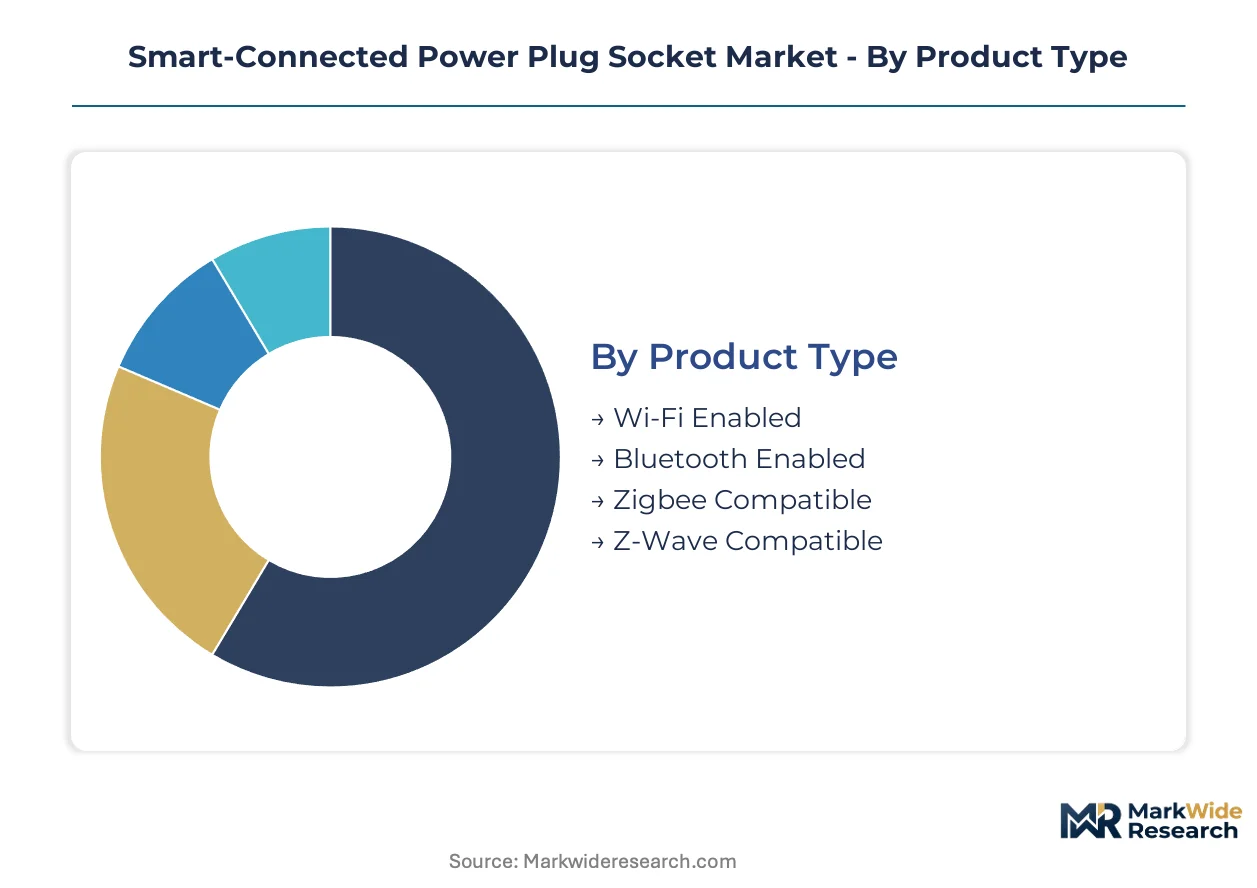
Segmentation reveals how technology choices, use cases, and buyer economics create distinct margin architectures. Manufacturers optimize chipset portfolios and certification investments differently across each slice.
Product Type:
Margin pools concentrate in protocol variants that command whole-home automation premiums versus router-dependent commodity units.
- Wi-Fi Enabled:These units integrate 802.11 b/g/n chipsets for direct router communication without hub infrastructure. Residential retrofit demand in aging German housing stock favors this plug-and-play architecture despite latency sensitivity during peak network congestion.
- Zigbee Compatible:Mesh-native devices using IEEE 802.15.4 standards achieve sub-100ms response times through self-healing node networks. Whole-home deployments in multi-device installations sustain premium pricing tiers where stability outweighs hub complexity.
- Bluetooth Enabled:Low-energy variants target proximity-controlled applications with smartphone-native pairing.
- Z-Wave Compatible:Sub-GHz spectrum operation avoids 2.4GHz interference in dense RF environments.
The dominant share belongs to Wi-Fi Enabled, while Zigbee Compatible is closing the gap fastest.
Application:
Volume distribution tracks where socket-level intelligence delivers measurable operational savings versus convenience features.
- Energy Management:Consumption telemetry with automated load shifting responds to utility time-of-use rate structures. German households under EU Green Deal efficiency mandates demonstrate willingness to pay for sub-metering accuracy that validates bill reductions.
- Home Automation:Scene-based actuation and voice integration drive replacement cycles in residential retrofit markets. Aging electrical infrastructure in North American suburbs favors wireless solutions that bypass rewiring permits.
- Remote Monitoring:Fleet dashboards for multi-site commercial operators require API reliability and data export portability.
- Smart Appliances:OEM-integrated sockets enable appliance-level diagnostics and predictive maintenance alerts.
Energy Management holds the revenue concentration, though Home Automation generates the highest unit volumes.
End User:
Buyer sophistication determines pricing power, with commercial procurement teams unbundling hardware from software subscriptions.
- Residential:Individual homeowners prioritize router compatibility and mobile app experience over technical specifications. German consumers show strongest premium acceptance for Matter-certified units with consumption visualization.
- Commercial:Facility managers in US retail chains negotiate socket hardware as commodity while competing on centralized fleet visibility tools. ESG reporting requirements drive demand for revenue-grade telemetry accuracy.
- Industrial:Harsh-environment ratings and DIN-rail mounting configurations dominate specification sheets.
- Hospitality:Guest room energy management integrates with property management systems for unoccupied load shedding.
Residential captures the volume base, while Commercial commands the steepest expansion trajectory.
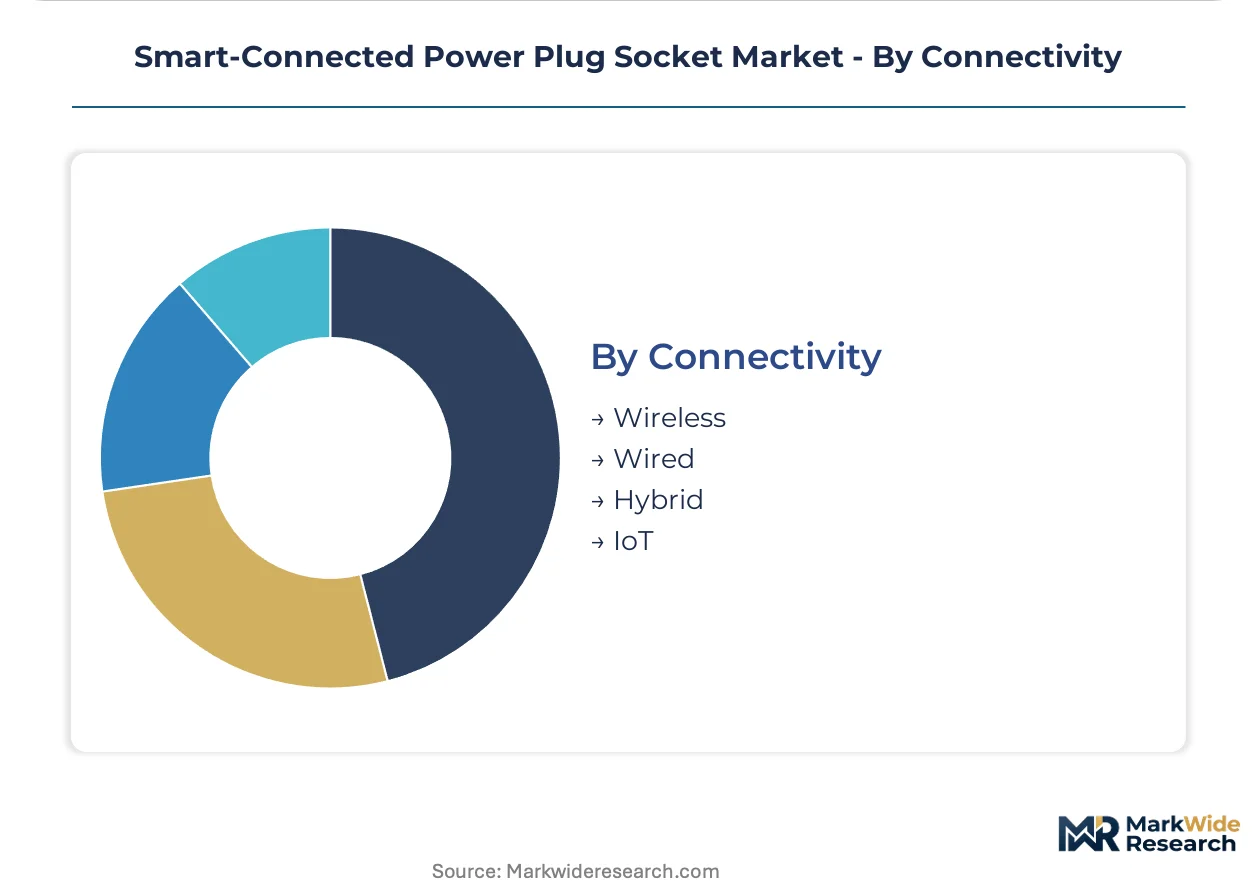
Connectivity:
Engineering trade-offs between power consumption, range, and interoperability define competitive positioning.
- Wireless:RF modules eliminate installation labor but introduce cybersecurity attack surfaces requiring firmware hardening. FCC Part 15 and CE marking under the Radio Equipment Directive multiply compliance costs for multi-market launches.
- Hybrid:Dual-path architectures combine wireless convenience with wired reliability for critical load applications. Matter-over-Thread convergence reduces engineering overhead for cross-platform compatibility in whole-home deployments.
- Wired:Power-over-Ethernet variants serve commercial installations with existing structured cabling infrastructure.
- IoT:Cloud-native architectures enable over-the-air updates and predictive analytics subscriptions.
Wireless maintains installed base dominance, though Hybrid architectures are gaining share fastest among new commercial specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Microcontroller fabrication concentrates in Taiwan and South Korea, exposing socket manufacturers to concentrated foundry capacity. German distributors now require Ecodesign compliance documentation before listing new SKUs. Regulatory divergence across major economies multiplies certification costs for multi-market launches.
United States
Utility time-of-use rate structures in California and Texas drive automated load shifting demand. FCC Part 15 governs unlicensed RF emissions, forcing chipset redesigns for domestic certification. Silicon Valley hardware startups cluster in San Jose, developing edge-computing socket architectures for commercial fleet management.
Germany
Building energy codes and consumer willingness to pay for premium connectivity features concentrate demand. EU Green Deal Ecodesign regulations mandate sub-watt standby power limits, directly influencing relay switch selection. Munich and Stuttgart host engineering teams optimizing Matter-over-Thread firmware for whole-home automation deployments.
China
Cost engineering and direct-to-consumer channel control dominate competitive positioning. MIIT sets domestic RF equipment standards that diverge from FCC and CE frameworks. Shenzhen manufacturing clusters produce Zigbee mesh modules for export markets while serving domestic smart home platform operators.
India
Bureau of Energy Efficiency mandates create first-mover advantages for consumption-monitoring hardware in commercial real estate. BIS certification requirements shape product access timelines for international suppliers. Bengaluru technology corridors attract firmware engineering talent for secure boot and encrypted telemetry development.
Japan
METI efficiency standards and aging residential housing stock accelerate retrofit demand. JIS standards for electrical safety influence socket form-factor specifications. Osaka industrial zones manufacture relay switches optimized for low-power sleep-state architectures required by EU export markets.
Smart-Connected Power Plug Socket Market Competitive Environment
Concentration sits with diversified electronics conglomerates and specialized connectivity vendors. The vendor base spans router ecosystem bundlers, cost-engineered direct-to-consumer brands, and commercial-grade electrical equipment specialists. Three archetypes dominate: network infrastructure bundlers leveraging router ecosystems, vertically integrated hardware-as-a-service platforms, and contractor-channel electrical equipment suppliers. Competitive moves center on Matter interoperability certification races and strategic partnerships with utility demand response programs.
Within the network infrastructure tier, TP-Link Technologies Co. Ltd. and D-Link Corporation exemplify router-native bundling strategies. Xiaomi Corporation anchors the cost-engineered direct-to-consumer archetype through channel control. Leviton Manufacturing Co., Inc. occupies the commercial-grade specialist position with contractor relationships and UL listing authority.
| Leading Market Players |
|---|
| Panasonic Corporation |
| TP-Link Technologies Co. Ltd. |
| Xiaomi Corporation |
| Belkin International, Inc. |
| D-Link Corporation |
| Leviton Manufacturing Co., Inc. |
| Lenovo Group Limited |
| SDI Technologies, Inc. |
| EDIMAX Technology Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Foundry scale economies in Taiwan and South Korea anchor microcontroller unit economics, compressing price floors for Wi-Fi enabled sockets while elevating margins for Zigbee variants that escape commodity trap dynamics. German Ecodesign compliance costs and Matter certification investments stratify pricing tiers by regulatory burden rather than raw component cost alone.
Pricing Analysis
EU Green Deal Ecodesign regulations dictate the pricing tier structure across European markets, mandating sub-watt standby power architectures that separate premium-certified units from uncertified economy alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by Matter interoperability grade and revenue-grade metering accuracy. Cost compression in Wi-Fi enabled segments is intensifying because router-native compatibility erodes technical moats. Residential retrofit buyers in aging North American housing stock exhibit highest price sensitivity, while commercial facility managers negotiating fleet dashboards demonstrate lowest sensitivity due to ESG reporting requirements.
Supply Chain Analysis
Taiwan Strait transit risk underwrites concentrated microcontroller fabrication exposure, with TSMC and Samsung Foundry capacity utilization rates directly influencing socket OEM lead time flexibility. Component sourcing draws from Malaysian RF module assembly, Chinese relay switch manufacturing, and Japanese precision passive suppliers. Single-source vulnerability concentrates in 40nm and below microcontroller nodes where alternative foundry qualification cycles extend product launch timelines. Distribution runs through German electrical wholesale cooperatives for European commercial specifications and direct-to-consumer platforms for Asian residential volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Residential retrofit demand in aging OECD housing stock signals cyclical recovery momentum as homeowners defer full rewiring investments while upgrading outlet-level intelligence. Utility time-of-use rate expansion provides recurring revenue anchoring for vendors with automated load-shifting firmware.
For Market Incumbents: Fortify Matter certification leadership through accelerated Thread protocol engineering in Munich and Stuttgart development centers. Deepen backward integration into relay switch manufacturing to offset Asian foundry concentration risk. Defensive patent filings around sub-metering telemetry algorithms protect against Silicon Valley edge-computing entrants targeting commercial fleet management. For New Entrants and Emerging Players: Differentiate on India Bureau of Energy Efficiency compliance as first-mover positioning in commercial real estate specifications. White-space opportunity concentrates in revenue-grade socket hardware for ESG reporting mandates where incumbent cost engineering underinvests. Direct-to-installer channel partnerships bypass established distributor relationships that lock out unbranded competitors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among commercial fleet management platform operators with API reliability guarantees and data export portability. Long-term viability favors acquisition targets with Matter-over-Thread firmware stacks and established utility demand response program relationships. Monitor FCC Part 15 cybersecurity labeling rulemaking as inflection signal for compliance cost restructuring across North American supplier bases.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Certification Race | Open interoperability standards fragment proprietary ecosystem lock-in, compressing hardware-tied subscription margins. |
| Utility Demand Response Partnership | Automated load shifting integration secures recurring revenue anchoring under time-of-use rate structures. |
| Sub-Metering Accuracy Investment | Revenue-grade telemetry differentiation captures commercial ESG reporting and utility program premiums. |
| Foundry Relationship Diversification | Alternative microcontroller sourcing mitigates Taiwan Strait transit and geopolitical supply disruption exposure. |
| Fleet Management Platform Development | Centralized visibility tools unbundle hardware commoditization pressure in US retail chain procurement. |
Study Parameters
A standing panel of smart home platform engineers, electrical contractor procurement managers, utility demand response program directors, and RF chipset product managers provided ongoing calibration across primary interview cycles. Secondary validation incorporated FCC equipment authorization databases, EU Ecodesign compliance registries, Matter specification release documentation, and utility regulatory filing archives. Bottom-up socket shipment estimates by protocol variant triangulated against top-down smart home device market assessments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated connectivity protocol, application use case, end-user sophistication tier, and regional regulatory cluster dimensions. CAGRs derived from protocol-specific adoption curves weighted by housing stock age demographics and utility rate structure evolution. Forecast inputs included foundry capacity utilization projections and Matter certification timeline assumptions.
Material uncertainties — semiconductor fabrication geopolitics, national cybersecurity labeling fragmentation, and utility rate structure reform delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding Thread protocol convergence and EU Green Deal enforcement continuity. Practitioners should keep alternative scenarios live as regulatory divergence and foundry concentration dynamics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Military 4D Printing Market
Others
ASEAN Agricultural Logistics Market
Others
Palatants Market
Others
Depth Gauge Market
Others
Europe Astrology Market
Others
Textile Composites Market
Others
Europe Intercom Devices Market
Others
Global B2B Enterprise and Industrial Wearables Market
Others
Underwater Light Market
Others
Level Measuring Instrument Market
Others
Global Multi Domain Controller Market
Others
Bakery Packaging Market
Others
Asia-Pacific Professional Scalp Treatment Products Market
Others
Italy 3D Printing Construction Market
Others
DNA Data Storage Market
Others
Defense Optronics Market