
 Bitcoin Mining Hardware Market | 2026-2036
Bitcoin Mining Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Bitcoin Mining Hardware Market Analysis
Buyer concentration among mining pools and enterprise data centers is consolidating as individual miners exit due to rising energy costs and ASIC commoditization. Bitmain leverages its foundry partnerships and Antminer product breadth to sustain design leadership across multiple process nodes. MicroBT differentiates through power efficiency benchmarks and direct sales to large-scale operators. Canaan competes on price-accessible hardware for mid-tier deployments, though its geographic footprint remains concentrated in Asian markets.
Bitcoin mining hardware comprises specialized computing equipment engineered to perform SHA-256 hashing at maximal throughput per watt, with leading ASICs fabricated on 7nm and 10nm process nodes achieving energy efficiencies below 30 joules per terahash. These systems serve the primary commercial purpose of securing proof-of-work consensus while generating block rewards and transaction fees for operators. ASIC Miners anchor the product mix due to algorithm-specific optimization that GPUs and FPGAs cannot match, while Cloud Mining captures growing interest from capital-constrained entrants seeking hash rate exposure without physical infrastructure. The 7nm technology tier leads on performance metrics though supply constraints at advanced foundries limit allocation, and the 5KW to 10KW power rating band concentrates margin pools by balancing density with cooling feasibility.
The US SEC and FERC shape market access through capital formation rules and interconnection standards for mining facilities drawing grid-scale power. China's SAMR and NMPA historically influenced hardware supply chains through foundry oversight and export control frameworks, though policy shifts have relocated manufacturing planning. The EU's CSRD and emerging MiCA framework impose disclosure obligations on publicly traded mining enterprises that cascade into hardware procurement criteria. Stakeholders must monitor how energy regulators in key jurisdictions recalibrate tariff structures for high-load computing facilities.
Market Dynamics
Hash rate consolidation among mining pools is compressing margins for mid-tier operators while concentrating procurement power in the hands of vertically integrated data center developers who negotiate directly with foundries.
Growth Catalysts
- Texas ERCOT interconnection queue:The state's grid operator has fast-tracked over 37 gigawatts of crypto mining load applications, creating infrastructure pull-through for ASIC deployments.
- Stranded methane capture:Oilfield operators in North Dakota and Alberta are repurposing vented natural gas to power modular mining containers, converting waste into hash rate.
- 7nm process maturation:Yield improvements at TSMC and Samsung foundries are expanding allocation availability for energy-efficient chip designs.
Market Restraints
- Foundry concentration risk:Over 80% of advanced ASIC production depends on Taiwan-based semiconductor fabrication, exposing supply to geopolitical friction.
- US FERC interconnection delays:Grid connection timelines for large-scale facilities now stretch 18-36 months in competitive ISO markets, freezing capital deployment.
- GPU residual threat:Ethereum's proof-of-stake transition released millions of high-performance GPUs into secondary markets, creating price pressure on entry-level ASIC segments.
Strategic Opportunities
- Kazakhstan regulatory recalibration:Post-2022 mining registration frameworks are stabilizing, attracting Chinese-operated facilities seeking lower-cost hosting.
- Heat reuse integration:District heating contracts in Nordic municipalities are creating dual-revenue streams for facilities willing to co-locate with residential thermal networks.
- Direct-to-miner sales channels:Hardware vendors are bypassing distributor markups through warehouse-direct fulfillment to enterprise buyers, capturing margin previously lost to intermediaries.
Industry Challenges
- Power systems engineering scarcity:Grid-scale electrical design talent with crypto-mining specialization commands premium compensation, constraining facility buildout velocity.
- Immersion cooling retrofit complexity:Existing air-cooled deployments face stranded asset risk as heat density requirements outpace legacy infrastructure capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bitcoin Mining Hardware Market |
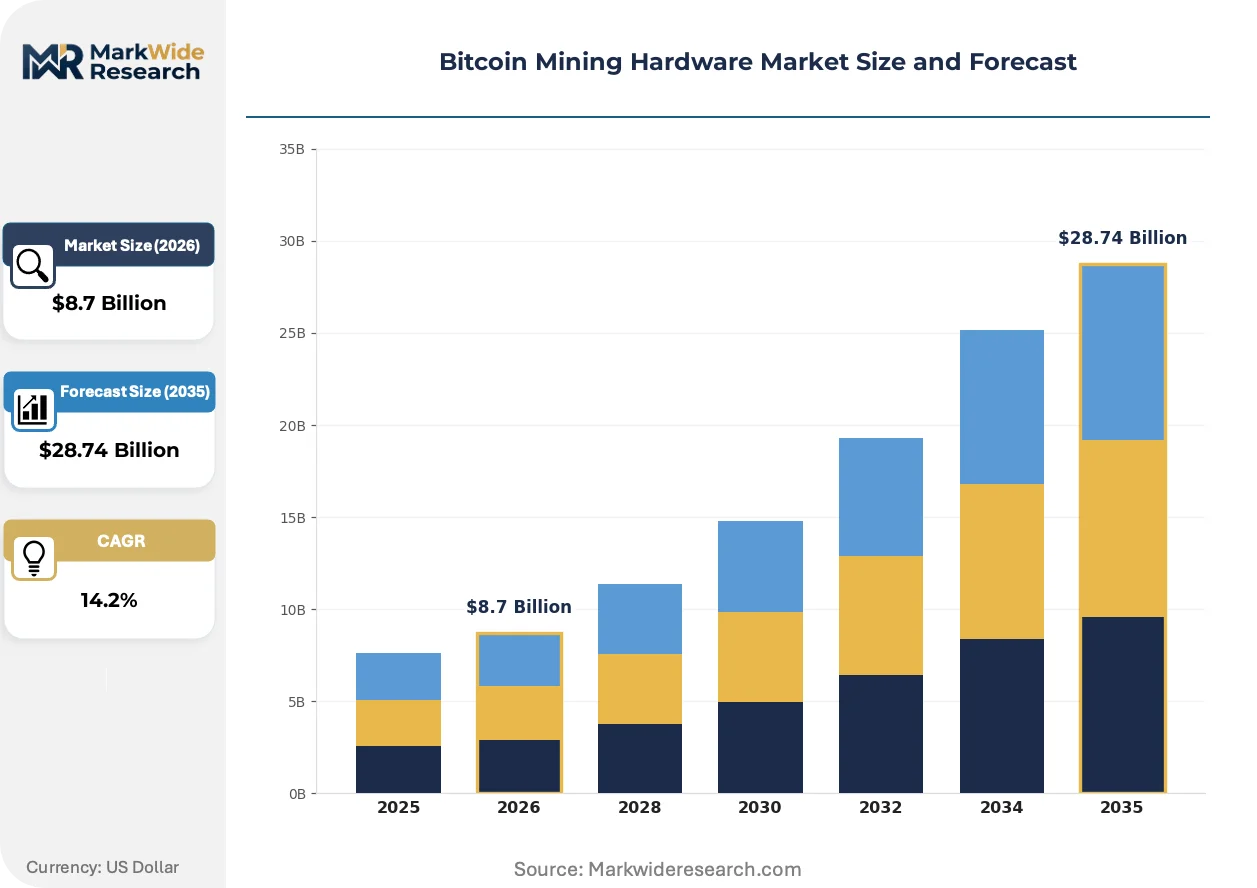
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ASIC Miners, FPGA Miners, GPU Miners, Cloud Mining Technology: 7nm, 10nm, 14nm, 16nm End User: Individual Miners, Mining Pools, Enterprises, Data Centers Power Rating: Less than 1KW, 1KW to 5KW, 5KW to 10KW, More than 10KW |
| Companies Covered | Bitmain, MicroBT, Canaan, Bitdeer Technologies Group, Bitfury, Argo Blockchain Plc, BIT Digital Inc, Cango, Phoenix Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bitcoin Mining Hardware Market Emerging Trajectories
Silicon design methodologies and energy sourcing strategies are converging to redefine operational economics for proof-of-work infrastructure. Three developments are compressing deployment cycles and reshaping competitive differentiation.
3nm process development is unifying performance and efficiency targets previously traded off in ASIC architecture. Bitmain and MicroBT engineering teams are tape-out testing designs that push below 20 joules per terahash. Enterprise data centers with direct foundry relationships are securing early allocation, while second-tier buyers face 12-month delivery queues.
EU CSRD disclosure mandates are forcing publicly traded mining enterprises to document scope 3 emissions from hardware procurement. German and Swedish operators are now requiring supplier ESG certifications as contract preconditions. This is filtering procurement criteria down to mid-tier facilities seeking institutional capital access.
Hash rate futures contracts on derivatives exchanges are decoupling hardware ownership from mining exposure. Capital-constrained entrants in Argentina and Nigeria are purchasing synthetic hash rate rather than deploying physical infrastructure. This is fragmenting demand between financialized exposure and direct ASIC ownership, with divergent implications for vendor sales cycles.
Bitcoin Mining Hardware Market Segmentation
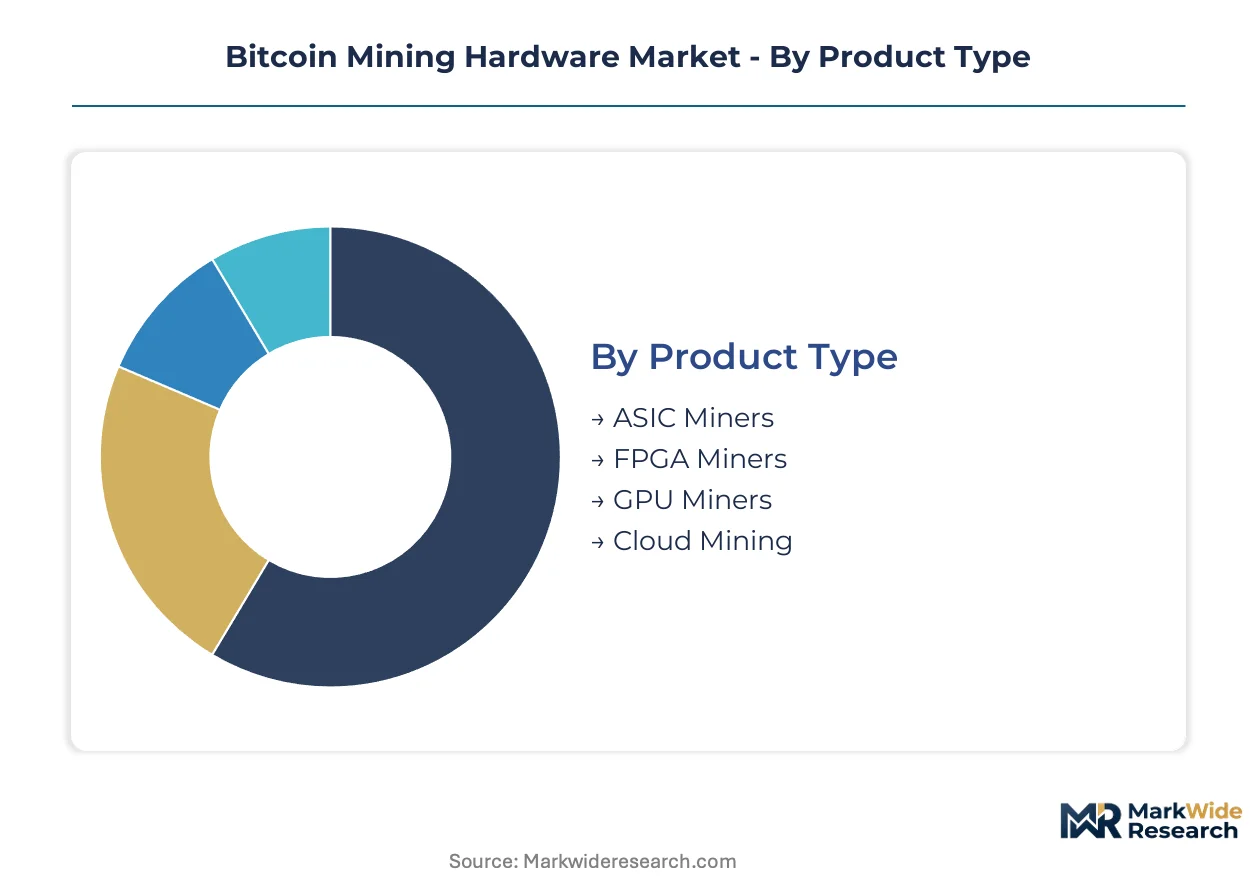
Hardware segmentation in Bitcoin mining reveals how capital deployment strategies diverge between institutional scale and distributed operations. Procurement patterns cluster around power infrastructure availability and foundry allocation access.
Product Type:
Capital intensity varies dramatically across hardware categories, with physical deployments demanding millions in facility investment while contractual alternatives require minimal upfront commitment.
- ASIC Miners:Purpose-built SHA-256 processors fabricated on advanced nodes achieve energy efficiencies below 30 joules per terahash. Texas-based mining pools and Kazakh enterprise facilities concentrate procurement here, driven by hash rate competition and direct foundry negotiation leverage.
- Cloud Mining:Hash rate subscription contracts eliminate physical infrastructure ownership. Nigerian and Argentine entrants favor this model where capital constraints and import tariffs block hardware access, though counterparty risk and opaque fee structures constrain institutional adoption.
- FPGA Miners:Reconfigurable logic arrays offer algorithm flexibility but sacrifice efficiency versus ASICs. Research clusters and university labs in Germany deploy limited quantities for protocol experimentation.
- GPU Miners:General-purpose graphics processors retain residual Bitcoin mining utility despite Ethereum's proof-of-stake transition. Secondary market liquidation from former Ethereum operations in Russia creates price pressure on entry-level segments.
ASIC Miners absorb the bulk of installed capacity; Cloud Mining is expanding most quickly among capital-constrained entrants.
Technology:
Process node selection determines foundry allocation priority and energy economics, with advanced lithography commanding premium pricing and extended delivery timelines.
- 7nm:Leading-edge production from TSMC and Samsung delivers peak efficiency for enterprise deployments. Texas and North Dakota facilities secure priority allocation through direct foundry relationships, though geopolitical exposure to Taiwan concentrates supply risk.
- 10nm:Mature yield curves balance performance with allocation availability. Russian and Kazakh mid-tier operators favor this tier where 7nm queues extend beyond 12 months.
- 14nm:Legacy node production sustains price-accessible hardware for individual miners. Chinese manufacturing clusters retain capacity here following policy-driven relocation of advanced node planning.
- 16nm:Older fabrication standards support secondary market refurbishment and developing market entry points. Nigerian distributed mining networks deploy these units where grid instability favors lower-density installations.
7nm technology captures the dominant share of new enterprise procurement; 10nm is climbing the fastest as yield maturation expands allocation access.
End User:
Customer scale determines procurement channel access, with enterprise buyers bypassing distributor networks while individual miners face margin compression from energy cost inflation.
- Data Centers:Vertically integrated facilities in Texas and Kazakhstan negotiate directly with Bitmain and MicroBT engineering teams. ERCOT interconnection fast-tracking and stranded methane partnerships in Alberta secure power cost advantages unavailable to smaller operators.
- Individual Miners:Distributed operators face existential pressure from ASIC commoditization and rising electricity tariffs. German residential miners exploit district heating integration subsidies, though EU CSRD disclosure mandates complicate capital access.
- Mining Pools:Collective hash rate aggregation concentrates procurement bargaining power. Chinese-operated pools relocating to Kazakhstan leverage registration framework stabilization for facility hosting.
- Enterprises:Corporate treasury diversification strategies drive limited direct hardware ownership. Publicly traded entities in Sweden and Germany face ESG certification requirements from institutional investors.
Data Centers command the largest procurement volumes; Individual Miners are contracting fastest as operational economics force exit.
Power Rating:
Density specifications align with cooling infrastructure investment and grid interconnection capacity, creating tiered barriers to facility scale.
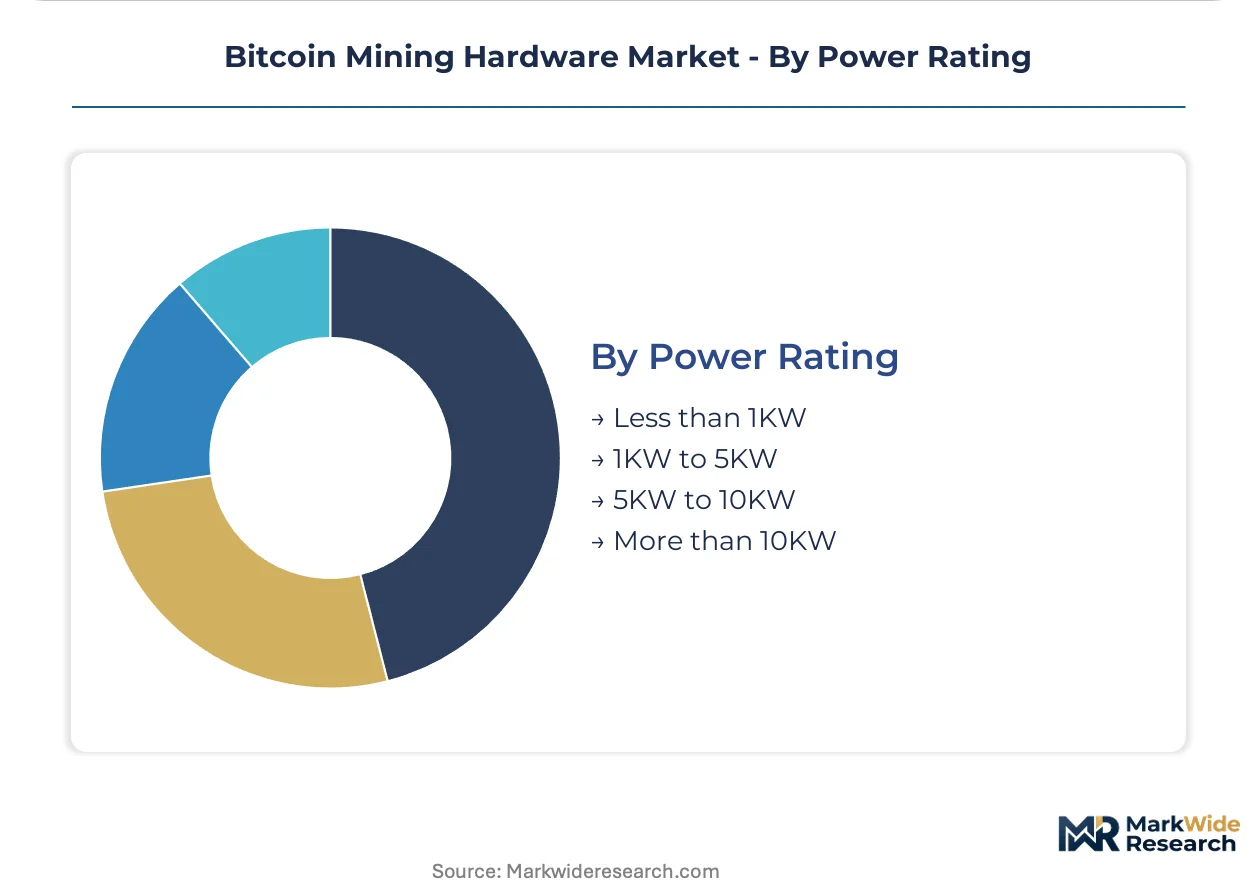
- 5KW to 10KW:Optimal thermal density for air-cooled industrial deployments without immersion retrofit requirements. Texas and North Dakota facilities standardize here, balancing hash rate density with cooling feasibility.
- More than 10KW:Ultra-high-density units demand immersion cooling or advanced HVAC engineering. Alberta oilfield containerized deployments and Nordic heat-reuse facilities adopt this tier where thermal output generates secondary revenue.
- 1KW to 5KW:Mid-range units suit retrofit air-cooled facilities and smaller industrial spaces. Russian hosting providers deploy these where Soviet-era electrical infrastructure limits per-circuit capacity.
- Less than 1KW:Entry-level hardware for residential and small commercial installations. Nigerian and Argentine distributed networks favor this tier where grid connection permits restrict commercial-scale draw.
5KW to 10KW ratings dominate current enterprise deployment; More than 10KW is gaining share fastest as immersion cooling retrofits advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for Bitcoin mining hardware clusters in jurisdictions offering energy cost arbitrage and regulatory ambiguity. Texas, Kazakhstan, and Russia concentrate procurement volumes. Facility developers prioritize grid interconnection speed and power pricing over geographic diversification.
United States
Texas ERCOT fast-tracked 37 gigawatts of crypto mining load applications, pulling ASIC deployments through infrastructure buildout. FERC interconnection standards govern grid-scale facility approvals, with timelines stretching 18-36 months in competitive ISO markets. North Dakota oilfield operators partner with miners for stranded methane capture, converting vented natural gas into hash rate through modular container deployments.
Kazakhstan
Chinese-operated mining pools relocated facilities following post-2022 registration framework stabilization, attracted by lower-cost hosting. The country's national energy regulator recalibrated tariff structures for high-load computing facilities. Almaty and surrounding industrial zones concentrate hosting capacity as operators exploit regulatory gaps unavailable in neighboring jurisdictions.
Russia
Soviet-era electrical infrastructure in Siberian regions supports mid-tier deployments where per-circuit capacity limits favor 1KW to 5KW units. The central bank maintains ambiguous stance on digital asset classification, creating operational uncertainty. Irkutsk and Krasnoyarsk industrial clusters absorb secondary market GPU liquidation from former Ethereum operations, pressuring entry-level ASIC pricing.
Germany
EU CSRD disclosure mandates force publicly traded mining enterprises to document scope 3 emissions from hardware procurement. German operators require supplier ESG certifications as contract preconditions for institutional capital access. Bavarian and North Rhine-Westphalian municipalities explore district heating contracts with mining facilities, creating dual-revenue thermal networks.
Canada
Alberta oilfield operators repurpose vented natural gas to power modular mining containers, mirroring North Dakota's stranded methane strategy. Provincial energy regulators oversee interconnection standards for facilities drawing grid-scale power. Calgary and Edmonton industrial corridors attract enterprise data centers seeking direct foundry relationships and ERCOT-competitive power economics.
Bitcoin Mining Hardware Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue hash rate exposure through financialized instruments rather than physical infrastructure ownership. The vendor base concentrates around three design houses with foundry allocation priority, while second-tier fabricators compete on price-accessible hardware for mid-tier deployments. Strategic archetypes include vertically integrated data center developers, specialized ASIC design firms, and cloud-based hash rate intermediaries. Competitive moves center on direct-to-miner sales channel development and immersion cooling retrofit partnerships.
Within the established tier, Bitmain and MicroBT anchor design leadership through foundry partnerships and power efficiency benchmarks. Canaan occupies a position serving price-sensitive mid-tier deployments concentrated in Asian markets. Bitfury and Bitdeer Technologies Group exemplify the vertical integration archetype, combining hardware procurement with facility ownership and energy sourcing. These five entities represent the competitive core around which procurement power concentrates.
| Leading Market Players |
|---|
| Bitmain |
| MicroBT |
| Canaan |
| Bitdeer Technologies Group |
| Bitfury |
| Argo Blockchain Plc |
| BIT Digital Inc |
| Cango |
| Phoenix Group |
| Others |
Supply Flow & Price Mechanics
EU CSRD disclosure mandates gate qualified supply and premium-tier pricing access by forcing publicly traded mining enterprises to document scope 3 emissions from hardware procurement, filtering procurement criteria down to mid-tier facilities seeking institutional capital access.
Pricing Analysis
Volume concentration among Texas-based mining pools and Kazakh enterprise facilities compresses margins for mid-tier operators while preserving premium capture for direct foundry negotiators. Pricing stratifies across 7nm priority allocation, 10nm mature yield, and 14nm price-accessible tiers, with energy efficiency benchmarks and ESG certification levels driving differentiation. Cost compression in the 14nm legacy tier intensifies because Chinese manufacturing clusters retain surplus capacity following policy-driven relocation of advanced node planning. Individual miners and Nigerian distributed networks exhibit highest price sensitivity; vertically integrated data center developers with direct foundry relationships demonstrate lowest sensitivity due to captive allocation access.
Supply Chain Analysis
ESG certification and foundry qualification gating restricts supply base participation, with TSMC and Samsung foundry partnerships serving as mandatory prerequisites for advanced node access. Taiwan, South Korea, and China anchor semiconductor fabrication capacity, with Taiwan concentrating over 80% of advanced ASIC production. Raw material dependencies center on silicon wafers, specialized packaging substrates, and immersion cooling fluids. Single-source vulnerability to Taiwan-based fabrication exposes supply to geopolitical friction. Distribution runs through direct-to-miner sales channels bypassing distributor markups, with warehouse-direct fulfillment capturing margin previously lost to intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hash rate consolidation among mining pools is compressing margins for mid-tier operators and forcing weaker players toward exit, making this market a consolidation play for well-capitalized participants with direct foundry access.
For Market Incumbents: Cement design leadership through 3nm tape-out testing that pushes below 20 joules per terahash, securing early foundry allocation before second-tier buyers face extended delivery queues. Deepen backward integration into stranded methane capture partnerships in North Dakota and Alberta, converting waste gas into captive power cost advantages unavailable to smaller competitors. Threat substitution from hash rate futures contracts on derivatives exchanges demands defensive positioning around physical infrastructure ownership.
For New Entrants and Emerging Players: Immersion cooling retrofit technology offers a technology-first wedge for specialized engineering firms lacking foundry allocation priority. Target the 1KW to 5KW power rating segment in Russian and Nigerian markets where Soviet-era electrical infrastructure and grid connection permits restrict commercial-scale draw. Go-to-market angle should emphasize heat reuse integration contracts with Nordic municipalities seeking district heating partnerships.
For Investors and Strategic Acquirers: FERC interconnection timeline compression is the leading indicator that capital deployment velocity will accelerate for facilities with queue priority. Long-term viability favors vertically integrated data center developers combining hardware procurement with facility ownership and energy sourcing. Acquisition target archetype: mid-tier hosting providers with secured power purchase agreements and pending ERCOT fast-track approval. Signal to monitor: Kazakhstan regulatory recalibration stabilizing registration frameworks for Chinese-operated facility relocations.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Foundry Partnership | Secures priority 7nm and 3nm allocation ahead of 12-month delivery queues facing second-tier buyers. |
| Stranded Methane Capture Integration | Converts vented natural gas in North Dakota and Alberta into captive power cost advantages below grid tariffs. |
| Immersion Cooling Retrofit Deployment | Addresses stranded asset risk for air-cooled facilities as heat density requirements outpace legacy infrastructure capacity. |
| ESG Certification Investment | Unlocks institutional capital access for German and Swedish operators facing EU CSRD disclosure mandates. |
| Heat Reuse Contract Structuring | Creates dual-revenue thermal networks with Nordic municipalities seeking district heating partnerships. |
Methodological Framework
SEC filings, FERC interconnection databases, and EIA power market data formed the secondary backbone for this analysis, supplemented by customs records tracking ASIC import flows into Texas, Kazakhstan, and Russia. Primary interviews with data center procurement directors, foundry account managers, mining pool operators, and oilfield methane capture specialists provided operational validation. Bottom-up unit economics modeling and top-down hash rate deployment tracking were triangulated against secondary validation sources.
Historical trendline analysis of hash rate growth, energy efficiency improvement curves, and foundry allocation patterns informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, process node technology, end user scale, and power rating tier, with regional regulatory framework clusters as an industry-specific dimension. CAGRs were derived from deployment velocity assumptions tied to ERCOT interconnection queue progression and Kazakhstan registration framework stabilization. Forecast inputs incorporated stranded methane partnership expansion rates and immersion cooling retrofit adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Taiwan geopolitical disruption or FERC interconnection standard recalibration scenarios. Forecasts reflect documented assumptions regarding foundry yield maturation and energy tariff structures. A model refresh is warranted upon material change in SEC digital asset classification stance or ERCOT interconnection queue prioritization methodology.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
DIY Smart Home Market
Others
APAC Smart Home Market
Others
Global Digital Market
Others
China Smart Home Market
Others
Education and Learning Analytics Market
Others
Fiberglass Storage Tanks Market
Others
Asia-Pacific Induced Pluripotent Stem Cells (Ipscs) Market
Others
Military Sensors Software Market
Others
Canada Laser Hair Removal Market
Others
Wood Stoves Market
Others
IT Device Market
Others
Connected TV Market
Others
Server Market
Others
Spain Feed Additives Market
Others
Motor Grader Market
Others
India Home Automation Market