
 Deflectometer Market | 2026-2036
Deflectometer Market Size, Share, and Industry Trends Forecast 2026-2036
Deflectometer Market Analysis
Direct distribution to government laboratories and departments of transportation is tilting toward bundled service contracts that include calibration and field training. Zorn Instruments leverages its German manufacturing base to sustain proximity to European road authorities. Dynatest competes through deep specialization in falling-weight deflectometer systems for airport runway certification. Humboldt Mfg. Co. anchors North American supply through a distributor network serving state DOT testing laboratories.
A deflectometer measures vertical deformation or deflection of materials under applied load, typically resolving displacement to 0.01 mm precision through linear variable differential transformer or laser triangulation sensors. Civil engineers deploy these instruments to assess structural integrity of pavements, bridges, and foundations by quantifying load-response behavior under standardized force application. Portable deflectometers lead unit shipments due to flexibility across remote job sites, while digital deflectometers command margin concentration through integrated data-logging and cloud-connectivity modules. Laser technology segments attract premium positioning as optical measurement systems displace mechanical sensors in high-speed continuous-profiling applications.
Federal Highway Administration protocols and ASTM International standards govern equipment calibration intervals and test methodologies in the United States, while EU Green Deal carbon-footprint disclosure rules shape procurement specifications for lifecycle-assessment-capable instruments. Germany's KBA and France's ANSM coordinate cross-border recognition of metrological certificates, reducing retesting burdens for manufacturers serving multiple European markets. Stakeholders must monitor evolving interoperability mandates between national road databases and deflectometer output formats to preempt compliance-driven replacement cycles.
Market Dynamics
Laser triangulation sensors are compressing calibration cycles and forcing incumbent mechanical-sensor suppliers to reposition around service bundling. Road authorities in Germany and France now embed carbon-footprint disclosure into procurement scoring, reshaping vendor qualification criteria.
Growth Catalysts
- EU Green Deal carbon-accounting mandates:Infrastructure lifecycle assessments now require continuous deflection profiling, accelerating replacement of mechanical units with laser-capable systems in European road maintenance contracts.
- Metro-rail structural analysis:Urban corridor expansion in Japan and South Korea generates recurring inspection contracts for portable deflectometers deployed on elevated track beds and tunnel linings.
- Falling-weight deflectometer standardization:Airport runway certification protocols under FAA and EASA harmonization are consolidating test methodologies, expanding addressable demand for automated load-drop systems.
Market Restraints
- Optical component supply concentration:Laser diode and precision lens sourcing clusters in East Asian manufacturing hubs, exposing European and North American instrument builders to extended lead times.
- ASTM D4694 calibration complexity:The reference standard for falling-weight systems requires traceable force verification that adds 15-20% to total cost of ownership for smaller pavement-testing contractors.
- Ground-penetrating radar substitution:Subsurface imaging technologies are capturing share in bridge-deck assessment applications where full structural mapping displaces point-load deflection measurement.
Strategic Opportunities
- India National Highways Authority asset management:The country's 50,000-kilometer expressway expansion creates first-time demand for continuous-profiling deflectometers in a market historically served by manual Benkelman beams.
- Cloud-connected predictive maintenance:Integration of deflection data with pavement management systems enables subscription-based analytics revenue streams beyond equipment sale.
- Brazil ANVISA medical-device crossover:Deflectometer manufacturers with ISO 13485 certification can access hospital floor-vibration testing for MRI installation, an adjacent vertical with limited incumbent competition.
Industry Challenges
- Metrological technician scarcity:Field calibration of LVDT and laser sensors requires specialized training that state DOT laboratories struggle to staff, extending equipment downtime.
- Legacy data format fragmentation:National road databases in Germany, France, and the United States operate on incompatible file structures, forcing manufacturers to maintain multiple software export modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deflectometer Market |
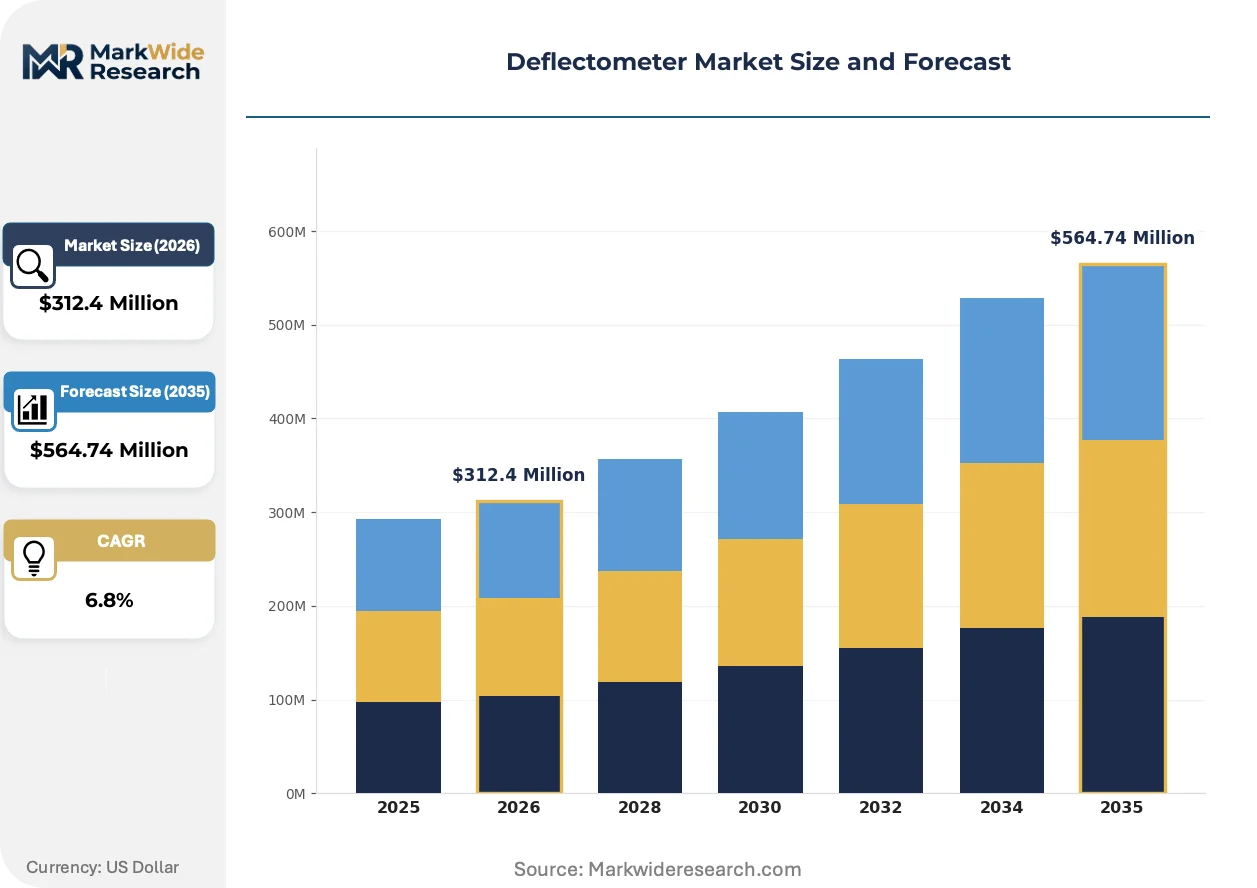
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Deflectometers, In-Situ Deflectometers, Fixed Deflectometers, Digital Deflectometers End User: Civil Engineering, Construction Companies, Road Maintenance Firms, Research Institutions Technology: Laser Technology, Mechanical Sensors, Ultrasonic Devices, Optical Measurement Systems Application: Pavement Evaluation, Structural Analysis, Load Testing, Soil Testing |
| Companies Covered | Zorn Instruments, InfraTest Prüftechnik GmbH, KERN & SOHN GmbH, Dynatest, TERRATEST, Geomil Equipment BV, TSI Incorporated, Cooper Technology Ltd., Humboldt Mfg. Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deflectometer Market Emerging Trajectories
Measurement modality convergence is collapsing the distinction between portable spot-testing and continuous profiling, while regulatory data-sharing mandates are rewriting software architecture requirements. Vendors now compete on interoperability depth rather than hardware precision alone.
Optical triangulation systems are migrating from high-speed continuous-profiling installations into mid-tier portable units previously dominated by mechanical LVDT sensors. German road authorities are piloting these compact laser units on rural networks where laboratory-grade precision was previously uneconomical. This migration is compressing the price-performance gap between premium and standard equipment tiers, forcing mechanical-sensor specialists to defend position through calibration service contracts.
EU Green Deal carbon-footprint disclosure rules are embedding lifecycle-assessment capability into procurement specifications for infrastructure monitoring equipment. French ANSM and German KBA coordination on cross-border metrological certificate recognition is reducing retesting burdens, but the underlying technical requirements are tightening. Portable deflectometer manufacturers serving multiple European markets must now engineer for simultaneous compliance with divergent national database formats.
Service unbundling is separating hardware procurement from calibration and field training in North American state DOT contracts. Traditional bundled offerings from distributor networks are yielding to direct manufacturer relationships for equipment, paired with third-party metrological service providers for ongoing certification. This pattern is most visible in California and Texas, where centralized procurement offices are optimizing supplier pools by function rather than by integrated capability.
Deflectometer Market Segmentation
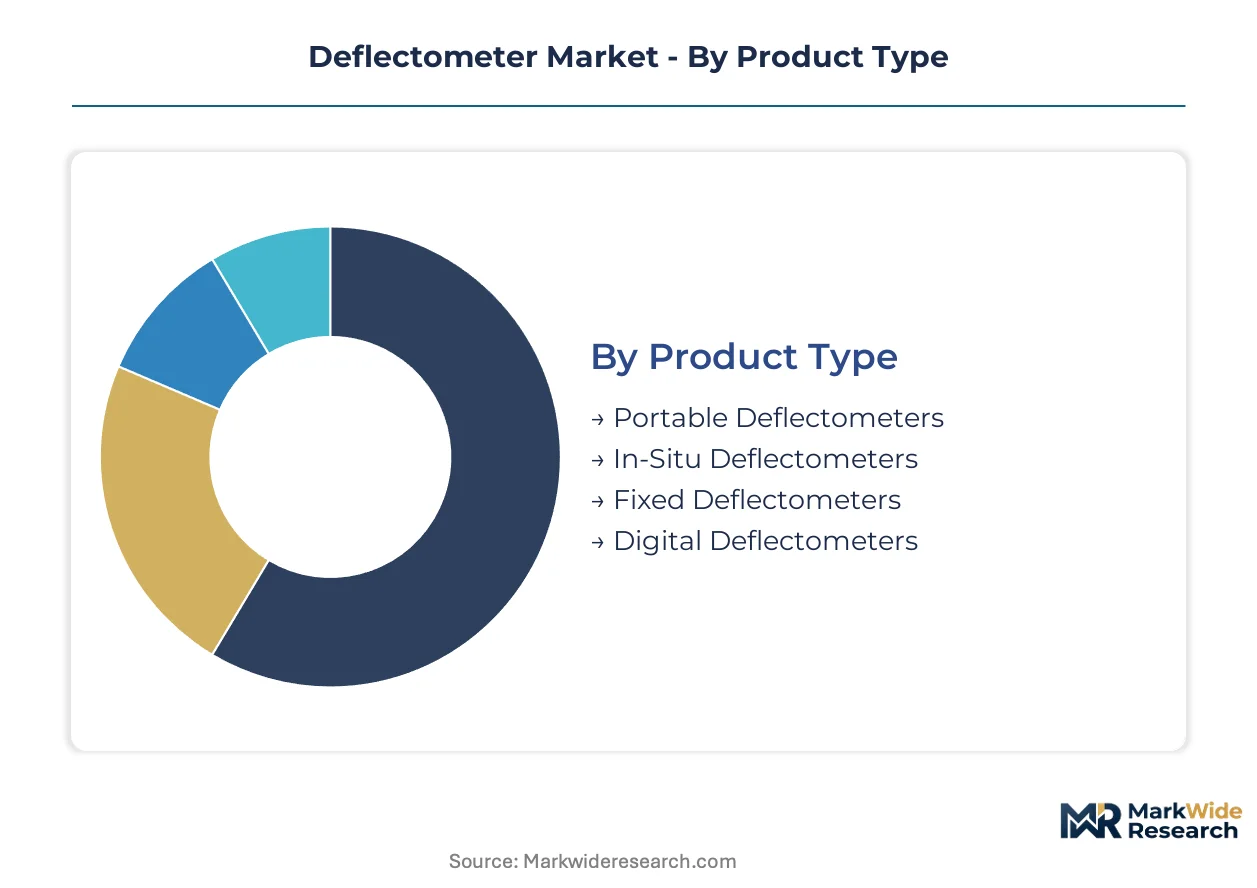
Deflectometer procurement patterns diverge sharply across product configurations and end-use contexts, with calibration service bundling and data interoperability requirements reshaping vendor selection criteria. Segment boundaries are blurring as optical sensors migrate downward from premium continuous-profiling systems into portable units previously served by mechanical LVDT technology.
Product Type:
After-sales-service intensity varies dramatically across product categories, with fixed installations demanding continuous calibration contracts while portable units rely on periodic field technician visits.
- Portable Deflectometers:Battery-powered units with integrated data loggers resolve displacement to 0.01 mm through compact LVDT or emerging laser triangulation modules. Road maintenance firms in Germany are expanding procurement of laser-based portable units as EU Green Deal carbon-accounting requirements tighten for infrastructure lifecycle assessments.
- Digital Deflectometers:Cloud-connected architectures with embedded cellular modules transmit deflection data directly to pavement management systems, enabling subscription-based analytics revenue beyond hardware sale. Demand concentrates in East Asian urban corridors where metro-rail expansion drives structural-analysis contracts requiring real-time monitoring.
- In-Situ Deflectometers:Semi-permanent installations for long-term structural health monitoring of bridges and tunnels.
- Fixed Deflectometers:Permanent high-speed continuous-profiling systems deployed on major highway corridors.
Portable deflectometers hold the largest share; momentum sits with digital deflectometers.
End User:
Procurement authority fragmentation creates distinct sales cycles, with government laboratories emphasizing metrological traceability and construction companies prioritizing rental flexibility.
- Road Maintenance Firms:Fleet operators managing thousands of lane-kilometers annually require ruggedized equipment with rapid calibration turnaround. German road authorities now embed carbon-footprint disclosure into procurement scoring, reshaping vendor qualification criteria for these high-volume buyers.
- Civil Engineering:Consulting firms conducting forensic pavement analysis demand laboratory-grade precision with full ASTM D4694 traceability. Federal Highway Administration protocols govern equipment calibration intervals for US-based civil engineering contracts, creating compliance-driven replacement cycles.
- Construction Companies:Project-based procurement favors rental models and short-term service agreements.
- Research Institutions:University laboratories and national metrology institutes drive specification evolution through collaborative standard-setting.
Road maintenance firms hold the largest share; research institutions are climbing the fastest as standard-setting influence.
Technology:
Component sourcing geography is concentrating competitive risk, with laser diode and precision lens supply clustering in East Asian manufacturing hubs.
- Laser Technology:Optical triangulation systems achieve non-contact measurement at highway speeds, eliminating mechanical wear. French ANSM and German KBA coordination on cross-border metrological certificate recognition reduces retesting burdens for laser-equipped instruments serving multiple European markets.
- Mechanical Sensors:Traditional LVDT architectures dominate budget-conscious portable applications where 0.01 mm precision suffices. Falling-weight deflectometer standardization under FAA and EASA harmonization is consolidating test methodologies, preserving mechanical-sensor demand in airport runway certification.
- Optical Measurement Systems:Advanced interferometric approaches for laboratory-grade structural analysis.
- Ultrasonic Devices:Emerging contactless alternatives for specialized soil testing applications.
Mechanical sensors hold the largest share; laser technology is gaining share fastest.
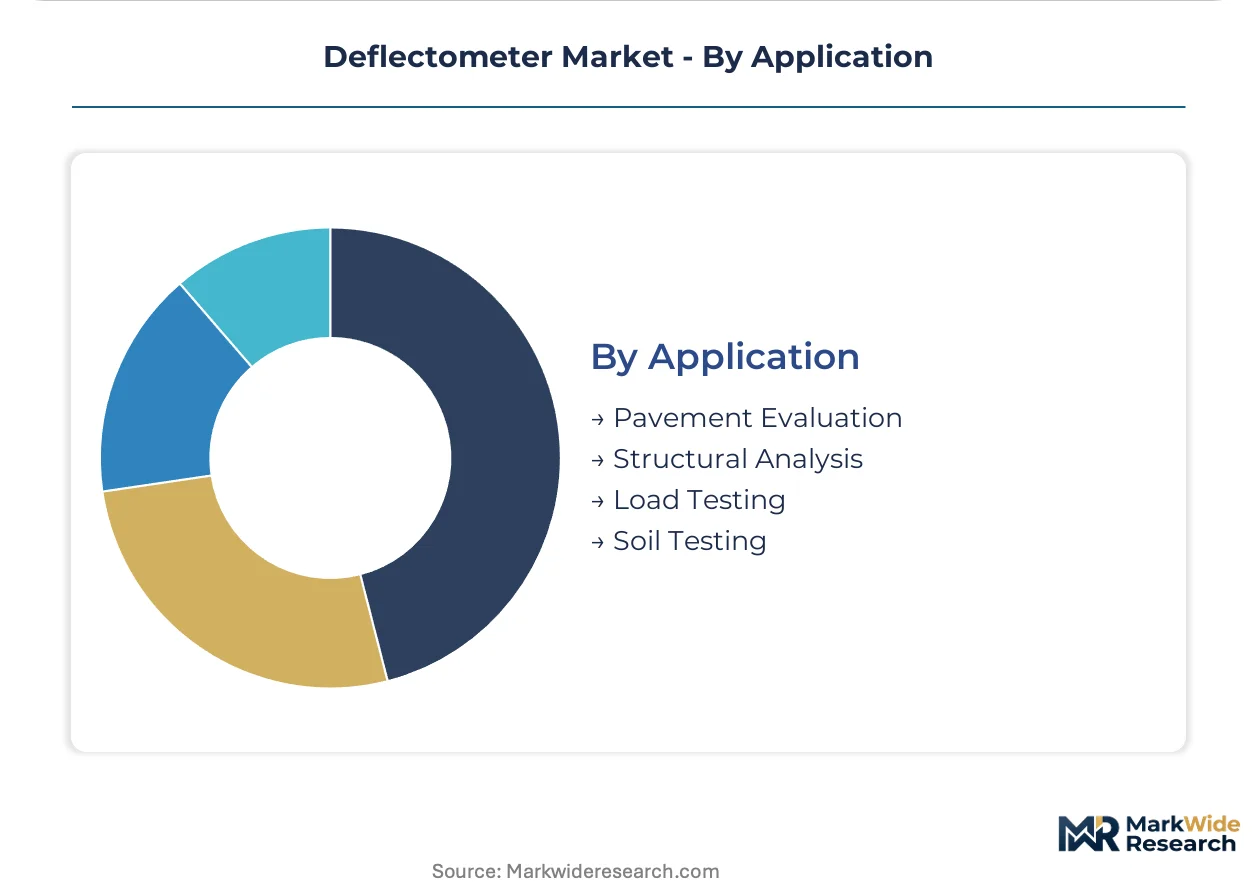
Application:
Measurement modality convergence is collapsing distinctions between spot-testing and continuous profiling, with regulatory data-sharing mandates rewriting software architecture requirements.
- Pavement Evaluation:Surface deflection profiling under standardized wheel loads determines structural capacity and remaining service life. India's National Highways Authority 50,000-kilometer expressway expansion creates first-time demand for continuous-profiling deflectometers in a market historically served by manual Benkelman beams.
- Structural Analysis:Bridge deck and tunnel lining assessment requires multi-point deflection mapping under controlled loading. Metro-rail expansion in Japan and South Korea generates recurring inspection contracts for portable deflectometers deployed on elevated track beds.
- Load Testing:Foundation verification through controlled force application and settlement measurement.
- Soil Testing:Subgrade modulus determination for earthwork quality control.
Pavement evaluation holds the largest share; structural analysis shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's autobahn network underwrites European demand leadership, with continuous-profiling deflectometers deployed across federal highway corridors to meet EU Green Deal carbon-accounting mandates. Infrastructure lifecycle assessment requirements are reshaping procurement patterns across multiple geographies.
United States
FAA and EASA harmonization on falling-weight deflectometer protocols is expanding airport runway certification contracts. Federal Highway Administration calibration intervals govern state DOT laboratory equipment replacement cycles. Texas and California procurement offices are unbundling hardware purchases from calibration services.
Germany
Road maintenance firms are expanding laser-based unit procurement as KBA tightens metrological certificate requirements for cross-border equipment recognition. Carbon-footprint disclosure now embeds into vendor qualification scoring. Bavarian manufacturing clusters anchor Zorn Instruments' proximity to European road authorities.
Japan
Metro-rail expansion across Tokyo-Osaka corridors generates recurring inspection contracts for portable deflectometers on elevated track beds. METI infrastructure standards mandate structural health monitoring for tunnel linings. Kansai region engineering firms are piloting cloud-connected units for real-time pavement management integration.
India
National Highways Authority's 50,000-kilometer expressway expansion creates first-time demand for continuous-profiling systems in a market historically served by manual Benkelman beams. BIS certification requirements are accelerating equipment standardization. Gujarat and Maharashtra road contractors are consolidating procurement through centralized state infrastructure funds.
South Korea
Seoul Capital Area metro-rail extensions drive structural-analysis contracts requiring portable deflectometers with 0.01 mm precision. MFDS medical-device crossover pathways enable hospital floor-vibration testing applications. Busan-Ulsan industrial corridors are deploying laser triangulation units for port infrastructure assessment.
Deflectometer Market Vendor Landscape
On the supply side, the industry is moderately consolidated around specialized instrumentation manufacturers with deep domain expertise in pavement testing or structural monitoring. Three strategic archetypes dominate: German-engineered precision specialists serving European regulatory markets, North American distributor-network players anchoring state DOT relationships, and falling-weight system specialists concentrated in airport runway certification. Competitive moves center on calibration service bundling to offset hardware margin compression, and geographic expansion into India's expressway build-out through local partnership structures.
Among German-engineered specialists, Zorn Instruments and InfraTest Prüftechnik GmbH exemplify the precision-tier archetype with proximity-based positioning toward European road authorities. Dynatest occupies a distinct specialization niche in automated load-drop systems for airport applications. These three anchors illustrate how vendor selection increasingly weights service interoperability and metrological traceability over standalone hardware specifications.
| Leading Market Players |
|---|
| Zorn Instruments |
| InfraTest Prüftechnik GmbH |
| KERN & SOHN GmbH |
| Dynatest |
| TERRATEST |
| Geomil Equipment BV |
| TSI Incorporated |
| Cooper Technology Ltd. |
| Humboldt Mfg. Co. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in East Asian optical component fabrication is compressing margins for European and North American deflectometer assemblers while simultaneously elevating pricing power among laser diode suppliers serving the precision measurement sector.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement, with laser-equipped continuous-profiling systems commanding premium positioning against mechanical-sensor portable units. Price differentiation rests on calibration service bundling and EU Green Deal carbon-accounting certification tiers. Cost compression in standard portable units is intensifying because mechanical-sensor specialists defend share through extended warranty offerings. State DOT laboratories exhibit highest price sensitivity due to unbundled procurement mandates, while airport runway certification authorities show lowest sensitivity given FAA-EASA harmonization requirements.
Supply Chain Analysis
Contract manufacturing for precision optical assemblies concentrates in Taiwanese and South Korean electronics manufacturing services, with German and Japanese instrument builders retaining final calibration and metrological certification in-house. Laser diodes, precision aspheric lenses, and linear variable differential transformer cores draw from Japan, Germany, and China respectively. Single-source vulnerability in laser diode supply exposes European assemblers to allocation risk during capacity constraints. Distribution runs through authorized distributor networks serving state DOT laboratories in North America and direct manufacturer relationships with European road authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calibration and field-training service contracts are expanding faster than hardware unit sales, creating durable recurring revenue streams that offset equipment margin compression across the deflectometer sector.
For Market Incumbents: Build switching-cost moats through embedded software interoperability with national road database formats. Deepen backward integration into laser triangulation module assembly to reduce East Asian component exposure. Certify equipment simultaneously under German KBA and French ANSM protocols to preempt competitor cross-border entry. Ground-penetrating radar substitution in bridge-deck applications threatens point-load deflection market share. For New Entrants and Emerging Players: Establish a beachhead in India's National Highways Authority expressway expansion, where manual Benkelman beam displacement creates first-time demand for continuous-profiling systems. Target cloud-connected predictive maintenance subscriptions as the most penetrable revenue layer, with state infrastructure funds in Gujarat and Maharashtra consolidating procurement. Pursue ISO 13485 certification to access Brazil ANVISA medical-device crossover for hospital floor-vibration testing adjacent to core pavement markets. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across portable laser-deflectometer sub-segments as optical components commoditize and software attach rates rise. Long-term viability favors precision-tier specialists with embedded calibration service networks over hardware-only assemblers. Acquisition targets should demonstrate metrological certificate reciprocity across at least two European regulatory regimes. Monitor German KBA procurement scoring changes for carbon-footprint disclosure weighting as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Expansion | Recurring revenue from German road authority contracts offsets hardware margin compression. |
| Laser Triangulation Module Integration | Optical sensor migration into portable units collapses price-performance gaps against mechanical competitors. |
| Cloud-Connected Platform Development | Real-time data transmission to pavement management systems enables subscription analytics revenue. |
| Cross-Border Metrological Certification | Simultaneous KBA and ANSM compliance reduces retesting burdens for multi-market European vendors. |
| India Distribution Partnership Structure | Local relationships with Gujarat and Maharashtra state infrastructure funds accelerate National Highways Authority penetration. |
Methodological Framework
A spread of perspectives from road authority procurement officers, metrological laboratory directors, pavement engineering consultants, and aftermarket service technicians converged on the working assumptions underpinning this analysis. Primary field engagement combined structured interviews with secondary validation against Federal Highway Administration protocol documents, ASTM International calibration standards, EU Green Deal infrastructure disclosure requirements, and national road database specification sheets. Bottom-up equipment shipment tracking and top-down infrastructure spending allocation were triangulated to anchor volume estimates.
Demand-supply-balance framing structured the analytical approach across the projection horizon, with segmentation dimensions spanning product configuration, end-user procurement authority, measurement technology, and application context. CAGRs were derived from equipment replacement cycle analysis and infrastructure contract flow data. Forecast inputs incorporated EU Green Deal carbon-accounting mandate implementation timelines and India's expressway construction phase commitments.
Stress conditions across optical component supply availability, metrological technician labor scarcity, and ground-penetrating radar substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization progress and infrastructure spending continuity. Quarterly review of German KBA procurement scoring weights and East Asian laser diode capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
5G Devices Market
Others
Connected Homes Market
Others
Global Augmented Reality in Retail Market
Others
Digital Tattoos Market
Others
Dental Ceramics Market
Others
Thermoformed Plastics Market
Others
Bitcoin Mining Servers Market
Others
Bulgur Market
Others
Embedded Computer Market
Others
Middle East and Africa Cocoa Products Market
Others
Saudi Arabia Laser Hair Removal Market
Others
Powder Coating Equipment Market
Others
Solid White Films Market
Others
Short Video Applications Market
Others
Fenoxanil Market
Others
5G Tester Market