
 Free Space Optics (FSO) Market | 2026-2036
Free Space Optics (FSO) Market Size, Share, and Industry Trends Forecast 2026-2036
Free Space Optics (FSO) Market Intelligence
The divergence in R&D investment for atmospheric turbulence mitigation is bifurcating the competitive landscape. Mynaric AG specializes in capital-intensive laser communication terminals designed for aerospace and satellite constellations. In contrast, LightPointe Communications leverages its expertise in more established terrestrial applications like building-to-building links. fSONA Networks also competes in this ground-based segment, offering solutions for enterprise last-mile connectivity.
Free space optics technology transmits data through the atmosphere using a focused beam of light, typically an infrared laser with a wavelength around 1550 nm. It provides a high-bandwidth, license-free alternative to fiber optic cables for line-of-sight communication. Military communications and disaster recovery are critical application areas driving innovation. While defense agencies remain a primary end user, telecom operators are increasingly deploying FSO for rapid 5G backhaul network expansion.
Equipment standards are influenced by bodies like the US Federal Communications Commission (FCC) and the European Telecommunications Standards Institute (ETSI), which define operational parameters. In China, the Ministry of Industry and Information Technology (MIIT) governs network access and equipment approval. Eye safety regulations, such as IEC 60825, also impose strict design constraints on laser power. Future investment decisions hinge on achieving interoperability between different vendors' terrestrial and satellite-based systems.
Market Dynamics
The global push for high-bandwidth connectivity is creating a structural tension between terrestrial fiber and wireless alternatives. This positions FSO as a critical technology for bridging last-mile gaps and enabling next-generation satellite networks.
Growth Catalysts
- 5G Network Densification:Telecom operators use FSO for rapid 5G backhaul, avoiding costly and slow fiber trenching in dense urban areas.
- Resilient Laser Technology:Advances in laser diodes and adaptive optics mitigate atmospheric interference, increasing system uptime for critical military and commercial applications.
- Defense Modernization:United States defense agency projects are funding development of jam-resistant, high-throughput FSO systems for secure aerospace and military communications.
Market Restraints
- Atmospheric Attenuation:System reliability is constrained by weather, as fog, rain, and snow absorb and scatter the light beam, causing link failure.
- Line-of-Sight Requirement:The need for an unobstructed path between terminals complicates deployment in dense urban environments or hilly terrain, limiting potential sites.
- Fiber Optic Competition:The falling cost and expanding footprint of terrestrial fiber networks present a powerful, high-reliability substitute for many fixed applications.
Strategic Opportunities
- Inter-Satellite Links:Low Earth Orbit (LEO) satellite constellations create a new market for FSO to provide high-speed, intra-constellation data backbones.
- Hybrid RF/FSO Systems:Integrating FSO with radio frequency (RF) creates high-availability systems that combine FSO's bandwidth with RF's all-weather reliability.
- Last-Mile Connectivity:In regions with limited fiber, FSO provides a cost-effective solution for extending high-speed internet to underserved enterprises and communities.
Industry Challenges
- Interoperability Standards:A lack of universal standards hinders interoperability between different vendors' equipment, particularly between terrestrial and satellite systems, complicating network integration.
- Eye Safety Compliance:Adhering to strict eye safety regulations, such as IEC 60825, imposes significant design constraints on laser power, which directly impacts link distance and reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Free Space Optics (FSO) Market |
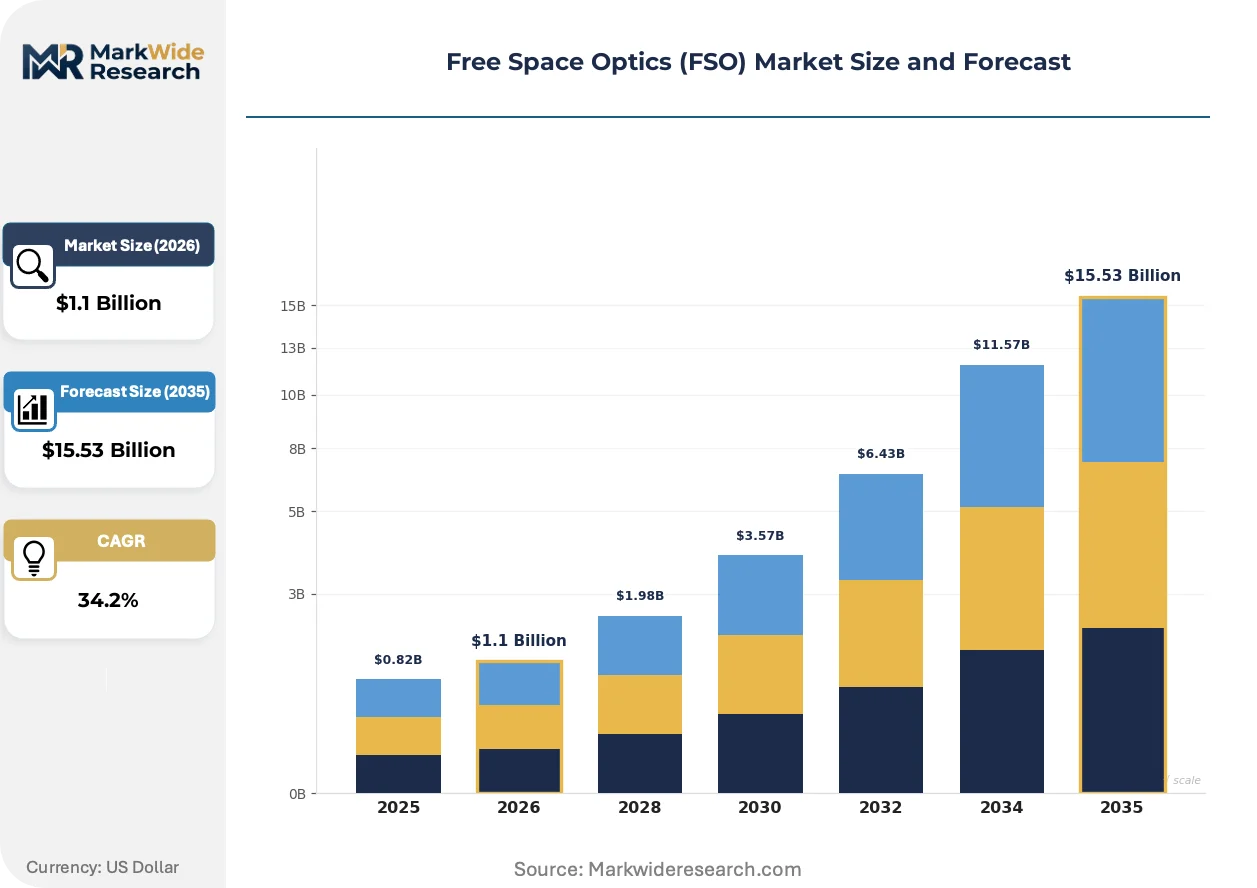
| Market Size in 2026 | $1.1 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transceivers, Modulators, Detectors, Amplifiers, Optical Components Technology: Infrared, Near-Infrared, Ultraviolet, Visible Light Communication, Laser Diodes Application: Military Communications, Data Center Interconnects, Building-to-Building Links, Disaster Recovery, Temporary Networks End User: Telecom Operators, Data Centers, Defense Agencies, Enterprise Networks |
| Companies Covered | AOptix Technologies, EC System, Trimble, Anova Technologies, Mynaric AG, fSONA Networks, Wireless Excellence, Mostcom, LightPointe Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Free Space Optics (FSO) Market Strategic Shifts & Innovations
The technical evolution of FSO is defined by a push for greater atmospheric resilience and system intelligence. Innovations are focused on active beam correction and hybrid architectures to expand the technology's operational domain beyond niche, clear-weather applications.
Adaptive optics (AO) systems actively correct for atmospheric-induced beam distortion in real time using deformable mirrors. The aerospace and defense sectors are the primary adopters for high-value satellite and airborne communication links. This active beam correction technology is supplanting older, static compensation methods, enabling more reliable long-distance connectivity.
Spectrum allocation policies from regulators like the US Federal Communications Commission (FCC) and international bodies are creating dedicated pathways for space-based FSO. This provides regulatory certainty for LEO constellation operators planning global services. Consequently, investment is shifting towards systems compliant with these new orbital and spectrum rules.
A shift toward managed "Connectivity-as-a-Service" (CaaS) models is gaining traction over direct equipment purchasing by enterprise customers. This approach unbundles high upfront capital costs, making FSO more accessible to smaller operators and businesses. The model is most visible in urban 5G backhaul and campus network deployments in North America and Europe.
Free Space Optics (FSO) Market Segmentation
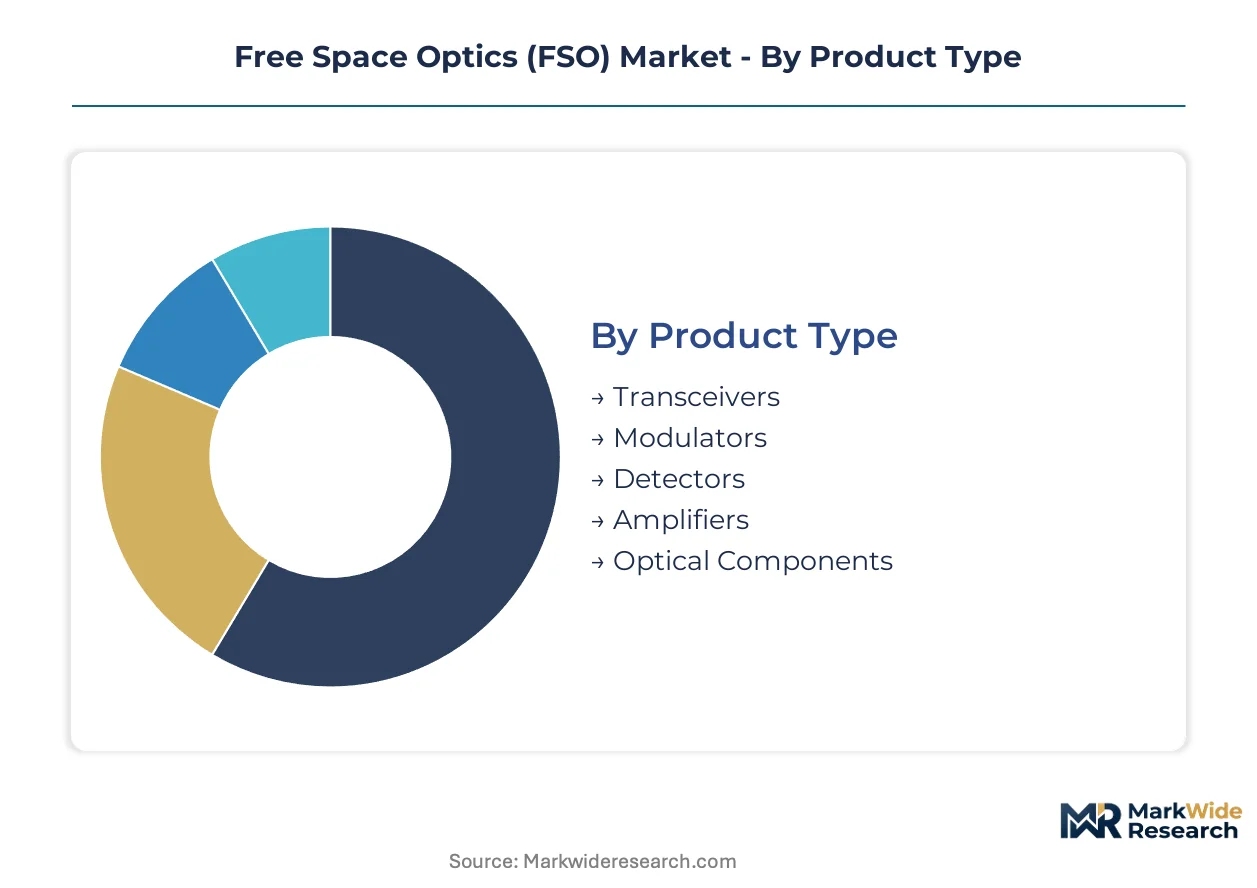
The Free Space Optics market segments reflect the diverse requirements and technological approaches driving its expansion. Understanding these distinctions clarifies the value proposition for various stakeholders and highlights the specialized componentry essential for robust FSO deployments.
Product Type:
The distribution of FSO solutions relies heavily on the integration of various product types, each flowing through specific supply channels to meet diverse operational demands.
- Transceivers:These integrated units combine a laser emitter and a light detector, forming the core communication link. Demand concentrates in 5G backhaul networks for telecom operators, driven by the need for high-speed, rapid deployment solutions.
- Optical Components:This broad category includes lenses, mirrors, beam splitters, and filters that manipulate the light beam. Defense agency projects in the United States drive demand for high-precision, ruggedized optical components for secure military communications.
- Modulators:Devices that encode data onto the laser beam by varying its intensity, phase, or polarization.
- Detectors:Components, typically photodiodes, that convert the received light signal back into electrical data.
- Amplifiers:Optical devices that boost the strength of the light signal, extending link distances in FSO systems.
By volume, Transceivers lead. By growth pace, Optical Components are ahead.
Technology:
Different FSO technology types address distinct performance requirements across varying atmospheric conditions and link distances.
- Infrared:This technology utilizes laser wavelengths around 1550 nm, offering good atmospheric penetration and eye safety. Military communications and long-distance inter-satellite links are primary demand centers, requiring resilient, high-bandwidth connections.
- Laser Diodes:Semiconductor devices that produce the coherent light beam for FSO systems, with advancements improving power efficiency and atmospheric resilience. Telecom operators increasingly integrate advanced laser diodes for reliable 5G urban backhaul.
- Near-Infrared:Operates at slightly shorter wavelengths than infrared, often used for shorter-range terrestrial links.
- Ultraviolet:Employs UV light, which can offer better non-line-of-sight capabilities in certain atmospheric conditions.
- Visible Light Communication:Uses visible light spectrum, often for short-range, high-security indoor or specific outdoor applications.
Infrared technology maintains the broadest installed base, while Laser Diodes show the steepest expansion trajectory.
Application:
Specific FSO applications cater to unique operational needs, dictating the customer profiles and deployment scenarios for each solution.
- Military Communications:FSO provides secure, jam-resistant, high-bandwidth links for tactical and strategic military operations. United States defense agencies are a major driver for innovation in this segment, funding new research and deployments.
- Data Center Interconnects:FSO links provide high-speed, low-latency connectivity between data centers, especially in urban environments where fiber trenching is impractical. Demand comes from large cloud providers and co-location facilities seeking rapid network expansion.
- Building-to-Building Links:Connects adjacent buildings or campuses with high-speed internet without needing underground cables.
- Disaster Recovery:Rapidly deployable FSO systems restore communication links after natural disasters or infrastructure failures.
- Temporary Networks:Provides quick, scalable connectivity for events, construction sites, or remote operations.
Military Communications command significant investment, with Data Center Interconnects expanding most quickly.
End User:
End-user segments drive FSO demand, with each group exhibiting distinct procurement patterns and bandwidth requirements.
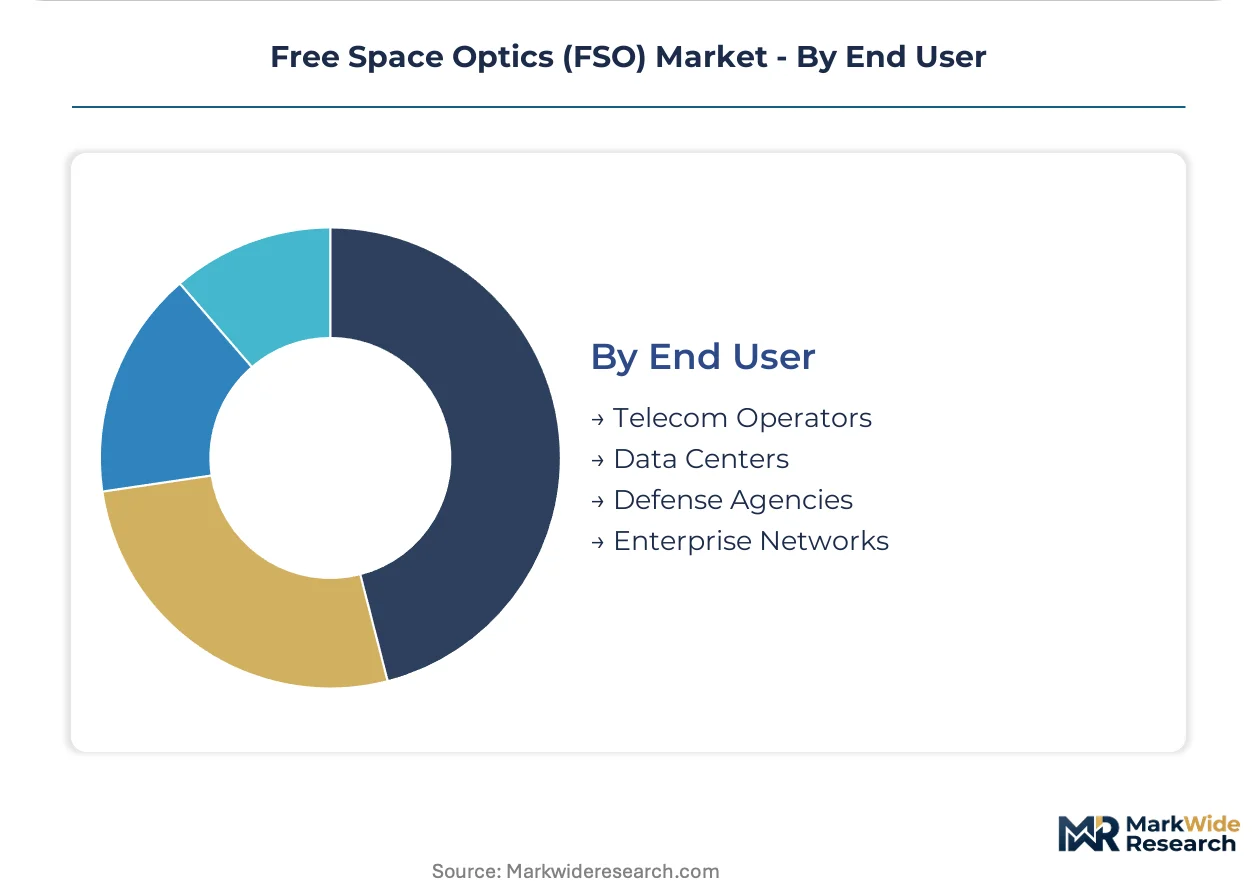
- Telecom Operators:Deploy FSO for 5G backhaul, last-mile connectivity, and network densification, particularly in urban areas. Demand is concentrated in North America and Europe, where 5G rollout is aggressive.
- Defense Agencies:Utilize FSO for secure, high-throughput communication in air, space, and ground-based military operations. The US Department of Defense remains a primary end-user, driving requirements for advanced FSO systems.
- Data Centers:Implement FSO for high-speed, point-to-point links between facilities.
- Enterprise Networks:Leverage FSO for campus connectivity, disaster recovery, and bridging network gaps.
Defense Agencies represent the highest-value segment, as Telecom Operators gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Free Space Optics market exhibits varying demand elasticity across regions, with defense and aerospace applications demonstrating lower price sensitivity compared to high-volume urban backhaul deployments. Strategic investments in FSO infrastructure are concentrated in geographies with advanced telecommunications networks and significant military modernization programs. Regulatory frameworks and local industry clusters influence deployment patterns.
United States
United States defense agencies drive substantial demand for secure, jam-resistant FSO systems in military communications and aerospace. The US Federal Communications Commission (FCC) allocates spectrum for space-based FSO, providing regulatory certainty for satellite operators. Silicon Valley and aerospace hubs in California and Texas remain centers for FSO research and development, attracting private aerospace ventures.
Germany
Germany's industrial base and telecom operators increasingly deploy FSO for 5G network densification and industrial campus connectivity. The European Telecommunications Standards Institute (ETSI) influences equipment standards, ensuring interoperability across European markets. Munich and Berlin host significant FSO research institutions and technology companies, fostering innovation in adaptive optics and laser diode design.
China
China's rapid 5G network expansion fuels demand for FSO as a cost-effective alternative for backhaul and last-mile connectivity. The Ministry of Industry and Information Technology (MIIT) governs network access and equipment approval, shaping the domestic market. Technology centers in Shenzhen and Beijing are developing indigenous FSO solutions, focusing on both terrestrial and satellite applications.
Japan
Japan leverages FSO for disaster recovery and high-bandwidth data center interconnects, driven by its advanced telecom infrastructure. The Ministry of Economy, Trade and Industry (METI) supports research into resilient communication technologies, including FSO for critical infrastructure. Tokyo and Osaka urban centers utilize FSO for building-to-building links, overcoming fiber deployment challenges.
India
India's digital transformation initiatives and aggressive 5G rollout create opportunities for FSO in bridging last-mile connectivity gaps. The Telecom Regulatory Authority of India (TRAI) supports wireless solutions for expanding internet access in underserved areas. Bangalore and Hyderabad, major IT and telecom hubs, see FSO deployments for enterprise connectivity and temporary network solutions.
Free Space Optics (FSO) Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the Free Space Optics market, creating a tiered competitive structure. Specialized firms focus on high-performance, resilient solutions for niche applications, while broader telecommunications equipment providers target volume deployments. The market fragments across these specialized and generalist approaches, with strategic partnerships and R&D investment in atmospheric resilience emerging as dominant competitive moves.
Among specialized providers, Mynaric AG represents the aerospace and satellite communication segment, offering capital-intensive laser communication terminals. LightPointe Communications exemplifies expertise in established terrestrial applications, such as building-to-building links. fSONA Networks sits within the ground-based segment, providing solutions for enterprise last-mile connectivity, often competing directly with fiber optic alternatives for specific deployments.
| Leading Market Players |
|---|
| AOptix Technologies |
| EC System |
| Trimble |
| Anova Technologies |
| Mynaric AG |
| fSONA Networks |
| Wireless Excellence |
| Mostcom |
| LightPointe Communications |
| Others |
Cost & Logistics Intelligence
Fiber optic cable substitution by FSO technology reshapes both network deployment strategies and the cost economics of last-mile connectivity. This dynamic influences component sourcing and final system pricing across various FSO applications.
Pricing Analysis
After-sales service contracts for FSO systems drive significant lifetime value, especially for defense agencies. The dominant pricing model is project-based, reflecting customization for military communications and satellite constellations. Price differentiation stems from performance specifications, such as atmospheric resilience, and certification levels for eye safety regulations like IEC 60825. Pricing pressure stems from fiber optic competition in terrestrial applications, making telecom operators highly price-sensitive, while defense agencies show lower sensitivity for mission-critical systems.
Supply Chain Analysis
Inbound logistics costs, particularly for high-precision optical components, impact the FSO supply chain. Geographic supply concentration for advanced laser diodes and specialized optics centers on Germany, the United States, and Japan. Raw material dependencies include rare earth elements for laser diodes and high-purity glass for lenses. Single-source vulnerability for specific critical components presents a key supply chain risk. Distribution runs through specialized integrators and direct sales channels to defense agencies and telecom operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Free Space Optics market represents a high-growth disruption, driven by the technological inflection of resilient laser diodes and the regulatory certainty for LEO satellite constellations. This creates significant strategic opportunities across various end-user segments.
For Market Incumbents: Compound existing expertise in adaptive optics and robust laser technology to mitigate atmospheric attenuation, a primary threat. Develop hybrid RF/FSO systems through strategic partnerships to offer all-weather reliability, addressing market restraints. Invest in advanced R&D for inter-satellite links, leveraging established relationships with defense agencies. This strategy solidifies market position against emerging specialized FSO providers.
For New Entrants and Emerging Players: Differentiate on cost-effectiveness for last-mile connectivity in underserved urban areas, targeting enterprise networks. Focus on rapid deployment solutions for temporary networks and disaster recovery, where fiber installation is impractical. The most penetrable segment remains 5G backhaul in developing regions like India, offering a strong go-to-market angle. Emphasize managed Connectivity-as-a-Service (CaaS) models to reduce upfront capital costs for smaller operators.
For Investors and Strategic Acquirers: The market sits at an early-growth phase that favors specialized technology developers with proven atmospheric resilience. Long-term viability depends on achieving interoperability standards between terrestrial and satellite systems. Acquisition targets include agile firms specializing in adaptive optics or hybrid RF/FSO solutions. The signal to watch is the widespread commercial deployment of inter-satellite links within LEO constellations, indicating scalability beyond defense applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid RF/FSO System Development | Integrates FSO's bandwidth with RF's all-weather reliability for telecom operators. |
| Adaptive Optics Integration | Enhances atmospheric resilience for high-value military communications and LEO satellite links. |
| Inter-Satellite Link R&D | Positions for the emerging high-speed data backbone market within LEO constellations. |
| Connectivity-as-a-Service Offering | Reduces upfront capital costs, making FSO more accessible to enterprise customers. |
| Eye Safety Standard Compliance | Ensures market access and design adherence to regulations like IEC 60825 for global deployment. |
Research Approach
A standing panel of FSO engineers, telecom operators, defense procurement specialists, and optical component manufacturers provided ongoing calibration for this analysis. Primary interviews with these industry stakeholders were triangulated with extensive secondary validation. Secondary sources included FCC filings, ETSI standards documents, MIIT reports, and aerospace industry publications. This approach ensured robust bottom-up and top-down data consistency.
All quantitative outputs were validated against external benchmarks and prior FSO market studies across the analysis window. The analytical framework modeled segmentation by product type, technology, application, end-user, and regional demand. Compound annual growth rates were derived from historical trends and projected technological advancements. Key forecast inputs included 5G rollout projections and defense spending allocations.
The analysis sits within stated boundaries; outcomes outside significant atmospheric interference breakthroughs or major regulatory shifts would require recalibration. Forecasts reflect assumptions concerning current technological trajectories and market adoption rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Conditional Access System (CAS) Market
Others
Global Retail Media Networks Market
Others
Plastic Films and Sheets Market
Others
Gym Wipes Market
Others
Vegetable Carbon Market
Others
Infant Positioning Aids Market
Others
Finished Leather Market
Others
Asia-Pacific 3D Printing Construction Market
Others
Content Experience Platforms Market
Others
Legal Services Market
Others
Fresh Apples Market
Others
Military Wearable Market
Others
Biopharma Plastics Market
Others
Global Military Wearable Sensors Market
Others
Canada Feed Additives Market
Others
IoT Testing Market