
 Dry Washer Market | 2026-2036
Dry Washer Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Washer Market Foresight
Electrostatic separation and precision airflow engineering is reconfiguring dry washer performance benchmarks across the mining sector. Alliance Laundry Systems leverages its industrial equipment heritage to anchor commercial-grade dry processing platforms. Electrolux Professional competes through European engineering standards in high-efficiency separation systems. JENSEN-GROUP specializes in automated material handling integration that extends operational uptime in remote installations.
A dry washer is a gravity-based mineral processing device that uses forced air and mechanical vibration to separate denser particles from lighter gangue without water, typically operating with airflow rates between 100-400 CFM and deck angles adjustable from 5 to 15 degrees for optimal stratification. The technology serves gold recovery and sand separation applications where water access is limited or prohibited. Industrial dry washers dominate the product landscape due to their throughput capacity in continuous mining operations. Airflow separation technology leads the technology dimension because of its lower energy footprint compared to cyclonic alternatives, though cyclonic separation is gaining traction in waste management applications where fine particulate capture is critical.
MSHA ventilation standards and EPA particulate matter regulations constrain equipment design by mandating dust containment and operator exposure limits. ISO 14001 environmental management frameworks shape procurement criteria for multinational mining companies operating across multiple jurisdictions. Stakeholders must monitor evolving water-use restrictions and carbon intensity disclosures as these criteria increasingly determine equipment qualification and site licensing outcomes.
Market Dynamics
Water scarcity mandates and EPA dust emission standards are compressing equipment procurement cycles, forcing mining operators to prioritize zero-water separation systems that simultaneously satisfy MSHA ventilation requirements and ISO 14001 environmental frameworks.
Growth Catalysts
- Arid-region mining expansion:Operations in Nevada, Western Australia, and Northern Cape Province depend on dry processing infrastructure where aquifer depletion prohibits wet separation methods.
- MSHA workplace safety enforcement:Underground ventilation standards mandate dust containment systems that accelerate replacement of legacy equipment with sealed-airflow designs.
- Electrostatic separation maturation:Precision charge-differential technology now achieves recovery rates competitive with water-based sluice systems in fine gold applications.
Market Restraints
- Steel and aluminum input volatility:Deck fabrication and blower housing costs fluctuate with commodity metal indices, compressing OEM margins on fixed-price contracts.
- Component supply concentration:High-efficiency centrifugal blowers source primarily from German and Chinese manufacturers, creating single-source vulnerability for North American fabricators.
- Fine particulate capture limitations:Sub-50-micron gold recovery remains below wet separation yields, restricting adoption in high-grade refractory deposits.
Strategic Opportunities
- Copper belt expansion:Zambian and Chilean operations face glacial retreat and seasonal water restrictions that favor dry pre-concentration stages.
- Solar-powered remote installations:Photovoltaic-battery integration eliminates diesel generator dependence, cutting operating costs at off-grid placer sites.
- E-waste precious metal recovery:Circuit board shredding operations require dry density separation to avoid aqueous contamination of mixed-plastic streams.
Industry Challenges
- Specialized technician scarcity:Electrostatic calibration and airflow engineering expertise concentrates in mining equipment OEMs, limiting third-party maintenance capacity.
- Legacy system integration friction:Retrofitting sealed-deck designs into existing crushing circuits requires structural modifications that extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Washer Market |
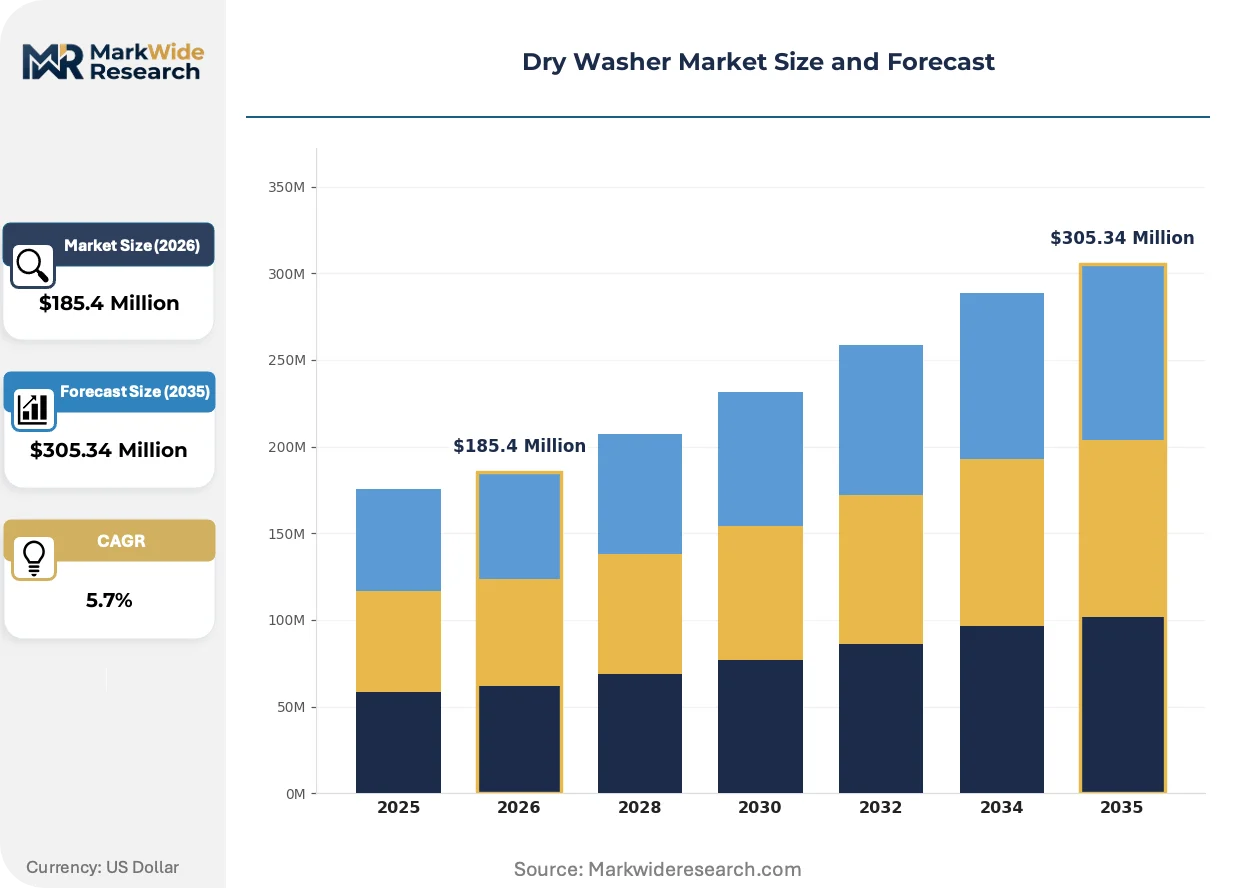
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $305.34 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Dry Washers, Commercial Dry Washers, Industrial Dry Washers, High-Efficiency Dry Washers Application: Gold Recovery, Sand Separation, Waste Management, Mining Operations End User: Mining Companies, Construction Firms, Environmental Agencies, Hobbyists Technology: Airflow Separation, Vibration Mechanism, Cyclonic Separation, Filtration Technology |
| Companies Covered | Alliance Laundry Systems, Electrolux Professional, JENSEN-GROUP, Kannegiesser GmbH, Girbau, Fagor Professional, Danube International, Speed Queen, Dexter Laundry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Washer Market Shifts & Advancements
Forced-air separation technology is converging with sensor-based sorting and renewable power systems, redefining operational economics at water-stressed mining frontiers while regulatory compliance frameworks harden equipment specification requirements.
Pulsed-fluidized bed designs are hybridizing mechanical vibration with precision airflow modulation to achieve stratification previously requiring water density gradients. Tier-one gold producers in Western Australia and Nevada deploy these systems for continuous alluvial processing. The technology is hybridizing capital allocation patterns, enabling mid-scale operators to bypass centralized processing plant investments.
EPA National Ambient Air Quality Standards tightening on PM10 and PM2.5 thresholds mandate baghouse filtration retrofits on dry washer exhaust streams. Mining contractors in Arizona and New Mexico face permit renewal conditions requiring real-time dust monitoring integration. Surface placer operations absorb the steepest compliance costs, accelerating consolidation toward operators with captive environmental engineering capabilities.
Equipment-as-a-service contracting is displacing outright purchase arrangements among junior mining ventures capital-constrained by exploration drilling commitments. Rental providers bundle maintenance and emission compliance monitoring, transferring regulatory liability from operator to lessor. This model penetrates fastest in South Africa's informal artisanal sector, where water-use licensing uncertainties deter capital deployment.
Dry Washer Market Segmentation
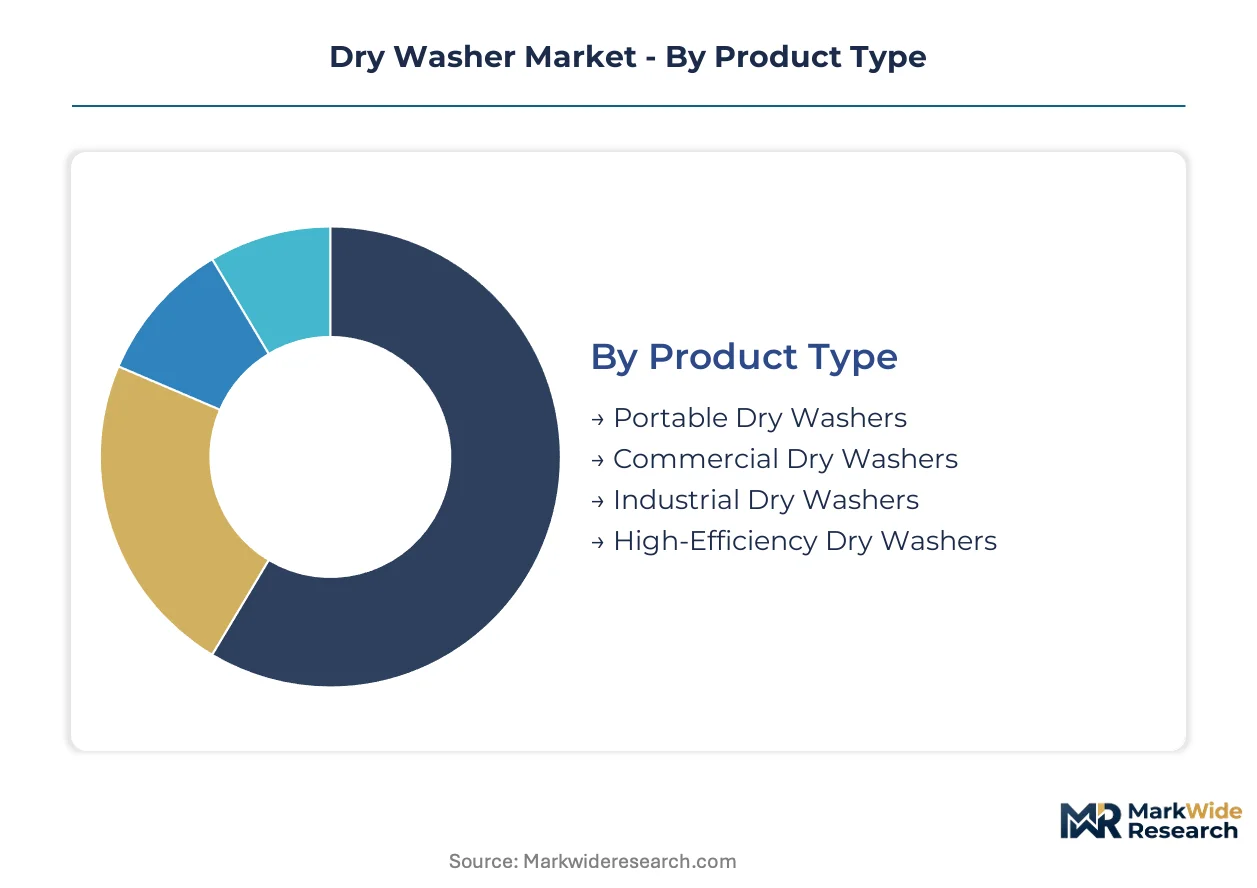
Dry washer procurement patterns diverge sharply across operational scales and regulatory environments. Mining operators select equipment tiers based on throughput requirements, dust containment mandates, and site power infrastructure.
Product Type:
Cost tier stratification determines equipment specifications, fabrication materials, and automation levels across the product spectrum.
- Portable Dry Washers:Compact units weighing under 150 pounds deploy gasoline-powered blowers and fabric decks for remote prospecting. Hobbyists in Arizona's Mohave County and Nevada's Humboldt County drive replacement demand as seasonal gold prices fluctuate.
- Commercial Dry Washers:Mid-scale systems feature steel-framed riffle decks and electric blowers rated for 8-hour continuous operation. Small contractors in Western Australia's Pilbara region favor these units for alluvial patch mining where water trucking costs exceed equipment depreciation.
- Industrial Dry Washers:High-throughput designs integrate sealed airflow circuits and automated feed systems for integration with crushing circuits. EPA dust emission compliance and MSHA ventilation standards mandate these configurations for surface placer operations exceeding 100 tons daily.
- High-Efficiency Dry Washers:Electrostatic-augmented separation achieves recovery rates approaching wet sluice performance on fine gold. Tier-one producers in Nevada's Carlin Trend deploy these systems where refractory ore characteristics justify capital intensity.
Industrial dry washers command the established base. The steepest expansion runs through high-efficiency dry washers.
Application:
Application selection hinges on particle size distribution, target mineral density, and contamination sensitivity of the output stream.
- Gold Recovery:Primary application employs riffle decks and forced-air stratification to isolate dense gold particles from quartz sand and clay aggregates. Arid-region placer deposits in Australia's Victorian Goldfields and South Africa's Barberton Greenstone Belt depend entirely on dry processing infrastructure.
- Sand Separation:Construction aggregate producers use dry washers to remove fines and organic matter from concrete-grade sand. Water-scarce jurisdictions in the southwestern United States specify these systems for compliance with aquifer withdrawal restrictions.
- Waste Management:Cyclonic dry washers pre-sort shredded e-waste and construction debris by density differential. California's electronic waste regulations drive adoption for precious metal recovery from circuit board fractions.
- Mining Operations:Integrated dry pre-concentration reduces haulage volumes to centralized processing plants. Chilean copper-gold porphyry operations deploy these systems at altitude where water freezing and scarcity converge.
Gold recovery commands the established base. The steepest expansion runs through waste management applications.
End User:
Customer type dictates procurement channel, financing structure, and service contract expectations.
- Mining Companies:Integrated operators and junior explorers specify ISO 14001-certified equipment with real-time dust monitoring. Procurement runs through equipment-as-a-service contracts that transfer regulatory liability to lessors.
- Construction Firms:Road building and aggregate supply contractors deploy portable units for on-site sand processing. Seasonal demand peaks align with infrastructure appropriation cycles in water-stressed states.
- Environmental Agencies:Remediation contractors use dry washers for soil washing operations where aqueous treatment would mobilize heavy metals. EPA Superfund site specifications drive specialized equipment configurations.
- Hobbyists:Recreational prospectors purchase entry-level units through specialty retailers and online marketplaces. Price sensitivity concentrates demand in the sub-two-thousand-dollar segment.
Mining companies command the established base. The steepest expansion runs through environmental agencies.
Technology:
Technology selection balances energy consumption, particulate capture efficiency, and maintenance accessibility.
- Airflow Separation:Dominant technology employs adjustable blower systems and riffle deck geometry to create stratified particle beds. Lower energy footprint relative to cyclonic alternatives sustains preference in off-grid solar installations.
- Vibration Mechanism:Mechanical or electromagnetic deck agitation enhances particle mobility across air-fluidized beds. Integration with pulsed-fluidized designs extends recovery efficiency to sub-100-micron fractions.
- Cyclonic Separation:Centrifugal force classification captures fine particulates in vortex separators. Waste management applications favor this technology where dust containment exceeds recovery precision in priority.
- Filtration Technology:Baghouse and cartridge filtration systems treat exhaust streams to EPA PM10 and PM2.5 thresholds. Arizona and New Mexico permit renewals mandate these retrofits on legacy equipment.
Airflow separation commands the established base. The steepest expansion runs through filtration technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mining operators in water-scarce jurisdictions drive equipment procurement decisions. Arid-region gold producers and construction aggregate suppliers concentrate demand in specific national markets where aquifer depletion and dust emission rules intersect.
United States
Nevada's Carlin Trend and Arizona's Mohave County anchor surface placer operations dependent on dry processing infrastructure. EPA National Ambient Air Quality Standards enforcement on PM10 and PM2.5 thresholds mandates baghouse filtration retrofits on legacy equipment. Junior mining ventures in Humboldt County favor equipment-as-a-service contracts that transfer regulatory liability to lessors.
Australia
Western Australia's Pilbara region and Victorian Goldfields host tier-one gold producers deploying pulsed-fluidized bed designs for continuous alluvial processing. The country's environmental protection agencies impose strict dust containment requirements on remote installations. Mid-scale contractors in Kalgoorlie bypass centralized processing plant investments through mobile dry pre-concentration systems.
South Africa
The Barberton Greenstone Belt and Northern Cape Province sustain artisanal and industrial-scale dry processing operations where water licensing uncertainties deter capital deployment. The Department of Mineral Resources and Energy enforces workplace ventilation standards that accelerate sealed-airflow equipment replacement. Informal sector operators in Mpumalanga absorb rental bundles combining maintenance and emission compliance monitoring.
Chile
Copper-gold porphyry operations at altitude in the Atacama face glacial retreat and seasonal water restrictions favoring dry pre-concentration stages. The national mining regulator enforces closure plan requirements that favor zero-water separation technologies. State-owned and private operators in the El Teniente district deploy solar-powered remote installations eliminating diesel generator dependence.
Canada
Construction aggregate producers in Alberta and Saskatchewan deploy portable dry washers for on-site sand processing where aquifer withdrawal restrictions apply. Provincial environmental agencies mandate dust containment systems for surface operations exceeding threshold volumes. Road building contractors in the Prairie Provinces align seasonal equipment demand peaks with infrastructure appropriation cycles.
Dry Washer Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct value-capture tiers. The vendor base organizes around industrial equipment heritage, regional engineering standards, and automated material handling integration capabilities. Three archetypes dominate: diversified industrial conglomerates with laundry-to-mining equipment crossover, European precision engineering specialists, and automated systems integrators focused on operational uptime. Competitive moves concentrate on strategic partnerships for blower component sourcing and geographic expansion into copper belt jurisdictions.
Among diversified industrial equipment providers, Alliance Laundry Systems anchors commercial-grade platform development while Electrolux Professional exemplifies European engineering standards in high-efficiency separation systems. JENSEN-GROUP occupies a position within automated material handling integration specialists serving remote installation requirements. These three entities represent distinct competitive vectors: heritage industrial scale, precision engineering certification, and uptime-focused automation.
| Leading Market Players |
|---|
| Alliance Laundry Systems |
| Electrolux Professional |
| JENSEN-GROUP |
| Kannegiesser GmbH |
| Girbau |
| Fagor Professional |
| Danube International |
| Speed Queen |
| Dexter Laundry |
| Others |
Supply & Pricing Matrix
Single-source dependency on German and Chinese centrifugal blower manufacturers compresses OEM margins while widening pricing spreads between sealed-system industrial units and portable gasoline-powered alternatives. Steel and aluminum commodity indexation in fabrication contracts forces tiered equipment pricing that tracks London Metal Exchange volatility rather than manufacturing efficiency gains.
Pricing Analysis
Cost-plus contracts with LME-linked indexation dominate industrial dry washer procurement, tying deck fabrication and blower housing prices to monthly metal commodity settlements. Three-tier pricing structure across premium, standard, and economy levels separates EPA-certified sealed systems from commercial electric units and portable gasoline models. Pricing pressure stems from fixed-price contract exposure during aluminum price spikes, with junior mining ventures absorbing the steepest cost compression through equipment-as-a-service rentals.
Supply Chain Analysis
Contract-manufacturing concentration rests on German blower specialists and Chinese foundries for centrifugal impeller production, with North American fabricators dependent on trans-Pacific component flows. Deck fabrication draws from domestic steel service centers while electrostatic separation modules source from Taiwanese electronics assemblers. Single-source vulnerability in high-efficiency blower supply creates procurement risk, with distribution running through mining equipment OEMs and specialized rental providers serving remote installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrostatic calibration expertise and sealed-system engineering capability concentrate among incumbent OEMs, creating defensive moats that new entrants must bridge through targeted capability acquisition or partnership structures.
For Market Incumbents: Insulate margin position by deepening captive production of blower housings and riffle deck assemblies to offset commodity indexation exposure. Secure MSHA pre-certification for next-generation sealed airflow designs before EPA dust emission standards tighten, locking in replacement cycles among surface placer operators facing permit renewal conditions.
For New Entrants and Emerging Players: Build out aftermarket service networks in South Africa's informal artisanal sector where rental bundling transfers regulatory liability and equipment-as-a-service penetration runs highest. Target environmental agency remediation contractors with specialized soil washing configurations, leveraging ISO 14001 certification gaps among incumbent mining-focused suppliers.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors automated material handling specialists with remote installation uptime capabilities. Long-term viability hinges on solar-power integration and electrostatic separation maturation as water scarcity mandates harden across copper belt jurisdictions. Watch EPA National Ambient Air Quality Standards enforcement intensity as the signal for accelerated sealed-system replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blower Manufacturing | Captive production of centrifugal impellers insulates margins from German and Chinese supply concentration. |
| Solar-Powered Remote Installation Development | Photovoltaic-battery integration eliminates diesel dependence at off-grid placer sites in Nevada and Western Australia. |
| Electrostatic Separation Technology Licensing | Precision charge-differential recovery systems close the gap with wet sluice performance on sub-50-micron gold fractions. |
| Equipment-as-a-Service Platform Expansion | Rental bundling transfers MSHA and EPA regulatory liability from capital-constrained junior miners to lessors. |
| Copper Belt Geographic Market Entry | Dry pre-concentration stages gain traction in Chilean and Zambian operations facing glacial retreat and seasonal water restrictions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of MSHA enforcement records, EPA permit renewal databases, and mining equipment trade flow data. Mining operations directors, plant engineers at surface placer sites, and aftermarket service managers provided operational perspective on equipment performance and downtime patterns. OEM procurement teams and rental fleet managers supplied contract structure and pricing intelligence. Bottom-up equipment shipment tracking triangulates against top-down mining capital expenditure surveys across Nevada, Western Australia, and South Africa.
Forecast inputs incorporate product type segmentation across portable, commercial, industrial, and high-efficiency tiers; application splits between gold recovery, sand separation, waste management, and mining operations; and technology dimensions spanning airflow separation, vibration mechanism, cyclonic separation, and filtration systems. CAGRs derive from regression analysis of historical equipment deployment against water scarcity indices and regulatory enforcement intensity. Electrostatic separation maturation curves and solar-power adoption rates at remote installations inform technology transition assumptions across the modeling period.
Stress conditions across aluminum price volatility, blower component lead times, and EPA PM2.5 threshold enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding MSHA ventilation standard continuity and copper belt water licensing trajectories. Quarterly review of metal commodity indices and EPA regional enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Europe Virtual Reality Gaming Market
Others
North America Compressor Oil Market
Others
Spend Analytics Market
Others
Europe Battery Packaging Market
Others
Global Smart Devices Market
Others
HPHT Diamond Cubic Press Market
Others
Global Learning Analytics Market
Others
Belt Loader Market
Others
Asia Pacific Automotive LED Lighting Market
Others
Saudi Arabia Cat Food Market
Others
North America Astrology Market
Others
Industrial Computers Market
Others
Lightweight Compact Wheel Loader Market
Others
Ambient Assisted Living and Smart Home Market
Others
Cloud Digital Video Recorder Market
Others
Egg and Egg Products Market