
 Fermented Plant-Based Ingredient Market | 2026-2036
Fermented Plant-Based Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Fermented Plant-Based Ingredient Market Insights
The split between premium artisanal cultures and commodity-grade fermented inputs is repositioning procurement strategies across the value chain. DuPont leverages its microbial strain libraries to command premium positioning in high-activity fermentation cultures. Cargill anchors large-scale supply through backward integration into soybean processing and captive fermentation infrastructure. Chr. Hansen competes on strain-specific intellectual property, differentiating its catalog by documented health-benefit profiles rather than commodity specifications.
Fermented plant-based ingredients comprise proteins, peptides, organic acids, and bioactive metabolites produced through controlled microbial fermentation of legumes, grains, or oilseeds, typically requiring pH monitoring, temperature control between 30-42°C, and 24-72 hour incubation cycles to achieve target enzymatic conversions and flavor development. These inputs function primarily as texturizers, umami enhancers, and nutritional fortifiers in industrial food manufacturing. Fermented soy occupies the largest existing volume pool within product type segmentation, while tempeh-derived concentrates capture expanding margin pools in meat substitute applications. Dried powders dominate current form-based shipments due to logistical efficiency, though liquid extracts are gaining traction among sauce and dairy alternative manufacturers seeking cleaner-label dissolution properties.
FDA oversight of fermentation-derived food ingredients through GRAS self-determination pathways and EFSA novel food assessments under EU Regulation 2015/2283 create divergent compliance burdens that shape market entry timelines and documentation costs for suppliers. ISO 22000 and FSSC 22000 certifications function as baseline qualifiers for commercial relationships with multinational food manufacturers, effectively filtering smaller fermentation houses from tier-one supply agreements. Stakeholders must monitor evolving strain editing regulations, as precision-fermentation techniques using genetically modified microorganisms face distinct approval trajectories across jurisdictions that will determine competitive moats in next-generation ingredient development.
Market Dynamics
The split between artisanal fermentation cultures and commodity-grade inputs is forcing procurement teams to dual-source across strain libraries and bulk soybean processors. This structural tension between premium positioning and volume anchoring reshapes supplier relationships and margin capture across the value chain.
Growth Catalysts
- EFSA novel food assessments:Clearer approval pathways under EU Regulation 2015/2283 accelerate market entry timelines for precision-fermented ingredients, reducing documentation uncertainty for European suppliers.
- Meat substitute manufacturers:Tempeh-derived concentrates command expanding margin pools as formulators seek texturizers that deliver clean-label dissolution without synthetic additives.
- Berlin fermentation clusters:Dedicated capacity buildouts by German startups and established ingredient houses concentrate technical expertise and strain development capabilities in a single metropolitan hub.
Market Restraints
- Soybean input volatility:Commodity price swings in oilseed markets compress margins for fermentation houses lacking backward integration into captive soybean processing infrastructure.
- Strain editing approval divergence:Genetically modified microorganisms face distinct regulatory trajectories across FDA GRAS self-determination and EFSA frameworks, fragmenting R&D investment and commercialization timelines.
- Enzymatic conversion ceilings:Current pH monitoring and temperature control systems hit throughput limits at 72-hour incubation cycles, constraining batch economics for high-volume dairy alternative contracts.
Strategic Opportunities
- Liquid extract formats:Sauce and dairy alternative manufacturers are pivoting from dried powders to liquid concentrates that dissolve without emulsifier labels, opening premium positioning in clean-label formulations.
- ISO 22000 certification gaps:Smaller fermentation houses without FSSC 22000 or ISO 22000 credentials are filtered from tier-one supply agreements, creating acquisition targets for mid-cap players seeking instant compliance infrastructure.
- Umami enhancement applications:Bioactive metabolites from controlled fermentation are penetrating savory snack and ready-meal segments beyond traditional meat and dairy substitutes, diversifying addressable end-use verticals.
Industry Challenges
- Strain-specific IP enforcement:Documented health-benefit profiles require costly patent landscaping and licensing negotiations, particularly for catalog entries competing on microbial strain libraries rather than commodity specifications.
- Legacy system integration:Temperature control and pH monitoring hardware from incumbent fermentation infrastructure often lacks API compatibility with modern batch analytics platforms, forcing expensive retrofit cycles.
- Documentation cost inflation:GRAS self-determination pathways demand escalating toxicology and exposure assessment investments, squeezing smaller suppliers with limited regulatory affairs headcount.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermented Plant-Based Ingredient Market |
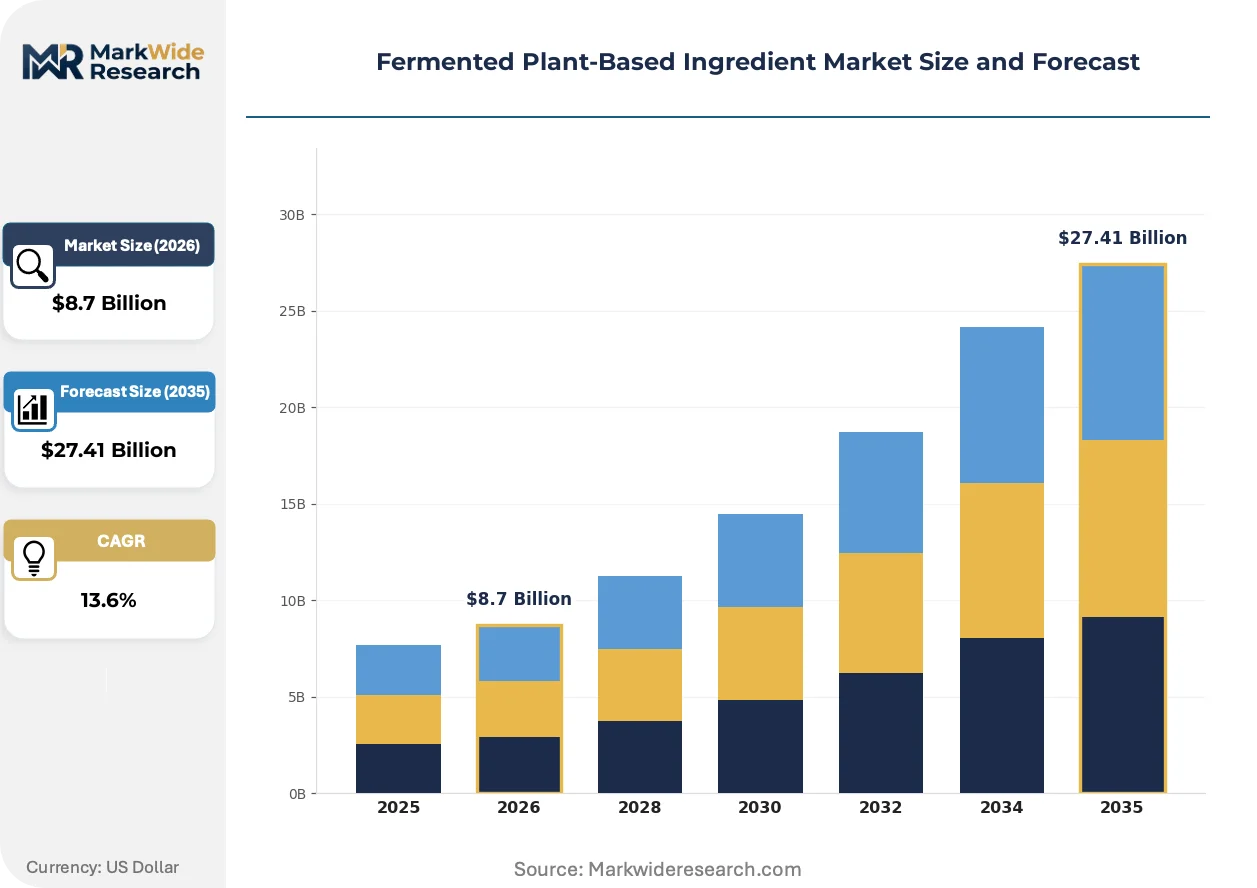
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $27.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fermented Soy, Tempeh, Miso, Fermented Rice Application: Dairy Alternatives, Meat Substitutes, Sauces, Snacks End User: Food Manufacturers, Retail Chains, Restaurants, Home Cooks Form: Dried Powders, Liquid Extracts, Concentrates, Granules |
| Companies Covered | DuPont, Cargill, BASF, Chr. Hansen, Angel Yeast, Lallemand, Kerry Group, Evonik, Arla Food Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermented Plant-Based Ingredient Market Trends and Innovations
Controlled microbial fermentation is absorbing capital and technical talent from adjacent bioprocessing sectors as food manufacturers seek alternatives to synthetic texturizers. The convergence of strain engineering, process analytics, and clean-label marketing is compressing development cycles and reshaping competitive positioning.
Precision fermentation using metabolically optimized microbial chassis is absorbing development resources previously allocated to enzymatic extraction methods. Dairy alternative formulators in Germany and the Netherlands are adopting these platforms at pilot scale, compressing time-to-market for novel protein concentrates while forcing legacy suppliers to defend commodity positions.
REACH chemical safety registrations and impending CSRD sustainability disclosures are tightening documentation requirements for fermentation-derived inputs entering European supply chains. Industrial food manufacturers are responding by pre-qualifying suppliers with completed EFSA novel food dossiers, effectively front-loading compliance investment and filtering smaller strain developers from strategic partnerships.
Direct procurement relationships between end-use manufacturers and dedicated fermentation facilities are displacing traditional ingredient distributor networks. Clean-label dairy alternative producers in Scandinavia are negotiating volume commitments directly with Berlin-based fermentation houses, capturing margin previously allocated to intermediaries while forcing distributors to reposition around technical service and formulation support.
Fermented Plant-Based Ingredient Market Segmentation
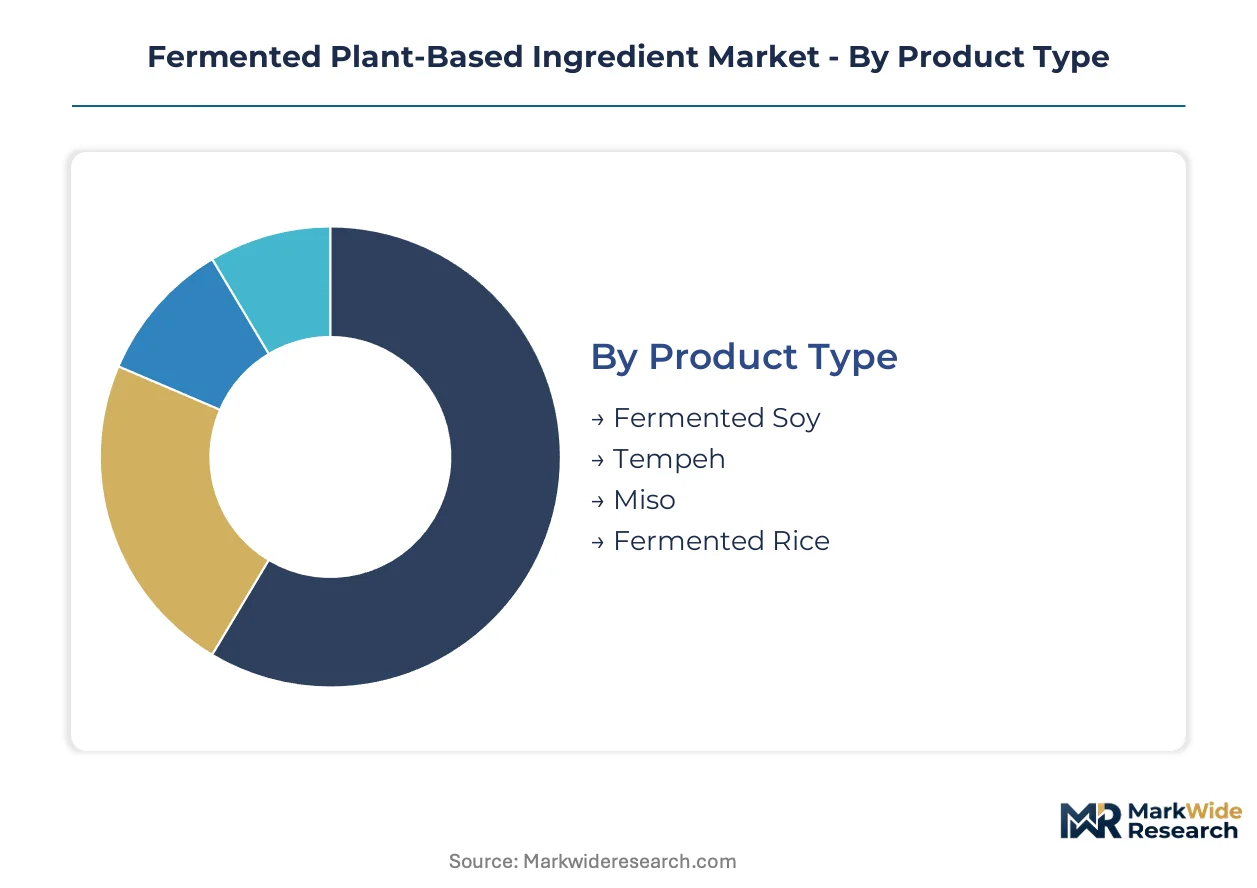
Fermented plant-based ingredient procurement splits across technical specifications, application requirements, and supply chain configurations. Each segmentation axis reveals distinct margin structures and supplier qualification criteria that shape commercial relationships.
Product Type:
Strain libraries and substrate compatibility define the technology axis across fermentation categories.
- Fermented Soy:Proteins, peptides, and organic acids produced through controlled microbial fermentation of soybeans with pH monitoring and 30-42°C temperature control. Food manufacturers in Germany and the Netherlands anchor volume demand for dairy alternative formulations seeking texturizers with documented enzymatic conversion profiles.
- Tempeh:Whole-culture fermentation using Rhizopus oligosporus on dehulled soybeans, delivering intact mycelial matrices that bind water and fat in meat substitute applications. Berlin-based startups concentrate technical expertise here, capturing expanding margin pools as clean-label formulators reject synthetic binders.
- Miso:Long-culture fermentation of soybeans with Aspergillus oryzae, yielding umami-rich pastes and concentrates. Japanese and Korean restaurant chains drive specialty procurement for soup bases and marinades.
- Fermented Rice:Koji-based fermentation of rice substrates, producing amylase-rich cultures for sauce applications and alcoholic beverage adjacents. Southeast Asian food manufacturers represent the primary demand concentration.
Fermented soy leads on scale; tempeh leads on momentum.
Application:
Functional requirements and dissolution properties segment demand by end-use formulation.
- Dairy Alternatives:Liquid extracts and concentrates with clean-label dissolution properties. Scandinavian manufacturers negotiate direct procurement relationships with fermentation houses, bypassing distributor networks to capture margin.
- Meat Substitutes:Tempeh-derived concentrates and textured fermented proteins. EFSA novel food assessments under EU Regulation 2015/2283 accelerate approval timelines for precision-fermented texturizers entering European formulations.
- Sauces:Miso and fermented rice derivatives delivering umami enhancement without synthetic additives. Liquid formats gain traction among manufacturers seeking cleaner-label declarations.
- Snacks:Dried powders and granules for seasoning applications. Bioactive metabolites from controlled fermentation penetrate savory snack segments beyond traditional meat and dairy substitutes.
Dairy alternatives command the largest volume commitments; meat substitutes exhibit the steepest expansion trajectory.
End User:
Procurement scale and technical service requirements stratify the customer base.
- Food Manufacturers:Multinational processors with ISO 22000 and FSSC 22000 pre-qualification requirements. Tier-one supply agreements filter smaller fermentation houses lacking certification infrastructure.
- Retail Chains:Private-label dairy alternative and meat substitute programs. Direct procurement relationships with dedicated fermentation facilities displace traditional ingredient distributor networks.
- Restaurants:Specialty miso and artisanal fermentation cultures for menu differentiation. Premium positioning depends on documented strain-specific health-benefit profiles.
- Home Cooks:Small-format dried powders and starter cultures. E-commerce channels and specialty retailers serve this fragmented demand pool.
Food manufacturers dominate procurement scale; retail chains are gaining share fastest through private-label expansion.
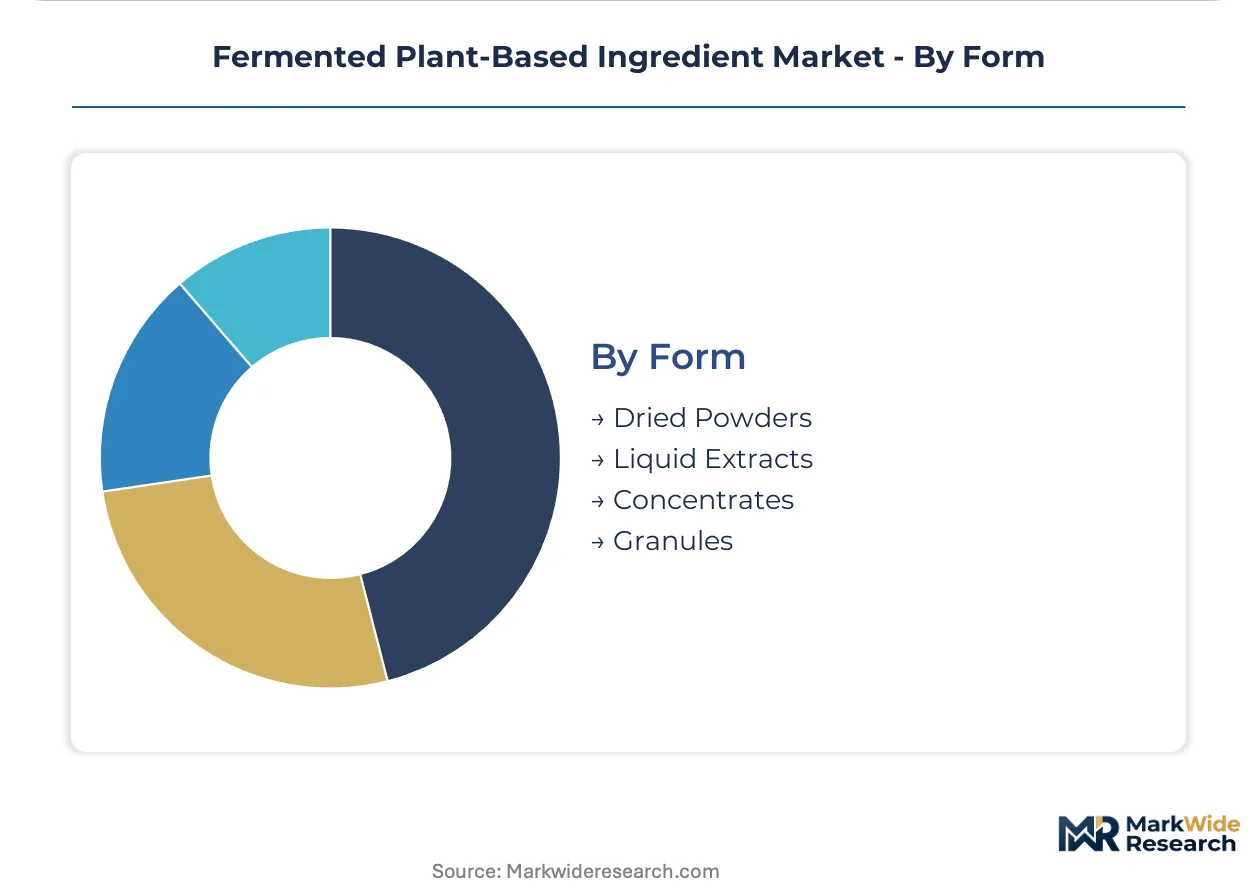
Form:
Logistical efficiency and dissolution behavior create distinct margin tiers.
- Dried Powders:Spray-dried or freeze-dried fermentation outputs with extended shelf stability. Current form-based shipments concentrate here due to transportation economics and storage convenience.
- Liquid Extracts:Aqueous concentrates dissolving without emulsifier labels. Sauce and dairy alternative manufacturers pivot toward this format for clean-label positioning.
- Concentrates:High-solids preparations requiring refrigerated supply chains. Tempeh-derived variants capture premium pricing in meat substitute texturization.
- Granules:Agglomerated powders for controlled dissolution in seasoning applications. Snack manufacturers favor this format for uniform coating distribution.
Dried powders anchor existing logistics infrastructure; liquid extracts lead on format innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized fermentation scientists and process engineers concentrate in metropolitan clusters across Germany, the Netherlands, and Scandinavia, drawing talent from adjacent biotech and brewing industries. These workforce pools anchor Europe's dominant position in precision-fermented ingredient development.
Germany
Berlin-based startups and established ingredient houses build dedicated fermentation capacity for tempeh-derived concentrates and dairy alternative texturizers. EFSA novel food assessments under EU Regulation 2015/2283 accelerate approval timelines for precision-fermented ingredients entering European formulations. The Berlin-Brandenburg metropolitan region concentrates strain development capabilities and pilot-scale facilities serving Scandinavian dairy alternative manufacturers.
United States
Food manufacturers scale purchases of fermented soy inputs for plant-based dairy formulations, particularly in California and the Midwest. FDA GRAS self-determination pathways create distinct compliance burdens compared to European frameworks, fragmenting R&D investment timelines. The Greater Boston area hosts microbial strain libraries and precision-fermentation startups competing on documented health-benefit profiles.
Netherlands
Dairy alternative formulators adopt precision-fermentation platforms at pilot scale, compressing time-to-market for novel protein concentrates. REACH chemical safety registrations tighten documentation requirements for fermentation-derived inputs entering European supply chains. The Eindhoven Region and Randstad corridor concentrate technical expertise in process analytics and clean-label dissolution technologies.
China
Domestic food manufacturers expand procurement of fermented rice and traditional koji-based cultures for sauce and beverage applications. SAMR oversight of novel food ingredients creates approval trajectories distinct from FDA and EFSA frameworks. The Yangtze River Delta anchors large-scale fermentation infrastructure serving both domestic consumption and export markets.
Denmark
Clean-label dairy alternative producers negotiate direct procurement relationships with fermentation houses, bypassing traditional distributor networks. CSRD sustainability disclosures tighten documentation requirements for ingredient suppliers entering Nordic supply chains. Copenhagen's fermentation cluster specializes in high-activity cultures and strain-specific intellectual property development.
Fermented Plant-Based Ingredient Market Competitive Landscape
Top-tier vendors anchor premium positioning through microbial strain libraries and documented health-benefit profiles, while commodity-grade processors compete on backward integration into soybean processing and captive fermentation infrastructure. The vendor base splits between precision-fermentation specialists and legacy bulk suppliers. Three archetypes dominate: strain-library owners, integrated agribusinesses with captive infrastructure, and mid-cap players acquiring compliance certifications. Competitive moves concentrate on M&A for ISO 22000 credentialing and direct procurement relationships displacing distributor networks.
Within the integrated agribusiness tier, Cargill exemplifies scale-driven positioning through upstream control over substrate supply and fermentation capacity. DuPont anchors premium-tier competition leveraging extensive microbial strain libraries. Chr. Hansen occupies a position defined by strain-specific intellectual property and documented health-benefit differentiation rather than commodity specifications.
| Leading Market Players |
|---|
| DuPont |
| Cargill |
| BASF |
| Chr. Hansen |
| Angel Yeast |
| Lallemand |
| Kerry Group |
| Evonik |
| Arla Food Ingredients |
| Others |
Pricing and Supply Chain Analysis
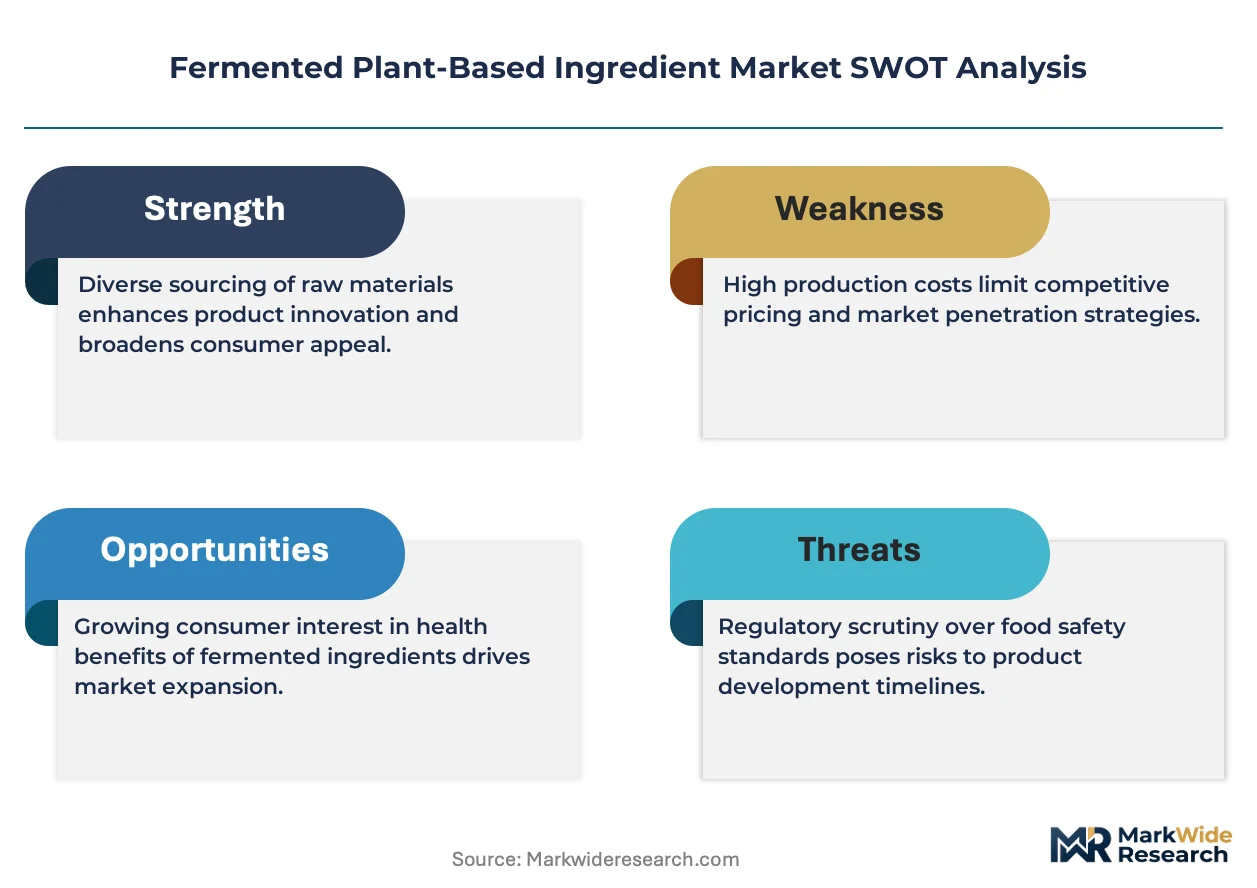
Soybean input costs cascade through three distinct pricing tiers as fermentation houses with backward integration into captive processing infrastructure capture margin pools unavailable to strain-library competitors sourcing on spot markets.
Pricing Analysis
Bundled technical service and strain-specific intellectual property commands premium positioning, while unbundled commodity-grade fermented inputs compete on volume scale. Three-tier pricing structure across premium, standard, and economy levels separates documented health-benefit profiles from generic enzymatic conversion specifications. Cost compression in commodity-grade tempeh concentrates is intensifying because Berlin-based startups scale dedicated fermentation capacity. Retail chains negotiating direct procurement relationships exhibit highest price sensitivity; precision-fermentation specialists with proprietary microbial chassis show least.
Supply Chain Analysis
ISO 22000 and FSSC 22000 certifications function as gating mechanisms that filter smaller fermentation houses from tier-one supply agreements with multinational food manufacturers. Germany, the Netherlands, and Denmark anchor supply concentration for precision-fermented ingredients. Raw material flows draw from soybean processors in the US Midwest, tempeh culture substrates in Southeast Asia, and koji-based rice fermentation inputs in China. Single-source vulnerability in Rhizopus oligosporus strain supply creates structural risk. Distribution runs through direct procurement relationships displacing traditional ingredient distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where Scandinavian dairy alternative manufacturers pivot toward liquid extract formats with clean-label dissolution properties, forcing suppliers to defend position on documented enzymatic conversion profiles rather than commodity specifications.
For Market Incumbents: Anticipate margin compression in dried powder formats as precision-fermentation startups in Berlin and Copenhagen capture premium positioning in liquid concentrates. Defend market position by deepening backward integration into soybean processing infrastructure and accelerating FSSC 22000 certification coverage across captive facilities.
For New Entrants and Emerging Players: EFSA novel food assessments under EU Regulation 2015/2283 in Germany open a window for precision-fermented texturizers entering meat substitute formulations. Target white-space in tempeh-derived concentrates for clean-label meat applications and liquid extract formats for sauce manufacturers. Pursue go-to-market through direct procurement relationships with Scandinavian retail chains bypassing distributor networks.
For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 22000 certification gaps exclude smaller fermentation houses from tier-one supply agreements. Long-term viability favors mid-cap players with completed EFSA novel food dossiers and established strain development capabilities. Signal to monitor: regulatory divergence on genetically modified microorganism approvals fragmenting R&D investment trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Soybean Processing | Cargill's captive infrastructure model insulates margin from commodity price swings in oilseed markets. |
| Precision-Fermentation Platform Scale-Up | DuPont leverages microbial strain libraries to compress time-to-market for novel protein concentrates. |
| EFSA Novel Food Dossier Completion | Chr. Hansen's documented health-benefit profiles differentiate catalog entries from commodity specifications. |
| Liquid Extract Format Development | Berlin-based fermentation houses capture premium positioning in clean-label dairy alternative formulations. |
| Direct Procurement Relationship Establishment | Scandinavian manufacturers bypass distributor networks to capture margin previously allocated to intermediaries. |
Research Methodology
Bottom-up fermentation capacity modeling reconciled against top-down soybean input tracking forms the analytical core of this study. Primary interviews with fermentation scientists, procurement leads at multinational food manufacturers, regulatory affairs specialists, and strain development directors combined with secondary validation against EFSA novel food submission databases, FDA GRAS notification filings, customs trade data on fermented ingredient shipments, and ISO 22000 certification registries. Triangulation between demand-side volume commitments and supply-side capacity buildouts ensures cross-verification of market sizing assumptions.
Historical trendline analysis of fermented ingredient pricing and volume trajectories established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product type, application vertical, form factor, and end-user procurement scale. CAGRs were derived from curve-fitting techniques applied to disclosed capacity expansions and volume commitments. Forecast inputs incorporate EFSA approval timelines, precision-fermentation platform adoption rates, and clean-label dissolution technology penetration in dairy alternative formulations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under strain editing regulatory divergence and soybean commodity price volatility. Model outputs reflect assumptions on incubation cycle throughput limits and certification pre-qualification thresholds. A model refresh is warranted upon material change in EFSA novel food assessment timelines or FDA GRAS pathway documentation requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant Based Cheese Market
Plant Based Food
Vegan Dips Market
Plant Based Food
Plant Based Meat Market
Plant Based Food
Insoluble Pea Protein Market
Plant Based Food
South America Meat Substitute Market
Plant Based Food
Global Plant Based Milk Market
Plant Based Food
Middle East and Africa Meat Substitute Market
Plant Based Food
Vegan Protein Concentrate Market
Plant Based Food
Vegan Drink Mixes Market
Plant Based Food
Burdock Root Extract Market
Plant Based Food
Faba Bean Protein Market
Plant Based Food
Vegan Cookies Market
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
Flax-Based Protein Market
Plant Based Food
Plant Derived Proteins Market
Plant Based Food
Vegan Gelatin Market