
 Meatless Meat Market | 2026-2036
Meatless Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Meatless Meat Market Analytics
Clean-label ingredient specifications is unwinding the commodity positioning that earlier plant-based entrants relied upon. Beyond Meat leverages pea-protein isolate and beet-juice extract formulations to sustain premium shelf placement in North American retail. Impossible Foods anchors its competitive stance through heme-fermentation technology leadership and deep food-service partnerships with national burger chains.
Meatless meat denotes protein-rich food products engineered to replicate the sensory properties of conventional animal muscle tissue, typically formulated from soy, pea, wheat gluten, or mycoprotein with added lipids, binders, and flavor precursors to achieve target moisture retention, chew resistance, and Maillard browning during cooking. The category serves industrial food manufacturers, restaurant operators, and retail consumers seeking to reduce animal-product intake without sacrificing gustatory familiarity. Plant-based burgers currently occupy the largest revenue pool within product-type segmentation, while meat alternatives formulated for fast-food application represent the fastest-growing demand vector as quick-service chains expand dedicated vegetarian menu boards. Flexitarian consumers within customer-type segmentation command disproportionate trial and repeat rates, concentrating margin capture among brands that bridge taste parity with nutritional transparency.
The FDA oversees ingredient safety and novel-protein GRAS determinations, while the USDA regulates labeling integrity and inspection protocols for cell-cultured products, creating dual-agency compliance requirements that shape R&D investment priorities and time-to-market timelines. The EU Green Deal and Farm-to-Fork Strategy impose sustainability disclosure obligations on protein suppliers seeking European market access, favoring operations with verified supply-chain carbon accounting. Stakeholders must monitor evolving precision-fermentation scale-up economics and cultivated-meat cost curves to determine optimal timing for capital allocation across alternative protein technology platforms.
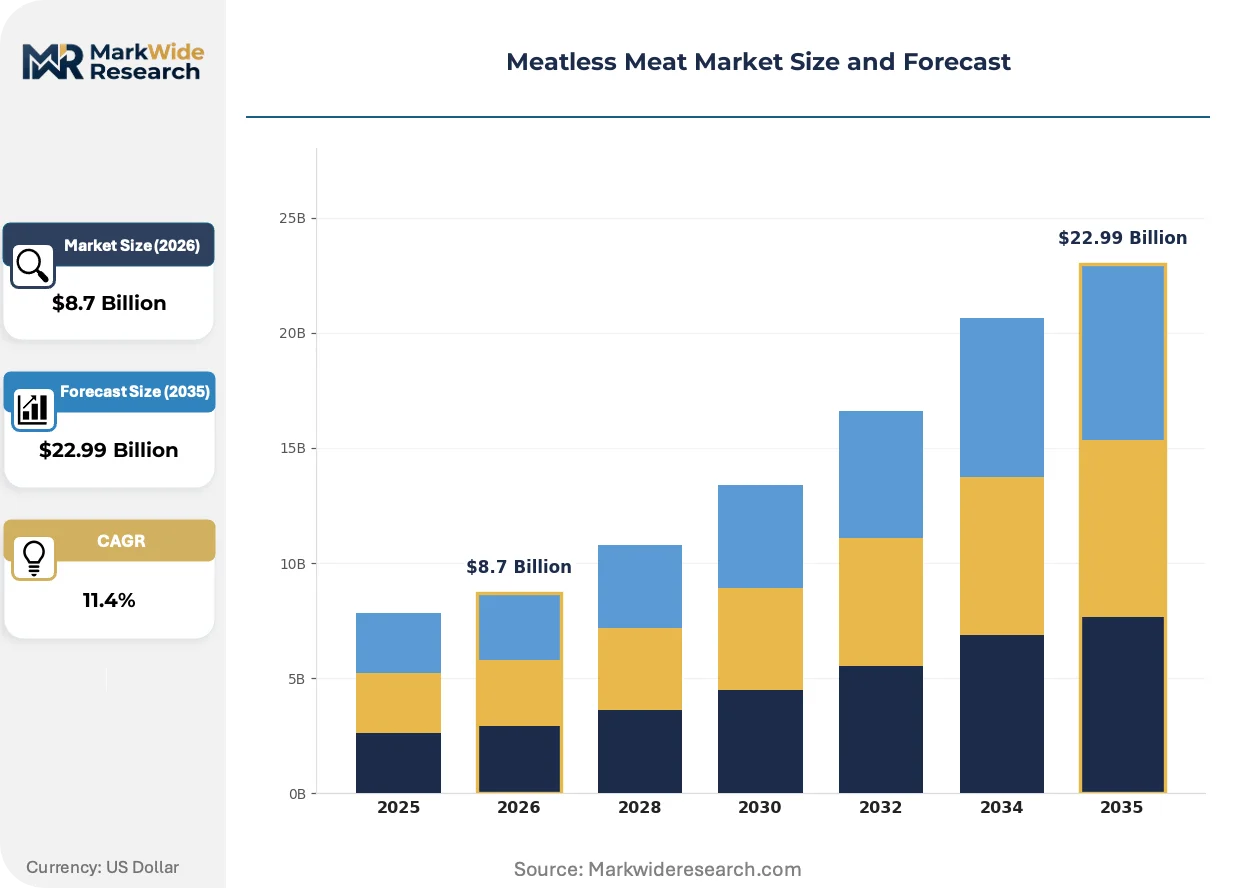
Market Dynamics
Dual-agency regulatory friction between the FDA and USDA is compressing time-to-market timelines for cell-cultured protein entrants while advantaging incumbents with captive compliance infrastructure. This structural bottleneck is reshaping capital allocation across fermentation scale-up versus cultivated-meat R&D.
Growth Catalysts
- EU Green Deal sustainability disclosure mandates:Verified carbon-accounting supply chains now unlock preferential retail placement in German and Dutch supermarket chains, concentrating margin capture among compliant suppliers.
- Quick-service restaurant permanent menu integration:Burger chains have shifted plant-based patties from limited-time promotions to core menu architecture, institutionalizing repeat purchase velocity.
- Precision-fermentation scale-up economics:Mycoprotein and heme-protein production costs are approaching parity thresholds that enable mainstream food-service pricing.
Market Restraints
- Pea-protein isolate supply concentration:North American and Canadian crop processing capacity limits create input cost volatility for extruded-textured protein formulations.
- Dual-agency labeling compliance burden:FDA-USDA co-regulation of cell-cultured products imposes redundant safety review cycles that extend commercialization timelines by 18-24 months.
- Animal-meat price elasticity:Conventional beef and poultry commodity pricing cycles compress plant-based premium positioning during livestock oversupply periods.
Strategic Opportunities
- Brazilian food-service penetration:Underdeveloped quick-service vegetarian menu boards in São Paulo and Rio de Janeiro metro corridors offer first-mover positioning ahead of ANVISA regulatory finalization.
- Hybrid meat-mycoprotein formulations:Blended products that reduce animal content by 30-50% while retaining sensory familiarity unlock flexitarian trial among skeptical conventional meat buyers.
- Indian FSSAI clean-label certification pathway:Domestic regulatory recognition of plant-protein nutritional equivalence opens institutional catering contracts in education and healthcare sectors.
Industry Challenges
- Food technologist talent scarcity:Maillard-chemistry and lipid-binding formulation expertise concentrates among a limited pool of specialists with cross-training in both culinary arts and materials science.
- Extrusion equipment capex intensity:High-moisture extrusion lines capable of fibrous texture replication require seven-figure capital commitments with 4-6 year depreciation horizons.
- GRAS self-determination documentation:Novel protein ingredient safety dossiers demand 12-18 month toxicology study completion before FDA enforcement discretion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meatless Meat Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plant-Based Burgers, Meat Alternatives, Sausages, Nuggets Distribution Channel: Retail Supermarkets, Online Stores, Health Food Stores, Wholesalers Customer Type: Vegans, Vegetarians, Flexitarians, Health-Conscious Consumers Application: Fast Food, Home Cooking, Food Service, Meal Kits |
| Companies Covered | Beyond Meat, Impossible Foods, Quorn Foods, Tofurky, Lightlife Foods, Maple Leaf Foods, Conagra Brands, Gardein, Amy's Kitchen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meatless Meat Market Evolving Landscape
Clean-label ingredient declarations and precision-fermentation scale-up are converging to unwind the commodity positioning that defined first-generation plant-based entrants. Formulation transparency now functions as a competitive differentiator rather than a compliance burden.
High-moisture extrusion technology is displacing low-moisture texturized vegetable protein as the dominant processing platform for whole-muscle analogues. Food manufacturers in Germany and the Netherlands are retrofitting production lines at accelerating pace. This equipment transition is compressing capital return timelines for suppliers capable of delivering fibrous bite resistance without methylcellulose binders.
The EU Farm-to-Fork Strategy imposes mandatory sustainability disclosure obligations on protein suppliers seeking European retail placement. Operations with verified supply-chain carbon accounting capture preferential listing terms in German and Dutch supermarket chains. Cell-cultured protein ventures are responding by front-loading lifecycle assessment documentation ahead of commercial scale-up.
Flexitarian consumers now demand ingredient transparency that exceeds regulatory minimums, compressing tolerance for artificial coloring and synthetic flavor precursors. Direct-to-consumer subscription channels in urban U.S. and UK markets are displacing conventional retail trial as the primary awareness driver. This channel rotation concentrates marketing spend on digital education rather than slotting-fee negotiations.
Meatless Meat Market Segmentation
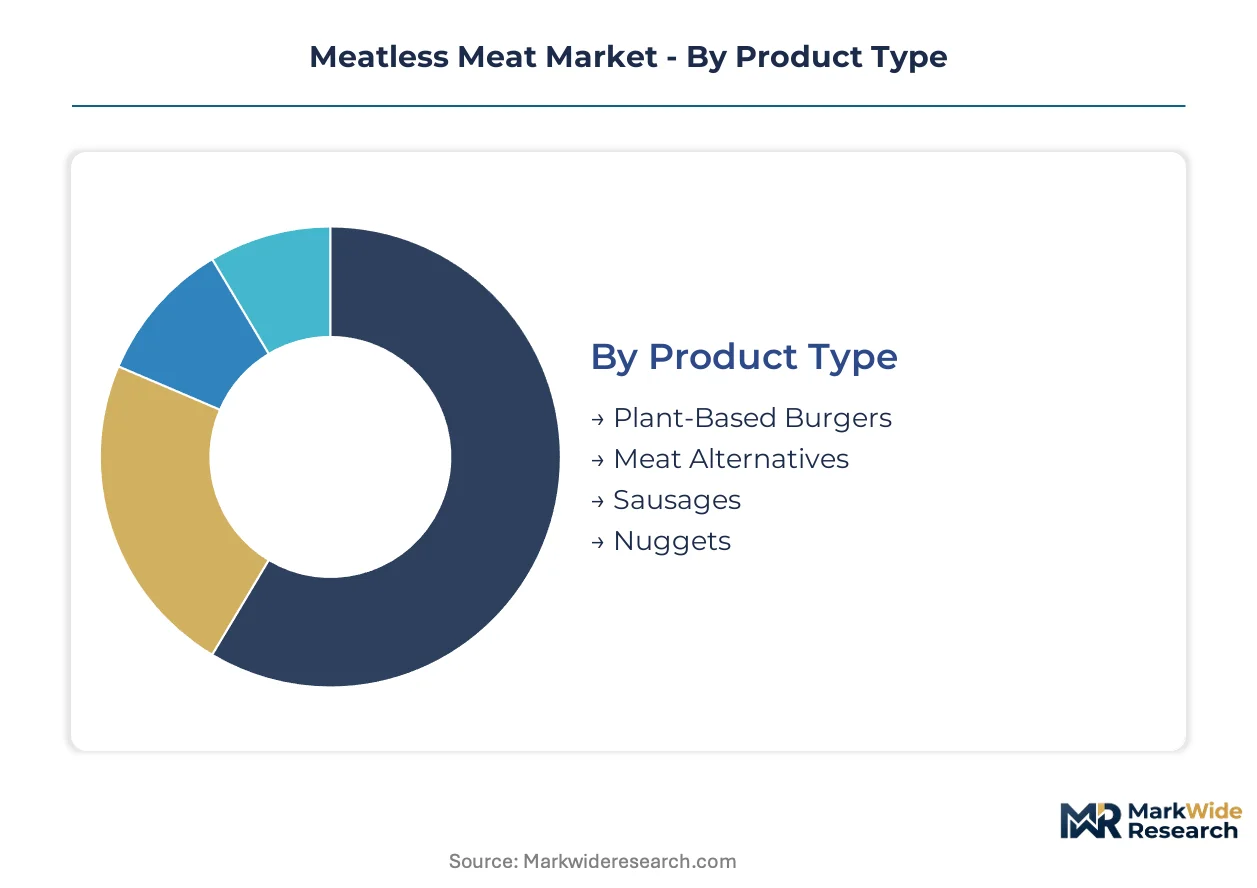
Segmentation in the meatless meat market reveals divergent substitution pressures across product formats and purchase contexts. Understanding which segments face direct competition from conventional animal protein versus emerging cultivated alternatives shapes portfolio prioritization and channel investment decisions.
Product Type:
Plant-based burgers face the most acute substitution threat from both conventional beef and emerging cell-cultured alternatives, forcing continuous formulation innovation to defend shelf positioning.
- Plant-Based Burgers:Formulated from pea-protein isolates, soy concentrates, or mycoprotein with lipid systems engineered for Maillard browning and juiciness retention. Quick-service restaurant chains in Germany and the United States now mandate permanent menu placement, institutionalizing volume commitments that stabilize manufacturing throughput.
- Meat Alternatives:Encompasses whole-muscle cuts, deli slices, and ground formats beyond the burger patty. High-moisture extrusion lines in the Netherlands and Germany are retrofitting at accelerating pace to capture flexitarian trial in retail refrigerated sections.
- Sausages:Casing technologies using alginate or cellulose derivatives replicate snap and texture.
- Nuggets:Breaded and formed products targeting children's menus and school foodservice contracts.
Plant-based burgers anchor the volume base while meat alternatives gain share at the steepest rate.
Distribution Channel:
Cost tier stratification separates premium placement in health-focused channels from commodity positioning in mass retail, with margin structures determining supplier prioritization.
- Retail Supermarkets:Chilled and frozen sections with dedicated planogram space in German chains driving repeat purchase velocity through promotional programming.
- Online Stores:Direct-to-consumer subscription models in urban UK and US markets displace conventional retail trial as primary awareness drivers.
- Health Food Stores:Curated assortments emphasizing clean-label credentials and certified organic supply chains.
- Wholesalers:Institutional and food-service volume aggregation with private-label manufacturing partnerships.
Retail supermarkets concentrate the revenue pool while online stores expand most quickly.
Customer Type:
Application context determines whether purchase motivation centers on ethical alignment, health optimization, or sensory familiarity without dietary commitment.
- Flexitarians:Consumers reducing but not eliminating animal-product intake command disproportionate trial and repeat rates, bridging taste parity demands with nutritional transparency expectations in German and Dutch markets.
- Health-Conscious Consumers:Prioritize protein density, sodium reduction, and absence of artificial additives in formulation screening.
- Vegans:Eliminate all animal-derived inputs including dairy, eggs, and honey from dietary patterns.
- Vegetarians:Exclude flesh meats while retaining dairy and egg consumption.
Flexitarians anchor the volume base while health-conscious consumers gain share at the steepest rate.
Application:
Geographic clustering of food-service innovation creates divergent maturity profiles across preparation contexts, with capital intensity separating industrial-scale from home-use formats.
- Fast Food:Quick-service chains have shifted plant-based patties from limited-time promotions to core menu architecture, with national burger chains in the United States and Germany institutionalizing repeat purchase velocity.
- Food Service:Institutional catering contracts in education and healthcare sectors in India pending FSSAI clean-label certification pathway finalization.
- Home Cooking:Raw and minimally processed formats requiring consumer preparation skill.
- Meal Kits:Pre-portioned ingredients with recipe instructions targeting convenience-oriented households.
Fast food anchors the volume base while food service gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented producers in Germany and the Netherlands supply chilled meat alternatives across European retail chains, while the United States and Brazil balance import substitution with emerging domestic capacity. Trade flows concentrate plant-protein ingredients from Canadian and Chinese processing facilities toward formulation hubs in Western Europe and North America.
United States
Quick-service restaurant chains have integrated plant-based patties into permanent menu architecture, institutionalizing volume commitments from national burger operators. The FDA and USDA maintain dual-agency oversight of cell-cultured protein labeling, creating compliance complexity that advantages established producers with dedicated regulatory affairs teams. Chicago and Los Angeles metro corridors concentrate food-service distribution infrastructure for meatless meat procurement.
Germany
Retail chains dedicate full refrigerated sections to chilled meat alternatives, with flexitarian consumers driving repeat purchase velocity through promotional programming. The EU Green Deal and Farm-to-Fork Strategy impose mandatory sustainability disclosure obligations on protein suppliers seeking market access. Berlin and Hamburg anchor formulation R&D clusters where high-moisture extrusion technology retrofits accelerate.
Netherlands
Food manufacturers retrofit high-moisture extrusion production lines at accelerating pace to capture flexitarian trial in retail refrigerated sections. EFSA clean-label recognition pathways favor operations with verified supply-chain carbon accounting. Wageningen and Eindhoven host precision-fermentation scale-up facilities where mycoprotein production costs approach parity thresholds.
India
Institutional catering contracts in education and healthcare sectors await FSSAI clean-label certification pathway finalization for plant-protein nutritional equivalence. Domestic regulatory recognition opens procurement channels for meatless meat suppliers meeting protein density and sodium reduction specifications. Maharashtra and Karnataka concentrate urban flexitarian demand in Mumbai and Bangalore metro corridors.
Brazil
Underdeveloped quick-service vegetarian menu boards in São Paulo and Rio de Janeiro metro corridors offer first-mover positioning ahead of ANVISA regulatory finalization for novel protein ingredients. Import substitution dynamics favor domestic extrusion capacity investment as conventional beef price volatility compresses plant-based premium positioning. Campinas and Curitiba emerge as industrial food manufacturing clusters for South American market supply.
Meatless Meat Market Competitive Landscape
Listed leaders compete with private specialists across technology platforms and channel access dimensions. The vendor base stratifies into three tiers: multinational food conglomerates with protein diversification portfolios, venture-backed pure-plays with fermentation technology leadership, and regional private-label manufacturers serving institutional accounts. Strategic moves concentrate on M&A-driven technology acquisition and food-service partnership exclusivity arrangements.
Within the venture-backed pure-play tier, Beyond Meat and Impossible Foods exemplify divergent technology anchoring strategies, with the former representing pea-protein isolate formulation approaches and the latter occupying heme-fermentation positioning. Quorn Foods anchors the mycoprotein fermentation archetype with decades of European market presence. These three entities collectively illustrate how intellectual property concentration in protein extraction and flavor precursor technologies determines competitive differentiation.
| Leading Market Players |
|---|
| Beyond Meat |
| Impossible Foods |
| Quorn Foods |
| Tofurky |
| Lightlife Foods |
| Maple Leaf Foods |
| Conagra Brands |
| Gardein |
| Amy's Kitchen |
| Others |
Value Network & Pricing Analysis
EU Green Deal sustainability disclosure mandates gate both supply qualification and price differentiation, forcing suppliers to absorb carbon-accounting certification costs while capturing premium placement in German and Dutch retail chains that flexitarian consumers frequent.
Pricing Analysis
Industrial food-service buyers anchor contract pricing through volume commitments to quick-service restaurant chains. Three-tier pricing structure across premium clean-label, standard extruded, and economy textured-vegetable-protein tiers separates Beyond Meat's pea-isolate positioning from private-label alternatives. Price differentiation rests on heme-fermentation technology licensing and verified carbon-accounting documentation. Pricing pressure intensifies as conventional beef commodity cycles compress plant-based premium windows during livestock oversupply periods.
Supply Chain Analysis
Inventory cycles for high-moisture extrusion equipment stretch 4-6 years, constraining rapid capacity response to demand spikes. Pea-protein isolate supply concentrates in Canada and China, while mycoprotein fermentation feeds from Netherlands and UK facilities. Raw material dependencies center on yellow-pea crop yields, beet-juice extract availability, and heme-protein fermentation feedstocks. Single-source vulnerability in North American extrusion equipment manufacturers exposes capacity expansion timelines. Distribution runs through chilled logistics networks serving German retail chains and US food-service distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as quick-service permanent menu integration institutionalizes repeat purchase velocity ahead of cultivated-meat scale-up.
For Market Incumbents: Shield formulation R&D leadership through captive high-moisture extrusion capacity additions in Germany and the Netherlands. Lock in multi-year pea-protein isolate offtake agreements with Canadian processors to neutralize input cost volatility from crop yield fluctuations. Deepen regulatory affairs infrastructure to navigate FDA-USDA dual-agency labeling friction that delays cell-cultured entrants.
For New Entrants and Emerging Players: Anchor in Brazilian food-service white space ahead of ANVISA regulatory finalization for novel protein ingredients. Target hybrid meat-mycoprotein formulations that reduce animal content 30-50% to unlock flexitarian trial among skeptical conventional meat buyers in São Paulo metro corridors. Pursue direct-to-consumer subscription channels in urban UK markets to bypass slotting-fee barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision-fermentation scale-up facilities as mycoprotein production approaches cost parity thresholds. Five-to-ten-year viability favors venture-backed pure-plays with intellectual property concentration in protein extraction and flavor precursor technologies. Monitor heme-fermentation cost curves as the inflection signal for optimal timing across alternative protein technology platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Moisture Extrusion Capacity Expansion | Retrofitting Netherlands and German production lines accelerates fibrous texture replication without methylcellulose binders. |
| Precision-Fermentation Scale-Up Partnership | Wageningen mycoprotein facilities approaching cost parity unlock mainstream food-service pricing acceptance. |
| EU Carbon-Accounting Certification Investment | Verified supply-chain documentation secures preferential retail placement in German supermarket chains. |
| Quick-Service Restaurant Exclusivity Arrangement | Permanent menu integration with national burger chains institutionalizes volume commitments and manufacturing throughput stability. |
| Backward Integration into Pea-Protein Processing | Captive Canadian crop processing capacity neutralizes input cost volatility from North American supply concentration. |
Research Methodology
Operator-level perspectives from food-service procurement directors, plant-based R&D formulation leads, retail category buyers, and regulatory affairs specialists anchored the qualitative base. Primary interview insights triangulated against FDA GRAS determination filings, USDA labeling guidance documents, EU Farm-to-Fork Strategy implementation reports, and customs trade data on pea-protein isolate flows. Secondary validation drew from SEC filings of listed protein diversification portfolios, carbon-accounting verification databases, and food-service distribution volume aggregators. Bottom-up manufacturing capacity estimates reconciled with top-down retail scanner data across the analysis window.
Sensitivity analysis tested demand elasticity to conventional beef price cycles and regulatory timeline slippage for cell-cultured approvals. The analytical framework modeled volume and value trajectories across product type, distribution channel, customer type, and application dimensions. CAGRs derived from segment-level growth rate reconciliation with aggregate market expansion. Forecast inputs incorporated high-moisture extrusion equipment deployment schedules and precision-fermentation cost curve assumptions throughout the projection horizon.
Material uncertainties — regulatory timeline extensions for FDA-USDA co-oversight finalization, pea crop yield volatility from climate patterns, and cultivated-meat cost parity achievement — sit outside the modeled envelope. Forecasts reflect documented assumptions on flexitarian adoption velocity and quick-service menu integration pace. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Asia Pacific Plant-Based Milk Market
Plant Based Food
New Jersey Vegan Products Market
Plant Based Food
Vegan Oatmeal Market
Plant Based Food
Vegan Food Market
Plant Based Food
Plant-Based Spreads Market
Plant Based Food
Plant Based Meat Market
Plant Based Food
Plant Based Cheese Market
Plant Based Food
China Plant Protein Market
Plant Based Food
Vegan Dessert Market
Plant Based Food
North America Rice Protein Market
Plant Based Food
Canada Plant-Based Food and Beverages Market
Plant Based Food
Soy- Based Food Market
Plant Based Food
Japan Plant Protein Market
Plant Based Food
Europe Meat Substitutes Market
Plant Based Food
Plant Based Supplement Market
Plant Based Food
China Pea Protein Market