
 Oat-Based Cereals Market | 2026-2036
Oat-Based Cereals Market Size, Share, and Industry Trends Forecast 2026-2036
Oat-Based Cereals Market Outlook
USDA Organic certification is rotating competitive access across the oat-based cereals landscape, forcing reformulation investments that smaller brands struggle to fund. General Mills sustains manufacturing scale through vertically integrated oat sourcing networks across North American growing regions. Nature's Path Foods differentiates through exclusive organic supply chain control and co-manufacturing partnerships with regional millers. Kellogg Company leverages its global distribution infrastructure to secure shelf space dominance in conventional retail channels.
Oat-based cereals comprise processed oat groats, flakes, or milled fractions formulated for human consumption, typically containing beta-glucan fiber levels between 3-5% by weight and moisture content below 12% to ensure shelf stability. These products serve commercial and household markets as ready-to-eat breakfast solutions or ingredient inputs for baked goods and nutrition bars. Instant Oatmeal commands the largest volume share due to convenience positioning, while Granola extracts premium pricing through health-food store distribution and clean-label positioning. The Online Retail channel is accelerating fastest as direct-to-consumer subscription models bypass traditional supermarket slotting fees and capture recurring household purchases.
The FDA enforces whole-grain health claim standards that oat-based cereals must meet to display coronary heart disease risk reduction language on packaging. The USDA Organic seal and Non-GMO Project verification create tiered market access where certified products command price premiums in specialty retail. EFSA's health claim assessments in Europe restrict beta-glucan cholesterol-lowering assertions to specific daily intake thresholds, shaping product serving-size engineering. Stakeholders must monitor evolving clean-label enforcement intensity and decide whether to pursue dual certification strategies or consolidate behind single-standard dominance.
Market Dynamics
Clean-label enforcement intensity is compressing formulation timelines across the oat-based cereals sector, forcing manufacturers to reconcile beta-glucan retention with simplified ingredient decks before EFSA's updated health claim assessments take effect.
Growth Catalysts
- EFSA Cholesterol-Lowering Thresholds:Specific daily intake benchmarks for beta-glucan claims are engineering precise serving-size architectures that premium brands exploit for differentiation.
- Whole-Grain Breakfast Migration:German and French households are rotating morning consumption toward groat-based formats with measurable fiber content.
- Direct-to-Consumer Subscription Models:Online retail channels are capturing recurring household purchases by bypassing conventional supermarket slotting fee structures.
Market Restraints
- USDA Organic Certification Costs:Rotating competitive access requirements demand reformulation investments that smaller brands cannot fund.
- North American Oat Supply Concentration:Vertically integrated sourcing networks by dominant processors limit independent miller access to certified organic groats.
- Moisture-Control Shelf Stability:Technical limitations in maintaining sub-12% moisture content through clean-label preservation methods constrain distribution radius.
Strategic Opportunities
- Western European Penetration Depth:Underpenetrated rural markets in France and Germany offer expansion vectors for instant oatmeal formats.
- Nutrition Bar Ingredient Inputs:Emerging application demand from baked goods manufacturers is absorbing milled oat fractions at premium pricing.
- Dual Certification Strategies:EU Nutrition and Health Claims Regulation alignment with USDA Organic creates tiered market access for compliant products.
Industry Challenges
- Clean-Label Reformulation Expertise:Talent scarcity in beta-glucan retention chemistry extends product development timelines.
- Co-Manufacturing Partner Vetting:Certification timeline delays for regional organic millers compress launch windows for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oat-Based Cereals Market |
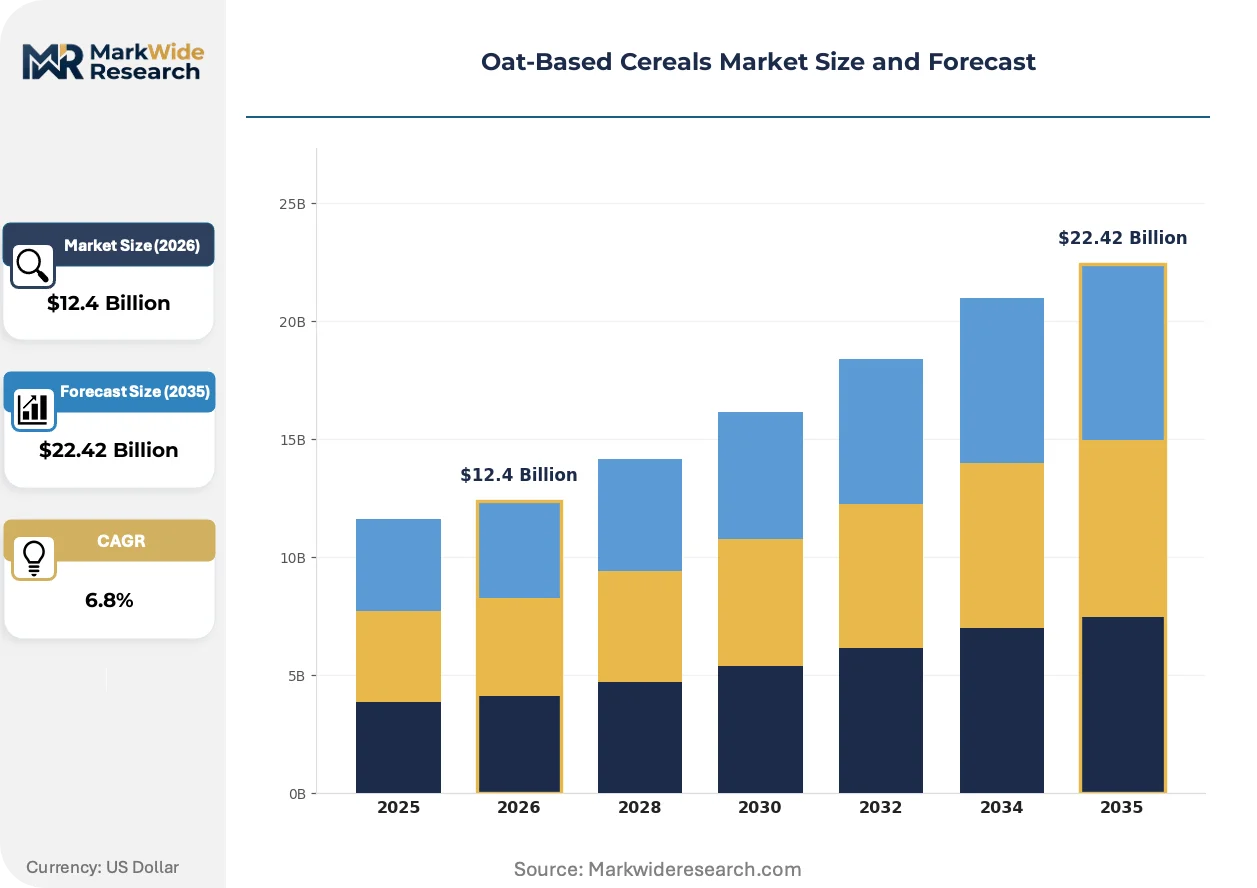
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Oatmeal, Granola, Oat Flakes, Oat Bran Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Specialty Stores End User: Households, Food Manufacturers, Cafes, Nutritionists Form: Ready-to-Eat, Cooked, Raw, Instant |
| Companies Covered | PepsiCo (Quaker Oats Company), General Mills, Kellogg Company, Post Consumer Brands, Nestlé, Bob's Red Mill, Nature's Path Foods, Mondelez International, The Hain Celestial Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oat-Based Cereals Market Strategic Shifts
Processing technologies and distribution architectures are actively reshaping competitive positioning in oat-based cereals, with fiber preservation methods and channel economics driving divergent investment priorities.
Steam-rolling and cutting technologies for groat processing are bifurcating the manufacturing landscape. Large-scale processors deploy continuous steam-rolling for instant oatmeal volume, while artisanal millers adopt batch cutting for granola texture differentiation. This technology split is compressing mid-tier equipment suppliers between scale and specialty demands.
EFSA's updated health claim assessments are restricting beta-glucan cholesterol-lowering language to precise formulation thresholds. Industrial consequence includes serving-size engineering that locks in specific gram-per-portion architectures. Granola and premium ready-to-eat segments are responding with dual-label strategies targeting both EU and export markets.
Subscription-based replenishment models are displacing conventional retail stocking cycles among health-conscious households. Direct-to-consumer channels capture recurring purchases through personalized portion sizing. This behavioral shift concentrates most visibly in German urban clusters where delivery infrastructure supports cold-chain granola distribution.
Oat-Based Cereals Market Segmentation
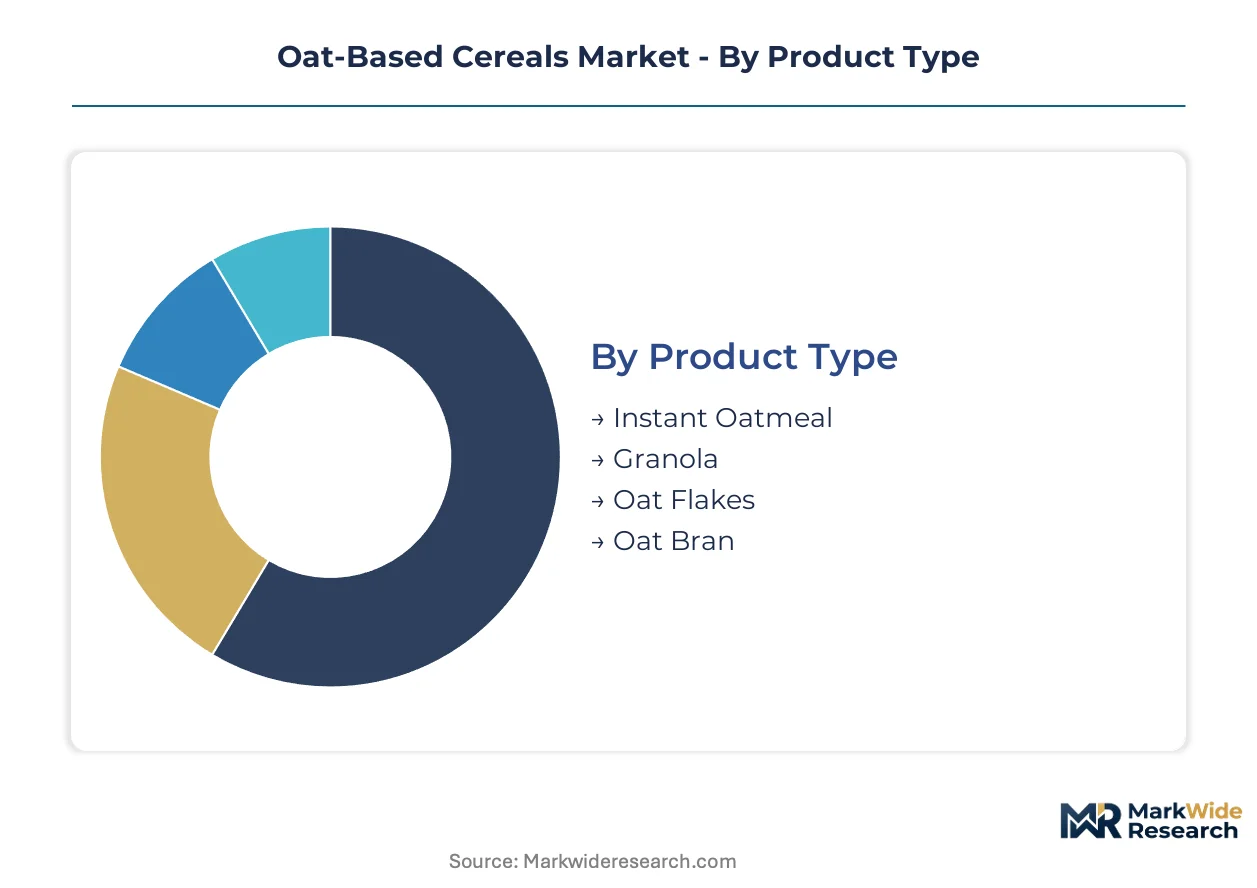
Oat-based cereals fragment across four functional dimensions that determine pricing architecture and channel access. Each category reveals distinct margin concentration points shaped by processing complexity, certification requirements, and household consumption patterns.
Product Type:
Margin pools concentrate in segments where beta-glucan retention commands premium positioning and clean-label compliance justifies price architecture.
- Instant Oatmeal:Steam-rolled oat groats processed to sub-12% moisture content for shelf-stable hydration. German and French households drive volume through convenience-oriented breakfast routines constrained by EFSA serving-size thresholds for cholesterol-lowering claims.
- Granola:Baked oat clusters combined with sweeteners and inclusions, requiring batch cutting technology for texture differentiation. Health-food store distribution in urban German clusters extracts premium pricing through organic certification and cold-chain logistics.
- Oat Flakes:Rolled whole groats retaining bran layer integrity for fiber content labeling.
- Oat Bran:Milled endosperm fractions concentrated in beta-glucan for ingredient input applications.
The dominant share belongs to Instant Oatmeal, while Granola is closing the gap fastest.
Distribution Channel:
Channel economics diverge sharply between slotting-fee structures and subscription-based customer lifetime value models.
- Supermarkets:Conventional retail commanding shelf space through trade spend and promotional calendars. Kellogg and General Mills leverage global infrastructure to secure positioning, though slotting fees compress margins for smaller organic entrants.
- Online Retail:Direct-to-consumer subscription models bypassing traditional fee structures. German urban delivery infrastructure supports recurring household purchases with personalized portion sizing and cold-chain granola distribution.
- Health Food Stores:Specialty retail tiered by USDA Organic and Non-GMO Project verification requirements.
- Specialty Stores:Regional artisanal millers distributing through co-manufacturing partnerships.
Supermarkets retain volume leadership, though Online Retail is expanding most quickly through subscription retention mechanics.
End User:
Application demand splits between direct household consumption and industrial ingredient absorption at divergent price points.
- Households:Primary consumption segment purchasing ready-to-eat and instant formats for breakfast occasions. French and German health-conscious rotation toward whole-grain options deepens penetration in Western European markets.
- Food Manufacturers:Industrial buyers absorbing milled oat fractions for nutrition bars and baked goods. Clean-label reformulation timelines compress as EFSA updates health claim assessments.
- Cafes:Foodservice operators sourcing bulk instant formats for breakfast menu items.
- Nutritionists:Professional recommenders influencing household brand selection through beta-glucan content specifications.
Households dominate absolute demand, while Food Manufacturers are gaining share fastest through ingredient input premiumization.
Form:
Processing intensity and preservation requirements create tiered cost structures across preparation states.
- Ready-to-Eat:Fully processed cereals requiring no preparation, demanding moisture control below 12% through clean-label preservation methods that constrain distribution radius.
- Instant:Pre-cooked and dehydrated groats reconstituting with hot water. Steam-rolling technology enables continuous production scale for volume leadership.
- Cooked:Traditional preparation formats requiring stovetop or microwave time investment.
- Raw:Unprocessed groats and flakes for home preparation or industrial milling inputs.
Ready-to-Eat holds the largest position, while Instant is climbing the fastest on convenience positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious households concentrate most densely in Western European urban clusters, where EFSA beta-glucan thresholds and USDA Organic certification create tiered market access that rewards precise formulation engineering.
Germany
Bavarian and North Rhine-Westphalian households drive instant oatmeal volume through convenience-oriented breakfast routines. EFSA's cholesterol-lowering claim thresholds shape precise serving-size architectures for products seeking premium positioning. Berlin's direct-to-consumer subscription infrastructure supports recurring granola purchases through cold-chain logistics networks.
France
Île-de-France and Auvergne-Rhône-Alpes regions exhibit deepening whole-grain breakfast migration among urban professionals. The EU's updated Nutrition and Health Claims Regulation tightens permissible labeling, forcing reformulation investments before products reach shelves. Lyon-based artisanal millers leverage co-manufacturing partnerships to access certified organic groat supplies.
United States
Midwest growing regions anchor North American oat supply concentration, with vertically integrated processors controlling access to certified organic inputs. FDA whole-grain health claim standards govern coronary heart disease risk reduction language on packaging. Minneapolis-St. Paul manufacturing clusters sustain continuous steam-rolling capacity for instant oatmeal volume leadership.
United Kingdom
London and Southeast England health-food store distribution extracts premium pricing through Non-GMO Project verification requirements. EFSA health claim assessments restrict beta-glucan assertions to specific daily intake thresholds, shaping product engineering decisions. Manchester-based online retail channels capture recurring household purchases through personalized portion sizing models.
Canada
Prairie Provinces oat cultivation supplies North American processors with conventional and organic groat streams. Health Canada maintains whole-grain labeling standards aligned with FDA frameworks for cross-border product consistency. Toronto's direct-to-consumer infrastructure accelerates subscription-based replenishment among urban health-conscious demographics.
Oat-Based Cereals Market Competitive Environment
Player mix skews toward diversified multinationals with global distribution infrastructure and specialty organic operators with supply chain control. The market structure concentrates shelf-space dominance among scale-driven processors while fragmenting across certified-organic entrants. Two strategic archetypes predominate: vertically integrated volume leaders and co-manufacturing-dependent clean-label specialists. Competitive moves center on certification pursuit and direct-to-consumer channel bypass of conventional retail slotting fees.
Within the diversified multinational tier, PepsiCo (Quaker Oats Company) and General Mills occupy positions exemplifying scale-driven manufacturing and global distribution infrastructure. Among specialty organic operators, Nature's Path Foods represents the co-manufacturing partnership model with regional miller networks. Kellogg Company anchors the conventional retail channel dominance archetype through trade spend and promotional calendar execution. These three company structures illustrate the competitive tension between volume-scale efficiency and clean-label differentiation that defines sector positioning.
| Leading Market Players |
|---|
| PepsiCo (Quaker Oats Company) |
| General Mills |
| Kellogg Company |
| Post Consumer Brands |
| Nestlé |
| Bob's Red Mill |
| Nature's Path Foods |
| Mondelez International |
| The Hain Celestial Group |
| Others |
Value Chain & Pricing Dynamics
Ninety-day certified organic groat procurement cycles compress margin buffers for mid-tier processors, concentrating pricing power among vertically integrated operators with captive North American oat supplies while forcing spot-market buyers into volatile premium tiers.
Pricing Analysis
Cost-plus contracts indexed to Minneapolis grain exchange benchmarks dominate volume transactions between processors and retail chains. Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic certified products from conventional and private-label tiers. Pricing pressure stems from EFSA's updated health claim assessments requiring reformulation investments. Food manufacturers exhibit highest price sensitivity due to compressed ingredient budgets, while health-food store channels absorb premiums for dual-certified SKUs.
Supply Chain Analysis
Canada and the United States anchor North American oat cultivation, supplying conventional and organic groat streams to integrated processors. Steam-rolling equipment, batch-cutting technology, and cold-chain logistics infrastructure constitute critical capital dependencies. Single-source vulnerability concentrates in Prairie Provinces organic certification capacity. Distribution runs through vertically controlled mill networks into supermarket slotting-fee structures and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oat-based cereals represent early-cycle expansion in Western European breakfast migration, with EFSA cholesterol-lowering claim thresholds accelerating premium-format adoption among German and French health-conscious households.
For Market Incumbents: Consolidate backward integration into certified organic groat sourcing to defend against Nature's Path Foods' supply chain control model. Add continuous steam-rolling capacity in Minneapolis-St. Paul manufacturing clusters. Pursue dual USDA Organic and EFSA-aligned certification to lock in health-food store shelf positioning before smaller competitors fund reformulation. For New Entrants and Emerging Players: Anchor in underpenetrated rural French markets for instant oatmeal distribution, where conventional retail slotting fees remain negotiable for regional co-manufacturing partnerships. Target Lyon-based artisanal miller networks for certified organic supply access. Launch direct-to-consumer subscription models with personalized beta-glucan portion sizing to bypass supermarket trade spend requirements. For Investors and Strategic Acquirers: Long-term, this sits as a clean-label consolidation play because EFSA regulatory tightening will strand non-compliant formulations and reward certified-organic supply chain control. Acquisition targets should display captive organic groat sourcing or established co-manufacturing partnerships with Prairie Provinces millers. Watch EFSA serving-size engineering announcements as inflection signals for premium-format margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | USDA Organic and EFSA alignment unlocks health-food store premium tiers and EU export access. |
| Direct-to-Consumer Launch | Bypasses supermarket slotting fees and captures recurring German urban household subscriptions. |
| Backward Integration into Organic Sourcing | Captive Prairie Provinces groat supplies insulate against spot-market volatility and certification delays. |
| Co-Manufacturing Partnership | Lyon and Berlin regional miller networks accelerate organic certification timelines for new entrants. |
| Serving-Size Engineering | Precision beta-glucan thresholds lock in EFSA cholesterol-lowering claim eligibility for premium positioning. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with oat processors, health-food store category buyers, brand managers at diversified multinationals, and regulatory affairs specialists navigating EFSA health claim pathways. Secondary validation drew from USDA organic certification databases, FDA whole-grain labeling guidance, EFSA scientific opinions, Nielsen retail audit data, and North American grain exchange price indices. Bottom-up volume modeling triangulated against top-down macroeconomic consumption trend analysis.
Across the analysis window, forecasts applied segmented growth rate derivation across product type, distribution channel, end user, and form dimensions. Modeled inputs included EFSA regulatory timeline assumptions, German and French household penetration trajectories, and organic certification capacity expansion in Prairie Provinces growing regions. CAGRs were computed from annualized segment-level value projections reconciled against aggregate market sizing.
Decision-makers should treat outputs as directional under sustained EFSA enforcement intensity and stable North American oat supply conditions; material deviation in regulatory timelines or organic groat availability would warrant model refresh. Recalibration cycles align with material shifts in clean-label enforcement intensity and certified organic supply chain access.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Margarine Market
Plant Based Food
South America Rice Protein Market
Plant Based Food
Indonesia Plant-Based Food and Beverages Market
Plant Based Food
Global Vegan Fast Foods Market
Plant Based Food
Rhubarb Root Extract Market
Plant Based Food
Plant-Based Sausages Market
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
United States Plant Protein Market
Plant Based Food
Plant-Based Margarine Market
Plant Based Food
Vegan Protein Blend Market
Plant Based Food
Australia Plant Protein Market
Plant Based Food
Plant-Based Nuggets Market
Plant Based Food
Plant Chocolate Protein Powder Market
Plant Based Food
Hemp-Based Food Market
Plant Based Food
Plant Based Pasta Market
Plant Based Food
Soy- Based Food Market