
 Lentil Protein Market | 2026-2036
Lentil Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Lentil Protein Market Intelligence
Value-added formulation revenue is fragmenting the previously commoditized supply of bulk lentil protein isolate. Major suppliers like Roquette Frères leverage extensive R&D to develop functional proteins for specific food systems. AGT Food and Ingredients sustains its position through deep backward integration into lentil sourcing and primary processing. Ingredion Incorporated competes by offering a broad portfolio of plant-based ingredients to global food manufacturers.
Lentil protein is a plant-based protein derived from the seeds of the Lens culinaris plant, extracted to create powders. Commercial isolates achieve over 85% protein content via aqueous extraction or dry fractionation, serving as a nutritional and functional ingredient. Concentrated lentil protein is gaining traction due to a favorable cost-to-functionality ratio in applications like bakery. The meat alternatives and sports nutrition segments drive significant volume growth, demanding proteins with specific textural and solubility characteristics.
Market access is governed by food safety and labeling regulations enforced by bodies like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA). These agencies' guidelines on novel foods and allergen labeling directly influence product formulation and marketing claims. Processors must now decide whether to invest in advanced fractionation technologies to unlock higher-value functional properties or to compete on volume in the concentrate segment.
Market Dynamics
The central tension shaping the lentil protein market is the divergence between high-volume, price-sensitive concentrates and high-margin, functional isolates. This split is driven by advancements in fractionation technology that unlock specific texturizing and solubility properties for premium food applications.
Growth Catalysts
- Clean-Label Demand:Consumer demand for simple, recognizable ingredients in food products, particularly within the meat alternatives and healthy snacks sectors, propels the adoption of lentil protein as a non-GMO, allergen-friendly option.
- Processing Technology:Advances in dry fractionation and aqueous extraction methods are improving protein purity, reducing off-flavors, and enhancing functionalities like emulsification and gelling, thereby expanding use cases in complex food systems like dairy alternatives.
- Sustainability Initiatives:Government-backed sustainability frameworks, such as the EU Green Deal, encourage the use of plant-based proteins with lower environmental footprints, creating a favorable policy environment for pulse-derived ingredients like lentil protein.
Market Restraints
- Input Price Volatility:Dependence on agricultural outputs from key regions like Canada makes lentil protein prices susceptible to climate-related events, such as droughts or floods, which can disrupt supply and create cost instability for processors.
- Flavor and Formulation Hurdles:The inherent beany or earthy flavor profile of some lentil proteins requires additional masking agents or processing steps, adding cost and complexity to food formulation compared to more neutral-tasting proteins.
- Competition from Established Proteins:Lentil protein faces intense competition from soy and pea proteins, which benefit from more mature supply chains, greater economies of scale, and a longer history of use in the food industry.
Strategic Opportunities
- Geographic Expansion:Significant opportunity exists in Asian markets like Japan and South Korea, where rising incomes and health consciousness are creating new demand for plant-based foods, yet lentil protein remains a niche ingredient.
- Hybrid Product Development:Formulating hybrid products that combine animal-based meat with lentil protein offers a pathway to improve the nutritional profile, reduce cost, and enhance the sustainability credentials of conventional processed meat products.
- Fermentation and Bio-processing:Applying fermentation technologies to lentil protein can enhance its digestibility, reduce anti-nutritional factors, and create novel flavor profiles, unlocking applications in specialized nutrition and premium food categories.
Industry Challenges
- Capital-Intensive Processing:Building and scaling facilities with advanced fractionation technologies requires significant capital expenditure, creating a high barrier to entry for new players and smaller companies aiming to compete in the functional isolate segment.
- Functional Standardization:A lack of industry-wide standards for measuring and reporting functional properties like water-holding capacity or foaming stability complicates procurement for food manufacturers and can lead to batch-to-batch inconsistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lentil Protein Market |
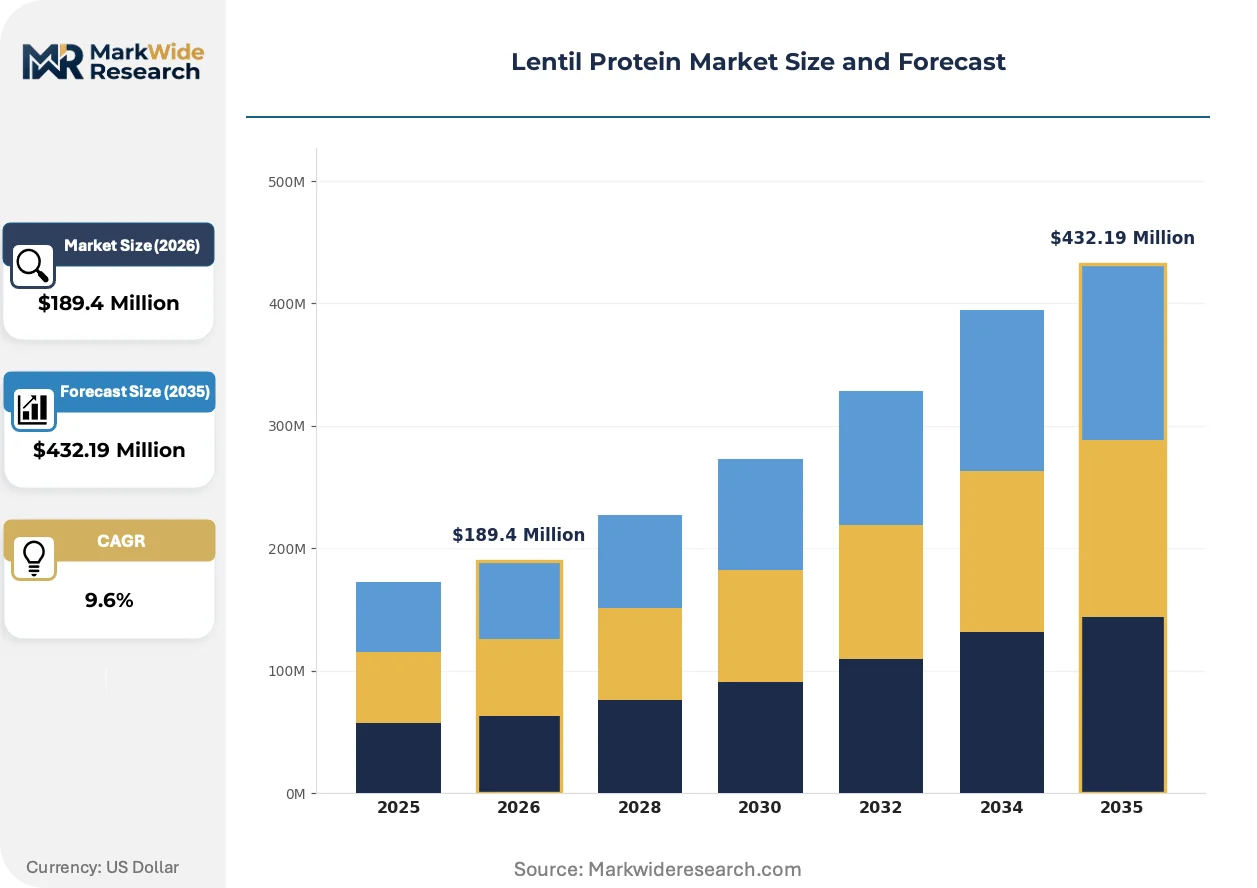
| Market Size in 2026 | $189.4 Million |
| Market Size in 2035 | $432.19 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolated Lentil Protein, Concentrated Lentil Protein, Textured Lentil Protein, Hydrolyzed Lentil Protein Application: Bakery, Meat Alternatives, Functional Beverages, Infant Nutrition, Sports Nutrition, Nutraceuticals End User: Food & Beverage Manufacturers, Dietary Supplement Producers, Animal Feed Industry, Cosmetic Manufacturers Distribution Channel: Online Retail, Specialty Stores, Supermarkets & Hypermarkets, Direct Sales |
| Companies Covered | AGT Food and Ingredients, Roquette Frères, Ingredion Incorporated, Puris Foods, Avena Foods Limited, Archer Daniels Midland Company, Cargill, Kerry Group, Glanbia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lentil Protein Market Strategic Shifts & Innovations
A fundamental shift from viewing lentil protein as a simple nutritional supplement to a critical functional ingredient is underway. This evolution is driven by processing innovations that tailor protein properties for specific textural and sensory outcomes in sophisticated food systems.
Advanced dry fractionation, including air classification, allows for the precise separation of protein and starch components from lentil flour. Food formulators in the bakery and meat alternative segments are rapidly adopting these tailored ingredients to improve texture and structure. This technology's ability to create proteins with specific gelling or emulsifying capacities is rendering obsolete the one-size-fits-all approach of early-generation, less functional concentrates.
The European Union's push for harmonized front-of-pack nutrition labeling, including systems like Nutri-Score, creates a powerful incentive for food reformulation. This regulatory pressure encourages the use of ingredients like lentil protein to boost protein scores without negatively impacting fat or sugar ratings. The prepared meals, sauces, and savory snacks categories are most affected, with manufacturers actively redesigning products to achieve more favorable nutritional labels.
Food manufacturers are increasingly moving away from the transactional purchase of bulk ingredients toward collaborative co-development partnerships with protein suppliers. This trend disrupts the traditional commodity distribution model, as large consumer packaged goods firms now engage directly with processors to design custom isolates for specific applications. The practice is most visible in the competitive North American plant-based dairy and meat alternative sectors, where unique textures are a key point of differentiation.
Lentil Protein Market Segmentation
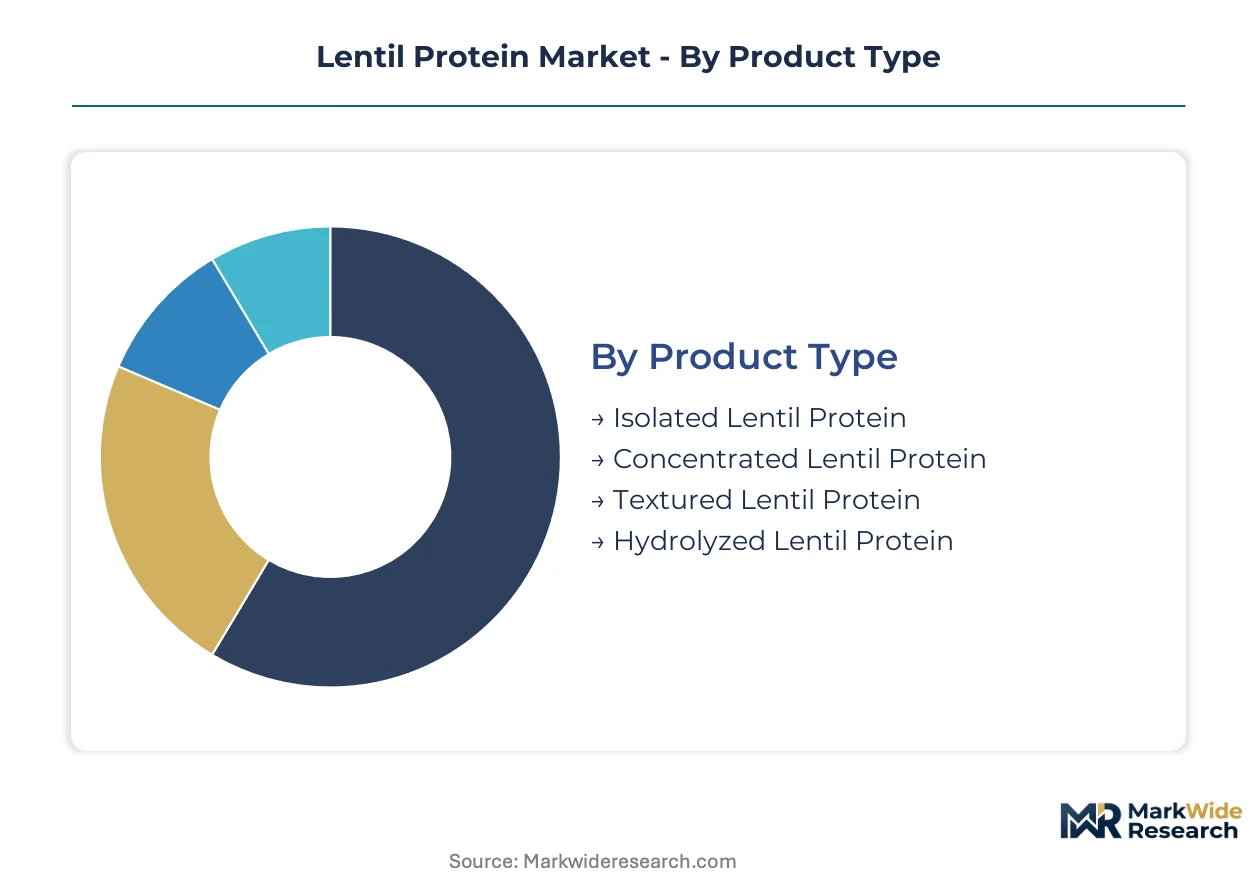
The lentil protein market dissects into distinct segments, each reflecting varying product functionalities, application needs, and distribution mechanisms. Understanding these granular divisions enables stakeholders to identify specific growth pockets and tailor product development strategies for targeted end-user requirements.
Product Type:
The functional and cost-efficiency characteristics of lentil protein drive its classification by product type.
- Isolated Lentil Protein:This product type achieves over 85% protein content through advanced aqueous extraction or dry fractionation, offering superior purity and functionality for complex food systems. Demand concentrates in the meat alternatives and sports nutrition sectors, where specific textural, emulsification, and solubility characteristics are crucial for product performance.
- Concentrated Lentil Protein:Containing 50-85% protein, this more cost-effective variant serves as a robust nutritional and functional ingredient across various food matrices. Bakery and functional beverage applications exhibit strong demand, leveraging its favorable cost-to-functionality ratio for protein enrichment and structural improvement.
- Textured Lentil Protein:This form provides a fibrous, meat-like texture, making it highly suitable for mimicking conventional meat products.
- Hydrolyzed Lentil Protein:Enzymatic hydrolysis enhances the digestibility and solubility of this protein, making it ideal for specialized nutritional products.
Concentrated Lentil Protein commands the established base. The steepest expansion runs through Isolated Lentil Protein.
Application:
Diverse end-use applications define the market's demand profile for lentil protein.
- Meat Alternatives:Lentil protein provides essential binding, texture, and nutritional value, serving as a primary ingredient in plant-based burgers, sausages, and ground meat substitutes. North American and European markets drive significant volume, propelled by consumer demand for clean-label and sustainable protein sources.
- Sports Nutrition:Utilized in protein powders, bars, and ready-to-drink beverages, lentil protein offers a complete amino acid profile for muscle recovery and growth. Global athletes and fitness enthusiasts increasingly seek plant-based options for their dietary regimens.
- Bakery:Lentil protein enhances the nutritional profile and improves the structure of gluten-free and functional baked goods.
- Functional Beverages:This application leverages lentil protein for protein fortification and emulsification in health-oriented drinks.
- Infant Nutrition:As a hypoallergenic protein source, lentil protein finds use in specialized infant formulas for sensitive dietary needs.
- Nutraceuticals:Lentil protein contributes bioactive compounds and protein to dietary supplements and health-promoting formulations.
Meat Alternatives represent a significant volume driver. Sports Nutrition exhibits rapid growth.
End User:
The varied customer base for lentil protein reflects its versatility across industries.
- Food & Beverage Manufacturers:These large-scale entities integrate lentil protein into a wide array of products, from snacks and prepared meals to dairy alternatives. Global food companies drive substantial procurement to meet the expanding plant-based and functional food trends.
- Dietary Supplement Producers:Companies in this segment formulate lentil protein into capsules, powders, and nutritional bars, targeting health-conscious consumers. Demand is robust from individuals seeking natural, plant-derived protein sources for overall wellness and specific health goals.
- Animal Feed Industry:Lentil protein serves as an alternative protein source in sustainable and cost-effective animal feed formulations.
- Cosmetic Manufacturers:This industry utilizes lentil protein for its beneficial properties in natural and plant-derived skin and hair care products.
Food & Beverage Manufacturers constitute the largest consumer segment. Dietary Supplement Producers are expanding their usage.
Distribution Channel:
The pathways through which lentil protein reaches its end-users vary by scale and consumer access.
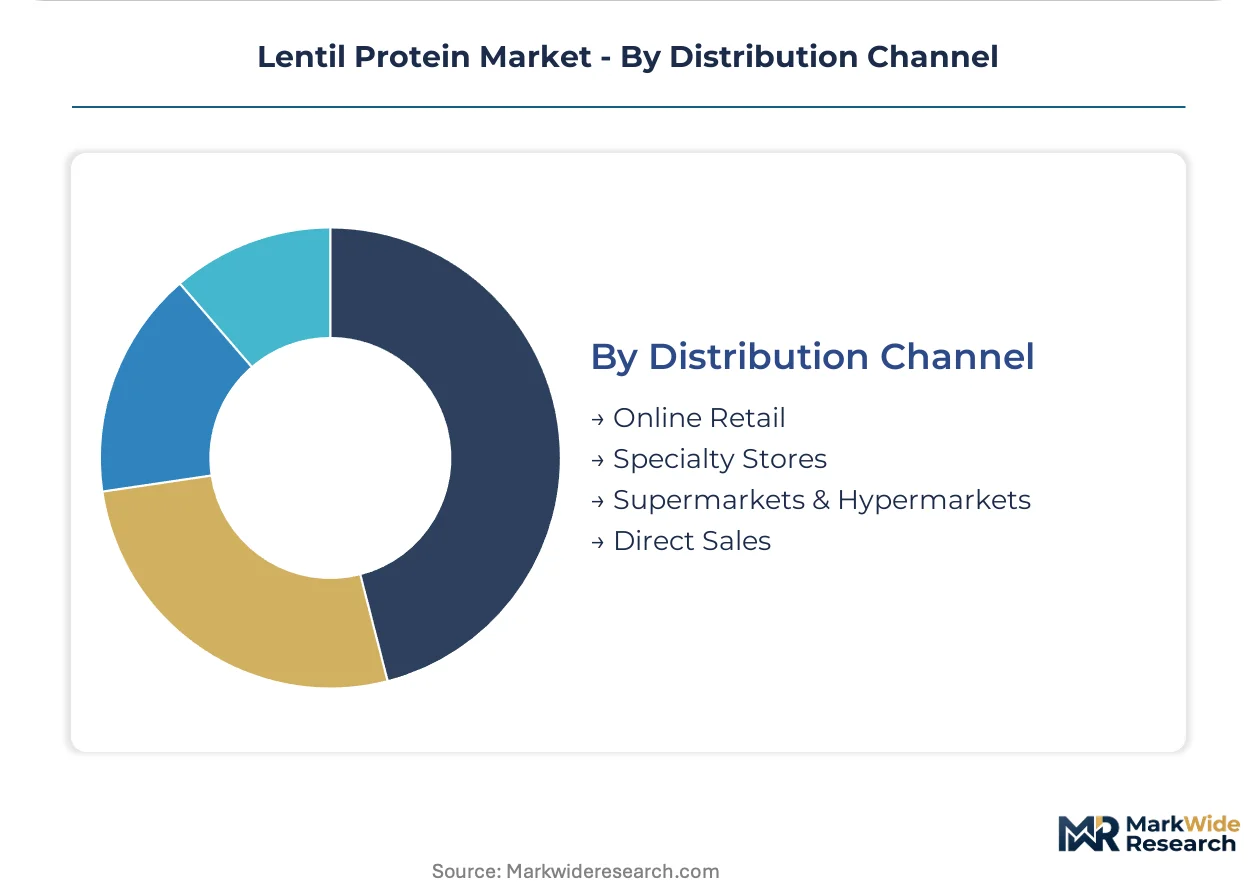
- Direct Sales:This channel involves bulk sales directly from lentil protein processors to large-scale food and beverage manufacturers. Major food companies prefer direct procurement to ensure specific product specifications, consistent quality, and volume requirements for their production lines.
- Specialty Stores:These retail outlets, including health food stores and organic markets, cater to niche consumer segments seeking specific plant-based and natural ingredients. Consumers actively search for premium and specialized lentil protein products through these channels.
- Online Retail:E-commerce platforms provide convenient access for individual consumers and smaller businesses to purchase various lentil protein products.
- Supermarkets & Hypermarkets:These mass-market retailers distribute packaged food products containing lentil protein to a broad consumer base.
Direct Sales dominate the B2B supply. Online Retail demonstrates increasing consumer accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption-mix differential for lentil protein varies significantly by geography, with some regions prioritizing functional isolates for high-value applications while others focus on nutritional enrichment. Demand for lentil protein concentrates and isolates is expanding across continents, driven by diverse factors including health trends and regulatory support for plant-based ingredients.
Canada
Meat alternative and sports nutrition sectors drive significant demand for lentil protein in Canada. Health Canada's food regulations support the inclusion of plant-based proteins in various food products. Saskatchewan, as a major pulse-producing region, hosts key processing hubs for lentil protein extraction.
United States
Consumer demand for clean-label and sustainable protein sources fuels the lentil protein market in the United States. The US Food and Drug Administration (FDA) provides guidelines for novel foods and allergen labeling, influencing product formulation. California and the Midwest are emerging as centers for plant-based food innovation and manufacturing.
Germany
Clean-label demand and sustainability initiatives propel lentil protein adoption in Germany's food industry. The EU Green Deal encourages the use of plant-based proteins, creating a favorable policy environment. Food manufacturers in North Rhine-Westphalia are actively integrating lentil protein into new product developments.
Japan
Rising incomes and health consciousness are creating new demand for plant-based foods in Japan. The Ministry of Health, Labour and Welfare (MHLW) regulates food additives and nutritional labeling for plant-based products. Tokyo and Osaka serve as innovation hubs for plant-based food development, including lentil protein applications.
India
A large vegetarian population and increasing health awareness contribute to lentil protein demand in India. The Food Safety and Standards Authority of India (FSSAI) governs the use of novel food ingredients and nutritional claims. Maharashtra and Gujarat are key states for pulse processing and food manufacturing using plant-based ingredients.
Lentil Protein Market Key Industry Players
Capability concentration sits with one tier of suppliers focusing on advanced functional properties; scale advantage sits with another tier emphasizing backward integration and volume. The lentil protein market exhibits a tiered structure, with specialized ingredient companies competing alongside large agricultural processors. Strategic archetypes include R&D-driven functional specialists, vertically integrated commodity providers, and broad-portfolio ingredient suppliers. Competitive moves involve significant capital expenditure in advanced fractionation technologies and collaborative co-development partnerships with food manufacturers.
Roquette Frères and Ingredion Incorporated exemplify the R&D-driven functional specialist archetype, leveraging extensive research to develop tailored protein solutions for complex food systems. AGT Food and Ingredients occupies a position as a vertically integrated commodity provider, sustaining its market presence through deep control over lentil sourcing and primary processing. These companies anchor the industry's competitive dynamics, with their distinct approaches to product development and supply chain management.
| Leading Market Players |
|---|
| AGT Food and Ingredients |
| Roquette Frères |
| Ingredion Incorporated |
| Puris Foods |
| Avena Foods Limited |
| Archer Daniels Midland Company |
| Cargill |
| Kerry Group |
| Glanbia |
| Others |
Cost & Logistics Intelligence
Saskatchewan's significant pulse production capacity dictates downstream pricing power for bulk lentil protein, creating an environment where input cost fluctuations directly influence processor margins. This dynamic highlights the tight coupling between agricultural output and ingredient market stability.
Pricing Analysis
Long-term offtake agreements and contract-based pricing models dominate the lentil protein market for large-volume buyers. Price differentiation stems from protein purity (isolate vs. concentrate), specific functional properties, and volume scale. Pricing pressure stems from the intense competition with more established pea and soy proteins. Food & Beverage Manufacturers seeking cost-effective protein enrichment for high-volume products exhibit the highest price sensitivity, while specialized formulators requiring specific functional isolates are less sensitive.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are increasingly common mechanisms to manage working capital for processors sourcing raw lentils. Geographic supply concentration centers in Canada, India, and the United States, leveraging established agricultural infrastructure. The supply chain draws from raw lentil harvests, making it susceptible to climate-related commodity price volatility. Direct sales from processors to large food manufacturers constitute the dominant distribution model, ensuring product specification adherence and consistent quality.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lentil protein market presents a service-attach opportunity, with collaborative co-development partnerships for custom formulations expanding faster than transactional bulk ingredient sales.
For Market Incumbents:Build R&D-driven functional expertise by investing in advanced fractionation technologies to create tailored protein solutions. Secure long-term, diversified lentil sourcing agreements to mitigate agricultural input volatility, which poses a significant threat to consistent supply. Pursue certification investments to differentiate premium isolates in a competitive landscape. Develop proprietary functional protein libraries to maintain a competitive edge against generic protein offerings.
For New Entrants and Emerging Players:Niche functional applications in specialized nutrition and underpenetrated Asian markets like Japan and South Korea represent the most penetrable entry points. Focus on developing fermentation-enhanced lentil proteins to improve digestibility and create novel flavor profiles. A go-to-market angle emphasizing customized solutions for specific food system challenges can bypass direct competition with established bulk suppliers. Target hybrid product formulations that combine lentil protein with other ingredients for unique benefits.
For Investors and Strategic Acquirers:Long-term, this sits as a technology-driven ingredient play because advanced processing unlocks higher-value functional properties. Seek acquisition targets with proprietary fractionation technologies or unique intellectual property in functional protein development. A key signal to watch is the increasing regulatory support for novel plant-based protein sources, which can accelerate market adoption and valuation for innovative players. Focus on firms demonstrating strong co-development partnerships with major food manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion: Advanced Fractionation | Increases production of high-value functional isolates for premium applications. |
| Collaborative Co-Development | Fosters innovation and secures long-term partnerships with food manufacturers. |
| Geographic Market Entry: Asia | Taps into rising health consciousness and plant-based demand in underserved regions. |
| Fermentation Technology Investment | Enhances protein functionality and opens new applications in specialized nutrition. |
| Sustainability Certification Program | Aligns with consumer and regulatory demand for environmentally responsible ingredients. |
Research Approach
A standing panel of food scientists, procurement managers, R&D directors, and sustainability officers provided ongoing calibration and validation for market insights. This approach combined extensive primary interviews with industry stakeholders and rigorous secondary validation. Data collection leveraged FDA guidelines, EFSA reports, industry association publications, and academic journals, triangulating information through both bottom-up and top-down analyses.
Scenario-bracketing framed the analytical framework across the analysis window, accounting for various market conditions. The model segmented the market by product type, application, end-user, distribution channel, and processing technology. Compound annual growth rates were derived from historical trends and projected market shifts, incorporating plant-based food innovation rates and consumer dietary shifts as key forecast inputs.
Practitioners should monitor climate events impacting lentil harvests and new regulatory approvals for novel proteins for early signals that could necessitate forecast revisions. Forecasts reflect assumptions documented through this comprehensive process. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Meatballs Market
Plant Based Food
Plant-Based Butter Market
Plant Based Food
China Pea Protein Market
Plant Based Food
Europe Pea Protein Market
Plant Based Food
India Plant Based Milk Market
Plant Based Food
Italy Plant Protein Market
Plant Based Food
Global Plant Based Milk Market
Plant Based Food
Africa Pea Protein Market
Plant Based Food
Organic Pea Protein Market
Plant Based Food
Europe Rice Protein Market
Plant Based Food
Vegan Cookies Market
Plant Based Food
Middle East and Africa Meat Substitute Market
Plant Based Food
Vegan Alternatives Market
Plant Based Food
Vegan Food Market
Plant Based Food
Europe Plant-Based Food Market
Plant Based Food
Pea Protein Market