
 Green Pepper Market | 2026-2036
Green Pepper Market Size, Share, and Industry Trends Forecast 2026-2036
Green Pepper Market Analysis
GlobalGAP certification for fresh produce is collapsing the supplier base as smaller growers fail audit costs. Mastronardi Produce leverages its greenhouse network across Canada and Mexico to sustain year-round supply continuity. Dole Food Company anchors its position through backward integration into Central American growing operations. Greenyard competes on scale, controlling distribution infrastructure across European retail channels.
Green pepper denotes the unripe fruit of Capsicum annuum, harvested before color change and typically containing 0-5 Scoville Heat Units for bell varieties, with firm walls suited to mechanical harvesting and extended cold-chain transit. The crop serves fresh consumption, industrial processing into diced and roasted formats, and as a base for sauces and salsas. Bell varieties dominate retail volume due to universal culinary application and low heat tolerance among mainstream consumers. Food Service leads end-user value capture, with institutional buyers demanding consistent sizing and pack specifications that wholesale channels struggle to match. Processing represents the fastest-expanding segment as prepared meal manufacturers seek fire-roasted and IQF formats.
USDA Organic standards and FDA Food Safety Modernization Act traceability rules shape US market access, while EU Green Deal pesticide reduction targets and EFSA residue limits govern European import eligibility. BIS food safety certifications and FSSAI labeling mandates control India's formal channel participation. Stakeholders must monitor divergence between EU and North American maximum residue limits, as tightening thresholds in either bloc will reroute trade flows and disqualify legacy growing regions.
Market Dynamics
Controlled-environment agriculture is displacing open-field cultivation across water-stressed growing regions, fundamentally altering cost structures and procurement patterns for year-round supply.
Growth Catalysts
- Hydroponic greenhouse expansion:Water-efficient closed-loop systems enable cultivation in arid zones previously unsuitable for pepper production. Mexico's Sinaloa cluster deploys these systems to maintain continuous harvest cycles.
- FDA Food Safety Modernization Act traceability mandates:Retail and food service buyers now require lot-level tracking from field to fork. Compliance investments filter out informal suppliers, consolidating volume with certified operations.
- Prepared meal manufacturing surge:Industrial demand for fire-roasted and IQF formats accelerates as meal-kit and ready-to-eat producers seek consistent raw material inputs with extended shelf stability.
Market Restraints
- Energy cost volatility:Greenhouse heating and supplemental lighting expose growers to natural gas and electricity price swings that field cultivation avoids.
- Supplier base collapse under GlobalGAP audit costs:Smallholder farms in traditional growing regions cannot absorb certification expenses, reducing sourcing diversity for buyers.
- Mechanical harvesting limitations:Firm-walled bell varieties tolerate automated picking, but damage rates on softer specialty types block full automation adoption.
Strategic Opportunities
- EU Green Deal pesticide reduction targets:Residue-compliant growers gain preferential access to European retail channels as EFSA thresholds tighten.
- Direct-to-food service procurement platforms:Digital sourcing tools bypass wholesale intermediaries, capturing margin from institutional buyers demanding precise sizing specifications.
- Controlled-environment convergence with renewable energy:Solar-integrated greenhouse designs in Baja California reduce operational carbon intensity for export markets.
Industry Challenges
- Scarcity of controlled-environment agronomists:Technical expertise in climate control, nutrient dosing, and integrated pest management lags facility expansion timelines.
- USDA Organic certification timeline compression:Three-year transition periods for conventional land conversion strain grower cash flow during premium-price exclusion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Pepper Market |
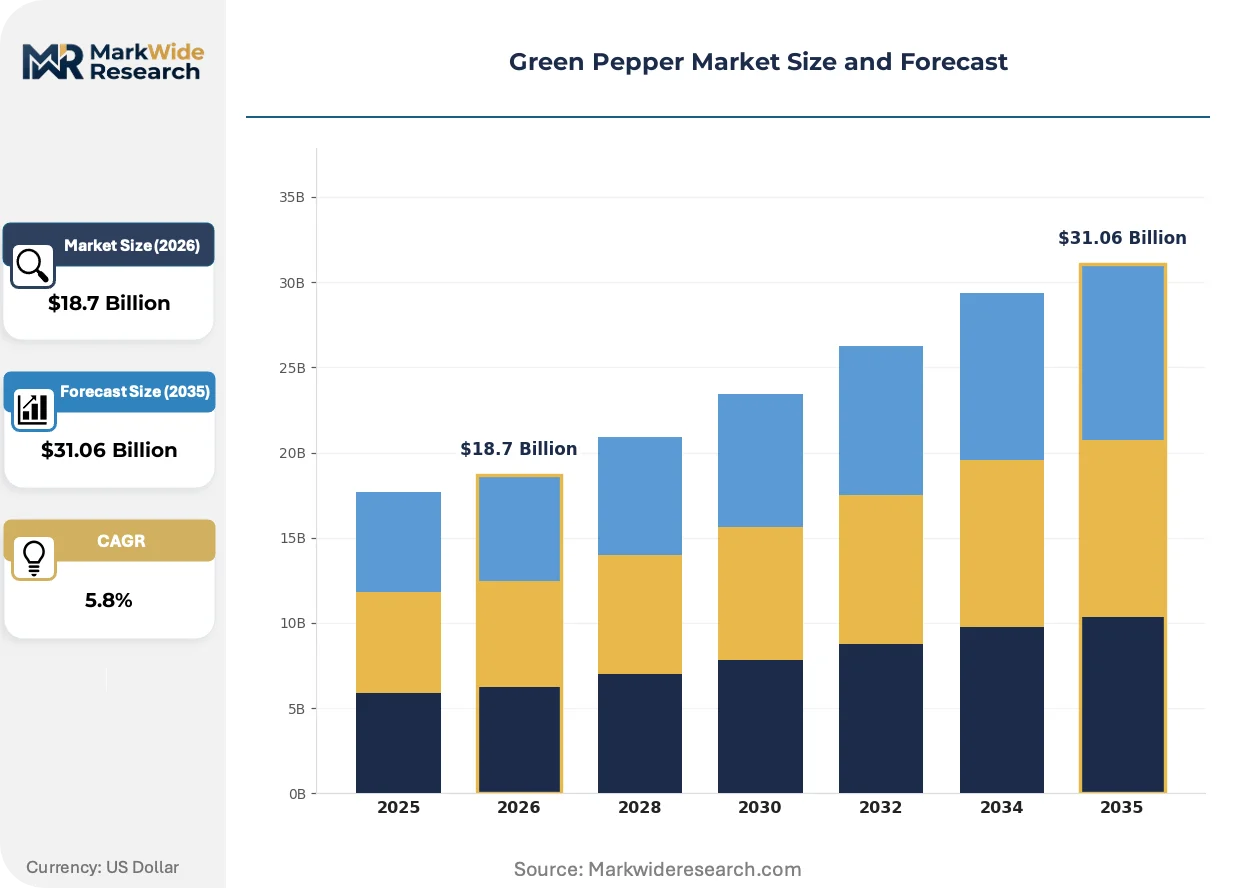
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serrano, Jalapeño, Anaheim, Bell Packaging Type: Bulk Bags, Plastic Containers, Cardboard Boxes, Retail Packs Distribution Channel: Supermarkets, Online Retail, Wholesale Markets, Direct Sales End User: Food Service, Retail, Processing, Home Cooking |
| Companies Covered | Greenyard, Mastronardi Produce, Olam International, Viet Star Import Export Company Limited, Henan Alchemy Food Co, Ltd, Dole Food Company, Chiquita Brands International, Cargill, Del Monte Fresh Produce, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Pepper Market Emerging Trajectories
Automation, regulatory stringency, and procurement centralization are converging to reshape how green peppers move from cultivation through processing to final consumption channels.
LED supplemental lighting systems combined with climate-controlled hydroponic infrastructure are displacing seasonal field dependence in North American supply chains. Large retail buyers now contract directly with greenhouse operators for twelve-month delivery schedules. This technology shift compresses the traditional import window and reduces exposure to weather-driven volume disruptions.
EFSA residue limit revisions under the EU Green Deal pesticide reduction framework are tightening import eligibility criteria. European retailers are consolidating supplier lists to pre-qualified operations with documented compliance histories. Processing-grade shipments from legacy growing regions face elevated rejection risk at border inspection points.
Food service procurement teams now mandate lot-level digital traceability as a baseline qualification. Wholesale distributors lacking real-time inventory visibility lose share to vertically integrated greenhouse networks with direct delivery capability. This pattern concentrates volume in Mexico's Baja California and Sinaloa clusters where infrastructure investments support compliance documentation.
Green Pepper Market Segmentation
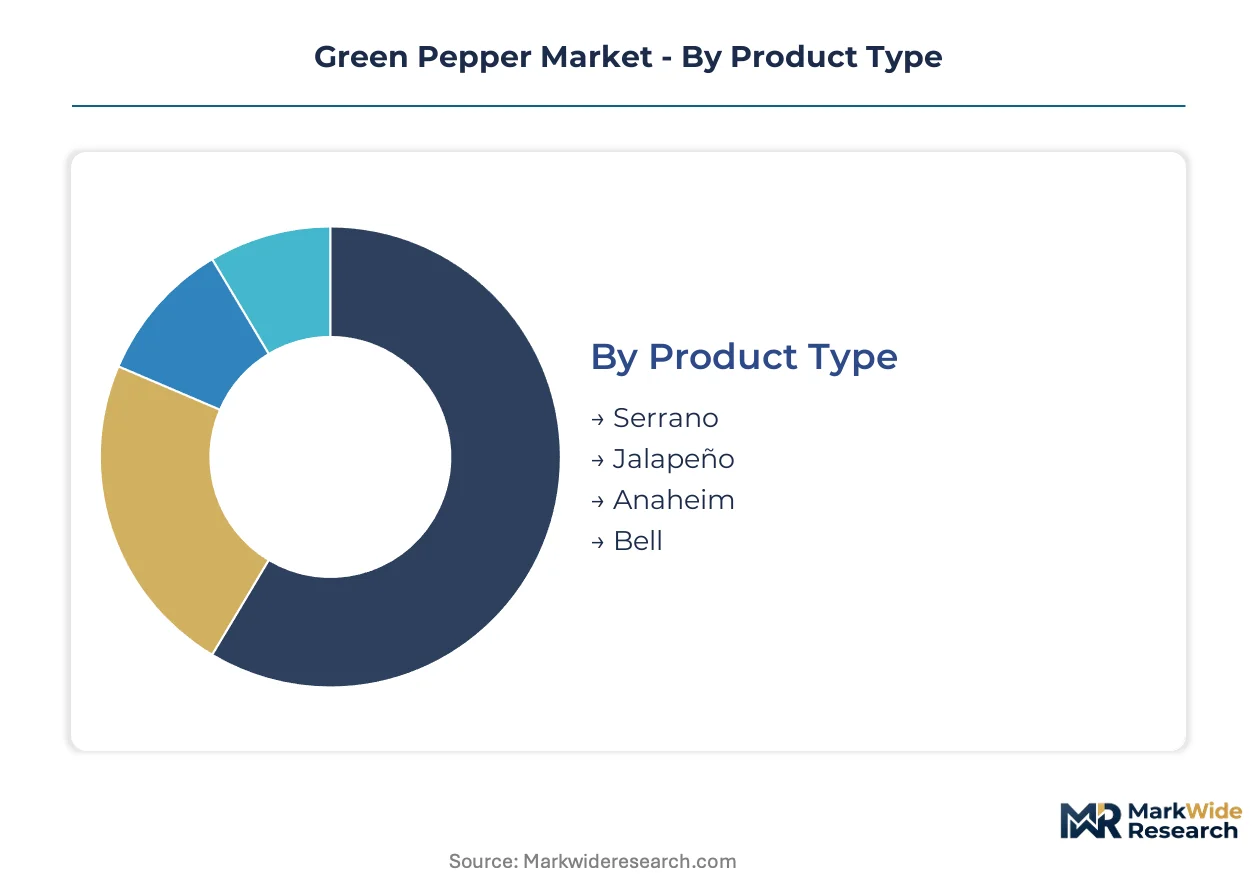
Green pepper segmentation reveals distinct channel economics. Heat tolerance, shelf stability, and pack specifications determine which varieties flow through food service procurement platforms versus retail grocery aisles. Understanding these flow patterns exposes margin concentration points.
Product Type:
Channel-mix dynamics separate fresh consumption from industrial processing streams. Heat profiles and wall thickness dictate mechanical harvest compatibility and cold-chain requirements.
- Bell:Zero-heat fruit with thick, firm walls engineered for mechanical harvesting and extended refrigerated transit. Food service buyers in the United States demand precise sizing tiers that field-grown supply struggles to match, consolidating procurement with Mexico's Sinaloa greenhouse operators.
- Jalapeño:Moderate heat range (2,500-8,000 Scoville units) with thinner walls requiring gentler handling. Processing manufacturers seeking fire-roasted and IQF formats in California and Texas drive volume concentration for this segment.
- Serrano:Higher heat profile (10,000-23,000 Scoville units) favored in salsa and hot sauce production. Mexican domestic consumption and US Southwest retail channels absorb most volume.
- Anaheim:Mild heat (500-2,500 Scoville units) with elongated shape suited to stuffing applications. New Mexico and California regional markets sustain niche demand.
Bell dominates installed base. Jalapeño is where expansion concentrates.
Packaging Type:
Cost tier stratification separates commodity bulk from value-added retail presentation. Packaging investment directly correlates with shelf-life extension and damage reduction.
- Retail Packs:Pre-sized consumer units with breathable film and branding real estate. European supermarket chains mandate recyclable materials under EU Green Deal packaging directives, forcing supplier retooling.
- Bulk Bags:Woven polypropylene sacks for food service and processing procurement. Mexico's Baja California export facilities favor this format for ocean freight efficiency to US West Coast distribution centers.
- Plastic Containers:Rigid clamshells protecting delicate thin-walled varieties. Premium positioning in Canadian and US organic retail channels justifies unit cost premiums.
- Cardboard Boxes:Standard corrugated for wholesale market aggregation. India's FSSAI labeling mandates require printed lot codes that informal repackers often omit, filtering participation.
Bulk Bags dominate installed base. Retail Packs is where expansion concentrates.
Distribution Channel:
Volume concentration tracks infrastructure investment and traceability compliance capability. Digital integration separates consolidating channels from declining intermediaries.
- Supermarkets:Multi-banner retail requiring year-round supply continuity and GlobalGAP certification. Mexico's vertically integrated greenhouse networks capture increasing share from traditional wholesale importers.
- Online Retail:Direct-to-consumer platforms demanding single-unit fulfillment and temperature-controlled last-mile logistics. Urban density in São Paulo and Mexico City supports emerging viability.
- Wholesale Markets:Traditional aggregation points for spot purchasing by small food service operators. FDA Food Safety Modernization Act traceability mandates are compressing participation as documentation costs rise.
- Direct Sales:Contracted supply from grower to processor or institutional buyer. Prepared meal manufacturers in the United States increasingly bypass distributors for captive supply arrangements.
Supermarkets dominate installed base. Direct Sales is where expansion concentrates.
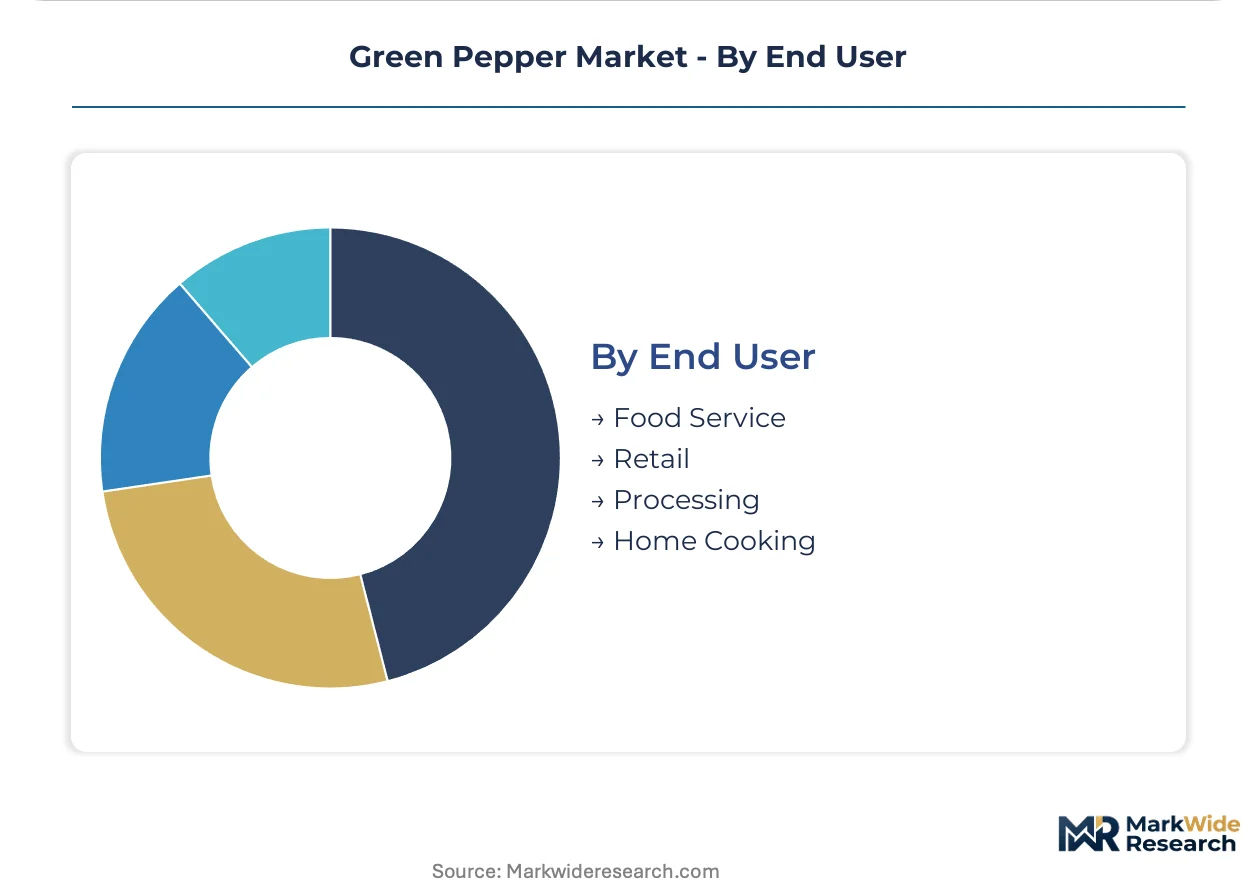
End User:
Application-specific specifications create divergent procurement patterns. Consistency requirements and volume scale determine supplier qualification thresholds.
- Processing:Industrial input demanding fire-roasted, diced, and IQF formats with documented lot traceability. US meal-kit manufacturers and European prepared food producers are climbing the fastest as automation-compatible raw material specifications tighten.
- Food Service:Institutional buyers requiring uniform sizing and pack weights for kitchen efficiency. Casino and hotel chains in Las Vegas and Atlantic City contract directly with Baja California greenhouse operators.
- Retail:Consumer-facing presentation with visual quality grading and extended shelf-life expectations. USDA Organic certification gates access to premium shelf placement.
- Home Cooking:Traditional wet market and neighborhood store purchasing in emerging markets. India's informal channel remains significant despite FSSAI formalization pressure.
Food Service dominates installed base. Processing is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach handles the majority of North American green pepper import volume, connecting Mexico's Baja California greenhouse clusters to US distribution networks with refrigerated container throughput that underwrites year-round supply continuity.
United States
Food service procurement teams in Las Vegas and Atlantic City casino-hotel chains demand uniform sizing specifications that field-grown supply cannot match. FDA Food Safety Modernization Act traceability mandates now require lot-level documentation from field to fork. California's Central Valley processing facilities concentrate fire-roasted and IQF format production for meal-kit manufacturers.
Mexico
Sinaloa and Baja California greenhouse operators supply twelve-month delivery schedules to US retail and institutional buyers. SENASICA phytosanitary certification gates export eligibility under the USMCA trade framework. The Culiacán-Mazatlán corridor deploys hydroponic closed-loop systems to maintain continuous harvest cycles despite water stress.
Netherlands
Westland greenhouse complexes supply European retail chains with GlobalGAP-certified bell pepper volume. EU Green Deal pesticide reduction targets and EFSA residue limit revisions tighten import eligibility criteria for non-EU suppliers. The Rotterdam port cold-chain infrastructure enables rapid distribution to German and French supermarket banners.
Spain
Almería's plasticulture greenhouses dominate European winter production with energy-efficient thermal screens. The EU's Farm to Fork Strategy mandates 50% pesticide reduction by 2030, accelerating grower investment in biological pest control. Murcia's processing facilities export fire-roasted formats to Northern European prepared meal manufacturers.
India
Maharashtra's Nashik district supplies domestic retail and food service channels with bell and specialty pepper varieties. FSSAI labeling mandates and BIS food safety certifications filter informal suppliers from formal channel participation. Bangalore's meal-kit startups drive emerging demand for pre-cut, value-added formats in metropolitan South India.
Green Pepper Market Vendor Landscape
Listed leaders compete with private specialists across certification compliance and supply chain control dimensions. The supplier base consolidates around vertically integrated greenhouse networks and diversified agricultural conglomerates with backward integration into growing operations. Three archetypes dominate: certified greenhouse operators with year-round capacity, diversified fresh produce multinationals with Central American farm assets, and commodity traders with origin sourcing scale. Competitive moves center on M&A for greenhouse facility acquisition and strategic partnerships for renewable energy integration.
Within the certified greenhouse tier, Mastronardi Produce and Dole Food Company exemplify divergent approaches to North American market positioning. Mastronardi's Canada-Mexico facility network represents the controlled-environment specialist archetype with direct retail contracting capability. Dole anchors the diversified multinational model with upstream farm ownership in Central American growing regions. Greenyard occupies the European distribution infrastructure position, leveraging continental scale to supply retail channel consolidation. Olam International exemplifies the commodity trader archetype with origin sourcing networks spanning multiple hemispheres.
| Leading Market Players |
|---|
| Greenyard |
| Mastronardi Produce |
| Olam International |
| Viet Star Import Export Company Limited |
| Henan Alchemy Food Co, Ltd |
| Dole Food Company |
| Chiquita Brands International |
| Cargill |
| Del Monte Fresh Produce |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between US food service chains and Mexico's Sinaloa greenhouse operators lock in twelve-month supply access and price visibility, insulating buyers from spot-market volatility while committing growers to fixed-volume delivery schedules under USDA Organic certification tiers.
Pricing Analysis
Volume-discount tiering structures separate contract pricing for casino-hotel chains in Las Vegas from spot-market rates at wholesale terminals. Premium-mid-economy pricing differentiation tracks GlobalGAP certification status and lot-level traceability documentation, with FDA Food Safety Modernization Act compliance adding audit-cost premiums to base rates. Cost compression in economy-tier field-grown supply is intensifying because energy-efficient greenhouse operators in Baja California capture margin through renewable-integrated designs. Food service buyers with direct contracting capability show least price sensitivity; small restaurant operators dependent on wholesale intermediaries absorb full spot-market exposure.
Supply Chain Analysis
Port congestion at Long Beach and container availability fluctuations on the Trans-Pacific lane expose Mexican export schedules to transit-time variability that greenhouse operators mitigate through dedicated cold-chain partnerships. Geographic supply concentration centers on Mexico, Spain, and the Netherlands, with Sinaloa and Baja California clusters feeding North American demand and Almería's thermal-screen greenhouses supplying European winter volumes. Raw material dependencies rest on fertilizer inputs, climate-control equipment, and biological pest-control agents. Single-source vulnerability concentrates in Mexico's vertically integrated greenhouse networks where SENASICA phytosanitary certification gates USMCA market access. Distribution runs through direct retail contracting and processor captive-supply arrangements that bypass traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward institutional food service chains as direct-to-grower contracting consolidates procurement volume away from fragmented wholesale distributors, compressing intermediary margins and filtering supplier participation toward certified greenhouse operators.
For Market Incumbents: Shield year-round supply relationships by deepening backward integration into Baja California renewable-energy greenhouse facilities, countering the threat of emerging controlled-environment specialists with SENASICA-certified export capacity. Prioritize GlobalGAP re-certification investments ahead of EU Green Deal pesticide threshold tightening to defend European retail channel positioning against Spanish and Dutch competitors.
For New Entrants and Emerging Players: Differentiate on fire-roasted and IQF format specialization for US meal-kit manufacturers, targeting the processing segment where demand climbs fastest and incumbent greenhouse networks lack dedicated industrial-capacity configuration. Pursue direct sales contracting with prepared meal producers in California and Texas as the most penetrable go-to-market angle, bypassing supermarket banner consolidation barriers.
For Investors and Strategic Acquirers: Capital is best deployed toward controlled-environment greenhouse operators with existing SENASICA and GlobalGAP certification infrastructure, positioned for long-term viability as water-stress and traceability mandates displace open-field cultivation across the projection horizon. Monitor EU EFSA residue limit revision timing as the signal to watch for trade-flow rerouting that would elevate premium-tier pricing for compliant Mexican supply.
| Strategic Initiative | Industry Significance |
|---|---|
| Greenhouse Capacity Expansion | Sinaloa operators capture twelve-month contract share from seasonal field competitors. |
| Renewable Energy Integration | Solar-thermal designs in Baja California reduce natural gas exposure for export-grade production. |
| GlobalGAP Re-Certification Investment | Pre-qualified status gates European retail access under EU Green Deal pesticide reduction framework. |
| Direct-to-Processor Supply Agreements | Bypass wholesale intermediaries to capture margin from California meal-kit manufacturers. |
| Biological Pest Control Adoption | Almería growers meet Farm to Fork 50% pesticide reduction targets ahead of regulatory deadlines. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of USDA AMS trade data, FDA Food Safety Modernization Act guidance documents, EU Farm to Fork Strategy implementation reports, and SENASICA export certification records. Primary interviews engaged greenhouse operations managers in Sinaloa and Baja California, food service procurement directors at Las Vegas casino-hotel chains, European retail category buyers, and California processing facility technical directors. Bottom-up cultivation volume estimates triangulate against top-down trade flow analysis through the Port of Long Beach.
Segmentation dimensions modeled include product type (bell, jalapeño, serrano, anaheim), packaging format (retail packs, bulk bags, plastic containers, cardboard boxes), distribution channel (supermarkets, online retail, wholesale markets, direct sales), and end-use application (processing, food service, retail, home cooking). CAGRs derive from regression analysis of historical trade volumes against regulatory implementation timelines and technology adoption curves. Industry-specific forecast inputs incorporate hydroponic greenhouse expansion rates and EU pesticide threshold revision schedules.
The analysis sits within stated boundaries; outcomes outside sustained USMCA trade framework continuity, stable energy cost environments for greenhouse heating, and gradual EU regulatory phase-in would require recalibration. Forecasts reflect assumptions regarding certification audit cost trajectories and controlled-environment agronomist labor availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Fennel Powder Market
Spices and Seasonings
Sichuan Peppercorn Market
Spices and Seasonings
Middle East and Africa Food Micronized Salt Market
Spices and Seasonings
Kosher Salt Market
Spices and Seasonings
Ginger Oil Market
Spices and Seasonings
Low Sodium Sea Salt Market
Spices and Seasonings
Onion Powder Market
Spices and Seasonings
Ginger Market
Spices and Seasonings
Onion Salt Market
Spices and Seasonings
Wild Cherry Powder Market
Spices and Seasonings
Wasabi Market
Spices and Seasonings
Europe Seasoning Market
Spices and Seasonings
Africa Seasoning and Spices Market
Spices and Seasonings
Cardamom Oil Market
Spices and Seasonings
Mint Oils Market
Spices and Seasonings
Carthamus Yellow Market