
 Egg-Free Dressing Market | 2026-2036
Egg-Free Dressing Market Size, Share, and Industry Trends Forecast 2026-2036
Egg-Free Dressing Market Foresight
Clean-label certification tiers is collapsing the distinction between premium egg-free dressings and conventional alternatives, forcing reformulation across the price spectrum. Unilever leverages its global procurement infrastructure to secure aquafaba and avocado oil supplies at scale. Kraft Heinz Company anchors its position through mainstream retail shelf-space dominance, while Follow Your Heart differentiates through dedicated vegan brand equity built over decades.
Egg-free dressing denotes emulsified condiments and sauces formulated without egg yolk, typically relying on aquafaba, modified starches, or lecithin to achieve comparable viscosity and mouthfeel in the 3,000–15,000 centipoise range. These products serve commercial kitchens and retail consumers requiring allergen avoidance, plant-based compliance, or cholesterol reduction. Vegan mayonnaise leads ingredient-base segmentation due to its functional interchangeability with traditional mayonnaise in food service applications. Aquafaba-based formulations represent the fastest-growing ingredient category, driven by neutral flavor profiles and zero-waste sourcing appeal from chickpea processing. Supermarkets control the largest distribution channel volume, though online retail captures the highest margin pool through subscription and direct-to-consumer specialty brands.
The U.S. FDA enforces allergen disclosure under FALCPA, compelling manufacturers to highlight egg absence as a competitive attribute rather than mere omission. The EU's EFSA guidelines on novel food ingredients and REACH-compliant emulsifier approvals shape which binding agents gain commercial traction across member states. Stakeholders must monitor evolving jurisprudence around "egg-free" versus "mayonnaise" nomenclature, as standards of identity disputes in multiple jurisdictions threaten label compliance and market access strategies.
Market Dynamics
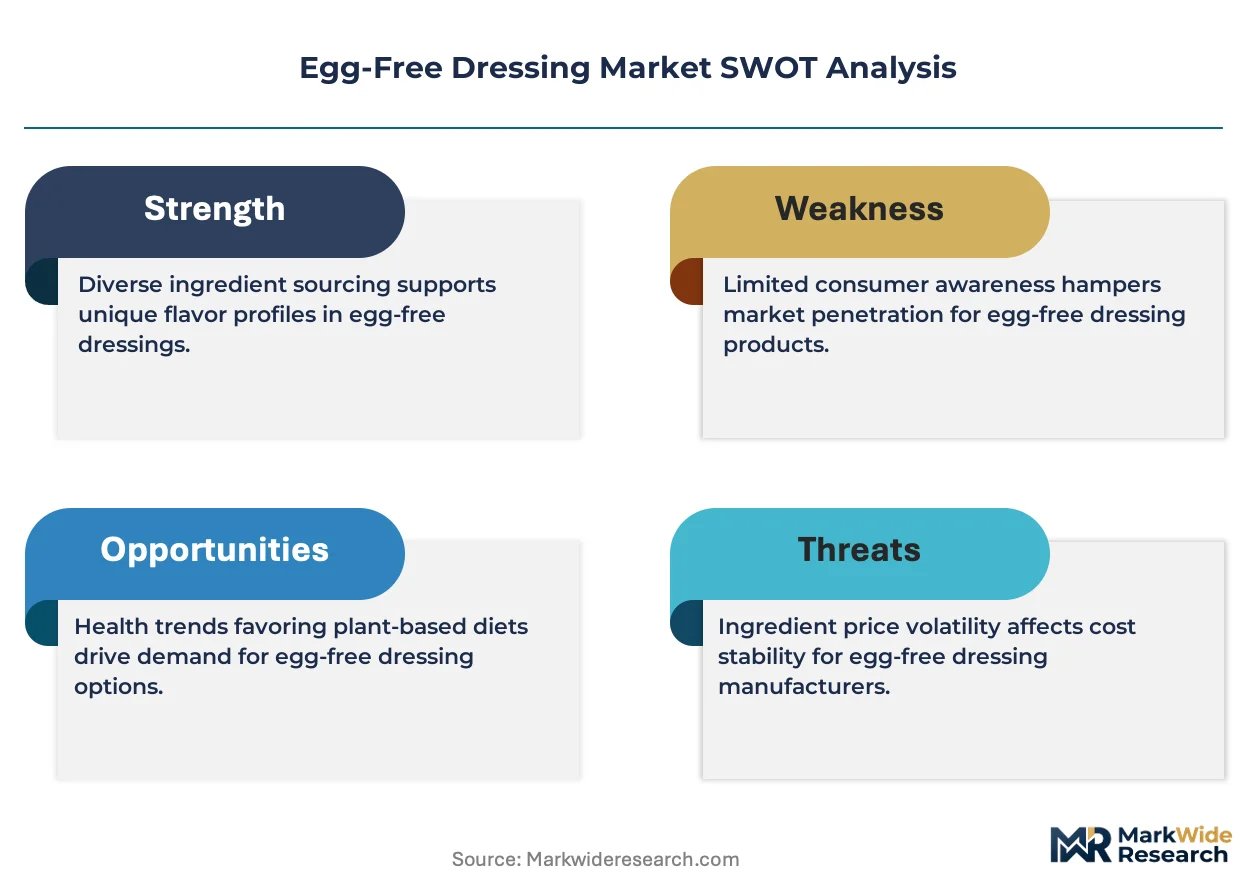
Clean-label certification tiers is collapsing the distinction between premium egg-free dressings and conventional alternatives, forcing reformulation across the price spectrum. Aquafaba sourcing networks and modified starch supply chains are concentrating among a handful of ingredient suppliers, creating procurement leverage asymmetries between large CPG manufacturers and mid-scale entrants.
Growth Catalysts
- FALCPA Allergen Disclosure:The U.S. FDA mandates prominent egg labeling, compelling manufacturers to highlight egg absence as a competitive attribute rather than mere omission in retail packaging.
- Quick-Service Plant-Based Menus:Fast-casual and quick-service restaurant chains are expanding vegan mayonnaise and dressing SKUs to capture flexitarian consumer spending during daypart expansion.
- Chickpea Processing Residue Utilization:Aquafaba extraction from commercial hummus and canned chickpea operations is displacing synthetic emulsifiers with zero-waste positioning.
Market Restraints
- Avocado Oil Price Volatility:Drought conditions in Mexican and Peruvian growing regions create input cost instability for premium egg-free mayonnaise formulations.
- Standards of Identity Disputes:Jurisdictional battles over "mayonnaise" versus "egg-free dressing" nomenclature threaten label compliance and retail shelf access in multiple markets.
- Lecithin Supply Concentration:Sunflower and soy lecithin production clusters in Eastern Europe and Argentina create geographic single-point-of-failure risk for binding agent procurement.
Strategic Opportunities
- Direct-to-Consumer Subscription Models:Specialty brands are bypassing supermarket slotting fees through refrigerated subscription boxes targeting metropolitan health food consumers.
- EU Novel Food Ingredient Pathways:EFSA approval frameworks for emerging binding agents create first-mover advantage windows for reformulated clean-label emulsions.
- Food Service Bulk Dispensing:Pump-format aquafaba-based dressings for commercial kitchens reduce packaging waste while capturing institutional procurement contracts.
Industry Challenges
- Emulsion Stability Expertise Gap:Food science talent capable of optimizing aquafaba-protein interactions without egg yolk phospholipids commands premium compensation in tight labor markets.
- Clean-Label Certification Timeline:Third-party non-GMO and organic verification processes extend product launch cycles by six to twelve months versus conventional alternatives.
- Cold Chain Integration Complexity:Refrigerated egg-free formulations require reconfiguration of legacy ambient condiment distribution infrastructure at retail and food service tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egg-Free Dressing Market |
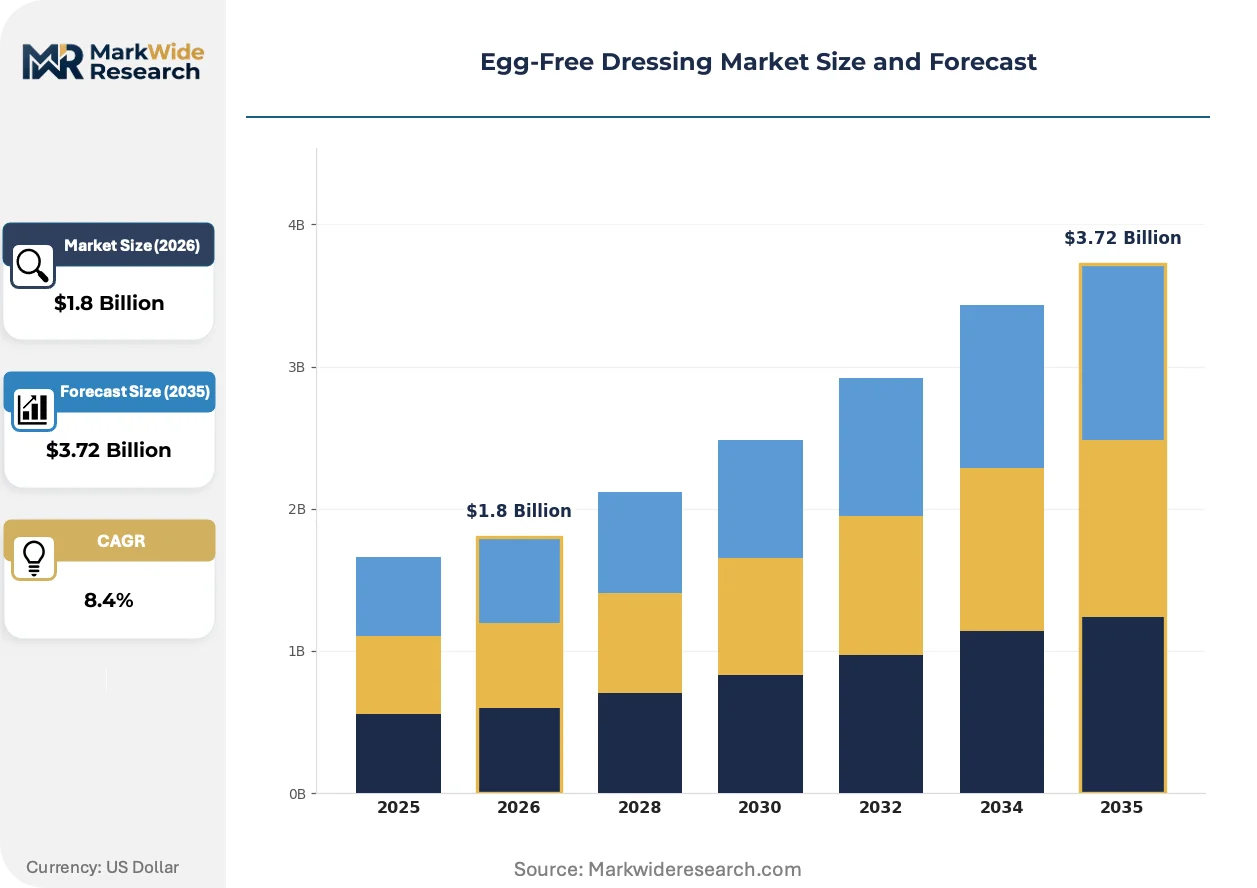
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegan Mayonnaise, Salad Dressings, Sauces, Dips Ingredient Base: Avocado, Aquafaba, Soy, Nuts Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Food Service Consumer Segment: Health-Conscious, Vegans, Allergic Individuals, Culinary Professionals |
| Companies Covered | Unilever, Kraft Heinz Company, Follow Your Heart, Eat Just, Inc., Dr. Oetker, McCormick, Annie's Homegrown, Newman's Own, Danone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egg-Free Dressing Market Shifts & Advancements
Reformulation science is advancing beyond simple egg substitution toward functional parity in mouthfeel, stability, and browning response. Manufacturers are deploying precision fermentation and enzymatic modification to close sensory gaps with traditional mayonnaise.
High-pressure processing technology is displacing thermal pasteurization in refrigerated egg-free dressing production. Premium natural retailers and food service distributors are adopting HPP-treated SKUs to extend clean-label shelf life without chemical preservatives. This shift is compressing the viability window for conventional preservative-stabilized formulations in the refrigerated set.
REACH-compliant emulsifier approvals under ECHA frameworks are reshaping which binding agents gain commercial traction across EU member states. Manufacturers reformulating for European export must navigate substance authorization timelines that lag FDA Generally Recognized as Safe determinations by eighteen to thirty-six months. The regulatory friction is accelerating regional formulation divergence between North American and European product lines.
Metropolitan health food retail density in the United States is concentrating demand for premium-positioned SKUs within specific urban corridors. Brooklyn, Austin, and Portland clusters generate disproportionate velocity for aquafaba-based and avocado-oil formulations. Regional distributors are consolidating warehouse allocation models around these demand nodes, bypassing traditional broadline distribution for temperature-controlled direct delivery.
Egg-Free Dressing Market Segmentation
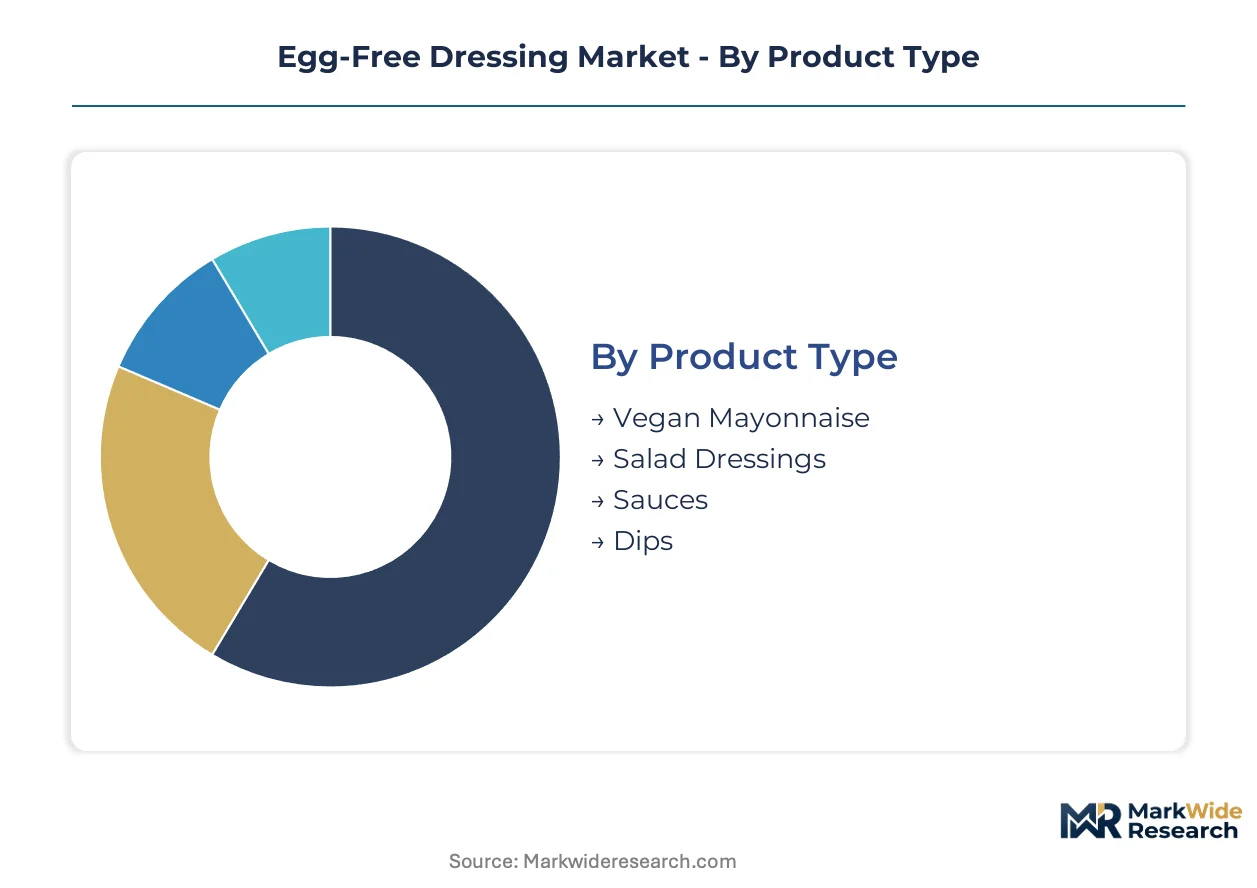
Segmentation in the egg-free dressing market reflects divergent regulatory pressures and sourcing economics across formulation types and buyer categories. Manufacturers optimize production lines around specific binding agent portfolios and cold-chain requirements rather than pursuing universal formulations.
Product Type:
FDA standards of identity disputes and EU nomenclature rules create divergent permissible claims across mayonnaise-alternative categories, forcing region-specific product architectures.
- Vegan Mayonnaise:Emulsified condiments in the 3,000–15,000 centipoise viscosity range rely on aquafaba or modified starches to replicate egg yolk functionality. Quick-service restaurant chains in the United States specify vegan mayonnaise for plant-based sandwich programs to maintain operational interchangeability with conventional mayonnaise. This segment handles the majority of throughput; salad dressings are the fastest mover on share.
- Salad Dressings:Pourable emulsions and vinaigrettes formulated without egg leverage lecithin or gum systems for suspension stability. Metropolitan health food retail clusters in Brooklyn, Austin, and Portland generate disproportionate velocity for refrigerated clean-label variants with shortened ingredient decks.
- Sauces:Spoonable condiments including tartar, hollandaise-style, and specialty finishes for food service plating applications.
- Dips:Thickened preparations for direct consumption, typically requiring higher viscosity and enhanced flavor masking of plant-based binding systems.
Volume concentrates in vegan mayonnaise due to food service operational requirements; salad dressings climb fastest as clean-label retail penetration deepens.
Ingredient Base:
Input cost volatility and supply geography dictate formulation choices for manufacturers targeting specific price tiers and sustainability positioning.
- Avocado:Oil-based emulsions deliver premium mouthfeel and monounsaturated fat positioning. Drought conditions in Mexican and Peruvian growing regions create procurement cost instability that constrains mass-market expansion.
- Aquafaba:Chickpea processing residue provides neutral-flavor emulsification with zero-waste sourcing credentials. Commercial hummus and canned chickpea operations supply aquafaba extraction networks that large CPG manufacturers are securing through long-term procurement contracts.
- Soy:Lecithin and protein isolate systems offer cost-competitive binding with established supply infrastructure.
- Nuts:Cashew and almond bases deliver premium positioning in specialty natural retail channels with higher fat content and distinctive flavor profiles.
Avocado oil anchors premium tier positioning; aquafaba gains share fastest on sustainability credentials and neutral sensory performance.
Distribution Channel:
Cold-chain capabilities and margin structures vary dramatically across channel types, forcing SKU differentiation in packaging format and shelf-life engineering.
- Supermarkets:Ambient and refrigerated sets controlled by slotting fee structures favor manufacturers with broad SKU portfolios and established retail relationships. Kraft Heinz Company leverages shelf-space dominance to maintain mainstream visibility.
- Online Retail:Subscription and direct-to-consumer models capture the highest margin pool through temperature-controlled logistics targeting metropolitan health food consumers. Follow Your Heart and specialty brands bypass supermarket slotting fees through refrigerated subscription boxes.
- Health Food Stores:Natural retail channels prioritize clean-label certification tiers and regional brand differentiation.
- Food Service:Bulk dispensing formats and pump systems for commercial kitchens emphasize operational efficiency and waste reduction in institutional procurement contracts.
Supermarkets move the largest absolute volume; online retail expands most quickly on margin capture and direct consumer relationships.
Consumer Segment:
FALCPA disclosure requirements and allergen avoidance behaviors create distinct purchasing triggers that manufacturers address through label architecture and channel placement.
- Health-Conscious:Buyers prioritizing cholesterol reduction and clean-label ingredient decks drive refrigerated set expansion in metropolitan corridors.
- Vegans:Ethical positioning and dedicated vegan brand equity built over decades commands loyalty and price tolerance in specialty channels.
- Allergic Individuals:Egg avoidance mandated by FALCPA labeling requirements creates demand for explicit "egg-free" claims rather than mere omission, with parents of children with egg allergies driving household penetration.
- Culinary Professionals:Food service chefs and institutional buyers specify functional performance parameters including emulsion stability under heat and freeze-thaw tolerance for operational reliability.
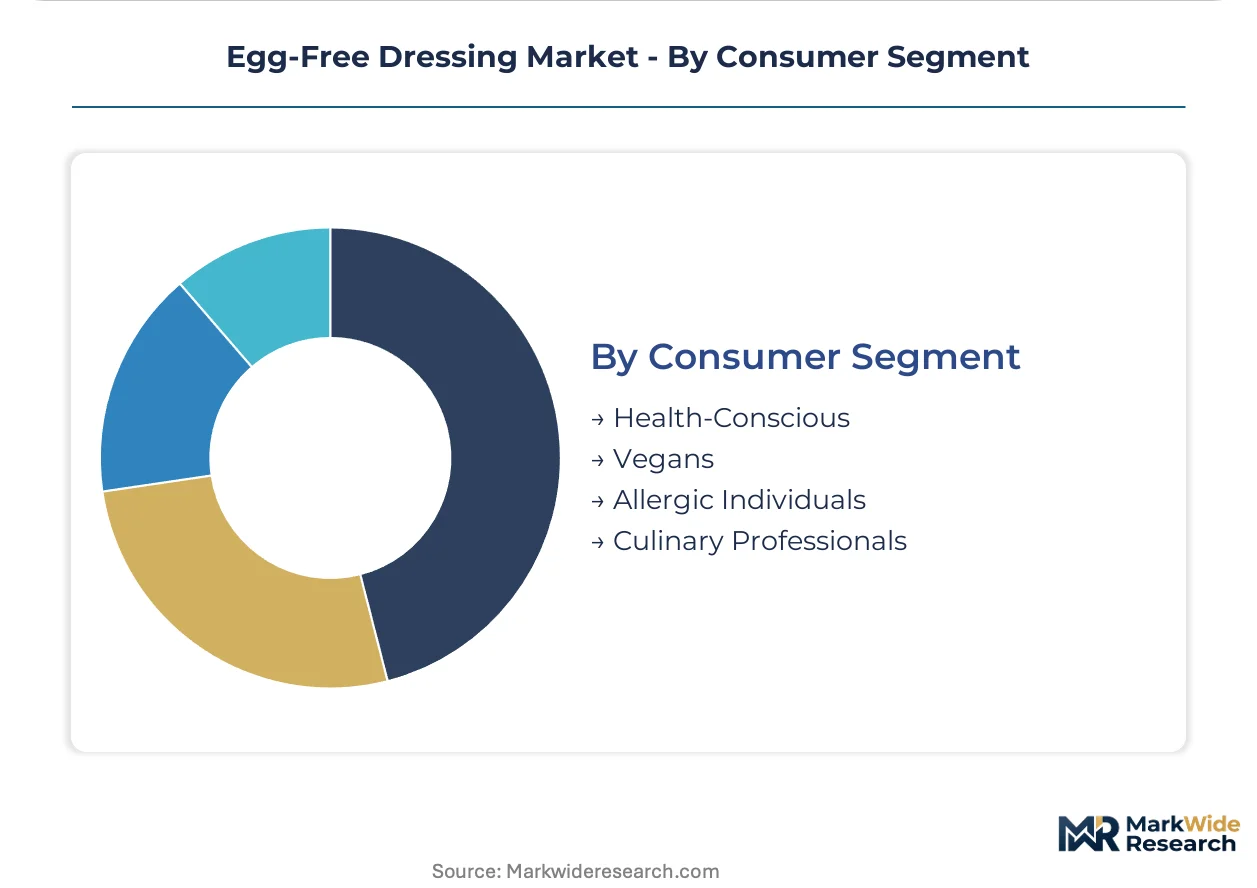
Health-conscious consumers provide the broadest addressable base; allergic individuals represent the most price-inelastic demand segment with regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for egg-free dressings diverges sharply across markets. Metropolitan health food clusters in the United States absorb premium pricing with minimal volume loss, while mass-market penetration in emerging economies demands aggressive cost engineering to match conventional mayonnaise price points.
United States
FDA allergen disclosure mandates under FALCPA compel explicit "egg-free" labeling that converts regulatory compliance into marketing advantage. Brooklyn, Austin, and Portland health food retail corridors generate disproportionate velocity for aquafaba-based and avocado-oil formulations. Cold-chain infrastructure investments by regional distributors now bypass traditional broadline networks for temperature-controlled direct delivery to these demand nodes.
Germany
EFSA novel food ingredient frameworks and REACH-compliant emulsifier approvals determine which binding agents gain commercial traction across EU member states. ECHA substance authorization timelines lag FDA GRAS determinations by eighteen to thirty-six months, accelerating formulation divergence from North American product lines. Berlin and Hamburg metropolitan clusters concentrate demand for clean-label refrigerated variants with shortened ingredient decks.
United Kingdom
Post-Brexit divergence from EU food information standards creates parallel compliance obligations for manufacturers serving both markets. The Food Standards Agency maintains allergen labeling stringency comparable to FALCPA, preserving "free-from" claim viability. London and Southeast England retail density supports premium positioning for subscription-based specialty brands circumventing supermarket slotting fees.
Canada
Health Canada and PMRA regulatory alignment with FDA standards facilitates cross-border product standardization, though bilingual labeling requirements add production complexity. Toronto and Vancouver metropolitan markets mirror U.S. health food retail density patterns. Food service operators in these corridors specify vegan mayonnaise for plant-based menu expansion with operational interchangeability requirements.
Australia
TGA and FSANZ food standards govern allergen declaration protocols with enforcement intensity comparable to FDA and EFSA frameworks. Sydney and Melbourne metropolitan clusters concentrate demand for premium-positioned refrigerated SKUs. Regional distributors are consolidating warehouse allocation models around these demand nodes, replicating the direct-delivery infrastructure emerging in U.S. urban corridors.
Egg-Free Dressing Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics rather than direct confrontation. Large multinational CPG manufacturers leverage global procurement infrastructure and retail shelf-space dominance to anchor mainstream volume positions. Mid-scale specialty brands compete through dedicated vegan brand equity and direct-to-consumer channel control. Emerging entrants exploit novel ingredient pathways and regional regulatory arbitrage to secure niche positioning. Dominant competitive moves include strategic partnerships with chickpea processing operations for aquafaba supply security, and portfolio diversification across refrigerated and ambient formulation formats.
Within the multinational CPG tier, Unilever and Kraft Heinz Company occupy positions defined by procurement scale and retail access respectively. Unilever leverages global infrastructure to secure aquafaba and avocado oil supplies at volume. Kraft Heinz Company anchors mainstream visibility through established supermarket relationships. Among dedicated vegan specialists, Follow Your Heart exemplifies decades-built brand equity that commands loyalty and price tolerance in specialty channels. These three players represent the archetype spectrum: procurement-scale multinational, shelf-space dominant incumbent, and purpose-built vegan specialist.
| Leading Market Players |
|---|
| Unilever |
| Kraft Heinz Company |
| Follow Your Heart |
| Eat Just, Inc. |
| Dr. Oetker |
| McCormick |
| Annie's Homegrown |
| Newman's Own |
| Danone |
| Others |
Supply & Pricing Matrix
Clean-label certification tiers gate both supplier qualification and price differentiation simultaneously, as USDA Organic and Non-GMO Project verification determine which aquafaba and avocado oil sources command premium positioning against conventional modified starch alternatives. Manufacturers without certification access face margin compression in supermarket slotting fee environments while certified players capture subscription channel price premiums.
Pricing Analysis
After-sales revenue through refrigerated subscription boxes and direct-to-consumer replenishment drives lifetime value beyond initial unit economics. Three-tier pricing structure across premium avocado-oil, standard aquafaba, and economy modified-starch levels segments buyers by certification sensitivity and mouthfeel requirements. Pricing pressure stems from drought-driven avocado oil cost volatility squeezing premium tier margins. Health-conscious metropolitan consumers show least price sensitivity; mass-market flexitarian buyers through quick-service channels exhibit highest elasticity.
Supply Chain Analysis
Just-in-time aquafaba sourcing from commercial hummus operations dominates over strategic stockpiling due to spoilage constraints and chickpea processing residue perishability. Supply concentrates in Mexico and Peru for avocado oil, Eastern Europe and Argentina for sunflower lecithin, and domestic U.S. chickpea processing corridors for aquafaba. Binding agent procurement draws from single-source vulnerability in lecithin production clusters. Distribution runs through temperature-controlled regional direct delivery bypassing traditional broadline networks for refrigerated SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The egg-free dressing market sits in early-cycle expansion as flexitarian menu adoption at quick-service chains accelerates penetration beyond vegan core consumers into mainstream daypart occasions.
For Market Incumbents: Fortify aquafaba supply security through long-term procurement contracts with chickpea processing operations, locking in zero-waste sourcing credentials before mid-scale competitors consolidate access. Expand cold-chain distribution infrastructure in Brooklyn, Austin, and Portland metropolitan clusters to defend against specialty brands bypassing supermarket slotting fees through direct delivery. For New Entrants and Emerging Players: Lead with food service bulk dispensing formats targeting institutional procurement contracts, as pump-system operational efficiency creates white-space outside retail-dominated incumbent strongholds. Target quick-service restaurant chains requiring vegan mayonnaise operational interchangeability with conventional alternatives, positioning on functional parity rather than ethical differentiation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across refrigerated clean-label formulation capacity as HPP technology deployment and cold-chain infrastructure requirements reshape viable scale thresholds. Acquisition candidates with established EFSA novel food ingredient approvals and REACH-compliant emulsifier portfolios offer European market access arbitrage. Watch aquafaba supply contract renewal cycles as inflection indicator for input cost trajectory and margin sustainability across the projection horizon.| Strategic Initiative | Industry Significance |
|---|---|
| Aquafaba Supply Contracting | Long-term chickpea processing partnerships lock in zero-waste binding agent security against procurement leverage asymmetries. |
| HPP Technology Deployment | High-pressure processing adoption extends clean-label shelf life without chemical preservatives in refrigerated sets. |
| Direct-to-Consumer Subscription Launch | Refrigerated subscription boxes bypass supermarket slotting fees while capturing highest-margin metropolitan health food demand. |
| EFSA Novel Food Approval Pathway | First-mover binding agent authorization under EU frameworks creates eighteen-to-thirty-six month regulatory arbitrage windows. |
| Food Service Bulk Dispensing Format | Pump-format systems reduce packaging waste while securing institutional procurement contracts with operational efficiency specifications. |
Research Methodology
Cross-validation between food service operator interviews and retail audit data anchors the qualitative findings across the analysis window. Primary fieldwork engaged R&D directors at CPG manufacturers, category buyers at natural retailers, procurement leads at quick-service chains, and food science talent specializing in emulsion stability. Secondary sources incorporated FDA FALCPA guidance documents, EFSA novel food ingredient registers, USDA organic certification databases, and refrigerated distribution infrastructure disclosures. Bottom-up SKU velocity modeling triangulated against top-down category expenditure estimates.
Sensitivity analysis around aquafaba supply concentration and avocado oil price volatility informs the forecast framework across the projection horizon. Segmentation dimensions modeled include ingredient base, product type, distribution channel, and consumer segment with regional regulatory cluster differentiation. CAGRs derived from weighted average of historical velocity trends and adoption curve penetration assumptions. Forecast inputs incorporated quick-service plant-based menu expansion rates and clean-label certification timeline impacts on product launch cycles.
The analysis sits within stated boundaries; outcomes outside sustained flexitarian spending growth or EFSA approval timeline acceleration would require recalibration. Forecasts reflect assumptions around cold-chain infrastructure investment continuity and chickpea processing residue supply scaling. Revision becomes warranted when aquafaba procurement cost spreads versus synthetic emulsifiers cross threshold differentials or when standards of identity disputes trigger jurisdictional label compliance disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Soups and Sauces Market
Condiments & Sauces
Sandwich Spread Market
Condiments & Sauces
Low Fat Pasta Sauce Market
Condiments & Sauces
Dry Cooking Sauces Market
Condiments & Sauces
Sweet and Savory Spread Market
Condiments & Sauces
Curry Cube Market
Condiments & Sauces
Hoisin Sauce Market
Condiments & Sauces
Culinary Sauces Market
Condiments & Sauces
Condiments Market
Condiments & Sauces
Pesto Sauces Market
Condiments & Sauces
Cooking Sauces Market
Condiments & Sauces
Asia-Pacific Condiments Market
Condiments & Sauces
Vegan Pasta Sauce Market
Condiments & Sauces
Acciughe Pasta Sauce Market
Condiments & Sauces
Dips and Spreads Market
Condiments & Sauces
Dipping Sauces Market