
 Asia Pacific Hot Sauce Market | 2026-2036
Asia Pacific Hot Sauce Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Hot Sauce Market Insights
Vietnam is rewriting condiment manufacturing dynamics as industrial park investments in Binh Duong and Long An provinces attract regional sauce producers. Huy Fong Foods leverages its Sriracha production expertise to sustain brand recognition across Southeast Asian export channels. Lee Kum Kee anchors premium positioning through fermented bean and chili formulations that dominate Chinese diaspora markets. Kikkoman Corporation competes via diversified Asian sauce portfolios extending beyond soy into chili-based variants.
Asia Pacific hot sauce encompasses chili-based condiments manufactured through fermentation, vinegar acidification, or fresh pepper maceration, typically achieving Scoville ratings from 1,000 to over 50,000 SHU depending on pepper cultivar and capsaicin extraction method. These products serve primarily as flavor enhancers for prepared foods, table condiments, and industrial ingredient inputs across foodservice and retail channels. Chili sauce segments occupy the largest volume share due to universal compatibility with regional cuisines, while Sriracha formulations generate disproportionate margin pools through premium positioning in urban retail. Glass bottle packaging dominates perceived quality tiers despite higher logistics costs, whereas pouch formats capture institutional foodservice demand through portion control and reduced breakage.
FSSAI in India mandates additive disclosure and capsaicin content labeling that shapes product reformulation strategies for entrants targeting the subcontinent. China's SAMR enforces GB standards for fermented condiments that determine market access eligibility for imported and domestic brands alike. Australia's TGA parallel import rules and FSANZ labeling requirements create additional compliance layers for regional exporters. Stakeholders must monitor evolving capsaicin threshold definitions and packaging sustainability mandates as regulatory divergence between jurisdictions intensifies supply chain complexity.
Market Dynamics
FSSAI clean-label mandates in India and SAMR fermentation standards in China are compressing formulation cycles across the Asia Pacific hot sauce landscape, forcing manufacturers to rebuild preservative systems and accelerate natural ingredient sourcing.
Growth Catalysts
- Quick-service restaurant procurement:Southeast Asian fast-food chains are expanding hot sauce volumes as menu localization accelerates in Vietnam, Thailand, and the Philippines.
- FSSAI additive disclosure rules:India's enforcement of capsaicin content labeling is pulling manufacturers toward transparent ingredient decks and natural preservative alternatives.
- Urban corridor demand concentration:Vietnam's Ho Chi Minh City to Da Nang corridor is anchoring premium sauce consumption through rising middle-class household formation.
Market Restraints
- Fresh chili input volatility:Weather-dependent harvests in India's Andhra Pradesh and Vietnam's Central Highlands create raw material cost instability for fermentation-based producers.
- Glass bottle logistics burden:Premium packaging formats impose higher freight costs and breakage rates across Southeast Asian archipelago distribution.
- Regulatory divergence friction:Australia's TGA parallel import rules and FSANZ labeling requirements add compliance layers that slow regional exporter market entry timelines.
Strategic Opportunities
- Indonesia's underpenetrated retail:Modern trade expansion in Jakarta and Surabaya creates shelf space for premium chili sauce entrants beyond traditional warung channels.
- Pouch format foodservice adoption:Institutional buyers in Singapore and Malaysia are shifting toward portion-control packaging that reduces waste and simplifies inventory management.
- PLI scheme alignment:India's production-linked incentive framework for food processing offers capital subsidy pathways for domestic fermentation capacity buildout.
Industry Challenges
- Fermentation microbiology talent scarcity:Commercial-scale koji and lacto-fermentation expertise remains concentrated in legacy Chinese and Japanese producers, limiting new entrant process reliability.
- Dual certification timelines:Simultaneous GB standards compliance for China and FSSAI registration for India extends product launch cycles by twelve to eighteen months.
- Legacy ERP integration:Mid-tier manufacturers face friction connecting batch-level traceability systems to modern supply chain visibility platforms required by major retailers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Hot Sauce Market |
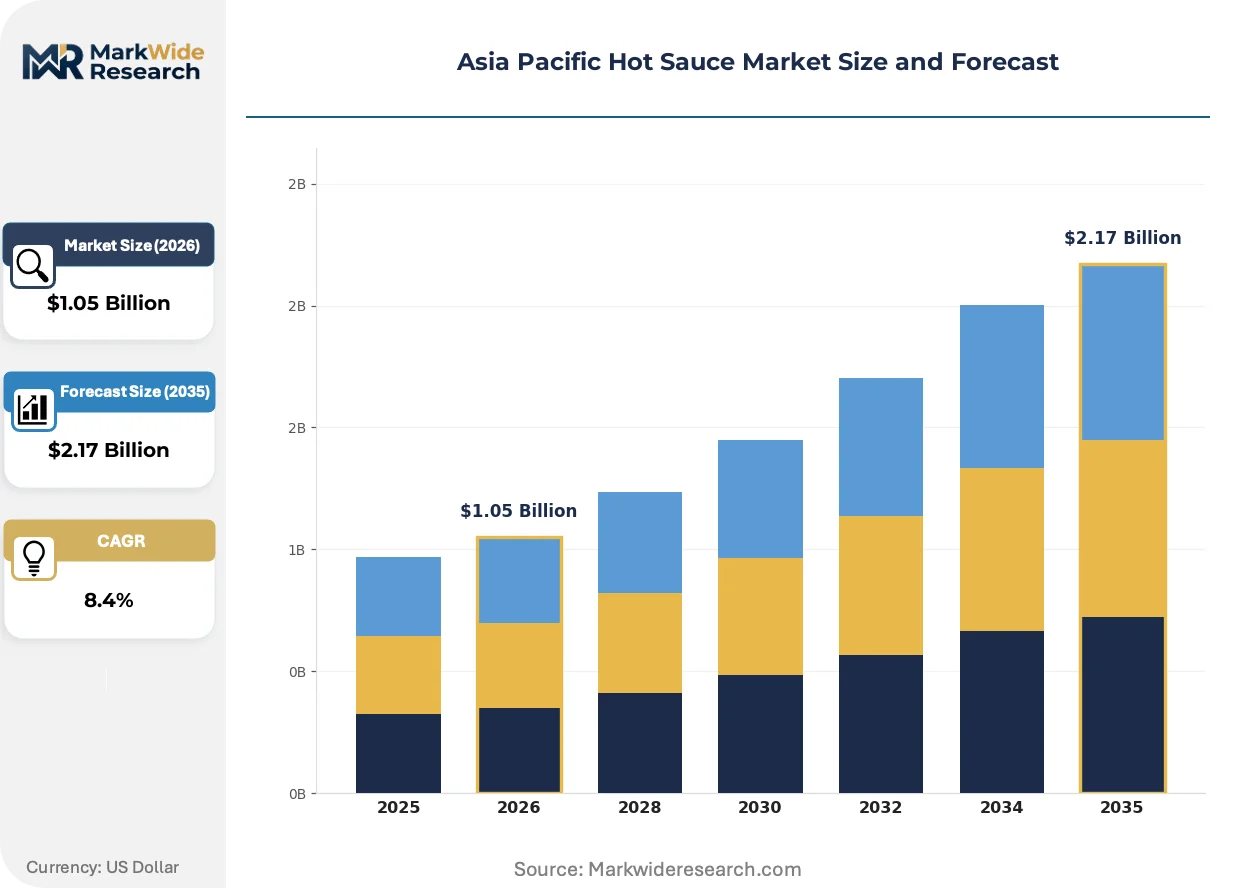
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chili Sauce, Sriracha, Salsa, Barbecue Sauce Flavor Profile: Spicy, Sweet, Smoky, Tangy Packaging Type: Glass Bottles, Plastic Bottles, Pouches, Jars Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Convenience Stores |
| Companies Covered | East by Northeast, Integrow Brands Pvt. Ltd., El Diablo Sauces, Pico Sauces, NAAGIN Sauces, Thaitan Foods International Co. Ltd., Lee Kum Kee, Huy Fong Foods, Kikkoman Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Hot Sauce Market Trends and Innovations
Automation and sensor-based process control are penetrating condiment manufacturing floors, compressing batch-to-batch variation while enabling real-time capsaicin consistency monitoring across fermentation and acidification workflows.
Hyperspectral imaging is digitizing quality assurance protocols in premium hot sauce production lines. Large-scale fermentation facilities in Thailand and Vietnam are deploying inline spectroscopy to monitor pepper mash maturity and vinegar acidification curves without laboratory latency. This compression of analytical feedback loops is enabling just-in-time blending adjustments that protect margin pools in high-Scoville product tiers.
SAMR enforcement of GB standards for fermented condiments is tightening import documentation requirements and domestic facility inspection cadences. Manufacturers targeting China must now demonstrate HACCP-equivalent process controls and submit capsaicin stability data across shelf-life testing protocols. The premium retail segment is responding by investing in captive laboratory capacity to accelerate compliance documentation turnaround.
Foodservice procurement patterns are fragmenting as regional cloud kitchen operators bypass traditional distributor tiers. Direct-to-operator purchasing platforms in Singapore and Bangkok are compressing order cycles from monthly to weekly frequencies while demanding smaller minimum order quantities. This channel disintermediation is most visible in Vietnam's Ho Chi Minh City metropolitan zone, where independent restaurant clusters are consolidating purchasing through mobile-enabled procurement collectives.
Asia Pacific Hot Sauce Market Segmentation
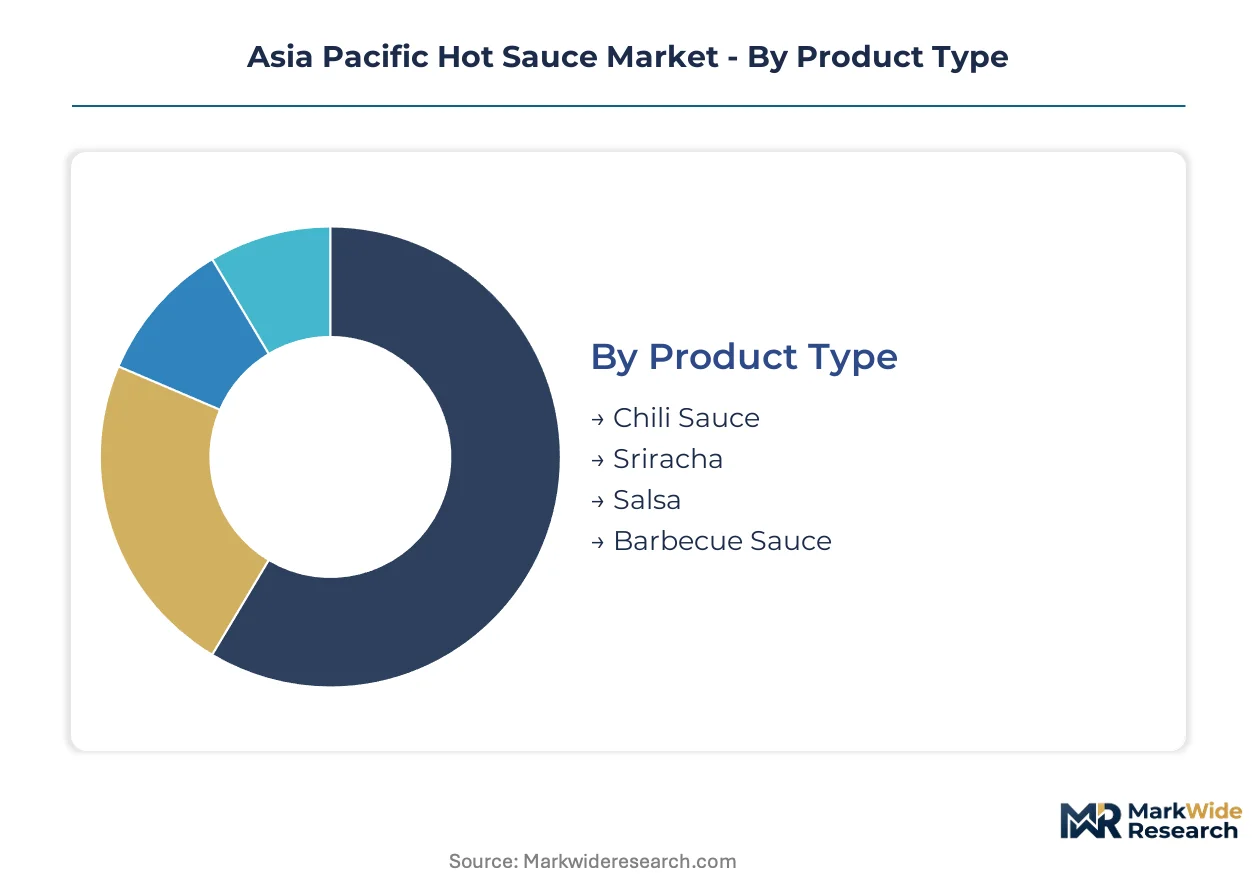
Hot sauce segmentation across Asia Pacific reflects divergent consumption contexts, from industrial foodservice procurement to premium retail gifting. Manufacturers calibrate formulation intensity, packaging format, and channel strategy against distinct margin structures and regulatory requirements in each slice.
Product Type:
Mature chili sauce formats anchor volume throughput across institutional buyers, while emerging variants capture urban premiumization.
- Chili Sauce:Fermented or vinegar-based preparations using bird's eye, cayenne, or local cultivars achieve Scoville ratings from 2,000 to 30,000 SHU. Quick-service chains in Vietnam's Ho Chi Minh City corridor standardize procurement around 5-liter foodservice pouches for kitchen-line efficiency. Chili sauce retains volume leadership; Sriracha holds the steepest expansion curve.
- Sriracha:Emulsified chili-garlic formulations with sugar and vinegar balance heat with sweetness, typically registering 2,500-5,000 SHU. Thailand's Chonburi province and Vietnam's Binh Duong industrial parks concentrate fermentation capacity serving export demand to Australia and Japan. Urban retail in Bangkok and Jakarta positions Sriracha as a premium table condiment with 40-60% price premiums over commodity chili sauce.
- Salsa:Tomato-based preparations with jalapeño or habanero additions target expatriate communities and Western-influenced foodservice in Singapore and Kuala Lumpur.
- Barbecue Sauce:Smoke-infused variants with mild heat profiles align with Korean and Australian grilling cultures, penetrating modern trade in Seoul and Sydney.
Chili sauce retains volume leadership; Sriracha holds the steepest expansion curve.
Flavor Profile:
Cost tier stratification separates commodity heat delivery from layered taste experiences commanding formulation premiums.
- Spicy:Pure capsaicin-forward formulations dominate industrial foodservice where heat intensity drives purchase decisions. Central kitchen operators in Manila and Jakarta specify minimum Scoville thresholds without sweetness interference.
- Sweet:Palm sugar or honey-balanced profiles resonate with Thai and Vietnamese palate preferences, capturing premium positioning in Bangkok's gourmet retail. Sweet variants gain share fastest among millennial households in Vietnam's Da Nang urban corridor.
- Smoky:Chipotle or liquid smoke infusions target barbecue culture adoption in Australia and South Korea, requiring specialized ingredient import channels.
- Tangy:Elevated vinegar acidity cuts through fatty protein preparations, preferred by Filipino and Malaysian foodservice for pork and poultry applications.
Spicy formulations dominate procurement volumes; sweet profiles are expanding most quickly in premium retail.
Packaging Type:
Application context dictates format selection, with foodservice prioritizing operational efficiency and retail emphasizing shelf presence.
- Glass Bottles:Premium positioning vehicles with superior oxygen barrier properties protect fermented product integrity across 18-24 month shelf lives. Australia's FSANZ labeling mandates and Singapore's strict import documentation favor glass for traceability compliance.
- Plastic Bottles:HDPE and PET formats reduce freight weight by 60-70% versus glass, enabling cost-competitive distribution across Indonesia's archipelago logistics. Plastic bottles scale fastest in Jakarta and Surabaya modern trade expansion.
- Pouches:Flexible multilayer films with spout closures capture institutional demand in Singapore's cloud kitchen clusters and Malaysia's hospital catering, reducing waste and enabling precise portion control.
- Jars:Wide-mouth glass or PET containers accommodate chunky salsa and relish textures, occupying specialty store shelves in Melbourne and Auckland.
Glass bottles command retail premium tiers; pouches are gaining share fastest in foodservice procurement.
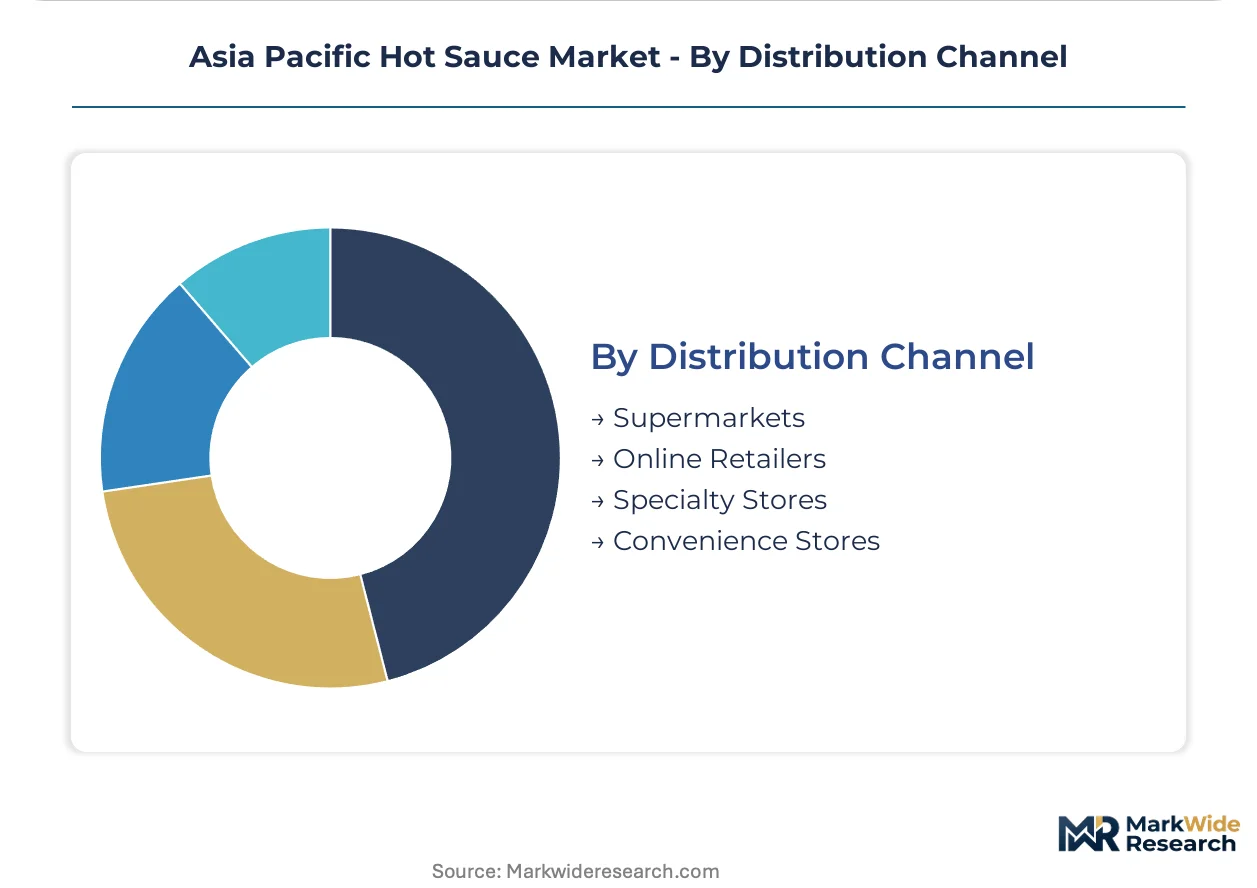
Distribution Channel:
Customer type fragmentation separates mass-market throughput from curated discovery experiences with divergent service requirements.
- Supermarkets:Hypermarket and supermarket chains in Thailand's CP All network and Vietnam's VinMart system enforce strict slotting fees and promotional calendar compliance. Supermarket volumes concentrate in Bangkok's metropolitan zone and Ho Chi Minh City's District 2 retail corridors.
- Online Retailers:Shopee, Lazada, and Tokopedia platforms enable direct-to-consumer reach bypassing traditional distributor margins, climbing fastest in Indonesia's underpenetrated secondary cities. Same-day delivery promises in Singapore and Kuala Lumpur reshape replenishment frequency from monthly to weekly cycles.
- Specialty Stores:Gourmet importers and ethnic grocers in Sydney's Cabramatta and Melbourne's Box Hill serve diaspora communities seeking authentic regional formulations unavailable in mass retail.
- Convenience Stores:7-Eleven, FamilyMart, and local chains stock impulse-format sachets and small bottles for immediate consumption, anchoring penetration in Japan's urban corridors and Taiwan's night market districts.
Supermarkets retain volume leadership; online retailers are expanding most quickly across Southeast Asian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI in India anchors regulatory momentum across the Asia Pacific hot sauce landscape, with its additive disclosure mandates reshaping formulation standards that neighboring jurisdictions increasingly reference. China's SAMR fermentation protocols and Vietnam's industrial park incentives collectively determine where capacity investments flow.
Vietnam
Urban household formation along the Ho Chi Minh City to Da Nang corridor drives premium sauce consumption. Provincial industrial zones in Binh Duong and Long An attract fermentation capacity through tax holidays and streamlined permitting. Huy Fong Foods maintains export-oriented production facilities serving Australian and Japanese markets from this manufacturing base.
China
GB standards enforcement by SAMR compresses import documentation timelines and intensifies domestic facility inspection cadences. Fermented condiment regulations require HACCP-equivalent process controls and capsaicin stability data across shelf-life testing. Lee Kum Kee anchors premium positioning through bean and chili formulations targeting diaspora communities in Southeast Asia and Australia.
India
FSSAI clean-label mandates pull manufacturers toward natural preservative alternatives and transparent ingredient decks. The PLI scheme for food processing offers capital subsidy pathways for domestic fermentation capacity buildout. Andhra Pradesh's chili belt supplies raw material inputs, though weather-dependent harvests create cost volatility for acidification-based producers.
Thailand
Chonburi province concentrates Sriracha fermentation capacity serving export demand to premium retail in Australia and Japan. Quick-service restaurant procurement from Bangkok-based chains standardizes around 5-liter foodservice pouches for kitchen-line efficiency. Kikkoman Corporation competes through diversified Asian sauce portfolios extending into chili-based variants for regional foodservice.
Indonesia
Modern trade expansion in Jakarta and Surabaya creates shelf space for premium chili sauce entrants beyond traditional warung channels. Pouch format adoption accelerates among institutional buyers seeking portion control and reduced waste. Regulatory harmonization with ASEAN standards remains incomplete, extending product registration timelines for imported formulations.
Asia Pacific Hot Sauce Market Competitive Landscape
Capability concentration sits with fermentation specialists possessing legacy microbiology expertise; scale advantage sits with diversified sauce conglomerates leveraging cross-category distribution infrastructure. The market structure tiers between premium heritage brands commanding diaspora loyalty and mid-tier regional players competing on procurement efficiency. Three archetypes dominate: fermentation heritage houses, diversified Asian sauce portfolios, and niche export-oriented specialists. Competitive moves center on backward integration into chili cultivation and strategic partnerships with cloud kitchen procurement platforms.
Within the heritage fermentation tier, Lee Kum Kee and Huy Fong Foods exemplify contrasting geographic anchoring strategies. Lee Kum Kee represents the Chinese diaspora-focused archetype with bean-based formulation expertise. Huy Fong Foods occupies the export-oriented specialist position, leveraging Sriracha production recognition across Southeast Asian channels. Kikkoman Corporation sits within the diversified portfolio archetype, extending soy sauce distribution infrastructure into chili-variant categories. These three players collectively illustrate how regional origin and category breadth determine competitive positioning in Asia Pacific hot sauce markets.
| Leading Market Players |
|---|
| East by Northeast |
| Integrow Brands Pvt. Ltd. |
| El Diablo Sauces |
| Pico Sauces |
| NAAGIN Sauces |
| Thaitan Foods International Co. Ltd. |
| Lee Kum Kee |
| Huy Fong Foods |
| Kikkoman Corporation |
| Others |
Pricing and Supply Chain Analysis
Vietnam's Central Highlands and India's Andhra Pradesh chili belts concentrate raw material sourcing for fermentation-based producers, anchoring margin pools in premium retail tiers where glass bottle packaging commands shelf price premiums. Pricing power downstream reflects upstream weather volatility and the logistics burden of premium formats across Southeast Asian archipelago distribution.
Pricing Analysis
Urban retail in Bangkok and Ho Chi Minh City commands 40-60% premiums over commodity tiers for Sriracha formulations, while foodservice procurement in Jakarta and Manila operates on volume-scaled contract pricing. Three-tier pricing structure across premium, standard, and economy levels separates heritage fermentation brands from private-label entrants and institutional bulk supply. Cost compression in the pouch format tier is intensifying because cloud kitchen operators demand weekly replenishment cycles with smaller minimum orders. Quick-service chains exhibit highest price sensitivity; diaspora-focused specialty retailers show least.
Supply Chain Analysis
Fresh chili feedstock draws from Vietnam, India, and Thailand, with bird's eye and cayenne cultivars anchoring regional fermentation recipes. Glass bottles, HDPE containers, and multilayer flexible films constitute critical packaging inputs alongside vinegar acidification agents. Single-source vulnerability concentrates in weather-dependent harvest cycles that disrupt input cost stability. Distribution runs through modern trade networks in Bangkok and Jakarta, cloud kitchen procurement platforms in Singapore, and traditional warung channels across Indonesian secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from private-label entrants and direct-to-operator platforms that bypass traditional distributor tiers, compressing margin capture for legacy brands.
For Market Incumbents: Harden fermentation microbiology capabilities through captive laboratory investment or specialist recruitment to defend against process reliability gaps. Secure backward integration into chili cultivation in Vietnam's Central Highlands or Andhra Pradesh to buffer raw material volatility. Channel control through exclusive cloud kitchen platform partnerships represents the critical defensive lever against disintermediation. For New Entrants and Emerging Players: Pursue Indonesia's underpenetrated modern trade corridors in Surabaya and Bandung where premium shelf space remains available beyond entrenched warung networks. Target pouch format foodservice contracts in Malaysia's hospital catering and Singapore's institutional procurement where portion control demand outstrips supply. A direct-to-operator go-to-market angle through mobile-enabled procurement collectives bypasses distributor margin stacking. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-tier regional fermentation houses possessing legacy koji expertise but lacking ERP integration for batch traceability. Long-term viability hinges on regulatory compliance automation and captive laboratory capacity buildout. Watch FSSAI capsaicin threshold revisions as the inflection signal for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chili Cultivation | Captive supply from Vietnam's Central Highlands buffers weather-driven input volatility for fermentation-based producers. |
| Cloud Kitchen Platform Partnership | Direct procurement relationships with Singapore and Bangkok operators bypass traditional distributor margin extraction. |
| Premium Glass Bottle Line Expansion | Oxygen barrier properties protect fermented product integrity for 18-24 month shelf life in Australian retail. |
| Pouch Format Foodservice Launch | Multilayer flexible films with spout closures capture institutional demand in Malaysia's hospital catering sector. |
| Captive Laboratory Compliance Buildout | In-house capsaicin stability testing accelerates SAMR documentation turnaround for China market access. |
Research Methodology
The analysis maps chili sauce, Sriracha, salsa, and barbecue sauce segments, each validated through fermentation microbiologists, quick-service restaurant procurement directors, modern trade category buyers, and cloud kitchen platform operators. Primary interviews with supply chain planners at regional manufacturers and distribution channel partners in Vietnam, Thailand, and Indonesia combined with secondary validation from FSSAI additive disclosure filings, SAMR GB standards documentation, and customs trade data. Bottom-up volume builds and top-down market sizing triangulate against Nielsen retail audit data and foodservice procurement platform transaction records.
Assumptions held fixed include FSSAI enforcement intensity and SAMR inspection cadences, while chili harvest yield variability and cloud kitchen penetration rates were stress-tested across scenarios. Segmentation dimensions modeled encompass product type, flavor profile, packaging format, and distribution channel alongside regional regulatory cluster differentiation. CAGRs were derived from trend extrapolation anchored in documented procurement volume shifts and urban household formation patterns. Industry-specific inputs include Scoville rating standardization trends and fermentation capacity utilization rates across Binh Duong and Chonburi industrial zones.
Sensitivities concentrate around FSSAI capsaicin threshold revisions, SAMR import documentation timeline compressions, and weather-driven chili harvest disruptions. Forecasts reflect these assumptions with acknowledged variance potential from regulatory divergence acceleration or logistics cost spikes. Cross-checking against VinMart and CP All promotional calendar data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Egg-Free Dressing Market
Condiments & Sauces
Vegan Pasta Sauce Market
Condiments & Sauces
Barbecue Sauce Market
Condiments & Sauces
Mayonnaise Sauce Market
Condiments & Sauces
Asia Pacific Fish Sauce Market
Condiments & Sauces
Europe Hot Sauce Market
Condiments & Sauces
Table Sauce Market
Condiments & Sauces
Low Fat Mayo Market
Condiments & Sauces
Vegan Sauces Market
Condiments & Sauces
Sauces, Condiments, and Dressings Market
Condiments & Sauces
Hot Sauce Powder Market
Condiments & Sauces
Low Fat Pasta Sauce Market
Condiments & Sauces
Vegan Fish Sauce Market
Condiments & Sauces
Egg-Free Mayonnaise Market
Condiments & Sauces
Fat Free Salad Dressings Market
Condiments & Sauces
Vegan Sauces, Dressings and Spreads Market