
 Cat and Dog Food Toppers Market | 2026-2036
Cat and Dog Food Toppers Market Size, Share, and Industry Trends Forecast 2026-2036
Cat and Dog Food Toppers Market Outlook
Modular single-serve pouch formats is decoupling topper purchases from bulk kibble buying cycles, letting pet owners mix proteins and textures without committing to full diet switches. Stella & Chewy's leverages freeze-dried expertise to anchor premium freezer-aisle placement. Blue Buffalo sustains broad retail coverage through mass-channel ubiquity. Nestlé Purina Petcare competes on manufacturing scale across wet and dry topper formats.
Cat and dog food toppers are supplemental meal enhancers, typically comprising 5-15% moisture or protein-dense ingredients applied atop base feed to improve palatability, nutritional density, or functional outcomes such as joint support and digestive health. Freeze-dried meat-based toppers lead volume due to shelf stability and raw-nutrient retention, while sauce formats in single-serve pouches capture the fastest growth through convenience positioning and portion control. Bulk bag dehydrated vegetable-based options occupy mature, price-sensitive channels with thinner margins.
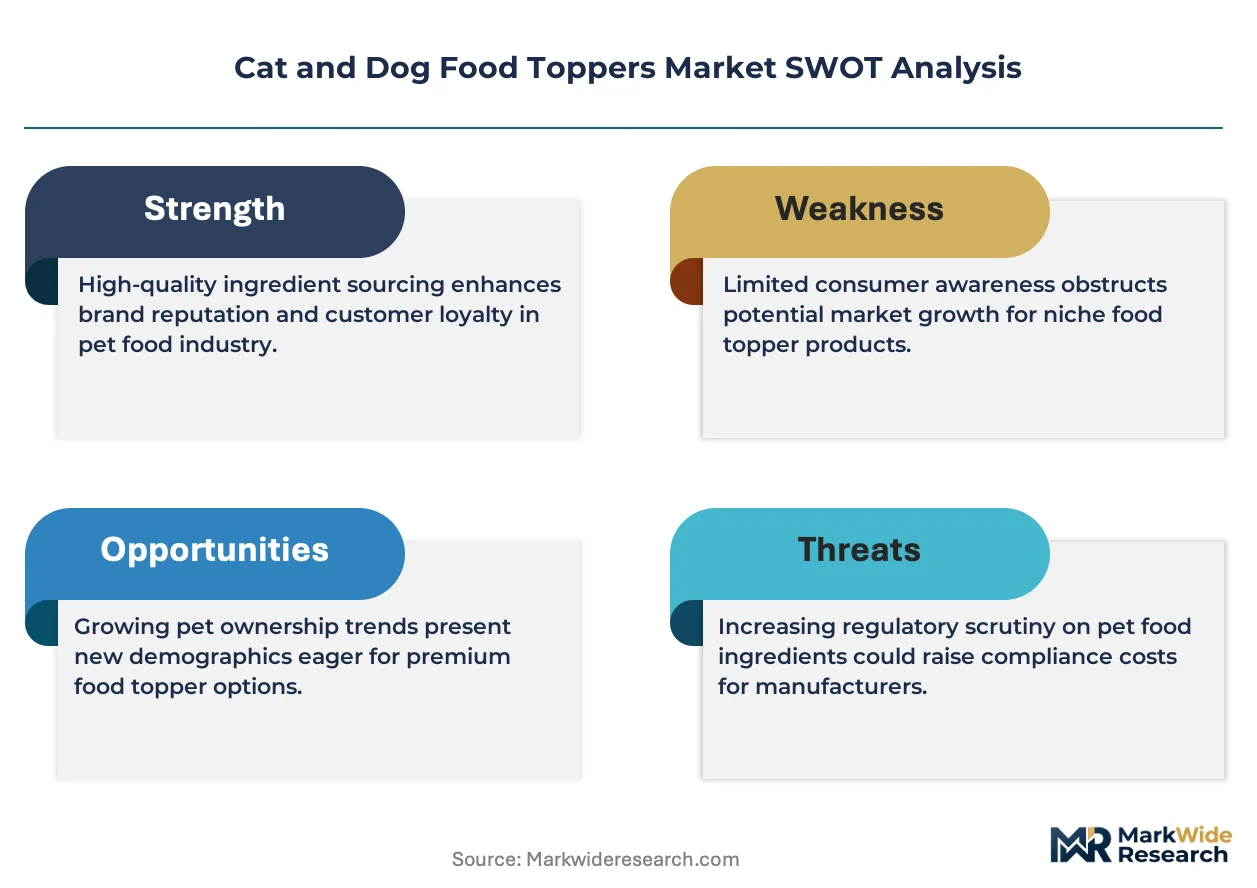
FDA Center for Veterinary Medicine guidelines on pet food labeling and ingredient safety shape permissible health claims and manufacturing protocols in the United States. AAFCO nutrient profiles further constrain formulation boundaries for products marketed as complete or supplemental feeds. Stakeholders must monitor evolving state-level raw-feeding regulations and retailer-driven clean-label certification requirements to anticipate compliance costs and channel access shifts.
Market Dynamics
Modular single-serve packaging is decoupling topper purchases from bulk kibble replenishment cycles, letting pet owners rotate proteins without full diet overhauls while specialty retailers capture recurring foot traffic.
Growth Catalysts
- EU nutritional adequacy guidelines:The EU Pet Food Industry Federation's tightening formulation standards are pushing manufacturers toward clean-label ingredient sourcing and premium positioning.
- Freeze-dried processing:Shelf-stable raw-nutrient retention technology is enabling freezer-aisle placement expansion without cold-chain infrastructure investments.
- US specialty retail:Independent pet stores and veterinary clinics are building subscription-driven topper categories that bypass mass-channel price compression.
Market Restraints
- Input cost volatility:Human-grade meat and organic vegetable prices fluctuate with agricultural commodity cycles, squeezing margin on premium-positioned products.
- Regulatory friction:FDA Center for Veterinary Medicine labeling requirements constrain permissible health claims, limiting functional marketing differentiation.
- Substitution threat:Homemade fresh food and raw feeding protocols divert spending from packaged topper categories among dedicated pet nutritionists.
Strategic Opportunities
- Veterinary channel penetration:Clinics represent underdeveloped prescription topper distribution for therapeutic formulations targeting joint support and digestive health.
- AAFCO nutrient profile convergence:Supplemental feed certification pathways enable functional ingredient claims that complete diets cannot legally make.
- Direct-to-consumer subscription:Automated replenishment platforms bypass retail slotting fees while capturing recurring revenue and consumption data.
Industry Challenges
- Formulation talent scarcity:Veterinary nutritionists and food scientists with companion animal specialization command premium compensation, constraining R&D expansion.
- Clean-label certification timelines:Third-party non-GMO and organic validations extend product launch windows by 8-14 months.
- Legacy ERP integration:Batch tracking and lot-specific recall management require costly software upgrades for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cat and Dog Food Toppers Market |
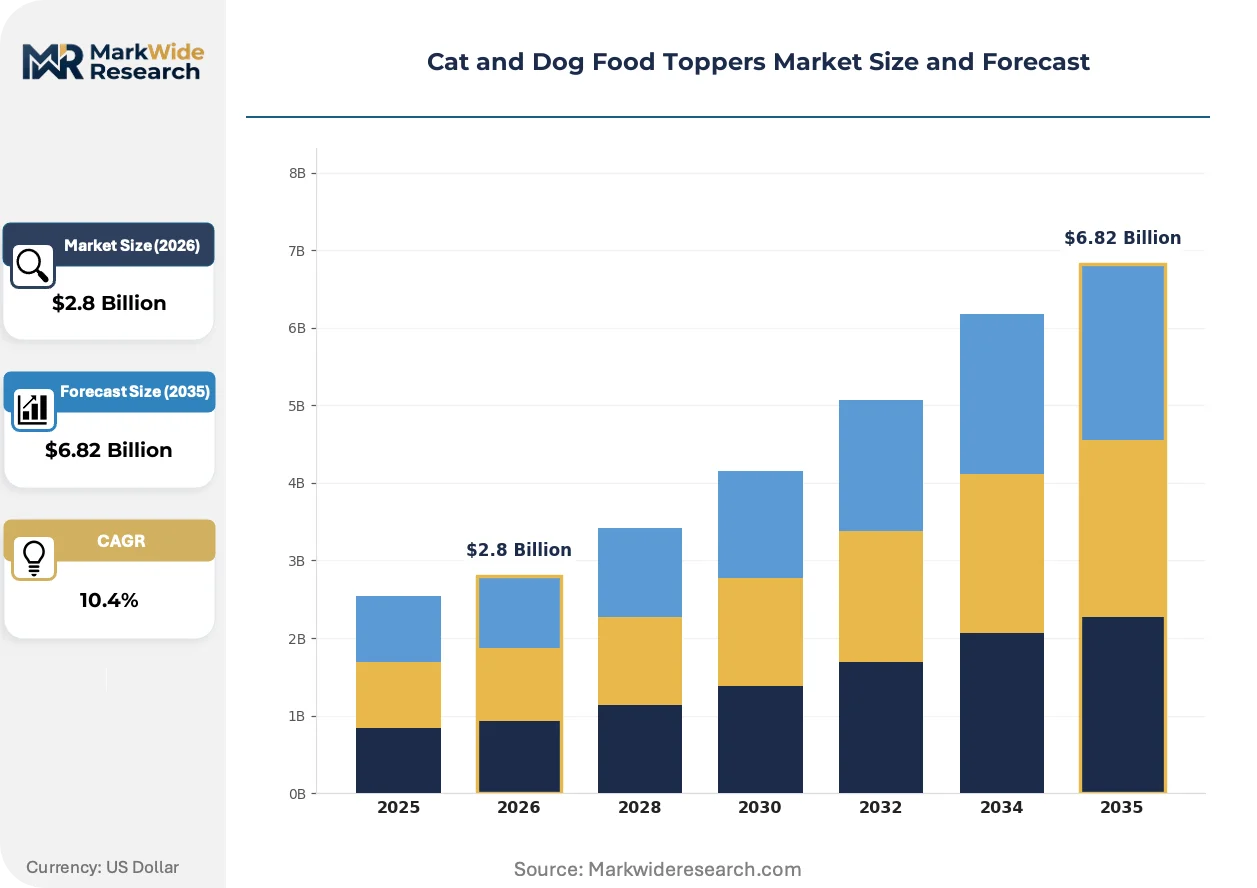
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.82 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grain-Free, Freeze-Dried, Dehydrated, Sauces Ingredient Type: Meat-Based, Vegetable-Based, Fish-Based, Nutritional Supplements Packaging Type: Single-Serve Pouches, Jars, Bulk Bags, Tubs Distribution Channel: Online Retailers, Specialty Pet Stores, Supermarkets, Pet Expos |
| Companies Covered | Stella & Chewy's, Blue Buffalo, Nestlé Purina Petcare, Merrick Pet Care, Wellness Pet Food, Mars Petcare, The Honest Kitchen, Nature's Variety, Hill's Pet Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cat and Dog Food Toppers Market Strategic Shifts
Active reformulation around functional ingredients and portion-format experimentation is compressing product development cycles while regulatory scrutiny tightens permissible marketing language.
High-pressure processing (HPP) is expanding into raw-meat topper preservation, eliminating pathogens without thermal degradation. Premium subscription services in the United States are adopting HPP-treated products to satisfy safety-conscious raw feeders. This technology is expanding into previously inaccessible retail channels that barred unprocessed frozen SKUs.
AAFCO's evolving stance on hemp-derived CBD and novel protein labeling is forcing reformulation roadmaps and claim substantiation investments. Manufacturers must now pre-validate structure-function statements before market entry. Wet sauce formats targeting senior cats with renal considerations face the most immediate compliance recalibration.
Subscription bundling is replacing single-transaction purchasing among urban millennial pet owners. Chewy and independent platforms now offer automated kibble-plus-topper pairings that lock in six-month commitments. This pattern concentrates most visibly in coastal United States metro markets where delivery density supports unit-economics viability.
Cat and Dog Food Toppers Market Segmentation
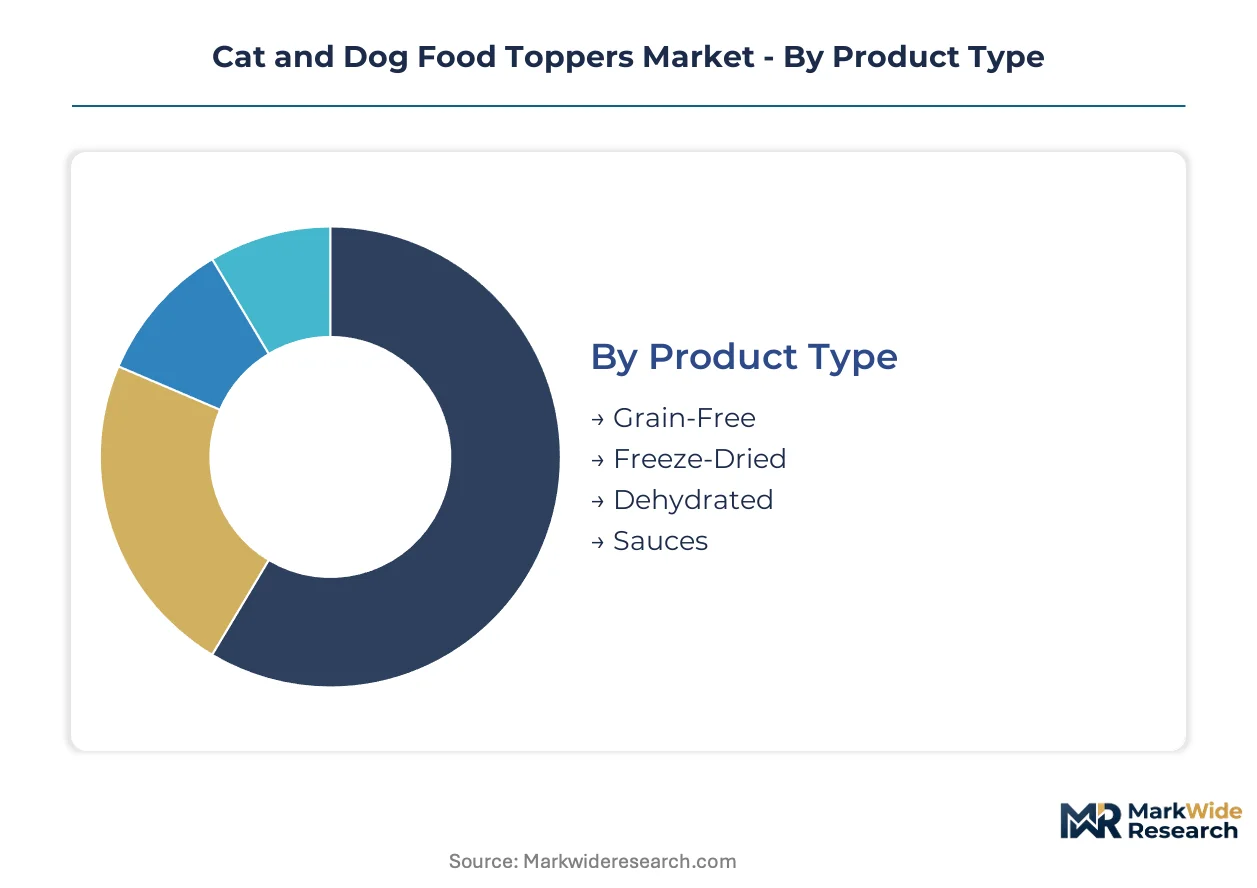
Pet food topper segmentation reflects the tension between nutritional customization and manufacturing standardization. Owners increasingly demand protein rotation and portion control while processors seek formulation and packaging efficiencies at scale.
Product Type:
Customization intensity varies sharply across this category, from rigidly standardized bulk formats to highly configurable single-serve systems.
- Freeze-Dried:Raw meat undergoes sublimation dehydration at -40°F, preserving enzyme activity and amino acid profiles without refrigeration. Demand clusters in US coastal metro markets where cold-chain-averse retailers stock freezer-aisle placements. Shelf stability drives veterinary clinic adoption for therapeutic feeding protocols.
- Sauces:Wet gravies and broths in portion-controlled formats target palatability enhancement for senior pets with dental limitations. Growth concentrates in subscription-driven urban households seeking meal variety without kibble switching. Moisture content complicates preservative-free clean-label positioning.
- Grain-Free:Eliminates corn, wheat, and soy to address allergen-sensitive pet populations. Formulations rely on tapioca or legume binders.
- Dehydrated:Low-temperature air-dried meats and vegetables rehydrate with water addition. Popular among camping and travel-oriented owners.
Most installed capacity flows through Freeze-Dried. Expansion is steepest in Sauces.
Ingredient Type:
Margin structure inverts across this category, with commodity vegetable inputs at the base and therapeutic-grade functional ingredients commanding premium positioning.
- Meat-Based:Beef, chicken, turkey, and organ meats supply complete amino acid spectra and high biological value protein. US demand concentrates in the Southeast and Texas markets with strong raw-feeding subcultures. Input cost volatility from cattle and poultry commodity cycles squeezes mid-tier processors without long-term supply contracts.
- Nutritional Supplements:Glucosamine, omega-3 fatty acids, and probiotic blends target joint mobility, coat quality, and digestive outcomes. Veterinary channel penetration is accelerating as clinics seek prescription-adjacent revenue streams. FDA Center for Veterinary Medicine labeling constraints limit structure-function claim latitude.
- Vegetable-Based:Sweet potato, pumpkin, and leafy green formulations appeal to sustainability-conscious owners. Lower protein density limits functional positioning.
- Fish-Based:Salmon, whitefish, and krill deliver EPA/DHA omega-3s for inflammatory and cognitive support. Supply concentrates in Pacific Northwest processing facilities.
Volume leadership sits with Meat-Based. Nutritional Supplements are gaining share fastest in clinic and specialty retail channels.
Packaging Type:
Format selection directly determines replenishment frequency, inventory carrying costs, and cross-selling attachment rates at point of purchase.
- Single-Serve Pouches:Portion-sealed films enable protein rotation without spoilage risk. Urban millennial owners in US Northeast and West Coast metros drive subscription bundling with automated kibble replenishment. Unit economics favor high-margin wet sauce formats over dry alternatives.
- Bulk Bags:Multi-pound dehydrated and freeze-dried formats serve multi-pet households and price-sensitive channels. Warehouse club and farm supply distribution dominates.
- Jars:Glass or rigid plastic containers target premium wet topper positioning. Refrigeration requirements limit retail penetration.
- Tubs:Reclosable rigid packaging for high-viscosity products. Common in veterinary-exclusive therapeutic lines.
Manufacturing throughput centers on Bulk Bags. Single-Serve Pouches show the steepest trajectory as specialty retailers build subscription infrastructure.
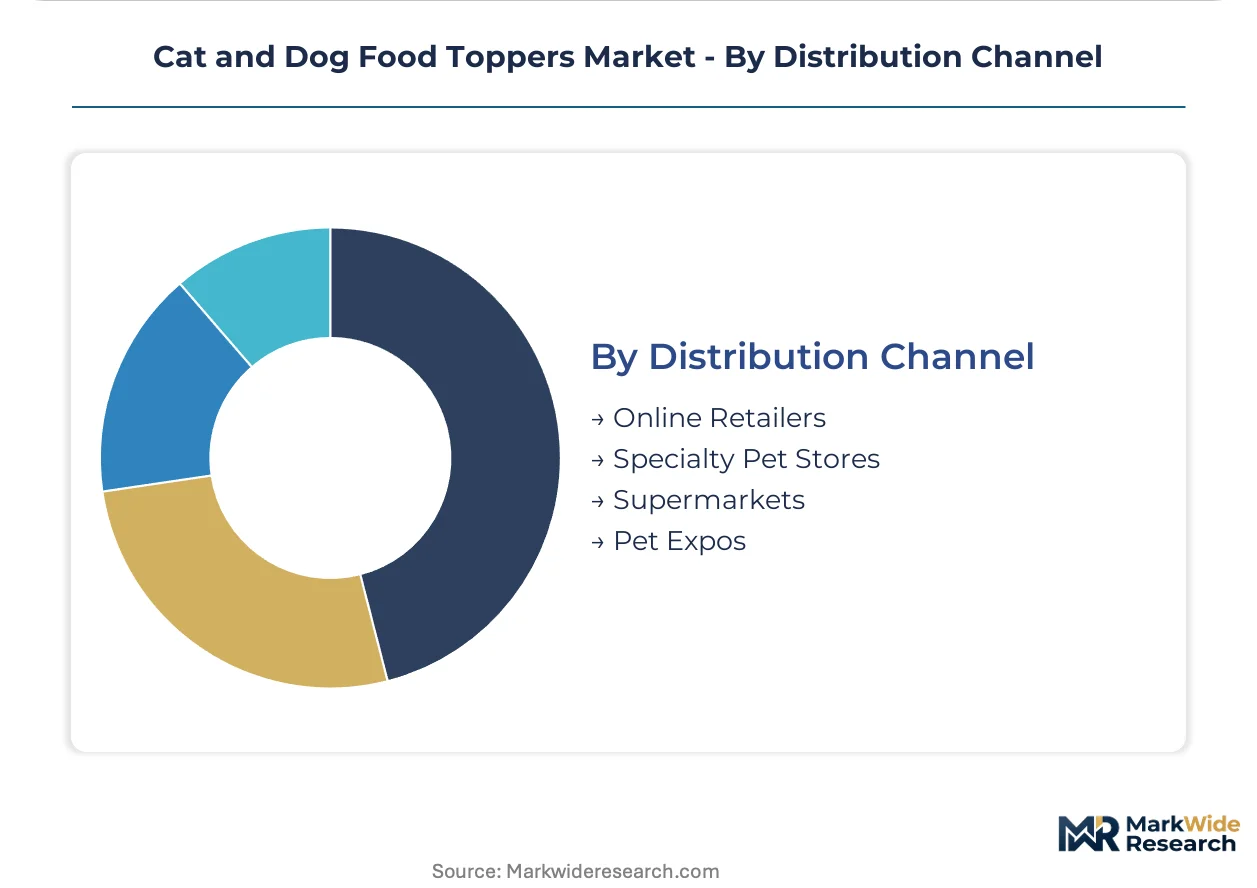
Distribution Channel:
Channel selection shapes permissible price positioning, with mass retail enforcing standardization and independent specialty enabling customization premiums.
- Specialty Pet Stores:Independent retailers and regional chains curate rotation-heavy topper assortments with trained staff consultation. Foot traffic recurrence depends on subscription program enrollment and kibble-topper bundling. Clean-label certification requirements from retailers like Petco and independent cooperatives extend supplier onboarding timelines.
- Online Retailers:Chewy, Amazon, and direct-to-consumer platforms capture automated replenishment with consumption data feedback loops. Coastal US metro delivery density supports unit-economics viability for frozen and refrigerated formats excluded from brick-and-mortar.
- Supermarkets:Mass-channel placement demands price compression and simplified SKU matrices. Blue Buffalo and Nestlé Purina Petcare dominate shelf space.
- Pet Expos:Trade show and consumer exhibition channels enable new brand trial and raw-feeding education. Concentrated in regional events across Florida, California, and Ohio.
Transaction volume concentrates in Specialty Pet Stores. Online Retailers are climbing the fastest as platform infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cat and dog food toppers industry traces its commercial origins to United States specialty pet retail channels in the early 2000s, where freeze-dried raw feeding protocols first gained mainstream traction among urban pet owners seeking nutritional customization beyond conventional kibble.
United States
Pet humanization trends and specialty retail expansion drive category penetration, with subscription bundling now dominating coastal metro markets. FDA Center for Veterinary Medicine labeling requirements constrain permissible health claims while shaping manufacturing protocols. The Pacific Northwest processing corridor, anchored by Portland and Seattle metro clusters, concentrates freeze-dried meat production capacity serving veterinary and direct-to-consumer channels.
Germany
Clean-label ingredient sourcing and sustainability-conscious ownership patterns accelerate demand for organic-certified toppers. EU Pet Food Industry Federation nutritional adequacy guidelines tighten formulation standards and extend supplier certification timelines. The Bavaria industrial corridor hosts specialized dehydration equipment manufacturers supplying mid-tier European processors with low-temperature air-drying technology.
United Kingdom
Independent pet store chains and veterinary clinic partnerships build recurring revenue through subscription-driven topper categories. Food Standards Agency pet food safety regulations align with EU FEDIAF guidelines while maintaining post-Brexit divergence monitoring. Greater London and Southeast England retail density supports premium wet sauce format distribution through automated replenishment platforms.
Japan
Aging pet demographics and single-person households generate demand for portion-controlled palatability enhancers targeting senior cats with dental limitations. Ministry of Economy, Trade and Industry (METI) quality labeling standards enforce strict ingredient traceability requirements. The Kanto region surrounding Tokyo anchors specialty retail innovation, with Osaka-Kansai clusters developing high-pressure processing applications for raw-meat preservation.
Australia
Outdoor-oriented pet ownership cultures sustain demand for dehydrated travel formats and camping-compatible packaging. Australian Pesticides and Veterinary Medicines Authority (APVMA) registration requirements govern therapeutic claim substantiation for joint support and digestive health products. New South Wales and Victoria processing facilities leverage proximity to Pacific Northwest salmon supply chains for omega-3 dense fish-based formulations.
Cat and Dog Food Toppers Market Competitive Environment
Premium-margin players sit above commodity-margin players across formulation complexity and distribution channel access, with freezer-aisle placement and veterinary channel penetration serving as the primary stratification mechanisms. The market structure exhibits moderate consolidation among multinational pet food conglomerates with diversified manufacturing scale, while specialized freeze-dried specialists and direct-to-consumer platforms occupy defensible niche positions. Three strategic archetypes dominate: raw-nutrient preservation specialists leveraging sublimation technology, mass-channel brands optimizing retail slotting efficiency, and subscription-native platforms capturing consumption data loops. Competitive moves concentrate on veterinary channel exclusivity agreements and high-pressure processing capacity expansion for pathogen elimination without thermal degradation.
Within the premium-tier freeze-dried segment, Stella & Chewy's and The Honest Kitchen occupy positions exemplifying raw-feeding protocol authenticity and human-grade ingredient sourcing respectively. Blue Buffalo and Nestlé Purina Petcare represent scale-driven archetypes with divergent channel strategies, the former optimizing mass-retail ubiquity while the latter leverages integrated wet-and-dry manufacturing infrastructure. These four entities collectively illustrate the competitive tension between nutritional customization depth and production standardization efficiency.
| Leading Market Players |
|---|
| Stella & Chewy's |
| Blue Buffalo |
| Nestlé Purina Petcare |
| Merrick Pet Care |
| Wellness Pet Food |
| Mars Petcare |
| The Honest Kitchen |
| Nature's Variety |
| Hill's Pet Nutrition |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up freeze-dried specialists anchor supply concentration in the Pacific Northwest, tightening procurement discipline while subscription bundling in coastal metros extracts premium pricing power from urban millennial owners seeking protein rotation flexibility.
Pricing Analysis
Three-tier pricing structure across premium freeze-dried, mid-tier dehydrated, and economy bulk formats separates veterinary-exclusive therapeutic lines from mass-channel commodity SKUs. Price differentiation rests on clean-label certification status and cold-chain delivery requirements. Cost compression in the dehydrated segment intensifies as human-grade meat input volatility squeezes mid-tier processors without long-term poultry contracts. Mass-channel buyers at supermarkets exhibit highest price sensitivity, while subscription-driven specialty retail customers accept 40-60% premiums for single-serve pouch convenience.
Supply Chain Analysis
Regional distribution centers in Portland, Seattle, and Denver operate hub-and-spoke patterns serving veterinary clinics and direct-to-consumer platforms with frozen and shelf-stable SKUs. Manufacturing gravity draws from the United States, Australia, and New Zealand for human-grade meat inputs, with Pacific Northwest salmon and Southeast cattle operations feeding freeze-dried production. Single-source vulnerability concentrates in sublimation dehydration equipment, where German and Italian machinery suppliers command 12-16 month lead times. Distribution runs through specialty pet store cooperatives and Chewy's automated fulfillment network, bypassing mass-retail slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in veterinary channel penetration and high-pressure processing capacity additions, as therapeutic positioning commands 25-35% premiums over mass-market equivalents while input cost hedging stabilizes manufacturing economics.
For Market Incumbents: Deepen freezer-aisle placement exclusivity agreements with regional specialty chains to defend against mass-channel private-label encroachment. Acquire high-pressure processing capacity in the Kanto region to satisfy Japanese METI traceability requirements for raw-meat preservation. Lock in long-term contracts with Pacific Northwest salmon processors to insulate against omega-3 input volatility. For New Entrants and Emerging Players: FDA Center for Veterinary Medicine labeling guidelines in the United States open a window for AAFCO supplemental feed certification pathways that incumbent complete-diet manufacturers cannot legally pursue. Target veterinary clinic prescription-adjacent distribution for joint support formulations, where trained staff consultation justifies premium positioning. Launch direct-to-consumer subscription platforms with automated kibble-topper bundling to capture consumption data loops before retail infrastructure matures. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier dehydrated specialists lacking freeze-dried sublimation expertise or clean-label certification. Long-term viability favors entities with backward integration into human-grade meat supply and subscription platform infrastructure. Watch FDA raw-feeding state-level regulatory shifts as inflection indicators for compliance cost acceleration and channel access restriction.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Expansion | Clinic-exclusive therapeutic formulations capture prescription-adjacent revenue streams with trained staff endorsement. |
| High-Pressure Processing Investment | Pathogen elimination without thermal degradation opens previously restricted retail channels for raw-meat SKUs. |
| Subscription Platform Launch | Automated replenishment bypasses slotting fees while locking in six-month commitments from urban millennial owners. |
| Clean-Label Certification Acceleration | Third-party organic and non-GMO validations extend supplier onboarding timelines but defend premium positioning against private-label encroachment. |
| Direct-to-Consumer Geographic Expansion | Coastal metro delivery density supports frozen and refrigerated format unit economics excluded from brick-and-mortar. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with freeze-dried production facility managers, veterinary clinic procurement leads, specialty pet store category buyers, and direct-to-consumer platform operations directors with secondary validation from FDA Center for Veterinary Medicine labeling guidance documents, AAFCO nutrient profile databases, EU Pet Food Industry Federation nutritional adequacy standards, and Nielsen retail audit data. Bottom-up SKU-level volume estimates and top-down category spending analysis were triangulated to constrain forecast variance.
Segment-weighting approaches modeled product type, ingredient composition, packaging format, and distribution channel dimensions across the projection horizon. CAGRs were derived from fitted growth curves against historical trajectory validation. Forecast inputs incorporated veterinary channel penetration rates, subscription platform enrollment velocity, and clean-label certification adoption patterns specific to companion animal nutrition.
Revisions become necessary when FDA raw-feeding state-level regulations tighten, human-grade meat commodity cycles spike beyond historical variance bands, or high-pressure processing equipment lead times extend beyond supplier capacity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Global Hispanic Foods Market
Specialty Foods
Asia Pacific Cat Food Market
Specialty Foods
Global Bee Products Market
Specialty Foods
Manuka Honey Market
Specialty Foods
Low Calorie Hummus Market
Specialty Foods
Yeast-Based Spreads Market
Specialty Foods
Organic Skin Care Market
Specialty Foods
Non-GMO Food Products Market
Specialty Foods
Cannabis Infused Drinks Market
Specialty Foods
Sweet Spreads Market
Specialty Foods
Soft Tofu Market
Specialty Foods
Middle East and Africa Hummus Market
Specialty Foods
Tahini Market
Specialty Foods
Low Calorie Desserts Market
Specialty Foods
Halal Market
Specialty Foods
Super Foods Market