
 Edible Mushroom Market | 2026-2036
Edible Mushroom Market Size, Share, and Industry Trends Forecast 2026-2036
Edible Mushroom Market Analysis
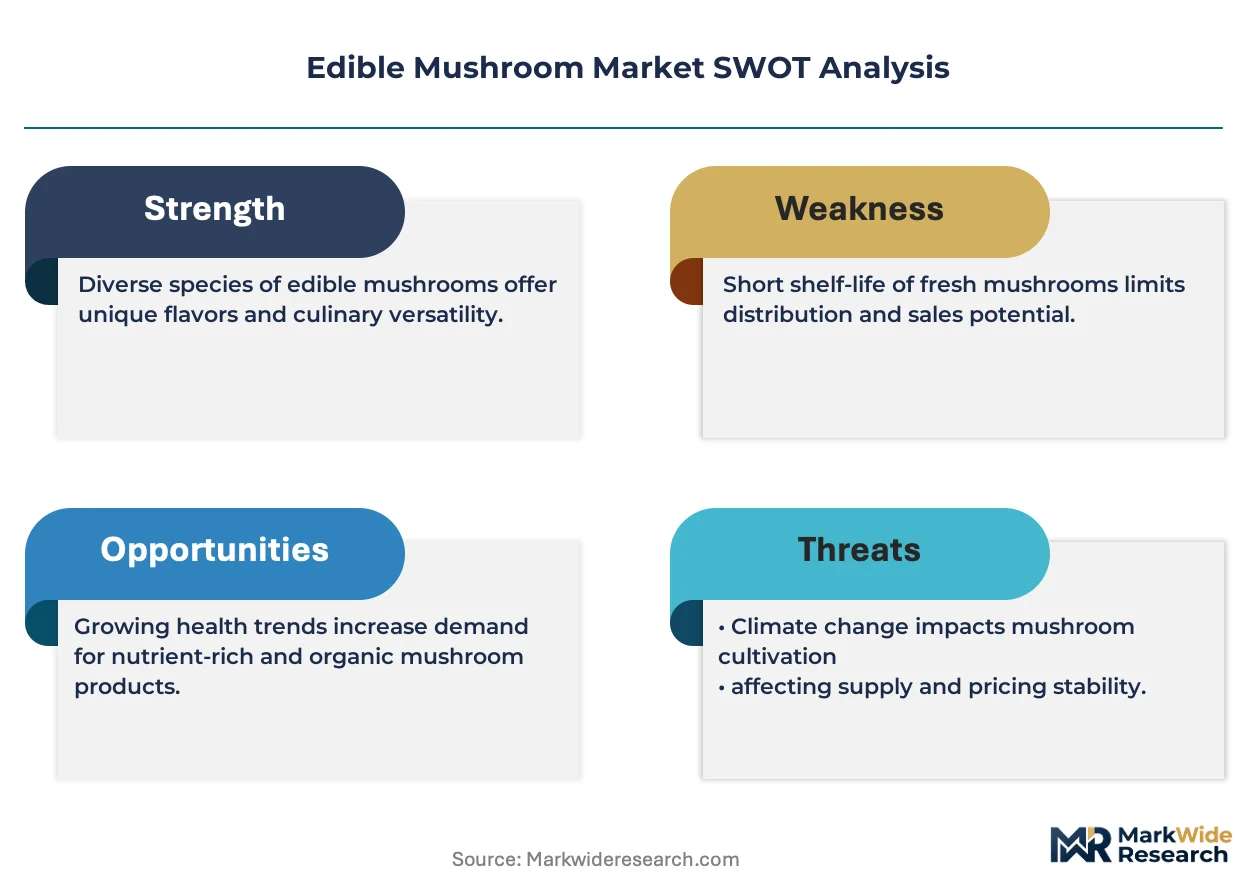
Organic and premium-grade certification is rotating the edible mushroom market toward higher-margin supply tiers. Monterey Mushrooms Inc. leverages integrated composting and spawn production across North American facilities. Bonduelle Group anchors European retail and food service channels through frozen and canned mushroom portfolios. Shanghai Finc Bio-Tech Inc. dominates functional extract supply for pharmaceutical and nutraceutical offtake in Asia.
Edible mushrooms comprise the fruiting bodies of macrofungi species cultivated or wild-harvested for human consumption, with moisture content typically ranging from 85% to 95% fresh weight and protein concentrations of 15% to 40% on a dry basis depending on species. These organisms serve as whole-food ingredients, umami flavor enhancers, and bioactive compound sources for dietary supplements and therapeutic applications. Button mushrooms occupy the mature volume tier across Western retail channels, while shiitake and oyster varieties represent faster-growing segments driven by Asian cuisine proliferation and mycelium-based meat alternative formulations. The food service end user channel captures concentrated margin pools through pre-sliced and value-added prepared formats supplied to institutional kitchens and restaurant chains.
The European Food Safety Authority enforces maximum residue limits under EU Regulation 396/2005, while the FDA oversees HACCP compliance and GRAS determinations for novel mushroom-derived ingredients in the United States. China's National Health Commission and National Medical Products Administration regulate functional food and dietary supplement claims for mushroom extracts. Stakeholders must monitor evolving novel food authorization pathways and adapt cultivation protocols to shifting mycotoxin testing thresholds.
Market Dynamics
The EU's Farm to Fork Strategy is compressing pesticide tolerance thresholds while China's dual carbon goals force energy-intensive composting facilities toward biogas capture retrofits, reshaping cost structures across the supply base.
Growth Catalysts
- Plant-based protein substitution:Food manufacturers reformulate meat analogues using mycelium biomass to hit clean-label targets, pulling shiitake and oyster varieties into industrial ingredient pipelines.
- EU organic certification expansion:Retail chains in Germany and France now mandate organic SKUs for shelf placement, accelerating grower conversion to certified substrates.
- Functional extract demand:Pharmaceutical offtake for beta-glucan and triterpenoid isolates is expanding cultivation acreage dedicated to reishi and maitake species.
Market Restraints
- Input cost volatility:Wheat straw and poultry manure prices swing with grain futures, compressing margins for compost-dependent growers.
- Geographic supply concentration:Zhejiang and Fujian provinces process over half of China's export volume, creating single-point vulnerability to climate shocks.
- Regulatory friction:FDA novel food determinations for mycelium-based ingredients delay US market entry by 18-24 months versus conventional mushroom products.
Strategic Opportunities
- Underpenetrated Indian retail:Organized grocery expansion in Mumbai and Bangalore creates first-mover slots for pre-packaged fresh varieties.
- Regulatory tailwind:China's National Health Commission is streamlining functional food claim approvals for mushroom extracts, opening nutraceutical white space.
- Controlled-environment agriculture convergence:Vertical farming operators are retrofitting LED arrays and climate systems for year-round oyster mushroom production.
Industry Challenges
- Spawn genetics expertise gap:Commercial cultivation requires mycologists capable of strain isolation and contamination control, talent concentrated in academic and government labs.
- Organic certification timelines:EU organic conversion mandates 24-month substrate tracking, locking land and capital before revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edible Mushroom Market |
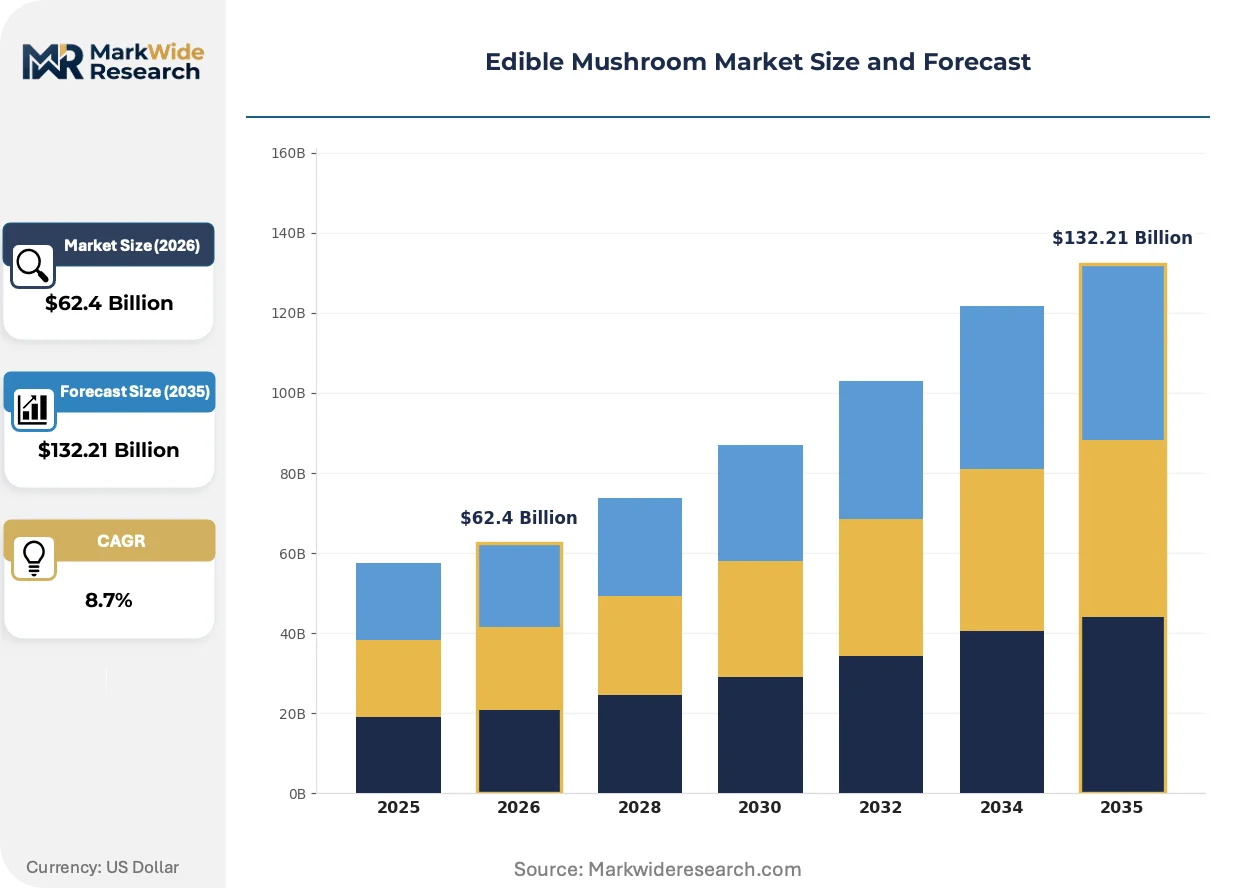
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $132.21 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Button, Shiitake, Oyster, Portobello End User: Retail, Food Service, Food Processing, Pharmaceuticals Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale Packaging Type: Bulk, Clamshell, Modified Atmosphere, Cartons |
| Companies Covered | Bonduelle Group, Costa Group, Monterey Mushrooms Inc., Monaghan Mushrooms, Shanghai Finc Bio-Tech Inc., Okechamp S.A., Drinkwater Mushrooms Ltd., Greenyard, Agro Dutch Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edible Mushroom Market Emerging Trajectories
Automation and biotechnology are compressing production cycles while regulatory tightening and shifting buyer preferences force segmentation along certification and format lines.
Automated harvesting robotics equipped with computer vision is miniaturizing labor footprints in large-scale button mushroom operations. North American fresh produce distributors are piloting these systems to offset wage inflation. The technology is compressing per-unit harvest costs and enabling 24-hour picking cycles that manual crews cannot match.
REACH chemical registration requirements are extending to novel substrate treatments and sanitizing agents used in European cultivation facilities. Dutch and Polish growers face reformulation deadlines for compost additives previously grandfathered under older frameworks. The frozen and canned segments are absorbing compliance costs through supplier consolidation and longer-term contracting.
Direct-to-restaurant procurement platforms are disintermediating traditional wholesale produce markets for specialty varieties. Chef-driven demand for exotic strains like lion's mane and king trumpet is bypassing centralized terminal markets in favor of farm-to-kitchen logistics. This pattern is most visible in Tokyo, Singapore, and Melbourne where high-end dining density supports premium sourcing premiums.
Edible Mushroom Market Segmentation
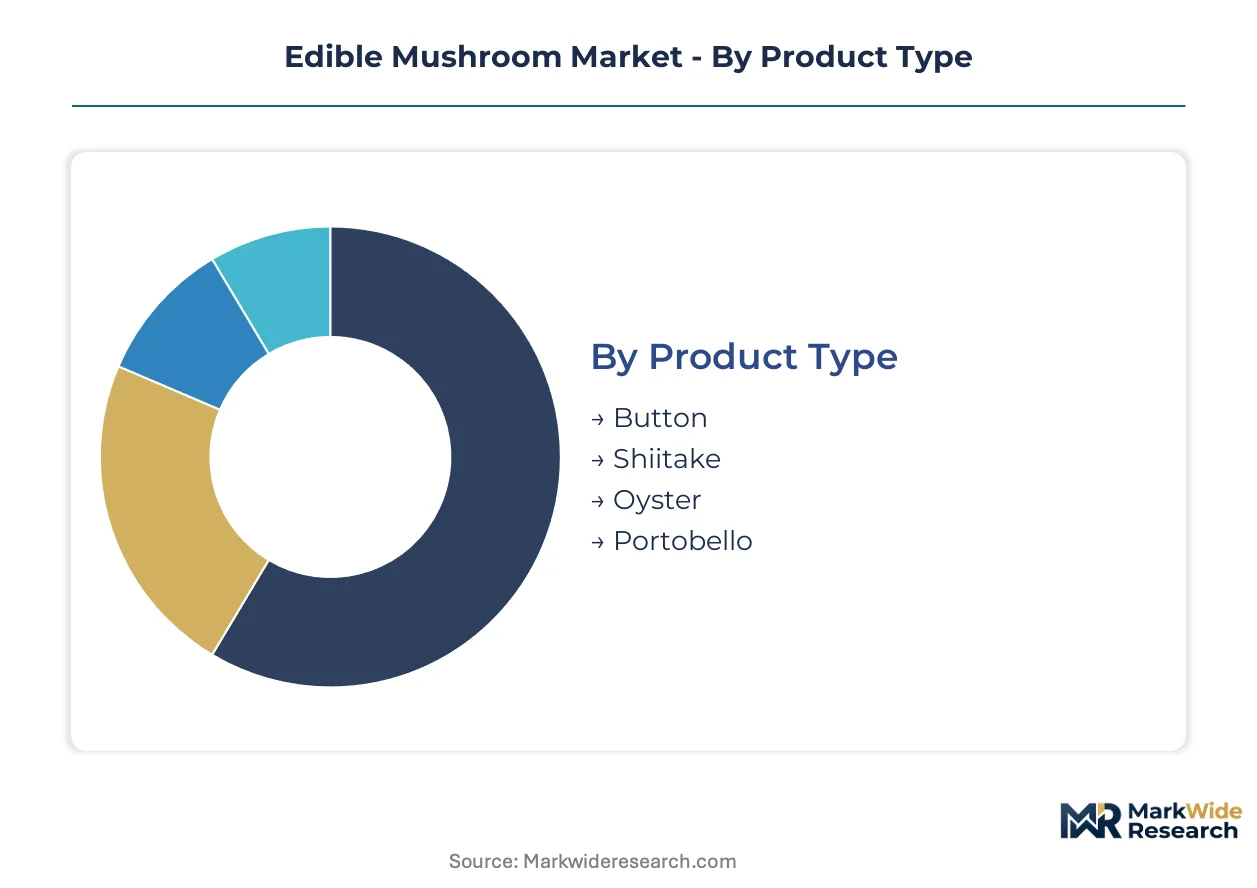
Mushroom suppliers calibrate product mix and certification tiers against divergent buyer price sensitivities and shelf-life requirements. Segmentation discipline separates commodity volume plays from premium-margin extraction opportunities across cultivation and processing stages.
Product Type:
Button mushrooms face the most acute substitution pressure from mycelium-based meat alternatives and plant-based umami enhancers, forcing growers to defend positioning through organic certification and pre-sliced convenience formats.
- Button:These white-capped Agaricus bisporus varieties dominate Western retail shelves with mild flavor profiles suited to mass-market palates. US and German supermarket chains source primarily from Pennsylvania and Poland composting clusters, though margin compression from private-label expansion limits pricing power.
- Shiitake:Lentinula edodes delivers concentrated umami compounds and beta-glucan content prized in Asian cuisine and extract applications. Japanese and Korean restaurant chains in Los Angeles and Sydney drive premium fresh demand, while Chinese processors supply dried and powdered formats for nutraceutical offtake.
- Oyster:Pleurotus species offer rapid cultivation cycles on agricultural waste substrates with lower capital intensity than button operations. Vertical farming operators in Singapore and the Netherlands favor this segment for controlled-environment retrofit compatibility.
- Portobello:Mature Agaricus bisporus with extended cap development serves grilling and meat-substitution applications in food service. Casual dining chains specify diameter grading for plate coverage consistency.
Button mushrooms anchor the volume base while oyster varieties gain share at the steepest rate.
End User:
Margin structures diverge sharply across buyer categories, with pharmaceutical extract demand commanding five-fold premiums over fresh retail tonnage.
- Retail:Supermarket and online channels demand consistent sizing, minimal bruising, and extended shelf-life through modified atmosphere packaging. German and French chains now mandate organic certification for shelf placement, accelerating substrate conversion timelines.
- Food Service:Institutional kitchens and restaurant chains purchase pre-sliced, pre-washed formats to reduce labor costs. Tokyo and Melbourne fine-dining establishments source exotic strains through direct farm procurement platforms that bypass wholesale terminals.
- Food Processing:Canned and frozen manufacturers require uniform moisture content and texture stability through thermal processing. Bonduelle and similar operators contract acreage years ahead to lock supply.
- Pharmaceuticals:Beta-glucan and triterpenoid extraction demands strain-specific cultivation with documented substrate provenance and contaminant testing. China's NMPA regulates functional food claims, creating compliance barriers for new entrants.
Retail absorbs the highest tonnage while pharmaceutical applications deliver the steepest margin expansion trajectory.
Distribution Channel:
Channel selection determines spoilage exposure and working capital intensity, with fresh formats requiring faster inventory turns than shelf-stable alternatives.
- Supermarkets:Chains like Kroger and Carrefour consolidate procurement through centralized produce distributors, squeezing grower margins via volume commitments and promotional funding requirements.
- Online Retail:Direct-to-consumer platforms enable subscription models for specialty varieties, though cold-chain logistics costs erode profitability outside dense urban corridors.
- Specialty Stores:Asian grocers and organic cooperatives stock dried shiitake and medicinal varieties with higher per-unit value and lower velocity than mainstream fresh SKUs.
- Wholesale:Terminal markets in Zhejiang and California handle spot pricing for uncommitted volume, exposing growers to weather-driven price volatility.
Supermarkets dominate volume throughput while online retail climbs fastest as cold-chain infrastructure matures.
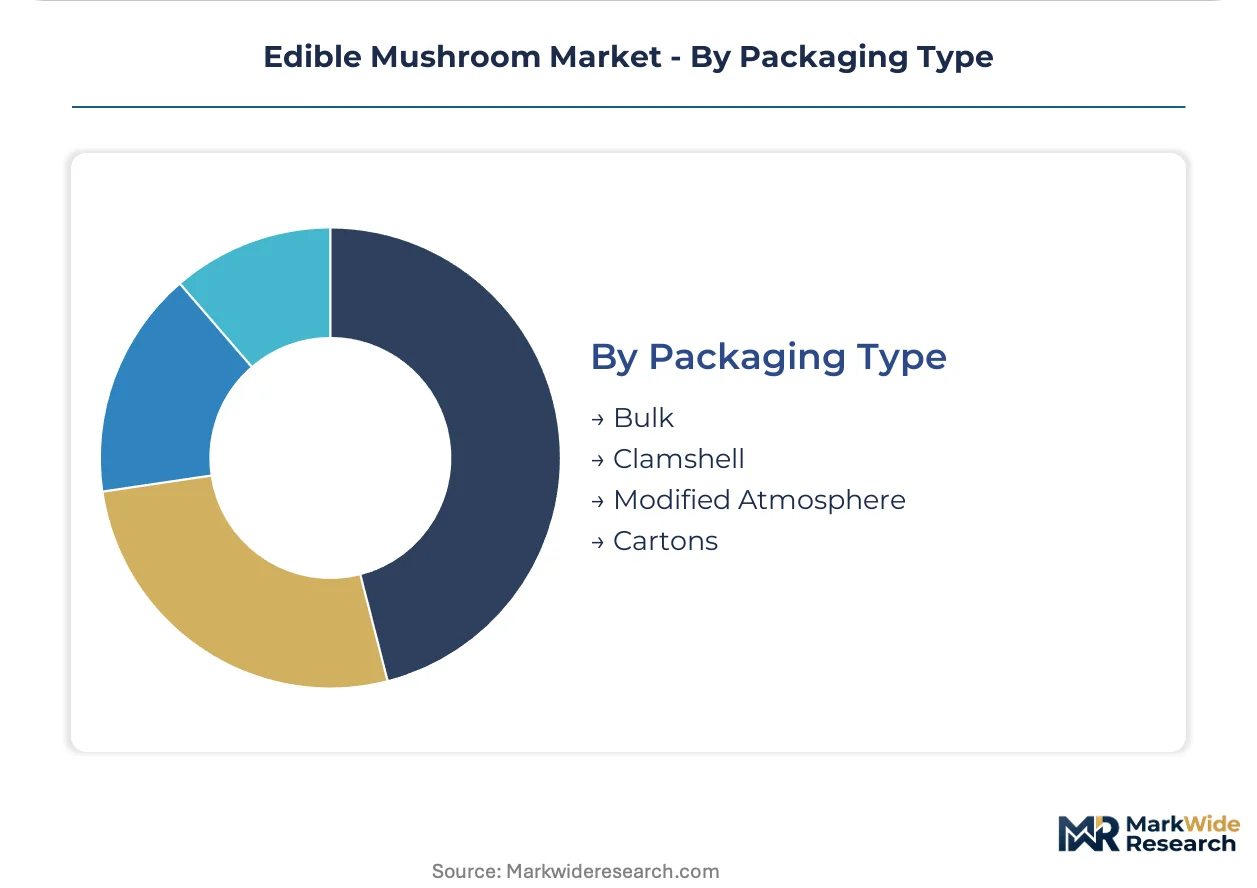
Packaging Type:
Packaging selection balances shelf-life extension against sustainability mandates and unit economics, with regulatory pressure on single-use plastics reshaping format preferences.
- Bulk:Loose mushrooms in returnable crates serve food service and processing buyers with immediate consumption timelines, minimizing packaging cost but requiring rapid turnover.
- Clamshell:PET or molded fiber containers protect cap integrity during retail handling and home transport. EU single-use plastic directives are forcing fiber substitution trials across Dutch and Belgian packing facilities.
- Modified Atmosphere:Gas-flushed films extend fresh shelf-life from days to weeks, enabling centralized packing and longer distribution radii. Premium retailers specify this format for organic SKUs.
- Cartons:Dried and processed mushrooms ship in corrugated with moisture barriers, optimizing cube utilization for export container loads from Chinese processing clusters.
Clamshell formats anchor retail presentation standards while modified atmosphere packaging expands most quickly in premium fresh segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fresh mushroom buyers in Germany and France absorb organic certification premiums without volume contraction, while price-sensitive food service operators in India and Southeast Asia trade down to conventional substrates when input costs spike.
United States
Plant-based protein manufacturers in California and Illinois source mycelium biomass for meat analogues, pulling shiitake and oyster varieties into industrial ingredient pipelines. The FDA oversees HACCP compliance and GRAS determinations for novel mushroom-derived ingredients, creating 18-24 month entry delays versus conventional products. Pennsylvania's composting clusters supply Kroger and Walmart with button mushroom volume, though private-label expansion limits grower pricing power.
Germany
Retail chains including Aldi and Lidl mandate organic SKUs for shelf placement, accelerating substrate conversion timelines across Bavarian and Lower Saxony growing operations. EFSA enforces maximum residue limits under EU Regulation 396/2005, tightening pesticide tolerance thresholds. Dutch and Polish growers face REACH chemical registration deadlines for compost additives previously grandfathered under older frameworks.
China
Pharmaceutical offtake for beta-glucan and triterpenoid isolates expands cultivation acreage dedicated to reishi and maitake species in Zhejiang and Fujian provinces. The National Health Commission and National Medical Products Administration regulate functional food and dietary supplement claims for mushroom extracts. Dual carbon goals force energy-intensive composting facilities toward biogas capture retrofits, reshaping cost structures across the supply base.
Japan
Fine-dining establishments in Tokyo source exotic strains like lion's mane and king trumpet through direct farm procurement platforms that bypass wholesale terminals. METI oversees standards for functional food manufacturing and novel ingredient safety assessments. Kansai region processors supply dried shiitake formats for nutraceutical offtake across domestic and export markets.
India
Organized grocery expansion in Mumbai and Bangalore creates first-mover slots for pre-packaged fresh varieties as modern retail penetration accelerates. FSSAI regulates food safety standards and labeling requirements for mushroom products entering the domestic market. Maharashtra and Karnataka cultivation clusters experiment with oyster mushroom vertical farming retrofits using LED arrays and climate control systems.
Edible Mushroom Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure across the edible mushroom market. Large-scale integrated operators dominate volume tiers through captive composting and spawn production, while specialized extract suppliers capture premium-margin pools in pharmaceutical and nutraceutical channels. Strategic moves center on backward integration into substrate supply and geographic expansion into underpenetrated retail corridors.
Among North American integrated producers, Monterey Mushrooms Inc. exemplifies the scale-driven archetype with facilities spanning multiple US states. European retail and food service channels anchor around Bonduelle Group, which occupies a position across frozen and canned mushroom portfolios. Shanghai Finc Bio-Tech Inc. represents the functional extract specialist tier, supplying pharmaceutical and nutraceutical offtake across Asian markets.
| Leading Market Players |
|---|
| Bonduelle Group |
| Costa Group |
| Monterey Mushrooms Inc. |
| Monaghan Mushrooms |
| Shanghai Finc Bio-Tech Inc. |
| Okechamp S.A. |
| Drinkwater Mushrooms Ltd. |
| Greenyard |
| Agro Dutch Industries Ltd. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Dutch composting clusters and German retail chains lock in substrate supply access while anchoring price visibility against wheat straw and poultry manure volatility. These arrangements insulate volume buyers from spot market swings but compress grower margins when input costs spike.
Pricing Analysis
EU Regulation 396/2005 dictates the pricing tier structure across European cultivation, with EFSA maximum residue limits separating certified organic premiums from conventional substrate tiers. Three-tier pricing structure across premium organic, standard integrated, and economy conventional levels tracks certification grade and substrate provenance documentation. Cost compression in economy tiers is intensifying because private-label expansion at Kroger and Walmart limits branded pricing power. Food service buyers exhibit highest price sensitivity due to menu cost pressures, while pharmaceutical extract offtake shows lowest sensitivity given beta-glucan purity requirements.
Supply Chain Analysis
Inventory turns for fresh clamshell formats run 48-72 hours from packing to shelf, forcing modified atmosphere packaging investments that extend distribution radii. Supply concentrates in China, the Netherlands, and Poland, with Zhejiang province processing clusters and Dutch composting facilities anchoring global volume. Raw material flows draw from wheat straw, poultry manure, and hardwood sawdust streams vulnerable to grain futures volatility. Single-source vulnerability to climate shocks in Fujian province poses structural risk. Distribution runs through centralized produce distributors serving supermarket chains, with direct-to-restaurant platforms disintermediating wholesale terminals for specialty varieties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Functional extract supply contracts represent a service-attach opportunity expanding faster than fresh tonnage, with beta-glucan and triterpenoid isolates commanding recurring pharmaceutical offtake premiums beyond one-time harvest sales.
For Market Incumbents: Consolidate spawn genetics capabilities through captive mycology labs or exclusive university partnerships to defend against strain contamination risks. Lock multi-year substrate supply contracts in Pennsylvania and Poland composting clusters before wheat straw volatility intensifies. Backward integration into poultry manure sourcing insulates margin structures from agricultural commodity swings. For New Entrants and Emerging Players: Anchor in Mumbai and Bangalore organized grocery expansion, where modern retail penetration creates first-mover slots for pre-packaged organic oyster varieties. Target vertical farming retrofit compatibility using LED arrays and climate control systems to bypass land-intensive composting infrastructure. Pursue direct procurement platform partnerships with Tokyo and Melbourne fine-dining establishments seeking exotic strains like lion's mane. For Investors and Strategic Acquirers: Capital is best deployed toward functional extract specialists with NMPA-registered facilities and documented substrate provenance systems serving pharmaceutical offtake. Long-term viability over the projection horizon favors players with certified organic conversion completion and biogas capture retrofits aligned with China's dual carbon goals. Monitor FDA GRAS determination timelines for mycelium-based ingredients as inflection indicator for US market entry acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Supply | Captive composting facilities in Pennsylvania and Poland insulate margin structures from wheat straw volatility. |
| Organic Certification Conversion | EU Farm to Fork Strategy mandates 24-month substrate tracking that locks shelf placement at Aldi and Lidl. |
| Functional Extract Capacity Expansion | Pharmaceutical offtake for reishi beta-glucan isolates commands five-fold premiums over fresh retail tonnage. |
| Vertical Farming Retrofit Deployment | LED array and climate system investments enable year-round oyster production in Singapore and Netherlands facilities. |
| Direct-to-Restaurant Platform Launch | Farm-to-kitchen logistics bypass wholesale terminals in Tokyo and Melbourne, capturing premium sourcing premiums. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA GRAS determinations, EFSA pesticide residue databases, and Chinese NMPA functional food registrations. Cultivation facility managers, pharmaceutical procurement leads at extract buyers, retail category buyers at Carrefour and Kroger, and spawn genetics specialists at academic mycology labs provided operational validation. Trade flow data from Zhejiang and Fujian export clusters, EU organic certification registries, and vertical farming operator capex disclosures supplied quantitative anchors. Bottom-up tonnage estimates from composting cluster capacities triangulate against top-down retail scan data.
Segmentation dimensions modeled span product type, end user channel, distribution format, and packaging technology across the analysis window. CAGRs derive from regression against historical volume trajectories in button, shiitake, oyster, and portobello segments, adjusted for regulatory timeline impacts on novel ingredient approvals. Forecast inputs incorporate substrate cost indices, organic certification conversion rates, and pharmaceutical extract purity premiums.
Material uncertainties — FDA novel food determination delays, climate shock frequency in Fujian province, and wheat straw futures volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory pathway timelines and buyer certification mandates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Vegetarian Taquitos Market
Specialty Foods
Global Freeze-Dried Pet Food Market
Specialty Foods
Dog Food Toppers Market
Specialty Foods
North American Jam, Jelly, and Preserve Market
Specialty Foods
Marine Thermal Water Ferments Market
Specialty Foods
Low-Fat Low-Calorie Desserts Market
Specialty Foods
Keto Low-Calorie Meals Market
Specialty Foods
Gluten-Free Desserts and Ice Creams Market
Specialty Foods
Low Calorie Veggie Dip Market
Specialty Foods
Mediterranean Kimchi-Style Vegetable Culture Starters Market
Specialty Foods
Low Fat Hummus Market
Specialty Foods
Gluten-Free Oats Market
Specialty Foods
Mexico Guacamole Market
Specialty Foods
Superfood Bars Market
Specialty Foods
Coconut Butter Market
Specialty Foods
Grain-Free Pet Food Market