
 Global Nata De Coco Market | 2026-2036
Global Nata De Coco Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nata De Coco Market Outlook
Private-label formulation services is expanding as a distinct revenue layer, allowing regional distributors to commission custom flavor profiles and moisture specifications without building captive fermentation capacity. Happy Alliance Sdn Bhd leverages its Malaysian palm-coconut belt location to sustain raw material proximity advantages. PT Denikin Industri Nusantara anchors supply contracts with Indonesian beverage conglomerates through dedicated tank farm operations. Del Monte Asia Pte Ltd competes on food safety certification depth across multiple export jurisdictions.
Nata de coco is a bacterial cellulose gel produced through Acetobacter xylinum fermentation of coconut water, yielding a translucent, high-fiber matrix with chew-resistant elasticity valued in dessert and beverage applications. The gel contains approximately 99% water bound within a nanofibrillar cellulose network, delivering zero-fat texture enhancement in bubble tea and fruit salad formulations. Flavored nata commands premium positioning in beverage applications where color stability and syrup compatibility determine procurement decisions. Bulk packaging serves institutional food manufacturers with volume-scale margin structures, while pouch formats capture convenience-oriented retail channels in urban Southeast Asian markets.
FDA food additive regulations govern cellulose-derived ingredient imports into the United States, requiring GRAS self-affirmation or food contact notification pathways for novel fermentation substrates. EFSA novel food assessments shape European market access timelines for coconut-water-fermented cellulose products not historically consumed in the EU prior to 1997. BIS food safety standards in India mandate microbial load testing for imported nata de coco consignments, influencing supplier qualification protocols. Stakeholders must monitor evolving fermentation substrate labeling requirements across destination markets to preempt supply chain disruptions.
Market Dynamics
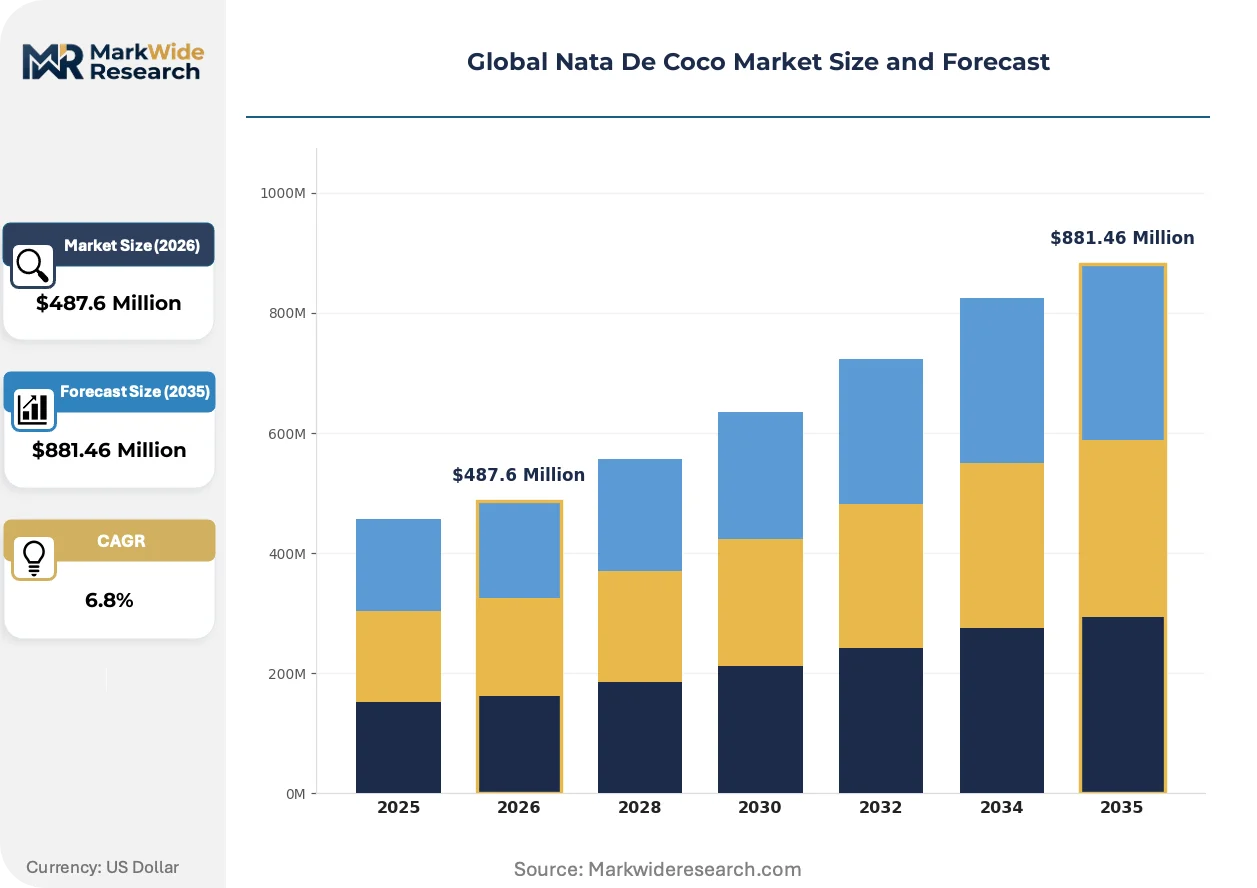
Bubble tea format proliferation in Southeast Asia is compressing flavor development cycles and forcing fermentation capacity investments closer to urban demand clusters. This structural pull is reconfiguring how nata de coco suppliers align substrate sourcing with finished-gel distribution economics.
Growth Catalysts
- PLI scheme incentives:India's production-linked incentive scheme for food processing infrastructure is drawing fermentation equipment investments into coastal coconut belts. Domestic nata de coco output expands as import substitution accelerates.
- Acetobacter xylinum strain optimization:Advanced microbial screening protocols are reducing fermentation cycle variability. Consistent gel yield improves contract reliability for institutional beverage manufacturers.
- Bubble tea chain standardization:Format specifications from major Southeast Asian beverage franchises are creating pull-through demand for certified nata de coco suppliers. Procurement volumes concentrate among qualified vendors.
Market Restraints
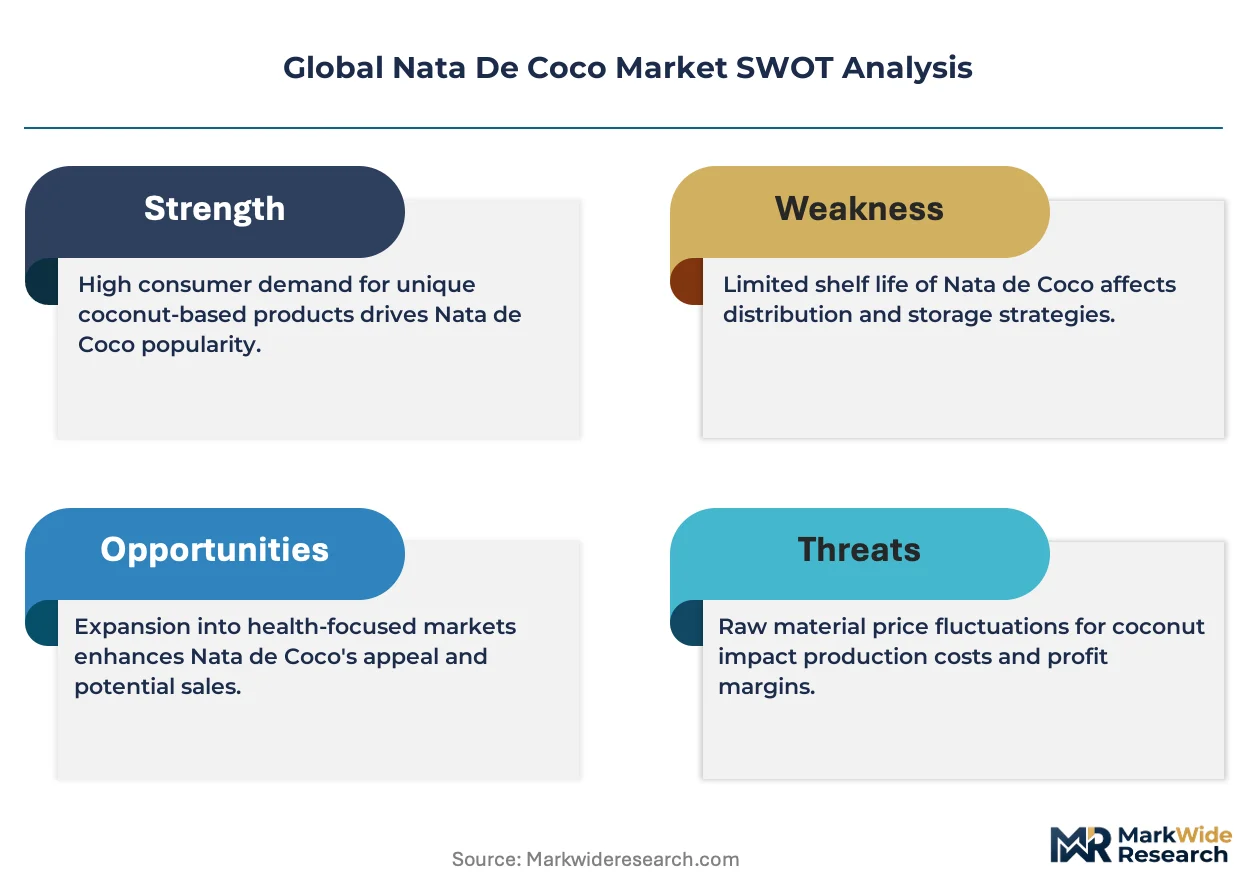
- Coconut water substrate volatility:Raw material costs fluctuate with tropical weather patterns and competing coconut oil demand. Margin compression hits smaller fermentation operators without backward integration into coconut crushing.
- EFSA novel food assessment timelines:European market access requires extensive safety documentation for coconut-water-fermented cellulose. Regulatory friction delays revenue recognition from EU beverage and dessert channels.
- Algal cellulose substitution:Marine-derived bacterial cellulose from alternative substrates threatens nata de coco's positioning in premium texture applications. R&D investment in algal fermentation is accelerating in East Asian biotechnology clusters.
Strategic Opportunities
- Clean-label dessert penetration in Germany:EFSA-compliant nata de coco holds positioning potential in European plant-based confectionery. Certification depth separates qualified entrants from commodity suppliers.
- FDA GRAS self-affirmation pathway:US food additive regulatory clarity for fermented cellulose creates accessible market entry. GRAS-affirmed suppliers capture institutional bakery and beverage formulation contracts.
- Direct-to-beverage-manufacturer e-procurement platforms:Digital sourcing channels are disintermediating traditional distributor networks. Fermentation operators with food safety documentation gain direct access to bubble tea chain procurement teams.
Industry Challenges
- Fermentation microbiology talent scarcity:Industrial-scale Acetobacter xylinum cultivation requires specialized process engineering expertise. Southeast Asian production clusters compete for limited bioprocessing technical personnel.
- Multi-jurisdiction certification burden:Simultaneous compliance with FDA, EFSA, and BIS standards demands dedicated regulatory affairs capacity. Documentation timelines extend customer qualification periods.
- Cold chain integrity for finished gel:High-moisture nata de coco requires temperature-controlled distribution to prevent microbial degradation. Logistics infrastructure gaps in secondary Southeast Asian urban markets constrain retail expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nata De Coco Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plain Nata, Flavored Nata, Sweetened Nata, Savory Nata Packaging Type: Glass Jar, Plastic Cup, Pouch, Bulk Packaging Distribution Channel: Online Retailers, Supermarkets, Food Service, Convenience Stores End User: Food Manufacturers, Restaurants, Retail Customers, Caterers |
| Companies Covered | Nata Food Manufacturing Sdn Bhd, PT Denikin Industri Nusantara, Happy Alliance Sdn Bhd, Hainan Yeguo Foods Co., Ltd., PT Pulau Sambu (Kara), Del Monte Asia Pte Ltd., Schmecken Agro Food Products, Siva Foods, HTK Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nata De Coco Market Strategic Shifts
Fermentation technology advances and regulatory documentation requirements are compressing supplier qualification timelines while expanding addressable application categories. Three developments are restructuring competitive capabilities.
Continuous fermentation bioreactor systems are modularizing production scale decisions for nata de coco manufacturers. Mid-cap suppliers in Indonesia and the Philippines adopt skid-mounted tank configurations to match batch size with contract volume without full plant reconstruction. This technology is modularizing capital deployment and enabling faster response to bubble tea chain demand spikes.
REACH registration requirements for cellulose derivatives are tightening substance documentation obligations for EU-bound nata de coco shipments. Industrial consequence falls heaviest on bulk exporters lacking in-house toxicology assessment capacity. Southeast Asian suppliers with third-party REACH compliance certification capture preferential positioning in European dessert ingredient procurement.
Ingredient specification portals operated by major beverage franchises are consolidating supplier discovery and qualification workflows. Direct platform access replaces traditional distributor relationship-building for nata de coco vendors with food safety certification depth. This channel shift concentrates procurement volume among documentation-complete suppliers in Malaysia and Thailand.
Global Nata De Coco Market Segmentation
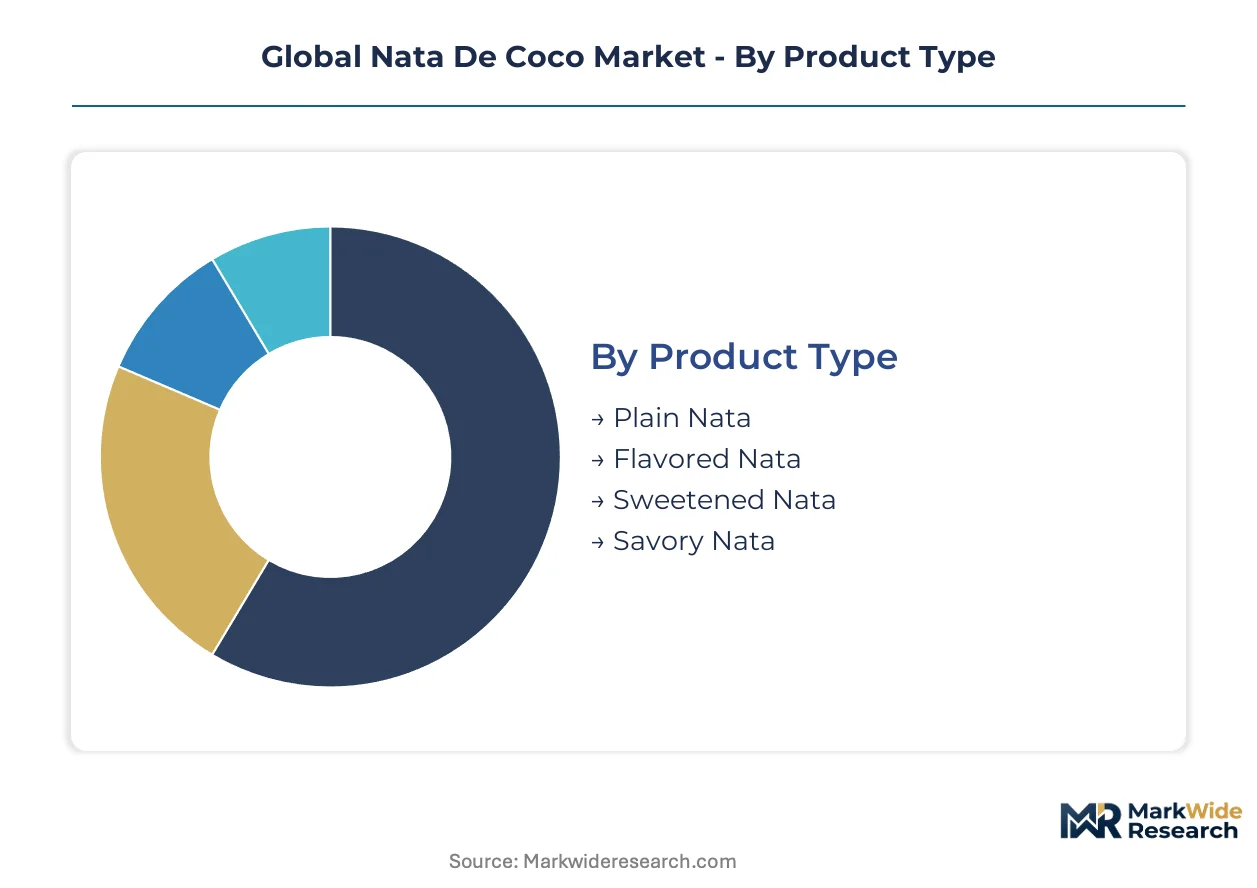
Nata de coco procurement decisions split across technical specifications and regulatory pathways. Certification requirements vary sharply by segment, determining which suppliers qualify for institutional contracts versus retail placement.
Product Type:
Certification burden concentrates in flavored and sweetened variants where EFSA novel food assessments and FDA GRAS self-affirmation govern European and US market access. Plain nata faces lighter documentation loads in established Asian markets.
- Plain Nata:Unflavored bacterial cellulose gel serves as the substrate for downstream flavoring operations. Food manufacturers in Indonesia and the Philippines absorb the bulk of plain nata volume for captive processing into finished dessert ingredients. FDA food additive regulations apply primarily to importers rather than intra-ASEAN trade.
- Flavored Nata:Syrup-infused variants with color stability requirements command premium positioning in bubble tea applications. EFSA-compliant suppliers capture European beverage chain procurement through REACH-registered cellulose documentation. Certification depth separates qualified entrants from commodity suppliers in German and French markets.
- Sweetened Nata:Pre-sweetened formulations reduce preparation steps for food service operators. BIS microbial load standards in India restrict import channels to documentation-complete vendors.
- Savory Nata:Salt and umami-seasoned variants target salad and appetizer applications in Southeast Asian food service. Smaller addressable market limits dedicated fermentation capacity investment.
Plain Nata sits at the top of the volume ranking, with Flavored Nata climbing the fastest.
Packaging Type:
Cost tier separation runs from bulk tanker deliveries at commodity margins to single-serve pouches capturing urban convenience premiums. Cold chain requirements escalate with moisture exposure and retail shelf visibility.
- Glass Jar:Traditional preservation format with premium positioning in gift-oriented retail channels. Higher unit logistics costs constrain distribution radius from Indonesian and Philippine production clusters.
- Plastic Cup:Food service portion control format dominates bubble tea chain specifications. Malaysian suppliers leverage palm-coconut belt proximity to compress delivery lead times for cup-format orders.
- Pouch:Lightweight flexible packaging captures convenience-oriented urban retail in Bangkok, Jakarta, and Manila. Shelf-stable pouch technology reduces cold chain dependency for secondary market penetration.
- Bulk Packaging:Institutional tanker and drum deliveries serve food manufacturers with volume-scale margin structures. Bulk buyers in India benefit from PLI scheme infrastructure incentives drawing fermentation investments into coastal coconut belts.
Bulk Packaging anchors procurement volume among institutional buyers, with Pouch formats expanding most quickly into convenience retail.
Distribution Channel:
Customer type determines channel selection, with food service and manufacturers bypassing retail intermediaries while household purchasers concentrate in supermarket and online pathways.
- Online Retailers:E-procurement platforms disintermediate traditional distributor networks for certified suppliers. Direct platform access replaces relationship-based selling for nata de coco vendors with food safety documentation depth.
- Supermarkets:Modern trade channels in urban Southeast Asia stock pouch and jar formats for household dessert preparation. Cold chain integrity requirements limit retail expansion in secondary Indonesian and Philippine cities.
- Food Service:Direct supply contracts with restaurant groups and bubble tea chains concentrate volume among qualified fermentation operators. Procurement teams specify Acetobacter xylinum strain documentation and moisture consistency thresholds.
- Convenience Stores:Grab-and-go single-serve positioning targets commuter demand in Bangkok, Kuala Lumpur, and Singapore metro corridors. Limited shelf space favors pouch formats over rigid packaging.
Food Service commands the largest transaction volumes, with Online Retailers gaining share fastest through platform-based supplier discovery.
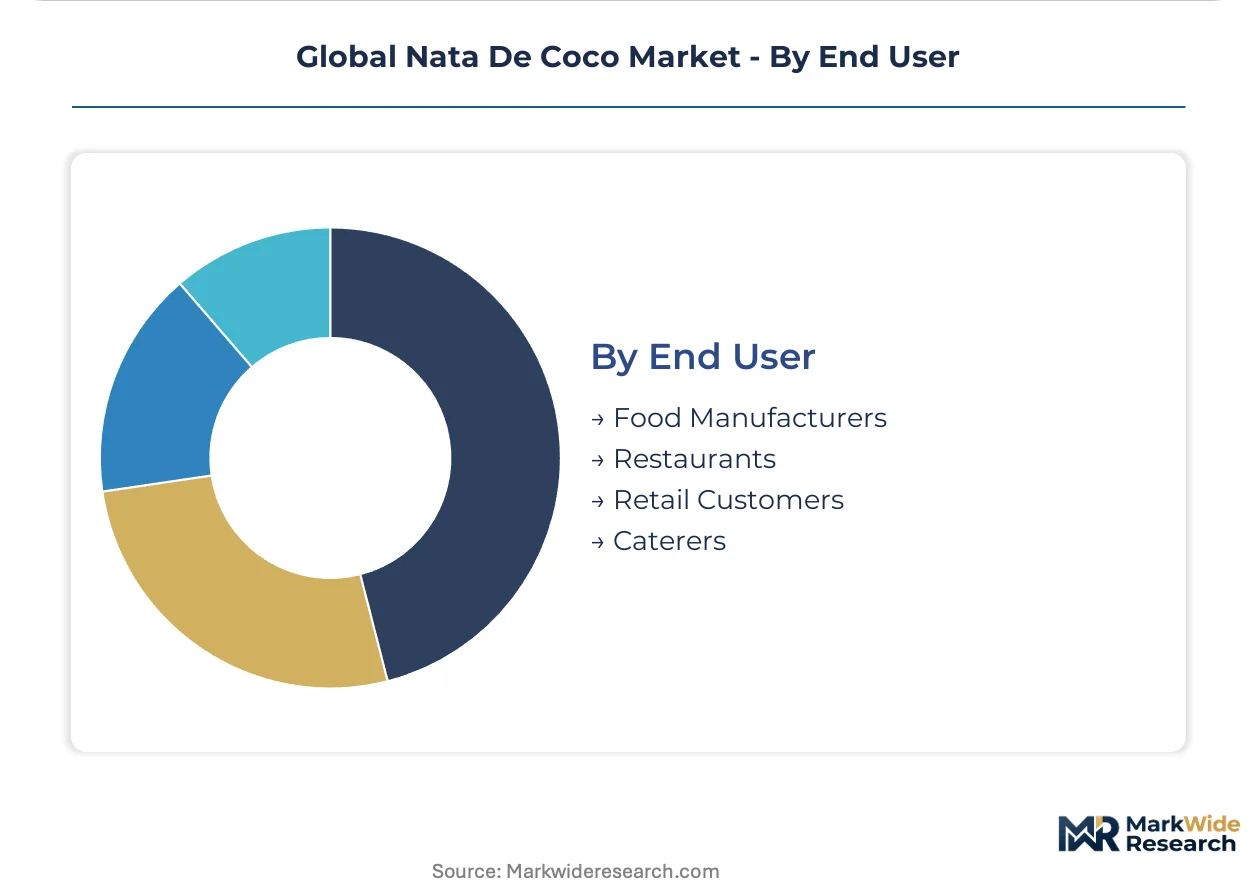
End User:
Application maturity varies from established dessert manufacturing to emerging beverage texture innovation, with margin structures inversely correlated with buyer concentration.
- Food Manufacturers:Integrated dessert and beverage producers absorb bulk nata de coco for downstream formulation. Continuous fermentation bioreactor adoption enables batch size matching with contract volume without full plant reconstruction.
- Restaurants:Bubble tea chains and dessert cafes drive flavored nata specification standardization across Southeast Asia. Format proliferation compresses flavor development cycles and forces fermentation capacity investments closer to urban demand clusters.
- Retail Customers:Household purchasers in jar and pouch formats exhibit price sensitivity and brand loyalty variation. Urban Southeast Asian markets show stronger repeat purchase patterns than emerging rural channels.
- Caterers:Event and institutional food service demands bulk packaging with flexible portioning options. Smaller aggregate volume limits dedicated product development attention from major suppliers.
Food Manufacturers represent the most mature demand base, with Restaurants generating the steepest expansion trajectory through beverage format proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is shifting fermentation capacity toward jurisdictions with streamlined food additive approval pathways and integrated coconut processing infrastructure. Cost-of-compliance gaps between EFSA novel food jurisdictions and established Asian markets are accelerating supplier migration patterns.
Indonesia
Bubble tea chain procurement contracts concentrate demand in Jakarta and Surabaya metropolitan corridors. FSSAI-equivalent export documentation requirements from the national food and drug regulator govern shipments to Indian buyers. Integrated coconut crushing clusters in North Sulawesi and Riau Islands anchor substrate supply for fermentation tank farm operations.
Philippines
Dessert manufacturing absorption of plain nata de coco drives volume-scale contracts with institutional food processors. BIS-aligned microbial testing protocols from the Food and Drug Administration shape supplier qualification for export-oriented producers. Davao Region and Quezon Province fermentation facilities leverage proximity to coconut oil crushing infrastructure for backward integration advantages.
Malaysia
Palm-coconut belt geography compresses raw material logistics costs for fermentation operators serving Singapore and Thai markets. Halal certification requirements from JAKIM create export qualification barriers for non-compliant suppliers. Johor Bahru and Klang Valley production clusters specialize in pouch-format packaging for urban convenience retail channels.
Thailand
Bangkok metro bubble tea format proliferation generates pull-through demand for flavored nata with color stability specifications. FDA Thailand food additive notifications govern domestic distribution while REACH-aligned documentation supports EU-bound shipments. Central Plains coconut water substrate availability fluctuates with competing coconut milk export demand.
India
PLI scheme incentives for food processing infrastructure are drawing fermentation equipment investments into Kerala and Tamil Nadu coastal belts. FSSAI microbial load standards for imported nata de coco consignments restrict supplier channels to documentation-complete vendors. Domestic production expansion targets import substitution in dessert and beverage manufacturing applications.
Global Nata De Coco Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with private-label formulators capturing margin in flavored variants while bulk plain nata suppliers compete on fermentation yield consistency. Market structure tilts toward geographic concentration in Southeast Asian coconut belts, where substrate proximity determines cost position. Three archetypes dominate: integrated coconut processors with captive fermentation, dedicated nata specialists with certification depth, and beverage-conglomerate-affiliated suppliers with dedicated tank farm operations. Competitive moves concentrate on backward integration into coconut crushing and multi-jurisdiction food safety certification stacking.
Among Malaysia-based specialists, Happy Alliance Sdn Bhd exemplifies the palm-coconut belt proximity archetype, while Indonesia's PT Denikin Industri Nusantara anchors the beverage-conglomerate contract manufacturing tier. Del Monte Asia Pte Ltd occupies a position representing multi-jurisdiction food safety certification depth across export markets. These three entities illustrate how geographic origin and corporate structure align with distinct competitive positioning vectors in global nata de coco supply.
| Leading Market Players |
|---|
| Nata Food Manufacturing Sdn Bhd |
| PT Denikin Industri Nusantara |
| Happy Alliance Sdn Bhd |
| Hainan Yeguo Foods Co., Ltd. |
| PT Pulau Sambu (Kara) |
| Del Monte Asia Pte Ltd. |
| Schmecken Agro Food Products |
| Siva Foods |
| HTK Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Bubble tea chain procurement concentration in Southeast Asia compresses pricing power toward contract-based long-term offtake structures. This buyer archetype dominance forces fermentation operators into volume-commitment pricing with certification-grade premiums layered on top.
Pricing Analysis
Capacity additions in Indonesia and the Philippines are reshaping price floors for plain nata de coco. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-compliant exporters from domestic-grade suppliers and bulk commodity traders. Price differentiation hinges on certification depth and Acetobacter xylinum strain documentation. Cost compression in standard-tier bulk supply is intensifying because smaller operators lack backward integration into coconut crushing. Institutional beverage manufacturers exhibit lowest price sensitivity; secondary urban retailers in emerging Indonesian cities show highest.
Supply Chain Analysis
REACH registration and FDA GRAS documentation requirements gate supplier qualification for EU and US-bound shipments. Geographic supply concentration centers on Indonesia, the Philippines, and Malaysia. Raw material dependencies draw from coconut water substrate, fermentation nutrients, and packaging materials. Single-source vulnerability runs through integrated coconut crushing clusters in North Sulawesi and Riau Islands. Distribution runs through direct platform access for certified suppliers and traditional distributor networks for commodity-grade product.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where EFSA-compliant certification depth commands procurement preference over volume-scale commodity positioning. Bubble tea chain specification standardization pulls demand toward documented fermentation reliability.
For Market Incumbents: Anticipate algal cellulose substitution pressure by deepening captive coconut water supply through upstream control over crushing infrastructure. Accelerate multi-jurisdiction certification stacking to defend contract renewals against emerging Indonesian fermentation operators with PLI scheme backing.
For New Entrants and Emerging Players: German clean-label dessert manufacturers represent an underserved buyer archetype with limited EFSA-compliant supplier options. White-space targets include shelf-stable pouch formats for secondary Southeast Asian urban markets and direct-to-beverage-manufacturer platform access. Penetrable entry point runs through REACH-registered cellulose documentation for EU dessert ingredient procurement.
For Investors and Strategic Acquirers: Beverage conglomerates with captive bubble tea chains are the most active acquirer in this space. Long-term viability favors mid-cap fermentation specialists with integrated substrate supply and certification depth. Acquisition target archetype: Indonesian or Malaysian operators with JAKIM halal credentials and FDA GRAS self-affirmation pathway completion. Signal to watch: bubble tea chain platform consolidation accelerating direct supplier discovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coconut Crushing | Captive substrate supply insulates margin from coconut oil demand volatility. |
| Multi-Jurisdiction Certification Stacking | Simultaneous FDA, EFSA, and BIS compliance unlocks institutional procurement contracts. |
| Continuous Fermentation Bioreactor Deployment | Modular tank configurations match batch size with bubble tea chain demand spikes. |
| Direct E-Procurement Platform Access | Ingredient specification portals disintermediate distributor networks for qualified suppliers. |
| Shelf-Stable Pouch Format Development | Reduced cold chain dependency enables secondary market penetration in Indonesian and Philippine cities. |
Study Parameters
Coverage spans Southeast Asia, South Asia, Europe, and North America, with primary inputs from each. Fermentation process engineers, bubble tea chain procurement directors, coconut crushing facility managers, and regulatory affairs specialists at export-oriented suppliers provided structured interviews. Secondary validation drew from FSSAI import notifications, EFSA novel food assessment registers, FDA GRAS affirmation filings, and ASEAN customs trade databases. Bottom-up facility capacity tallies and top-down demand absorption estimates were triangulated.
Granularity-level framing applied country-level modeling for Indonesia, the Philippines, Malaysia, Thailand, and India; segment-level disaggregation across plain, flavored, sweetened, and savory product types; and channel-level splits between food service, online retail, supermarkets, and convenience stores. CAGRs were derived from fitted growth curves anchored to bubble tea format proliferation rates and PLI scheme infrastructure incentive absorption. Forecast inputs included Acetobacter xylinum strain optimization timelines and REACH registration completion rates for EU-bound exporters.
Underlying measurement precision varies by segment; flavored and sweetened variants carry tighter precision than savory nata given established procurement data from beverage chain specifications. Forecasts reflect assumptions about fermentation cycle consistency and regulatory documentation pathway timelines. A model refresh is warranted upon material change in EFSA novel food assessment processing speeds or PLI scheme incentive disbursement rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Cultures Market
Specialty Foods
Marine Thermal Water Ferments Market
Specialty Foods
US Jam Jelly and Preserves Market
Specialty Foods
Manuka Honey Market
Specialty Foods
Global Ethnic Foods Market
Specialty Foods
Cannabis Infused Drinks Market
Specialty Foods
Middle East and Africa Hummus Market
Specialty Foods
Brahmi Market
Specialty Foods
Triphala Powder Market
Specialty Foods
Superfood Bars Market
Specialty Foods
CBD-Infused Ice Cream Market
Specialty Foods
Chamomile Market
Specialty Foods
Organic Skin Care Market
Specialty Foods
Kelp Noodles Market
Specialty Foods
Dill Juice Market
Specialty Foods
Low Fat Hummus Market